
 Food Disinfection Equipment Market | 2026-2036
Food Disinfection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Food Disinfection Equipment Market Insights
Aftermarket service revenue for spare parts and recalibration is fragmenting across regional service networks as OEMs lose exclusivity on maintenance contracts. JBT Corporation leverages its installed base of sterilization tunnels to sustain recurring revenue streams through long-term service agreements. HISAKA WORKS anchors its position in thermal processing through specialized steam sterilizer engineering for Asian seafood exporters. Systec competes on modular ultraviolet system architecture that allows food manufacturers to scale disinfection capacity without full line replacement.
Food disinfection equipment encompasses engineered systems that reduce pathogenic microorganisms on surfaces, in water, or within processing environments using ultraviolet irradiation, ozone injection, chemical dosing, or pressurized steam at temperatures exceeding 121 degrees Celsius. These systems serve the essential commercial purpose of ensuring compliance with microbiological safety standards while extending shelf stability for perishable goods. Ultraviolet systems lead product type demand due to their chemical-free operation and minimal residue risk in organic-certified facilities, while ozone generators represent the fastest-growing technology segment as processors seek alternatives to chlorine-based washes. Chemical disinfectants retain mature volume share in cost-sensitive emerging markets where capital constraints limit electromechanical system adoption.
FDA enforcement of FSMA preventive controls and EFSA's evolving specifications for biocidal product efficacy are reshaping equipment validation requirements and accelerating replacement cycles for non-compliant legacy installations. EPA registration mandates for ozone-generating devices and EU REACH restrictions on certain chemical disinfectant formulations further constrain product design freedom and favor electrochemical oxidation platforms. Stakeholders must monitor pending revisions to ISO 22000 prerequisite programs and emerging state-level water discharge regulations that could mandate closed-loop disinfection systems in high-volume processing zones.
Market Dynamics
Ultraviolet and ozone-based electromechanical systems are displacing legacy chemical wash stations across high-volume food processing corridors, driven by tightening microbiological safety thresholds from FDA and EFSA that mandate validated pathogen reduction without residue risk.
Growth Catalysts
- FSMA Preventive Controls:FDA enforcement mandates validated kill-step documentation for ready-to-eat products, forcing processors to retrofit lines with automated UV tunnel systems that generate continuous compliance data.
- Organic certification expansion:Chemical-free operation requirements in organic-certified facilities accelerate demand for ozone generators that eliminate chlorine residue concerns in produce washing operations.
- Germany's industrial baking corridor:Concentrated retrofit activity among large-scale bakeries replacing steam sterilizers with modular ultraviolet architectures that scale with production volume.
Market Restraints
- Capital intensity barrier:Electromechanical system costs limit adoption in cost-sensitive emerging markets where chlorine-based chemical washes retain economic advantage.
- Mercury lamp supply concentration:UV system OEMs depend on concentrated rare earth element sourcing for high-output lamps, creating input cost volatility and supply security exposure.
- EPA ozone device registration:Extended approval timelines for ozone-generating equipment create regulatory friction that delays commercial deployment and extends replacement cycles.
Strategic Opportunities
- California Central Valley cluster:Dense concentration of fruit and vegetable processors seeking closed-loop water recycling creates demand for integrated ozone-UV disinfection systems that meet emerging discharge regulations.
- EU Green Deal biocidal restrictions:REACH limitations on quaternary ammonium compounds create regulatory tailwind favoring electrochemical oxidation platforms in European meat and dairy processing.
- IoT-enabled predictive maintenance:Convergence of ultraviolet hardware with sensor networks and cloud analytics enables outcome-based service contracts that unbundle equipment from recurring revenue streams.
Industry Challenges
- Validation engineering scarcity:Shortage of technicians capable of executing EPA and FDA-mandated efficacy studies slows deployment timelines and inflates commissioning costs for UV and ozone installations.
- Legacy line integration complexity:Retrofitting automated disinfection tunnels into existing chemical wash infrastructure requires custom mechanical engineering that extends project duration and disrupts production continuity.
- ISO 22000 prerequisite alignment:Pending revisions to international food safety management standards create certification uncertainty that delays capital commitment among risk-averse processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Disinfection Equipment Market |
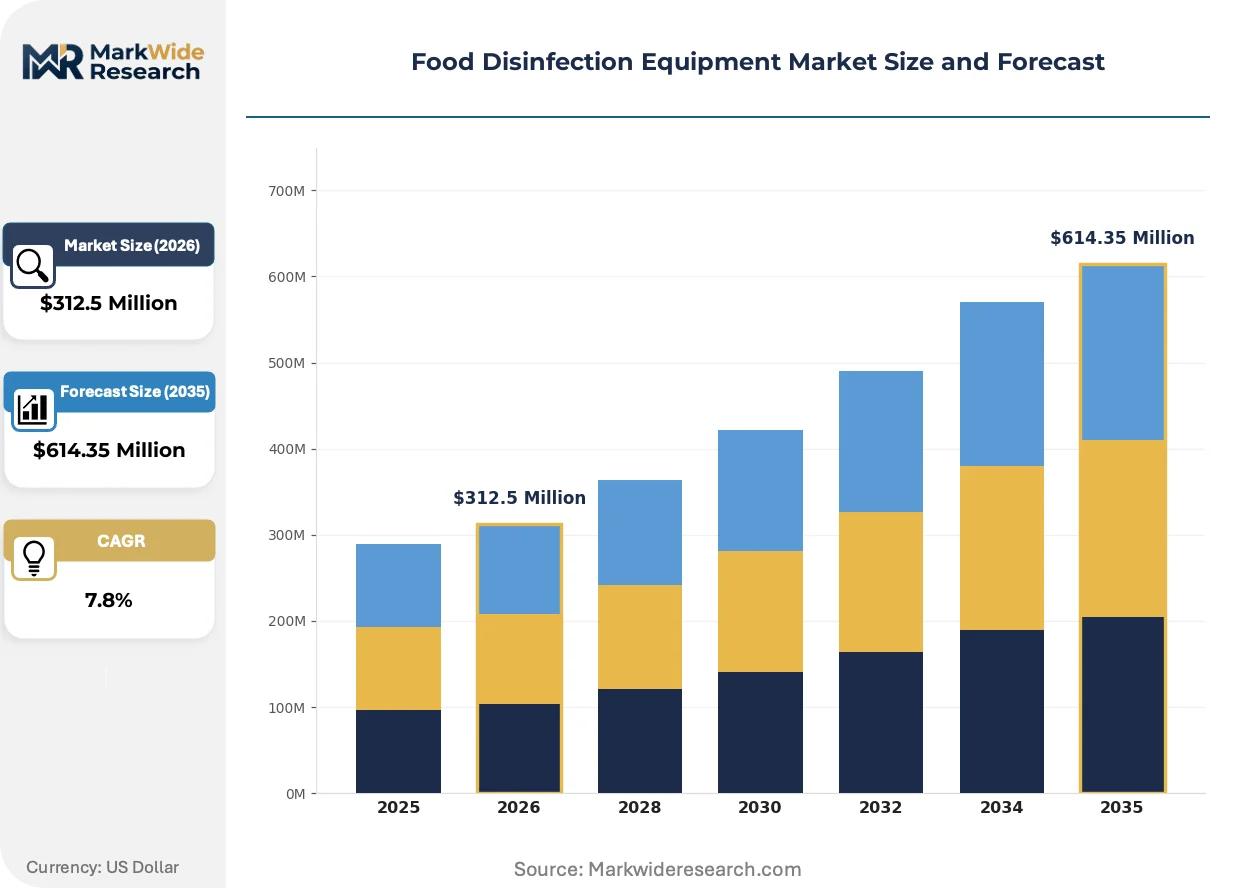
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $614.35 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultraviolet Systems, Ozone Generators, Chemical Disinfectants, Steam Sterilizers Technology: Electrolytic Oxidation, Photocatalytic Oxidation, Thermal, Chemical Reaction Application: Food Processing, Beverage Industry, Agricultural Products, Seafood End User: Restaurants, Food Manufacturers, Catering Services, Retail Outlets |
| Companies Covered | JBT Corporation, Systec, Cosmed Group, Allpax Products, DE LAMA S.P.A, HISAKA WORKS, Napasol AG, Surdry, Ventilex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Disinfection Equipment Market Trends and Innovations
Connected sensor architecture and real-time microbiological monitoring are compressing the gap between disinfection treatment and quality assurance, enabling processors to shift from scheduled maintenance to condition-based intervention protocols.
Ultraviolet LED arrays are digitizing pathogen detection and dosage calibration through integrated photodiode feedback loops. Poultry and ready-to-eat meat processors in the US Southeast are piloting these systems at scale. This convergence is digitizing the traditional separation between disinfection hardware and quality control software, collapsing equipment procurement into integrated platform decisions.
EFSA's evolving specifications for biocidal product efficacy are mandating quantitative microbial risk assessment documentation for all installed disinfection equipment. European processors must now demonstrate log-reduction performance under actual operating conditions rather than laboratory validation. Seafood exporters in Spain and the Netherlands are responding by adopting third-party certified UV systems with built-in data logging to satisfy heightened audit requirements.
Service contract unbundling is fragmenting the traditional OEM-captive maintenance model. Food manufacturers now procure spare parts and recalibration through regional service networks rather than original equipment suppliers. This pattern is most visible in Germany's dairy processing sector, where mid-sized cooperatives negotiate directly with component distributors to reduce lifecycle costs on ultraviolet lamp replacement programs.
Food Disinfection Equipment Market Segmentation
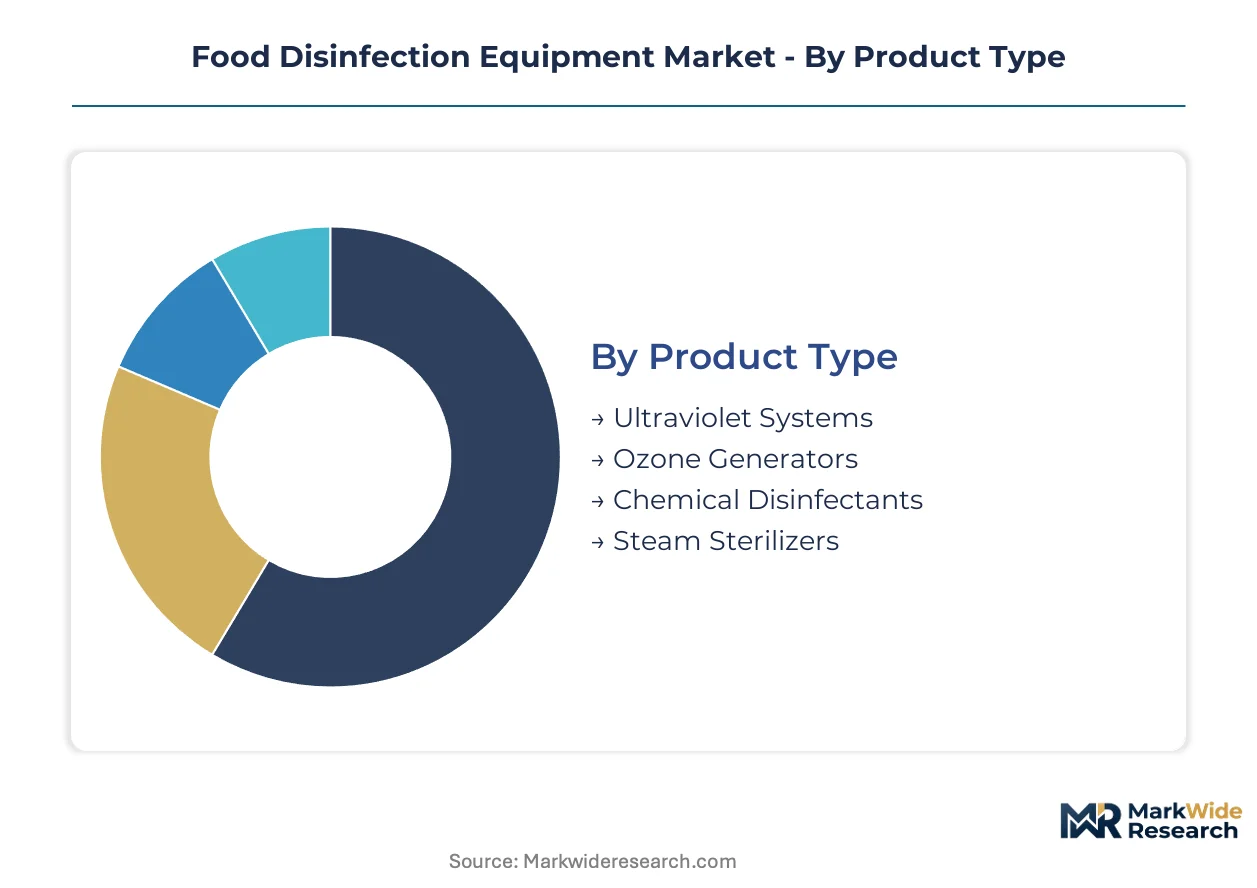
Equipment selection in food disinfection hinges on pathogen load characteristics, water chemistry, and residue constraints that vary dramatically across protein, produce, and beverage processing environments. Segmentation reveals where capital flows concentrate and which technology platforms capture margin premiums.
Product Type:
Use-case spectrum spans chemical-free organic certification compliance to legacy cost engineering in emerging markets.
- Ultraviolet Systems:Mercury-vapor and emerging LED arrays deliver 254-nanometer irradiation for surface and water disinfection without chemical residue. Demand clusters in Germany's industrial baking corridor and California's Central Valley processing facilities where FDA FSMA documentation requirements favor automated kill-step validation.
- Ozone Generators:Corona-discharge and electrolytic systems produce dissolved ozone for produce washing and CIP applications. EFSA biocidal efficacy mandates and EU REACH restrictions on quaternary ammonium compounds accelerate replacement of chlorine washes in Spanish seafood and Dutch dairy operations.
- Chemical Disinfectants:Chlorine-based, peracetic acid, and quaternary ammonium formulations retain installed base in cost-sensitive markets with limited capital availability for electromechanical retrofits.
- Steam Sterilizers:Pressurized thermal systems operating above 121 degrees Celsius serve high-risk ready-to-eat meat and poultry applications where log-reduction validation is mandatory.
Established volume favors chemical disinfectants; emerging adoption favors ultraviolet architectures.
Technology:
Cost tier stratification separates premium electrochemical platforms from mature thermal and chemical engineering.
- Electrolytic Oxidation:On-site generation of ozone or hypochlorous acid from water and salt eliminates bulk chemical storage. Installations concentrate in California fruit processors seeking closed-loop water recycling compliance with emerging discharge regulations.
- Photocatalytic Oxidation:Titanium dioxide catalysts activated by UV-A irradiation produce hydroxyl radicals for advanced oxidation. Pilot deployments in US Southeast poultry facilities test integrated pathogen detection feedback loops.
- Thermal:Saturated steam and hot-water systems anchor legacy infrastructure in Asian seafood export processing where HISAKA WORKS maintains specialized engineering presence.
- Chemical Reaction:Controlled dosing of chlorine dioxide, peracetic acid, and ozone from external supply chains dominates budget-constrained retrofit scenarios.
Capital intensity barriers protect thermal and chemical reaction share; regulatory tailwinds accelerate electrolytic oxidation expansion.
Application:
Volume concentration tracks perishability gradients and microbiological risk classification across commodity categories.
- Food Processing:Meat, dairy, bakery, and prepared meal operations drive system specification toward validated kill-step documentation. Retrofit activity concentrates where FDA preventive controls enforcement is strictest.
- Beverage Industry:Bottled water, juice, and brewing applications favor ozone and UV for taste-neutral disinfection without chemical residual.
- Agricultural Products:Fresh-cut produce washing generates demand for chemical-free alternatives that satisfy organic certification and export residue limits.
- Seafood:High-value export processing in Spain and Netherlands requires EFSA-compliant quantitative microbial risk assessment documentation.
Food processing commands equipment expenditure; agricultural products climb fastest on organic certification expansion.
End User:
Customer type determines scale economics and service contract structure across the equipment lifecycle.
- Food Manufacturers:Large-scale facilities in Germany's baking corridor and California's processing clusters drive modular UV system adoption with IoT-enabled predictive maintenance contracts.
- Restaurants:Commercial kitchen point-of-use systems for produce washing and surface disinfection favor compact ozone generators.
- Catering Services:Central commissary operations balance throughput requirements against space constraints in urban logistics environments.
- Retail Outlets:In-store deli and prepared food sections generate demand for validated disinfection in limited-footprint installations.
Food manufacturers concentrate capital deployment; retail outlets fragment procurement across regional service networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German and US buyers prioritize validated compliance over capital cost, while processors in India and Brazil defer electromechanical upgrades where chlorine washes remain economically viable.
United States
California's Central Valley fruit and vegetable processors drive retrofit demand as EPA discharge regulations tighten. FDA enforcement of FSMA preventive controls mandates automated kill-step documentation. Los Angeles and Fresno processing clusters replace legacy chemical stations with closed-loop ozone-UV systems.
Germany
Industrial baking corridors in Bavaria and North Rhine-Westphalia accelerate modular ultraviolet adoption. EU REACH restrictions on quaternary ammonium compounds eliminate chemical alternatives. Munich-area facilities scale disinfection capacity without full line replacement through Systec-compatible architectures.
China
Domestic food manufacturers balance export compliance against capital constraints in tier-two processing zones. SAMR tightening of microbiological safety standards for ready-to-eat products pressures legacy installations. Yangtze River Delta seafood exporters pilot electrochemical oxidation to satisfy EU import requirements.
Spain
Seafood processors in Galicia and Basque Country face EFSA quantitative microbial risk assessment mandates for export certification. EU Green Deal biocidal restrictions favor ozone generators over chlorine washes. Vigo and Bilbao processing ports adopt third-party certified UV systems with built-in data logging.
India
Cost-sensitive dairy and spice processing limits electromechanical system penetration outside multinational-owned facilities. FSSAI alignment with Codex Alimentarius standards gradually elevates validation requirements. Maharashtra's Nashik and Pune food parks represent concentrated upgrade activity among export-oriented units.
Food Disinfection Equipment Market Competitive Landscape
Capability concentration sits with specialized engineering houses; scale advantage sits with diversified industrial equipment conglomerates. The vendor base stratifies into three tiers: integrated multinationals with sterilization tunnel portfolios, regional specialists in thermal or ultraviolet architectures, and modular system architects competing on scalability. Consolidation pressure runs through aftermarket service contract capture and validation engineering talent acquisition. Geographic expansion into California and German processing clusters represents the dominant competitive vector alongside technology licensing for LED-based UV arrays.
Within the diversified industrial tier, JBT Corporation anchors North American market presence through sterilization tunnel installed bases and long-term service agreements. HISAKA WORKS occupies a specialist position in thermal processing engineering for Asian seafood export corridors. Systec exemplifies the modular architecture approach, enabling European food manufacturers to scale ultraviolet capacity without full production line replacement. These three represent distinct strategic postures: captive service revenue, regional engineering depth, and product platform flexibility.
| Leading Market Players |
|---|
| JBT Corporation |
| Systec |
| Cosmed Group |
| Allpax Products |
| DE LAMA S.P.A |
| HISAKA WORKS |
| Napasol AG |
| Surdry |
| Ventilex |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp freight corridors carry rare earth elements and mercury lamp components from Asian refineries to German UV system assemblers, where inbound logistics costs compound with OEM service contract erosion to widen price spreads between integrated suppliers and modular architects. California processors absorbing ozone generator EPA registration delays face extended payback periods that compress upfront equipment budgets and shift procurement toward regional component distributors.
Pricing Analysis
Aftermarket service revenue streams now exceed hardware margins for ultraviolet system providers, with recalibration contracts and lamp replacement programs generating recurring value that OEMs struggle to retain against independent regional networks. Pricing stratifies across premium certified tiers (FDA-validated kill-step documentation), standard modular architectures (Systec-compatible scaling), and economy chemical disinfectant systems for cost-constrained emerging markets. Price differentiation rests on validation engineering depth and IoT-enabled predictive maintenance bundling. Cost compression in the standard tier intensifies as Asian component suppliers bypass European assemblers. Food manufacturers in India's Nashik food parks exhibit highest price sensitivity; German industrial baking cooperatives prioritize compliance documentation over capital cost.
Supply Chain Analysis
Upstream rare earth element feedstock concentrates in Chinese mining and separation operations, with mercury lamp phosphor materials additionally sourced from Russian and Kazakh refineries. Quartz glass tubing for UV lamp housings draws from specialized German and Japanese manufacturers, while ozone generator electrode assemblies rest on South Korean ceramic substrate production. Single-source vulnerability in mercury lamp phosphor supply creates exposure to export restriction shocks. Distribution runs through OEM direct sales for large-scale retrofits, regional equipment distributors for mid-market installations, and component resellers for spare parts procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach economics now dominate food disinfection equipment valuation, with predictive maintenance contracts and validation engineering subscriptions expanding faster than ultraviolet hardware shipments as OEMs lose exclusivity on legacy installed bases.
For Market Incumbents: Harden aftermarket revenue capture by in-housing recalibration technician certification programs and locking long-term service agreements before regional distributors consolidate lamp replacement networks. Backward integration into quartz glass sourcing reduces exposure to Japanese supply concentration. Priority investment in FDA-validated data logging architectures defends against modular competitors offering cheaper validation-lite alternatives. For New Entrants and Emerging Players: India's tier-two dairy processing clusters present the most penetrable white-space, where FSSAI compliance elevation pressures legacy chlorine installations but multinational OEMs have limited service presence. Target compact ozone generator point-of-use systems for commercial kitchen applications where restaurant chains seek organic certification without capital-intensive tunnel retrofits. Go-to-market through regional HVAC distributors with existing foodservice relationships accelerates trial adoption. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized sterilization tunnel portfolios and fragmented regional service networks. Long-term viability favors platforms with IoT-enabled outcome-based contracting capabilities over pure hardware manufacturers. Signal to monitor: EPA ozone device registration timeline acceleration that would unlock California Central Valley cluster demand and validate electrochemical oxidation platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Engineering Talent Acquisition | Scarce EPA/FDA compliance technicians command premium compensation in California and Germany clusters. |
| IoT-Enabled Predictive Maintenance Platform | Sensor-integrated UV systems unbundle hardware from recurring service revenue streams for food manufacturers. |
| Backward Integration into Quartz Glass Supply | Captive lamp housing production reduces Japanese supplier dependency and stabilizes input cost volatility. |
| Regional Service Network Consolidation | Independent recalibration providers in Germany's dairy sector threaten OEM aftermarket revenue retention. |
| Electrochemical Oxidation Technology Licensing | LED-based UV array patents from US Southeast poultry pilots enable European organic certification expansion. |
Research Methodology
Desk research of FDA warning letters, EFSA biocidal product efficacy guidance, and EPA ozone device registration databases preceded structured interviews with plant engineers at California fruit processors, maintenance directors in Germany's industrial baking corridor, and aftermarket service heads at ultraviolet system distributors. Secondary validation drew from customs trade data on rare earth element imports, SEC 10-K equipment revenue disclosures, and ISO 22000 certification body audit statistics. Bottom-up installation counts across processing facilities triangulated against top-down OEM shipment estimates.
Forecast assumptions held fixed the current EPA ozone device registration timeline and EFSA quantitative microbial risk assessment documentation requirements, while varying capital expenditure sensitivity across organic certification expansion scenarios and REACH biocidal restriction enforcement intensity. Segmentation modeling spanned equipment type, technology platform, application category, and end-user scale tier. CAGRs derived from equipment replacement cycle analysis and regulatory-driven retrofit acceleration patterns. Industry-specific inputs included mercury lamp phosphor price indices and validation engineering wage inflation in German processing clusters.
Practitioners should monitor EPA ozone device registration backlog clearance and pending ISO 22000 prerequisite program revisions for early signals of demand inflection. Forecasts reflect assumptions about regulatory enforcement continuity and rare earth supply chain stability that material shifts could invalidate. Cross-checking against FAO food safety incident frequency data and national organic certification enrollment statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Granular Ice Machine Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Ice Maker Machines Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Spray Dryer Market
Food Processing Equipment
USA Commercial Walk-In Refrigeration Market
Food Processing Equipment
Hydrostatic Steam Blancher Market
Food Processing Equipment
Europe Industrial Food and Beverages Filtration System Market
Food Processing Equipment
North America Food and Beverage Filling and Capping Machines Market
Food Processing Equipment
Smart Meat Thermometer Market
Food Processing Equipment
Deep Fryer Oil Filtration Market
Food Processing Equipment
Bread Processing Equipment Market
Food Processing Equipment
Fish Deboning Machine Market
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Food Processing Equipment Market