
 Air Cooled Cube Ice Machines Market | 2026-2036
Air Cooled Cube Ice Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Air Cooled Cube Ice Machines Market Outlook
Stainless steel is hardening its position as the dominant cabinet and evaporator material in air cooled cube ice machines, displacing lower-grade alloys that corrode under continuous freeze-thaw cycling. Hoshizaki Corporation leverages its in-house stainless fabrication to command premium positioning in commercial kitchens. Manitowoc Ice anchors North American distribution through a dense authorized dealer network. Scotsman Ice Systems differentiates via proprietary scale-reduction technologies that extend descaling intervals.
Air cooled cube ice machines are self-contained refrigeration appliances that produce uniform cube ice by circulating ambient air across the condenser, eliminating water-cooled infrastructure; typical units operate between 100 and 2,000 pounds of daily ice production with evaporator temperatures near minus 7 degrees Celsius, serving foodservice and hospitality operations where potable ice is consumed on-site. Modular configurations dominate installed base economics by allowing operators to pair ice heads with separate storage bins matched to peak demand patterns. Under-counter units are gaining fastest in compact urban bars and coffee shops where floor space commands premium rents. Large-capacity systems concentrate margin pools in chain hotel and cafeteria contracts where volume purchasing and service bundling compress unit economics for smaller competitors.
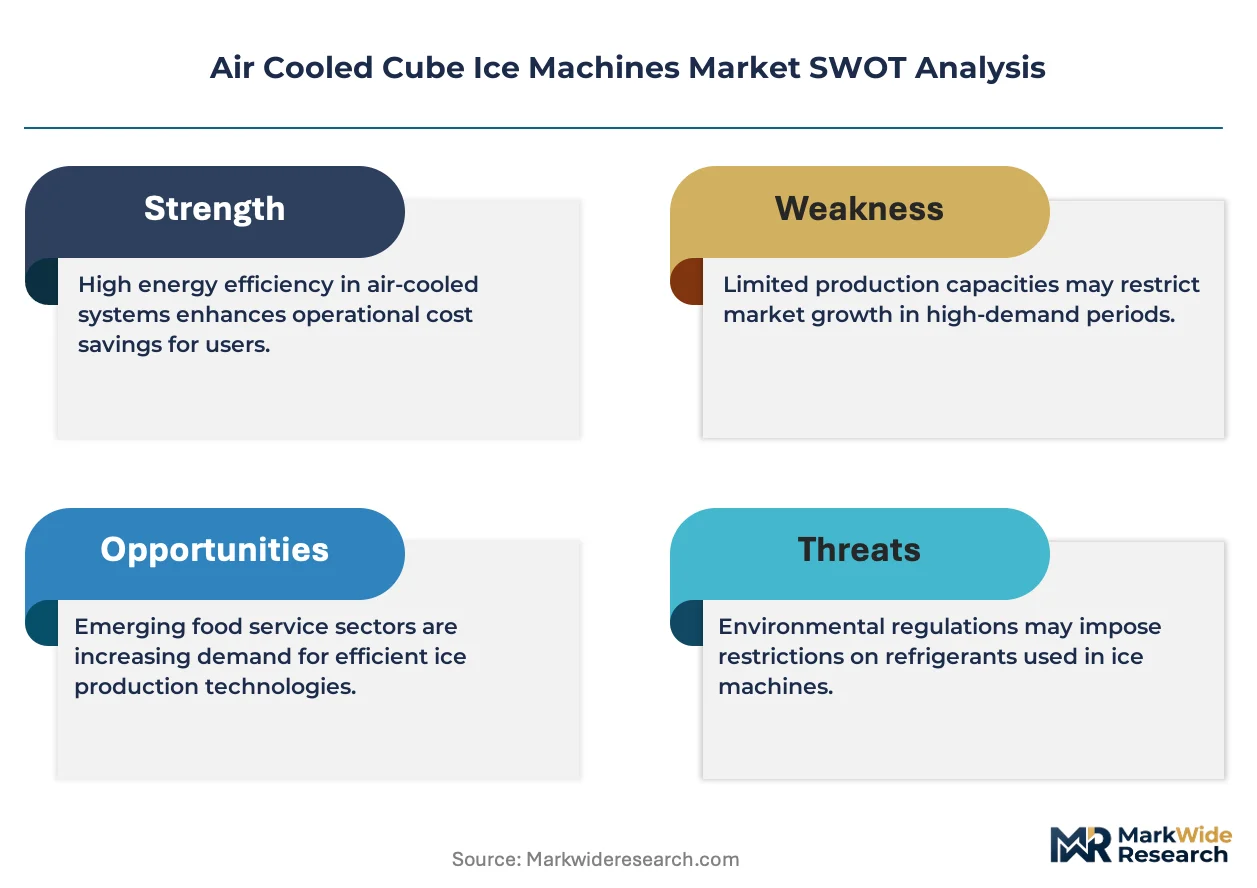
The US Department of Energy enforces minimum efficiency standards under commercial refrigeration regulations, while the EPA's SNAP program governs refrigerant transitions away from high-GWP hydrofluorocarbons. NSF International certification shapes product access by mandating sanitary design for food-contact surfaces and ice storage zones. Stakeholders must monitor refrigerant phase-down schedules and efficiency tier upgrades to avoid stranded inventory and secure specification in institutional procurement cycles.
Market Dynamics
The US Department of Energy's commercial refrigeration efficiency standards are compressing legacy compressor architectures and accelerating variable-speed scroll adoption across foodservice equipment portfolios.
Growth Catalysts
- Sun Belt Beverage Demand:Extended cooling seasons across Texas, Florida, Arizona, and California are expanding daily ice consumption per capita in quick-service chains and full-service restaurants.
- EPA SNAP Phase-Down:The refrigerant transition mandate away from high-GWP hydrofluorocarbons is pulling forward replacement cycles as operators avoid stranded R-404A inventory.
- Modular Head-and-Bin Economics:Foodservice operators are standardizing on separate ice production heads paired with matched storage bins to align capacity with peak demand windows.
Market Restraints
- Stainless Steel Input Volatility:Grade 304 and 316 sheet pricing swings compress margin visibility for cabinet and evaporator fabricators locked into annual procurement contracts.
- Authorized Dealer Concentration:North American distribution runs through a dense tier of factory-authorized service dealers, limiting direct channel access for emerging manufacturers.
- Water-Cooled Substitution in High-Humidity Zones:Coastal Gulf operators facing ambient air temperatures above 35 degrees Celsius retain water-cooled condensers despite infrastructure costs.
Strategic Opportunities
- Under-Counter Urban Penetration:Compact cube ice machines are displacing flake and nugget units in Manhattan, Chicago, and San Francisco coffee shops where floor space rents exceed 75 dollars per square foot annually.
- NSF/ANSI 7 Sanitary Design Mandate:Certification-driven procurement at institutional cafeterias and healthcare foodservice is creating specification advantages for compliant equipment.
- IoT-Enabled Predictive Maintenance:Sensor-integrated ice heads transmitting cycle counts and harvest times to dealer service portals are unbundling traditional break-fix contracts.
Industry Challenges
- Refrigerant Technician Scarcity:The transition to A2L mildly flammable refrigerants requires EPA Section 608 certification upgrades that lag equipment deployment timelines.
- Legacy Control System Integration:Chain hotel property management systems demand BACnet or Modbus connectivity that older ice machine architectures lack without costly gateway retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Cooled Cube Ice Machines Market |
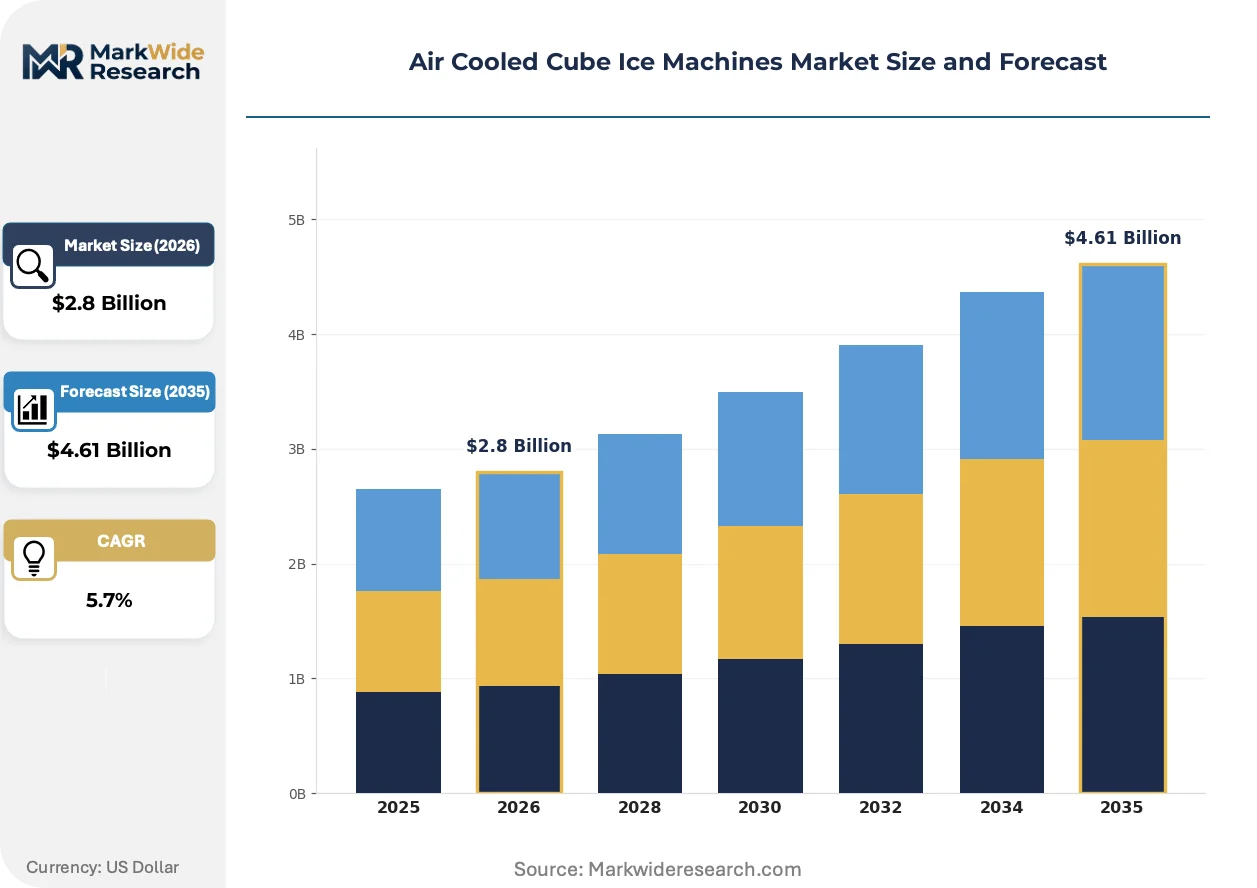
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
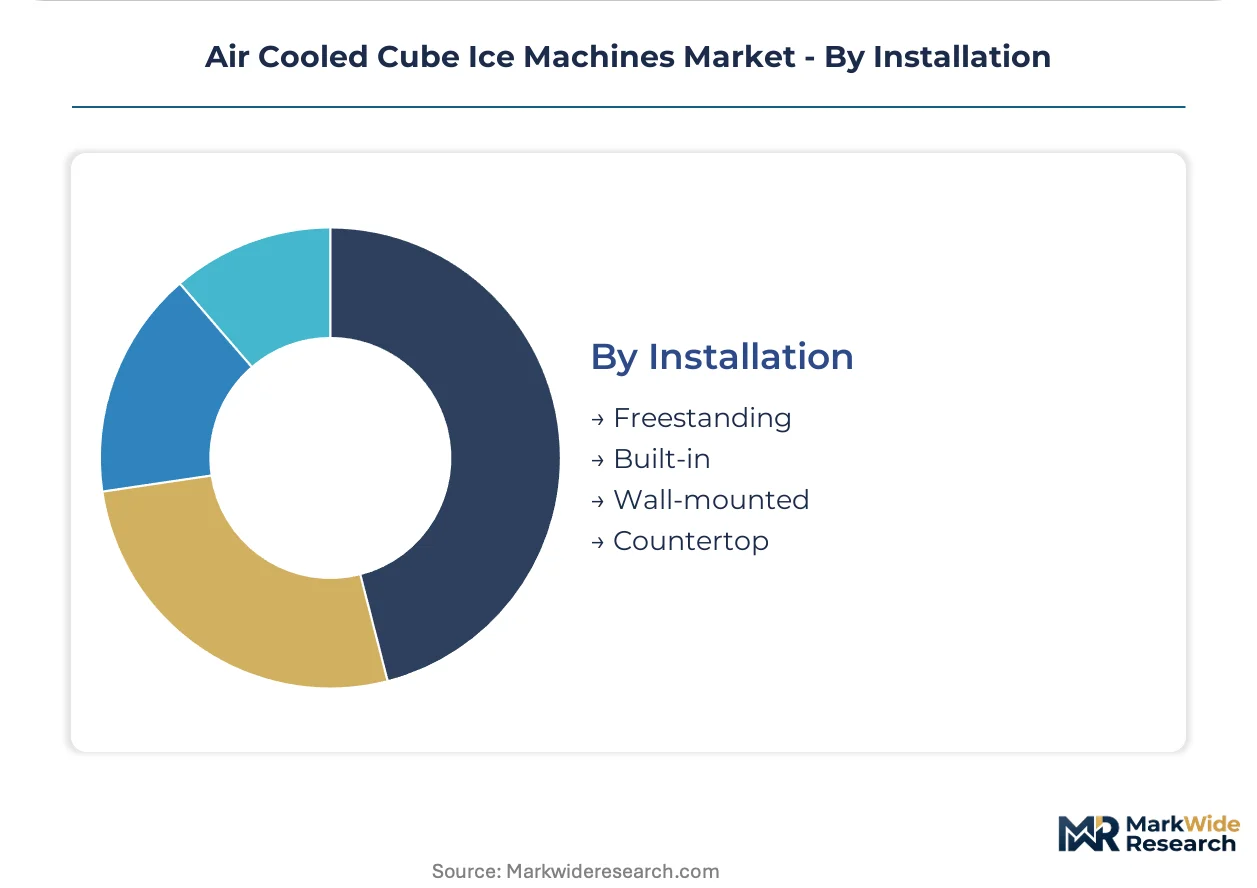
| Segmentation | Product Type: Modular, Under-counter, Stackable, Portable End User: Restaurants, Hotels, Bars, Cafeterias Capacity: Small, Medium, Large, Extra Large Installation: Freestanding, Built-in, Wall-mounted, Countertop |
| Companies Covered | Hoshizaki Corporation, Manitowoc Ice, Scotsman Ice Systems, Ice-O-Matic, Follett Corporation, Beverage-Air, Kooler Ice, Sonic Ice, Koller, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Cooled Cube Ice Machines Market Strategic Shifts
Equipment intelligence and material science are converging to reshape how operators specify, monitor, and service cube ice production assets across commercial kitchens.
Variable-speed scroll compressors with permanent magnet motors are rewriting energy consumption profiles in mid-capacity ice heads. Full-service restaurant chains operating 200-plus locations are specifying these units in new-build prototypes. The technology is compressing payback periods for efficiency upgrades below 36 months in high-electricity-rate territories.
The EPA's SNAP program is accelerating refrigerant transitions across the installed base. R-448A and R-449A blends are displacing R-404A in new equipment while retrofit kits face compatibility constraints with legacy mineral oil systems. Quick-service chains with standardized equipment footprints are absorbing the transition costs fastest through volume purchasing agreements.
After-sales service unbundling is fragmenting traditional dealer relationships. Large cafeteria and hotel operators are negotiating direct parts-and-labor contracts with national service aggregators, bypassing authorized dealer networks for multi-site portfolios. This pattern is most visible across Sun Belt states where chain density supports dedicated technician deployment.
Air Cooled Cube Ice Machines Market Segmentation
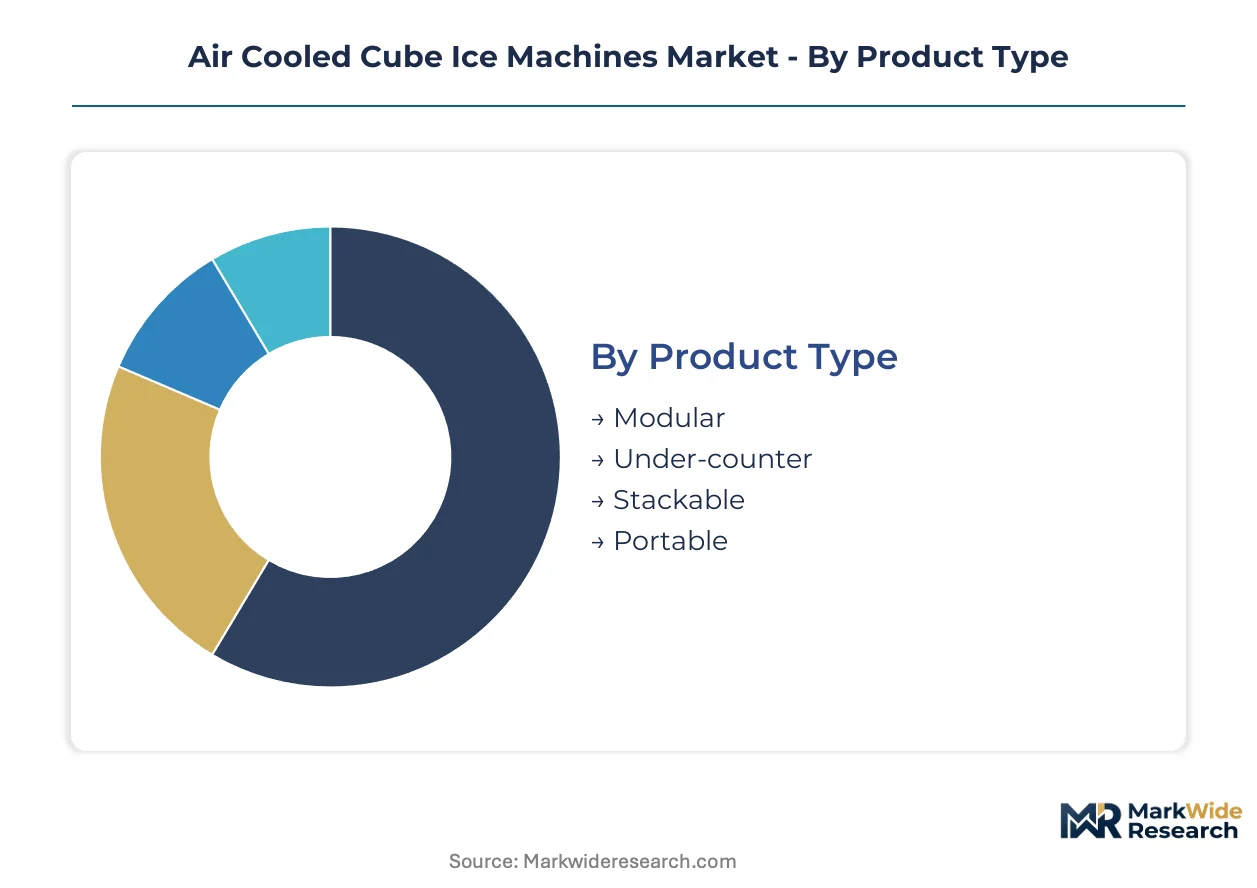
Operators specify air cooled cube ice machines across four intersecting dimensions: production configuration, end-use environment, daily output tier, and physical installation constraints. Procurement decisions cascade from peak demand patterns, spatial economics, and service infrastructure availability.
Product Type:
Configuration flexibility defines how ice production assets integrate with storage and distribution workflows across foodservice footprints.
- Modular:Separate ice heads mount atop dedicated storage bins, allowing operators to scale production independently from holding capacity. Chain hotels in Texas and Florida standardize on modular architectures to match 500-pound daily peaks with 800-pound bins for weekend banquet surges.
- Under-counter:Self-contained units slide beneath existing countertops, combining production and storage in compact footprints. Manhattan coffee shops and Chicago cocktail bars deploy these where floor space exceeds 75 dollars per square foot annually and dedicated ice rooms are economically unviable.
- Stackable:Vertical stacking configurations double output density within identical floor footprints. Caterers and stadium concessionaires leverage these for temporary event deployments.
- Portable:Castor-mounted units with integrated water reservoirs serve outdoor catering and emergency backup scenarios.
Mature deployment sits with modular systems. Newer deployment is concentrated in under-counter configurations.
End User:
Demand intensity varies sharply across foodservice verticals based on beverage-to-food revenue mix and guest traffic patterns.
- Restaurants:Full-service and quick-service chains generate the highest per-location ice consumption, driven by fountain beverage programs and bar operations. Sun Belt quick-service locations deploy redundant ice heads to avoid service interruptions during 10-month cooling seasons.
- Hotels:Property-wide ice demand concentrates at breakfast buffets, pool bars, and floor-dispenser networks. Large hospitality portfolios negotiate national service contracts that bundle ice machine maintenance with HVAC and refrigeration assets.
- Bars:Craft cocktail venues prioritize cube clarity and hardness for shaken drinks. Urban markets show fastest uptake of under-counter units.
- Cafeterias:Institutional foodservice at universities and healthcare facilities mandates NSF/ANSI 7 sanitary design for procurement eligibility.
Volume concentration rests with restaurant chains. Specification velocity runs highest in bars.
Capacity:
Daily production ratings align equipment selection with demand peaks, safety stock requirements, and electrical infrastructure constraints.
- Small:Units producing under 200 pounds daily serve low-volume bars and satellite coffee kiosks with intermittent ice needs.
- Medium:The 200-600 pound range dominates independent restaurant deployments, balancing first cost against peak lunch and dinner rushes.
- Large:Systems rated 600-1,200 pounds anchor casino buffet lines and hospital central kitchens with continuous production requirements.
- Extra Large:Industrial-scale heads exceeding 1,200 pounds concentrate in stadium concessions, airport terminals, and centralized commissary operations serving multiple satellite locations.
Equipment margins compress most severely in small capacity tiers. Extra large systems command the steepest expansion trajectory through chain consolidation.
Installation:
Physical mounting constraints determine ventilation clearance, service access, and integration with existing kitchen workflows.
- Freestanding:Floor-mounted units with rear or side discharge dominate back-of-house installations where clearance for airflow and technician access is unrestricted.
- Built-in:Flush-mounted configurations integrate with custom millwork in front-of-house bar designs, requiring zero-clearance ventilation engineering.
- Wall-mounted:Elevated installation preserves floor space in compact kitchens, though structural load limits restrict capacity.
- Countertop:Self-contained units serving under 100 pounds daily occupy customer-facing positions in specialty beverage shops.
Freestanding architectures retain the deepest installed base. Built-in specifications are climbing the fastest through design-forward hospitality renovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for air cooled cube ice machines concentrates in the United States, where extended cooling seasons and dense foodservice footprints drive per-capita ice consumption above all other markets. Sun Belt states anchor volume deployment, while regulatory pressure from federal efficiency standards shapes replacement cycles nationwide.
United States
Texas, Florida, Arizona, and California generate the highest daily ice consumption per foodservice location due to 10-month cooling seasons and fountain beverage dominance. The US Department of Energy's commercial refrigeration efficiency standards mandate minimum performance thresholds that accelerate variable-speed compressor adoption. Dallas-Fort Worth and Houston metropolitan clusters see fastest deployment of modular ice heads paired with high-capacity storage bins for quick-service chain expansion.
Germany
Full-service restaurant chains and hotel operators drive steady replacement demand as energy efficiency regulations tighten operational cost structures. The EU F-Gas Regulation mandates refrigerant phase-down schedules that pull forward equipment refresh cycles away from high-GWP hydrofluorocarbons. Industrial fabricators in Bavaria and Baden-Württemberg specialize in stainless steel evaporator components exported to European foodservice OEMs.
Japan
Compact urban foodservice formats in Tokyo and Osaka prioritize under-counter configurations where floor space exceeds premium valuations. METI energy conservation standards shape procurement specifications for commercial refrigeration equipment in institutional cafeterias. Nagoya-based manufacturing clusters supply precision compressor assemblies to domestic ice machine producers serving the Asia-Pacific market.
Australia
Coastal hospitality venues in Queensland and New South Wales balance air cooled efficiency against water-cooled performance in high-humidity subtropical conditions. The country's national energy regulator enforces minimum energy performance standards for commercial refrigeration that filter non-compliant imports. Sydney and Melbourne metropolitan areas concentrate specification activity for design-forward bar and restaurant renovations.
United Kingdom
London's dense independent restaurant and specialty coffee sectors drive under-counter unit penetration where real estate costs constrain back-of-house footprints. The UK's implementation of EU-derived F-Gas regulations continues to govern refrigerant transitions in post-Brexit equipment standards. Manchester and Birmingham hospitality clusters demonstrate fastest uptake of IoT-enabled ice heads for predictive maintenance contracting.
Air Cooled Cube Ice Machines Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbent manufacturers extend service capabilities and refrigerant transition expertise to capture replacement cycle volume. The vendor base organizes around three strategic tiers: multinational refrigeration specialists with captive distribution networks, regional fabricators competing on stainless steel fabrication quality, and emerging challengers unbundling after-sales service through direct national contracts. Two competitive moves define current positioning: authorized dealer network expansion to lock out direct channel access, and vertical integration into compressor and control system manufacturing to secure supply continuity.
Within the multinational specialist tier, Hoshizaki Corporation, Manitowoc Ice, and Scotsman Ice Systems exemplify divergent competitive anchors. Hoshizaki represents the stainless steel fabrication advantage, leveraging in-house metalworking to command specification in premium commercial kitchen environments. Manitowoc Ice occupies the North American distribution density position, anchoring volume through factory-authorized dealer networks that limit competitive access. Scotsman Ice Systems sits within the technology differentiation archetype, where proprietary scale-reduction capabilities extend maintenance intervals and reduce total cost of ownership for high-volume operators.
| Leading Market Players |
|---|
| Hoshizaki Corporation |
| Manitowoc Ice |
| Scotsman Ice Systems |
| Ice-O-Matic |
| Follett Corporation |
| Beverage-Air |
| Kooler Ice |
| Sonic Ice |
| Koller |
| Others |
Value Chain & Pricing Dynamics
Backward integration into compressor manufacturing anchors supply security and pricing power for air cooled cube ice machine producers, as captive production of scroll compressors and control systems insulates margins from component volatility while enabling premium positioning against fabricators dependent on third-party sourcing. This integration choice concentrates among multinational refrigeration specialists serving quick-service chains and hotel portfolios with national service contracts.
Pricing Analysis
Volume concentration in extra-large capacity tiers compresses margins through chain purchasing power, while small and medium segments retain pricing flexibility through customization and NSF certification premiums. Price differentiation hinges on stainless steel grade certification and after-sales service bundling, with Grade 304 and 316 evaporator specifications commanding tier premiums. Cost compression in modular configurations is intensifying as quick-service chains consolidate national purchasing agreements. Independent restaurants and urban bars demonstrate lowest price sensitivity, prioritizing reliability and space efficiency over first cost.
Supply Chain Analysis
Dual-sourcing requirements from institutional buyers and chain operators mandate multi-supplier qualification for compressors and control systems, fragmenting procurement across Japanese precision manufacturers and North American refrigeration specialists. Stainless steel sheet from China and domestic US mills feeds cabinet fabrication, while copper tubing and electronic controllers draw from Mexican and Southeast Asian assembly operations. Tariff exposure on steel inputs and semiconductor-dependent control modules creates supply vulnerability. Distribution runs through factory-authorized dealer networks that limit direct manufacturer access to end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where compressor manufacturing and IoT-enabled service platforms represent the decisive upstream and downstream levers. Players capturing both positions will dominate replacement cycles and national account procurement.
For Market Incumbents: Hedge refrigerant transition risk by accelerating A2L-compatible platform deployment ahead of technician certification bottlenecks. Secure captive stainless steel fabrication capacity to insulate margins from commodity volatility. Defend dealer network density against national service aggregator encroachment through predictive maintenance technology bundling. For New Entrants and Emerging Players: IoT-enabled remote diagnostics capability offers the most penetrable technology wedge for displacing legacy break-fix service relationships. Target under-counter configurations in Manhattan, Chicago, and San Francisco where floor space premiums override brand loyalty. Pursue direct national contracts with cafeteria and hotel operators seeking to unbundle authorized dealer relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational refrigeration portfolios seeking refrigerant transition expertise and connected service platforms. Five-to-ten year viability favors manufacturers with backward-integrated compressor supply and demonstrated EPA SNAP compliance execution. Watch for inflection when chain operators accelerate R-404A replacement cycles ahead of regulatory deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Variable-Speed Compressor Platform Launch | Manitowoc Ice and Hoshizaki are specifying permanent magnet scroll designs to meet DOE efficiency tiers. |
| Refrigerant Transition Compliance Program | Scotsman Ice Systems and Ice-O-Matic are securing EPA SNAP certification for R-448A and R-449A blends ahead of phase-down schedules. |
| IoT Service Platform Integration | Predictive maintenance portals transmitting cycle counts and harvest times are unbundling traditional dealer break-fix contracts. |
| Stainless Steel Fabrication Scale-Up | In-house Grade 304 and 316 evaporator production insulates margin visibility from annual procurement contract volatility. |
| Under-Counter Product Line Expansion | Compact configurations for urban bars and coffee shops capture premium rents exceeding 75 dollars per square foot annually. |
Study Parameters
Document review covered regulatory filings from the US Department of Energy and EPA SNAP program, trade data from customs records, and industry association disclosures, complemented by interviews with foodservice equipment procurement directors, authorized dealer service managers, chain hotel facility directors, and commercial refrigeration OEM product planners. Secondary validation drew from NSF International certification databases, DOE efficiency standard dockets, and SEC filings from publicly traded parent companies. Bottom-up demand modeling triangulated against top-down market sizing across production configuration, end-use vertical, and capacity tier dimensions.
Cross-reference approaches weighted historical shipment data against expert panel input regarding refrigerant transition timelines and chain expansion patterns across the projection horizon. Segmentation modeling captured modular, under-counter, stackable, and portable configurations intersecting with restaurant, hotel, bar, and cafeteria end uses. CAGRs derived from unit economics analysis incorporating electricity rate differentials, ice consumption intensity by geography, and replacement cycle acceleration from regulatory mandates. Forecast inputs included Sun Belt cooling season duration, stainless steel price indices, and technician certification pipeline constraints.
Several conditions sit outside the modeled scope, including abrupt refrigerant phase-down acceleration, trade policy shifts affecting steel or compressor imports, and pandemic-scale demand disruptions in foodservice. Forecasts reflect assumptions regarding steady regulatory implementation and intact authorized dealer network structures. Deviation in EPA enforcement intensity or DOE efficiency tier advancement schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Flakes Making Machine Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
Vacuum Frying Machine Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
Convection Ovens Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Ice Cream Freezer Market
Food Processing Equipment
Fish Cutting Machine Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Commercial Tunnel Oven Market
Food Processing Equipment
Mobile Bottling Line Market
Food Processing Equipment
Double Stack Oven Market