
 Global Controlled Release Fertilizer Market | 2026-2036
Global Controlled Release Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Controlled Release Fertilizer Market Foresight
Subscription-based agronomy advisory bundled with controlled release fertilizer formulations is repositioning how manufacturers capture recurring revenue from farm operations. Nutrien Ltd. leverages its retail agronomy network to embed fertilizer recommendations within digital farm management platforms. ICL Group Ltd. anchors its competitive stance through backward integration into specialty phosphate mining and downstream polymer coating technology. Yara International ASA extends its reach through controlled release product lines tied to variable-rate application software.
Controlled release fertilizers encapsulate soluble nutrients within polymer membranes, sulfur layers, or bio-based matrices to meter nitrogen, phosphorus, and potassium release across 30 to 180 days, matching plant uptake curves and reducing leaching losses. Polymer-coated variants command premium positioning due to precise temperature-responsive release kinetics and compatibility with drip irrigation systems. Sulfur-coated products compete on cost in broad-acre cereal applications where release precision matters less than upfront affordability. The horticulture application segment sustains above-average margins as greenhouse operators prioritize root-zone nutrient stability over per-ton procurement savings.
The EPA enforces Clean Water Act provisions that restrict agricultural nutrient discharge into watersheds, elevating controlled release formulations above conventional fertilizers in environmentally sensitive catchments. REACH compliance within Europe mandates disclosure of polymer coating chemistries, raising formulation costs while screening out smaller compounders. China's MEE applies dual carbon goals to fertilizer manufacturing, pushing domestic producers toward lower-emission coating processes. Stakeholders must monitor how carbon border adjustment mechanisms reshape the cost calculus of imported versus locally manufactured coated products.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is forcing reformulation toward polymer-coated products as nitrogen runoff limits tighten across member states, compressing conventional fertilizer margins while elevating controlled release premiums.
Growth Catalysts
- REACH compliance mandates:European disclosure requirements for polymer coating chemistries screen out smaller compounders, consolidating volume toward compliant manufacturers with certified formulations.
- Greenhouse horticulture expansion:Specialty crop growers in controlled environment agriculture prioritize root-zone nutrient stability, accepting per-ton premiums for temperature-responsive release kinetics.
- Brazil's Cerrado belt:Large-scale soybean and corn producers in this agricultural corridor seek yield optimization through precision nutrient delivery, concentrating import demand.
Market Restraints
- Specialty phosphate supply concentration:Backward integration into phosphate mining limits accessible feedstock for independent coaters, concentrating input leverage with integrated miners.
- Polymer resin cost volatility:Petrochemical-derived coating materials expose formulators to crude-linked input swings, compressing margin predictability.
- Sulfur-coated urea substitution:Lower-cost sulfur encapsulation competes effectively in broad-acre cereal applications where release precision matters less than upfront affordability.
Strategic Opportunities
- Subscription agronomy bundling:Manufacturers embedding fertilizer recommendations within digital farm management platforms capture recurring revenue beyond commodity tonnage.
- China's dual carbon goals:MEE enforcement pushes domestic producers toward lower-emission coating processes, creating technology licensing windows for foreign process innovators.
- Variable-rate application convergence:Controlled release product lines tied to precision agriculture software enable outcome-based pricing models in high-value cropping systems.
Industry Challenges
- Polymer coating R&D talent scarcity:Formulation chemists with expertise in temperature-responsive membrane design command premium compensation, constraining mid-tier expansion.
- Carbon border adjustment complexity:Importers face uncertain cost calculus as EU CBAM mechanisms reshape competitiveness of coated products versus locally manufactured alternatives.
- Drip irrigation system integration:Compatibility testing with existing fertigation infrastructure extends sales cycles and demands specialized agronomic field support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Controlled Release Fertilizer Market |
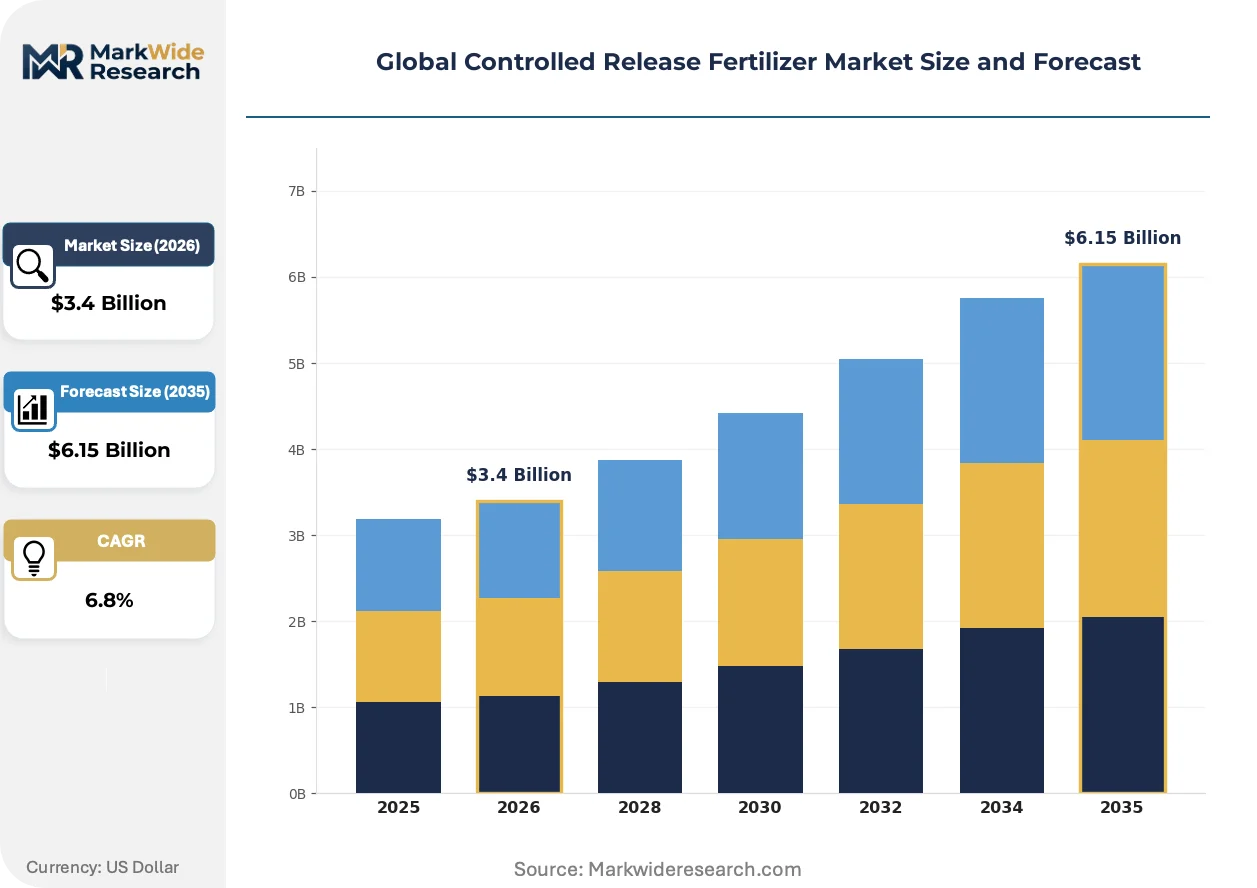
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-Coated, Sulfur-Coated, Bio-Based, Urea Formaldehyde, Others Application: Cereal Crops, Pulses & Legumes, Oilseeds, Horticulture, Turf & Ornamentals End Use Industry: Commercial Farms, Greenhouses, Landscape Contractors, Turf Managers Distribution Channel: Direct Sales, Agricultural Retailers, Online Stores, Cooperative Societies |
| Companies Covered | Nutrien Ltd., ICL Group Ltd., Kingenta Ecological Engineering Group Co., Ltd., Yara International ASA, Koch Industries, SQM, Grupa Azoty S.A., Haifa Chemicals, The Mosaic Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Controlled Release Fertilizer Market Shifts & Advancements
Coating technology convergence with digital agriculture platforms is reshaping how nutrient delivery is specified, procured, and validated across cropping systems.
Bio-based coating matrices derived from lignin and chitosan are unifying biodegradability with release precision. European greenhouse operators adopt these materials fastest, driven by retailer sustainability scorecards. This unification is compressing the performance gap between petroleum-derived and renewable encapsulants.
The EPA enforces Clean Water Act provisions restricting agricultural nutrient discharge into watersheds. Controlled release formulations gain preference in environmentally sensitive catchments above conventional fertilizers. Corn-soy rotations in the Chesapeake Bay watershed face the strictest discharge limits, accelerating polymer-coated urea uptake.
Outcome-based nutrient management contracts now displace spot procurement in high-value permanent crops. Almond and citrus growers in California's Central Valley contract for yield-per-acre guarantees rather than tonnage. This restructures manufacturer incentives toward field-level agronomic service deployment.
Global Controlled Release Fertilizer Market Segmentation
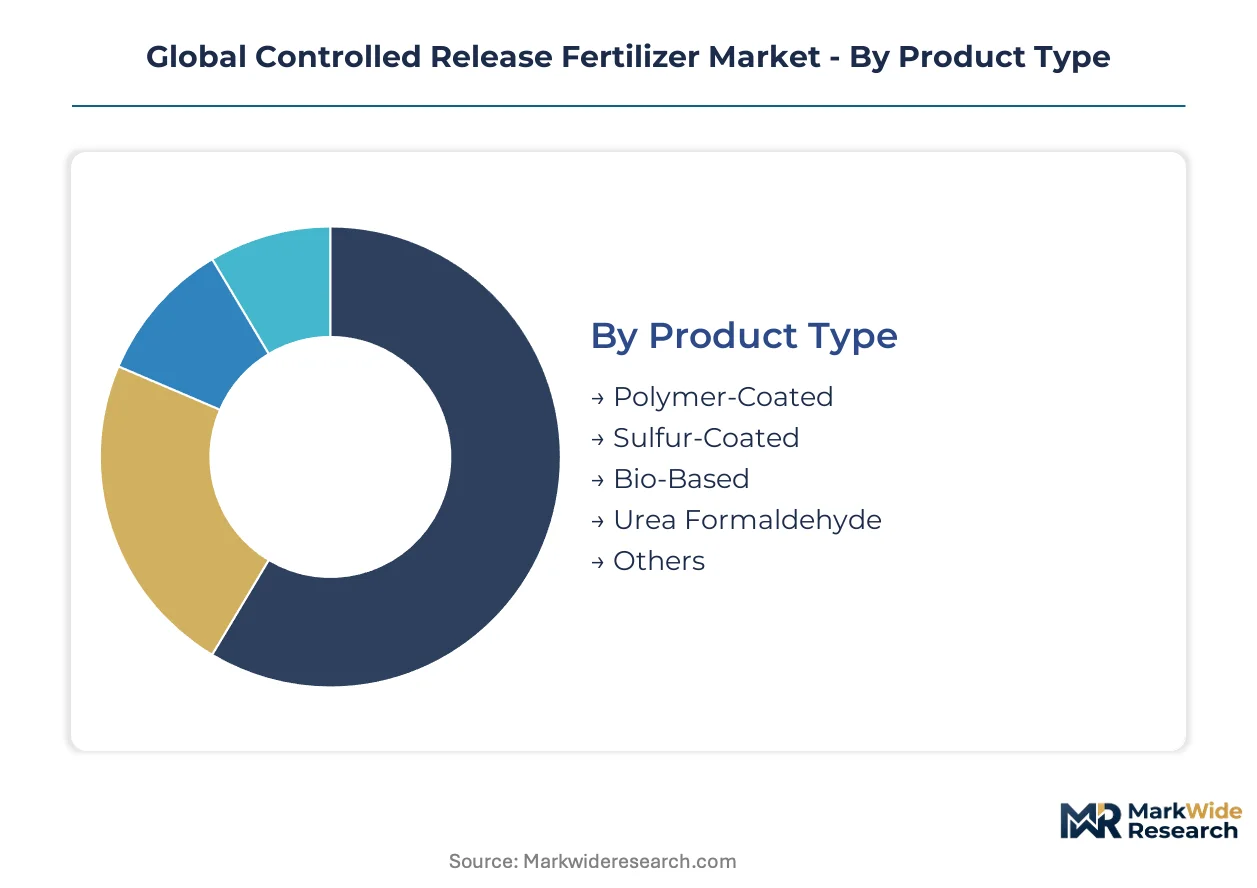
Segmentation in controlled release fertilizers reveals how coating chemistry, crop value, and procurement channel each create distinct margin architectures. Manufacturers configure production lines and field support teams around these divides rather than treating nutrient delivery as a single commodity pool.
Product Type:
Customization intensity spans from precision-engineered polymer membranes to standardized sulfur encapsulation, with cost and release kinetics trading off across the spectrum.
- Polymer-Coated:Thermoplastic or thermoset membranes meter nutrient release through temperature-responsive diffusion, achieving 60-180 day curves. Greenhouse operators in the Netherlands and Belgium absorb per-ton premiums for compatibility with drip irrigation and reduced leaching under REACH-monitored watersheds.
- Sulfur-Coated:Elemental sulfur layers provide cost-effective nitrogen protection through microbial degradation pathways. Brazilian Cerrado soybean producers prioritize upfront affordability over release precision in broad-acre applications where scale economics dominate procurement decisions.
- Bio-Based:Lignin and chitosan matrices deliver biodegradability with moderate release control. European retailers score sustainability metrics favorably for these formulations.
- Urea Formaldehyde:Slow hydrolysis of methylene urea fractions extends nitrogen availability across 10-12 weeks. Turf managers specify these for seasonal greening without surge growth.
- Others:Hybrid coatings and experimental encapsulants occupy niche positions in specialty crop trials.
Most installed capacity flows through Sulfur-Coated. Expansion is steepest in Polymer-Coated.
Application:
Margin capture correlates inversely with acreage scale — high-value per-hectare crops sustain coating premiums that broad-acre rotations cannot absorb.
- Cereal Crops:Wheat, rice, and maize rotations cover the largest treated hectarage globally. Chinese state procurement programs and Indian FPOs drive volume here, though sulfur-coated products dominate due to price sensitivity in grain-margin environments.
- Horticulture:Protected cultivation of vegetables, berries, and ornamentals demands root-zone stability above per-ton savings. Controlled environment agriculture clusters in Spain's Almería province and Mexico's Bajío region specify temperature-responsive polymer coatings to synchronize nutrient release with transpiration-driven uptake curves.
- Oilseeds:Canola and sunflower producers in Canada's Prairie provinces apply coated fertilizers to extend nitrogen availability through extended flowering periods.
- Pulses & Legumes:Nitrogen-fixing crops require phosphorus and potassium coating more than nitrogen, creating formulation specialization.
- Turf & Ornamentals:Golf course superintendents and municipal parks departments prioritize visual uniformity and labor reduction over agronomic yield.
Volume concentrates in Cereal Crops. Value capture peaks in Horticulture.
End Use Industry:
Customer sophistication determines whether procurement centers on tonnage price or integrated nutrient management outcomes.
- Commercial Farms:Large-scale operations with in-house agronomy staff evaluate coatings through yield-per-hectare modeling. Australian broad-acre wheat producers and Argentinian soybean cooperatives negotiate seasonal contracts with performance clauses tied to grain protein or oil content.
- Greenhouses:Controlled environment agriculture operators accept 40-60% premiums for polymer-coated formulations that eliminate fertigation complexity and reduce leachate treatment costs. Dutch tomato and cucumber growers specify coating dissolution curves matched to weekly harvest schedules.
- Landscape Contractors:Installation-scale projects prioritize labor efficiency and establishment survival rates over long-term nutrient efficiency.
- Turf Managers:Sports field and golf course maintenance budgets accommodate specialty coatings for color consistency and wear recovery.
Revenue tilts toward Commercial Farms. Margin expansion is sharpest in Greenhouses.
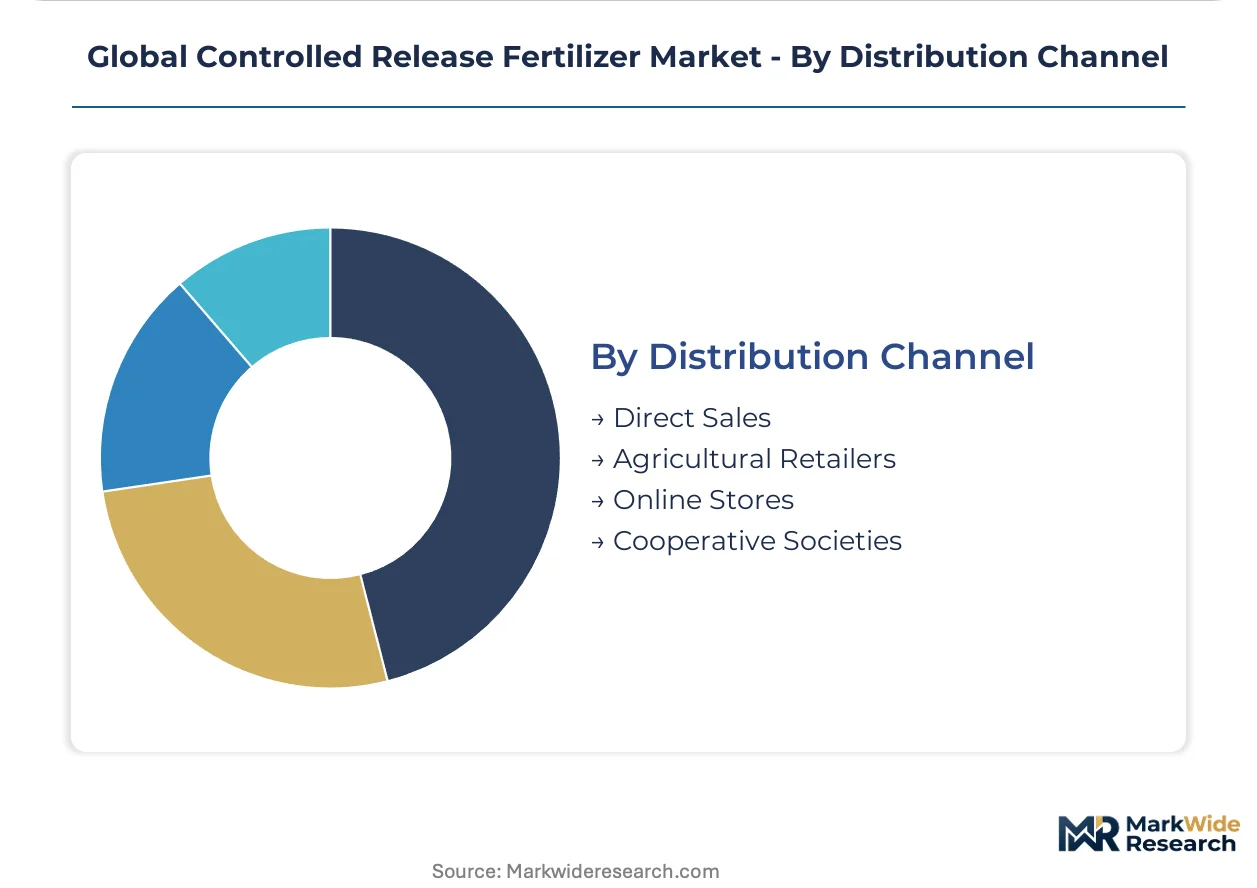
Distribution Channel:
Channel selection shapes manufacturer working capital requirements and agronomic service bundling intensity.
- Agricultural Retailers:Independent and chain retail networks dominate North American and European volume, embedding fertilizer within crop protection and seed portfolios. Nutrien's Loveland Products and similar retail agronomy platforms capture recurring revenue through prescription bundled with controlled release tonnage.
- Direct Sales:Large cooperative buyers and plantation operators in Indonesia's palm oil sector and Thailand's rubber belt negotiate directly with manufacturers for container-scale shipments with custom coating specifications.
- Cooperative Societies:Farmer-owned purchasing bodies in France's Axéréal and Germany's Raiffeisen structures aggregate demand for collective bargaining power.
- Online Stores:E-procurement platforms serve smallholder horticulture and specialty crop segments with sample-to-bulk conversion workflows.
Tonnage flows predominantly through Agricultural Retailers. Digital channel development is accelerating fastest in Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Cerrado belt concentrates soybean and corn demand for precision nutrient delivery, while the Netherlands dominates greenhouse horticulture adoption with polymer-coated formulations matched to drip irrigation schedules.
United States
Corn-soy rotations across the Chesapeake Bay watershed face EPA Clean Water Act discharge limits that accelerate polymer-coated urea uptake. The Farm Service Agency channels conservation program payments toward reduced-leaching fertilizer practices. California's Central Valley almond and citrus growers contract for yield-per-acre guarantees rather than tonnage procurement.
Brazil
Large-scale soybean and corn producers in the Cerrado agricultural corridor seek yield optimization through precision nutrient delivery, concentrating import demand for controlled release formulations. ANVISA monitors coating chemistry registrations for agricultural chemical compliance. Mato Grosso's mechanized farms negotiate seasonal contracts with performance clauses tied to grain protein content.
China
The Ministry of Ecology and Environment applies dual carbon goals to fertilizer manufacturing, pushing domestic producers toward lower-emission coating processes. State procurement programs for cereal crops drive sulfur-coated product volume in wheat and maize rotations. Shandong Peninsula phosphate refiners backward integrate into polymer coating technology to capture downstream margins.
Germany
REACH compliance mandates disclosure of polymer coating chemistries, raising formulation costs while screening out smaller compounders. The EU Green Deal's Farm to Fork strategy tightens nitrogen runoff limits across member states. Bavaria's sugar beet cooperatives aggregate demand through Raiffeisen purchasing structures for collective bargaining power on coated fertilizer specifications.
Netherlands
Greenhouse operators in Westland and Aalsmeer prioritize root-zone nutrient stability over per-ton procurement savings, accepting 40-60% premiums for temperature-responsive release kinetics. ECHA registration requirements favor established formulators with certified coating chemistries. Dutch tomato and cucumber growers specify coating dissolution curves matched to weekly harvest schedules.
Global Controlled Release Fertilizer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated miners capturing feedstock leverage and independent coaters competing on formulation agility. The vendor base organizes around three strategic archetypes: phosphate-integrated multinationals with captive raw material supply, regional compounders serving specialty crop clusters, and technology licensors monetizing coating process patents. Capacity expansion and strategic partnerships dominate competitive moves as players defend position in tightening regulatory environments.
Within the phosphate-integrated tier, Nutrien Ltd., ICL Group Ltd., and Yara International ASA exemplify archetypes spanning North American retail agronomy networks, Israeli specialty phosphate mining with downstream polymer coating, and Norwegian variable-rate application software convergence. Nutrien represents the retail-anchored model embedding fertilizer recommendations within digital farm management platforms. ICL occupies a position linking backward integration into specialty phosphate extraction with polymer membrane technology. Yara sits within the precision agriculture convergence vector, tying controlled release product lines to outcome-based pricing models in high-value cropping systems.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| ICL Group Ltd. |
| Kingenta Ecological Engineering Group Co., Ltd. |
| Yara International ASA |
| Koch Industries |
| SQM |
| Grupa Azoty S.A. |
| Haifa Chemicals |
| The Mosaic Company |
| Others |
Supply & Pricing Matrix
The EU Green Deal's nitrogen runoff limits gate both qualified supply and premium-tier pricing access, screening out non-compliant compounders while elevating polymer-coated formulations above sulfur-encapsulated alternatives in environmentally sensitive watersheds. REACH disclosure mandates raise formulation costs for coating chemistries, compressing margins for independent manufacturers without backward integration into phosphate mining or captive polymer resin supply.
Pricing Analysis
Capacity additions in Shandong Province are reshaping price floors for sulfur-coated urea in Asian cereal markets. Three-tier pricing structure across premium polymer-coated, standard sulfur-encapsulated, and economy uncoated tiers separates greenhouse operators from broad-acre grain producers from price-sensitive smallholders. Pricing pressure stems from petrochemical resin volatility feeding into membrane production costs. Brazilian Cerrado soybean cooperatives exhibit highest price sensitivity, while Dutch greenhouse clusters absorb per-ton premiums for temperature-responsive release kinetics.
Supply Chain Analysis
China's dual carbon goals and domestic-content preferences for state procurement programs are reshaping sourcing patterns for coating process equipment. Manufacturing gravity centers on China, Israel, and Norway for integrated phosphate-to-polymer production. Raw material flows draw from Moroccan phosphate rock, Gulf Coast petrochemical resins, and Brazilian sulfur deposits. Single-source vulnerability concentrates in specialty phosphate feedstock controlled by integrated miners. Distribution runs through agricultural retail networks embedding prescription agronomy with controlled release tonnage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
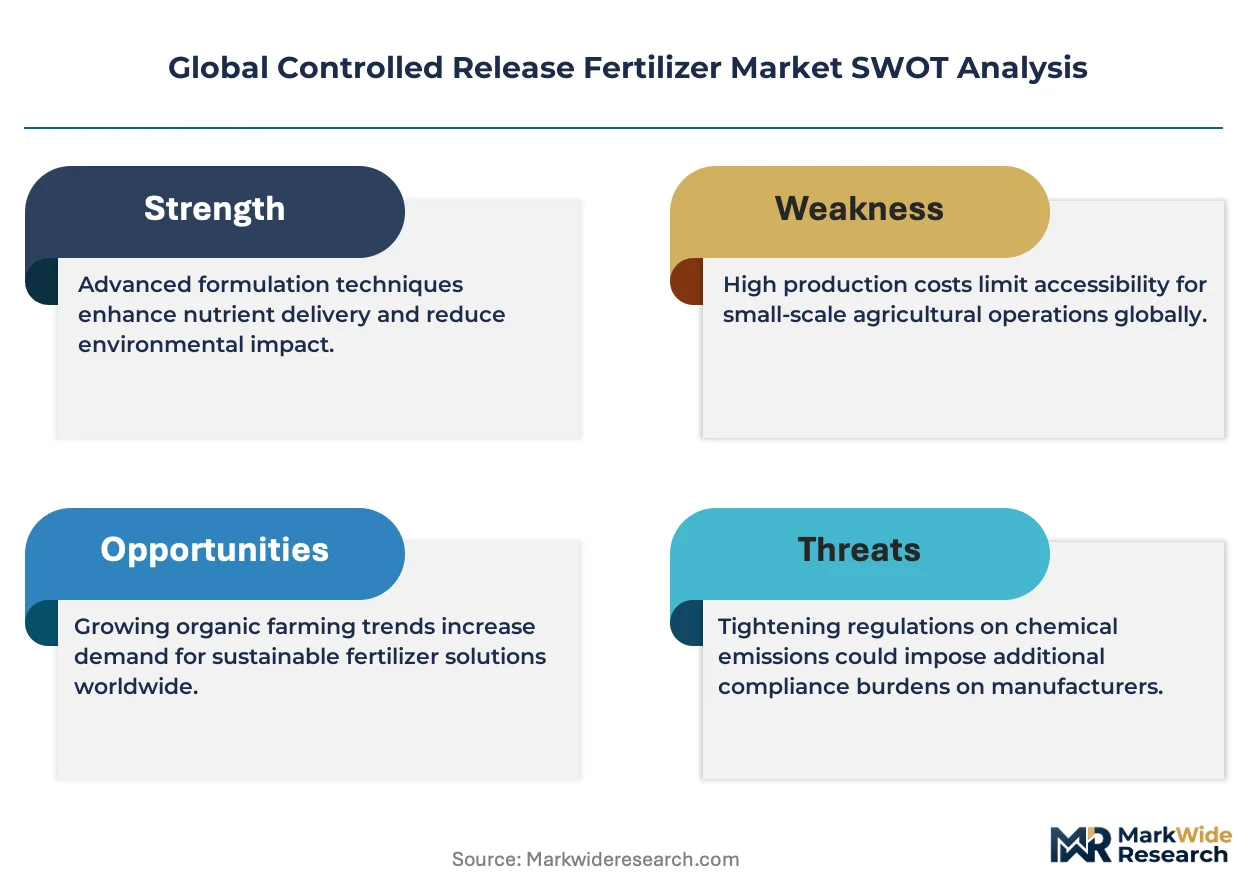
This market functions as a geographic-arbitrage play between EU REACH compliance costs and Chinese state-procurement volume scale, with nitrogen runoff regulations in European watersheds compressing conventional fertilizer margins while elevating premium-coated pricing power.
For Market Incumbents: To counter sulfur-coated urea substitution in broad-acre cereal applications, Nutrien-class retailers should deepen backward integration into specialty phosphate mining and deploy field agronomists for drip irrigation compatibility testing. Certification investment in ECHA-registered coating chemistries preserves premium-tier access against REACH-screened competitors.
For New Entrants and Emerging Players: Agricultural retailer networks in Brazil's Mato Grosso represent the most penetrable channel for polymer-coated formulations without captive phosphate supply. White-space targets include bio-based lignin-chitosan matrices for European sustainability scorecards and subscription agronomy bundling for California almond growers. A licensing play for lower-emission coating technology to Chinese domestic producers under MEE enforcement accelerates market entry without capital-intensive manufacturing.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders serving specialty crop clusters without captive phosphate leverage. Long-term viability hinges on regulatory tightening in nitrogen-sensitive watersheds and precision agriculture software convergence. Acquisition targets center on independent coaters with certified polymer formulations and established greenhouse channel relationships. The signal to watch is carbon border adjustment mechanism clarity reshaping import competitiveness of coated products versus locally manufactured alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Mining | Captive feedstock supply insulates ICL-class manufacturers from specialty phosphate concentration risk. |
| Polymer Coating Technology Licensing | Foreign process innovators monetize MEE-driven demand for lower-emission coating processes in Chinese domestic production. |
| Subscription Agronomy Bundling | Retail networks embed fertilizer recommendations within digital farm management platforms for recurring revenue capture. |
| Bio-Based Coating Matrix Development | Lignin-chitosan formulations satisfy European retailer sustainability scorecards while compressing petroleum-derived performance gaps. |
| Variable-Rate Application Convergence | Controlled release lines tied to precision agriculture software enable outcome-based pricing in California Central Valley permanent crops. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with coating formulation chemists, agricultural retailer procurement leads, greenhouse operations managers, and phosphate mining executives with secondary validation against customs trade data, EPA discharge monitoring reports, ECHA registration databases, and SEC filings from integrated fertilizer producers. Bottom-up volume modeling triangulated against top-down nutrient demand projections across the analysis window.
Segment-weighting applied coating chemistry type, crop value tier, and distribution channel intensity as primary dimensions across the projection horizon. CAGRs derived from regression analysis of historical adoption curves in nitrogen-regulated watersheds matched to regulatory enforcement timelines. Forecast inputs incorporated drip irrigation penetration rates in protected cultivation and dual carbon policy implementation trajectories in Chinese state procurement programs.
Revisions become necessary when carbon border adjustment mechanisms materially reshape import cost calculus, when polymer resin price volatility exceeds historical bands, or when bio-based coating performance achieves parity with petroleum-derived membranes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Europe Micronutrient Fertilizer Market
Fertilizers
Biological Organic Fertilizers Market
Fertilizers
Argentina Fertilizer Market
Fertilizers
GCC Fertilizer Market
Fertilizers
Urea Fertilizers Market
Fertilizers
Fertilizer Additives Market
Fertilizers
Thailand Fertilizers Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
India Specialty Fertilizer Market
Fertilizers
Diammonium Phosphate (DAP) Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
Controlled and Slow Release Fertilizers Market
Fertilizers
South Africa Fertilizer Market
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
North America Specialty Fertilizer Market