
 Diammonium Phosphate (DAP) Market | 2026-2036
Diammonium Phosphate (DAP) Market Size, Share, and Industry Trends Forecast 2026-2036
Diammonium Phosphate (DAP) Market Outlook
Subscription-based soil testing and prescription agronomy services is shifting how DAP gets sold, bundling nutrient recommendations with volume commitments rather than moving commodity tons alone. Nutrien Ltd. leverages its retail agronomy network to lock in farmer loyalty through integrated soil analytics and variable-rate application programs. The Mosaic Company anchors North American supply through its Florida phosphate mining and processing infrastructure, sustaining cost advantages on domestic granular product. OCP Group dominates Atlantic basin trade flows, positioning its Moroccan rock phosphate integrated chain to serve European and Latin American import demand.
Diammonium Phosphate is a water-soluble phosphate fertilizer manufactured by reacting phosphoric acid with ammonia to yield a compound containing approximately 18% nitrogen and 46% phosphorus pentoxide by weight, with granular forms dominating field application due to superior handling and reduced dust characteristics. Granular DAP commands the largest volume share in commercial agriculture, reflecting established blending infrastructure and mechanical spreader compatibility across major grain-producing regions. Powder DAP finds concentrated demand in fertilizer blends and specialty compound manufacturing, where rapid dissolution supports customized nutrient formulations. Agricultural cooperatives represent a structurally important end-user segment, consolidating procurement power and increasingly demanding transparent carbon footprint documentation alongside traditional pricing terms.
EPA water quality standards in the United States restrict phosphorus runoff from fertilizer application, pushing distributors toward coated and enhanced-efficiency formulations that reduce environmental loading. REACH registration requirements in Europe govern DAP import chemistry and safety data obligations, shaping market access conditions for non-EU producers. China's MEE enforces phosphate mining wastewater and tailings regulations that constrain raw material expansion and elevate compliance costs for integrated manufacturers. Stakeholders must monitor evolving carbon border adjustment mechanisms and farm-level emissions accounting protocols, as these frameworks will increasingly determine which supply chains qualify for premium market access and long-term offtake agreements.
Market Dynamics
Phosphate mining wastewater regulations under China's MEE are constraining feedstock availability and forcing procurement managers toward qualified supplier shortlists with verified compliance documentation. This regulatory compression is redrawing competitive access rules across integrated supply chains.
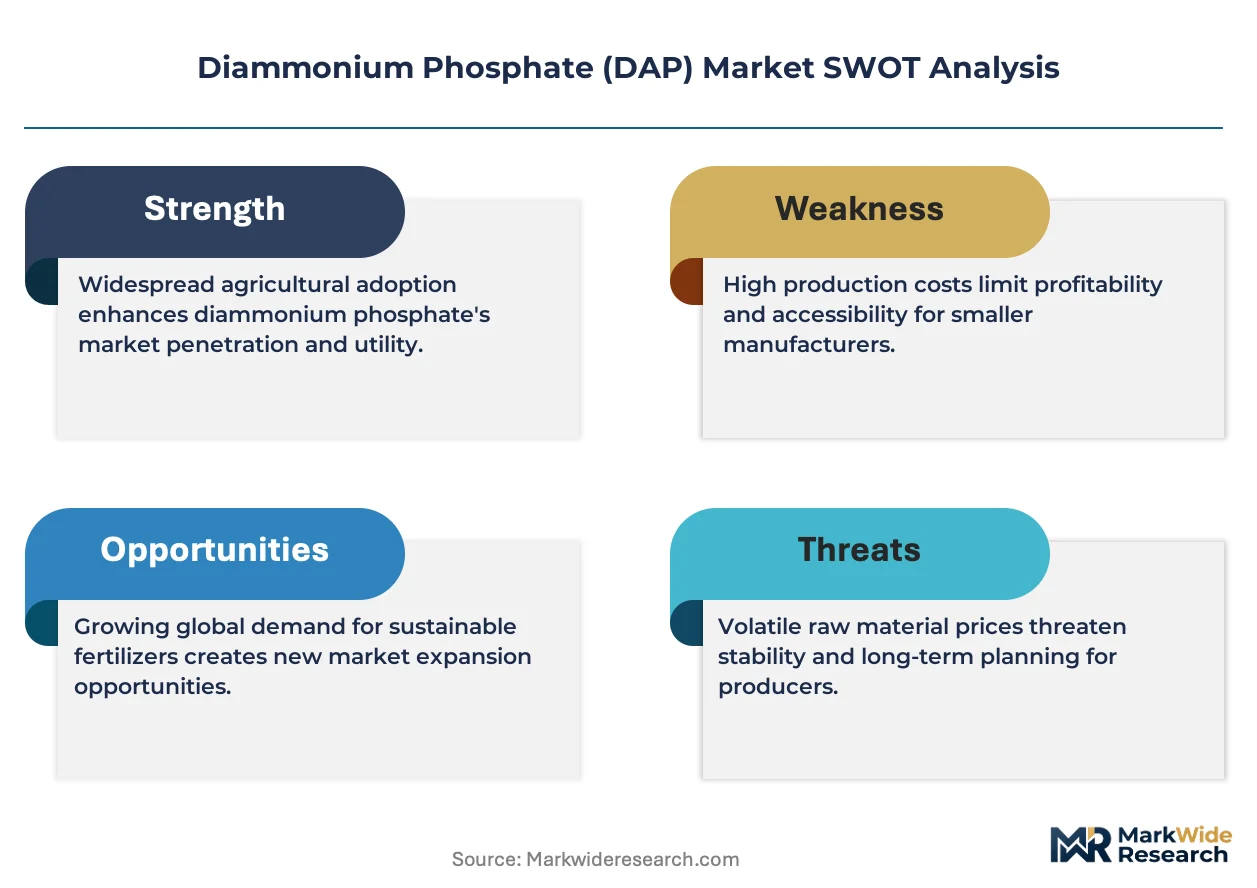
Growth Catalysts
- Triple-cropping intensity:Soybean producers in Brazil's Cerrado region are escalating DAP application rates to sustain nutrient extraction from previously phosphorus-depleted tropical soils.
- Soil testing digitization:Subscription agronomy platforms are bundling prescription nutrient recommendations with volume commitments, locking in farmer loyalty through data-driven application programs.
- Carbon border preparation:EU CBAM pilot phases are compelling exporters to document embedded emissions, advantaging supply chains with verified low-carbon phosphate rock sourcing.
Market Restraints
- Rock phosphate concentration:Moroccan and Chinese state-controlled entities dominate mineable reserves, creating geopolitical exposure for non-integrated compounders.
- Ammonia cost volatility:Natural gas price swings directly feed into DAP production economics, compressing margin predictability for merchant producers.
- Runoff liability:EPA water quality standards restrict phosphorus loading from fertilizer application, elevating compliance costs for distributors in Chesapeake Bay and Great Lakes watersheds.
Strategic Opportunities
- Enhanced-efficiency formulations:Polymer-coated and stabilized DAP variants command premium positioning where environmental regulations tighten application windows.
- Carbon-accounting services:Farm-level emissions protocols create white space for suppliers offering verified footprint documentation alongside physical product.
- Variable-rate infrastructure:Precision spreader compatibility gaps in Eastern European grain belts present equipment-and-nutrient bundling potential.
Industry Challenges
- Agronomy talent scarcity:Certified crop advisors with phosphorus management specialization are concentrated in mature markets, constraining prescription service rollout.
- Blending facility reconfiguration:Legacy granular handling infrastructure requires capital retrofit to accommodate coated product flow characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diammonium Phosphate (DAP) Market |
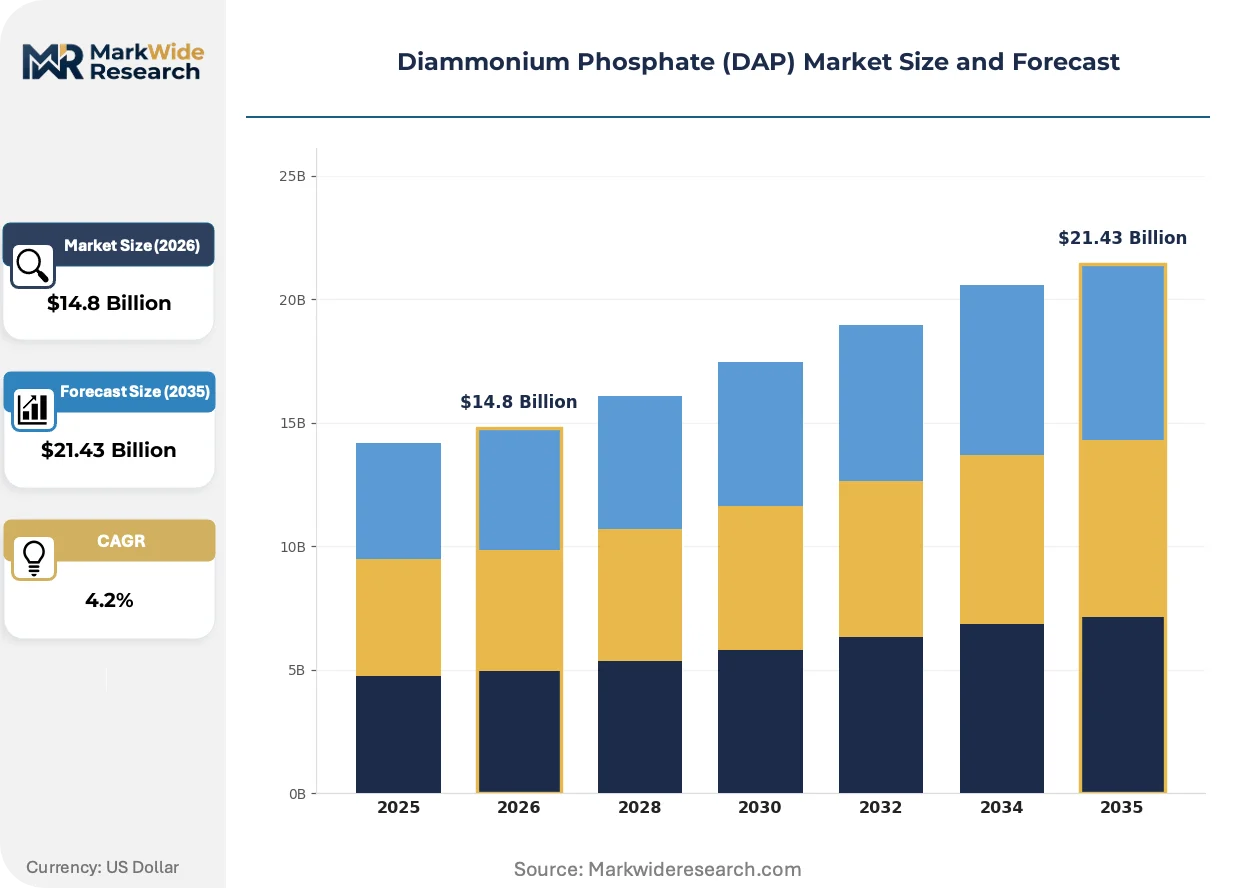
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular DAP, Powder DAP, Coated DAP, Liquid DAP Application: Agriculture, Horticulture, Hydroponics, Fertilizer Blends End User: Farmers, Agricultural Cooperatives, Distributors, Retailers Distribution Channel: Direct Sales, Online Retail, Wholesale, Agro-Distribution |
| Companies Covered | Nutrien Ltd., The Mosaic Company, OCP Group, PhosAgro Group of Companies, Yara International ASA, CF Industries Holdings, Inc., EuroChem Group AG, ICL Group Ltd., Coromandel International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diammonium Phosphate (DAP) Market Strategic Shifts
Digital soil analytics and prescription platforms are rewiring how DAP moves from manufacturer to field, replacing commodity ton transactions with data-anchored nutrient stewardship contracts.
Granular DAP with enhanced handling characteristics is overtaking standard-grade product in commercial agriculture. North American grain cooperatives are specifying dust-reduced formulations for mechanical spreader compatibility. This specification shift is compressing demand for untreated powder grades in bulk blending operations.
REACH registration requirements in Europe are tightening import chemistry documentation and safety data obligations for non-EU producers. Distributors are consolidating supplier panels to those with pre-validated regulatory packages. Baltic and North Sea port terminals are prioritizing storage for REACH-compliant cargo.
Farmer buying committees are consolidating procurement through cooperative purchasing platforms, disintermediating traditional distributor relationships. Brazilian soybean syndicates are negotiating direct offtake with Moroccan rock-integrated suppliers. This channel compression is most visible in Mato Grosso and Goiás states where cooperative membership density exceeds 70 percent.
Diammonium Phosphate (DAP) Market Segmentation
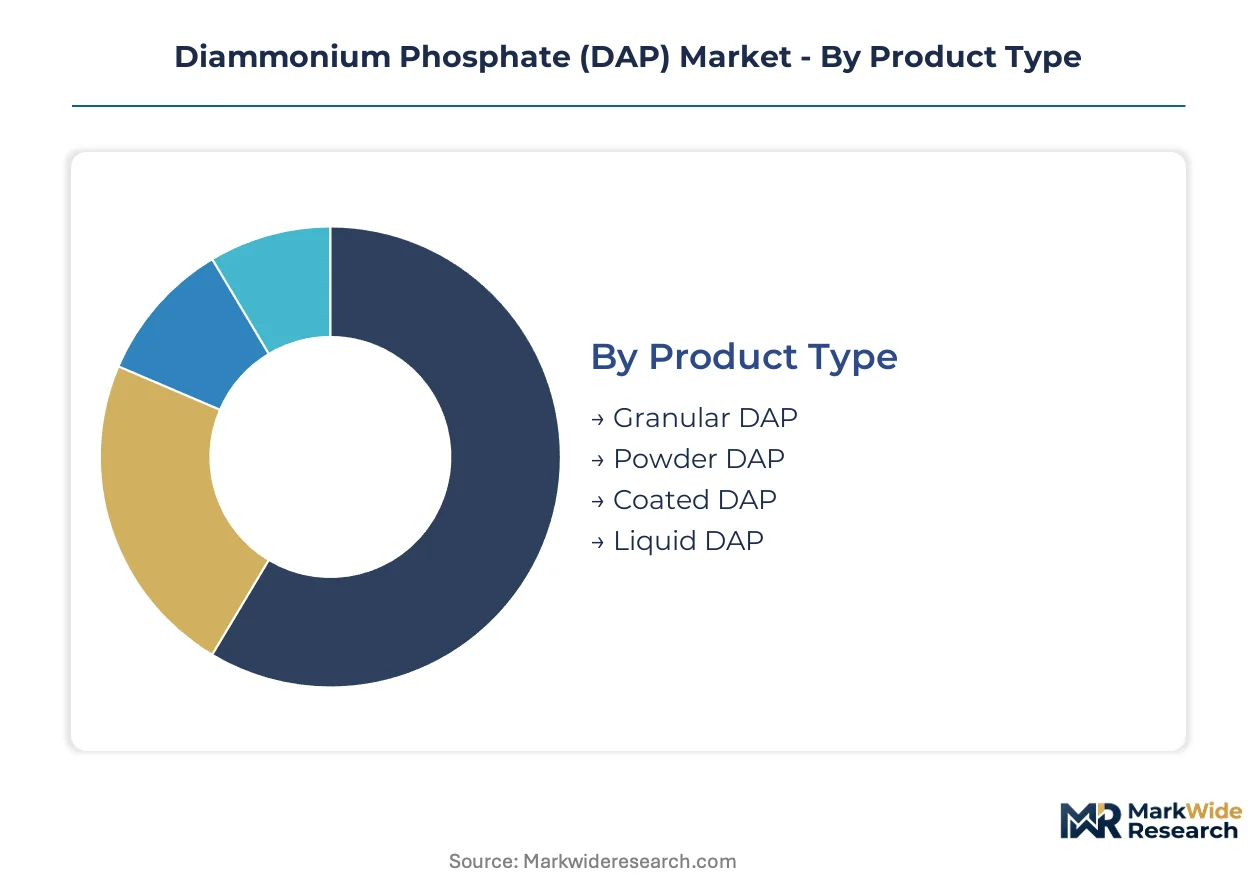
DAP segmentation reveals how product specifications, application methods, and procurement channels determine margin structures. Understanding these divisions exposes where suppliers can escape commodity pricing pressure through differentiated positioning.
Product Type:
Granular forms dominate standalone field application, while coated and liquid variants embed into precision delivery systems and controlled-release programs.
- Granular DAP:Standard-grade crystalline pellets containing 18% nitrogen and 46% phosphorus pentoxide by weight. Demand concentrates in North American Corn Belt grain operations where mechanical spreader compatibility and bulk handling infrastructure sustain procurement volumes. Dust-reduced formulations are displacing untreated grades as cooperatives specify handling performance.
- Coated DAP:Polymer-encapsulated granules engineered for sustained nutrient release and reduced phosphorus runoff. European distributors under REACH compliance pressure and Chesapeake Bay watershed retailers facing EPA loading restrictions are driving specification shifts toward these premium variants.
- Powder DAP:Finely milled product for fertilizer blend manufacturing and compound formulation. Rapid dissolution supports customized nutrient ratios in specialty agriculture.
- Liquid DAP:Concentrated solution for fertigation systems and hydroponic operations. Greenhouse vegetable producers in the Netherlands and Spain specify tank-mix compatibility.
Volume placements concentrate in Granular DAP; the faster expansion belongs to Coated DAP.
Application:
Cost tier separation runs from broad-acre commodity cropping through input-intensive protected cultivation systems.
- Agriculture:Row-crop and broad-acre cereal production consuming bulk DAP for phosphorus replenishment. Brazil's Cerrado soybean triple-cropping rotations and U.S. Corn Belt corn-soy sequences extract maximum nutrient loads, forcing escalating application rates to sustain yields.
- Fertilizer Blends:Custom-mixed compounds incorporating DAP as a nitrogen-phosphorus base. North American retail agronomy networks and European compounders source powder grades for formulation flexibility.
- Horticulture:Orchard, vineyard, and vegetable production with targeted phosphorus management. Premium pricing tolerance supports enhanced-efficiency product specifications.
- Hydroponics:Soilless cultivation systems requiring complete nutrient solution control. Dutch greenhouse clusters and Spanish Almería operations demand analytical-grade purity.
Revenue scale peaks in Agriculture; margin capture is steepest in Hydroponics.
End User:
Procurement sophistication separates price-takers from data-anchored volume committers across the customer base.
- Agricultural Cooperatives:Consolidated purchasing entities representing member farmers. Brazilian soybean syndicates in Mato Grosso and Goiás states negotiate direct offtake agreements, disintermediating traditional distribution and demanding carbon footprint documentation alongside tonnage pricing.
- Farmers:Individual producers accessing DAP through retail networks or direct manufacturer programs. Subscription soil testing platforms are converting this segment from spot buyers to contracted volume holders.
- Distributors:Regional wholesalers managing inventory and logistics for retail networks. Compliance documentation burdens under REACH and EPA standards are compressing supplier panels.
- Retailers:Point-of-sale agronomy service providers bundling product with application recommendations. Variable-rate program adoption locks in farmer loyalty.
Contract security concentrates with Agricultural Cooperatives; digital conversion is advancing fastest among Farmers.
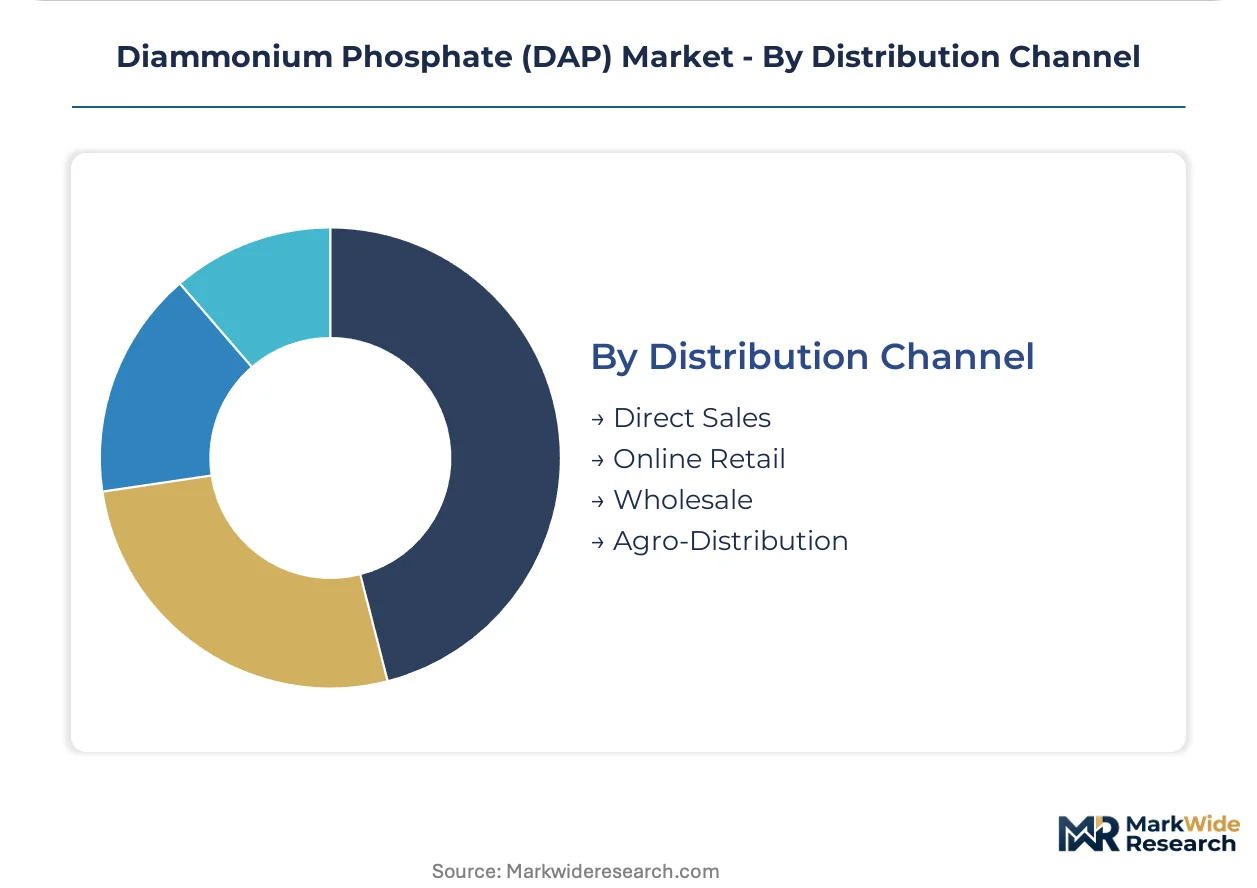
Distribution Channel:
Channel configuration determines working capital intensity and customer data access for suppliers.
- Direct Sales:Manufacturer-to-farmer or manufacturer-to-cooperative contracts eliminating intermediary margins. OCP Group's Moroccan supply chain leverages this channel for Atlantic basin bulk deliveries to Brazilian buyers.
- Agro-Distribution:Specialized agricultural supply networks combining product, equipment, and advisory services. Nutrien Ltd.'s retail network exemplifies this channel's data-capture potential.
- Wholesale:Volume trading through commodity merchants and terminal markets. Price transparency and low service attachment characterize this tier.
- Online Retail:E-commerce platforms for smaller-scale and specialty agriculture procurement. Emerging presence in horticultural input segments.
Tonnage flow dominates Agro-Distribution; channel growth is most rapid in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's port terminals handle the largest Atlantic phosphate cargo volumes, connecting Moroccan rock-integrated supply chains to European compounders and Brazilian importers. This logistics hub anchors trans-Atlantic DAP trade flows while regulatory divergence across major consuming markets reshapes sourcing patterns.
United States
Corn Belt grain operations in Iowa and Illinois drive granular DAP consumption for phosphorus replenishment after successive high-yield harvests. EPA water quality standards restrict phosphorus runoff in Chesapeake Bay and Great Lakes watersheds, pushing distributors toward coated formulations. Florida's phosphate mining corridor sustains domestic phosphoric acid supply for integrated manufacturers.
Brazil
Soybean producers in Mato Grosso and Goiás states escalate application rates to sustain triple-cropping rotations on nutrient-depleted Cerrado soils. ANVISA oversees fertilizer registration chemistry requirements that shape import documentation burdens. Santos port terminals prioritize storage capacity for direct offtake agreements between cooperatives and Atlantic basin suppliers.
China
Domestic fertilizer manufacturers face tightening feedstock constraints as MEE phosphate mining wastewater regulations elevate compliance costs and limit raw material expansion. The Yangtze River Delta blending hubs adjust procurement toward qualified supplier shortlists with verified environmental documentation. Shandong Province compounders reconfigure legacy handling infrastructure for coated product compatibility.
Morocco
OCP Group's integrated phosphate rock-to-fertilizer chain dominates Atlantic basin export supply, positioning Casablanca-Jorf Lasfar processing corridors to serve European and Latin American import demand. National mining concessions anchor cost advantages on downstream DAP production. Tangier-Med port facilities handle expanding bulk cargo volumes for Brazilian cooperative buyers.
India
Agricultural cooperatives in Gujarat and Maharashtra consolidate procurement power while demanding transparent carbon footprint documentation alongside traditional pricing terms. FSSAI governs fertilizer quality standards that importers must satisfy for market access. Kandla port terminals manage seasonal import surges ahead of monsoon planting windows.
Diammonium Phosphate (DAP) Market Competitive Environment
Capital-heavy producers compete with asset-light traders across the DAP value chain, with integrated mining-to-fertilizer operators holding structural cost advantages over merchant compounders dependent on spot phosphate rock and ammonia feedstock. Market concentration clusters around state-affiliated mining entities and North American integrated players with captive phosphate reserves. Three archetypes dominate: vertically integrated rock-to-granular manufacturers, regional blending specialists with agronomy service attachments, and commodity traders managing arbitrage between phosphate rock and finished fertilizer pricing. Competitive dynamics center on backward integration into phosphate mining concessions and forward integration into prescription agronomy platforms that lock in farmer volume commitments.
Among North American integrated producers, Nutrien Ltd. and The Mosaic Company exemplify the mining-to-retail archetype, anchoring supply security through Florida phosphate infrastructure and retail agronomy networks. OCP Group occupies a distinct position as the Atlantic basin's dominant rock-integrated exporter, leveraging Moroccan mining concessions to serve European and Brazilian import demand directly. These three entities represent the structural poles around which merchant compounders and regional blenders position for market access.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| The Mosaic Company |
| OCP Group |
| PhosAgro Group of Companies |
| Yara International ASA |
| CF Industries Holdings, Inc. |
| EuroChem Group AG |
| ICL Group Ltd. |
| Coromandel International Limited |
| Others |
Value Chain & Pricing Dynamics
Coated-to-commodity DAP grade divergence separates premium environmental-compliance product from standard bulk tonnage, with this bifurcation manifesting in both contract pricing structures and supplier qualification requirements across Atlantic basin trade flows. Moroccan rock-integrated producers capture margin premiums through verified low-carbon sourcing documentation demanded by EU CBAM pilot phases and Brazilian cooperative buyers, while merchant compounders lacking backward integration into phosphate mining concessions face compressed margins from ammonia feedstock volatility.
Pricing Analysis
Margin tightening in standard-grade granular DAP reflects natural gas price swings feeding directly into ammonia production economics, compressing predictability for non-integrated compounders dependent on spot feedstock procurement. Three-tier pricing structure across premium coated, standard granular, and economy powder levels tracks certification grade and carbon footprint verification status. Pricing pressure accelerates in Chesapeake Bay and Great Lakes watersheds as EPA water quality standards restrict phosphorus loading, elevating compliance costs for distributors. Agricultural cooperatives in Brazil's Mato Grosso state demonstrate highest price sensitivity through consolidated direct offtake negotiations, while Dutch greenhouse operators in hydroponics applications show least sensitivity due to analytical-grade purity requirements.
Supply Chain Analysis
Specialized agronomy talent shortages in Eastern European grain belts constrain precision agriculture service rollout and variable-rate program deployment. Geographic supply concentration centers on Morocco, China, and the United States as dominant phosphate rock reserve holders. Raw material dependencies draw from ammonia synthesis, phosphoric acid conversion, and polymer coating inputs. Single-source vulnerability runs through Moroccan state-controlled mining concessions dominating Atlantic basin export flows. Distribution runs through agro-distribution networks combining product with equipment and advisory services, exemplified by North American retail agronomy platforms capturing farmer data and locking in volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phosphate mining wastewater constraints under China's MEE prop feedstock scarcity, sustaining pricing power for qualified suppliers with verified environmental documentation. Capacity bottlenecks in compliant rock phosphate extraction prop the supply-constrained structure.
For Market Incumbents: Lock in backward integration into captive phosphate mining concessions or long-term rock supply agreements to defend against Moroccan and Chinese state-controlled reserve concentration. Deepen prescription agronomy platform investments to convert spot buyers into contracted volume holders, countering cooperative purchasing disintermediation. Prioritize carbon footprint verification infrastructure to qualify for EU CBAM premium access and Brazilian cooperative supplier shortlists. For New Entrants and Emerging Players: E-commerce channel routes for specialty horticulture and hydroponics inputs offer lowest incumbent saturation and highest margin capture potential. Target analytical-grade liquid DAP formulations for Dutch and Spanish greenhouse clusters where purity specifications command premium positioning. Pursue direct-to-grower digital platforms bundling soil testing subscriptions with volume commitments, bypassing traditional distributor relationships in fragmented horticultural segments. For Investors and Strategic Acquirers: Re-rating potential sits with rock-integrated compounders possessing verified low-carbon supply chains given EU carbon border adjustment mechanism rollout and farm-level emissions accounting protocol adoption. Long-term viability favors upstream reserve holders with downstream fertilizer manufacturing integration and Atlantic basin port access. Monitor MEE enforcement intensity in China as inflection indicator for feedstock availability compression and qualified supplier panel consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Mining | Moroccan and Florida reserve access anchors cost advantages against ammonia volatility. |
| Enhanced-Efficiency Formulation Development | Polymer-coated DAP variants capture EPA and REACH compliance-driven premium demand. |
| Prescription Agronomy Platform Expansion | Nutrien-style soil analytics bundling locks farmer loyalty through data-driven contracts. |
| Carbon Footprint Verification Infrastructure | EU CBAM qualification and Brazilian cooperative supplier panel access depend on documented emissions. |
| Direct Offtake Agreement Structuring | OCP Group's Atlantic basin model eliminates intermediary margins and secures volume commitments. |
Study Parameters
Document review covered customs and trade flow databases, SEC filings from listed fertilizer manufacturers, and MEE regulatory enforcement records, complemented by interviews with phosphate mining operations managers, procurement leads at Brazilian agricultural cooperatives, distribution channel partners in North American Corn Belt retail networks, and technical R&D directors at coating technology suppliers. Secondary validation drew from OCP Group sustainability disclosures, Nutrien retail network performance data, and EPA water quality standard implementation reports. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Cross-referencing historical price formation patterns with panel input from procurement managers and agronomists anchored the analytical framework across the analysis window. Segmentation dimensions modeled included product grade tier, application method, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from supply-demand balance projections incorporating phosphate rock reserve depletion curves and ammonia capacity expansion schedules. Industry-specific forecast inputs captured triple-cropping intensity in Brazil's Cerrado and variable-rate adoption rates in North American grain operations.
The model holds under sustained MEE enforcement intensity and EU CBAM phased implementation; deviation in natural gas price stability or Moroccan mining concession policy would shift supply-cost trajectories. Forecasts reflect these base-case assumptions with acknowledged sensitivity to feedstock availability shocks and carbon accounting protocol adoption velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
Single Superphosphate (SSP) Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
Russia Fertilizers Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Controlled and Slow Release Fertilizers Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
Chelate Fertilizer Market
Fertilizers
Australia Fertilizer Market
Fertilizers
Africa Specialty Fertilizer Market
Fertilizers
Europe Specialty Fertilizer Market
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
Middle East and Africa Fertilizers Market
Fertilizers
Global Micronutrient Fertilizer Market
Fertilizers
Global Controlled Release Fertilizer Market