
 Global Nitrogen Fertilizers Market | 2026-2036
Global Nitrogen Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nitrogen Fertilizers Market Intelligence
The integration of precision agriculture software and advisory services is shifting the traditional product-centric sales model. Yara International leverages its digital farming platforms to offer customized nutrient management plans. Nutrien Limited sustains its market presence through an extensive retail distribution network that provides agronomic advice. Meanwhile, CF Industries specializes in large-scale, efficient production of key nitrogen compounds like anhydrous ammonia, anchoring the commodity supply side of the industry.
Nitrogen fertilizers are synthetically derived chemical compounds, with urea being a primary example manufactured through the Haber-Bosch process. The core function of these products is to supply essential nitrogen to plants, directly boosting biomass and yield for food and feed crops. Demand from the cereal crops application segment remains foundational to market volume, reflecting global dietary staples. While granular and prilled forms are standard for broadacre farming, liquid fertilizer formulations are gaining traction in specialized horticultural uses.
Regulatory frameworks, including the European Union's Green Deal and directives from the US Environmental Protection Agency (EPA), influence application rates and product formulations. These policies aim to mitigate environmental impacts such as nutrient runoff into waterways and nitrous oxide emissions. Navigating the balance between ensuring global food security and meeting increasingly stringent environmental mandates defines the industry's primary strategic challenge.
Market Dynamics
The industry's trajectory is defined by the need to intensify crop production for global food security, clashing directly with tightening environmental mandates from regulators like the US EPA and frameworks such as the EU Green Deal.
Growth Catalysts
- Precision Agriculture Adoption:GPS-guided equipment and soil sensors enable optimized fertilizer application, maximizing crop yield per unit of input for large-scale farming.
- Cereal Crop Demand:Global reliance on staple crops like corn and wheat for food and feed underpins consistent, high-volume demand in populous nations.
- Food Security Mandates:Policies in agricultural economies like India prioritize crop intensification, ensuring stable domestic demand for essential nitrogen inputs to meet food needs.
Market Restraints
- Input Cost Volatility:The Haber-Bosch process links production costs to volatile natural gas prices, creating margin uncertainty for ammonia-based fertilizer manufacturers.
- Nutrient Management Regulation:Directives from the US EPA and EU Green Deal restrict application rates to mitigate waterway pollution, capping volume growth in developed markets.
- Geopolitical Supply Risk:Concentration of ammonia production in a few nations exposes the global supply chain to trade policy shifts and logistical disruptions.
Strategic Opportunities
- Enhanced-Efficiency Fertilizers:Developing controlled-release nitrogen products helps meet environmental rules while offering higher agronomic value and justifying premium prices to farmers.
- Sub-Saharan African Expansion:Low current fertilizer usage in Sub-Saharan Africa presents a vast market for boosting crop yields and addressing regional food security.
- Digital Agronomy Platforms:Bundling fertilizer with data-driven advisory services for custom nutrient management creates a high-margin, service-based revenue model.
Industry Challenges
- High Capital Intensity:Constructing new, large-scale ammonia and urea production plants requires massive capital investment and long lead times, limiting the entry of new competitors.
- Logistical Complexity:Managing the seasonal, geographically dispersed demand for bulk fertilizers requires a sophisticated and costly global supply chain infrastructure, including storage and transportation assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nitrogen Fertilizers Market |
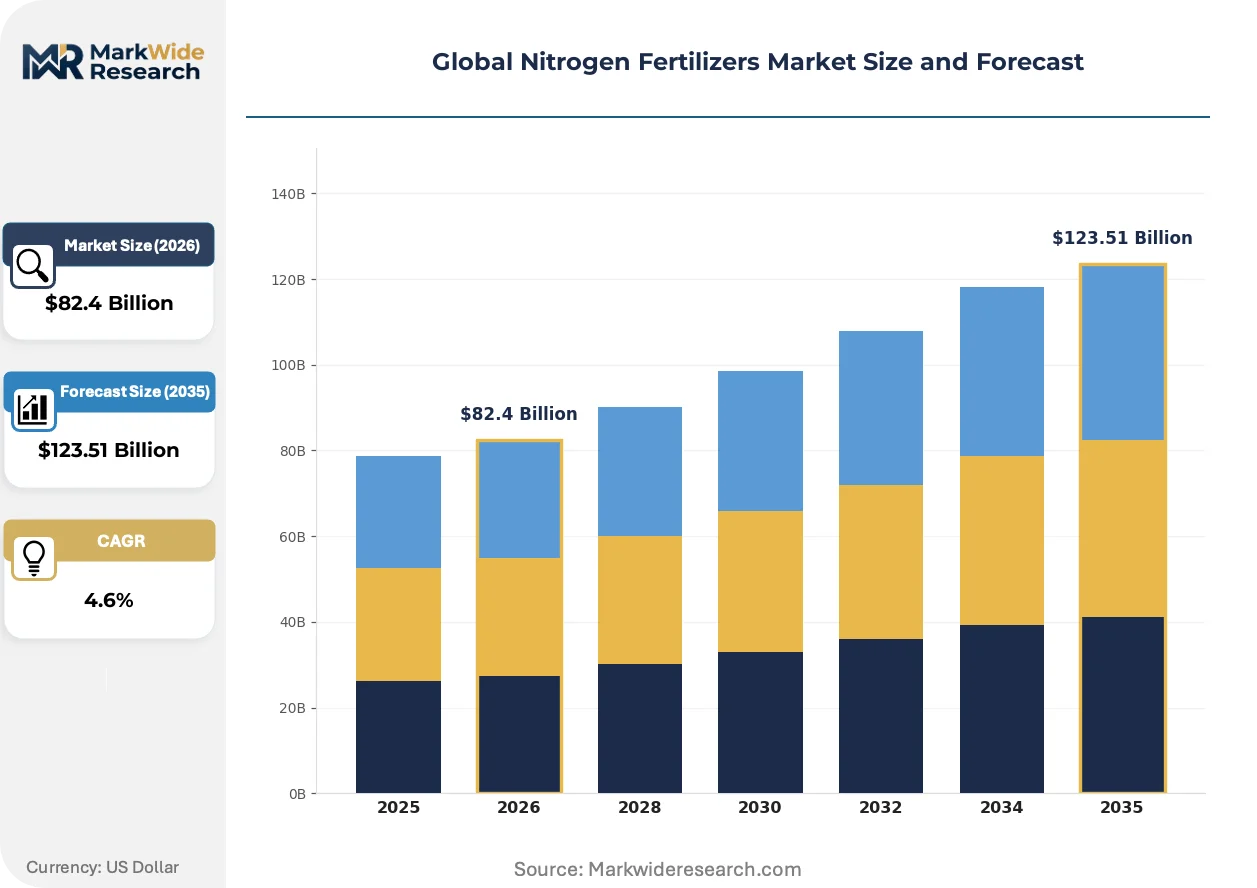
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $123.51 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, Calcium Ammonium Nitrate, Ammonium Sulfate, Anhydrous Ammonia Application: Cereal Crops, Pulses, Oilseeds, Horticulture, Plantation Crops, Floriculture Form: Granular, Prilled, Liquid, Powder Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Cooperatives, Agrochemical Dealers |
| Companies Covered | The Mosaic Company, Israel Chemicals Ltd. (ICL), CF Industries, Sociedad Química y Minera (SQM), Indian Farmers Fertiliser Co-operative Limited (IFFCO), Yara International, Haifa Group, Uralkali, Nutrien Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nitrogen Fertilizers Market Strategic Shifts & Innovations
A fundamental shift from selling a bulk commodity to delivering a technology-enabled service is redefining value in the nitrogen fertilizer industry. This evolution is driven by pressures for greater application efficiency and environmental accountability across global agriculture.
Digital farming platforms integrate satellite imagery, soil sensor data, and weather analytics to generate variable-rate application prescriptions. Large commercial farms and agricultural cooperatives are steadily adopting these tools to maximize input efficiency. This software-led approach is absorbing the traditional role of generalized agronomic advice, replacing it with data-driven, site-specific recommendations.
The European Union's Green Deal, through its Farm to Fork strategy, sets specific targets for reducing nutrient losses and fertilizer use. This policy directly incentivizes the development and adoption of enhanced-efficiency fertilizers that release nitrogen more slowly. Fertilizer manufacturers serving the European market are reformulating products and investing in nitrification inhibitors to meet these stringent environmental performance standards.
Farmers are increasingly purchasing comprehensive agronomic outcomes rather than just tons of urea or ammonia. This behavior disrupts traditional distributor relationships based on volume, favoring integrated providers that bundle products with soil testing and yield-linked services. The shift is most pronounced in North American and Australian agriculture, where precision technology adoption is highest.
Global Nitrogen Fertilizers Market Segmentation
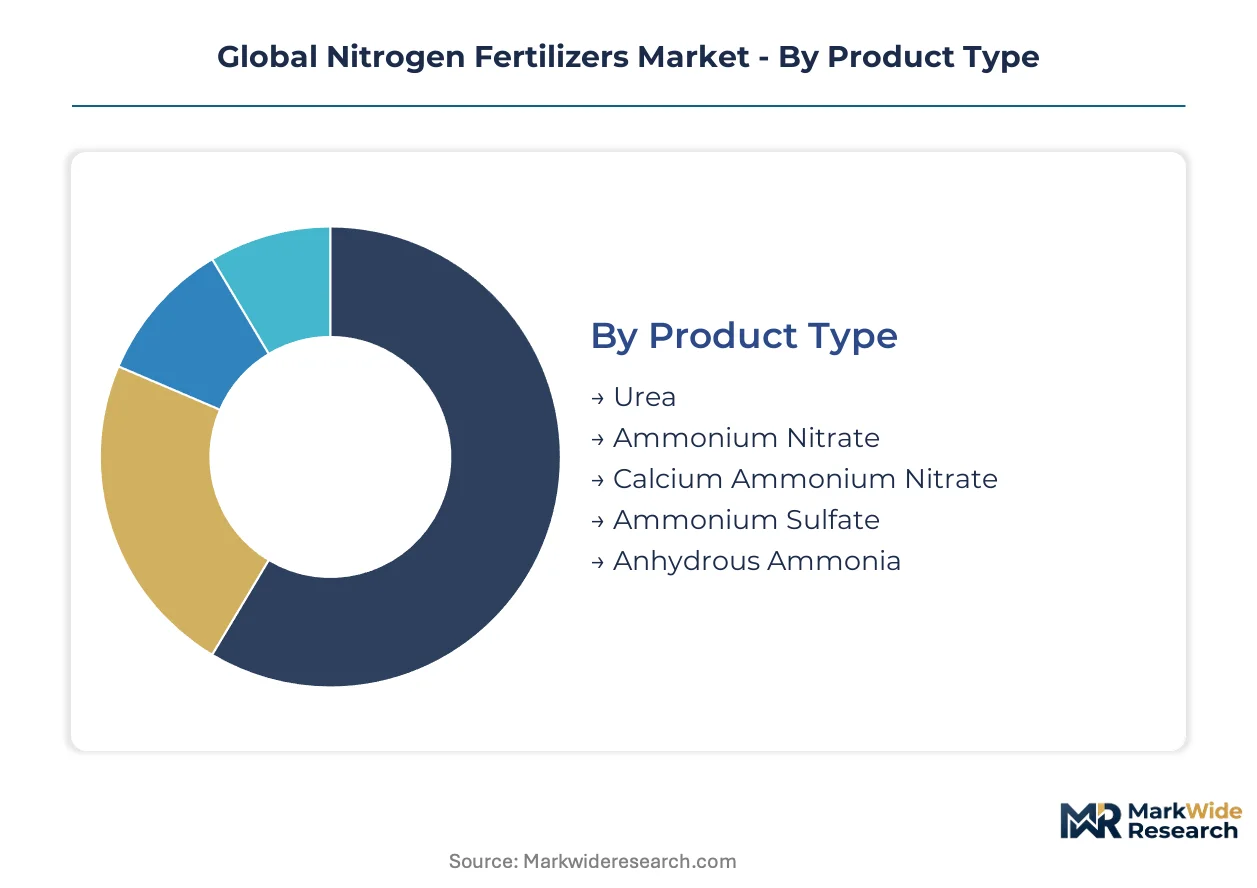
The nitrogen fertilizers market serves a diverse agricultural landscape, with segmentation revealing distinct purchasing behaviors and product preferences among farmers. Understanding these divisions allows manufacturers to tailor product offerings and distribution strategies effectively across different farming scales and crop types.
Product Type:
The chemical composition of nitrogen fertilizers differentiates buyers based on nutrient release profiles and application methods required for specific crops and soil conditions.
- Urea:This organic compound is a highly concentrated nitrogen source, synthetically produced from ammonia and carbon dioxide. Demand remains consistently high in agricultural economies like India for broadacre cereal crop cultivation due to its cost-effectiveness.
- Anhydrous Ammonia:Comprising pure ammonia gas, this compound delivers the highest nitrogen content directly into the soil as a liquid under pressure. Large commercial farms in North America utilize it for its efficiency and immediate nutrient availability.
- Ammonium Nitrate:A crystalline salt, ammonium nitrate provides both quick and slow-release nitrogen, suitable for various soil types.
- Calcium Ammonium Nitrate:This granular fertilizer offers a balanced nitrogen source with calcium, promoting soil health in European agricultural systems.
- Ammonium Sulfate:Delivering both nitrogen and sulfur, ammonium sulfate supports crops with high sulfur requirements.
Urea leads volumes today; Anhydrous Ammonia is gaining share fastest.
Application:
Crop-specific nutritional requirements dictate the choice of nitrogen fertilizer, influencing purchasing decisions based on desired yield and quality outcomes.
- Cereal Crops:These staple food crops, including wheat, corn, and rice, require significant nitrogen inputs to maximize grain yield and protein content. Global food security mandates in populous nations like China drive consistent demand.
- Horticulture:This segment encompasses fruits, vegetables, and ornamental plants, where precise nutrient delivery and enhanced-efficiency formulations are increasingly valued. Specialized liquid fertilizers are gaining traction for these high-value crops.
- Pulses:Crops such as lentils and chickpeas benefit from nitrogen supplementation to optimize growth, though their nitrogen-fixing capabilities reduce overall requirements.
- Oilseeds:Soybeans, canola, and sunflowers utilize nitrogen fertilizers to boost oil content and overall biomass production.
- Plantation Crops:Large-scale cultivation of crops like coffee, tea, and rubber relies on consistent nitrogen supply for sustained productivity.
- Floriculture:Nitrogen inputs support vigorous growth and vibrant blooms in flower production, often using specialized formulations.
Cereal Crops sustain the largest market share, while Horticulture demonstrates accelerated expansion.
Form:
The physical state of nitrogen fertilizers influences handling, storage, and application methods, differentiating buyer preferences based on farm size and equipment availability.
- Granular:This solid form consists of uniform pellets, offering ease of handling, storage, and precise broadcast application across large fields. Broadacre farming in regions like Brazil heavily relies on granular products.
- Liquid:These formulations are dissolved in water, allowing for uniform distribution through irrigation systems or foliar sprays. Precision agriculture adoption in Australia is increasing liquid fertilizer use for targeted nutrient delivery.
- Prilled:Produced as small, spherical particles, prilled fertilizers are commonly used for manual application and in areas with less sophisticated machinery.
- Powder:Fine powdered forms can be mixed with water for spray applications or incorporated into other fertilizer blends.
Granular forms account for the largest volume, with liquid formulations experiencing the steepest expansion trajectory.
Distribution Channel:
The pathway through which nitrogen fertilizers reach farmers varies by region and farm size, impacting pricing and accessibility for different customer segments.
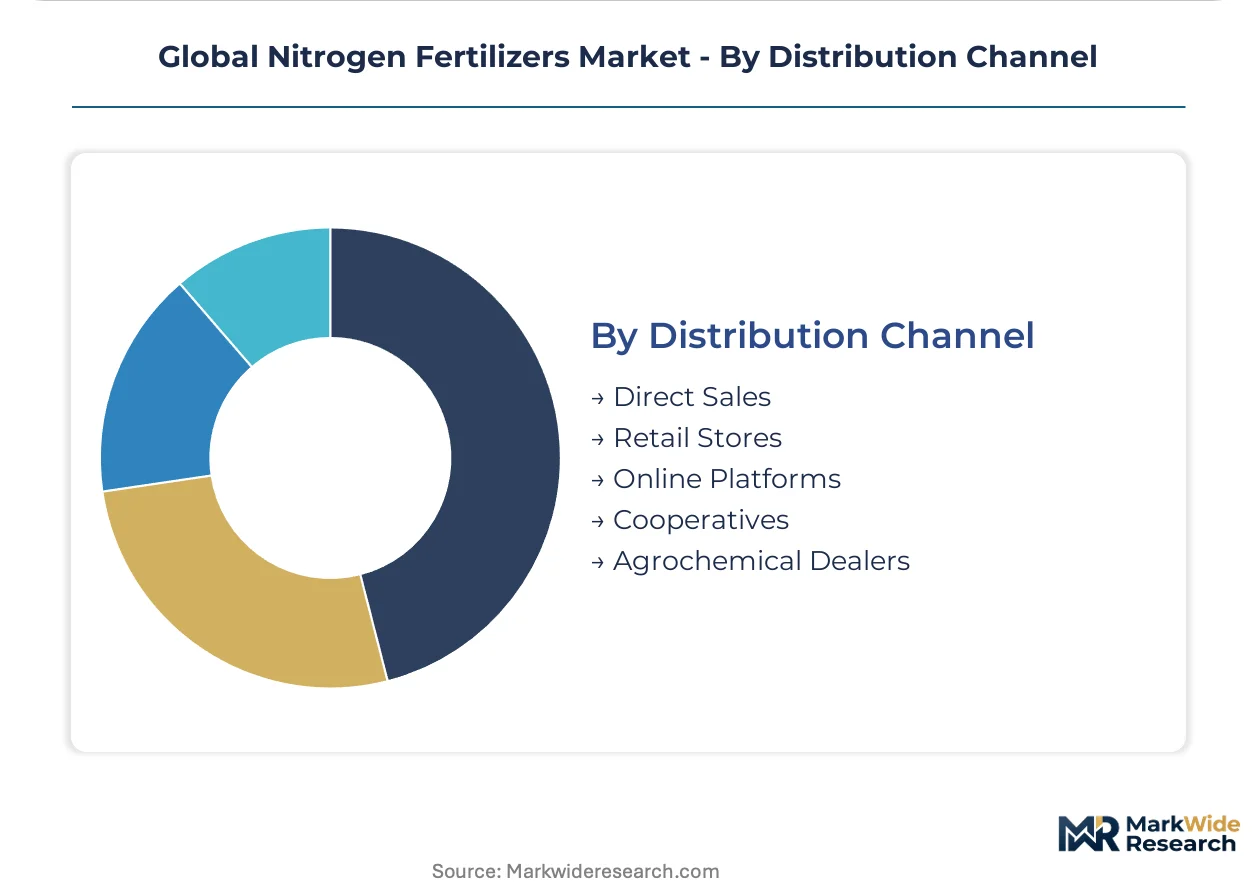
- Direct Sales:Large agricultural enterprises often purchase directly from manufacturers or major distributors, securing bulk quantities and customized supply agreements. This channel caters to high-volume buyers seeking efficiency.
- Retail Stores:Local agricultural retail outlets provide a convenient purchasing point for small and medium-sized farmers, offering a range of products and immediate availability. These stores are vital in regions with fragmented landholdings.
- Online Platforms:E-commerce channels are emerging for purchasing fertilizers, offering price comparisons and direct delivery, appealing to tech-savvy farmers.
- Cooperatives:Farmer cooperatives aggregate demand from members, enabling bulk purchases and often providing agronomic advice alongside product sales.
- Agrochemical Dealers:These specialized dealers offer a broad portfolio of agricultural inputs, including fertilizers, pesticides, and seeds, often coupled with expert advice.
Direct Sales represent the largest share of transactions, while Online Platforms are exhibiting rapid growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's substantial cereal crop cultivation drives significant nitrogen fertilizer demand, contrasting with the United States' focus on precision agriculture for efficiency. Both nations navigate the complex balance between maximizing food production and mitigating environmental impacts. This dynamic shapes regional market trajectories across diverse agricultural landscapes.
India
Demand for nitrogen fertilizers in India stems from extensive cereal crop cultivation and government food security mandates. The Indian government's emphasis on crop intensification supports consistent input requirements. Uttar Pradesh, a major agricultural state, sees high urea consumption for staple food production.
United States
Large commercial farms in the United States utilize nitrogen fertilizers for corn and wheat production, driving demand for high-efficiency products. The US Environmental Protection Agency (EPA) regulates application rates, influencing product formulation and usage. The Corn Belt region, including Iowa, remains a core market for anhydrous ammonia applications.
Brazil
Brazil's expanding broadacre farming for soybeans and corn fuels substantial demand for granular nitrogen fertilizers. The country's agricultural policies encourage productivity improvements to meet global export needs. Mato Grosso, a key agricultural frontier, experiences high fertilizer consumption for large-scale crop cultivation.
China
China's vast agricultural sector requires significant nitrogen inputs for staple crops like rice and wheat, driven by domestic food security goals. Environmental regulations from the Ministry of Ecology and Environment (MEE) promote efficient fertilizer use and reduced runoff. Shandong Province, a major agricultural hub, focuses on advanced nutrient management practices.
Germany
European agricultural systems, particularly in Germany, demand nitrogen fertilizers for diverse crops, including grains and sugar beets. The EU Green Deal mandates reductions in nutrient losses and fertilizer use, impacting product formulations. Bavaria, a leading agricultural state, adopts enhanced-efficiency fertilizers to comply with environmental standards.
Global Nitrogen Fertilizers Market Key Industry Players
Top-tier vendors anchor the global nitrogen fertilizers market, while regional specialists and niche players address specific local demands. The market structure integrates large-scale commodity producers with technology-driven service providers offering digital agronomy platforms. Strategic archetypes include integrated nutrient suppliers, pure-play ammonia manufacturers, and enhanced-efficiency fertilizer developers. Companies pursue capacity expansion and digital platform development to secure market share and differentiate offerings.
Integrated nutrient suppliers, such as Nutrien Limited, exemplify a broad retail distribution network combined with agronomic advice. CF Industries anchors the commodity supply side with its large-scale, efficient production of key nitrogen compounds like anhydrous ammonia. Yara International represents the shift towards technology-enabled services, leveraging digital farming platforms to offer customized nutrient management plans. These entities illustrate the diverse approaches to market presence and value creation within the industry.
| Leading Market Players |
|---|
| The Mosaic Company |
| Israel Chemicals Ltd. (ICL) |
| CF Industries |
| Sociedad Química y Minera (SQM) |
| Indian Farmers Fertiliser Co-operative Limited (IFFCO) |
| Yara International |
| Haifa Group |
| Uralkali |
| Nutrien Limited |
| Others |
Cost & Logistics Intelligence
Product differentiation between bulk commodities and enhanced-efficiency formulations creates a two-tiered market, influencing both pricing strategies and supply chain configurations. Commodity nitrogen fertilizers often trade at spot prices, while specialized products command premiums through dedicated distribution channels.
Pricing Analysis
Capacity additions in China and the Middle East are reshaping price floors for commodity nitrogen fertilizers. The dominant pricing structure combines commodity spot pricing for bulk products like urea with contract-based long-term offtake agreements for industrial buyers. Price differentiation stems from quality grade, particularly for enhanced-efficiency formulations, and from geographic delivery cost. Pricing pressure stems from volatile natural gas prices, which directly impact ammonia production costs. Cereal crop farmers, operating on tight margins, represent the most price-sensitive segment, while horticultural users prioritize performance and are less sensitive to price fluctuations.
Supply Chain Analysis
Local content mandates in agricultural economies like India reshape sourcing preferences for key inputs. Geographic supply concentration for ammonia production centers on nations with abundant natural gas reserves, including the United States, China, and several Middle Eastern countries. The industry relies heavily on natural gas as a primary raw material for the Haber-Bosch process. Geopolitical supply risk, stemming from trade policy shifts, represents a significant structural vulnerability. Downstream distribution runs through extensive retail networks, direct sales to large commercial farms, and agricultural cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Nitrogen Fertilizers Market is transitioning into a late-cycle quality story, driven by a pronounced demand-shift toward premium, environmentally compliant formulations. This evolution reshapes strategic imperatives across the value chain.
For Market Incumbents:
Deepen vertical integration into digital agronomy platforms to offer comprehensive nutrient management services. This strategy helps mitigate margin pressure from volatile input costs and tightening environmental regulations. Invest in enhanced-efficiency fertilizer research and development to meet increasingly stringent environmental mandates from the EU Green Deal and US EPA. Expand strategic production capacity in regions with stable natural gas supply to counter geopolitical supply risk.
For New Entrants and Emerging Players:
The EU Green Deal in Europe opens a window for specialized enhanced-efficiency fertilizer producers. Target the underserved Sub-Saharan African market, where low current fertilizer usage presents significant yield improvement opportunities. Focus on horticultural applications with specialized liquid formulations, which offer higher margins and require precise nutrient delivery. A robust go-to-market angle involves bundling sustainable product offerings with data-driven advisory services, appealing to environmentally conscious farmers.
For Investors and Strategic Acquirers:
Consolidation pressure builds where digital capabilities and advanced product formulations offer a competitive edge. Over the long term, the market remains vital for global food security, yet environmental compliance will dictate future growth. Acquisition targets should include technology providers specializing in precision agriculture software or manufacturers of enhanced-efficiency fertilizers. The signal to watch for inflection is the accelerated adoption rate of digital farming platforms across major agricultural regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Digital Agronomy Platforms | Yara International can enhance farmer loyalty and shift to a service-based revenue model. |
| Invest in Enhanced-Efficiency Formulations | CF Industries can meet EU Green Deal mandates and command premium pricing. |
| Secure Long-Term Natural Gas Contracts | Nutrien Limited can stabilize production costs and reduce input cost volatility. |
| Target Sub-Saharan African Market | Manufacturers can address regional food security and unlock new demand. |
| Acquire Precision Agriculture Software Firms | Integrated players can offer comprehensive, data-driven nutrient management plans. |
Research Approach
Direct dialogue with fertilizer manufacturers, large commercial farmers, agronomists, distribution channel partners, and regulatory officials provided critical primary insights. This qualitative grounding was triangulated with extensive secondary validation from government agricultural reports, environmental agency directives like those from the US EPA and EU, corporate annual reports, and trade association publications. Both bottom-up and top-down approaches ensured comprehensive market sizing and segmentation.
The quantitative model produced detailed volume and value forecasts across the analysis window, segmented by product type, application, form, distribution channel, and regional agricultural policy. Compound annual growth rates were derived through a combination of regression analysis and market share projections. Key industry-specific forecast inputs included global cereal crop production forecasts and natural gas price trends, which significantly influence production costs.
Revisions become necessary when geopolitical conflicts impacting energy supply, unforeseen climate events, or rapid shifts in agricultural subsidies materialize. Forecasts reflect assumptions regarding technological advancements and regulatory stability over the projection horizon. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Europe Micronutrient Fertilizer Market
Fertilizers
China Fertilizers Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
Organic Fertilizers Market
Fertilizers
EMEA Secondary Macronutrients Market
Fertilizers
Europe Controlled Release Fertilizer Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
Asia-Pacific Fertilizers Market
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
Russia Fertilizers Market
Fertilizers
Soil Conditioners Market
Fertilizers
Water Soluble NPK Fertilizers Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
Urea Fertilizers Market