
 Fertilizer Additives Market | 2026-2036
Fertilizer Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Fertilizer Additives Market Intelligence
The expansion of direct-to-farmer sales channels, including digital platforms and agricultural cooperatives, is rewriting traditional distribution models. BASF SE leverages its extensive R&D capabilities to develop advanced coating and anti-caking agents. Koch Agronomic Services specializes in nitrogen stabilizers and nutrient management solutions. Meanwhile, Clariant AG competes on the basis of its specialized portfolio for granular fertilizers.
Fertilizer additives are chemical or biological substances incorporated into fertilizers to improve their physical properties, nutrient stability, and efficacy. These materials include anti-caking agents to prevent clumping, coatings to control nutrient release rates, and dust control agents formulated with mineral oils or polymers. Additives for nitrogenous fertilizers command a significant portion of the market, driven by the need to minimize nitrogen loss. Within the form segment, coated and granular additives are gaining share over powders due to their superior handling characteristics and controlled-release benefits.
Regulatory frameworks, including the US EPA's guidelines on nutrient management and the EU's REACH regulation on chemical safety, directly influence product formulation. In China, national standards set by the MEE are pushing for additives that reduce soil and water pollution from fertilizer application. Stakeholders must now decide how to balance investments in biodegradable additives with performance requirements for conventional large-scale agriculture.
Market Dynamics
The central force shaping the fertilizer additives market is the global imperative to increase agricultural productivity on finite arable land amidst tightening environmental regulations. Policies like the European Union's Green Deal and standards from China's MEE are mandating reduced nutrient loss, pushing innovation beyond simple conditioning agents.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal and its Farm to Fork strategy create demand for additives that enhance nutrient use efficiency and reduce environmental runoff, directly supporting coated fertilizers and nitrogen stabilizers.
- Precision Agriculture:The adoption of variable rate technology in farming requires fertilizers with predictable, controlled-release characteristics, a function directly enabled by advanced polymer coatings and specialized granular additives.
- Intensive Farming Practices:In major agricultural economies like Brazil and the United States, large-scale farming operations depend on additives to maximize nutrient uptake and protect fertilizer investment, ensuring high crop yields per hectare.
Market Restraints
- Cost Sensitivity:The higher upfront cost of specialty additives compared to untreated bulk fertilizers remains a significant adoption barrier for smallholder farmers and in price-sensitive agricultural markets globally.
- Performance Trade-Offs:Some biodegradable and bio-based additives exhibit lower durability and less precise nutrient release control compared to conventional synthetic polymers, limiting their use in certain demanding applications.
- Feedstock Volatility:A substantial portion of additives, including coating polymers and dust control oils, are derived from petrochemicals, linking their production costs directly to the volatile global oil and gas market.
Strategic Opportunities
- Bio-Fertilizer Enhancement:A nascent opportunity exists in developing additives specifically for biological fertilizers to improve the viability, stability, and handling of microbial and biostimulant products during storage and application.
- Emerging Market Penetration:Government initiatives promoting sustainable agriculture in Southeast Asian nations are creating new markets for nutrient management solutions, including slow-release and stabilized fertilizer technologies.
- Smart Coatings:Integrating micro-sensors or indicator compounds into fertilizer coatings presents an opportunity to create "smart" fertilizers that provide real-time data on nutrient release, linking them to digital farming platforms.
Industry Challenges
- Regulatory Fragmentation:Manufacturers face the operational challenge of formulating products that comply with a patchwork of disparate chemical safety and environmental regulations, such as the EU's REACH and the US EPA's guidelines.
- Farmer Education and Training:Realizing the full value of advanced additives requires proper application, which poses a significant logistical challenge in educating a globally fragmented base of end-users on new agricultural practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertilizer Additives Market |
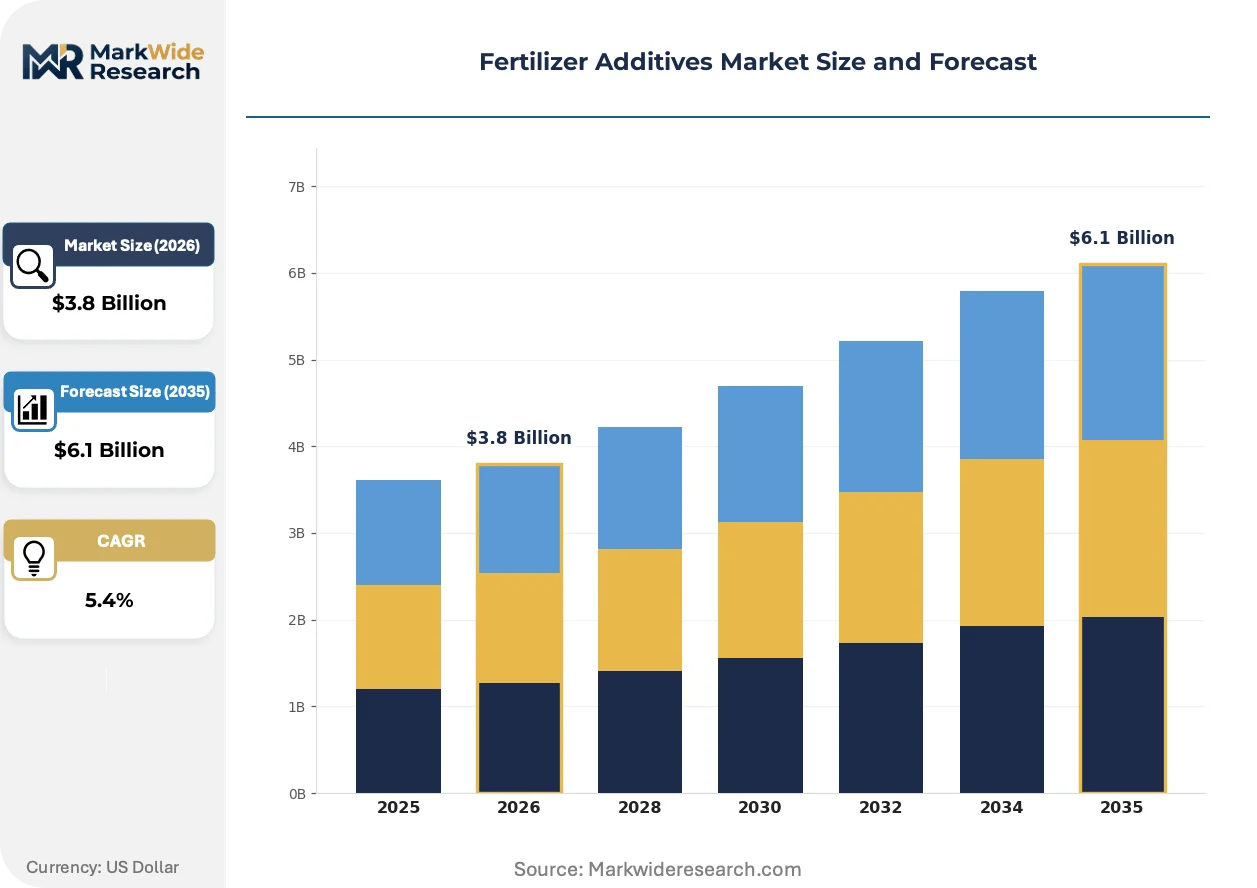
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Nitrogenous, Phosphatic, Potassic, Micro-nutrient Application: Agricultural, Horticultural, Turf Management, Landscape Form: Granular, Liquid, Powder, Coated Distribution Channel: Direct Sales, Online Retailers, Wholesale, Cooperatives |
| Companies Covered | Corteva Agriscience, BASF SE, Clariant AG, Kao Corporation, Koch Agronomic Services, Arrmaz, ChemSol LLC, Michelman, Inc., Tolsa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertilizer Additives Market Strategic Shifts & Innovations
Intensifying environmental scrutiny and the rise of data-driven agriculture are transforming additives from passive components into active, functional technologies. The market's evolution is defined by a shift toward materials that actively manage nutrient delivery, enhance soil biology, and integrate with digital farming ecosystems.
Biological additives, including microbial inoculants and plant biostimulants, are being formulated directly into fertilizer products. Specialty crop segments and organic farming operations are the earliest adopters of these advanced formulations. This development is hybridizing the boundary between conventional chemical additives and biological soil treatments, creating multifunctional products that offer both nutrient management and soil health benefits.
China's Ministry of Ecology and Environment (MEE) has enacted stringent GB standards to curb pollution from agricultural runoff. This national policy compels fertilizer manufacturers to incorporate proven technologies like nitrogen stabilizers and urease inhibitors into their product lines to meet efficiency targets. The nitrogenous fertilizer segment is most directly impacted, accelerating reformulation efforts to align with the country's soil and water protection goals.
A notable shift in distribution is occurring as direct-to-farmer (D2F) models, enabled by digital commerce platforms and strengthened agricultural cooperatives, challenge traditional, layered distribution networks. This disintermediation allows for more consultative selling and provides manufacturers with direct feedback from end-users. The trend is most visible in large agricultural markets with high digital adoption, including parts of North America, Brazil, and India.
Fertilizer Additives Market Segmentation
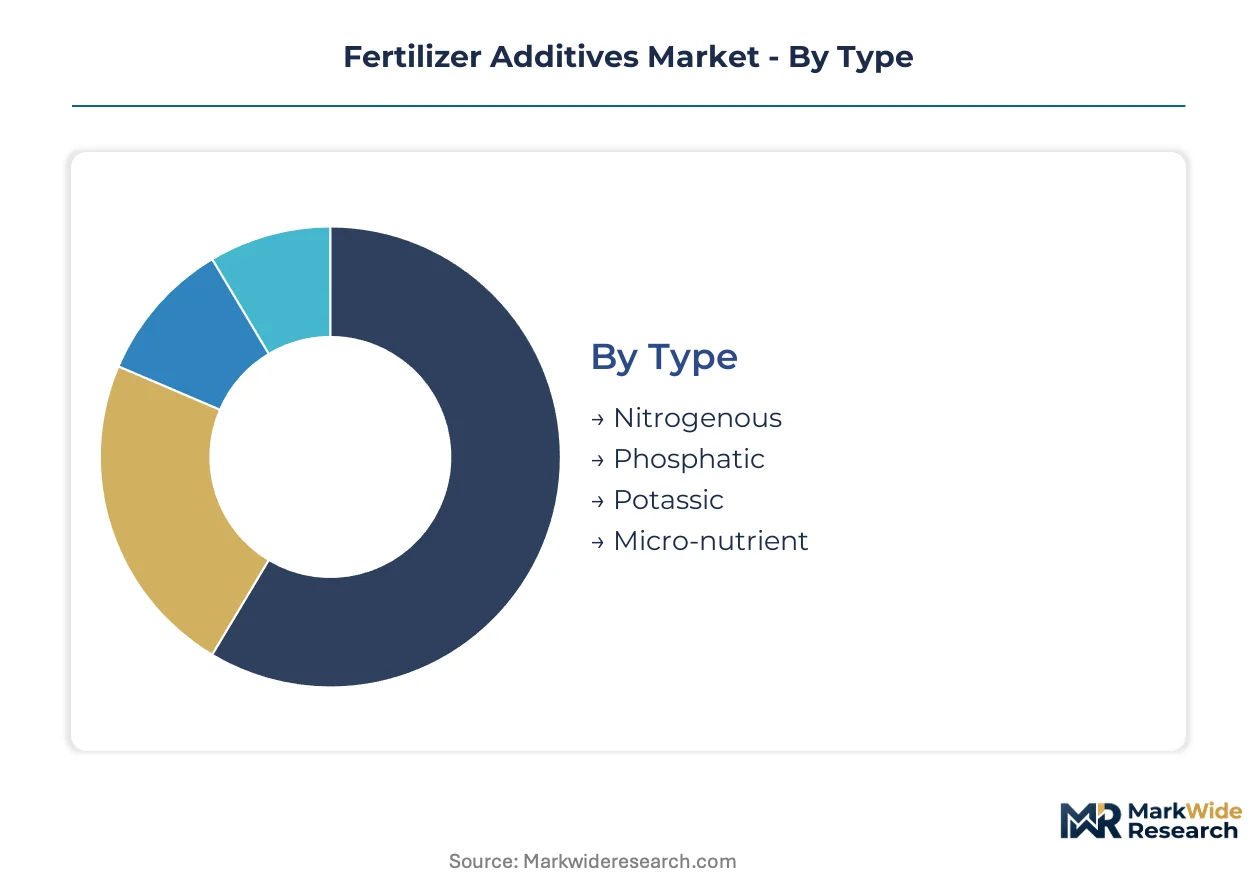
The fertilizer additives market segmentation illustrates diverse product applications and evolving distribution strategies. Understanding these distinct segments helps manufacturers align their solutions with specific agricultural needs and regional farming practices. Stakeholders develop targeted additive portfolios to enhance nutrient delivery across various crop types and cultivation methods.
Type:
The maturity spectrum within fertilizer types indicates established and developing areas for additive integration.
- Nitrogenous:Nitrogenous fertilizers represent the largest segment due to their critical role in plant growth and yield maximization. Additives like nitrogen stabilizers and urease inhibitors are crucial to minimize volatilization and leaching, particularly in large-scale corn and wheat cultivation across the United States.
- Micro-nutrient:Micro-nutrient additives address specific plant deficiencies, enhancing crop quality and stress resistance in high-value specialty crops. Chelating agents and specific carriers improve the bioavailability of essential elements like zinc and boron, supporting intensive horticulture in regions like California.
- Phosphatic:Additives improve phosphorus availability and reduce fixation in diverse soil types, boosting root development.
- Potassic:Enhancers for potassium uptake are vital for fruit and vegetable production, improving crop resilience.
Nitrogenous additives handle the majority of throughput; micro-nutrient additives are the fastest mover on share.
Application:
Volume requirements differentiate the application segments, influencing additive formulation and delivery.
- Agricultural:The agricultural segment dominates additive consumption, driven by large-scale production of staple crops such as corn, soy, and wheat. Additives here focus on maximizing nutrient use efficiency and minimizing environmental impact across vast farming operations in Brazil.
- Horticultural:Horticultural applications involve high-value fruits, vegetables, and flowers, where precise nutrient delivery and enhanced product quality are paramount. Additives improve nutrient uptake and shelf life for intensive greenhouse operations in the Netherlands.
- Turf Management:Additives ensure consistent greening and soil health for sports fields and golf courses in urban areas.
- Landscape:Residential and commercial landscape projects utilize additives for aesthetic plant vitality and reduced maintenance requirements.
The agricultural segment drives the bulk of additive demand, while horticultural applications exhibit rapid expansion.
Form:
Customer preferences and handling characteristics significantly influence the demand for different additive forms.
- Coated:Coated additives are gaining traction for their controlled-release properties, which reduce nutrient loss and extend nutrient availability over time. These advanced forms support precision agriculture practices, particularly for high-value crops in the US.
- Granular:Granular additives offer ease of handling and uniform distribution when blended with solid fertilizers. Their robust nature makes them suitable for large-scale mechanical application in major agricultural economies.
- Liquid:Liquid additives integrate easily into fertigation systems for efficient nutrient delivery in specialized farming.
- Powder:Powdered additives are cost-effective but require careful handling to prevent dust and caking during application.
Coated forms are experiencing the fastest growth, driven by advanced nutrient management needs, while granular forms maintain a substantial market presence.
Distribution Channel:
Market access and supply chain concentration dictate the effectiveness of various distribution channels for fertilizer additives.
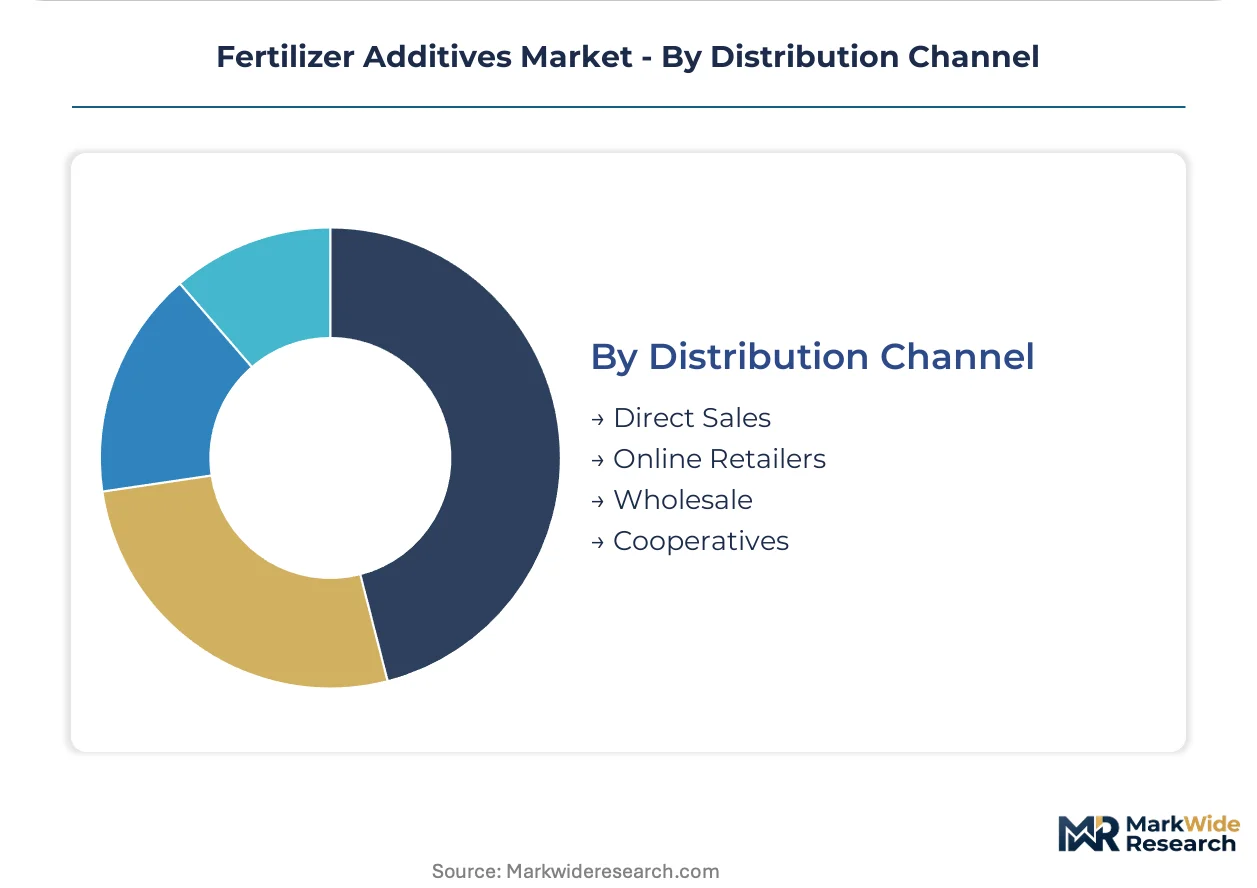
- Direct Sales:Direct sales channels facilitate direct engagement between manufacturers and large-scale farming operations, enabling customized technical support and product education. This model is prevalent for specialized additives requiring specific application knowledge in regions like North America.
- Cooperatives:Agricultural cooperatives serve as crucial distribution points, leveraging collective purchasing power and providing localized support to member farmers. These networks are particularly strong in European countries, ensuring broad access to new additive technologies.
- Online Retailers:Digital platforms offer convenience and broader product selection for smaller volume purchases by individual farmers.
- Wholesale:Traditional wholesale networks provide bulk distribution to smaller retailers and regional distributors across established markets.
Wholesale channels still distribute significant volumes, but direct sales and cooperatives are capturing increasing market share through specialized services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global agricultural trade routes and established fertilizer supply chains underwrite the geographic distribution of fertilizer additive demand. These critical networks facilitate the movement of raw materials and finished products, influencing where advanced nutrient management solutions are most effectively deployed. Regulatory initiatives and intensive farming practices further shape regional consumption patterns.
United States
The United States market demands fertilizer additives for large-scale corn and wheat cultivation, focusing on maximizing nutrient use efficiency. US EPA guidelines on nutrient management directly influence product formulation and application methods. Agricultural hubs in the Midwest, like those around Illinois, concentrate demand for nitrogen stabilizers and controlled-release coatings.
Brazil
Brazil's vast agricultural sector, particularly its large-scale soybean and sugarcane operations, drives significant demand for fertilizer additives. The country's Ministry of Agriculture, Livestock, and Food Supply (MAPA) promotes technologies that enhance soil health and reduce environmental impact. Mato Grosso, a major agricultural state, is a focal point for additive consumption aimed at boosting crop yields per hectare.
China
China's fertilizer additives market is shaped by stringent national standards from the MEE, which target reduced soil and water pollution. These regulations compel manufacturers to integrate technologies like urease inhibitors into nitrogenous fertilizers. Provinces such as Shandong, a key agricultural and chemical manufacturing region, are actively re-formulating products to meet efficiency targets.
Germany
Germany's precision agriculture sector and horticultural operations create specific demand for advanced fertilizer coatings and specialized granular additives. The European Union's Green Deal and its Farm to Fork strategy mandate reduced nutrient runoff and enhanced nutrient use efficiency. The Rhine-Ruhr region, with its chemical industry presence, supports research and production of innovative additive solutions.
India
India's agricultural landscape requires fertilizer additives to improve nutrient uptake and address soil deficiencies across diverse crop types. Government initiatives promoting sustainable agriculture and improved farmer incomes are expanding the market for slow-release technologies. States like Punjab, a major food grain producer, are seeing increased adoption of fortified fertilizers to sustain productivity.
Fertilizer Additives Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing critical raw materials and intermediate solutions. The market exhibits a tiered structure, with large multinational chemical companies offering broad portfolios alongside niche players specializing in specific additive functionalities. Strategic partnerships with agricultural cooperatives and technology licensing agreements are prevalent competitive moves.
Within the broad chemical sector, BASF SE and Clariant AG exemplify major players leveraging extensive R&D capabilities to develop advanced coating and anti-caking agents. Koch Agronomic Services, a US-based entity, specifically positions itself as a specialist in nitrogen stabilizers and nutrient management solutions. These companies represent the industry's strategic focus on innovation and environmental performance.
| Leading Market Players |
|---|
| Corteva Agriscience |
| BASF SE |
| Clariant AG |
| Kao Corporation |
| Koch Agronomic Services |
| Arrmaz |
| ChemSol LLC |
| Michelman, Inc. |
| Tolsa Group |
| Others |
Cost & Logistics Intelligence
Petrochemical-derived raw materials, essential for many advanced coatings and dust control agents, originate from volatile global oil and gas markets. This upstream concentration directly influences the cost structure of fertilizer additives, impacting profit margins for manufacturers and procurement expenses for large-scale agricultural operations.
Pricing Analysis
Pricing stratifies across volume tiers, where larger agricultural enterprises secure more favorable rates for bulk purchases. Price differentiation stems from the performance characteristics of the additive, such as controlled-release duration, and the provision of specialized after-sales technical support. Pricing softness stems from intense competition among additive producers and farmer cost sensitivity, especially for commodity applications. Smallholder farmers exhibit the highest price sensitivity, while large-scale agricultural operations prioritize performance for high-value crops.
Supply Chain Analysis
Specialized chemical manufacturing capacity for additive components concentrates in countries such as China for intermediates, Germany for advanced chemical synthesis, and the United States for polymer production. The supply chain draws from petrochemical feedstocks, specific mineral sources for anti-caking agents, and specialized chemical catalysts. Commodity price volatility for petrochemicals poses a significant supply chain risk, alongside regulatory restrictions like the EU's REACH impacting certain chemical components. Distribution runs through a blend of wholesale networks for bulk products, direct sales channels for specialized formulations, and agricultural cooperatives providing localized access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
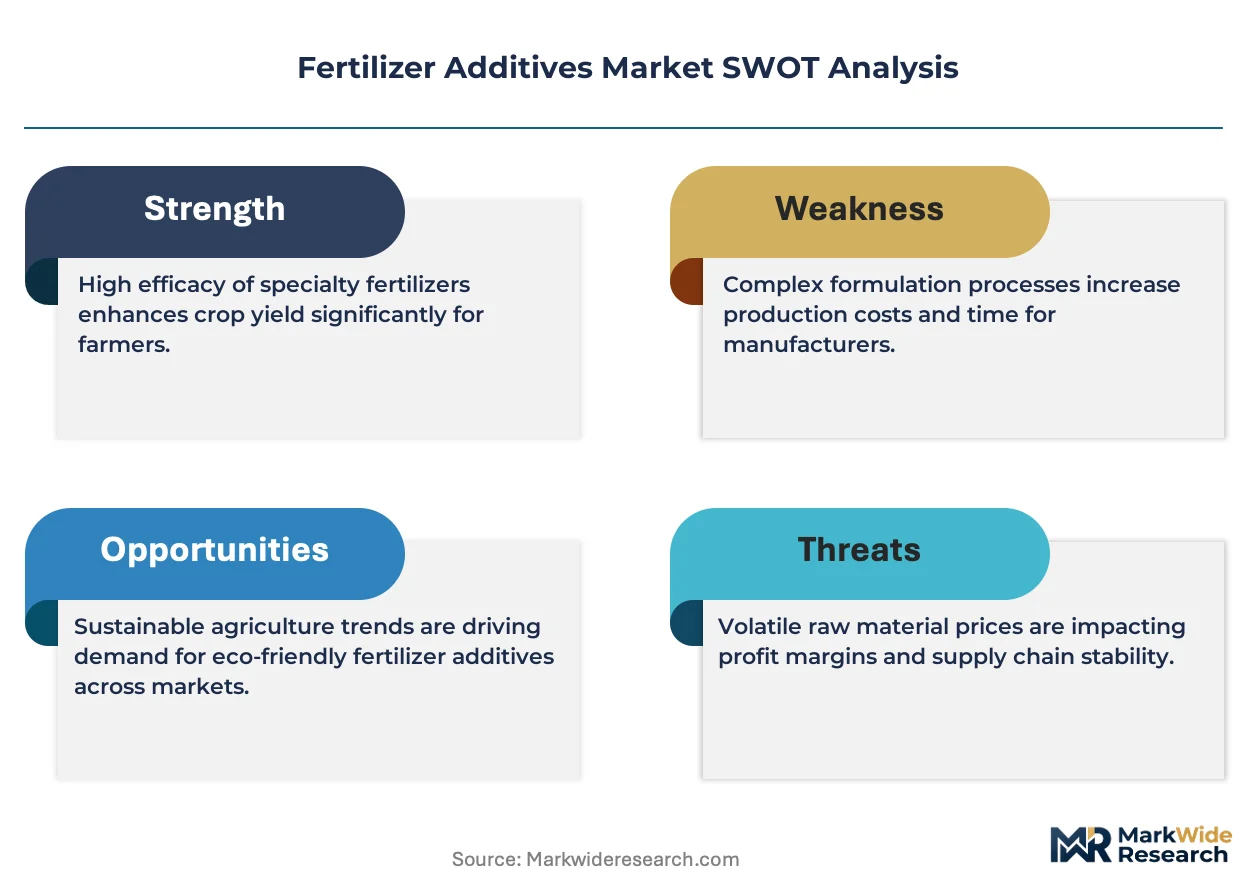
The fertilizer additives market requires a robust substitution defense. The rise of bio-fertilizers and enhanced plant genetics presents a threat, potentially reducing reliance on conventional chemical additives for nutrient management.
For Market Incumbents: Entrench core market positions by investing in research and development for next-generation biodegradable coatings and nitrogen stabilizers. Pursue strategic partnerships with precision agriculture technology providers to integrate additive functionality with digital farming platforms. Acquire niche biological additive manufacturers to diversify product portfolios and counter the bio-fertilizer threat. Environmental regulations, such as the EU Green Deal, push for reduced chemical dependency.
For New Entrants and Emerging Players: Establish a beachhead in specialty crop segments and organic farming operations. Focus on developing novel bio-based additives that enhance microbial viability or nutrient delivery in specific soil types. Target emerging markets in Southeast Asia with sustainable agriculture initiatives, leveraging government support. Direct-to-farmer digital platforms offer a go-to-market angle for consultative sales and rapid feedback loops.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized specialty chemical firms focused on agricultural inputs. The market demonstrates long-term viability driven by global food security needs and evolving environmental mandates. Seek out innovators in smart coatings, biological additives, or companies with strong intellectual property in nutrient use efficiency. Increased merger and acquisition activity among major agricultural chemical players targeting biological solution providers indicates a key signal to watch for market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Biodegradable Polymers | BASF SE and Clariant AG can meet stricter environmental regulations and capture demand for sustainable solutions. |
| Partnerships with AgTech Firms | Koch Agronomic Services can integrate its nutrient management solutions with digital farming platforms for real-time data. |
| Acquisition of Bio-Additive Specialists | Major players can expand their product portfolios into biological soil treatments, hybridizing offerings. |
| Capacity Expansion for Smart Coatings | Manufacturers can address growing demand for controlled-release fertilizers in precision agriculture. |
| Direct-to-Farmer Channel Investment | Companies can gain direct feedback from end-users and offer tailored solutions, bypassing traditional distributors. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation. Engagements included R&D directors, procurement leads at large agricultural enterprises, cooperative managers, and regulatory affairs specialists. Data was drawn from national agricultural statistics, environmental agency reports (e.g., US EPA, China MEE), and corporate financial filings. This approach enabled comprehensive bottom-up and top-down triangulation of market data.
Forecast inputs considered included agricultural land use trends, regulatory policy shifts, technological advancements in additive chemistry, and farmer adoption rates. The analytical framework modeled market dynamics across fertilizer type, application, form, and distribution channel over the projection horizon. Compound annual growth rates were derived from historical data analysis and projected market drivers. Key industry-specific inputs included nutrient loss reduction targets and specialty crop cultivation expansion.
Macroeconomic conditions sit as an overlay; deviation in global commodity prices or agricultural subsidies would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and technological innovation. Quarterly review of agricultural output data and new environmental policies is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
South America Fertilizers Market
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
Global Urea Market
Fertilizers
Fertilizer Bags Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
Potassium Thiosulfate Fertilizer Market
Fertilizers
Southeast Asia Fertilizer Market
Fertilizers
Global Potash Fertilizer Market
Fertilizers
Slow Release NPK Fertilizer Market
Fertilizers
Chelated Micronutrient Fertilizers Market
Fertilizers
Diammonium Hydrogen Phosphate (DAP) Market
Fertilizers
Nitrogen Nutrients Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
Global Complex Fertilizers Market