
 South Africa Fertilizer Market | 2026-2036
South Africa Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Fertilizer Market Insights
Precision agriculture is narrowing the operational gap between large-scale commercial farms and mid-tier grain producers across South Africa's maize belt. Omnia leverages its integrated manufacturing complex in Sasolburg to supply customized nitrogen blends directly to cooperatives in the Free State. Foskor anchors phosphate supply security through its mining and acid complex at Phalaborwa, sustaining captive feedstock for domestic compound fertilizer output. Sasol competes on ammonia cost position via its gas-to-liquids infrastructure, extending synthetic nitrogen access to coastal distributors.
Fertilizer denotes chemically or organically derived substances containing one or more essential plant nutrients—nitrogen, phosphorus, or potassium—formulated in granular, liquid, or gaseous states for soil application or foliar feeding, with NPK ratios and solubility parameters calibrated to crop-specific uptake curves. Nitrogenous products dominate volume throughput given maize's high nitrogen demand, though margin pools concentrate in compound formulations where blending precision commands premium pricing. Phosphate applications face structural pressure from ore grade decline at domestic mines, while potassium remains import-dependent through Durban port channels. Agricultural crops absorb the bulk of sector tonnage, yet horticulture in Limpopo and the Western Cape generates faster value growth per hectare through specialized micronutrient packages.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces fertilizer registration under Act 36 of 1947, while the Fertilizer Association of Southern Africa administers quality benchmarking that shapes product labeling and import specifications. The country's national water regulator imposes effluent discharge limits on fertilizer manufacturing facilities, forcing acid plant retrofits and wastewater recovery investments. Stakeholders must monitor how pending carbon border adjustments in key export destinations reshape the cost structure of ammonia-intensive production routes.
Market Dynamics
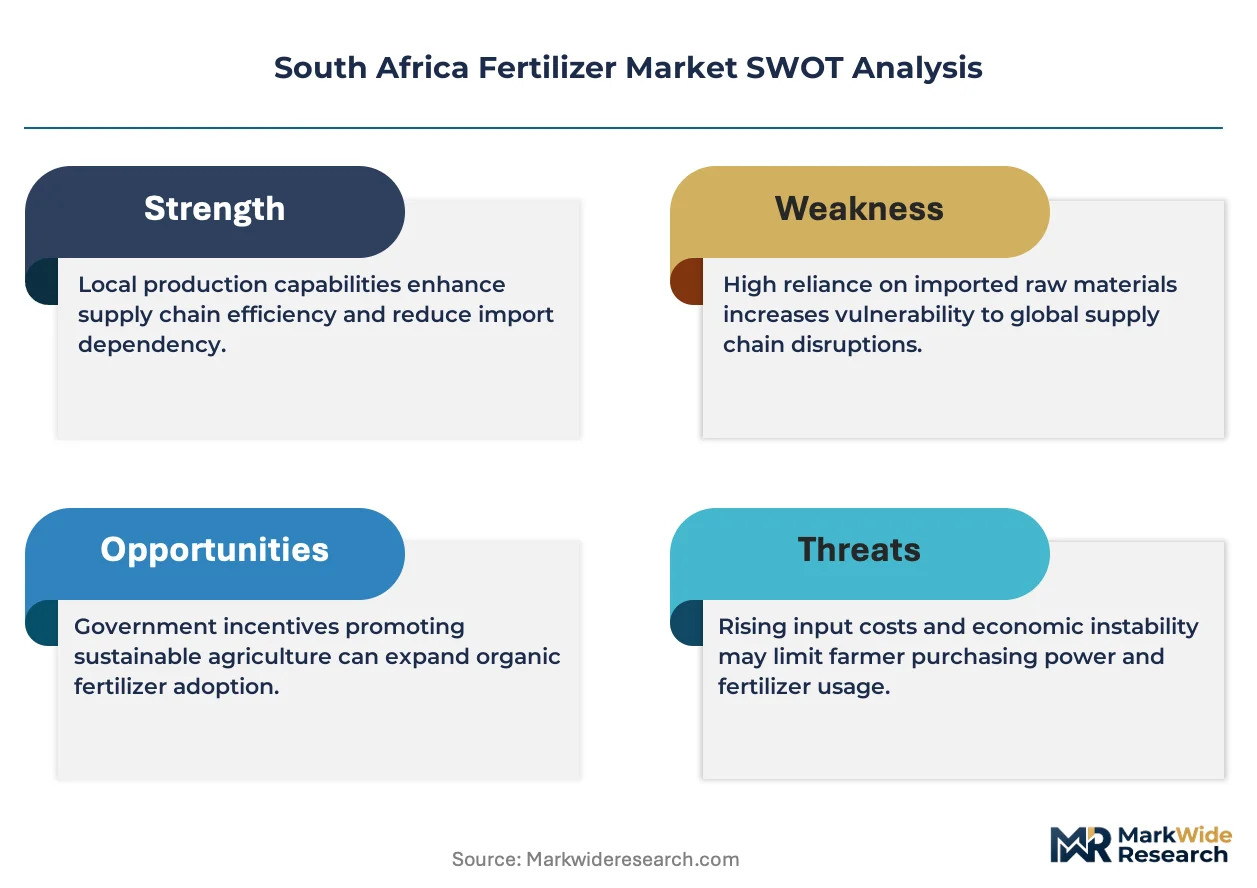
South Africa's fertilizer sector confronts a structural squeeze between rising input costs and tightening environmental compliance under the Conservation of Agricultural Resources Act. The Department of Agriculture, Land Reform and Rural Development enforces nutrient management protocols that force reformulation investments while domestic ammonia and phosphate feedstock costs climb.
Growth Catalysts
- Precision farming adoption:Variable-rate application technologies penetrate commercial grain operations in the Free State and North West provinces, lifting per-hectare fertilizer efficiency and justifying premium blended formulations.
- Irrigation expansion:The North West province's pivot irrigation networks extend planting windows and intensify nutrient cycling, generating sustained demand for water-soluble nitrogen products calibrated to high-frequency feeding schedules.
- Act 36 registration enforcement:The Fertilizer Association of Southern Africa's quality benchmarking protocols consolidate informal supply channels, redirecting volume toward registered compound manufacturers with certified NPK labeling.
Market Restraints
- Phosphate ore grade decline:Domestic mining operations at Phalaborwa face escalating beneficiation costs as ore quality deteriorates, compressing margins on superphosphate production and forcing greater reliance on imported acid.
- Potassium import dependency:The Durban port corridor handles nearly all muriate of potash arrivals, exposing inland distributors to shipping congestion, currency volatility, and demurrage penalties during peak application windows.
- Carbon border adjustment exposure:Pending European Union carbon border mechanisms threaten ammonia-intensive nitrogen fertilizer exports, requiring Sasolburg producers to certify process emissions or forfeit access to premium horticulture markets.
Strategic Opportunities
- Limpopo horticulture expansion:Avocado and citrus plantations in the Tzaneen and Letsitele valleys generate faster value growth per hectare than grain, creating demand for specialized micronutrient packages with chelated zinc and boron formulations.
- Western Cape vineyard micronutrition:Wine grape producers in Stellenbosch and Paarl adopt foliar feeding programs that bypass soil fixation losses, opening premium positioning for liquid fertilizer blends with precision application compatibility.
- Wastewater recovery investments:The national water regulator's effluent discharge limits force acid plant retrofits that yield recoverable gypsum and process water, converting compliance costs into circular economy credentials for domestic compound manufacturers.
Industry Challenges
- Blending technician scarcity:Customized NPK formulation requires skilled operators capable of interpreting soil test data and calibrating batch weights, yet technical training pipelines in Mpumalanga and the Free State remain underdeveloped relative to equipment sophistication.
- Legacy storage infrastructure:Coastal distributors in KwaZulu-Natal operate bagging plants designed for single-nutrient products, forcing capital-intensive silo reconfigurations to handle the bulk-blended compounds now preferred by commercial grain cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Fertilizer Market |
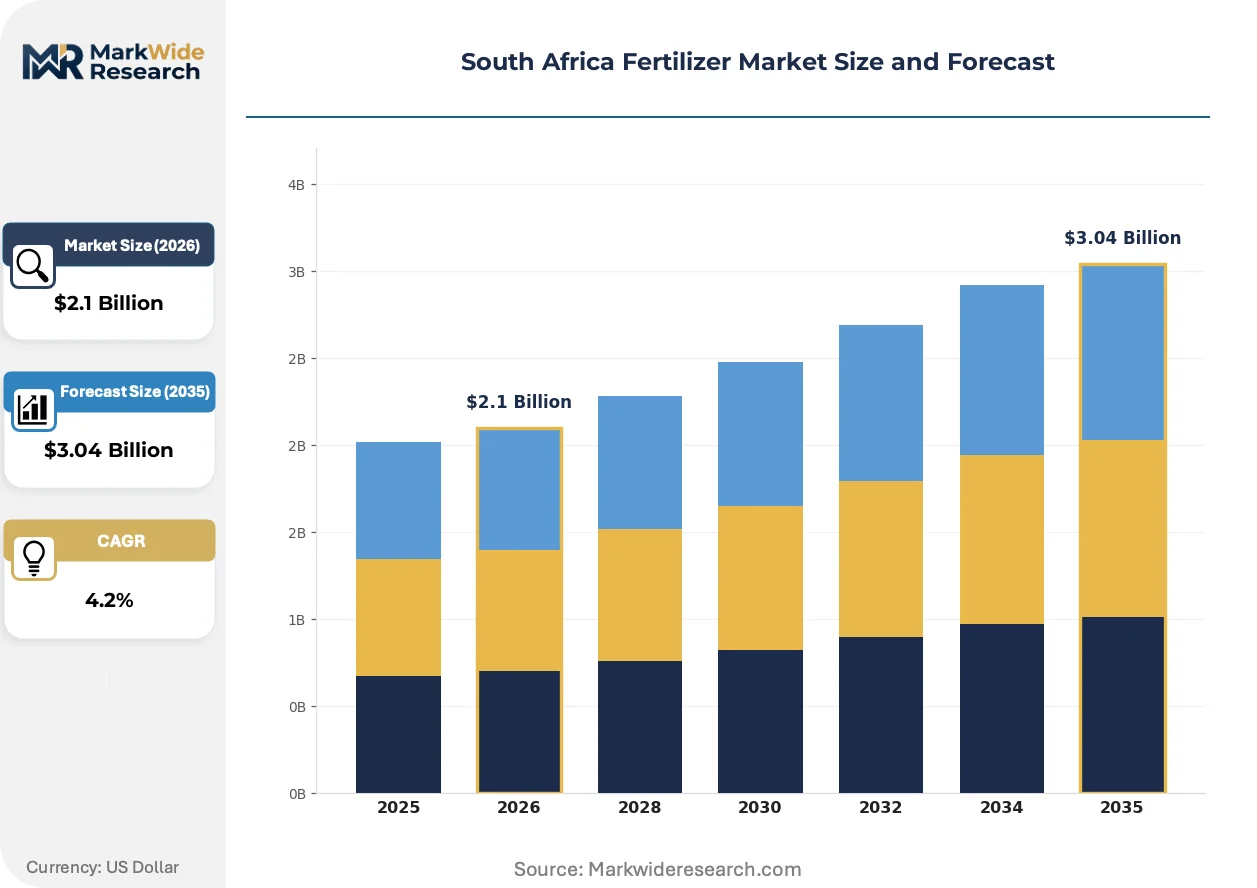
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogenous, Phosphate, Potassium, Compound Application: Agricultural Crops, Horticulture, Turf, Greenhouse End User: Farmers, Agricultural Cooperatives, Distributors, Retailers Packaging Type: Bags, Bulk, Liquids, Sachets |
| Companies Covered | Omnia, Foskor, Sasol, Kynoch, Nutrien Ag Solutions South Africa, Profert Fertilizers, GWK Ltd, TWK Agri, Senwes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Fertilizer Market Trends and Innovations
Digital soil mapping and sensor-based nutrient monitoring are compressing the gap between agronomic research and field-level application decisions. These technologies enable precise timing and placement of fertilizer inputs, reducing environmental runoff while protecting yield outcomes.
Controlled-release polymer coatings are hybridizing conventional urea granules with biodegradable membrane technologies that meter nitrogen availability across six to eight weeks. Commercial maize operations in the Free State deploy these formulations to align nutrient release with critical growth stages, reducing split-application labor costs while satisfying the Conservation of Agricultural Resources Act's leaching prevention mandates. The technology is hybridizing competitive positioning between integrated manufacturers with coating capabilities and commodity nitrogen traders lacking formulation depth.
The Department of Agriculture, Land Reform and Rural Development proposes amendments to Act 36 of 1947 that would mandate digital traceability from manufacturing batch to farm gate. This regulatory evolution forces compound fertilizer producers to retrofit packaging lines with QR-coded labeling systems and integrate with national agricultural databases. Medium-scale cooperatives in Mpumalanga face the steepest compliance curve, as their procurement systems lack the enterprise software architecture required for automated batch tracking.
Consolidated buying among grain cooperatives is compressing distributor margins and accelerating direct manufacturer relationships. The North West province's irrigation expansion zones witness cooperatives negotiating annual nitrogen supply contracts that bypass traditional wholesale channels, securing volume discounts in exchange for offtake commitments. This channel compression concentrates purchasing power among fewer farm-level decision-makers, privileging suppliers with integrated logistics networks capable of direct-to-farm delivery within 48-hour windows during critical planting periods.
South Africa Fertilizer Market Segmentation
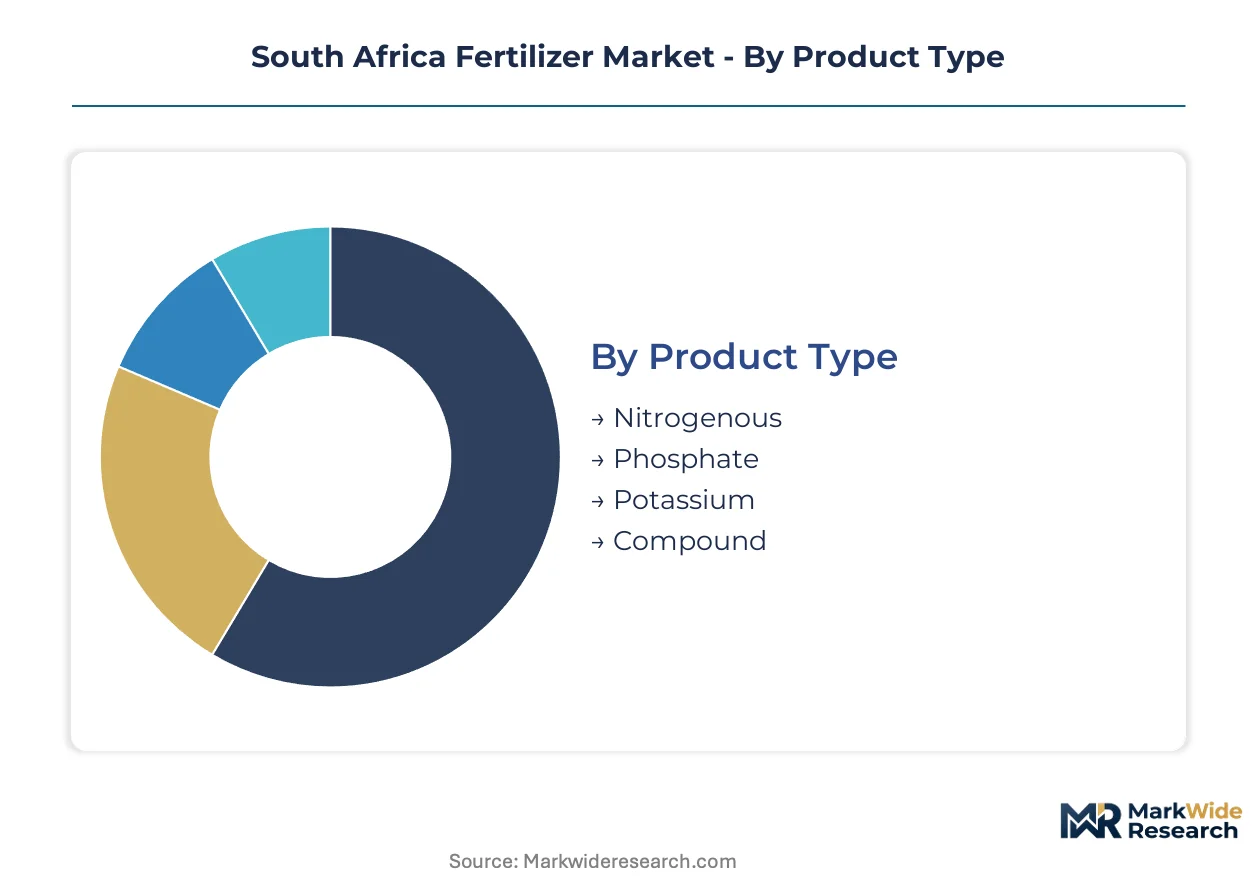
Fertilizer segmentation in South Africa tracks divergent demand rhythms across crop cycles, packaging economics, and procurement channels. Understanding these splits reveals where formulation investments yield returns versus where commodity trading dominates margin capture.
Product Type:
Nitrogenous products turn inventory fastest during maize planting windows, while compound fertilizers sit longer as blend specifications await soil test results.
- Nitrogenous:Urea and ammonium nitrate formulations supply maize's primary macronutrient demand. Free State grain cooperatives drive volume through Sasolburg-sourced ammonia derivatives, though price volatility in natural gas feedstock compresses margin predictability for distributors.
- Compound:Multi-nutrient blends with calibrated NPK ratios command premium pricing where precision farming penetrates. North West irrigation zones generate concentrated demand for customized formulations that match high-frequency feeding schedules to extended planting windows.
- Phosphate:Superphosphate output depends on Phalaborwa ore grades that deteriorate steadily, forcing beneficiation cost escalation.
- Potassium:Muriate of potash arrives almost entirely through Durban port channels, exposing inland supply to shipping congestion and currency fluctuation.
Nitrogenous dominates installed base. Compound is where expansion concentrates.
Application:
Cost tiers separate commodity grain applications from precision horticulture programs that recover micronutrient premiums per hectare.
- Agricultural Crops:Maize, wheat, and soybean operations in the Free State and Mpumalanga absorb bulk tonnage through seasonal procurement cycles. The Department of Agriculture, Land Reform and Rural Development's nutrient management protocols under the Conservation of Agricultural Resources Act force reformulation investments that favor registered compound suppliers over informal traders.
- Horticulture:Avocado and citrus plantations in Limpopo's Tzaneen valley generate faster value growth per hectare than grain through specialized chelated zinc and boron packages. Western Cape vineyard foliar programs bypass soil fixation losses entirely.
- Turf:Golf course and sports field maintenance in Gauteng urban corridors sustains steady demand for slow-release formulations with visual greening response.
- Greenhouse:Controlled environment agriculture near Johannesburg and Cape Town requires water-soluble feeding systems with pH-buffered nutrient solutions.
Agricultural crops anchor volume throughput. Horticulture is climbing the fastest in value terms.
End User:
Customer type determines procurement sophistication, from spot-market bag purchases to annual nitrogen supply contracts negotiated direct with manufacturers.
- Farmers:Commercial grain operations in the North West consolidate purchasing power through cooperative membership, securing volume discounts in exchange for offtake commitments. Mid-tier producers in Mpumalanga face steeper compliance curves as Act 36 registration mandates digital traceability systems they lack enterprise architecture to support.
- Agricultural Cooperatives:Buying groups in Free State irrigation districts negotiate direct manufacturer relationships that bypass traditional wholesale channels, demanding 48-hour delivery windows during critical planting periods.
- Distributors:Coastal bagging plants in KwaZulu-Natal require capital-intensive silo reconfigurations to handle bulk-blended compounds now preferred by commercial grain cooperatives.
- Retailers:Farm supply stores in rural towns serve smallholder markets with single-nutrient products in 50kg bags, though quality benchmarking protocols redirect volume toward registered suppliers.
Farmers control the largest addressable base. Agricultural cooperatives are where purchasing power is concentrating most rapidly.
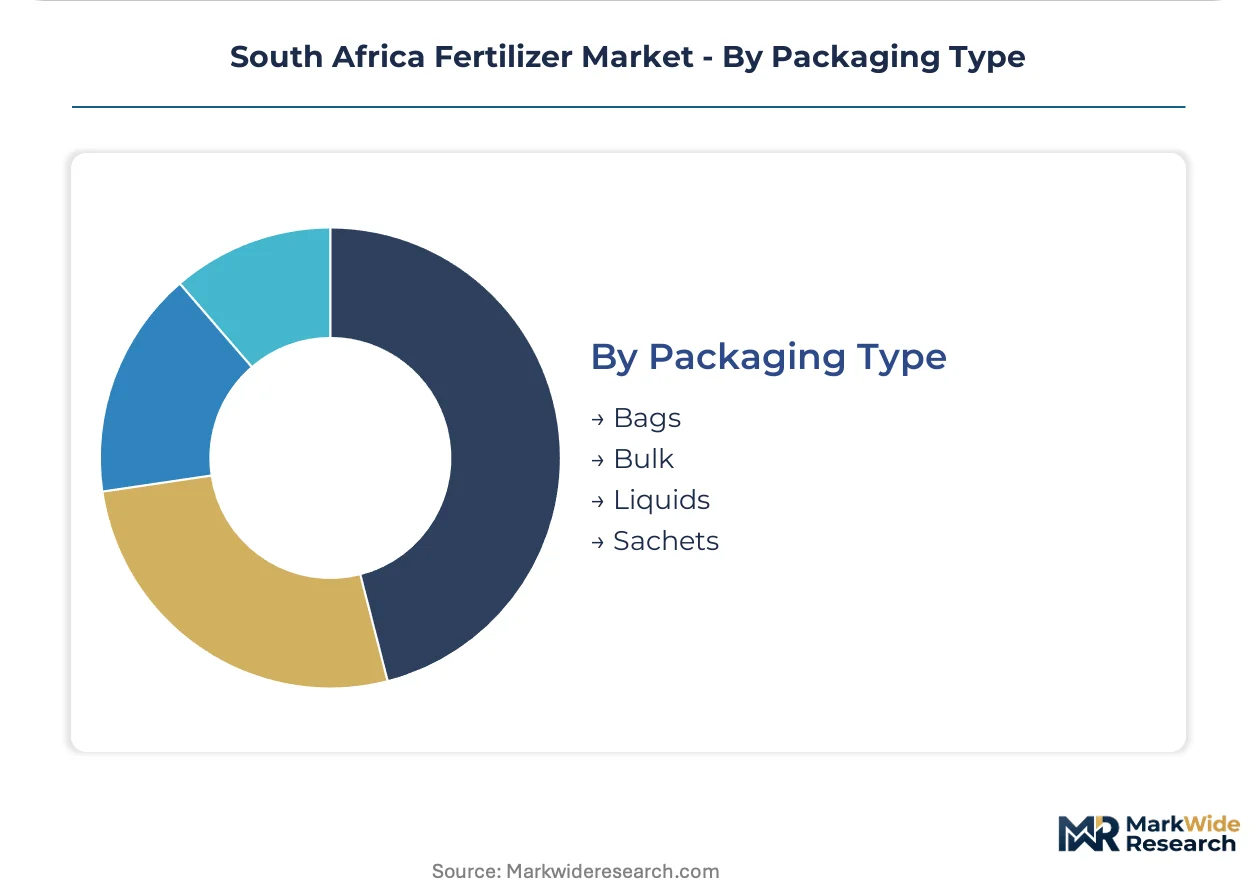
Packaging Type:
Volume economics and handling infrastructure shape packaging choice, with bulk systems favored where storage and application equipment justify capital deployment.
- Bulk:Unpacked delivery to on-farm silos minimizes per-unit handling cost for large commercial operations with pneumatic spreading equipment. North West grain cooperatives lead adoption where irrigation expansion justifies infrastructure investment.
- Bags:50kg woven polypropylene remains standard for small-to-mid tier farmers lacking bulk handling capacity, though rising labor costs erode economic advantage.
- Liquids:Urea-ammonium nitrate solutions and foliar micronutrient suspensions enable precision application through fertigation and aerial spraying systems in Western Cape vineyards.
- Sachets:Small-format packaging serves peri-urban vegetable gardeners and emerging farmer programs with trial-scale nutrient access.
Bags dominate current installed base. Bulk is gaining share fastest where cooperative infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial grain cooperatives concentrate purchasing power across South Africa's interior provinces, with irrigation expansion and precision farming adoption creating divergent demand profiles between the maize belt and coastal horticulture zones.
Free State
Maize cooperatives in the Free State drive bulk nitrogen demand through Sasolburg-sourced ammonia derivatives, with variable-rate application technologies penetrating commercial operations. The Department of Agriculture, Land Reform and Rural Development enforces nutrient management protocols under the Conservation of Agricultural Resources Act that force reformulation investments. Omnia's integrated manufacturing complex in Sasolburg supplies customized blends directly to cooperative buyers in Bethlehem and Kroonstad.
North West
Pivot irrigation networks in the North West province extend planting windows and intensify nutrient cycling, generating sustained demand for water-soluble nitrogen products. The Fertilizer Association of Southern Africa's quality benchmarking protocols consolidate informal supply channels toward registered compound manufacturers. Grain cooperatives in the Brits and Rustenburg corridors negotiate direct manufacturer relationships that bypass traditional wholesale channels.
Mpumalanga
Mid-tier producers in Mpumalanga face steeper compliance curves as Act 36 registration mandates digital traceability systems they lack enterprise architecture to support. The Department of Agriculture, Land Reform and Rural Development proposes amendments that would mandate QR-coded labeling from manufacturing batch to farm gate. Storage and blending infrastructure clusters around Nelspruit serve both commercial grain operations and emerging citrus plantings in the Lowveld.
Limpopo
Avocado and citrus plantations in the Tzaneen and Letsitele valleys generate faster value growth per hectare than grain, creating demand for specialized micronutrient packages with chelated zinc and boron formulations. The national water regulator's effluent discharge limits force acid plant retrofits that yield recoverable gypsum. Precision foliar feeding programs bypass soil fixation losses entirely in these high-value horticulture zones.
Western Cape
Wine grape producers in Stellenbosch and Paarl adopt foliar feeding programs that bypass soil fixation losses, opening premium positioning for liquid fertilizer blends with precision application compatibility. The Conservation of Agricultural Resources Act's leaching prevention mandates align with controlled-release polymer coating adoption in vineyard blocks. Cape Town's port infrastructure enables import access for specialized micronutrient formulations not manufactured domestically.
South Africa Fertilizer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across South Africa's fertilizer sector, with integrated manufacturers leveraging captive feedstock positions against distributors dependent on import corridors. The market structure concentrates around three archetypes: ammonia-based nitrogen producers with gas-to-liquids infrastructure, phosphate miners with acid complex integration, and cooperative-aligned blenders with regional logistics networks. Dominant competitive moves include backward integration into mining and acid production, plus direct-to-farm delivery partnerships that bypass wholesale intermediaries.
Within the integrated-manufacturer tier, Omnia, Foskor, and Sasol anchor competitive positioning through distinct feedstock advantages. Omnia leverages its Sasolburg complex for customized nitrogen blend supply to Free State cooperatives. Foskor represents the phosphate-integrated archetype through its Phalaborwa mining and acid operations. Sasol occupies the synthetic nitrogen position via gas-to-liquids infrastructure extending ammonia access to coastal distribution points. These three entities exemplify how captive supply of critical inputs—ammonia, phosphate rock, and synthesis gas—shapes margin capture in a market confronting rising import dependency for potassium and deteriorating domestic ore grades.
| Leading Market Players |
|---|
| Omnia |
| Foskor |
| Sasol |
| Kynoch |
| Nutrien Ag Solutions South Africa |
| Profert Fertilizers |
| GWK Ltd |
| TWK Agri |
| Senwes |
| Others |
Pricing and Supply Chain Analysis
Sasolburg ammonia concentration funnels margin capture toward integrated nitrogen manufacturers while coastal distributors absorb currency volatility on imported potassium. The Conservation of Agricultural Resources Act compliance costs compound feedstock pressure, forcing mid-tier blenders toward direct manufacturer contracts that sacrifice margin for supply security.
Pricing Analysis
Annual offtake contracts with Brent crude and Henry Hub indexation dominate nitrogen pricing, with Sasol leveraging gas-to-liquids cost position to undercut import parity. Three-tier pricing structure across premium compound blends, standard NPK formulations, and commodity urea reflects certification grade and volume scale differentiation. Cost compression in commodity nitrogen is intensifying because maize cooperatives consolidate purchasing power through direct Sasolburg negotiations. Small-to-mid tier farmers in Mpumalanga exhibit highest price sensitivity, while North West irrigation cooperatives least sensitive due to yield premiums from precision formulations.
Supply Chain Analysis
Contract manufacturing concentration rests with Omnia's Sasolburg complex, Foskor's Phalaborwa acid facilities, and coastal blending terminals operated by Kynoch and Profert. Geographic supply concentration centers on South Africa for phosphate rock and synthetic ammonia, with potassium chloride drawing from Canada, Russia, and Belarus through Durban port channels. Raw material dependencies hinge on natural gas feedstock for ammonia synthesis, apatite ore grades at Phalaborwa, and muriate of potash arrivals subject to shipping congestion. Single-source vulnerability on Durban bulk handling infrastructure poses structural risk. Distribution runs through cooperative procurement networks that bypass traditional wholesale tiers in Free State and North West provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical formulation capability scarcity defines competitive outcomes, with qualified blending technicians and digital traceability infrastructure representing the critical asset gap separating integrated manufacturers from stranded mid-tier operators.
For Market Incumbents: Insulate margin position by deepening captive ammonia supply through Sasolburg capacity optimization and accelerating Act 36 registration pre-emption to lock out informal traders before digital traceability mandates take effect. Defensive consolidation of cooperative delivery networks in North West irrigation corridors blocks emerging entrants from securing critical planting-window access. For New Entrants and Emerging Players: Build out micronutrient formulation capabilities targeting Limpopo avocado and Western Cape vineyard segments where premium pricing tolerates new supplier qualification cycles. The most penetrable white space sits in chelated zinc and boron packages for high-value horticulture, with foliar application compatibility as the go-to-market angle bypassing soil fixation competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors in KwaZulu-Natal holding coastal bagging infrastructure ripe for bulk-blend retrofit. Long-term viability across the analysis window favors targets with backward integration into acid production or captive ammonia offtake. Monitor Phalaborwa ore grade disclosure trends as the inflection signal for phosphate margin compression acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acid Production | Foskor's Phalaborwa complex secures phosphate feedstock against ore grade decline and import dependency. |
| Digital Traceability System Deployment | Act 36 amendments force QR-coded batch tracking that favors Omnia's enterprise software architecture. |
| Direct-to-Farm Logistics Network | North West cooperatives demand 48-hour delivery windows that concentrate purchasing power with integrated manufacturers. |
| Controlled-Release Coating Capacity | Polymer-urea hybrid formulations align nutrient release with maize growth stages under Conservation Act mandates. |
| Wastewater Recovery Infrastructure | National water regulator effluent limits convert compliance costs into circular economy credentials for compound producers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at Sasolburg and Phalaborwa facilities, procurement leads at Free State grain cooperatives, distribution channel partners in KwaZulu-Natal, and technical R&D directors at compound manufacturers; alongside secondary validation through customs and trade data, Fertilizer Association of Southern Africa quality benchmarking reports, Department of Agriculture registration filings, and SEC disclosures from listed chemical conglomerates. Bottom-up volume triangulation across crop-specific application rates and top-down value reconciliation against import parity pricing anchored forecast integrity.
Forecast inputs considered nitrogen demand elasticity to maize planting area, phosphate beneficiation cost curves at deteriorating Phalaborwa ore grades, potassium import exposure through Durban congestion patterns, and precision farming penetration rates across Free State and North West provinces. Segmentation dimensions modeled include product type tier, crop application intensity, end-user procurement sophistication, and packaging infrastructure maturity. CAGRs derived from regression against historical planting area cycles and nutrient management protocol enforcement timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by synthetic nitrogen producers or abrupt Phalaborwa mine closure would shift outcomes substantially. Quarterly review of Brent-Henry Hub spread movements, Durban port vessel queue depth, and Act 36 amendment implementation pace is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Italy Foliar Fertilizer Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
Russia Fertilizers Market
Fertilizers
Nitrogen Nutrients Market
Fertilizers
Global NPK Fertilizer Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Silicon Fertilizer Market
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
EMEA Secondary Macronutrients Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Middle East and Africa Fertilizers Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
Enhanced Efficiency Fertilizer Market