
 Sound Barriers Market | 2026-2036
Sound Barriers Market Size, Share, and Industry Trends Forecast 2026-2036
Sound Barriers Market Intelligence
The direct-to-contractor sales channel for custom-built sound barriers is fragmenting as large material suppliers and specialized engineering firms compete for project specification influence. Saint-Gobain leverages its extensive material science portfolio to offer integrated solutions for large-scale projects. Meanwhile, Kinetics Noise Control specializes in high-performance systems for industrial and architectural applications, targeting niche performance requirements.
Sound barriers are structures engineered to absorb or reflect sound energy, thereby reducing noise pollution from a specific source. These systems often utilize materials with a high Sound Transmission Class (STC) rating to block airborne sound, primarily for mitigating noise from highways and industrial sites. Concrete and metal barriers dominate the highways application due to durability. However, absorptive designs using advanced composites represent the fastest-growing segment in residential areas where acoustic performance is paramount.
Noise control regulations, such as the EU's Environmental Noise Directive and the US Federal Highway Administration's (FHWA) noise abatement criteria, mandate the use of sound barriers in infrastructure projects. Concurrently, material standards like ISO 10534 for acoustic impedance define product performance requirements, influencing design specifications. Stakeholder focus is shifting toward life-cycle costs and the integration of recycled materials, balancing initial investment with long-term durability and environmental compliance.
Market Dynamics
The market's central dynamic is the conflict between material durability for large-scale infrastructure and advanced acoustic performance for urban densification. This tension is amplified by regulations like the EU's Environmental Noise Directive, forcing a design divergence across applications.
Growth Catalysts
- Regulatory Mandates:The EU Environmental Noise Directive and US FHWA noise abatement criteria compel the inclusion of sound barriers in new and upgraded transport infrastructure, creating a baseline of regulatory-driven demand.
- Infrastructure Expansion:Sustained investment in national highway and high-speed rail networks, particularly across India, creates large-volume, long-term demand for durable concrete and metal barrier systems.
- Material Innovation:The development of effective sound-absorptive composites from recycled materials allows project specifiers to meet both acoustic performance and sustainability goals, especially in green building projects.
Market Restraints
- High Initial Cost:The significant capital investment required for concrete and metal barrier installation can strain the budgets of public works departments, leading to project delays or scope reductions.
- Input Material Volatility:Price fluctuations in steel, aluminum, and petrochemicals used for composites directly impact manufacturing costs and create margin uncertainty for producers of sound barriers.
- Physical Installation Constraints:The large footprint and weight of traditional reflective barriers are often impractical for retrofitting in dense urban areas with limited right-of-way, restricting market access.
Strategic Opportunities
- Building Retrofit Applications:A market exists for lightweight, aesthetically designed barriers to mitigate localized noise for existing residential and commercial buildings, moving beyond traditional transport applications.
- Multi-Functional Infrastructure:Integrating photovoltaic cells into barrier designs creates dual-use structures that generate renewable energy, offering a new value proposition for projects in Germany and Japan.
- Emerging Market Urbanization:Megacities in Latin America and Southeast Asia represent new frontiers where rising population density and public transport investments are creating nascent demand for noise control.
Industry Challenges
- Complex Certification Pathways:New materials face lengthy and fragmented testing protocols to achieve compliance with diverse acoustic, fire safety, and structural standards like ISO 10534, slowing innovation.
- Specialized Labor Scarcity:A shortage of installation teams with the expertise to handle advanced composite materials and complex custom-engineered systems can lead to project bottlenecks and quality control issues.
- Long-Term Durability and Maintenance:Establishing cost-effective cleaning and repair protocols for absorptive surfaces, which can degrade from pollution and weather, is a key operational challenge for asset owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sound Barriers Market |
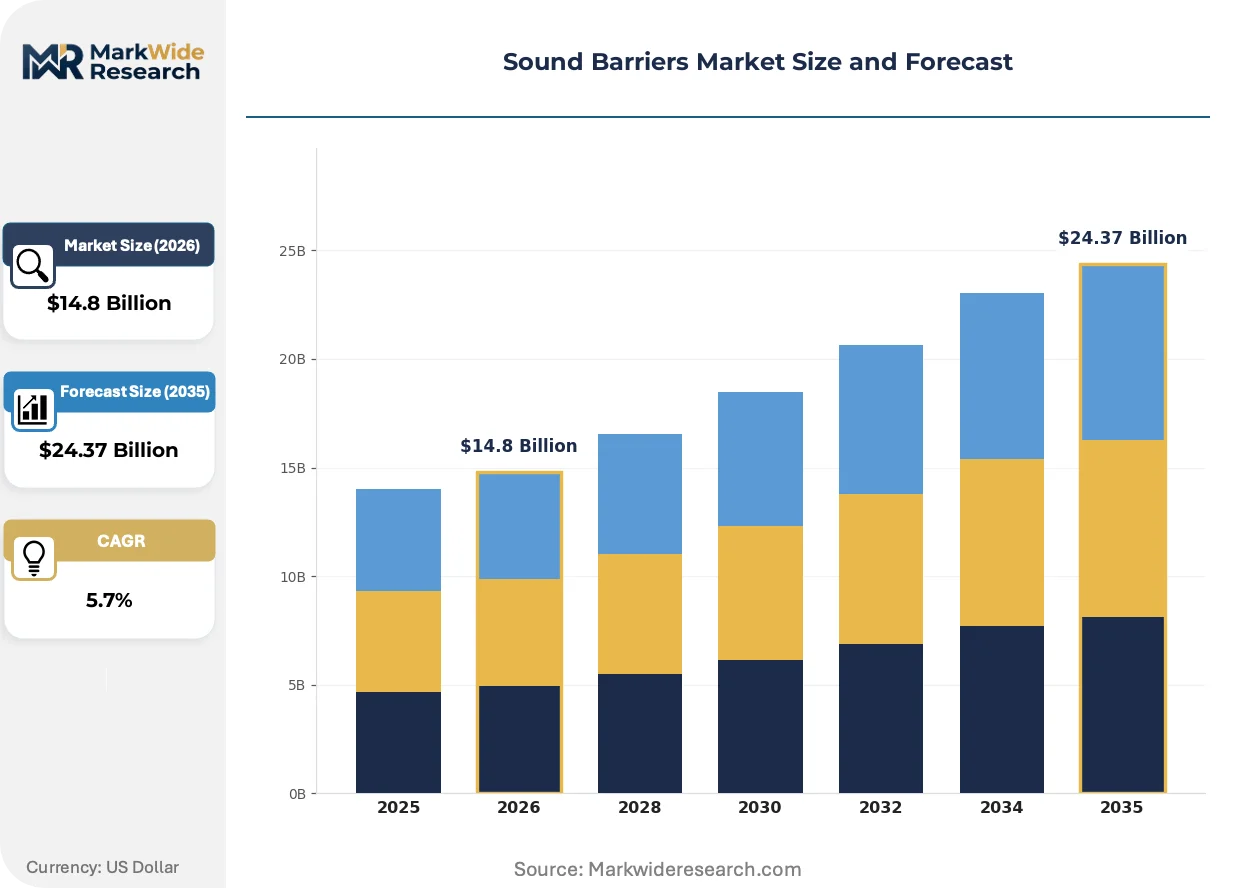
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Concrete, Wood, Metal, Polyethylene Application: Highways, Railways, Residential Areas, Industrial Sites Design Type: Absorptive, Reflective, Transparent, Fencing Installation Method: Precast, Modular, Custom-Built, Retrofit |
| Companies Covered | Saint-Gobain, Owens Corning, Rockwool, Kinetics Noise Control, Polymer Technologies, Durisol, Echo Barrier, Noise Barriers, Armstrong World Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sound Barriers Market Strategic Shifts & Innovations
Material science advancements and a focus on life-cycle sustainability are transforming sound barriers from passive structures into multi-functional assets. This evolution prioritizes acoustic efficiency, environmental impact, and integration with surrounding infrastructure.
Transparent Acoustic Panels
Transparent barriers made from acrylic or polycarbonate provide noise reduction without obstructing sightlines. Urban planners and architects specify these systems for bridges, railways, and residential balconies where visual access is a priority. This technology is collapsing the traditional trade-off between effective noise mitigation and aesthetic integration in high-value urban real estate.
Circular Economy Procurement
Circular economy principles are increasingly embedded in public infrastructure tenders, particularly in the Netherlands and Germany. These policies mandate the use of recycled content, such as granulated tires or post-consumer plastics, in new barrier construction. Highway agencies are the most affected segment, compelling manufacturers to re-engineer material formulations to meet sustainability targets.
Total Cost of Ownership Models
A notable shift in procurement involves evaluating barriers based on a Total Cost of Ownership (TCO) model rather than just initial installation price. This favors higher-performance absorptive composites that offer longer lifespans and reduced maintenance over less expensive but less durable options. This evaluation method is most visible in public-private partnership infrastructure projects in Australia and Canada.
Sound Barriers Market Segmentation
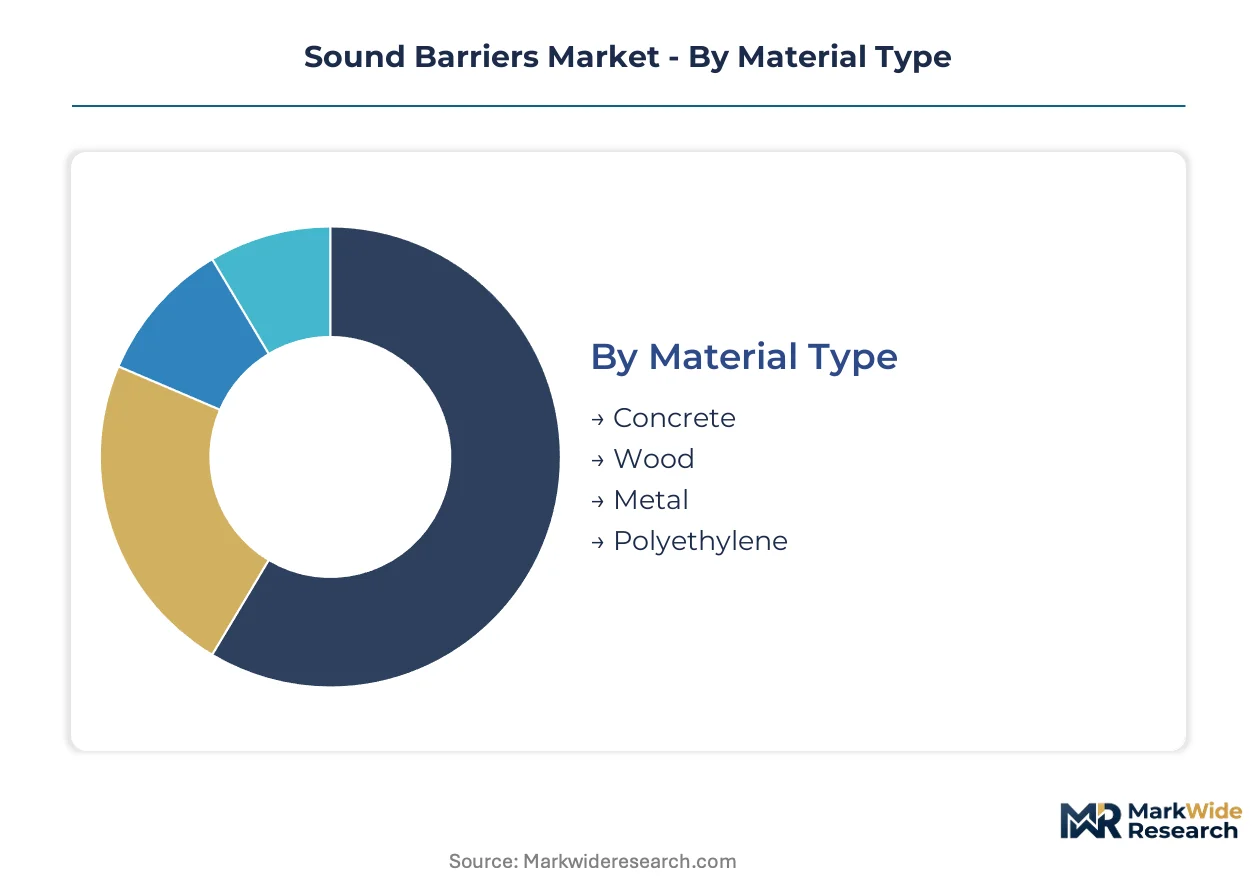
The sound barriers market segmentation reflects the diverse requirements driven by varying noise sources, environmental conditions, and regulatory compliance needs. Understanding these distinct segments is crucial for manufacturers to tailor solutions and for project specifiers to select optimal systems.
Material Type:
Sound barrier materials span a spectrum of performance and durability, tailored to specific environmental and aesthetic requirements across diverse projects.
- Concrete:Composed of dense aggregates and cement, concrete barriers offer high mass and structural integrity for airborne sound blocking. Demand concentrates in highway and rail infrastructure projects across India, driven by the need for long-term durability and resistance to harsh weather conditions.
- Metal:Fabricated from steel or aluminum, metal barriers provide excellent sound reflection properties and can be perforated for absorptive designs. Infrastructure developments in Germany frequently specify metal barriers due to their lighter weight compared to concrete and potential for integrated design elements.
- Wood:Wood barriers, often pressure-treated for longevity, are selected for their natural aesthetics in residential and parkland applications.
- Polyethylene:Polyethylene composites offer lightweight, absorptive solutions, increasingly utilized in urban retrofit projects for their flexibility and sustainability.
The dominant share belongs to Concrete, while Polyethylene is closing the gap fastest.
Application:
The volume of sound barrier deployment varies significantly across different end-use applications, reflecting diverse noise mitigation priorities.
- Highways:Noise barriers along highways primarily mitigate traffic sound, requiring durable, high-STC materials capable of withstanding environmental exposure. Large-scale highway expansion projects in emerging economies like India drive substantial demand for robust and cost-effective barrier solutions.
- Residential Areas:Barriers in residential settings prioritize aesthetic integration and high acoustic absorption to protect communities from localized noise sources. Urban densification projects in Germany increase demand for absorptive designs and transparent panels that maintain visual appeal and neighborhood quiet.
- Railways:Railway applications demand robust barriers to attenuate train noise, often integrating with existing infrastructure and requiring specific vibration isolation.
- Industrial Sites:Industrial site barriers focus on containing machinery noise and process sounds, utilizing heavy-duty materials for maximum sound blocking.
Highways represent the largest segment by installed volume, with Residential Areas showing the steepest expansion trajectory.
Design Type:
Sound barrier design types cater to specific application needs, balancing acoustic performance with spatial and visual considerations.
- Absorptive:Absorptive barriers contain porous or fibrous materials that convert sound energy into heat, preventing noise reflection back into the environment. Urban planners specify absorptive designs for residential areas and sensitive environments where minimizing echo and maximizing noise reduction is critical.
- Transparent:Constructed from acrylic or polycarbonate, transparent panels reduce noise while maintaining visual connectivity and natural light. Bridges and urban railway corridors in European cities like those in the Netherlands increasingly adopt transparent barriers for aesthetic integration and sightline preservation.
- Reflective:Reflective barriers, typically solid and non-porous, bounce sound energy back towards the source, effective for highway applications with sufficient setback.
- Fencing:Acoustic fencing offers a less intrusive noise mitigation option for localized residential or commercial property boundaries, prioritizing ease of installation.
Reflective designs hold a foundational position in infrastructure projects, while Absorptive and Transparent solutions are gaining share rapidly for urban applications.
Installation Method:
Installation methods for sound barriers are dictated by project scale, site constraints, and the specific operational requirements of the asset owner.
- Precast:Precast concrete panels are manufactured off-site and transported for rapid assembly, offering consistency and structural integrity. Public works departments managing highway expansions favor precast methods for their efficiency and reduced on-site construction time in major infrastructure corridors.
- Retrofit:Retrofit installations involve integrating sound barriers into existing structures or dense urban environments with minimal disruption. Urban densification projects in cities like Berlin necessitate lightweight, compact retrofit solutions to address noise pollution around established buildings.
- Modular:Modular systems, often factory-assembled panels, provide flexibility and quicker deployment for varied applications, including temporary or reconfigurable barriers.
- Custom-Built:Custom-built barriers address unique site challenges or aesthetic requirements, often involving specialized engineering for complex architectural integration.
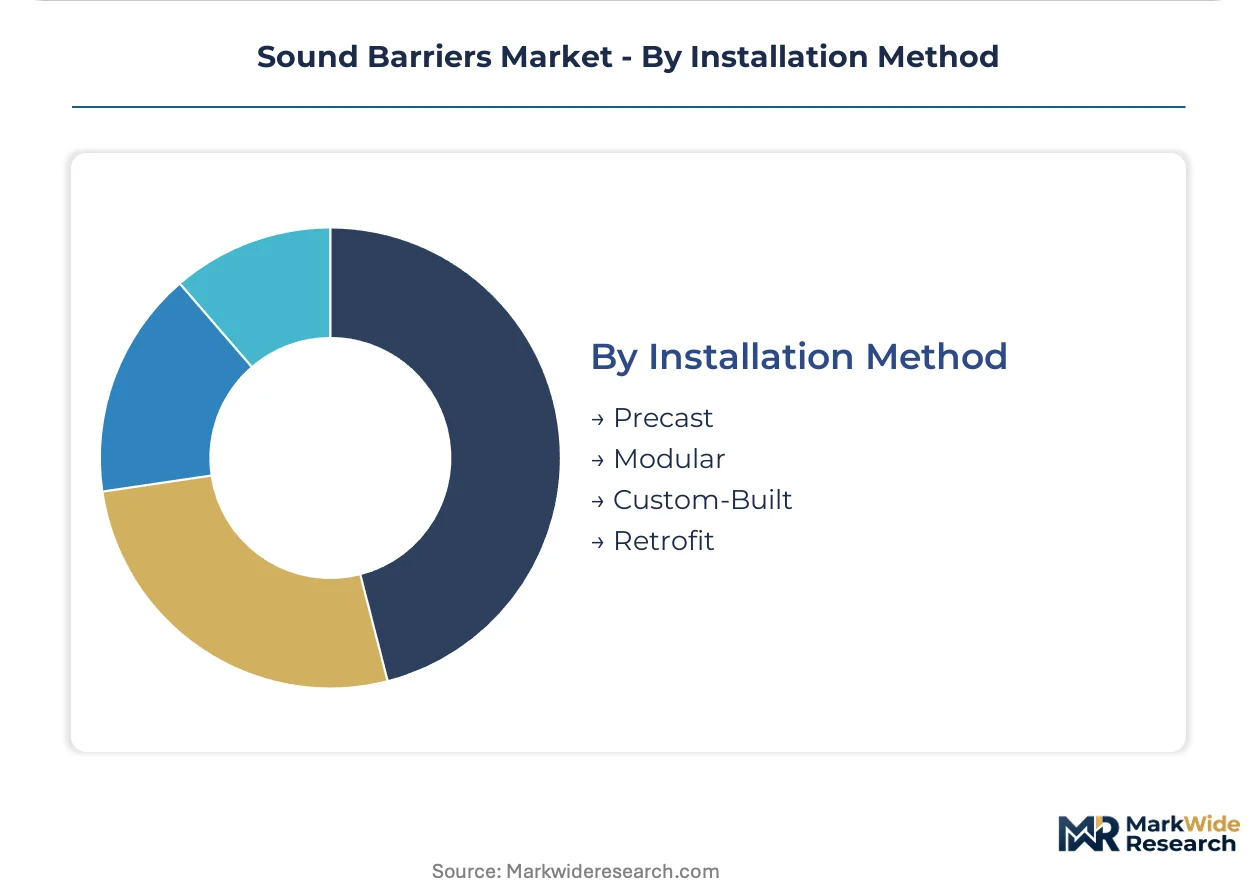
Precast methods remain fundamental for new large-scale projects, while Retrofit solutions are experiencing accelerated growth in built-up urban settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's Environmental Noise Directive drives demand for noise mitigation solutions across member states. This regulation compels infrastructure projects to integrate sound barriers, shaping design specifications and material choices. Global investments in transport networks and urban development further stimulate market expansion.
Germany
Urban densification projects and green building initiatives increase demand for absorptive and transparent sound barriers. Germany's KBA (Federal Motor Transport Authority) enforces strict noise emission limits for transport infrastructure. Berlin's urban planning emphasizes aesthetically integrated noise control solutions for residential areas.
India
Sustained investment in national highway and high-speed rail networks fuels significant demand for durable concrete and metal barrier systems. The Ministry of Road Transport and Highways mandates noise abatement measures for new road construction. Mumbai's rapidly expanding infrastructure requires robust barrier solutions to manage traffic noise.
United States
Federal Highway Administration (FHWA) noise abatement criteria compel the inclusion of sound barriers in highway expansion and upgrade projects. The US Environmental Protection Agency (EPA) also influences noise control standards for industrial sites. California's extensive freeway system often integrates precast concrete barriers for large-scale noise mitigation.
Netherlands
Circular economy principles and aesthetic integration are key drivers for sound barrier adoption, especially transparent panels. The Dutch Ministry of Infrastructure and Water Management promotes the use of recycled content in public tenders. Amsterdam's compact urban environment frequently utilizes lightweight, absorptive polyethylene barriers for residential retrofits.
Australia
Public-private partnership infrastructure projects demand sound barriers evaluated on Total Cost of Ownership models. The national Department of Infrastructure, Transport, Regional Development and Communications oversees transport noise guidelines. Melbourne's major road projects prioritize durable, low-maintenance barrier systems for long-term acoustic performance.
Sound Barriers Market Key Industry Players
Large material suppliers and specialized engineering firms split the market for sound barriers. This structure reflects a tension between standardized, high-volume production for infrastructure and custom, high-performance solutions for niche applications. Strategic archetypes include diversified material science conglomerates, dedicated acoustic engineering specialists, and regional manufacturers focusing on specific material types. Companies pursue portfolio diversification and strategic partnerships to broaden their market reach.
Within the specialized acoustic engineering segment, Kinetics Noise Control exemplifies a focus on high-performance systems for industrial and architectural applications. Saint-Gobain, a diversified material science conglomerate, occupies a position leveraging its extensive material portfolio to offer integrated solutions for large-scale projects. These players anchor different ends of the market, with Kinetics Noise Control targeting niche performance requirements and Saint-Gobain focusing on comprehensive offerings for major infrastructure.
| Leading Market Players |
|---|
| Saint-Gobain |
| Owens Corning |
| Rockwool |
| Kinetics Noise Control |
| Polymer Technologies |
| Durisol |
| Echo Barrier |
| Noise Barriers |
| Armstrong World Industries |
Cost & Logistics Intelligence
Commodity volatility in steel, aluminum, and petrochemicals determines both pricing tier spreads and regional supply chain configurations for sound barriers. This directly impacts the cost competitiveness of both traditional reflective and advanced absorptive systems, influencing material procurement strategies.
Pricing Analysis
Configured-to-order custom-built sound barriers command a premium due to specialized engineering and unique site integration, contrasting with standard precast concrete panels. Price differentiation is driven by material quality grade and the level of after-sales maintenance service. Pricing pressure stems from public works departments' budget constraints, particularly for large infrastructure projects. Highway applications represent the most price-sensitive buyer segment, prioritizing cost-effectiveness for high-volume deployments.
Supply Chain Analysis
Upstream feedstock for sound barriers draws heavily from global producers of steel, aluminum, and petrochemicals, with significant processing in China and India. Raw material dependencies include aggregates for concrete and specialized polymers for absorptive composites. Supply chain risk centers on commodity price volatility, directly impacting manufacturing costs for both traditional and advanced barrier systems. Distribution runs through a network of large material suppliers and specialized engineering firms, directly serving contractors and project specifiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sound barriers market is at a platform-economics inflection point, driven by the integration of multi-functional infrastructure elements like photovoltaic cells. This shift creates new value propositions and necessitates interoperability across disparate systems.
For Market Incumbents:Pre-empt the erosion of traditional barrier market share by investing in advanced composite R&D for absorptive and transparent designs. Develop integrated solutions that combine noise mitigation with renewable energy generation to counter emerging multi-functional alternatives. Expand certification investment for new materials to navigate complex regulatory pathways and accelerate market acceptance. This counters the threat from specialized engineering firms pushing niche performance requirements.
For New Entrants and Emerging Players:Emerging Market Urbanization in Latin America and Southeast Asia represents a significant geographic underpenetration for advanced sound barrier solutions. Target lightweight, aesthetically designed retrofit applications for existing residential and commercial buildings in these dense urban environments. A go-to-market angle focused on sustainability and rapid deployment using modular systems can differentiate offerings. Address localized noise issues where traditional large-footprint barriers are impractical.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors vertically integrated specialists with strong material science capabilities and established regulatory compliance. Long-term viability is strong, driven by persistent regulatory mandates and urban densification trends. Identify acquisition targets specializing in recycled material composites or transparent acoustic technologies for urban applications. The signal to watch is the increasing adoption rate of Total Cost of Ownership models in public tenders, favoring innovative solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Key Regions | Ensures product availability for large-scale infrastructure projects in India and other expanding markets. |
| Green Manufacturing Transition | Aligns production with circular economy principles and sustainability mandates in Europe. |
| Product Launch of Transparent Panels | Captures demand for aesthetic noise mitigation solutions in high-value urban real estate. |
| Strategic Partnership for PV Integration | Creates dual-use barrier systems, adding renewable energy generation to noise control. |
| Certification Investment for New Composites | Accelerates regulatory approval and market acceptance for innovative, sustainable materials. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings and quantitative estimates. This involved engaging with highway agency procurement leads, urban planners, material science R&D directors, and specialized installation contractors. Secondary data sources included regulatory filings, industry association reports, and material science journals. A bottom-up and top-down approach triangulated market size and growth projections.
Calibration of volume and value forecasts utilized a multi-factor analytical framework across the analysis window. Segmentation dimensions modeled included material type, application, design type, installation method, and regional regulatory environment. Compound Annual Growth Rates were derived from historical trends and projected shifts in technology adoption and infrastructure spending. Key forecast inputs included infrastructure investment budgets and material innovation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large material suppliers or specialized engineering firms would shift outcomes. Unforeseen changes in global commodity prices or new regulatory mandates represent specific risk factors. Cross-checking against national infrastructure spending plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
South America Ready Mix Concrete Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Chain Link Fencing Market
Building & Construction Materials
Household Mosaic Tiles Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Glazed Tiles Market
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
Window Film Market
Building & Construction Materials
Global Builder Hardware Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Prefabricated Bathroom Modules Market
Building & Construction Materials
US Commercial Windows Market