
 Sword Feeders Market | 2026-2036
Sword Feeders Market Size, Share, and Industry Trends Forecast 2026-2036
Sword Feeders Market Analytics
China's Guangdong province is narrowing its cost gap with legacy European suppliers through scaled manufacturing of precision-molded dispensing components. PETKIT leverages vertical integration across plastic injection and IoT module assembly to control unit economics. Xiaomi anchors its position through ecosystem bundling with existing smart-home platforms. WOPET differentiates via veterinary-partnership programs that validate portion-accuracy claims.
A sword feeder is a mechanized dispensing device engineered to distribute feed pellets, flakes, or granules into aquatic or terrestrial livestock environments at controlled rates, typically employing auger screws, vibrating channels, or pneumatic ejection mechanisms with throughput precision of ±3%. Its primary commercial purpose centers on reducing labor dependency while standardizing nutritional intake across high-density farming operations. Automated control systems command the dominant margin pool due to firmware complexity and recurring calibration-service revenue. Sensor-based systems represent the fastest-expanding category as optical and weight-based feedback loops enable real-time adjustment. Manual feeders retain volume share among smallholder cooperatives with constrained capital budgets.
The US EPA and FDA jointly shape product compliance through water-quality runoff standards and feed-contamination prevention protocols, while China's MIIT enforces GB-standard electromagnetic compatibility for networked farm equipment. These frameworks elevate engineering costs but simultaneously filter out unqualified entrants, tightening vendor qualification lists for commercial aquaculture tenders. Stakeholders must weigh certification investments against the contracting window for preferred-supplier status in expanding Southeast Asian procurement programs.
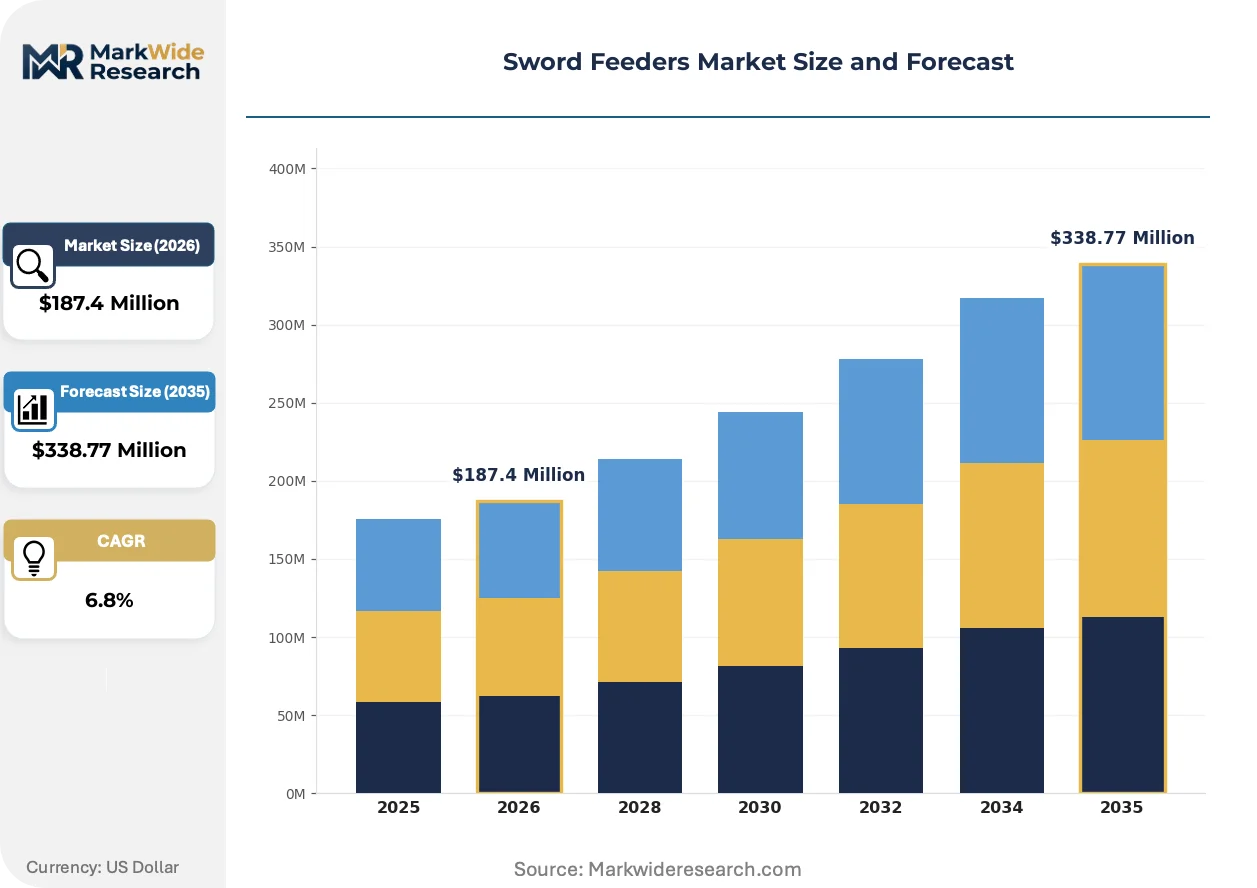
Market Dynamics
Sensor-based feedback loops are compressing calibration-service revenue windows while elevating firmware complexity as the primary margin determinant across automated sword feeder portfolios.
Growth Catalysts
- China's MIIT smart-equipment certification:GB-standard electromagnetic compatibility mandates are accelerating sensor-based system approvals and filtering unqualified vendors from commercial aquaculture tenders.
- Vietnam Mekong Delta cluster expansion:Mechanized feeding infrastructure deployments are scaling across high-density shrimp and catfish operations to standardize yield consistency.
- Optical weight-feedback convergence:Real-time pellet-dispensing adjustment algorithms are reducing feed waste ratios below manual-operator baselines in precision aquaculture environments.
Market Restraints
- Precision-molded component cost volatility:Engineering-grade polymer feedstock prices fluctuate with petrochemical indices, squeezing margin buffers for mid-tier dispensing mechanism manufacturers.
- Guangdong supply concentration:Scaled manufacturing of dispensing components clusters in a single province, creating geographic vulnerability to logistics disruptions or regional policy shifts.
- Manual feeder substitution persistence:Smallholder cooperatives with capital constraints continue deploying gravity-fed or timer-based alternatives, capping automated system penetration in fragmented ownership structures.
Strategic Opportunities
- Indonesia archipelago underpenetration:Maritime logistics barriers have slowed mechanized feeder deployment across dispersed island farming operations, creating first-mover whitespace for ruggedized, low-bandwidth units.
- EU Green Deal aquaculture sustainability mandates:Feed-efficiency reporting requirements are generating procurement preference for sensor-verified portion-accuracy systems in European marine-farm certification programs.
- IoT module ecosystem bundling:Integration with existing smart-home platforms is opening consumer-adjacent channels for premium automated feeders in ornamental aquarium and backyard pond segments.
Industry Challenges
- Firmware calibration technician scarcity:Automated control systems require specialized field-service competency that outpaces vocational training pipeline output in Southeast Asian deployment zones.
- Multi-standard certification timelines:Concurrent EPA water-runoff and FDA feed-contamination protocols extend product qualification cycles for vendors targeting North American commercial aquaculture procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sword Feeders Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Feeders, Automatic Feeders, Semi-Automatic Feeders, Portable Feeders Application: Agriculture, Aquaculture, Fish Farming, Poultry End User: Farmers, Aquaculture Operators, Poultry Producers, Livestock Managers Technology: Gravity Feed Systems, Automated Control Systems, Sensor-Based Systems, Wireless Monitoring |
| Companies Covered | PETKIT, Dogness, Xiaomi, PetSafe, Sure Petcare, PETLIBRO, WOPET, Whisker, Catit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sword Feeders Market Evolving Landscape
Convergence between optical sensing and cloud-based analytics is redefining competitive differentiation beyond hardware specifications toward data-service recurring revenue models.
Machine-vision pellet recognition systems equipped with spectral analysis capabilities are rendering obsolete manual calibration protocols that previously required weekly technician site visits. Large-scale Vietnamese shrimp operators are deploying these units across pond arrays exceeding fifty hectares each, compressing labor cost structures while elevating firmware update frequency as the critical vendor selection criterion.
China's MIIT guidelines on networked farm equipment interoperability are mandating open data-interface standards for sensor-based feeding systems. This regulatory architecture is fragmenting proprietary ecosystem lock-in strategies and forcing vendors to compete on analytics-layer differentiation rather than hardware-software bundling. Domestic Guangdong manufacturers are responding by accelerating cloud-platform development timelines.
Aquaculture procurement officers are unbundling after-sales service contracts from initial equipment purchases, shifting toward performance-guarantee fee structures tied to feed-conversion ratio improvements. This behavioral pivot is visible most acutely in Thailand's industrial prawn farming cooperatives, where tender evaluation weights now favor vendors offering real-time remote diagnostics over those with dense local technician networks.
Sword Feeders Market Segmentation
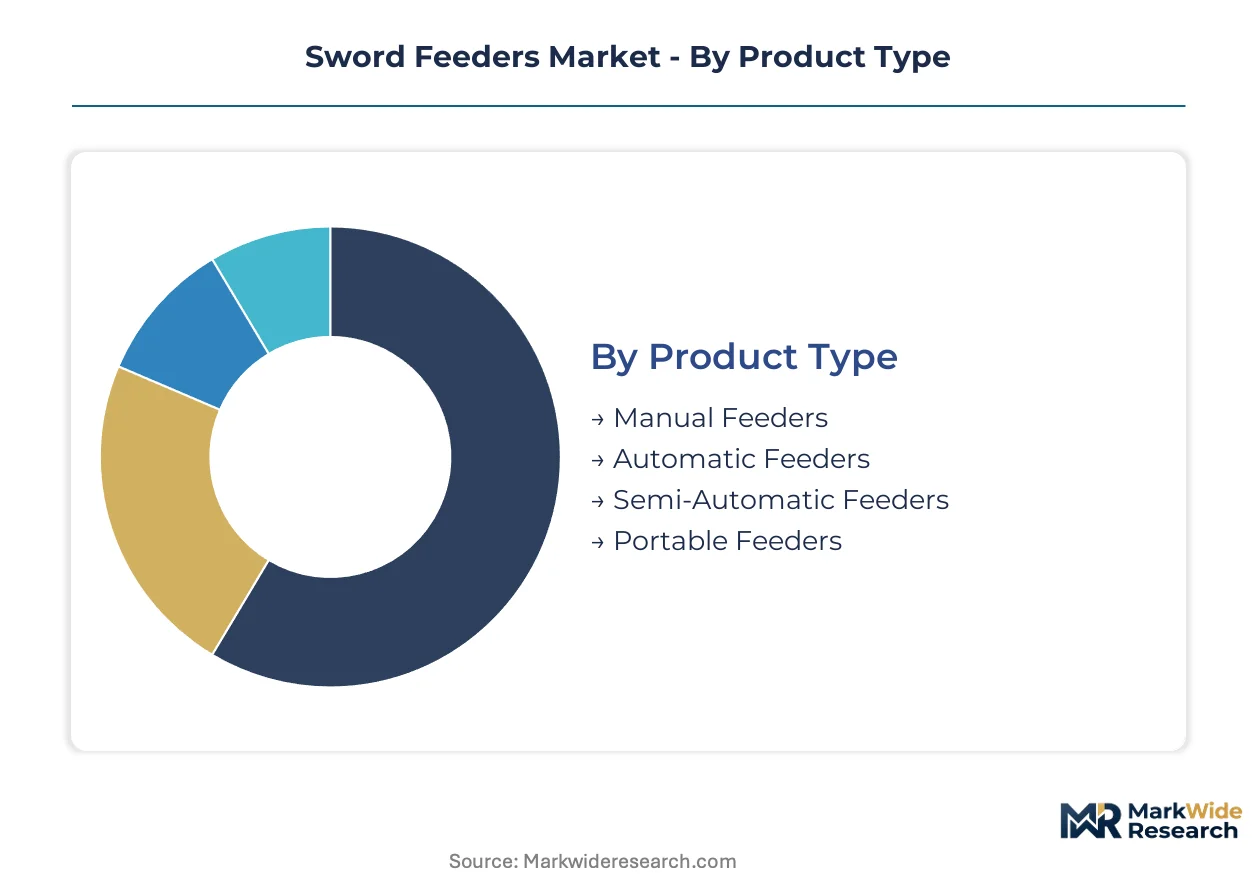
Sword feeder segmentation reveals divergent engineering requirements across manual versus automated deployment contexts. Product architecture, control technology, and end-user operational scale each create distinct procurement criteria that vendors must address through specialized portfolio configurations.
Product Type:
Deployment scenarios span from smallholder gravity-fed units to networked pond-array systems requiring precision throughput control.
- Manual Feeders:Gravity-fed or timer-actuated mechanisms with minimal moving parts suit capital-constrained cooperatives. Vietnam's Mekong Delta smallholders favor these units where technician scarcity limits automated system maintenance feasibility.
- Automatic Feeders:Auger-screw or pneumatic ejection systems with programmable dispensing schedules command premium positioning. Firmware complexity and recurring calibration-service revenue define margin structures for these units in Thailand's industrial prawn farming operations.
- Semi-Automatic Feeders:Hybrid architectures blending manual override with scheduled activation serve mid-tier aquaculture transitions.
- Portable Feeders:Battery-powered mobile units address Indonesia's dispersed island farming logistics barriers.
The dominant share belongs to Automatic Feeders, while Sensor-Based Systems (within Automatic) is closing the gap fastest.
Application:
Environmental conditions dictate corrosion resistance, moisture sealing, and feed-form compatibility specifications.
- Aquaculture:Submersible-rated housings with optical pellet-recognition capabilities dominate high-density shrimp and catfish operations. Real-time feed-conversion ratio optimization drives procurement in Vietnam's commercial pond clusters exceeding fifty hectares.
- Fish Farming:Freshwater versus marine salinity ratings determine stainless-steel grade selection and seal-material specifications. China's Guangdong manufacturers are narrowing cost gaps with European suppliers through scaled production of precision-molded dispensing components for these environments.
- Agriculture:Terrestrial livestock applications emphasize dust-ingress protection and larger pellet-handling capacity.
- Poultry:Chain-feeder integration and house-wide distribution networks characterize barn-scale deployments.
Aquaculture captures the largest application footprint, with Fish Farming expanding most quickly as marine-certification programs multiply.
End User:
Procurement sophistication varies sharply between industrial operators and fragmented smallholder structures.
- Aquaculture Operators:Industrial-scale buyers unbundle after-sales contracts in favor of performance-guarantee fee structures tied to feed-efficiency metrics. Thailand's procurement officers now weight real-time remote diagnostics above dense local technician networks in tender evaluations.
- Poultry Producers:Vertically integrated processors specify house-automation compatibility and centralized monitoring dashboards.
- Farmers:Price-sensitive owner-operators prioritize capital expenditure minimization over lifecycle cost optimization.
- Livestock Managers:Corporate farming entities demand fleet-management software integration and predictive maintenance scheduling.
Aquaculture Operators hold the dominant procurement volume, while Poultry Producers are gaining share fastest through consolidation-driven automation mandates.
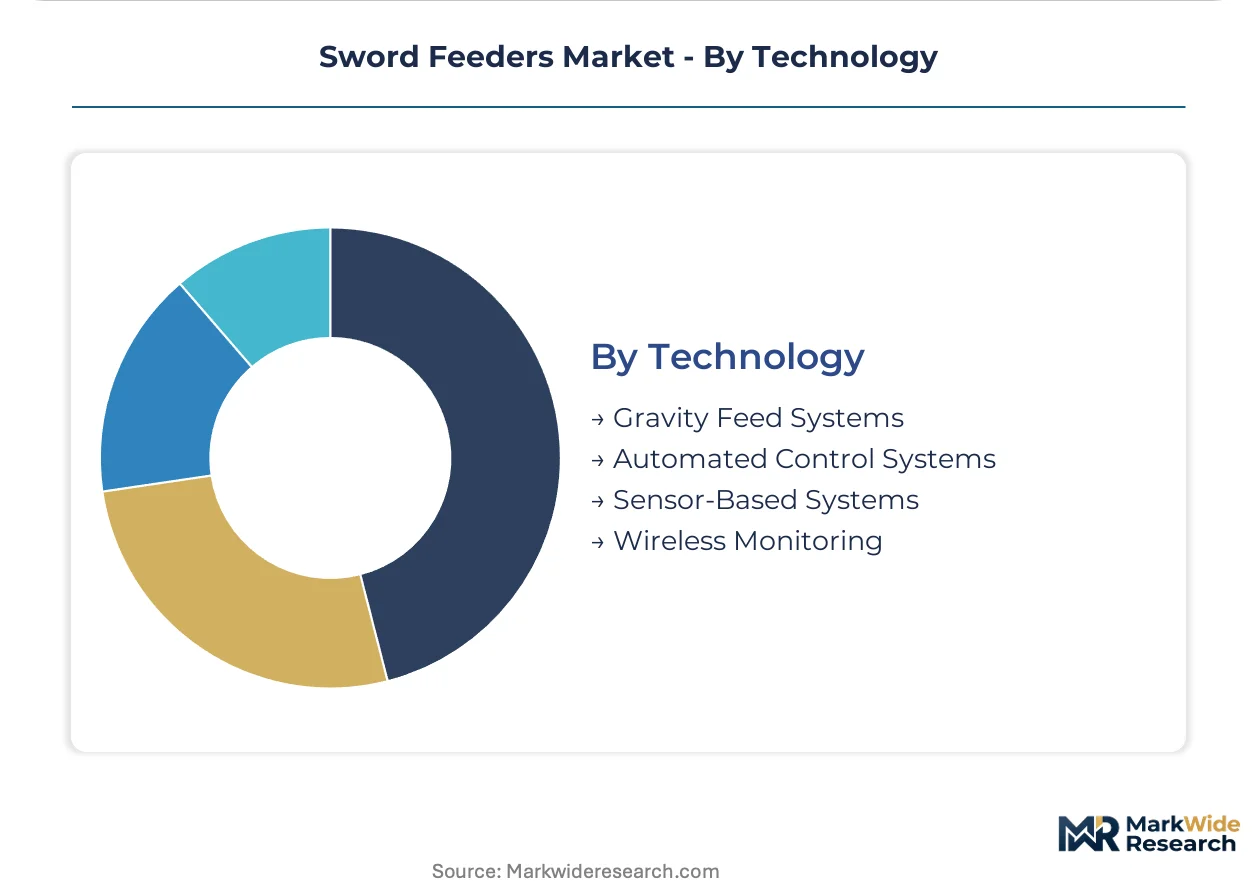
Technology:
Control-system architecture determines margin pool distribution and vendor competitive moat durability.
- Sensor-Based Systems:Machine-vision pellet recognition with spectral analysis and weight-based feedback loops enables real-time dispensing adjustment. These units are compressing calibration-service revenue windows while elevating firmware complexity as the primary margin determinant across automated portfolios.
- Automated Control Systems:Programmable logic controllers with auger-speed modulation and timer-based scheduling anchor mid-market positioning. China's MIIT GB-standard electromagnetic compatibility mandates are accelerating certification timelines for these networked configurations.
- Gravity Feed Systems:Passive mechanical designs without electronic components persist in manual-feeder categories.
- Wireless Monitoring:Cellular or LoRaWAN connectivity modules enabling cloud-platform data transmission satisfy procurement requirements for remote diagnostics in dispersed operations.
Automated Control Systems retain the dominant installed base, though Sensor-Based Systems show the steepest expansion trajectory as optical-weight feedback convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scaled manufacturing of precision-molded dispensing components clusters in China's Guangdong province, creating geographic vulnerability to logistics disruptions while narrowing cost gaps with legacy European suppliers. Southeast Asian aquaculture operators drive procurement volume through mechanized feeding infrastructure expansion.
China
Guangdong province hosts the dominant concentration of dispensing mechanism manufacturing, with scaled production lines supplying precision-molded components to domestic and export markets. MIIT guidelines on networked farm equipment interoperability mandate open data-interface standards for sensor-based feeding systems. Shenzhen and Foshan industrial clusters anchor firmware development and IoT module assembly operations serving commercial aquaculture tenders.
Vietnam
Mekong Delta farming clusters exceeding fifty hectares each deploy machine-vision pellet recognition systems to compress labor cost structures in high-density shrimp and catfish operations. The country's Ministry of Agriculture and Rural Development coordinates mechanization subsidies through provincial extension programs. Can Tho and An Giang provinces concentrate procurement activity for automated control systems with performance-guarantee fee structures.
Thailand
Industrial prawn farming cooperatives unbundle after-sales service contracts in favor of feed-conversion ratio improvement guarantees. The Thai Industrial Standards Institute enforces electromagnetic compatibility certification for imported networked farm equipment. Chanthaburi and Surat Thani provinces host tender evaluations that weight real-time remote diagnostics above dense local technician networks.
Indonesia
Maritime logistics barriers across the archipelago have slowed mechanized feeder deployment, creating whitespace for ruggedized, low-bandwidth units. The Ministry of Marine Affairs and Fisheries promotes aquaculture mechanization through regional development programs. Sulawesi and Sumatra farming operations represent priority zones for portable battery-powered feeder penetration.
United States
EPA water-quality runoff standards and FDA feed-contamination prevention protocols jointly shape product compliance requirements for commercial aquaculture procurement. The USDA Agricultural Research Service funds precision feeding technology validation trials. Gulf Coast shrimp farming operations in Texas and Louisiana concentrate demand for sensor-verified portion-accuracy systems.
Sword Feeders Market Competitive Landscape
Consumer-electronics conglomerates and dedicated pet-technology specialists split the market along ecosystem-bundling versus veterinary-validation vectors. The vendor base organizes into three strategic archetypes: platform-integrated consumer brands, precision-aquaculture equipment fabricators, and veterinary-partnership service providers. Competitive intensity centers on M&A activity targeting IoT module capabilities and strategic partnerships with cloud-analytics platforms.
Within the platform-integrated tier, Xiaomi anchors ecosystem bundling with existing smart-home infrastructure. PETKIT exemplifies vertical integration across plastic injection and IoT module assembly. WOPET occupies a position within the veterinary-validation archetype through partnership programs that validate portion-accuracy claims. These three entities represent divergent strategic postures rather than direct product competition.
| Leading Market Players |
|---|
| PETKIT |
| Dogness |
| Xiaomi |
| PetSafe |
| Sure Petcare |
| PETLIBRO |
| WOPET |
| Whisker |
| Catit |
| Others |
Value Network & Pricing Analysis
Overcapacity in Guangdong's precision-molding facilities is compressing component pricing while elevating bargaining power for aquaculture OEMs procuring at volume. This utilization dynamic simultaneously pressures mid-tier manufacturers to absorb feedstock volatility and accelerates consolidation toward vertically integrated suppliers with captive polymer sourcing.
Pricing Analysis
China's MIIT GB-standard electromagnetic compatibility certification dictates the pricing tier structure across automated sword feeder portfolios, separating sensor-integrated systems from basic programmable units. Three-tier pricing structure across premium, standard, and economy levels reflects firmware complexity, optical recognition capability, and after-sales bundling intensity. Cost compression in standard-tier auger-screw mechanisms is intensifying because engineering-grade polymer feedstock prices track volatile petrochemical indices. Smallholder cooperatives in Vietnam's Mekong Delta exhibit the highest price sensitivity, while Thailand's industrial prawn farming cooperatives prioritize performance-guarantee fee structures over capital expenditure minimization.
Supply Chain Analysis
Export-control restrictions on machine-vision sensor arrays and spectral analysis modules limit technology flows into Southeast Asian assembly operations, constraining local firmware development capacity. Manufacturing gravity centers on China's Guangdong province, South Korea's Gyeonggi-do cluster, and Taiwan's precision component fabricators. The supply chain draws from engineering-grade polymers, stainless-steel feed-grade alloys, and LoRaWAN connectivity modules. Single-source vulnerability concentrates in Guangdong's dispensing mechanism production, where regional logistics disruptions or policy shifts would cascade through global aquaculture equipment procurement. Distribution runs through OEM direct sales for large pond-array deployments and agricultural equipment distributors for fragmented smallholder channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Indonesia's archipelago farming operations and Thailand's unbundled service contracting creates multiple whitespace niches for specialized entrants. Procurement sophistication divergence between industrial aquaculture operators and capital-constrained cooperatives rewards targeted portfolio positioning over broad market coverage.
For Market Incumbents: Harden firmware update infrastructure as the primary competitive moat as machine-vision pellet recognition renders manual calibration protocols obsolete. Accelerate cloud-platform development timelines to offset MIIT-mandated open data-interface standards that fragment proprietary ecosystem lock-in. Consolidate backward integration into precision-molded dispensing component production to offset polymer feedstock price volatility squeezing mid-tier margin buffers.
For New Entrants and Emerging Players: Build out ruggedized, low-bandwidth portable feeder units targeting Indonesia's Sulawesi and Sumatra farming operations where maritime logistics barriers have slowed mechanized deployment. Prioritize veterinary-partnership programs that validate portion-accuracy claims, mirroring WOPET's differentiation archetype in consumer-adjacent channels. Pursue performance-guarantee fee structures tied to feed-conversion ratio improvements rather than equipment-sales margins.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-based system vendors with cloud-analytics platforms and remote diagnostics capabilities. Long-term viability over the projection horizon favors acquisition targets with firmware complexity advantages and established MIIT certification pathways. Monitor procurement officer behavioral shifts in Thailand's industrial prawn farming cooperatives as the inflection signal for unbundled service contract adoption accelerating across Southeast Asian aquaculture tenders.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Platform Development | MIIT open data-interface mandates fragment hardware-software bundling strategies across Guangdong manufacturers. |
| Veterinary Partnership Programs | Portion-accuracy validation opens consumer-adjacent channels in ornamental aquarium and backyard pond segments. |
| Backward Integration into Polymers | Captive supply of engineering-grade resins insulates margin buffers from petrochemical index volatility. |
| Performance-Guarantee Fee Structures | Thailand's procurement officers now weight feed-conversion ratio improvements above dense technician networks. |
| Ruggedized Low-Bandwidth Unit Design | Indonesia's maritime logistics barriers create first-mover whitespace for battery-powered mobile feeders. |
Research Methodology
Operator-level perspectives from aquaculture procurement officers, pond-array maintenance directors, agricultural equipment distributors, and firmware calibration technicians anchored the qualitative base for this study. Primary field engagement with Vietnam's Mekong Delta farming clusters and Thailand's industrial prawn cooperatives combined with secondary validation from MIIT certification databases, ASEAN customs trade records, and EPA water-quality compliance filings. Bottom-up unit economics modeling triangulated against top-down market sizing across sensor-based, automated control, and manual feeder categories.
Scenario-bracketing around feedstock price volatility, certification timeline compression, and archipelago logistics constraints shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, control technology sophistication, end-user operational scale, and regional regulatory cluster. CAGRs derived from installed base growth rates, replacement cycle acceleration, and technology substitution curves. Industry-specific forecast inputs incorporated MIIT smart-equipment certification velocity and EU Green Deal aquaculture sustainability mandate adoption trajectories.
Stress conditions across polymer feedstock indices, electromagnetic compatibility certification delays, and maritime logistics disruption severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding smallholder capital constraint persistence and industrial operator procurement sophistication evolution. Material shifts in China's dual carbon goals enforcement or ASEAN aquaculture mechanization subsidy allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Nugget Ice Machines Market
Food Processing Equipment
Food Slicer and Dicer Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
Food Recycling Machines Market
Food Processing Equipment
Brewing Chiller Market
Food Processing Equipment
Beer Brewing Equipment Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
North America Cold Storage Market
Food Processing Equipment
Dual-Ovenable Cook Trays Market
Food Processing Equipment
Food Processor Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Multiple Unit Pellet Systems Market