
 Holding and Proofing Cabinet Market | 2026-2036
Holding and Proofing Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Holding and Proofing Cabinet Market Insights
Modular cabinet configurations that combine holding and proofing functions in stackable units is expanding buyer flexibility for operators with limited kitchen footprints. Alto Shaam Inc. anchors this trend through its Halo Heat technology platform, which sustains precise low-temperature holding without forced air. Henny Penny Corp. competes with programmable control systems that extend operational automation across multi-unit restaurant chains. Duke Manufacturing occupies the institutional segment with heavy-duty stainless-steel construction designed for high-volume cafeterias and healthcare foodservice.
A holding and proofing cabinet is an insulated enclosure engineered to maintain prepared food or dough within precise temperature and humidity parameters, typically operating between 80°F and 200°F with relative humidity control up to 95% in proofing modes. Its primary purpose is to bridge production and service timelines while preserving food safety, texture, and yield in commercial kitchens. Floor model configurations dominate installed base volumes across full-service restaurants due to their capacity and durability, while mobile units represent the fastest-growing product type as catering services and pop-up operations prioritize equipment portability. Humidity-controlled temperature systems command premium positioning within the segment, reflecting bakeries' exacting requirements for crust development and fermentation consistency.
NSF International standards govern sanitation and materials safety for commercial food equipment across North America, while the U.S. Department of Energy sets minimum efficiency thresholds that filter non-compliant products from federal procurement channels. The European Union's Ecodesign Directive and CE marking requirements shape market access for manufacturers exporting into EU member states, particularly regarding insulation performance and standby power consumption. Stakeholders must monitor evolving state-level electrification mandates and building code amendments that increasingly restrict gas-powered kitchen equipment in new commercial construction.
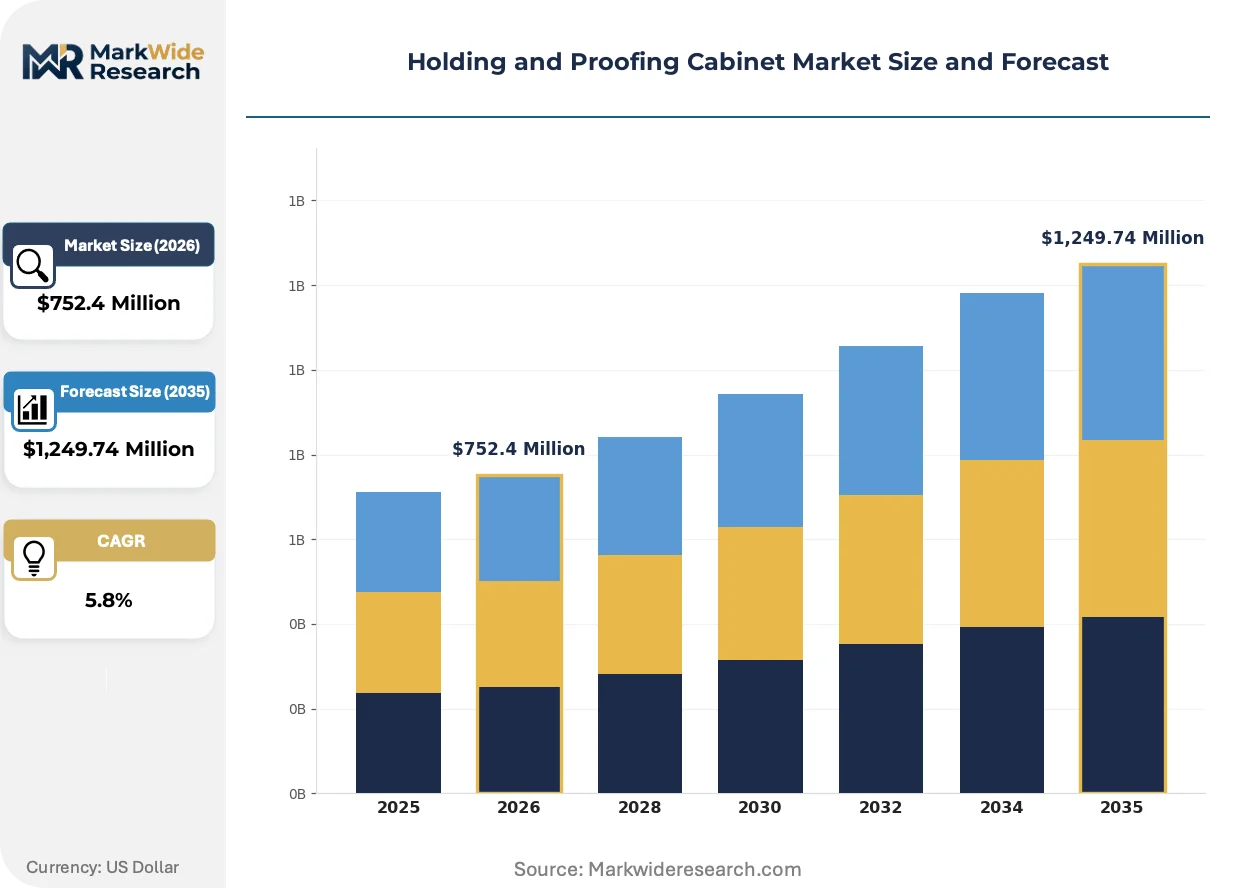
Market Dynamics
ENERGY STAR efficiency thresholds and evolving NSF International sanitation standards are compressing product development cycles, forcing manufacturers to redesign thermal management systems and control architectures ahead of standard renewal deadlines.
Growth Catalysts
- Quick-service restaurant expansion:Chains are deploying hot-holding infrastructure across new locations to standardize food quality and reduce labor dependency during peak service windows.
- NSF International sanitation mandates:Updated materials safety and cleanability requirements are accelerating replacement cycles in institutional kitchens and healthcare foodservice operations.
- Ghost kitchen proliferation:Delivery-only food production facilities in the United States require compact, high-throughput holding equipment to bridge batch cooking and order fulfillment timing.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 stainless steel price fluctuations compress margin visibility for manufacturers of heavy-duty institutional cabinets.
- Supply concentration in control electronics:Programmable logic controllers and humidity sensors rely on concentrated semiconductor sourcing, exposing lead times to foundry capacity constraints.
- Gas equipment restrictions:State-level electrification mandates in new commercial construction are rendering gas-powered proofing cabinets non-compliant in certain jurisdictions.
Strategic Opportunities
- Underpenetrated catering services:Mobile holding and proofing units address pop-up operations and event foodservice with equipment portability requirements.
- IoT-enabled predictive maintenance:Remote temperature monitoring and automated alert systems converge with cloud-based kitchen management platforms.
- European Ecodesign Directive alignment:Insulation performance and standby power consumption standards create competitive differentiation for export-ready manufacturers.
Industry Challenges
- Certification timeline compression:NSF International and ENERGY STAR recertification cycles demand concurrent engineering validation, stretching R&D resource allocation.
- Integration complexity with legacy kitchen systems:New humidity-controlled temperature cabinets must interface with existing ventilation hoods and building management systems without infrastructure overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Holding and Proofing Cabinet Market |
| Market Size in 2026 | $752.4 Million |
| Market Size in 2035 | $1,249.74 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Floor Model, Mobile, Custom Built End User: Restaurants, Bakeries, Catering Services, Food Retailers Temperature Control: Ambient, Heated, Humidity Controlled, Combination Control Type: Dials, Digital Display, Programmable, Manual |
| Companies Covered | Alto Shaam Inc., Henny Penny Corp., Vulcan, Duke Manufacturing, Carter-Hoffmann, Cres-Cor, BevLes, Tutco-Farnam, Lockwood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holding and Proofing Cabinet Market Trends and Innovations
Equipment architecture is fragmenting into configurable subsystems that operators can recombine based on menu mix and spatial constraints, displacing fixed-configuration cabinet purchasing.
Heating technology is modularizing around low-temperature radiant systems that eliminate forced air circulation, reducing moisture loss in held proteins and baked goods. Full-service restaurants are adopting these platforms fastest, retrofitting existing kitchen lines without ductwork modifications. This approach is modularizing supplier relationships, as operators mix holding, proofing, and finishing equipment from specialized vendors rather than single-source procurement.
The U.S. Department of Energy is tightening minimum efficiency thresholds for commercial food equipment, filtering non-compliant products from federal procurement channels and state rebate programs. Manufacturers must redesign insulation packages and control algorithms to maintain performance while reducing standby power draw. Healthcare and institutional cafeterias face the steepest compliance burden, as their extended holding cycles magnify energy consumption exposure.
Buyer preference is fragmenting across certification tiers rather than brand loyalty, with NSF listing status and ENERGY STAR qualification driving short-list inclusion ahead of historical supplier relationships. Distributor sales teams are repositioning as compliance consultants, translating regulatory requirements into equipment specifications. This behavior shift concentrates most visibly in the United States, where replacement-driven purchasing and fragmented operator ownership reward specification clarity over incumbent relationships.
Holding and Proofing Cabinet Market Segmentation
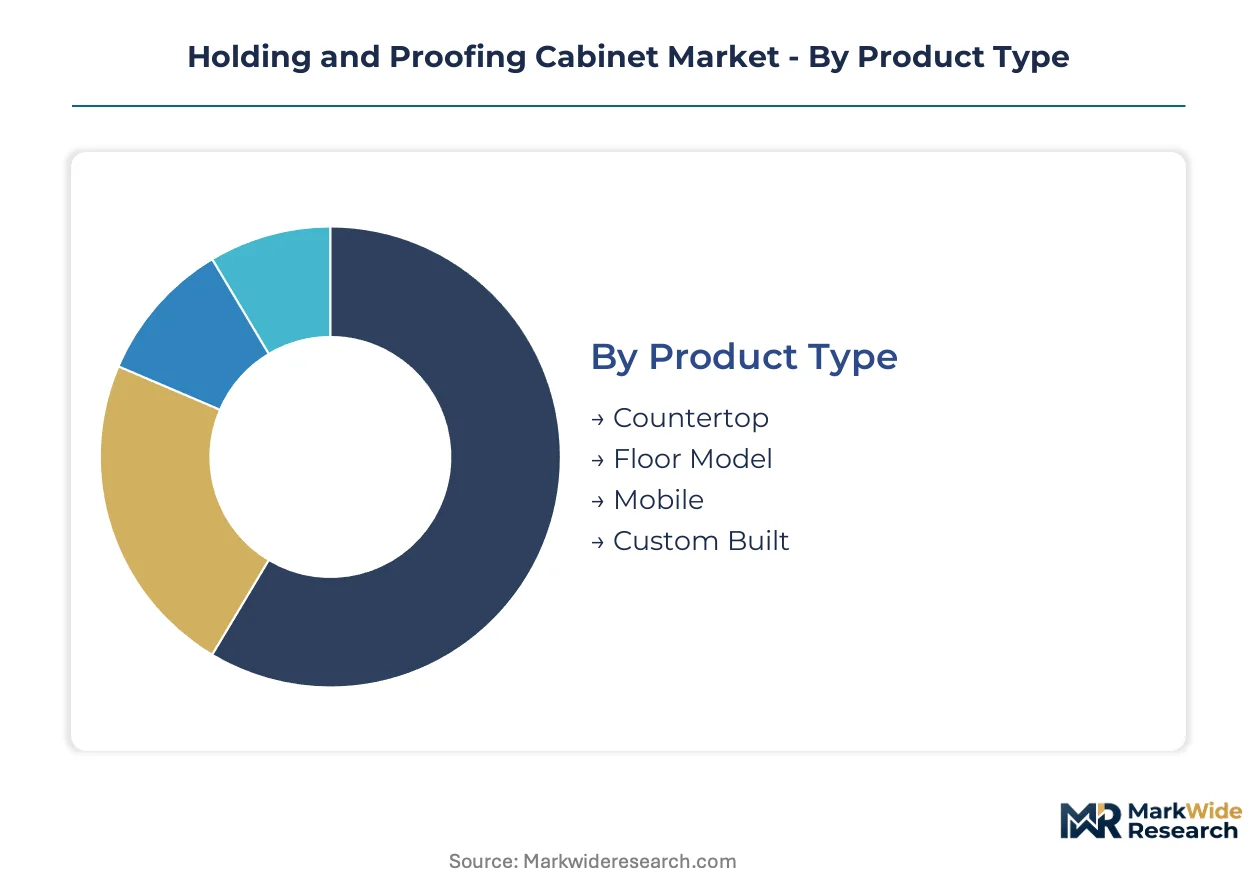
Holding and proofing cabinet procurement splits sharply between replacement-driven institutional buyers and expansion-focused quick-service chains. Segmentation clarity determines specification accuracy across divergent operational environments.
Product Type:
Replacement cycles vary dramatically by mounting configuration and mobility requirements, with institutional buyers favoring durability over flexibility while emerging operators prioritize adaptability.
- Floor Model:These full-height insulated enclosures anchor permanent kitchen lines with capacities exceeding 20 pan levels. Full-service restaurants in the United States drive replacement demand as legacy units reach end-of-life against tightened ENERGY STAR thresholds.
- Mobile:Castor-mounted units with detachable power connections enable rapid repositioning between prep stations and service points. Catering operations and ghost kitchens in dense urban markets favor these configurations for footprint flexibility and lease-term uncertainty.
- Countertop:Compact units designed for front-of-house finishing stations and limited-production bakeries.
- Custom Built:Application-specific dimensions and feature sets for integrated kitchen systems.
Floor Model sits at the top of the volume ranking, with Mobile climbing the fastest.
End User:
Cost tier differentiation separates specification-heavy institutional buyers from price-sensitive emerging operators, with certification requirements acting as the primary sorting mechanism.
- Restaurants:Full-service and quick-service chains deploy holding cabinets to bridge batch cooking and plate assembly. Chains expanding across the United States specify programmable humidity control to standardize product consistency across locations.
- Bakeries:Artisan and commercial producers require precise fermentation environments with relative humidity modulation up to 95%. Independent bakeries in metropolitan clusters prioritize crust development control and overnight proofing reliability.
- Catering Services:Event and institutional caterers demand transportable thermal management for off-premise service.
- Food Retailers:Grocery delis and prepared food departments use holding equipment for grab-and-go program expansion.
Restaurants command the largest installed base, while Catering Services gains share fastest among emerging operator categories.
Temperature Control:
Application maturity determines technology penetration, with humidity-controlled systems commanding premium positioning in precision-dependent segments while basic heated cabinets saturate high-volume institutional procurement.
- Humidity Controlled:Active moisture injection and extraction systems maintain 80-95% relative humidity for dough fermentation and protein holding. Bakeries and healthcare foodservice operations in the United States specify these systems to prevent crust hardening and yield loss.
- Heated:Dry thermal maintenance between 150-200°F dominates quick-service holding applications. Chains standardize on these units for fried protein and side dish retention across high-turnover locations.
- Ambient:Unheated insulated enclosures for dough resting and controlled cooling applications.
- Combination:Switchable modes enabling proofing and holding functions within single cabinet architecture.
Heated configurations maintain volume leadership, with Humidity Controlled systems showing the steepest expansion trajectory in premium segments.
Control Type:
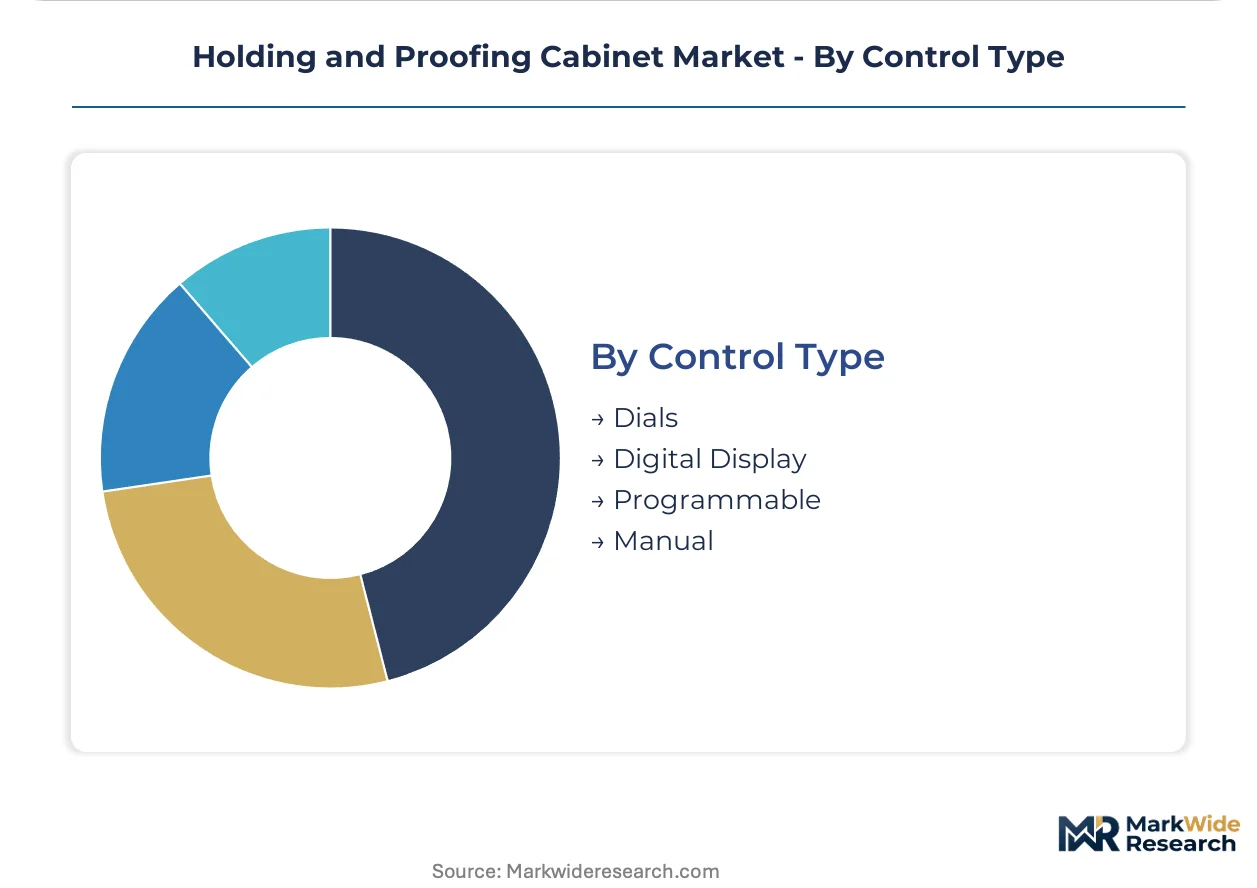
Customer type fragmentation separates enterprise chains seeking operational standardization from independent operators prioritizing capital efficiency, with programmable systems capturing multi-unit procurement while manual controls retain single-location share.
- Programmable:Microprocessor-based systems store multiple temperature and humidity profiles for menu-specific holding protocols. Multi-unit restaurant chains deploying across the United States mandate these controls to reduce training variance and ensure product consistency.
- Digital Display:Electronic temperature readouts with push-button adjustment for mid-market operators seeking precision without programmability complexity.
- Dials:Analog thermostatic controls for cost-constrained replacement procurement in institutional settings.
- Manual:Basic on/off or rheostat-controlled systems for minimal-holding applications and backup equipment.
Digital Display occupies the midpoint of volume distribution, with Programmable controls gaining fastest among chain expansion segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial kitchen equipment manufacturing first achieved industrial scale in the United States during the post-war restaurant expansion, establishing design standards and distribution networks that persist across North American foodservice infrastructure today.
United States
Quick-service restaurant chains and ghost kitchens drive replacement cycles for programmable humidity-controlled cabinets. The Department of Energy's tightening ENERGY STAR thresholds filter non-compliant products from federal procurement channels. Equipment clusters concentrate in Wisconsin and Ohio, where stainless-steel fabrication heritage supports component supply for institutional buyers.
Germany
Bakery chains and commercial producers demand precision fermentation environments with relative humidity modulation up to 95%. The Ecodesign Directive shapes insulation performance and standby power consumption standards for export-ready manufacturers. Industrial equipment manufacturing concentrates in Baden-Württemberg, where thermal engineering expertise feeds into commercial foodservice component supply.
China
Hotel chains and catering services expand hot-holding infrastructure across tier-one and tier-two cities. GB standards and MIIT efficiency regulations govern materials safety and energy consumption thresholds for domestic and export markets. Manufacturing clusters in Guangdong and Zhejiang provinces supply cost-optimized mobile and countertop configurations for emerging operators.
Japan
Compact kitchen footprints in urban restaurants favor stackable modular configurations combining holding and proofing functions. METI efficiency programs and JIS standards regulate thermal management performance and sanitation compliance. Equipment design centers in the Nagoya region specialize in precision control systems for bakery and healthcare foodservice applications.
United Kingdom
Independent bakeries and food retailers prioritize crust development control and overnight proofing reliability. CE marking requirements and evolving building code amendments restrict gas-powered equipment in new commercial construction. London and the Southeast corridor concentrate demand for premium humidity-controlled systems in high-density urban foodservice operations.
Holding and Proofing Cabinet Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and control system sophistication, with programmable microprocessor-based systems commanding price multiples over analog thermostatic alternatives. The vendor base spans multinational foodservice equipment conglomerates, regional stainless-steel fabricators, and specialized thermal control technology developers. Three archetypes dominate: integrated kitchen equipment platforms with broad holding and proofing portfolios, component specialists focused on humidity sensors and programmable logic controllers, and contract manufacturers serving private-label distributor brands. Competitive moves concentrate on technology licensing for IoT-enabled predictive maintenance and geographic expansion through distributor network partnerships.
Among North American equipment platforms, Alto Shaam Inc. and Henny Penny Corp. exemplify divergent technology strategies within the premium tier, while Duke Manufacturing occupies a distinct position in heavy-duty institutional construction. These three anchors represent the spectrum from precision low-temperature radiant systems to programmable automation and high-volume cafeteria durability, with each sitting within a different procurement channel based on end-user scale and specification complexity.
| Leading Market Players |
|---|
| Alto Shaam Inc. |
| Henny Penny Corp. |
| Vulcan |
| Duke Manufacturing |
| Carter-Hoffmann |
| Cres-Cor |
| BevLes |
| Tutco-Farnam |
| Lockwood |
| Others |
Pricing and Supply Chain Analysis
Grade 304 stainless steel price volatility cascades through manufacturer cost structures into three distinct procurement tiers, with institutional buyers absorbing premium pricing for heavy-duty construction while emerging operators trade durability for capital efficiency in mobile configurations.
Pricing Analysis
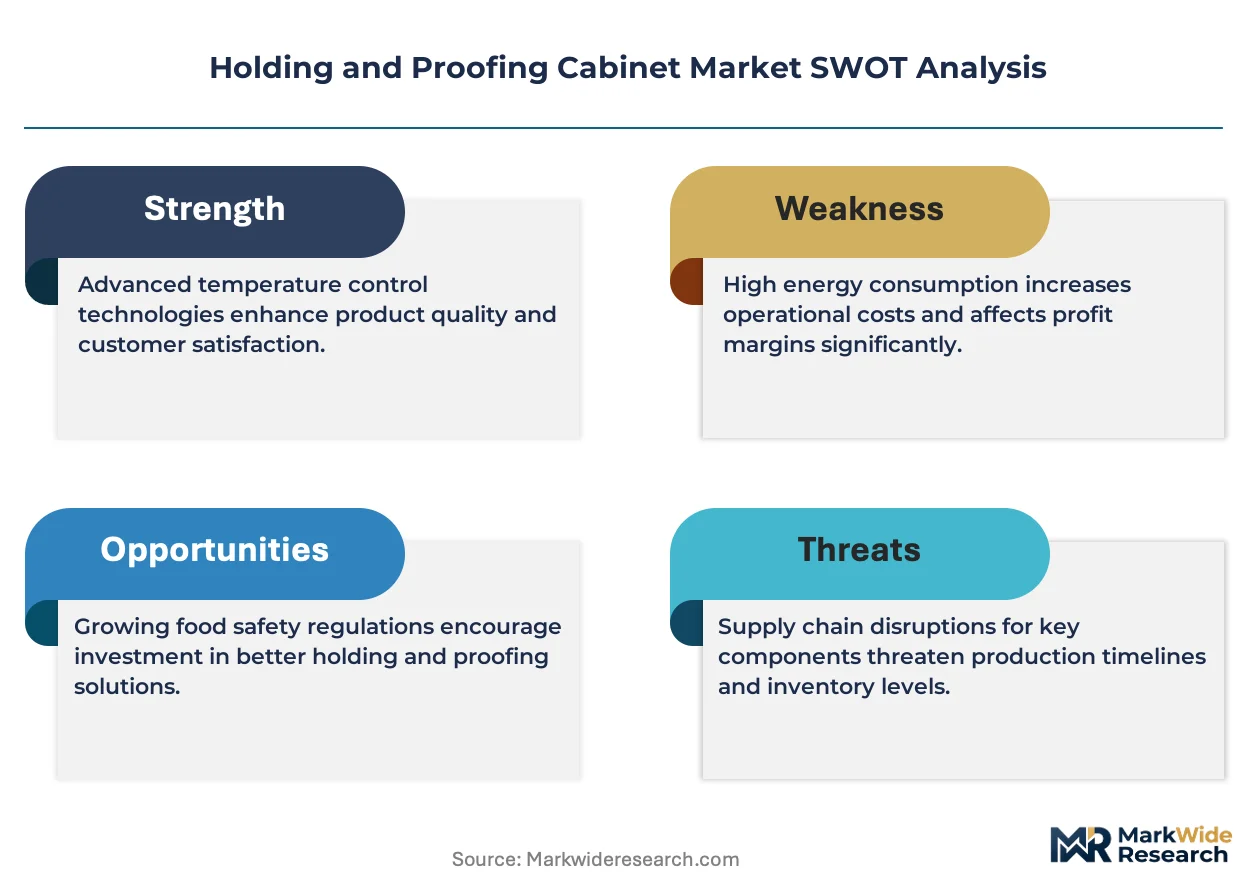
Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified programmable systems from basic heated cabinets and manual-control institutional units. Price differentiation rests on certification grade and control system sophistication, with ENERGY STAR qualification commanding measurable premiums. Pricing pressure stems from semiconductor input costs affecting programmable logic controllers. Quick-service chains show lowest price sensitivity, prioritizing operational standardization over upfront capital outlay.
Supply Chain Analysis
Programmable logic controller supply rests on concentrated semiconductor foundry capacity in Taiwan, South Korea, and China. Stainless steel sheet and humidity sensor assemblies draw from U.S. and German metalworking clusters. Single-source vulnerability in microprocessor sourcing exposes lead times to foundry allocation decisions. Distribution runs through foodservice equipment distributors repositioning as compliance consultants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with ENERGY STAR threshold tightening and NSF recertification cycles creating predictable replacement demand windows for prepared equipment.
For Market Incumbents: To counter margin compression from stainless steel input volatility, deepen captive supply of Grade 304 sheet through backward integration into Midwest metalworking clusters. Accelerate IoT-enabled predictive maintenance R&D to differentiate against programmable control commoditization. For New Entrants and Emerging Players: Ecodesign Directive alignment in Germany opens a window for insulation-performance specialists to capture export-ready manufacturer procurement. Target mobile unit configurations for underpenetrated catering services in dense U.S. urban markets. Lead with cloud-based kitchen management platform integration as primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where programmable control development costs outstrip mid-tier manufacturer R&D budgets. Five-to-ten-year viability favors platforms with installed base scale for aftermarket service annuity streams. Target acquisition archetype: humidity sensor technology specialists with healthcare foodservice validation. Watch state-level gas equipment restriction passage as electrification mandate inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Remote temperature monitoring converges with cloud-based kitchen management platforms from ghost kitchen operators. |
| Backward Integration into Stainless Supply | Captive Grade 304 sourcing insulates margin visibility against commodity price swings in institutional segments. |
| ENERGY STAR Certification Investment | Federal procurement channel access and state rebate program eligibility filter non-compliant competitors from bidding. |
| Mobile Unit Configuration Expansion | Catering services and pop-up operations prioritize equipment portability for lease-term uncertainty in urban markets. |
| Humidity Sensor Technology Licensing | Precision fermentation control transfers from bakery chains into healthcare foodservice yield preservation applications. |
Research Methodology
Bottom-up restaurant and bakery operator modeling reconciled against top-down equipment manufacturer production tracking forms the analytical core. Primary interviews with commercial kitchen equipment distributors, foodservice chain procurement directors, institutional cafeteria maintenance managers, and humidity control system engineers combined with secondary validation from NSF International certification databases, ENERGY STAR qualified product listings, and U.S. Department of Energy appliance standards filings.
Historical trendline analysis across replacement cycle data and regulatory compliance deadline clustering informed projection framework construction. Segmentation dimensions modeled include mounting configuration, end-user operational scale, temperature control sophistication, and control system architecture across the analysis window. CAGRs derived from equipment shipment volumes reconciled against end-user facility expansion permits and ghost kitchen licensing records.
Revisions become necessary when ENERGY STAR threshold implementation delays or stainless steel price spike persistence materialize beyond modeled scenarios. Forecasts reflect documented assumptions regarding regulatory compliance adoption curves and replacement cycle acceleration patterns. A small set of triggers—state electrification mandate passage, semiconductor foundry allocation shocks, and Ecodesign Directive enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Double Stack Oven Market
Food Processing Equipment
Decanter Centrifuge Market
Food Processing Equipment
Bottling Line Machinery Market
Food Processing Equipment
Flakes Making Machine Market
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Brewing Chiller Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Sword Feeders Market
Food Processing Equipment
Spray Dried Food Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Ice Cream Freezer Market