
 Global Food Dehydrators Market | 2026-2036
Global Food Dehydrators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Dehydrators Market Foresight
The food dehydrator category is pivoting along a sharp equipment-grade divide. Industrial-grade cabinet dehydrators with programmable humidity controls now command price multiples above countertop tray units. Excalibur Dehydrator leverages its vertical integration into heating element manufacturing to sustain margin control across premium residential lines. Hamilton Beach Brands competes through mass-market distribution density, while Tribest Corporation specializes in compact convection systems for raw-food enthusiasts.
Food dehydrators are electromechanical appliances that reduce moisture content in organic materials through controlled heat and airflow, typically operating between 95°F and 165°F depending on substrate sensitivity; their primary purpose is shelf-life extension without chemical preservatives. Tray dehydrators occupy the entry-level residential segment where price sensitivity dominates purchase decisions. Vacuum dehydrators command the fastest expansion in research institutions and specialty bakeries, where nutrient retention specifications justify capital intensity. Freeze drying technology anchors the highest margin pool, though hot air drying still leads installed base across food processing plants.
The EU Green Deal and REACH chemical safety standards shape European demand by mandating energy efficiency disclosures and restricting certain polymer contact materials in food equipment. FDA food contact substance regulations govern US market access, while China's GB standards and dual carbon goals push domestic manufacturers toward heat pump drying architectures. Stakeholders must weigh regulatory compliance timelines against technology substitution risks as osmotic drying and microwave methods gain process validation.
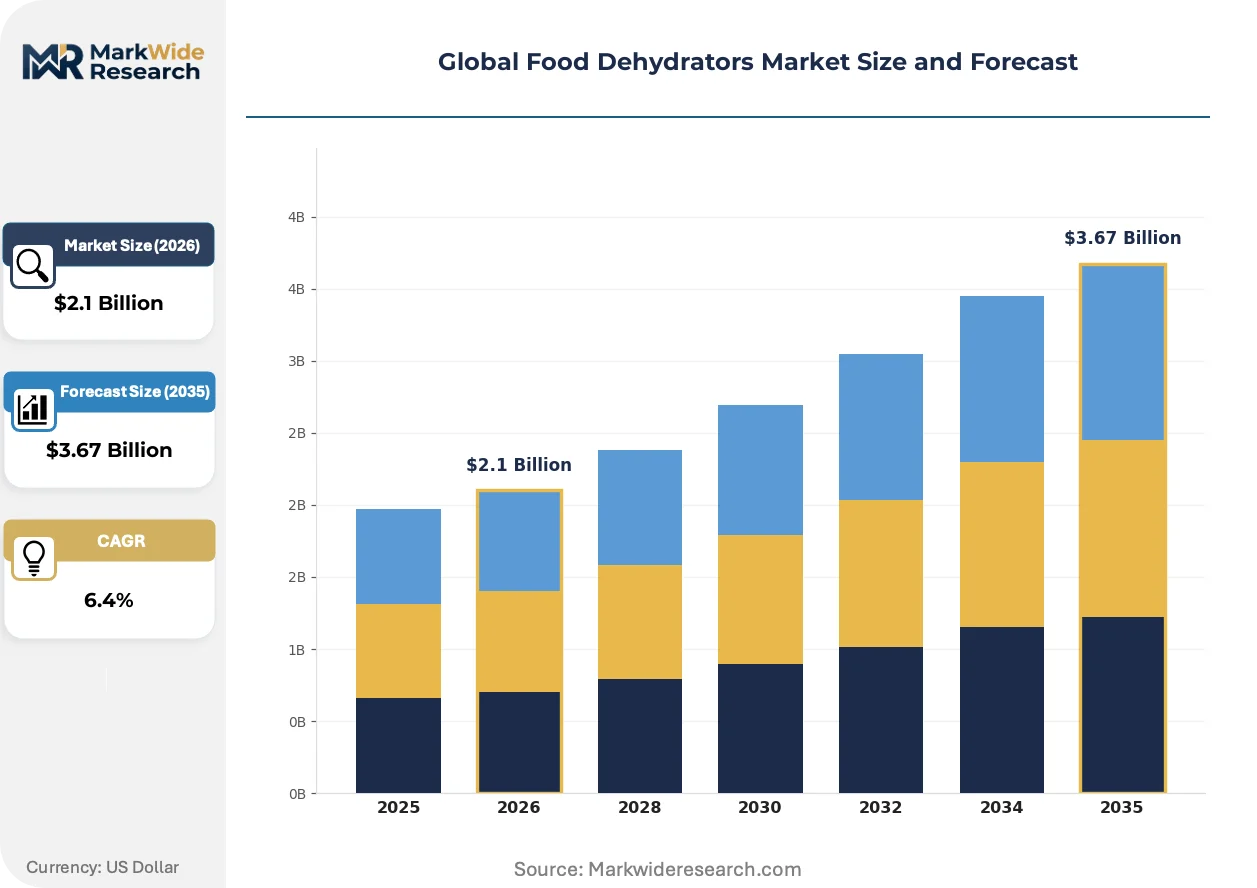
Market Dynamics
Energy efficiency mandates under the EU Green Deal are compressing payback periods for heat pump dehydrator investments, while precision humidity control specifications from specialty bakeries are fragmenting equipment tiers into discrete performance bands.
Growth Catalysts
- EU Green Deal food waste targets:Processors across Germany, France, and Italy face binding 2030 reduction mandates that accelerate capital deployment into automated drying lines with real-time moisture monitoring.
- Heat pump drying architectures:China's dual carbon goals and GB 21520 energy efficiency standards are forcing domestic manufacturers to abandon resistance heating in favor of vapor compression systems with coefficient of performance above 3.0.
- Raw-food consumer segment:Tribest Corporation's compact convection systems have validated demand for nutrient-retentive residential units operating below 118°F, expanding the addressable base beyond traditional preservation users.
Market Restraints
- Stainless steel input volatility:304-grade sheet metal constitutes 35-45% of cabinet dehydrator BOM cost, exposing Mittelstand processors in Baden-Württemberg to nickel price swings that compress quoted equipment margins.
- Freeze dryer supply concentration:Vacuum pump and refrigeration stack sourcing clusters in Switzerland and Germany, creating 16-24 week lead time exposure for North American research institutions expanding lyophilization capacity.
- REACH polymer restrictions:ECHA's evolving food contact material classifications threaten existing gasket and tray formulations, forcing reformulation cycles that delay CE marking renewals by 8-14 months.
Strategic Opportunities
- India FSSAI modernization:The 2023 Food Safety and Standards (Packaging) Regulation mandates shelf-life extension technologies for spice and dried fruit exports, opening procurement channels for EU-certified dehydrator OEMs in Maharashtra and Karnataka processing clusters.
- Solar-thermal hybrid systems:Convergence of photovoltaic generation and absorption heat pumps enables off-grid drying cooperatives in Kenya and Ethiopia to bypass diesel dependency for mango and coffee cherry processing.
- Direct-to-processor digital sales:Hamilton Beach Brands' mass-market distribution density model is being replicated by industrial OEMs through equipment-as-a-service platforms that bundle predictive maintenance with humidity sensor subscriptions.
Industry Challenges
- Multiphysics simulation talent scarcity:CFD modeling for airflow uniformity in cabinet designs requires rare cross-training in heat transfer and food rheology, extending R&D cycles for mid-cap manufacturers without captive engineering academies.
- Legacy PLC integration friction:Brownfield food plants in Italy's Emilia-Romagna region face 12-18 month retrofit timelines when connecting programmable humidity controls to existing Siemens S7 or Rockwell Automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Dehydrators Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tray Dehydrators, Cabinet Dehydrators, Convection Dryers, Solar Dryers, Vacuum Dehydrators Technology: Hot Air Drying, Freeze Drying, Infrared Drying, Microwave Drying, Osmotic Drying Application: Fruit Preservation, Vegetable Processing, Meat Drying, Herbal Processing, Seafood Preparation End User: Food Processing Plants, Agricultural Cooperatives, Specialty Bakeries, Commercial Kitchens, Research Institutions |
| Companies Covered | Excalibur Dehydrator, NESCO, Hamilton Beach Brands, Koolatron Corporation, National Presto Industries, Tribest Corporation, LEM Products Holding, Aroma Housewares Company, STX International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Dehydrators Market Shifts & Advancements
Electromechanical control systems are yielding to edge-computing architectures that embed moisture prediction algorithms directly into heating element drivers, compressing the feedback loop between sensor input and thermal output.
Heat pump drying technology is consolidating its position in mid-capacity industrial installations by delivering specific moisture extraction rates of 3.5-4.2 kg per kilowatt-hour. Specialty bakeries in Bavaria and Rhône-Alpes are specifying these systems for sourdough starter and fruit leather production where enzyme preservation dictates tight temperature bands. The technology is consolidating vendor margins by collapsing the historical premium between resistance-heated and thermodynamically efficient equipment tiers.
REACH chemical safety standards are forcing reformulation of polymer contact materials in tray and gasket assemblies, with ECHA's 2024 restriction proposals targeting phthalate plasticizers common in silicone seals. Industrial OEMs serving EU markets must now maintain dual material BOMs—one REACH-compliant, one for less regulated export destinations—adding procurement complexity and inventory carrying cost. German processors are responding by demanding material passports that trace polymer provenance through three-tier supplier chains.
Service unbundling is fragmenting traditional equipment sales into discrete revenue streams: hardware, humidity sensor subscriptions, and predictive maintenance contracts. Large food cooperatives in Denmark and the Netherlands now procure drying capacity on throughput-guarantee terms rather than capital expenditure, transferring operational risk to OEM service organizations. This shift is most visible in dairy powder and yeast extract processing where uptime penalties exceed equipment lease payments.
Global Food Dehydrators Market Segmentation
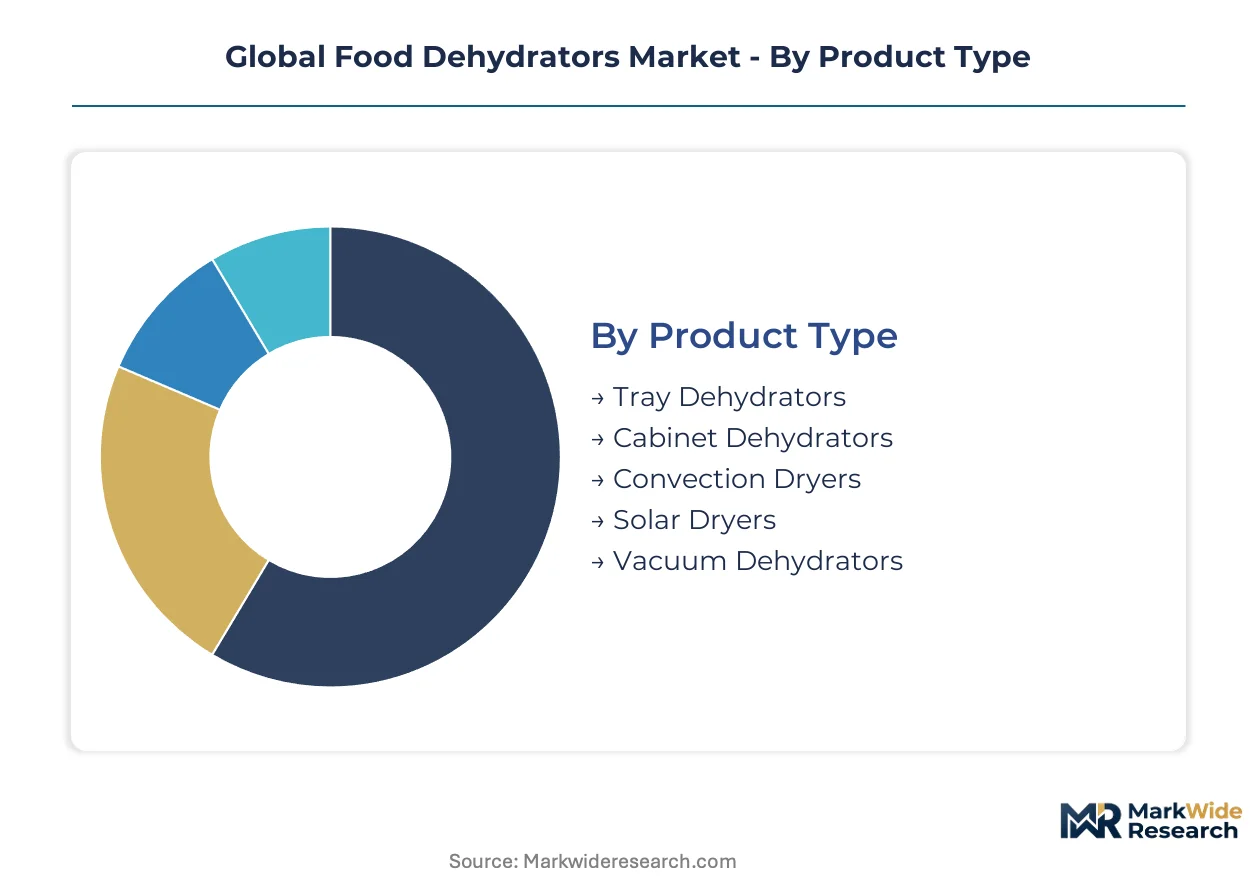
Equipment-grade stratification across food dehydrators creates distinct procurement behaviors between commodity preservation and precision nutrient retention. Segment boundaries harden around thermal control fidelity, with programmable humidity systems commanding multiples over fixed-temperature units.
Product Type:
Standardization dominates entry-level residential units while industrial applications demand bespoke cabinet configurations with zone-specific airflow engineering.
- Tray Dehydrators:Stackable polymer or stainless steel shelf systems with axial fan circulation occupy the mass-market residential tier. Demand clusters in North American and European households pursuing home preservation, constrained by countertop footprint limitations and noise sensitivity below 65 decibels.
- Cabinet Dehydrators:Vertical chamber designs with programmable humidity controls and multi-zone temperature regulation anchor industrial installations. Mittelstand food processors in Germany's Baden-Württemberg region specify these for automated fruit and vegetable lines, driven by EU Green Deal energy efficiency mandates and real-time moisture monitoring requirements.
- Convection Dryers:Forced-air circulation systems with recirculating airflow patterns serve mid-scale commercial operations.
- Solar Dryers:Passive or active thermal collection designs with photovoltaic hybrid options enable off-grid processing in Kenya and Ethiopia.
- Vacuum Dehydrators:Sub-atmospheric pressure systems with refrigeration stacks preserve heat-sensitive compounds for nutraceutical applications.
Most installed capacity flows through Cabinet Dehydrators. Expansion is steepest in Vacuum Dehydrators.
Technology:
Cost tier separation between mature thermal methods and capital-intensive precision systems determines adoption velocity across processor scale categories.
- Hot Air Drying:Convective heat transfer using resistance elements or gas combustion remains the dominant installed base across food processing plants. China's domestic manufacturers are abandoning this architecture under GB 21520 energy efficiency standards, forced toward heat pump alternatives with coefficient of performance above 3.0.
- Freeze Drying:Sublimation-based moisture removal under vacuum conditions delivers the highest nutrient retention specifications. Research institutions in Switzerland and Germany face 16-24 week lead times for vacuum pump and refrigeration stack procurement, concentrating supply risk in Alpine manufacturing clusters.
- Infrared Drying:Radiant heat transfer through ceramic or quartz elements offers rapid surface dehydration for thin-layer applications.
- Microwave Drying:Dielectric heating with volumetric moisture removal accelerates processing times for high-value substrates.
- Osmotic Drying:Hypertonic solution immersion preceding thermal treatment reduces energy intensity for fruit processing.
Volume concentration sits with Hot Air Drying. Steepest expansion trajectory belongs to Freeze Drying.
Application:
Customer type differentiation separates commodity-scale operations from premium ingredient producers with enzymatic preservation requirements.
- Fruit Preservation:Moisture reduction for shelf-stable snacks and baking ingredients spans residential through industrial scales. Specialty bakeries in France's Rhône-Alpes region specify precision systems for fruit leather production where temperature bands below 60°C preserve pectin structure and volatile aromatics.
- Vegetable Processing:Root and leafy crop dehydration for soup bases and instant meals drives demand in agricultural cooperatives. India's FSSAI 2023 packaging regulations mandate shelf-life extension technologies for spice and dried fruit exports, opening procurement channels in Maharashtra processing clusters.
- Meat Drying:Protein substrate dehydration with pathogen control requirements demands HACCP-compliant thermal profiles.
- Herbal Processing:Phytochemical retention specifications govern temperature and duration parameters for medicinal applications.
- Seafood Preparation:Salt-assisted moisture reduction for jerky and powder products requires corrosion-resistant chamber materials.
Most throughput volume processes through Fruit Preservation. Gaining share fastest is Vegetable Processing.
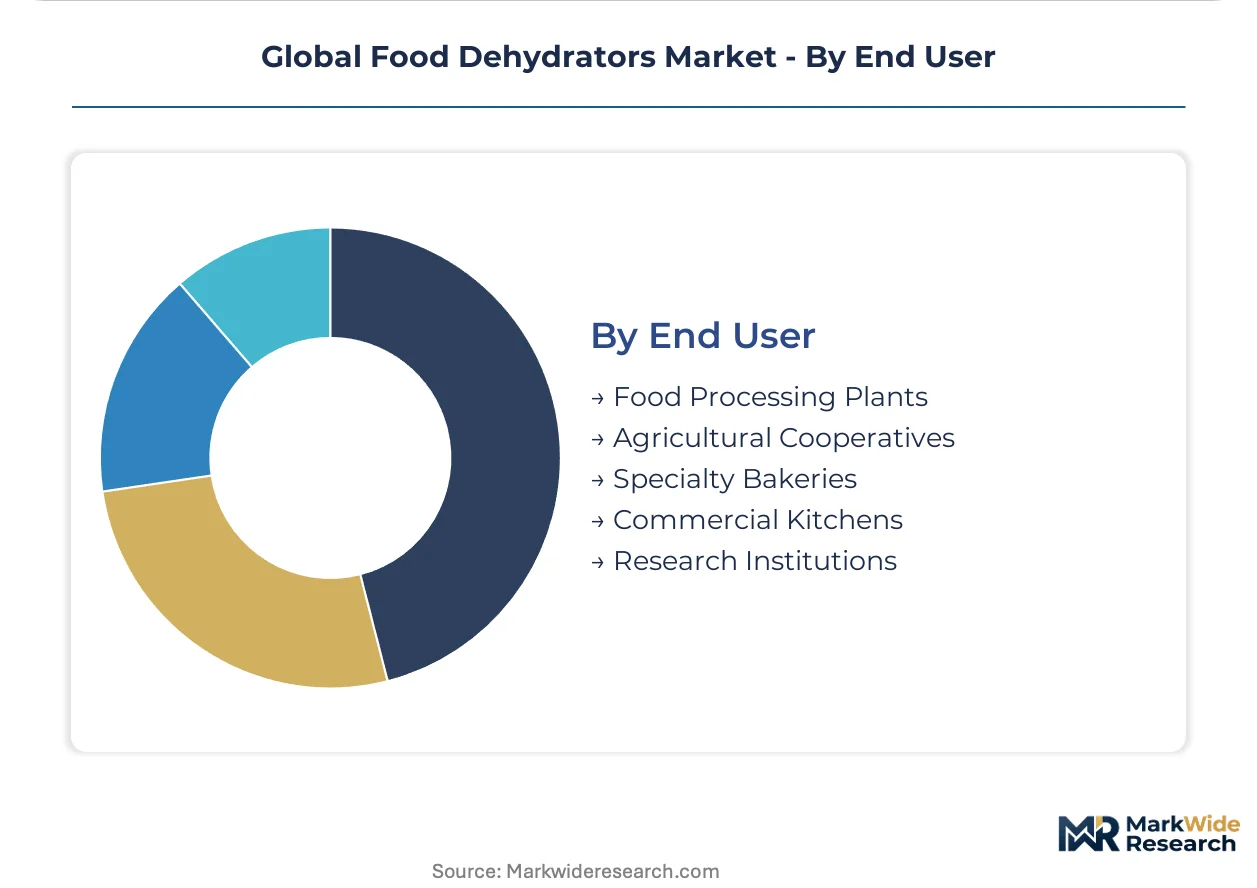
End User:
Application maturity separates legacy food manufacturing from emerging service-model procurement in cooperative and institutional segments.
- Food Processing Plants:Large-scale continuous operations with integrated packaging lines represent the historical revenue core. Brownfield facilities in Italy's Emilia-Romagna region face 12-18 month retrofit timelines when connecting programmable humidity controls to existing Siemens S7 or Rockwell Automation architectures.
- Specialty Bakeries:Artisan and industrial bakeries with sourdough starter and ingredient dehydration needs specify precision equipment. Bavarian producers are consolidating heat pump drying adoption for enzyme preservation, collapsing the historical premium between resistance-heated and thermodynamically efficient tiers.
- Agricultural Cooperatives:Producer-owned processing entities in Denmark and the Netherlands now procure drying capacity on throughput-guarantee terms rather than capital expenditure.
- Commercial Kitchens:Restaurant and hospitality operations with limited space and intermittent use patterns favor compact convection systems.
- Research Institutions:Academic and corporate R&D facilities with lyophilization requirements face supply concentration in Swiss and German vacuum component sourcing.
Revenue concentration remains with Food Processing Plants. Procurement model innovation is advancing fastest among Agricultural Cooperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering talent clusters around Stuttgart and Karlsruhe anchor precision manufacturing capabilities for industrial dehydration systems. Mittelstand food processors in Baden-Württemberg leverage this workforce density to deploy automated drying lines with real-time moisture monitoring.
Germany
EU Green Deal mandates compress payback periods for heat pump dehydrator investments among Bavarian specialty bakeries. ECHA's REACH polymer restrictions force reformulation of gasket and tray assemblies, delaying CE marking renewals. Mittelstand processors in Baden-Württemberg specify cabinet dehydrators with programmable humidity controls for fruit and vegetable lines.
China
Domestic manufacturers abandon resistance heating architectures under GB 21520 energy efficiency standards and dual carbon goals. MIIT enforcement pushes vapor compression systems with coefficient of performance above 3.0. Yangtze River Delta processing clusters adopt heat pump drying for spice and dried fruit export capacity.
United States
FDA food contact substance regulations govern market access for residential and commercial equipment. Raw-food consumer segments validate demand for nutrient-retentive units operating below 118°F. Specialty bakeries in California's Central Valley specify precision systems for sourdough starter dehydration.
India
FSSAI's 2023 Food Safety and Standards (Packaging) Regulation mandates shelf-life extension technologies for spice and dried fruit exports. Maharashtra processing clusters open procurement channels for EU-certified dehydrator OEMs. Karnataka agricultural cooperatives deploy solar-thermal hybrid systems for mango processing.
Switzerland
Research institutions face 16-24 week lead times for vacuum pump and refrigeration stack procurement. Alpine manufacturing clusters concentrate supply for lyophilization capacity expansion. Swissmedic-aligned equipment standards shape specifications for nutraceutical dehydration applications.
Global Food Dehydrators Market Competitive Landscape
Top-tier vendors anchor the precision industrial segment, while mass-market residential players compete through distribution density and price positioning. The vendor base stratifies across three performance tiers: premium cabinet systems with programmable controls, mid-range convection units for commercial kitchens, and entry-level tray dehydrators for household preservation. Strategic archetypes include vertically integrated heating element manufacturers, mass-market appliance brands with retail channel dominance, and compact-system specialists targeting raw-food enthusiasts. Competitive moves center on backward integration into component manufacturing and equipment-as-a-service platforms bundling predictive maintenance with sensor subscriptions.
Among North American appliance manufacturers, Excalibur Dehydrator and Hamilton Beach Brands occupy distinct positioning archetypes. Excalibur represents the vertically integrated specialist with captive supply of heating elements sustaining margin control across premium residential lines. Hamilton Beach exemplifies mass-market distribution density competing through retail channel penetration rather than technical differentiation. Tribest Corporation anchors the compact convection tier, validating nutrient-retentive demand among raw-food enthusiasts with temperature capabilities below 118°F.
| Leading Market Players |
|---|
| Excalibur Dehydrator |
| NESCO |
| Hamilton Beach Brands |
| Koolatron Corporation |
| National Presto Industries |
| Tribest Corporation |
| LEM Products Holding |
| Aroma Housewares Company |
| STX International |
| Others |
Supply & Pricing Matrix
Equipment-grade bifurcation between precision cabinet systems with programmable humidity controls and fixed-temperature tray units creates parallel pricing architectures and divergent supply chain footprints across the food dehydrator market. Premium industrial tiers source heating elements and sensor arrays from German engineering clusters while commodity residential lines draw from standardized component pools in Chinese manufacturing hubs, with each tier facing distinct margin compression dynamics.
Pricing Analysis
Service unbundling splits traditional equipment sales into hardware, humidity sensor subscriptions, and predictive maintenance contracts. Three-tier pricing structure across premium cabinet, mid-range convection, and entry-level tray levels reflects certification grade differentiation and after-sales bundling intensity. Cost compression in residential segments intensifies because nickel price volatility in 304-grade stainless steel exposes manufacturers to input cost swings. Mass-market household buyers exhibit highest price sensitivity, while agricultural cooperatives procuring on throughput-guarantee terms show lowest sensitivity due to operational risk transfer.
Supply Chain Analysis
304-grade stainless steel sheet metal supply rests on German, Chinese, and South Korean metallurgical producers serving as primary inputs for cabinet dehydrator fabrication. Heating element manufacturing draws from captive production at vertically integrated specialists alongside outsourced procurement from Taiwanese and Japanese component houses. Single-source vulnerability concentrates in Swiss and German vacuum pump and refrigeration stack sourcing for freeze drying systems, creating extended lead time exposure. Distribution runs through direct-to-processor digital platforms for industrial tiers and retail channel density for residential units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food dehydrator market functions as a regulatory compounder where EU Green Deal food waste reduction mandates accelerate capital deployment into automated drying infrastructure across European processing clusters.
For Market Incumbents: Hedge against margin erosion in residential tray segments by deepening backward integration into heating element manufacturing and expanding service revenue through equipment-as-a-service platforms. Heat pump technology substitution threatens resistance-heated legacy lines, necessitating certification investment in GB 21520 and EU energy efficiency standards to defend industrial positioning. For New Entrants and Emerging Players: Agricultural cooperatives in Denmark and the Netherlands represent the most penetrable buyer archetype due to procurement model innovation toward throughput-based contracting. Kenya and Ethiopian solar-thermal hybrid installations offer geographic white space with minimal incumbent saturation. Direct digital sales channels bypass traditional distributor markups and align with cooperative procurement preferences. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap manufacturers lack captive engineering academies for multiphysics simulation capabilities. Long-term viability favors vendors with integrated sensor technology and predictive maintenance infrastructure over pure hardware plays. Watch for REACH polymer restriction enforcement timelines as inflection indicators for compliance cost escalation and vendor shakeout.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Technology Transition | MIIT enforcement of GB 21520 standards forces vapor compression adoption with coefficient of performance above 3.0. |
| Equipment-as-a-Service Platforms | Danish dairy cooperatives procure drying capacity on throughput-guarantee terms transferring operational risk to OEMs. |
| REACH-Compliant Material Reformulation | ECHA polymer restrictions force dual BOM maintenance for EU-certified and export-destination equipment variants. |
| Edge-Computing Control Integration | Moisture prediction algorithms embedded in heating element drivers compress feedback loops for Bavarian specialty bakeries. |
| Solar-Thermal Hybrid Deployment | Photovoltaic-absorption heat pump convergence enables off-grid mango processing cooperatives in Kenya and Ethiopia. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant engineers at Mittelstand food processors, procurement leads at agricultural cooperatives, aftermarket service heads at industrial OEMs, and maintenance directors at brownfield facilities combine with secondary validation from EU ECHA regulatory filings, FDA food contact substance registrations, Chinese customs trade data for dehydration equipment, and SEC 10-K disclosures from listed appliance manufacturers. This dual-layer approach enables cross-verification of equipment shipment volumes against processing capacity expansion announcements.
Historical trendline analysis of installed base evolution and technology substitution patterns anchors the projection framework. Segmentation dimensions span product type, drying technology, application substrate, and end-user procurement model across the analysis window. CAGR derivation incorporates energy efficiency mandate compliance timelines, raw material cost trajectory assumptions, and service revenue unbundling velocity specific to food processing capital equipment cycles.
Underlying measurement precision varies by segment; industrial cabinet and vacuum dehydrator categories carry tighter precision than fragmented residential tray units due to concentrated vendor reporting. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology cost parity timelines. Material deviation in nickel price volatility, REACH restriction implementation schedules, or heat pump adoption curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Corn Puff Making Machine Market
Food Processing Equipment
Vee Bee Consistometer Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Food Irradiation Equipment Market
Food Processing Equipment
North America Food and Beverage Filling and Capping Machines Market
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
Ice Cream Freezer Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Food Processing Blades Market
Food Processing Equipment
Cookers and Ovens Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Food Waste Composting Machine Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Shrimp Peeling Machine Market