
 Pan Feeder Market | 2026-2036
Pan Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Pan Feeder Market Analytics
Single-source procurement for heavy-duty pan feeder systems is consolidating around integrated suppliers with full lifecycle capabilities. Metso leverages its aftermarket service network to lock in long-term mining contracts. McLanahan anchors North American aggregates demand through localized fabrication and field engineering support. Elecon Engineering Company Limited competes on cost-engineered electromechanical designs for Asian cement and steel producers.
A pan feeder is a bulk material handling device that uses a flat or slightly inclined trough to meter and convey particulate solids at controlled rates, typically operating at vibration frequencies between 15-60 Hz with stroke amplitudes of 3-12 mm depending on material cohesiveness. The equipment serves primary industries requiring uniform feed regulation from hoppers to crushers, screens, or processing vessels. Vibratory pan feeders occupy the largest installed base due to proven reliability in abrasive mining environments, while electromagnetic feeders capture precision-demanding pharmaceutical and food processing applications where batch consistency dictates output quality. Belt feeders retain dominance in high-tonnage coal and iron ore operations where mechanical simplicity reduces unplanned downtime.
ISO 10816 vibration severity standards, CE marking under the EU Machinery Directive, and MSHA noise exposure limits in US underground mines collectively dictate bearing specification, guarding design, and drive selection across supplier portfolios. Compliance with these frameworks extends product development cycles but creates specification stickiness once equipment achieves site certification. Stakeholders must weigh total cost of ownership against initial capital outlay as energy efficiency regulations tighten and remote monitoring capabilities become baseline expectations rather than differentiators.
Market Dynamics
Equipment replacement cycles in Australian mining operations are compressing as ISO 10816 vibration severity standards force premature retirement of legacy installations that cannot meet bearing specification thresholds.
Growth Catalysts
- Mineral processing corridor expansion:Rajasthan and Karnataka in India are witnessing concentrated capacity additions in cement and steel production, driving synchronized demand for electromechanical pan feeder systems.
- EU Machinery Directive compliance:CE marking requirements for new installations are accelerating procurement of certified equipment across European aggregates operations, locking out uncertified suppliers.
- Underground noise regulations:MSHA noise exposure limits in US mining are forcing adoption of enclosed drive systems and advanced guarding designs that reduce operator exposure.
Market Restraints
- High-grade alloy input volatility:Manganese steel and chromium-molybdenum alloy prices fluctuate with mining commodity cycles, compressing fabrication margins for heavy-duty trough assemblies.
- Drive component supply concentration:Specialized electromagnetic coils and variable frequency drives concentrate among German and Japanese suppliers, creating single-source vulnerability.
- Mechanical substitution in bulk coal:Belt feeders retain cost advantage in high-tonnage iron ore and thermal coal operations where precision metering is secondary to mechanical simplicity.
Strategic Opportunities
- Remote monitoring integration:IoT-enabled vibration sensors and predictive maintenance platforms are unifying equipment data streams, enabling suppliers to capture recurring service revenue.
- Pharmaceutical precision applications:Electromagnetic feeder technology is penetrating batch-sensitive food and drug processing where stroke amplitude control below 3 mm ensures output consistency.
- Energy efficiency mandates:tightening motor efficiency regulations are creating specification windows for regenerative drive systems that recover braking energy in continuous-duty installations.
Industry Challenges
- Vibration analysis skill scarcity:Field commissioning of tuned mass-spring systems requires specialized technicians proficient in frequency response analysis, a capability gap across service networks.
- Legacy system integration friction:Retrofitting variable frequency drives onto fixed-speed electromechanical installations demands custom control architecture, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pan Feeder Market |
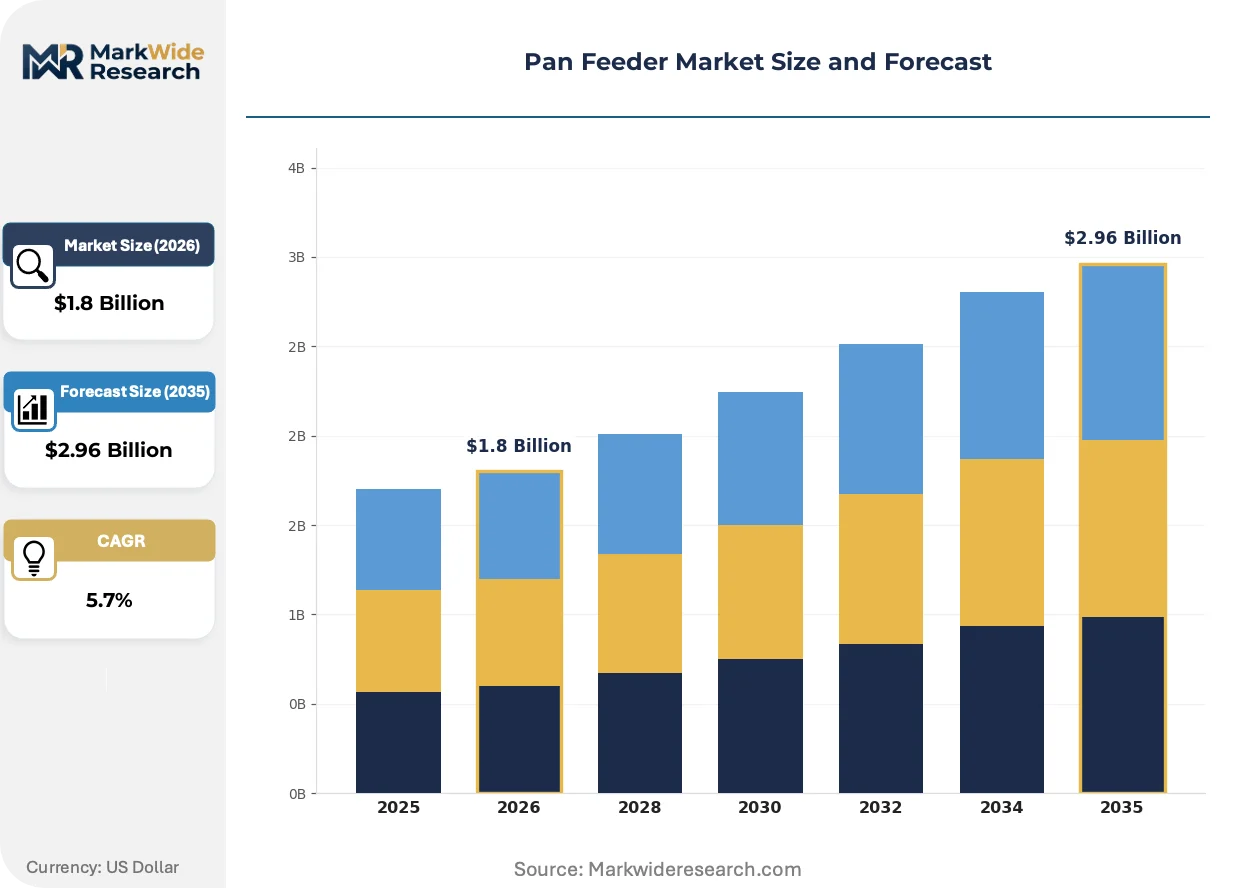
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibratory Pan Feeders, Belt Feeders, Electromagnetic Feeders, Rotating Feeders Application: Food Processing, Mining, Pharmaceutical, Chemical Technology: Electromechanical, Pneumatic, Mechanical, Hydraulic End User: Agriculture, Manufacturing, Construction, Waste Management |
| Companies Covered | McLanahan, TRF Ltd., Hewitt Robins International, Vibramech, Elecon Engineering Company Limited, Metso, Terex MPS, Osborn, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pan Feeder Market Evolving Landscape
Digitalization of maintenance workflows is compressing the traditional reactive service model, while regulatory tightening around energy efficiency and operator safety is reshaping equipment specification priorities across procurement functions.
Smart condition monitoring is unifying vibration, temperature, and current draw data into single-platform diagnostics. Mining operators in Western Australia are deploying these systems at scale, replacing scheduled inspections with exception-based alerts. The technology is compressing mean time to repair and enabling suppliers to shift toward subscription-based service contracts.
REACH chemical restrictions and EU F-Gas Regulation are limiting lubricant formulations and refrigerant options in enclosed drive cooling systems. Equipment manufacturers must reformulate bearing greases and redesign thermal management. Pharmaceutical and food processing segments are responding fastest, prioritizing compliant suppliers in vendor qualification processes.
Buyer consolidation among multinational mining houses is centralizing procurement authority at regional headquarters. Site-level engineering teams are losing specification autonomy, with capital equipment decisions migrating to corporate technical standards committees. This pattern is most visible in Chilean copper operations and South African platinum belt expansions, where global framework agreements now govern pan feeder selection.
Pan Feeder Market Segmentation
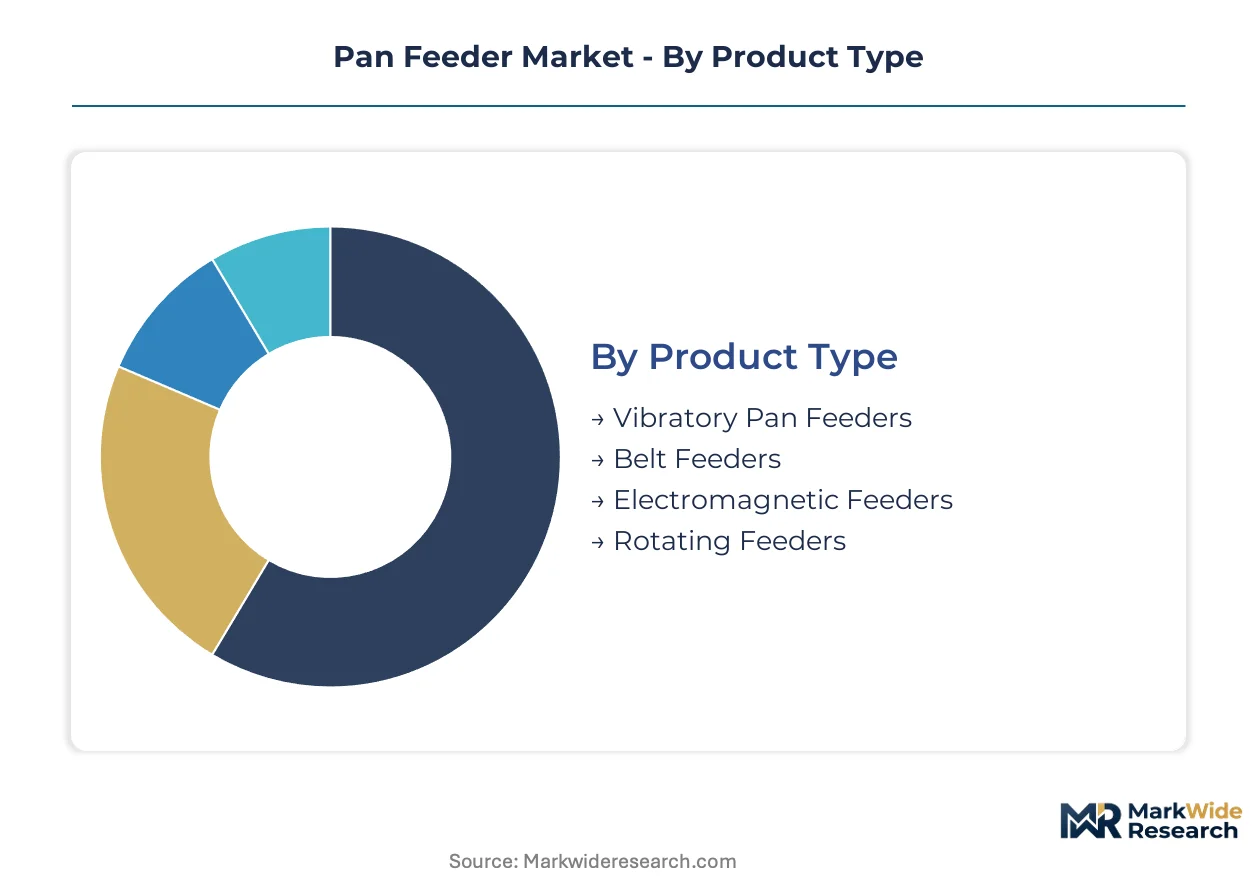
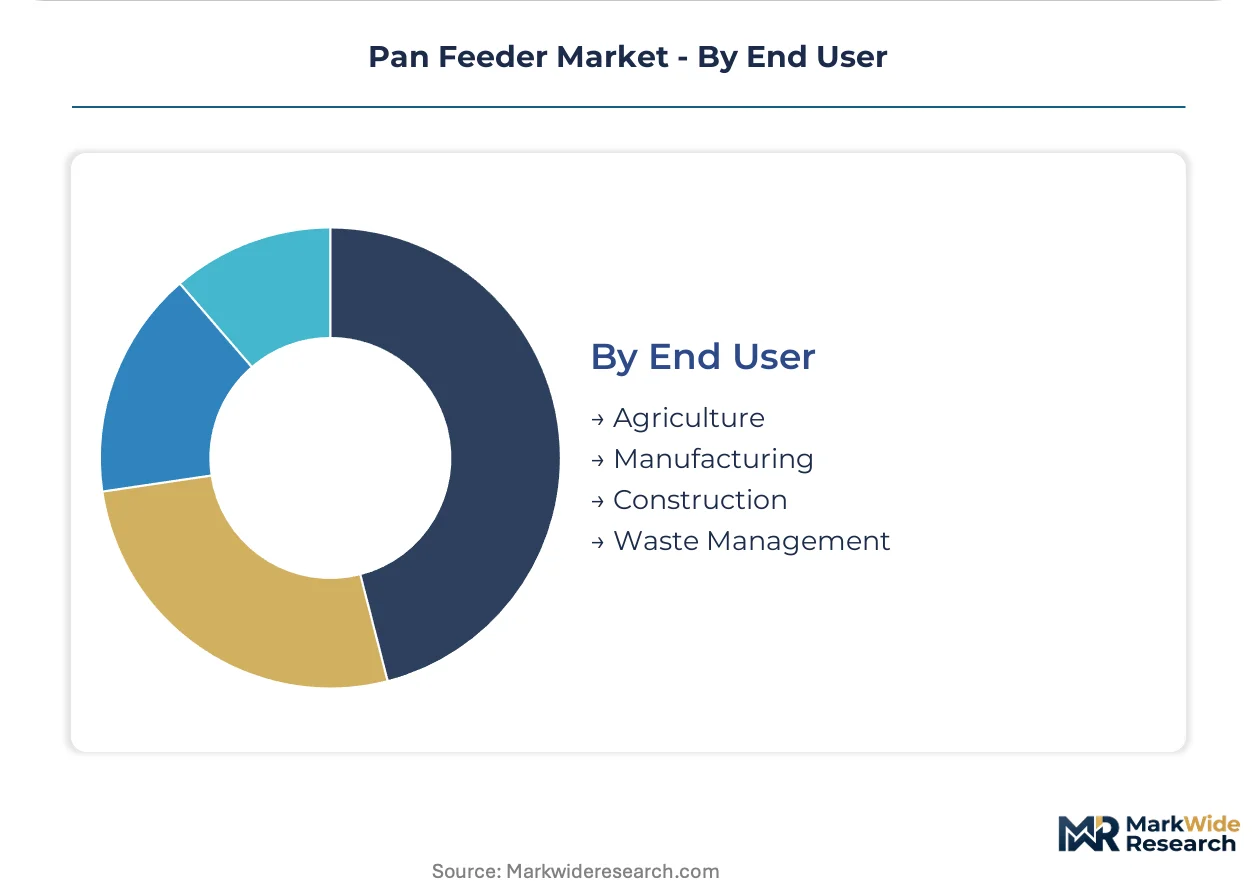
Pan feeder procurement patterns diverge sharply across operational contexts. Mining houses prioritize abrasion resistance and unplanned downtime reduction. Pharmaceutical and food processors demand stroke precision below 3 mm for batch consistency.
Product Type:
Vibration frequency and drive mechanism define the specification hierarchy across industrial applications.
- Vibratory Pan Feeders:These systems operate at 15-60 Hz with 3-12 mm stroke amplitudes, using tuned mass-spring arrangements to meter abrasive ores from hoppers to primary crushers. Australian iron ore operations in the Pilbara region specify these for their proven reliability in dust-laden environments where bearing contamination risks dominate lifecycle cost calculations.
- Electromagnetic Feeders:Coil-driven linear drives deliver sub-3 mm stroke control with near-instantaneous start-stop response, enabling precise batch dosing. Demand concentrates in Swiss and German pharmaceutical manufacturing corridors where FDA and EMA validation protocols require documented dosing consistency for oral solid dosage production lines.
- Belt Feeders:Simple mechanical traction systems handle high-tonnage thermal coal and iron ore streams where metering precision is secondary to mechanical simplicity and maintenance accessibility.
- Rotating Feeders:Star-wheel or lobe configurations manage cohesive, sticky materials in chemical processing where arching and ratholing risks demand active discharge assistance.
Mature deployment sits with vibratory pan feeders in mining. Newer deployment is concentrated in electromagnetic systems for precision batch processing.
Application:
End-use context dictates guarding design, surface finish requirements, and regulatory compliance burden.
- Mining:Primary crushing circuits in Western Australia's gold and iron ore belts specify heavy-duty manganese steel troughs with replaceable liners. MSHA noise exposure limits and ISO 10816 vibration severity standards force enclosed drive housings and premium bearing specifications that extend procurement cycles but lock in supplier relationships post-certification.
- Food Processing:USDA and FDA sanitary design requirements mandate 316 stainless steel construction, continuous welds, and quick-release components for clean-in-place protocols. Demand clusters in Wisconsin dairy processing and Netherlands ingredient handling facilities where allergen control and lot traceability drive vendor qualification.
- Pharmaceutical:Batch consistency requirements for oral solid dosage manufacturing favor electromagnetic technology with validated stroke repeatability and electronic batch recording integration.
- Chemical:Corrosive and hazardous material handling demands exotic alloy construction and explosion-proof electrical enclosures for solvent-laden powder feeds.
Volume concentration favors mining applications. Margin expansion is climbing the fastest in pharmaceutical installations where validation documentation commands premium pricing.
Technology:
Power transmission architecture determines energy efficiency, maintenance intervals, and control precision.
- Electromechanical:Rotating unbalanced motors or eccentric shaft drives convert electrical input to mechanical vibration through resiliently mounted troughs. These dominate aggregates and cement production in Rajasthan and Karnataka, India, where grid stability and technician familiarity favor established designs.
- Mechanical:Direct chain or belt drives from fixed-speed motors offer lowest capital cost for non-critical bulk material transfers in construction aggregate stockpiling.
- Pneumatic:Compressed air vibrators suit hazardous environments where electrical ignition risks prohibit standard motor drives, particularly in chemical solvent handling.
- Hydraulic:High-pressure fluid power delivers extreme force density for the heaviest mining applications where electromechanical torque limits constrain throughput.
Installed base concentration remains with electromechanical systems. Procurement momentum is shifting toward hydraulic drives in ultra-heavy mining expansions.
End User:
Capital allocation cycles and regulatory exposure vary dramatically across buyer categories.
- Manufacturing:Cement and steel producers in India's mineral processing corridor synchronize pan feeder procurement with kiln and blast furnace expansion timelines, creating lumpy demand patterns tied to infrastructure investment cycles.
- Agriculture:Grain handling and fertilizer blending operations specify corrosion-resistant coatings and weatherproof electrical enclosures for outdoor installation.
- Construction:Mobile crushing and screening contractors prioritize rapid setup and interchangeability across multiple aggregate products, favoring modular feeder designs with quick-change deck configurations.
- Waste Management:Municipal solid waste and construction debris recycling demands abrasion-resistant liners and oversized clearances for unpredictable feed material containing tramp metal and contaminants.
Replacement demand is deepest in manufacturing. Greenfield specification activity is expanding most quickly in waste management as circular economy regulations tighten across European and North American jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore deposits in Western Australia's Pilbara region anchor equipment replacement cycles for heavy-duty pan feeder systems. Mining houses there face compressed retirement timelines as vibration severity standards force upgrades of legacy installations.
Australia
ISO 10816 bearing specification thresholds are accelerating equipment turnover across Pilbara iron ore and Kalgoorlie gold operations. The country's national mining safety regulator enforces strict noise exposure protocols that favor enclosed drive housings. Perth-based engineering teams now specify premium bearing packages that extend procurement cycles but lock in supplier relationships post-certification.
Germany
EMA validation requirements and EU Machinery Directive CE marking are filtering uncertified suppliers from pharmaceutical and aggregates procurement channels. REACH chemical restrictions limit lubricant formulations for bearing greases. Industrial clusters around Stuttgart and Dortmund concentrate precision electromagnetic feeder manufacturing for batch-sensitive oral solid dosage production lines.
India
Cement and steel capacity additions in Rajasthan and Karnataka are synchronizing demand for electromechanical pan feeder systems. BIS standards and CEA energy efficiency mandates shape motor specification for new installations. The mineral processing corridor spanning Chittorgarh and Bellary is witnessing concentrated procurement activity tied to kiln and blast furnace expansion timelines.
United States
MSHA noise exposure limits in underground coal and metal mines are forcing adoption of advanced guarding designs and enclosed drive systems. EPA emissions frameworks indirectly affect foundry sourcing for manganese steel trough assemblies. Appalachian coal operations and Arizona copper belts represent divergent specification priorities between mechanical simplicity and precision metering.
South Africa
Platinum belt expansions in the Bushveld Complex are centralizing procurement authority under global mining house framework agreements. The country's national mining regulator enforces vibration and noise standards that align with ISO 10816 severity classifications. Rustenburg and Limpopo mining clusters are losing site-level specification autonomy as corporate technical standards committees assume capital equipment decisions.
Pan Feeder Market Competitive Landscape
Global majors compete with regional champions across aftermarket service networks and localized fabrication capabilities. The vendor base organizes around three tiers: integrated lifecycle providers with full service portfolios, regional fabricators with field engineering proximity, and cost-engineered specialists targeting price-sensitive cement and steel markets. Strategic moves concentrate on locking in long-term mining contracts through aftermarket service bundling and capturing regional demand through localized production.
Among diversified mining equipment providers, Metso exemplifies the integrated lifecycle archetype with its aftermarket service network, while McLanahan anchors North American positioning through regional fabrication presence. Elecon Engineering Company Limited occupies the cost-engineered specialist tier targeting Asian mineral processing demand. TRF Ltd. and Vibramech represent regional champions with field engineering proximity to Indian and African mining corridors respectively.
| Leading Market Players |
|---|
| McLanahan |
| TRF Ltd. |
| Hewitt Robins International |
| Vibramech |
| Elecon Engineering Company Limited |
| Metso |
| Terex MPS |
| Osborn |
| Bosch |
| Others |
Value Network & Pricing Analysis
Backward integration into manganese steel foundry operations anchors pricing power for heavy-duty trough fabricators serving Australian iron ore and Indian cement markets. Captive control over high-grade alloy inputs insulates integrated suppliers from commodity volatility while forcing price-taking behavior on smaller fabricators dependent on spot market sourcing.
Pricing Analysis
Warranty bundling separates premium-tier suppliers from unbundled commodity competitors in pan feeder procurement. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 10816 certification status and aftermarket service coverage. Cost compression in economy tiers is intensifying because Indian cement producers prioritize capital outlay minimization over lifecycle cost. Mining houses in Western Australia exhibit lowest price sensitivity due to unplanned downtime cost exposure.
Supply Chain Analysis
Regional distribution centers in Perth, Stuttgart, and Johannesburg anchor hub-and-spoke patterns for spare parts fulfillment. Manufacturing concentrates in Germany, India, and South Africa for electromagnetic coil assemblies, electromechanical drive systems, and heavy-duty trough fabrication respectively. Supply chain risk centers on single-source vulnerability for specialized variable frequency drives from Japanese suppliers. Distribution runs through OEM-direct channels for mining contracts and distributor networks for construction aggregate applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 10816 certification mandates are forcing consolidation as uncertified fabricators lose access to Australian and European procurement channels.
For Market Incumbents: Deploy aftermarket service bundling to lock in long-term mining contracts against emerging IoT-enabled competitors. Deepen captive supply of manganese steel trough assemblies to defend margin position against volatile alloy input costs. Accelerate vibration sensor integration to capture recurring platform revenue before predictive maintenance becomes table stakes. For New Entrants and Emerging Players: Regional fabricators with field engineering proximity represent the most penetrable channel partner type for breaking into African and Southeast Asian mining corridors. Target waste management recycling applications in Europe where circular economy regulations are expanding specification activity fastest. Pursue white-label electromagnetic feeder manufacturing for Swiss and German pharmaceutical OEMs seeking validated dosing consistency. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated lifecycle providers seeking regional fabrication footprints. Long-term viability favors suppliers with certified service networks spanning multiple mining jurisdictions. Watch MSHA noise regulation tightening in US underground operations as the inflection signal for enclosed drive system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Foundry Operations | Captive manganese steel supply insulates margin from commodity volatility in Australian mining procurement. |
| IoT-Enabled Predictive Maintenance Platform Launch | Vibration sensor subscriptions shift revenue from transactional equipment sales to recurring service contracts. |
| CE Marking Certification Investment | EU Machinery Directive compliance filters uncertified competitors from European aggregates procurement channels. |
| Regional Fabrication Facility Expansion | Localized production in Rajasthan and Karnataka reduces delivery cost for Indian cement capacity additions. |
| Pharmaceutical Validation Documentation Program | FDA and EMA batch consistency protocols command premium pricing in oral solid dosage manufacturing. |
Research Methodology
Trade publications, mining equipment procurement databases, and SEC filings from diversified industrial suppliers formed the secondary backbone of this analysis. Primary interviews with maintenance directors at Pilbara iron ore operations, plant engineers in Rajasthan cement corridors, aftermarket service heads at regional fabricators, and procurement managers at multinational mining houses combined with bottom-up and top-down triangulation to validate segment sizing.
Historical trendline analysis across installed base data and replacement cycle patterns informed the projection framework. Segmentation modeling covered product type, application context, power transmission technology, and end-user capital allocation cycle across the analysis window. CAGRs derived from equipment retirement timelines tied to ISO 10816 vibration severity thresholds and regional mining safety regulation enforcement patterns.
Several conditions sit outside the modeled scope, including commodity price shocks to manganese and chromium-molybdenum alloys, abrupt regulatory shifts in underground noise exposure limits, and breakthrough displacement of vibratory technology by alternative metering systems. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Food Preservation Equipment Market
Food Processing Equipment
Food Waste Disposal Equipment Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Reflow Oven Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Food Processor Market
Food Processing Equipment
Pizza Preparation Refrigerator Market
Food Processing Equipment
Individual Quick Freezing Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Global Shawarma Machines Market
Food Processing Equipment
Multi Ovens Market