
 Plant Sterol Supplements Market | 2026-2036
Plant Sterol Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Sterol Supplements Market Analytics
Subscription-based personalized nutrition programs is decoupling supplement purchasing from traditional retail cycles. BASF SE leverages its pharmaceutical-grade sterol ester production infrastructure to supply branded and private-label manufacturers globally. Cargill, Incorporated anchors North American supply through its integrated oilseed processing and sterol extraction operations. Kerry Group plc differentiates by offering formulation services that blend plant sterols with delivery-system technologies for beverage and food fortification clients.
Plant sterol supplements comprise bioactive phytosterols—primarily beta-sitosterol, campesterol, and stigmasterol—typically delivered in esterified or free forms at dosages ranging from 0.8 to 3 grams daily to inhibit intestinal cholesterol absorption. Softgels dominate product type volumes due to consumer familiarity and oil-soluble sterol compatibility, while powders gain traction in functional food integration where manufacturers seek clean-label dispersion. The natural formulation segment sustains premium positioning as clean-label demand from individuals and nutritionists pressures synthetic alternatives, though fortified variants expand through healthcare provider channels targeting clinical compliance.
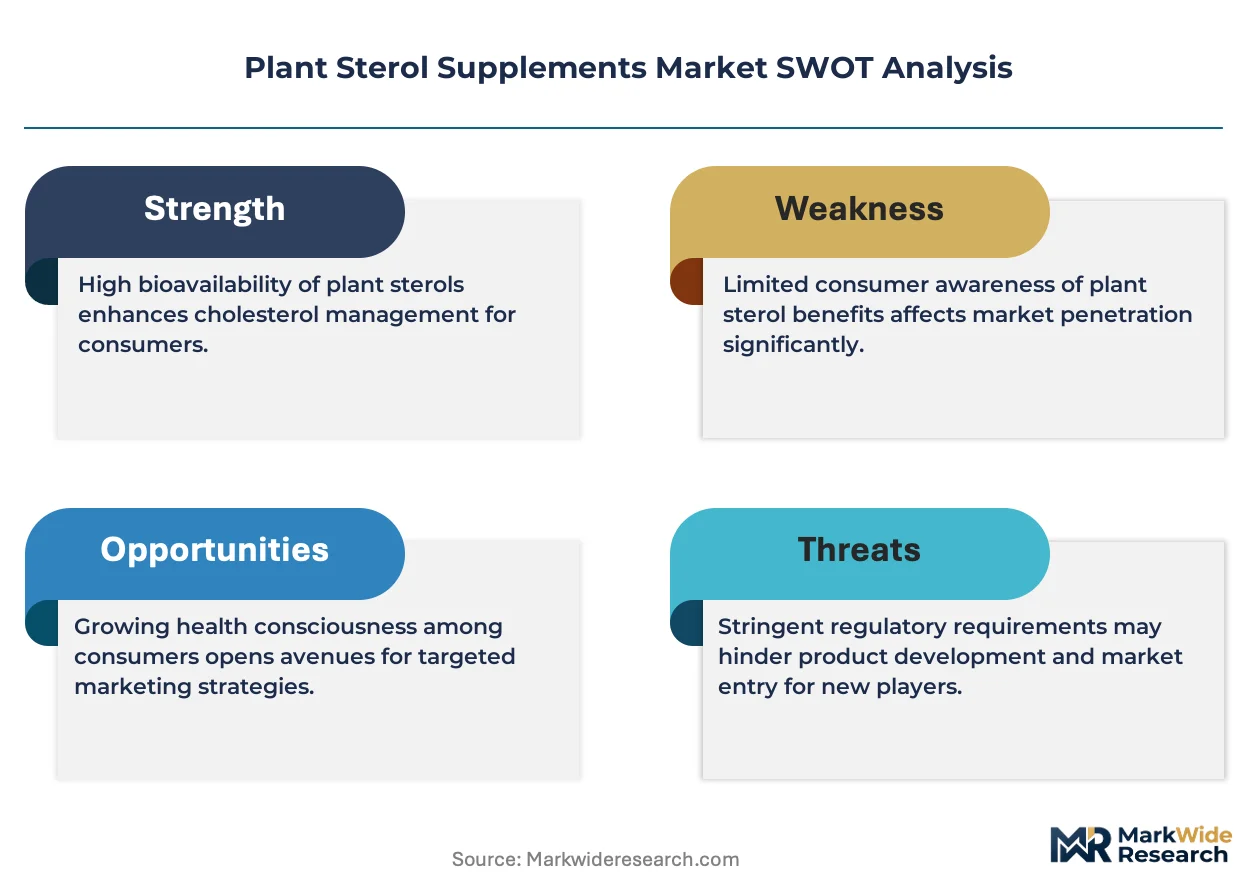
The FDA's qualified health claims for plant sterols and the EFSA's Article 14 health claims create divergent compliance pathways that shape regional product development investments. FSSAI fortification guidelines in India and China's National Health Commission standards for functional foods add emerging-market regulatory complexity for multinational suppliers. Stakeholders must monitor evolving substantiation requirements across jurisdictions where regulator divergence between pharmaceutical and food-category classification determines market access speed and competitive positioning.
Market Dynamics
The FDA's qualified health claims framework for plant sterols is restructuring competitive positioning by forcing manufacturers to substantiate label claims through clinical evidence, elevating barrier-to-entry for new entrants while rewarding established pharmaceutical-grade producers with compliant infrastructure.
Growth Catalysts
- Preventive cardiology protocols:Healthcare systems in the United States are integrating plant sterol supplementation into pre-statin intervention pathways for hyperlipidemia patients, creating institutional demand channels distinct from retail.
- EFSA Article 14 health claims:The European Food Safety Authority's approved claims for cholesterol reduction enable fortified food manufacturers to market functional benefits directly to consumers, accelerating product development cycles.
- Aging demographic cholesterol management:Populations over 55 in Germany and Japan are seeking non-pharmaceutical lipid control alternatives, expanding the addressable consumer base beyond diagnosed cardiovascular patients.
Market Restraints
- Soy and tall oil feedstock volatility:Plant sterol extraction depends on byproduct streams from vegetable oil refining, exposing margins to agricultural commodity price swings and biofuel policy competition for oilseed supply.
- Intestinal absorption ceiling:The physiological limit of roughly 10% phytosterol bioavailability constrains efficacy differentiation between formulations, compressing premium pricing justification and forcing competition on dosage convenience alone.
- Statin substitution threat:Generic atorvastatin and rosuvastatin availability at sub-dollar daily costs in the United States and India creates a cost-efficacy comparison that plant sterol supplements struggle to win in severe hypercholesterolemia cases.
Strategic Opportunities
- FSSAI fortification guidelines:India's 2022 edible oil fortification mandate creates a regulatory tailwind for sterol suppliers to partner with domestic refiners, converting a voluntary wellness category into compliance-driven volume.
- Beverage delivery system convergence:Nanoemulsion and liposomal encapsulation technologies are enabling sterol incorporation into water-based functional drinks, opening channels where oil-based softgels face formulation barriers.
- Subscription personalized nutrition:Direct-to-consumer platforms using biomarker-driven recommendations are capturing recurring revenue relationships that bypass pharmacy and mass retail margin structures entirely.
Industry Challenges
- Clinical substantiation capacity:The shortage of lipid metabolism specialists and contract research organizations capable of executing FDA-compliant sterol efficacy studies is extending product development timelines and inflating study costs.
- Cross-jurisdictional formulation complexity:Divergent maximum permitted levels between the FDA's 2 gram qualified claim threshold and EFSA's 3 gram approval force manufacturers to maintain separate SKUs or lowest-common-denominator dosing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Sterol Supplements Market |
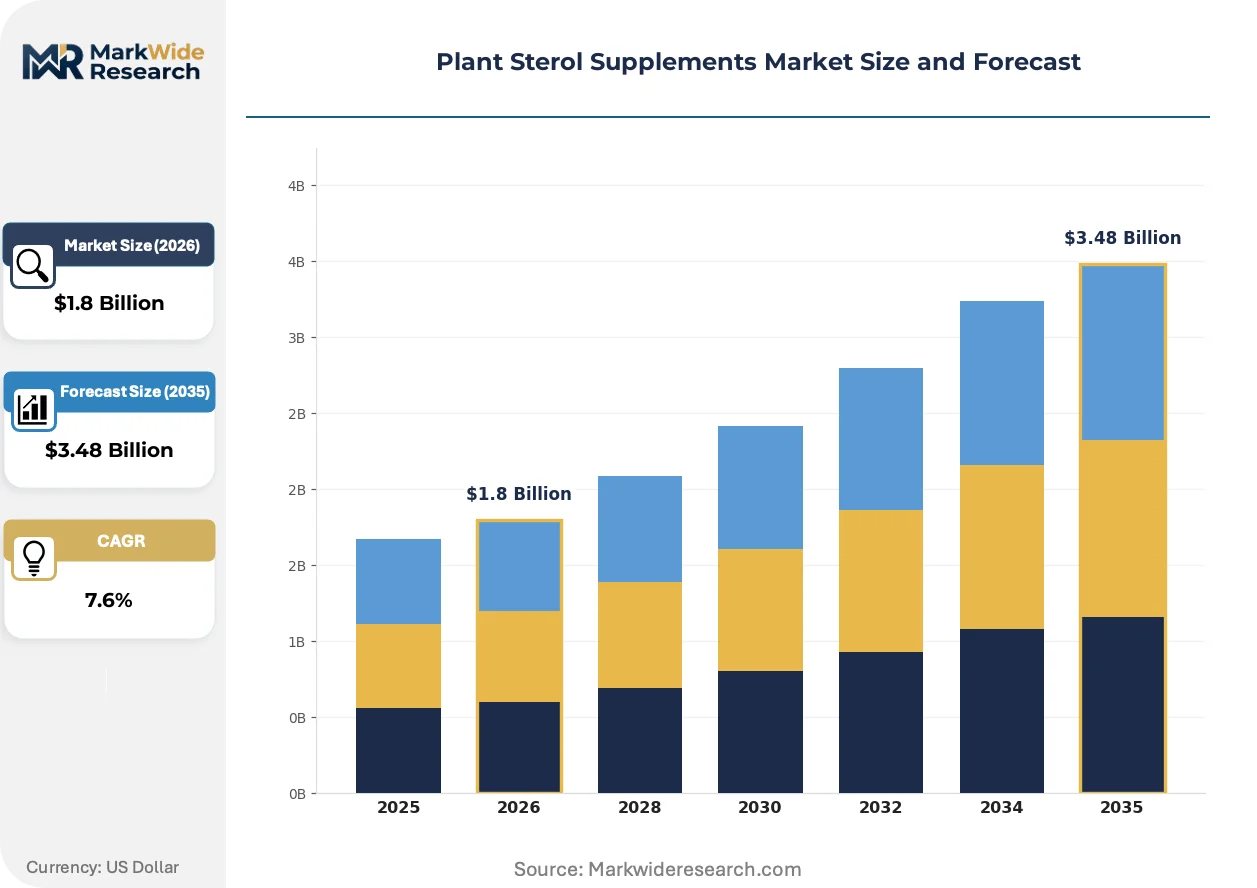
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softgels, Tablets, Powders, Liquid End User: Individuals, Healthcare Providers, Retailers, Nutritionists Distribution Channel: Online, Pharmacies, Health Stores, Supermarkets Formulation: Natural, Synthetic, Combined, Fortified |
| Companies Covered | BASF SE, Cargill, Incorporated, Archer Daniels Midland Company, Raisio Oyj, Arboris, LLC, DuPont de Nemours, Inc., Pharmachem Laboratories, Inc., Kerry Group plc, Blackmores, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Sterol Supplements Market Evolving Landscape
Delivery technology convergence and regulatory claim substantiation requirements are fragmenting the competitive landscape into pharmaceutical-grade specialists and commodity ingredient suppliers with divergent investment priorities.
Microencapsulation technology using modified starch and gum arabic carriers is modularizing plant sterol integration into ambient-stable bakery and snack applications. European functional food manufacturers are adopting these systems at accelerated rates to meet clean-label demands. The technology is compressing the traditional separation between supplement and fortified food categories, enabling single-product positioning across retail channels previously requiring distinct formulations.
REACH registration requirements for novel sterol derivatives in the European Union are forcing suppliers to pre-commit toxicology dossiers before market entry. The industrial consequence is a consolidation of innovation pipelines around existing approved molecular structures rather than novel phytosterol analogs. Food fortification clients in Germany and France are responding by demanding supply-chain documentation that traces sterol provenance to pre-registered base materials, privileging established European chemical suppliers over Asian entrants.
Direct-to-consumer genetic testing services are fragmenting supplement purchasing into phenotype-matched protocols. Wellness platforms in the United States are displacing generalized cholesterol support positioning with APOE genotype-specific recommendations, altering how manufacturers segment and message their products. This behavioral shift is most visible among 35-50 year old consumers in California and New York metropolitan areas where preventive cardiovascular screening penetration exceeds national averages.
Plant Sterol Supplements Market Segmentation
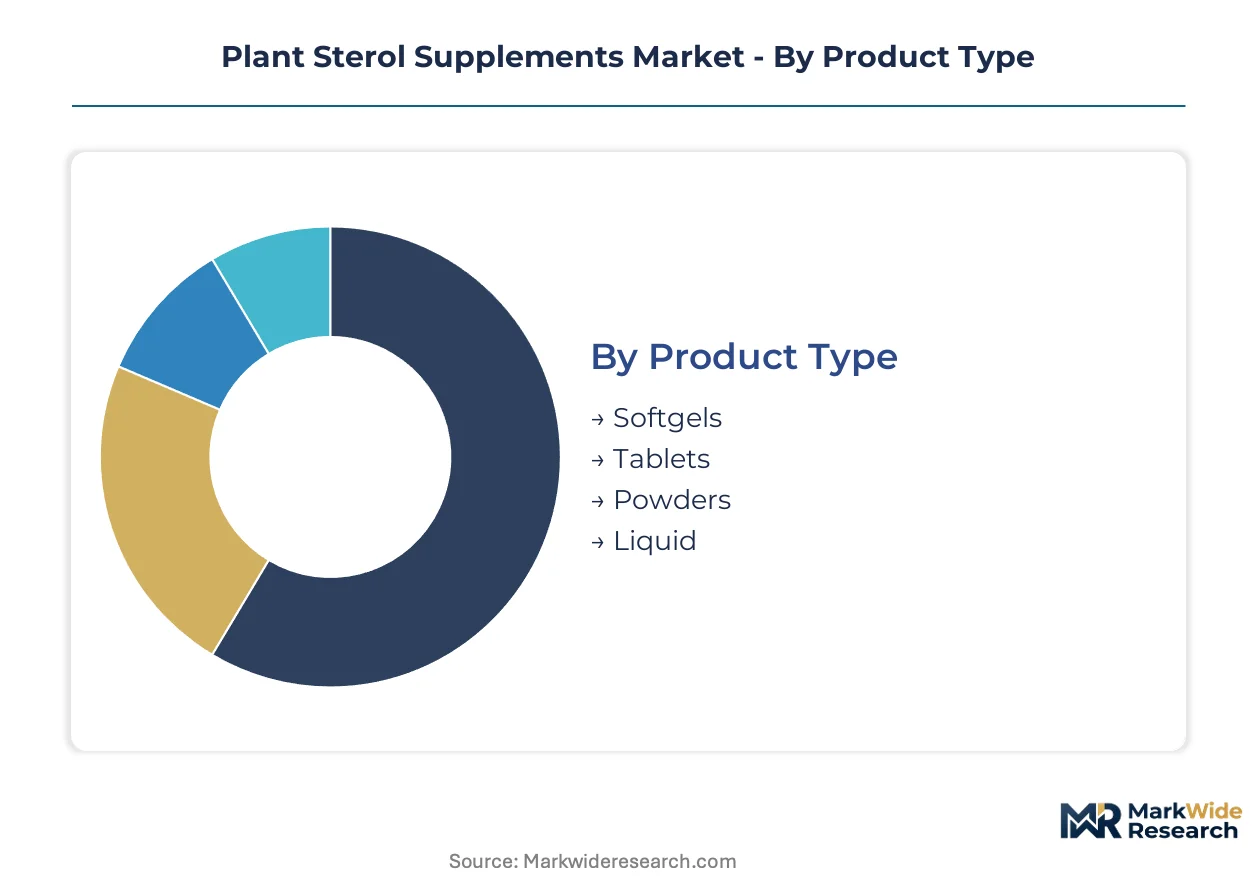
Plant sterol supplements fragment across four dimensions that determine regulatory pathway, margin structure, and customer acquisition cost. Product type and formulation govern FDA qualified health claim eligibility, while distribution channel and end user shape pricing power and repeat purchase rates.
Product Type:
Certification burdens cluster around oil-based delivery systems where sterol stability testing intersects with cGMP pharmaceutical standards, while water-compatible formats face distinct dissolution validation requirements.
- Softgels:Gelatin or vegetable-based capsules containing esterified sterols in oil suspension deliver standardized 0.8-2g doses with proven shelf stability. Demand concentrates among cardiovascular patients over 55 in Germany and Japan where physician recommendations favor familiar pharmaceutical formats. FDA qualified health claim substantiation is most advanced for softgel delivery, accelerating pharmacy channel placement.
- Powders:Microencapsulated free-form sterols enable functional food integration at 5-15% loading rates in bakery and dairy applications. European manufacturers in France and the Netherlands are adopting these systems fastest to meet EFSA Article 14 fortification compliance. Powder formats require additional dispersion testing under REACH registration protocols.
- Tablets:Compressed sterol formulations with binders and disintegrants target cost-sensitive retail segments. Tablet dissolution profiles must demonstrate bioequivalence to reference softgels for health claim eligibility.
- Liquid:Emulsified sterol concentrates for dropper or shot formats appeal to pediatric and geriatric populations with swallowing difficulties. Liquid stability testing demands accelerated thermal cycling protocols that extend development timelines.
Leading the category by volume: Softgels. Growing fastest: Powders.
End User:
Procurement authority and clinical validation requirements separate institutional buyers from direct consumers, with healthcare providers commanding documentation standards that reshape supplier qualification criteria.
- Healthcare Providers:Cardiology clinics and hospital outpatient services in the United States are integrating sterol protocols into pre-statin hyperlipidemia management, requiring batch-specific certificates of analysis and clinical trial bibliographies. These institutional channels sustain premium pricing through reimbursement-adjacent positioning.
- Individuals:Direct purchasers respond to APOE genotype-matched recommendations from personalized nutrition platforms, fragmenting demand into phenotype-specific protocols rather than generic cholesterol support claims.
- Retailers:Mass-market chains and specialty supplement stores negotiate slotting fees and promotional allowances that compress manufacturer margins in exchange for shelf visibility.
- Nutritionists:Registered dietitians in California and New York metropolitan areas prescribe clean-label natural formulations, creating referral-driven demand with higher customer lifetime value.
Volume concentrates with: Individuals. Steepest expansion trajectory: Healthcare Providers.
Distribution Channel:
Channel selection determines margin retention, with direct-to-consumer platforms capturing recurring revenue relationships that bypass wholesale markups entirely.
- Online:Subscription-based personalized nutrition platforms using biomarker-driven recommendations are displacing generalized positioning. These channels bypass pharmacy and mass retail margin structures, enabling APOE-specific protocol marketing to 35-50 year old consumers.
- Pharmacies:Chain and independent drugstores in the United States leverage FDA qualified health claim signage to position sterols adjacent to statin displays, capturing physician-referred patients seeking non-pharmaceutical alternatives.
- Health Stores:Specialty retailers emphasize natural formulation segments and clean-label positioning, serving nutritionist-referred clientele with higher education levels.
- Supermarkets:Mass grocery channels prioritize fortified food adjacent placement and promotional pricing, competing on convenience rather than clinical credibility.
Fastest channel expansion: Online. Dominant transaction volume: Pharmacies.
Formulation:
Raw material provenance and synthetic versus natural classification determine clean-label premium eligibility and regulatory claim substantiation pathway.
- Natural:Sterols extracted from tall oil or vegetable oil refining byproducts—primarily beta-sitosterol, campesterol, and stigmasterol—command premium positioning as consumer and nutritionist pressure shifts demand away from synthetic alternatives. REACH registration requirements for novel derivatives favor pre-registered base materials from established European suppliers.
- Fortified:Sterols combined with additional bioactives such as omega-3 fatty acids or coenzyme Q10 target clinical compliance channels where healthcare providers seek multi-mechanism cardiovascular support. These combinations require separate stability validation and interaction studies.
- Synthetic:Laboratory-derived phytosterol analogs face clean-label displacement pressure but maintain cost advantages for price-sensitive retail segments.
- Combined:Blended natural-synthetic formulations attempt margin optimization but encounter regulatory complexity in jurisdictions with divergent classification standards.
Category leadership by revenue: Natural. Climbing the fastest: Fortified.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American demand through its concentration of cardiovascular research institutions and pharmacy chain headquarters that shape sterol supplement distribution strategies across the United States.
United States
Preventive cardiology protocols at Cleveland Clinic and Mayo Clinic drive institutional procurement of plant sterol supplements for pre-statin patient management. The FDA's qualified health claims framework permits specific cholesterol reduction labeling for products delivering 0.8-2 grams daily. New Jersey's pharmaceutical corridor hosts formulation specialists serving both branded and private-label manufacturers with pharmaceutical-grade sterol ester production infrastructure.
Germany
Aging populations in Bavaria and Baden-Württemberg seek non-pharmaceutical lipid control alternatives, expanding demand beyond diagnosed cardiovascular patients. EFSA Article 14 health claims enable direct-to-consumer marketing of cholesterol reduction benefits for fortified foods. The Frankfurt-Rhine-Main metropolitan region concentrates clean-label formulation expertise serving European functional food manufacturers.
India
FSSAI's 2022 edible oil fortification mandate converts voluntary wellness consumption into compliance-driven volume for domestic refiners. The National Health Mission integrates sterol supplementation into non-communicable disease prevention programs in Maharashtra and Gujarat. Mumbai's processing infrastructure supports partnership models between international sterol suppliers and local oilseed refiners.
China
National Health Commission standards for functional foods create regulatory pathways for sterol-fortified products targeting urban middle-class consumers in Shanghai and Beijing. SAMR registration requirements favor established suppliers with documented toxicology dossiers for pre-approved molecular structures. The Yangtze River Delta hosts encapsulation technology providers enabling beverage-format sterol integration.
Japan
PMDA's Foods with Function Claims system permits specific cardiovascular benefit labeling for sterol supplements meeting clinical substantiation thresholds. METI's Silver Innovation program supports geriatric-friendly delivery formats for populations over 65 in Tokyo and Osaka metropolitan areas. Kansai region manufacturers specialize in liposomal encapsulation technologies for enhanced bioavailability positioning.
Plant Sterol Supplements Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the plant sterol supplements landscape. Integrated chemical conglomerates with captive oilseed processing infrastructure command feedstock cost advantages, while specialized nutrition houses focus on formulation IP and delivery-system patents. The market structure fragments between pharmaceutical-grade specialists serving healthcare channels and commodity ingredient suppliers competing on volume scale. Dominant competitive moves include backward integration into tall oil refining and strategic partnerships with functional food manufacturers seeking turnkey fortification solutions.
Among European chemical conglomerates, BASF SE and Kerry Group plc occupy positions exemplifying divergent strategic archetypes. BASF SE represents the integrated producer model with pharmaceutical-grade sterol ester capabilities. Kerry Group plc anchors the formulation services tier, blending technical expertise with delivery-system integration for beverage and food clients. Cargill, Incorporated exemplifies the agricultural processor archetype, leveraging North American oilseed infrastructure to secure feedstock positions.
| Leading Market Players |
|---|
| BASF SE |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Raisio Oyj |
| Arboris, LLC |
| DuPont de Nemours, Inc. |
| Pharmachem Laboratories, Inc. |
| Kerry Group plc |
| Blackmores |
| Others |
Value Network & Pricing Analysis
Lipid metabolism specialists concentrated in New Jersey's pharmaceutical corridor command wage premiums that propagate through three-tier pricing structures separating pharmaceutical-grade sterol esters from commodity-grade powders. Labor-cost differentials between FDA-compliant formulation houses and regional blenders widen spreads between premium softgels and economy tablets.
Pricing Analysis
Outcome-based pricing anchored to LDL cholesterol reduction metrics dominates institutional procurement by Cleveland Clinic and Mayo Clinic cardiology protocols. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade softgels with batch-specific certificates of analysis from unbranded tablet generics. Pricing pressure stems from generic atorvastatin availability at sub-dollar daily costs in United States and Indian pharmacy channels. Healthcare providers demonstrate lowest price sensitivity given reimbursement-adjacent positioning, while mass-market retail consumers exhibit highest elasticity.
Supply Chain Analysis
cGMP certification and REACH registration requirements gate supplier qualification for European and North American pharmaceutical channels. Feedstock concentration centers on United States, Germany, and India where tall oil refining and vegetable oil processing byproduct streams anchor sterol extraction. Raw material dependencies include soy deodorizer distillate, tall oil pitch, and gum rosin derivatives. Single-source vulnerability runs through agricultural commodity price swings and biofuel policy competition for oilseed supply. Distribution runs through integrated chemical conglomerates with captive oilseed processing infrastructure serving branded and private-label manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's qualified health claims framework for plant sterols erects a cost-of-compliance moat that rewards established pharmaceutical-grade producers while elevating barrier-to-entry for new participants lacking clinical substantiation infrastructure.
For Market Incumbents: Cement pharmaceutical-grade positioning by deepening backward integration into tall oil refining and securing multi-year supply agreements with Cleveland Clinic and Mayo Clinic cardiology networks. Generic statin substitution pressure demands differentiation through APOE genotype-matched protocol development rather than commodity dosage competition. For New Entrants and Emerging Players: FSSAI's 2022 edible oil fortification mandate in India opens a window for partnership models with domestic refiners converting voluntary wellness into compliance-driven volume. White-space concentration sits with beverage-format nanoemulsion delivery systems and subscription-based personalized nutrition platforms bypassing traditional pharmacy margin structures. For Investors and Strategic Acquirers: Re-rating potential sits with formulation-services specialists given convergence between supplement and functional food categories. Long-term viability favors asset-light designers with delivery-system patents over capital-heavy commodity producers. The signal to watch is EFSA Article 14 claim expansion into novel food matrices beyond traditional dairy and spreads.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tall Oil Refining | Captive feedstock supply secures margin insulation against agricultural commodity volatility for BASF SE and Cargill. |
| Nanoemulsion Delivery System Development | Liposomal encapsulation technology enables sterol incorporation into water-based functional drinks for California wellness platforms. |
| APOE Genotype-Matched Protocol Launch | Direct-to-consumer genetic testing integration captures recurring revenue relationships among 35-50 year old preventive cardiology consumers. |
| FSSAI Fortification Partnership | Compliance-driven volume conversion in India creates institutional procurement channels distinct from discretionary retail. |
| REACH Registration Pre-Commitment | Toxicology dossier investment privileges established European chemical suppliers over Asian entrants in German and French markets. |
Research Methodology
Multi-period observation of sterol extraction capacity utilization, EFSA Article 14 claim adoption rates, and FSSAI fortification compliance timelines anchored the trend analysis, supplemented by interviews with lipid metabolism specialists, regulatory affairs leads at functional food manufacturers, pharmacy chain category managers, and contract research organization directors. Secondary validation drew from FDA qualified health claim filings, EFSA scientific opinions, FSSAI fortification guidelines, and customs data on tall oil derivative trade flows. Bottom-up sterol demand modeling by product format and end-user segment triangulated against top-down market sizing from oilseed processing byproduct availability estimates.
Input-output matrices mapped sterol extraction yields from vegetable oil refining byproduct streams through formulation stages to finished supplement and fortified food outputs across the projection horizon. Segmentation dimensions modeled included product type, formulation provenance, distribution channel, and end-user procurement authority. CAGRs were derived from regression analysis of historical sterol incorporation rates in functional foods and supplements against cardiovascular disease prevalence and preventive screening penetration. Forecast inputs incorporated biofuel policy competition for oilseed supply and nanoemulsion technology adoption curves in beverage applications.
The model assumes a particular technology adoption path for liposomal encapsulation; alternative pathways for microencapsulation using modified starch carriers would alter the outlook for powder format growth. Forecasts reflect assumptions regarding EFSA claim expansion, FSSAI enforcement consistency, and FDA qualified health claim substantiation requirements. A model refresh is warranted upon material change in generic statin pricing dynamics or REACH registration requirements for novel sterol derivatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Asia Pacific Collagen Supplements Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Asia-Pacific Dietary Supplement Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Fish Protein Isolate Market
Nutritional Supplements
Global Collagen Peptides Market
Nutritional Supplements
Personalized Nutrition Market
Nutritional Supplements
Soy Isoflavones Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Wellness Supplements Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
North America Whey Protein Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market