
 Cold Storage Equipment Market | 2026-2036
Cold Storage Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Storage Equipment Market Outlook
Refrigerant technology is fragmenting as natural and low-GWP alternatives displace legacy hydrofluorocarbon systems across commercial cold storage infrastructure. Carrier Global Corporation leverages its compressor manufacturing depth to anchor North American distribution networks for sustainable refrigeration retrofits. Daikin Industries competes through integrated inverter-driven scroll systems that extend energy efficiency margins for warehouse operators. Thermo King specializes in transport-connected cold chain units that dominate intermodal pharmaceutical logistics.
Cold storage equipment comprises insulated enclosures, refrigeration machinery, and control systems engineered to maintain temperatures between -40°C and +15°C for perishable goods preservation. Vapor compression technology occupies the dominant share of installed capacity due to its proven coefficient of performance and service infrastructure maturity. Walk-in coolers and freezers sustain the largest product segment as food retail and foodservice operators replace aging ammonia-based systems with modular, prefabricated units that reduce on-site construction risk. Pharmaceutical end users represent the fastest-expanding demand pool, driven by cell and gene therapy distribution requirements that mandate validated temperature uniformity within ±2°C across storage volumes.
The EPA enforces hydrofluorocarbon phasedown schedules under the AIM Act, while the USDA mandates Hazard Analysis Critical Control Point compliance for meat and poultry cold storage facilities. These frameworks force capital deployment toward compliant equipment and reshape procurement criteria for federally inspected food warehouses. Stakeholders must monitor refrigerant quota allocations and energy efficiency standard revisions to time replacement cycles and avoid stranded asset exposure.
Market Dynamics
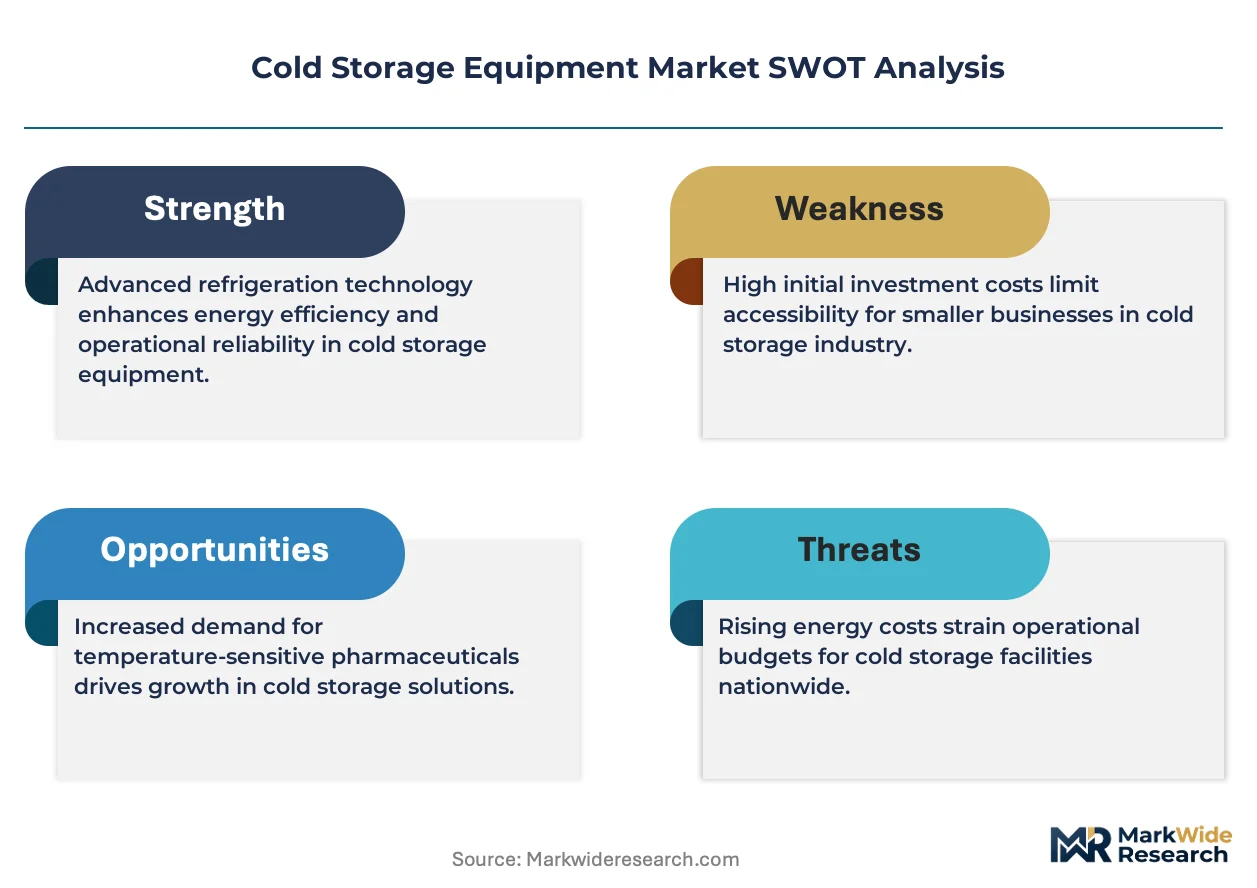
The EPA's AIM Act refrigerant phasedown is compressing replacement cycles across commercial cold storage infrastructure, forcing capital redeployment toward low-GWP systems before quota restrictions tighten. This regulatory pressure intersects with biologics distribution expansion to reshape equipment procurement criteria.
Growth Catalysts
- Pharmaceutical cold chain mandates:Cell and gene therapies require validated storage within ±2°C uniformity, driving demand for precision-controlled enclosures across distribution networks.
- USDA HACCP enforcement:Federally inspected meat and poultry facilities must upgrade monitoring systems, accelerating digital control system adoption in food processing hubs.
- CO₂ transcritical systems:Natural refrigerant technology is penetrating warehouse retrofits as operators seek compliance pathways independent of hydrofluorocarbon quotas.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger and piping materials face commodity price swings that compress equipment margins during contract bidding periods.
- Compressor supply concentration:Scroll and screw compressor manufacturing clusters in East Asia create lead time vulnerability for North American cold storage builders.
- Ammonia system retrofit complexity:Existing industrial installations require extensive engineering review before conversion to lower-charge alternatives, extending project timelines.
Strategic Opportunities
- India cold chain infrastructure:The country's PLI scheme for food processing and pharmaceutical exports is unlocking warehouse automation demand in temperature-controlled logistics.
- Last-mile pharmaceutical distribution:Urban clinic networks and direct-to-patient delivery models are creating demand for compact, validated storage units.
- EU F-Gas Regulation acceleration:The 2030 ban on high-GWP refrigerants in new commercial equipment is pulling forward replacement demand across member states.
Industry Challenges
- Refrigerant handling certification gaps:Technician shortages in flammable refrigerant safety protocols are constraining installation capacity for propane and isobutane systems.
- Legacy control system integration:BACnet and Modbus interoperability issues are complicating upgrades of 1990s-era warehouse management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Storage Equipment Market |
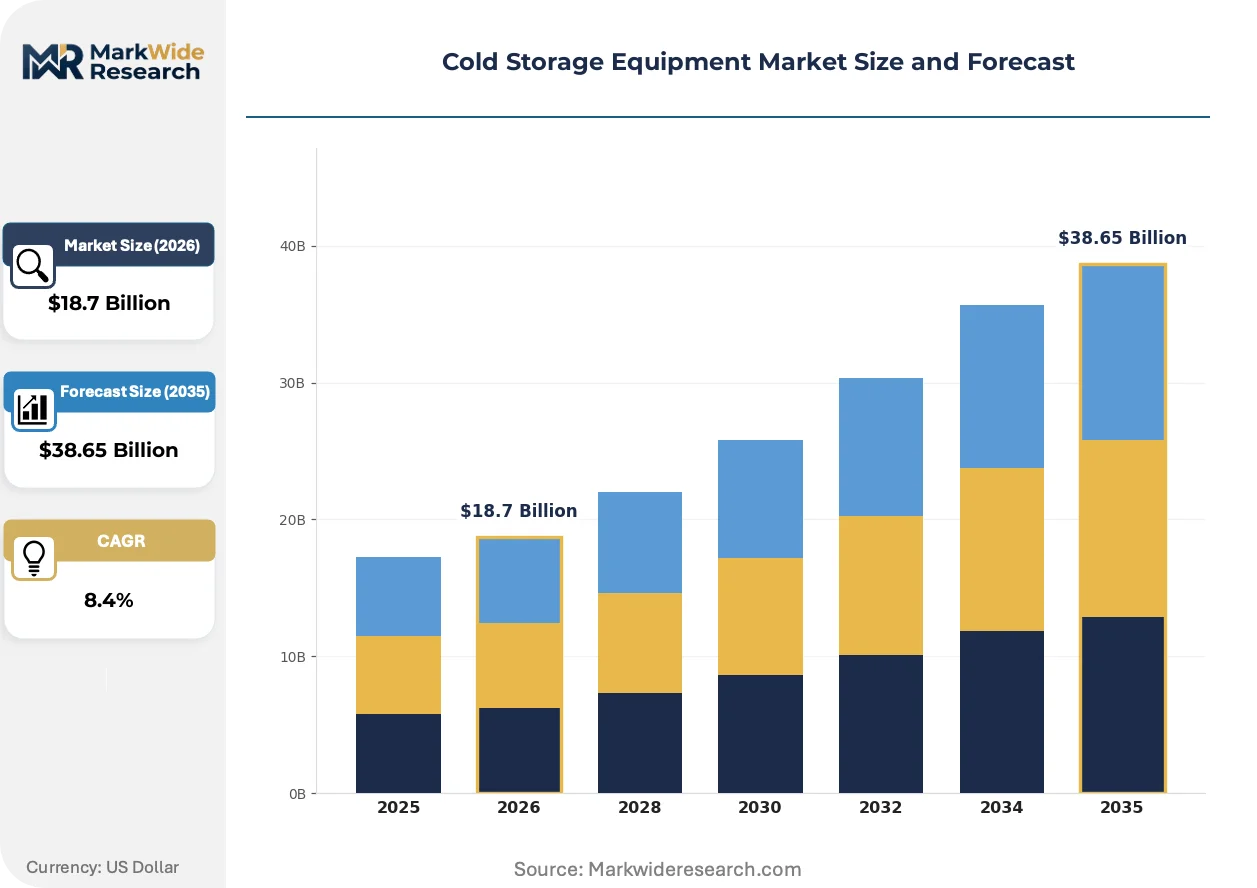
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-in Coolers, Freezers, Modular Cold Rooms, Blast Chillers End User: Food and Beverage, Pharmaceuticals, Chemicals, Warehousing Technology: Vapor Compression, Absorption Cooling, Thermoelectric, Air-Cooled Installation: On-site, Prefabricated, Customized, Portable |
| Companies Covered | Daikin Industries, Carrier Global Corporation, Thermo King, Thermo Fisher Scientific, Trane, Johnson Controls, BITZER SE, CAREL, Zanotti SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Storage Equipment Market Strategic Shifts
Refrigeration technology is fragmenting across multiple efficiency and compliance pathways, with equipment buyers navigating converging pressures from energy standards, refrigerant phaseouts, and pharmaceutical validation requirements. This complexity is accelerating specialization among subsystem suppliers.
Variable-speed inverter scroll compressors are collapsing energy consumption profiles in medium-temperature warehouse applications. Food retail operators are adopting these systems at replacement cycle points to hedge against electricity rate volatility. The technology is compressing payback periods for efficiency investments from seven years toward four years in high-utilization facilities.
The EU F-Gas Regulation is mandating stepped reductions in hydrofluorocarbon import quotas through 2030. Equipment manufacturers are reconfiguring product lines toward CO₂ and hydrocarbon architectures to maintain market access. Pharmaceutical cold storage operators face the steepest compliance curve due to stringent temperature validation requirements that limit refrigerant experimentation.
Service contract unbundling is separating equipment ownership from performance guarantees in pharmaceutical logistics. Third-party logistics providers are purchasing uptime commitments rather than capital assets, transferring operational risk to original equipment manufacturers. This shift is most pronounced in the United States, where vaccine distribution networks prioritize availability over asset control.
Cold Storage Equipment Market Segmentation
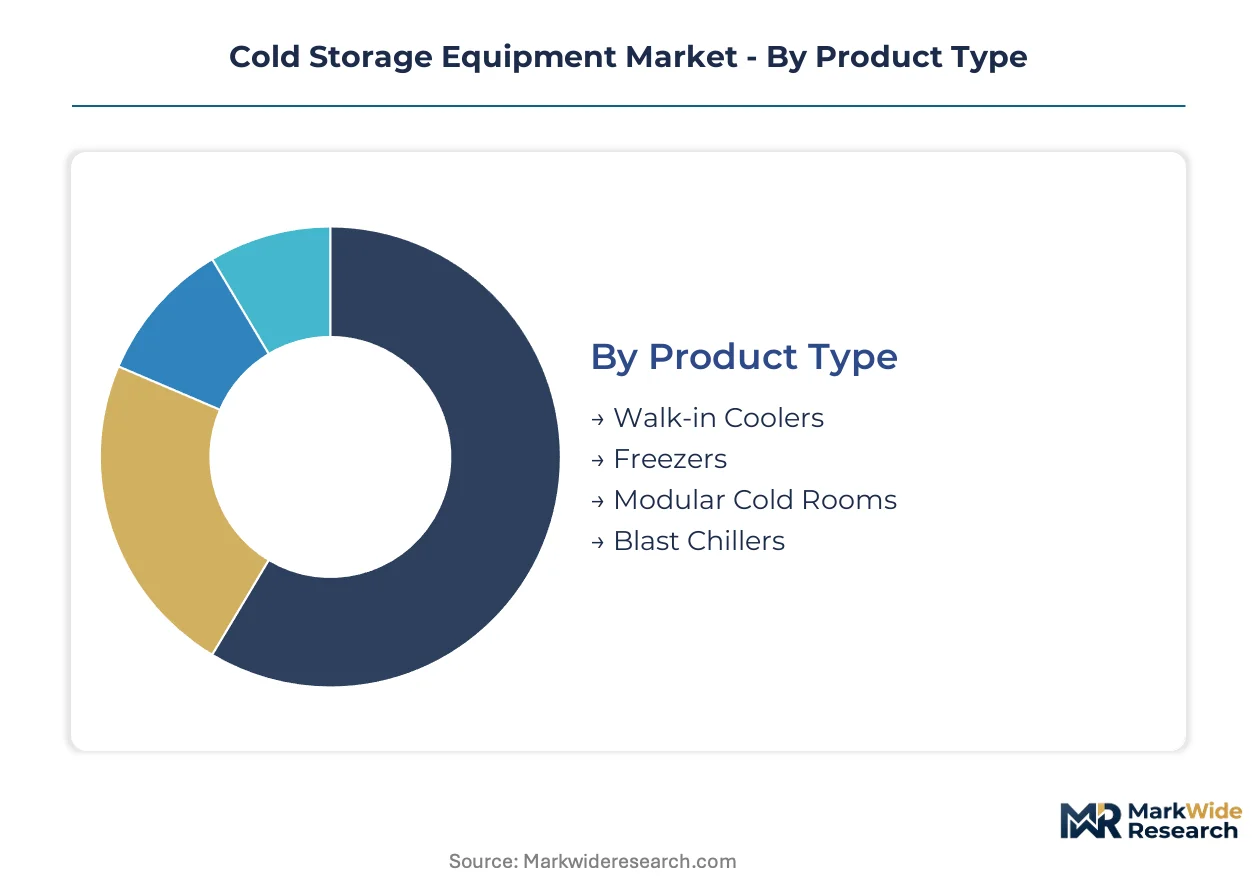
Cold storage equipment segmentation reflects divergent replacement cycles across product architectures and compliance pressures from refrigerant phaseouts. Equipment buyers prioritize modularity and validation precision differently depending on end-use temperature sensitivity and regulatory exposure.
Product Type:
Walk-in coolers and freezers turn over fastest as food retail chains cycle equipment every 12-15 years, while blast chillers in industrial processing endure 20-year lifespans with component refurbishment.
- Walk-in Coolers:Insulated panel enclosures with integrated refrigeration machinery maintain temperatures between 0°C and 10°C for fresh produce and dairy storage. US foodservice distributors and supermarket chains in California and Texas are replacing ammonia-based legacy systems with modular units to satisfy EPA refrigerant quotas and reduce on-site construction risk.
- Freezers:Low-temperature enclosures engineered for -18°C to -25°C operation utilize high-density polyurethane insulation and multi-stage compression. Frozen food logistics hubs in the Midwest are driving demand for units with validated temperature uniformity to meet USDA HACCP digital monitoring mandates.
- Modular Cold Rooms:Factory-assembled panel systems with plug-and-play refrigeration packages compress installation timelines for pharmaceutical distribution centers.
- Blast Chillers:Rapid temperature reduction units for commercial kitchens and food processing plants achieve core temperatures below 3°C within 90 minutes to inhibit bacterial proliferation.
Walk-in coolers dominate installed base. Blast chillers are where expansion concentrates in food safety-critical applications.
End User:
Cost tier stratification separates capital-intensive pharmaceutical validation from price-sensitive food retail procurement, with chemical storage occupying intermediate investment levels.
- Food and Beverage:Cold chain infrastructure for meat, dairy, and produce distribution constitutes the volume foundation. Operators face USDA inspection compliance and are retrofitting aging facilities with CO₂ transcritical systems ahead of hydrofluorocarbon quota restrictions.
- Pharmaceuticals:Cell and gene therapy distribution requires validated storage within ±2°C uniformity across entire chamber volumes. US vaccine distribution networks and biologics manufacturers are procuring redundant refrigeration architectures with continuous temperature monitoring to satisfy FDA quality system regulations.
- Chemicals:Temperature-controlled storage for industrial reagents and specialty materials maintains stability of moisture-sensitive compounds.
- Warehousing:Third-party logistics providers are unbundling equipment ownership from performance guarantees, purchasing uptime commitments rather than capital assets.
Food and beverage dominates installed base. Pharmaceuticals represent the steepest expansion trajectory as biologics pipelines mature.
Technology:
Application requirements dictate technology selection, with energy efficiency standards and refrigerant compliance reshaping investment priorities across commercial and industrial installations.
- Vapor Compression:Mechanical refrigeration cycles using compressor-driven refrigerant phase change deliver proven coefficient of performance across -40°C to +15°C ranges. The technology anchors existing capacity but faces refrigerant transition costs as EPA AIM Act quotas tighten.
- Absorption Cooling:Heat-activated refrigeration utilizing lithium bromide or ammonia-water solutions operates without electrical compression. Industrial cogeneration facilities and waste-heat recovery installations are adopting these systems where thermal energy is available at lower marginal cost.
- Thermoelectric:Solid-state Peltier cooling provides precise temperature control for small-volume pharmaceutical storage without moving parts or refrigerant charge.
- Air-Cooled:Condenser architectures rejecting heat directly to ambient air eliminate water consumption and cooling tower infrastructure.
Vapor compression dominates installed base. Absorption cooling is where expansion concentrates in industrial waste-heat recovery applications.
Installation:
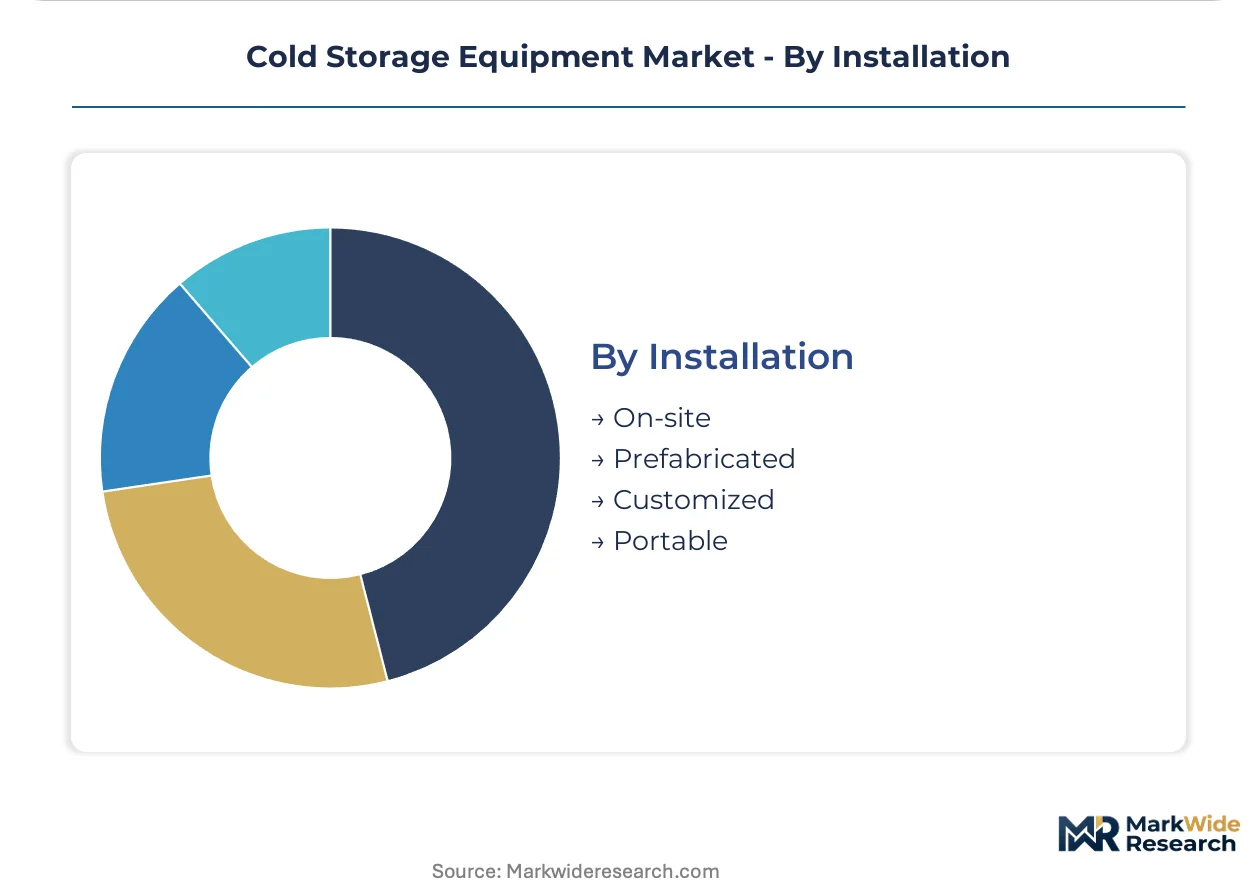
Supply chain configuration determines procurement mode, with prefabricated units compressing project risk for time-constrained pharmaceutical deployments versus customized engineering for complex industrial retrofits.
- On-site:Field-erected insulation and refrigeration systems accommodate non-standard dimensions and integration with existing building envelopes. Large-scale meat processing facilities and cold storage warehouses are pursuing this approach where ceiling heights exceed prefabricated panel limits.
- Prefabricated:Factory-manufactured modular units with pre-charged refrigeration circuits reduce installation duration and contractor coordination risk. Pharmaceutical third-party logistics providers are standardizing on these systems to accelerate validation timelines for vaccine distribution capacity.
- Customized:Engineered-to-specification enclosures address unique footprint constraints or specialized access requirements.
- Portable:Mobile cold storage units on trailer or skid mounts serve temporary capacity needs and emergency response logistics.
On-site construction dominates installed base. Prefabricated solutions are where expansion concentrates as operators prioritize speed-to-validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered refrigeration compressors to pharmaceutical distribution networks across the United States and India. These trade corridors reflect divergent regional compliance pressures and infrastructure investment cycles.
United States
Food processing hubs in the Midwest and vaccine distribution networks drive continuous cold storage infrastructure replacement. The EPA's AIM Act refrigerant phasedown accelerates capital redeployment toward low-GWP systems before quota restrictions tighten. Chicago and Dallas-Fort Worth anchor the largest concentration of warehouse automation projects for temperature-controlled logistics.
Germany
Industrial machinery exports and pharmaceutical manufacturing sustain demand for validated storage systems with precise temperature uniformity. The EU F-Gas Regulation mandates stepped reductions in hydrofluorocarbon import quotas through 2030. The Rhine-Ruhr industrial corridor hosts the densest cluster of CO₂ transcritical system retrofits for food retail distribution.
India
The PLI scheme for food processing and pharmaceutical exports unlocks warehouse automation demand in temperature-controlled logistics. FSSAI enforcement of cold chain standards for perishable food distribution forces equipment upgrades across fragmented storage networks. Maharashtra and Gujarat concentrate the fastest-expanding pharmaceutical cold storage capacity for export-oriented biologics manufacturing.
China
Domestic vaccine distribution scale and fresh produce e-commerce penetration drive modular cold room procurement. MEE oversight of hydrofluorocarbon consumption under dual carbon goals shapes refrigerant transition timelines. The Yangtze River Delta industrial cluster leads adoption of inverter-driven compression systems for energy efficiency compliance.
Japan
Cell and gene therapy commercialization and precision agriculture exports sustain demand for ultra-low temperature storage validation. METI energy efficiency standards for commercial refrigeration equipment compress replacement cycles in food retail. The Kanto region around Tokyo concentrates pharmaceutical logistics infrastructure investment for regional biologics distribution.
Cold Storage Equipment Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement channels in cold storage equipment. Consolidation pressures concentrate around compressor manufacturing and control system integration, while panel fabrication and installation services remain dispersed. Two strategic archetypes dominate: integrated HVAC conglomerates with captive distribution networks, and refrigeration-focused specialists with deep subsystem expertise. Competitive moves center on vertical integration into compressor manufacturing and strategic partnerships for refrigerant transition compliance.
Among integrated HVAC conglomerates, Carrier Global Corporation and Daikin Industries occupy positions anchored by compressor manufacturing depth and inverter-driven system portfolios. Thermo King exemplifies the transport-connected specialist archetype, sitting within the intermodal pharmaceutical logistics segment. These three companies represent divergent approaches to refrigerant transition timing and geographic market prioritization.
| Leading Market Players |
|---|
| Daikin Industries |
| Carrier Global Corporation |
| Thermo King |
| Thermo Fisher Scientific |
| Trane |
| Johnson Controls |
| BITZER SE |
| CAREL |
| Zanotti SpA |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's freight cost volatility compresses equipment margins for European cold storage builders sourcing compressor assemblies from East Asia. This logistics tension amplifies price differentiation between ammonia-based legacy retrofits and CO₂ transcritical system deployments, while downstream buyers in pharmaceutical logistics prioritize uptime guarantees over capital expenditure minimization.
Pricing Analysis
Technology-generation pricing gaps separate three distinct equipment tiers: prior-generation hydrofluorocarbon-based systems trade at commodity benchmarks, current-generation inverter-driven scroll configurations command efficiency premiums, and next-generation natural refrigerant architectures carry compliance-driven cost structures. Project-based contracting dominates pharmaceutical validation deployments, while food retail procurement favors per-unit transactional models with volume scale discounts. Price differentiation hinges on FDA 21 CFR Part 11 validation certification and geographic delivery cost from East Asian manufacturing clusters. Pricing pressure stems from copper and aluminum commodity volatility compressing heat exchanger margins. Foodservice distributors exhibit highest price sensitivity; biologics manufacturers accept premium positioning for redundant refrigeration architectures.
Supply Chain Analysis
Supplier-financing facilities from Japanese trading houses extend payment terms for Indian cold storage developers procuring modular panel systems. Manufacturing concentration clusters in China, Japan, and Germany for compressor assemblies, with polyurethane insulation panel fabrication distributed across regional markets. The supply chain draws from copper tubing, aluminum fin stock, and refrigerant gases as critical inputs. Single-source vulnerability concentrates in scroll compressor production from East Asian facilities. Distribution runs through OEM-direct channels for large industrial retrofits and specialized refrigeration distributors for commercial foodservice deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold storage equipment procurement is shifting toward platform-economics logic as service contract unbundling separates asset ownership from performance guarantees. BACnet and Modbus interoperability standardization enables this ecosystem transition by allowing third-party logistics providers to integrate multi-vendor monitoring infrastructure.
For Market Incumbents: Harden compressor manufacturing capacity in North America to offset lead time vulnerability from East Asian supply concentration. Anchor distribution networks with captive service capabilities that guarantee uptime commitments rather than equipment sales. The EPA's AIM Act refrigerant phasedown threatens stranded inventory for manufacturers slow to reconfigure product lines toward CO₂ architectures. Vertical integration into control system software development defends margin position against unbundling trends.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat pharmaceutical corridors offer underpenetrated demand for validated modular cold rooms as PLI scheme incentives accelerate biologics export capacity. Target last-mile urban clinic networks with compact thermoelectric storage units designed for direct-to-patient gene therapy distribution. A rental-based go-to-market model bypasses capital expenditure barriers among mid-sized third-party logistics providers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive refrigeration divisions lacking standalone scale. Long-term viability favors specialists with subsystem depth in compressor technology or pharmaceutical validation protocols. The inflection signal to watch is EU F-Gas Regulation quota allocation announcements accelerating replacement demand pull-forward.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Compliance | EPA AIM Act and EU F-Gas Regulation deadlines force product line reconfiguration toward natural refrigerant architectures. |
| Compressor Manufacturing Scale-Up | captive scroll and screw production in North America reduces lead time exposure from East Asian supply concentration. |
| Pharmaceutical Validation Partnership | FDA 21 CFR Part 11 compliance investments unlock biologics distribution contracts with precision temperature requirements. |
| Service Contract Unbundling | Uptime guarantee models transfer operational risk from third-party logistics providers to original equipment manufacturers. |
| India Cold Chain Infrastructure Expansion | PLI scheme incentives for food processing and pharmaceutical exports unlock warehouse automation demand in temperature-controlled logistics. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cold storage facility managers, pharmaceutical quality assurance directors, food retail procurement leads, and refrigeration contractor service heads. Secondary validation drew from EPA refrigerant quota filings, EU F-Gas Regulation implementation reports, USDA HACCP inspection data, and SEC 10-K disclosures from listed HVAC conglomerates. Bottom-up equipment shipment data triangulated against top-down infrastructure investment tracking across the analysis window.
Calibration against historical replacement cycle patterns and regulatory compliance deadlines anchored the analytical framework. Segmentation dimensions modeled include product architecture, end-use temperature sensitivity, refrigerant technology generation, and installation modality. CAGRs derived from equipment procurement pipeline analysis and capital expenditure surveys across food processing and pharmaceutical distribution networks. Forecast inputs incorporated EPA AIM Act phasedown schedules and EU F-Gas quota trajectories as structural demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese compressor manufacturers or accelerated refrigerant transition timelines by European regulators would shift outcomes. Macroeconomic deviation in commodity input costs, regulatory enforcement intensity, or biologics commercialization rates would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Vee Bee Consistometer Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Industrial Steam Peeler Market
Food Processing Equipment
Fish Feed Pellet Making Machine Market
Food Processing Equipment
Industrial Fryers Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Individual Quick Freezing Market
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Global Industrial Food Blanchers Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Vacuum Frying Machine Market
Food Processing Equipment
Destemmer Market