
 North America Dehydrated Onion Market | 2026-2036
North America Dehydrated Onion Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dehydrated Onion Market Analytics
The divergence between premium organic and commodity-grade dehydrated onion is hardening around moisture specification, origin certification, and clean-label pedigree. Van Drunen Farms anchors the premium tier through its vertically integrated grower network in Illinois and Wisconsin. Silva International specializes in custom dehydration profiles for industrial sauce manufacturers. McCormick & Company controls retail shelf presence through branded spice and seasoning portfolios.
Dehydrated onion comprises fresh Allium cepa subjected to controlled thermal reduction, typically achieving moisture content below six percent to inhibit microbial activity and extend shelf stability. The process preserves pungent sulfur compounds responsible for flavor intensity while reducing handling weight to roughly one-tenth of fresh equivalent. Powder and granule formats dominate industrial procurement for soup, sauce, and seasoning base production where solubility and dispersion uniformity matter. Flake and diced categories sustain stronger growth in foodservice and private-label retail channels where visual texture identification drives consumer preference. Bulk container packaging occupies the margin-rich institutional segment, while pouch formats compete aggressively in e-commerce channels.
The FDA's Food Safety Modernization Act and USDA organic certification requirements shape supplier qualification thresholds across the United States, while CFIA regulations govern parallel standards in Canada. Mexico's COFEPRIS alignment with CODEX standards facilitates cross-border ingredient trade under USMCA provisions. Processors must monitor evolving sulfite disclosure rules and organic fraud prevention protocols to defend market access. Stakeholders should evaluate backward integration into controlled-atmosphere storage and regional dehydration assets to secure supply continuity against climate volatility in key growing zones.
Market Dynamics
California's Central Valley dehydration capacity clusters are tightening procurement leverage for industrial sauce and ready-meal manufacturers, forcing processors to secure multi-year supply contracts with validated organic handlers before FDA Food Safety Modernization Act traceability mandates take full effect.
Growth Catalysts
- FSMA Traceability Mandates:FDA's Food Safety Modernization Act requires lot-level documentation from farm to processor, pushing institutional buyers toward certified suppliers with validated supply chain records.
- Ready-Meal Formulation Demand:Food processing operations across the United States and Mexico are expanding dehydrated onion procurement for soup, sauce, and seasoning base production.
- Controlled-Atmosphere Storage Technology:Onion dehydration facilities near raw material sources are adopting advanced storage systems to extend processing windows and reduce post-harvest loss.
Market Restraints
- Input Cost Volatility:Natural gas prices for thermal dehydration fluctuate with regional energy markets, compressing margin predictability for toll processors.
- Supply Concentration Risk:Dehydration capacity concentrates heavily in California's Central Valley and select Midwest growing zones, creating geographic vulnerability to drought and heat stress.
- Sulfite Disclosure Friction:Evolving sulfite labeling requirements under FDA and CFIA regulations impose reformulation costs on processors using sulfur dioxide as a color preservative.
Strategic Opportunities
- USMCA Cross-Border Integration:Mexico's COFEPRIS alignment with CODEX standards facilitates ingredient trade under USMCA provisions, opening sourcing diversification for US processors.
- Clean-Label Organic Premium:USDA organic certification requirements create pricing power for handlers with vertically integrated grower networks and validated organic fraud prevention protocols.
- E-Commerce Pouch Formats:Smaller-format retail packaging channels are expanding direct-to-consumer access beyond traditional institutional bulk container segments.
Industry Challenges
- Certification Timeline Compression:USDA organic and FDA supplier qualification protocols require eighteen-to-twenty-four-month validation cycles, delaying new entrant market access.
- Climate Volatility Reconfiguration:Heat stress and water allocation uncertainty in California and Pacific Northwest growing zones force supply chain reconfiguration toward irrigation-secure Midwest sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dehydrated Onion Market |
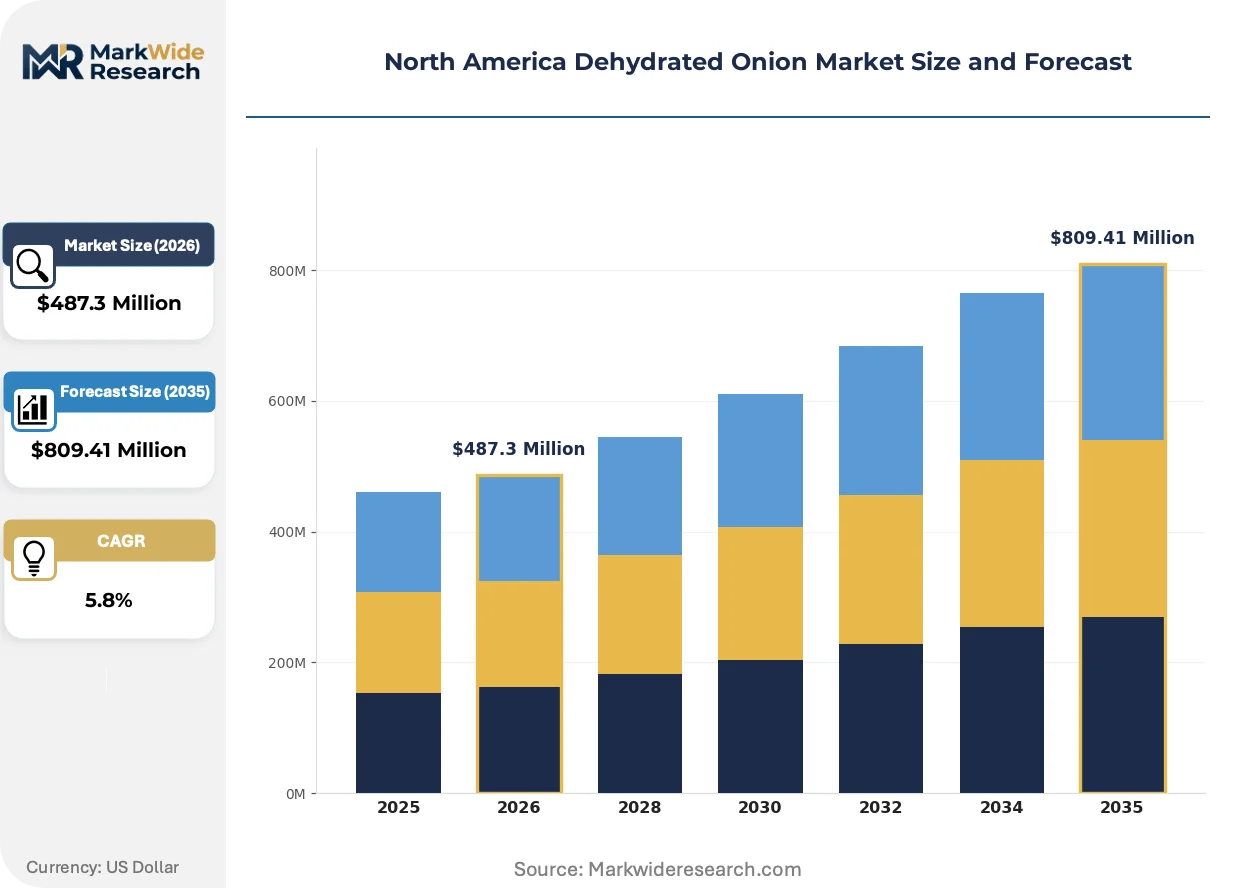
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diced, Flakes, Granules, Powder End Use: Food Processing, Snacks, Sauces, Seasonings Packaging Type: Bags, Jars, Bulk Containers, Pouches Distribution Channel: Online Retail, Supermarkets, Wholesale, Foodservice |
| Companies Covered | Harmony House Foods, Inc., Silva International, Inc., Van Drunen Farms, Rocky Mountain Spice Company, BC Foods Inc., Olam Food Ingredients, Sensient Natural Ingredients, McCormick & Company, Inc., R. J. Van Drunen & Sons, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dehydrated Onion Market Evolving Landscape
Thermal dehydration technology and regulatory traceability systems are compressing supplier qualification timelines while reshaping procurement relationships between processors and certified organic handlers.
Continuous belt dehydration systems with real-time moisture monitoring are consolidating control over final product specification uniformity. Industrial sauce manufacturers are adopting these systems at accelerated replacement cycles to meet solubility and dispersion requirements for high-volume soup bases. The technology is consolidating mid-scale toll processors into larger integrated operations capable of validating full supply chain documentation.
Canada's CFIA Safe Food for Canadians Regulations are tightening import documentation requirements for dehydrated vegetable ingredients entering Canadian processing facilities. Cross-border suppliers must now demonstrate equivalent preventive control protocols to FDA-registered US facilities. Bulk ingredient traders serving dual US-Canada markets are investing in parallel certification systems to maintain cross-border shipment eligibility.
Foodservice operators are unbundling traditional broadline distributor relationships to source dehydrated onion directly from regional dehydration facilities with custom granule and flake specifications. Casino and chain restaurant procurement teams in Nevada and Arizona are contracting directly with California processors for specific visual texture profiles. This disintermediation is most visible in the Southwestern United States where foodservice volume concentration supports dedicated production runs.
North America Dehydrated Onion Market Segmentation
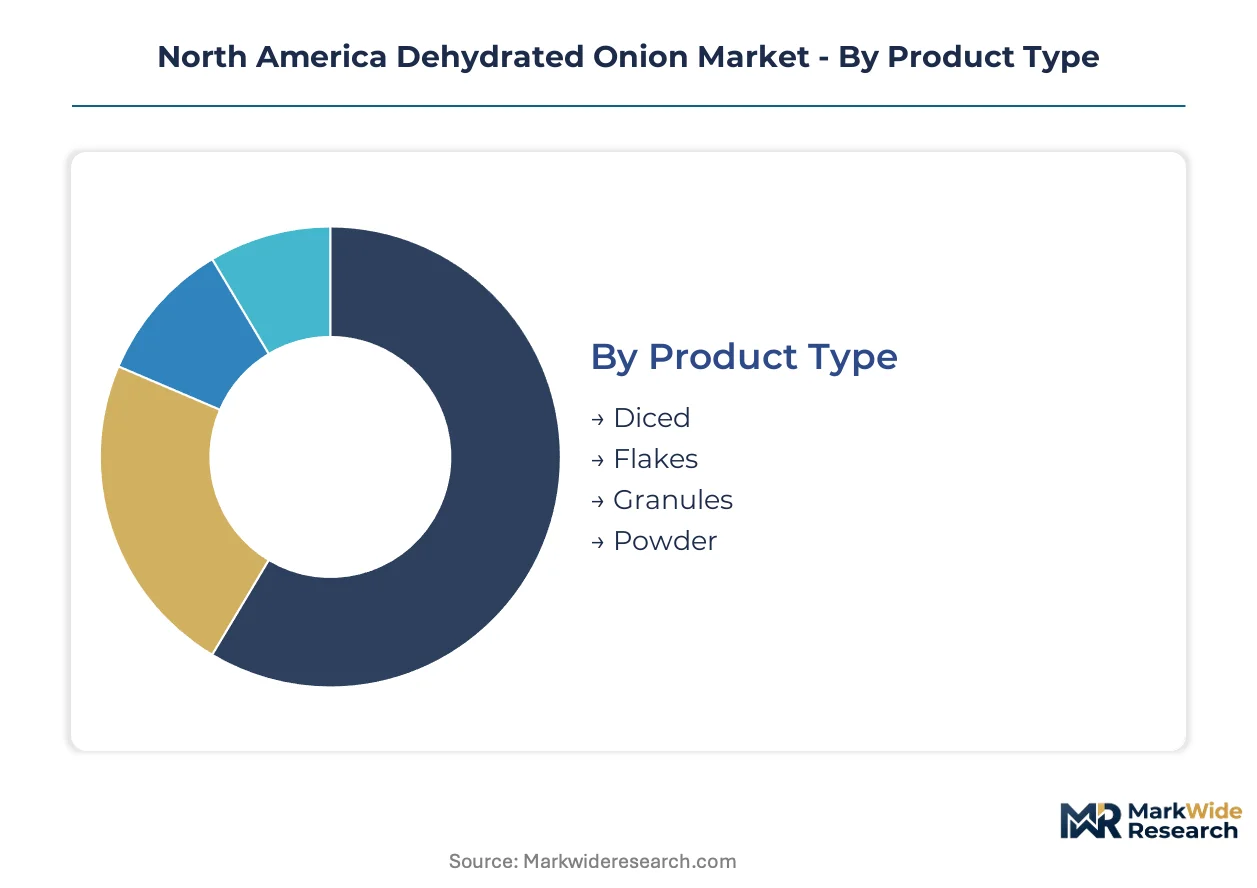
Dehydrated onion procurement patterns diverge sharply across product formats and channel structures. Industrial buyers prioritize solubility specifications and lot traceability, while retail and foodservice segments compete on visual texture and packaging convenience.
Product Type:
Capital intensity varies dramatically across dehydration profiles, with continuous belt systems requiring seven-figure investments for moisture uniformity control while batch operations serve niche specifications.
- Powder:Fine particle size below 80 mesh enables rapid hydration in high-volume soup bases. Sauce manufacturers in California's Central Valley specify powder for dispersion uniformity in institutional formulations. FDA traceability mandates favor suppliers with validated lot-control systems for this segment.
- Granules:Intermediate particle distribution balances solubility speed with visual texture identification. McCormick's retail seasoning portfolios anchor procurement volume here, with custom density specifications for flowability in automated packaging lines.
- Flakes:Retains structural integrity for foodservice applications where visual onion presence drives plate appeal. Casino operators in Nevada contract directly with processors for specific flake dimensions.
- Diced:Largest particle format requiring extended rehydration windows. Bulk institutional procurement dominates, with specifications tightening around sulfite residual thresholds.
Most installed capacity flows through Powder. Expansion is steepest in Flakes.
End Use:
Application-specific moisture and sulfite tolerances create distinct qualification barriers across buyer categories.
- Food Processing:Ready-meal manufacturers require sub-six-percent moisture with validated microbial suppression. USMCA cross-border sourcing from Mexico expands under COFEPRIS-aligned CODEX standards for soup and sauce base production.
- Seasonings:Blending operations demand consistent color retention and flowability profiles. USDA organic certification premiums concentrate here as clean-label positioning intensifies retail competition.
- Sauces:Viscosity stability requirements favor specific granule geometries. Industrial sauce producers specify custom dehydration curves for Maillard reaction control.
- Snacks:Flavor intensity specifications prioritize pungent sulfur compound preservation. Seasoning adherence challenges drive particle size optimization for coating uniformity.
Procurement volume concentrates in Food Processing. Margin expansion is most visible in Seasonings.
Packaging Type:
Format selection tracks channel economics, with bulk containers capturing institutional volume and pouch formats penetrating direct-to-consumer channels.
- Bulk Containers:Tote and drum formats dominate industrial procurement with lowest per-unit logistics cost. California dehydration clusters optimize outbound freight to sauce manufacturers.
- Pouches:Flexible packaging gains share in e-commerce channels where shipping cube efficiency matters. Resealability features compete for pantry shelf retention.
- Jars:Glass and PET containers sustain presence in conventional retail spice aisles. McCormick's branded portfolio controls shelf positioning here.
- Bags:Multi-wall paper and poly structures serve club store and foodservice redistribution. Moisture barrier specifications tighten for extended distribution cycles.
Unit economics favor Bulk Containers at scale. Channel growth is accelerating in Pouches.
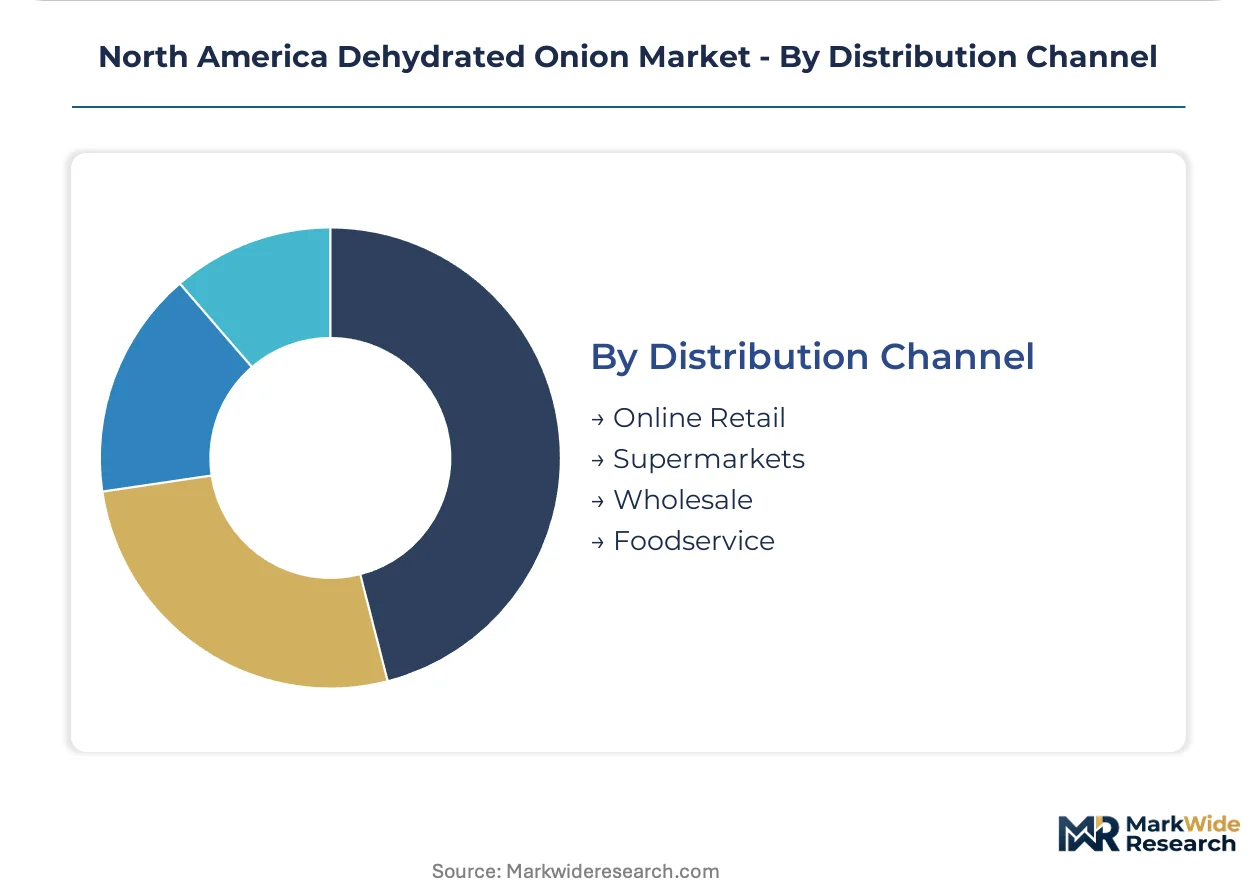
Distribution Channel:
Channel structure determines documentation depth, with foodservice direct contracts requiring full supply chain validation versus retail intermediaries.
- Foodservice:Broadline disintermediation accelerates as casino and chain restaurant procurement teams source directly from California processors. Custom flake and granule specifications justify dedicated production runs.
- Wholesale:Ingredient distributors maintain cross-border eligibility through parallel FDA and CFIA certification systems. Bulk volume consolidation occurs here for mid-scale processors.
- Supermarkets:Private-label and branded shelf competition intensifies around clean-label positioning. Slotting fees and promotional calendars shape supplier economics.
- Online Retail:Direct-to-consumer growth strains conventional packaging formats. Subscription models and specialty organic SKUs expand addressable market beyond institutional buyers.
Transaction volume flows predominantly through Wholesale. Structural change is most pronounced in Foodservice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized dehydration technicians and food safety auditors concentrate in California's Central Valley, anchoring North America's processing capacity for onion dehydration and quality validation.
United States
Ready-meal manufacturers in Illinois and Wisconsin expand procurement of certified organic dehydrated onion for clean-label soup bases. FDA's Food Safety Modernization Act mandates lot-level traceability documentation from farm to processor, compressing supplier qualification timelines. California's Central Valley dehydration clusters near Fresno and Bakersfield dominate capacity, with processors securing multi-year supply contracts ahead of full FSMA implementation.
Canada
Seasoning blenders in Ontario and Quebec prioritize CFIA-compliant import documentation for dehydrated vegetable ingredients entering Canadian processing facilities. CFIA's Safe Food for Canadians Regulations require equivalent preventive control protocols to FDA-registered US suppliers. Toronto-area ingredient distributors invest in parallel certification systems to maintain cross-border shipment eligibility under tightened import standards.
Mexico
Soup and sauce base producers in Guanajuato and Jalisco scale dehydrated onion procurement under USMCA provisions for cross-border ingredient trade. COFEPRIS alignment with CODEX standards facilitates regulatory equivalence for exports to US processing operations. Bajío Region dehydration facilities near León expand capacity to serve expanding ready-meal formulation demand from American manufacturers.
North America Dehydrated Onion Market Competitive Landscape
Top-tier vendors anchor premium organic and certified supply chain tiers, while mid-scale toll processors compete on custom dehydration profiles and regional logistics efficiency. The vendor base stratifies around three strategic archetypes: vertically integrated grower-processors with controlled-atmosphere storage assets, specialized custom-profile dehydrators serving industrial sauce manufacturers, and branded retail portfolio controllers with shelf-space dominance. Competitive moves concentrate on backward integration into regional dehydration assets and multi-year supply contract lock-ins ahead of regulatory traceability deadlines.
Within the vertically integrated tier, Van Drunen Farms and R. J. Van Drunen & Sons, Inc. exemplify grower-processor consolidation through captive supply networks in Illinois and Wisconsin. Silva International, Inc. occupies a position among custom-profile specialists, serving industrial manufacturers with tailored dehydration specifications. These three anchors represent distinct competitive vectors—captive raw material control, technical specification flexibility, and scale-driven cost efficiency—that define procurement alternatives for institutional buyers.
| Leading Market Players |
|---|
| Harmony House Foods, Inc. |
| Silva International, Inc. |
| Van Drunen Farms |
| Rocky Mountain Spice Company |
| BC Foods Inc. |
| Olam Food Ingredients |
| Sensient Natural Ingredients |
| McCormick & Company, Inc. |
| R. J. Van Drunen & Sons, Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned dehydration specialists in the Midwest and California anchor supply discipline through multi-generational grower relationships that resist short-term margin compression. Their captive storage assets and long-dated processor contracts insulate pricing from spot-market volatility while concentrating procurement leverage among validated organic handlers.
Pricing Analysis
Contract-based long-term offtake dominates bulk institutional procurement, while spot-market transactions serve smaller foodservice accounts needing custom flake specifications. Price differentiation hinges on USDA organic certification tier and volume scale, with certified organic handlers commanding premiums over conventional commodity grades. Cost compression in conventional powder tiers is intensifying because natural gas inputs for thermal dehydration fluctuate with regional energy markets. Mid-scale toll processors exhibit highest price sensitivity, lacking backward integration to buffer input volatility.
Supply Chain Analysis
Dual-sourcing requirements from FDA-registered ready-meal manufacturers mandate multi-supplier qualification across California, Mexico, and the Midwest growing zones. Raw material flows draw from fresh Allium cepa harvests in California's Central Valley, irrigation-secure Midwest sources, and expanding Bajío Region dehydration facilities near León. Single-source vulnerability concentrates in California's drought-exposed Central Valley clusters. Distribution runs through wholesale ingredient distributors maintaining parallel FDA and CFIA certification systems for cross-border eligibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America dehydrated onion market functions as a regulatory compounder, with FDA's Food Safety Modernization Act traceability mandates accelerating procurement consolidation among certified suppliers.
For Market Incumbents: Extend controlled-atmosphere storage capacity in Illinois and Wisconsin to secure captive supply networks against climate volatility in California growing zones. Invest in parallel FDA-CFIA certification systems to defend cross-border shipment eligibility as Canadian import documentation tightens. Lock multi-year supply contracts with organic handlers before full traceability implementation compresses qualified supplier pools. For New Entrants and Emerging Players: Foodservice redistribution channels offer lowest barrier to entry for custom flake and granule specifications unbundled from broadline distributor relationships. Target direct procurement contracts with casino and chain restaurant operators in Nevada and Arizona seeking specific visual texture profiles. Pursue e-commerce pouch format positioning where subscription models and specialty organic SKUs expand beyond institutional buyer concentration. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale toll processors lacking backward integration, presenting consolidation targets for larger integrated operations. Five-to-ten-year viability centers on dehydration facilities with validated organic fraud prevention protocols and regional logistics efficiency. Watch CFIA Safe Food for Canadians enforcement intensity as inflection indicator for cross-border supplier qualification costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled-Atmosphere Storage | Secures supply continuity against drought and heat stress in California's Central Valley clusters. |
| Parallel FDA-CFIA Certification Investment | Maintains cross-border shipment eligibility under tightened Canadian import documentation requirements. |
| Custom Dehydration Profile Development | Captures foodservice direct contracts from casino operators seeking specific flake dimensions. |
| E-Commerce Pouch Format Launch | Expands direct-to-consumer access beyond institutional bulk container segments through shipping cube efficiency. |
| Multi-Year Organic Supply Contract Lock-in | Defends procurement position ahead of FSMA traceability mandate compression of qualified supplier pools. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combined with secondary validation across trade and regulatory databases. Primary interviews engaged dehydration facility operations managers, ready-meal manufacturer procurement directors, foodservice redistribution buyers, organic certification auditors, and cross-border ingredient traders. Secondary sources incorporated FDA FSMA implementation guidance, CFIA Safe Food for Canadians regulatory filings, USDA organic handler databases, USMCA trade documentation, and customs records for dehydrated vegetable ingredient flows. Bottom-up capacity assessments and top-down demand modeling underwent triangulation against processor-reported volume trends.
Granularity-level modeling tracked product type, end-use application, packaging format, and distribution channel dimensions across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by price realization trends in organic versus conventional tiers. Forecast inputs incorporated natural gas price sensitivity for thermal dehydration operations, climate volatility scenarios for California and Midwest growing zones, and regulatory compliance cost escalations under evolving sulfite disclosure rules.
Revisions become necessary when FDA traceability mandate enforcement intensity, CFIA import documentation requirements, or climate-induced supply disruptions in key growing zones materialize outside baseline assumptions. Deviation in organic certification fraud prevention protocol stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food and Beverage Sterilizing Agent Market
Food Additives and Ingredients
Bakery Stabilizers Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
Food Grade Sodium Citrate Market
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
South Africa Food Colorants Market
Food Additives and Ingredients
Global Sodium Starch Glycolate Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Microencapsulated Food Ingredient Market
Food Additives and Ingredients
United Kingdom Food Additives Market