
 No Fat Snacks Market | 2026-2036
No Fat Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
No Fat Snacks Market Analytics
Non-GMO Project verification is unwinding as the baseline credential for shelf placement in mainstream retail, forcing reformulation cycles on suppliers that lack certified ingredient streams. General Mills leverages its grain-based R&D pipeline to sustain leadership in cracker and cookie segments with validated fat-free claims. Mondelez International anchors its competitive stance through manufacturing scale across North American and European production networks. PepsiCo differentiates via channel control, extending direct-store-delivery infrastructure into convenience retail for no-fat chip lines.
No fat snacks are formulated food products containing less than 0.5 grams of fat per reference amount customarily consumed, achieved through baked-not-fried processing, air-puffing, or enzymatic fat replacement systems designed to deliver texture and mouthfeel comparable to conventional alternatives. The vegetable-based ingredient segment leads volume contribution due to potato and cassava starch versatility, while the online retail distribution channel records the fastest growth trajectory as subscription models capture recurring purchases from fitness enthusiasts and weight watchers. Grain-based formulations occupy mature margin pools where oat and rice derivatives command stable pricing through established supplier relationships.
The FDA enforces Nutrition Facts labeling standards that mandate trans fat disclosure and substantiation of fat-free claims, while the USDA oversees ingredient sourcing integrity through its organic certification program applicable to grain and vegetable inputs. The EU's F-Gas Regulation indirectly shapes processing technology selection by restricting hydrofluorocarbon use in industrial refrigeration systems employed during snack manufacturing. Stakeholders must monitor evolving sodium reduction mandates from EFSA and state-level sugar disclosure laws that will compound formulation complexity beyond fat removal alone.
Market Dynamics
Corporate wellness procurement mandates are restructuring volume flows in the no-fat snacks sector, as large employers consolidate pantry purchasing around validated fat-free claims and transparent supply chain documentation.
Growth Catalysts
- FDA Nutrition Facts labeling:Mandatory trans fat disclosure requirements are compelling conventional snack manufacturers to accelerate reformulation toward sub-0.5g fat thresholds, expanding the addressable base for certified no-fat products.
- Enzymatic fat replacement systems:Advances in lipase-modified starch and protein-based texturizers are closing the mouthfeel gap between baked and fried alternatives, removing the primary sensory barrier to adoption.
- Urban health-conscious clusters:Dense metropolitan populations in the United States are concentrating premium demand for vegetable-based crisps, creating predictable recurring revenue streams through subscription retail models.
Market Restraints
- Cassava starch price volatility:Weather-driven harvest fluctuations in Southeast Asian sourcing regions are compressing margins for vegetable-based snack lines dependent on this input.
- Non-GMO certification scarcity:Limited verified grain streams are creating procurement bottlenecks for suppliers seeking baseline shelf placement in mainstream retail channels.
- Air-puffing equipment concentration:Specialized extrusion technology manufacturing concentrates among a narrow supplier base, extending lead times for capacity expansion.
Strategic Opportunities
- EU F-Gas Regulation compliance:Restrictions on hydrofluorocarbon refrigeration systems are creating first-mover advantage for processors investing in alternative cooling infrastructure for baked snack lines.
- Online subscription retail:Direct-to-consumer platforms are capturing fitness enthusiast and weight watcher segments through recurring purchase automation, bypassing traditional wholesale margin structures.
- Oat derivative innovation:Underexploited beta-glucan functionality in grain-based formulations offers positioning around cardiovascular health claims beyond fat reduction alone.
Industry Challenges
- Reformulation timeline compression:Accelerated label disclosure deadlines are forcing simultaneous sodium and sugar reduction alongside fat removal, multiplying testing and validation cycles.
- Ingredient traceability systems:Multi-tier supply chain documentation requirements for organic and non-GMO verification are demanding significant IT infrastructure investment from mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | No Fat Snacks Market |
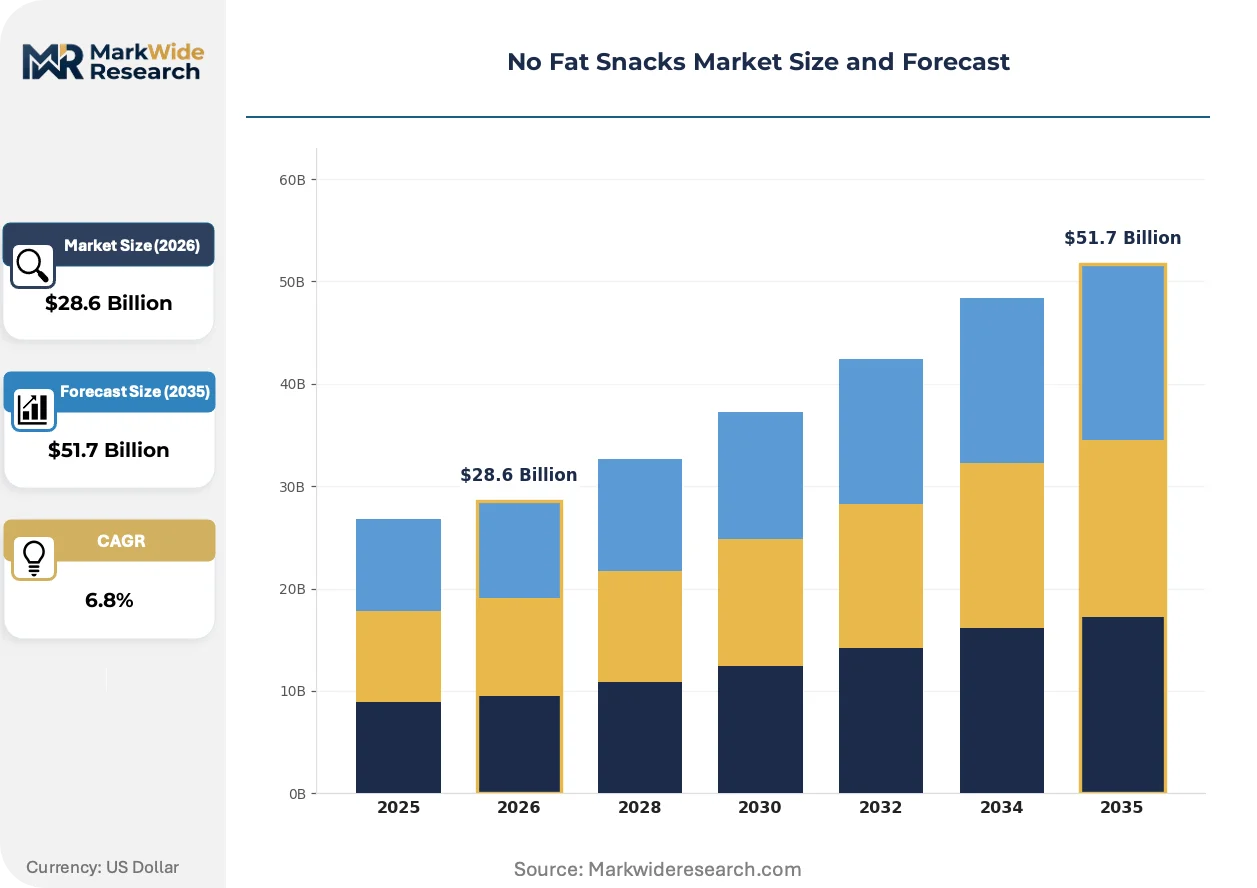
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Cookies, Crackers, Candy Ingredient Type: Vegetable-Based, Nut-Based, Fruit-Based, Grain-Based Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores Customer Type: Health Conscious, Fitness Enthusiasts, Weight Watchers, Diabetics |
| Companies Covered | General Mills, Mondelez International, PepsiCo, Nestlé, Kellogg Company, Kraft Heinz, Jack Link's Snacks, Unilever, Blue Diamond Growers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
No Fat Snacks Market Evolving Landscape
Processing technology convergence and disclosure mandate acceleration are compressing product development cycles while opening new positioning territory around clean-label credentials beyond the single attribute of fat content.
Air-puffing extrusion technology is supplanting conventional frying infrastructure in contract manufacturing facilities. Equipment suppliers report 18-month order backlogs as private-label brands and established processors simultaneously retrofit lines. This capital rotation is compressing price premiums for texture-comparable products and forcing legacy oil-dependent operators into accelerated obsolescence.
The EU's F-Gas Regulation is restricting hydrofluorocarbon use in industrial refrigeration systems employed during snack manufacturing. Processors are responding by selecting ammonia-based or transcritical CO2 cooling infrastructure, with capital allocation decisions now favoring greenfield facilities over brownfield retrofits. Baked-not-fried production networks in Northern Europe are experiencing the most acute equipment procurement pressure.
Direct-store-delivery infrastructure is capturing convenience retail channel access for no-fat chip lines, displacing traditional warehouse-distributor models. Fitness enthusiasts and weight watchers in dense US metropolitan areas are consolidating purchasing through subscription platforms, compressing wholesale margin capture and rewarding manufacturers with captive last-mile logistics capabilities.
No Fat Snacks Market Segmentation
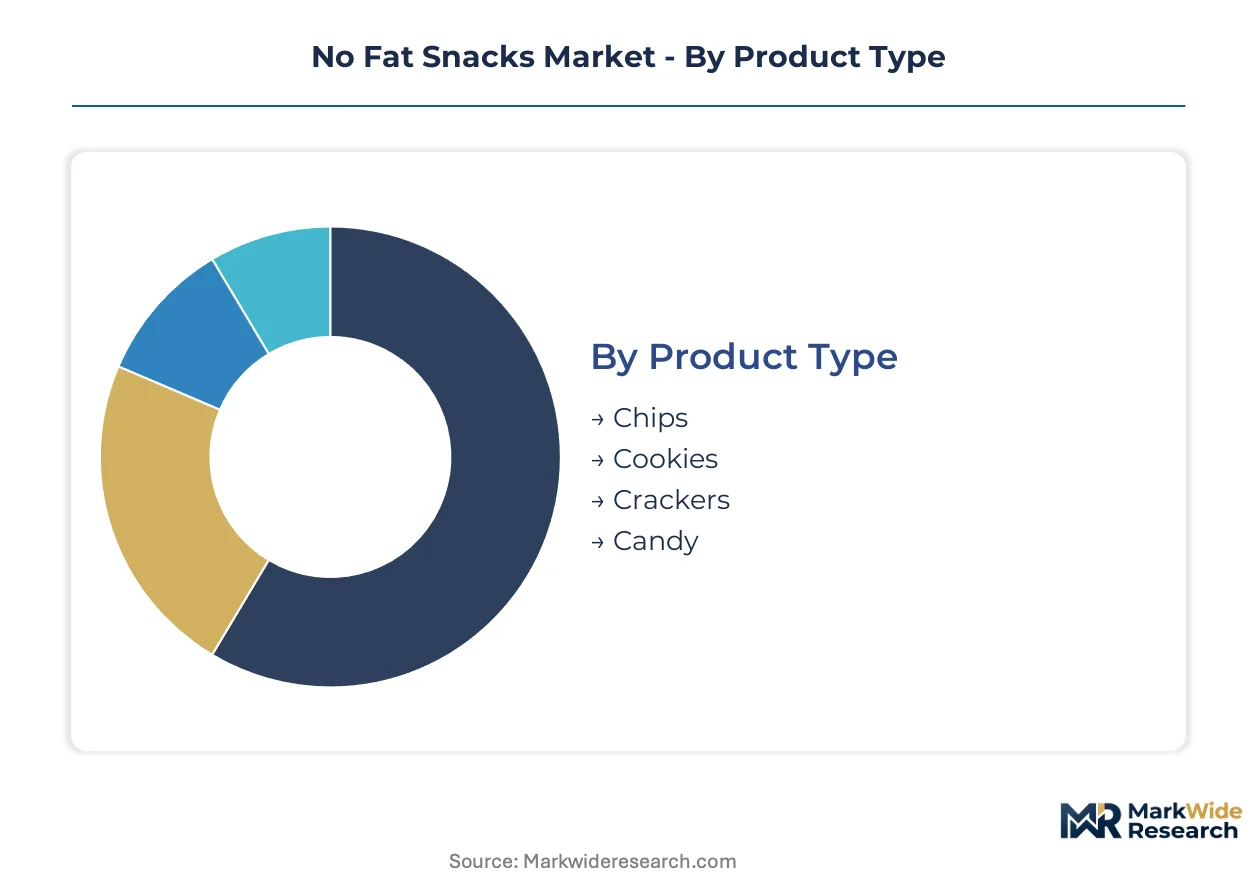
No-fat snack segmentation reveals divergent vulnerability to substitute products across categories. Ingredient sourcing constraints and distribution infrastructure gaps create asymmetric substitution pressure that reshapes competitive positioning within each segment cluster.
Product Type:
Substitution pressure concentrates most acutely in baked formats where conventional fried alternatives retain sensory advantages through fat-mediated flavor delivery.
- Chips:Air-puffed potato and cassava starch formulations achieve sub-0.5g fat thresholds through extrusion rather than frying. Demand clusters in United States metropolitan convenience retail where PepsiCo's direct-store-delivery infrastructure captures recurring purchases from fitness-focused urban consumers.
- Cookies:Enzymatic fat replacement systems using lipase-modified starch replicate shortbread mouthfeel without butter or shortening. General Mills sustains leadership through grain-based R&D pipelines that validate fat-free claims for cracker-cookie hybrid formats in corporate wellness procurement channels.
- Crackers:Baked wheat and rice derivatives dominate shelf-stable formats for employee pantry programs.
- Candy:Pectin and gelatin-based chewy formats replace fat-dependent chocolate coatings.
Chips anchor the volume base while cookies gain share at the steepest rate.
Ingredient Type:
Cost tier stratification separates commodity grain inputs from premium vegetable and nut derivatives with divergent margin structures.
- Vegetable-Based:Potato and cassava starch versatility enables texture engineering across chips and puffed formats. FDA trans fat disclosure mandates accelerate reformulation toward these inputs in United States manufacturing facilities.
- Grain-Based:Oat and rice derivatives command stable pricing through established supplier relationships in mature margin pools. Mondelez International leverages North American and European production network scale to secure preferred oat stream access for cracker segments.
- Nut-Based:Defatted almond and peanut flours provide protein fortification in premium positioning.
- Fruit-Based:Dehydrated apple and berry concentrates deliver natural sweetness without fat carriers.
Grain-based formulations dominate current revenue contribution while vegetable-based alternatives expand most quickly through air-puffing technology adoption.
Distribution Channel:
Volume concentration in legacy wholesale channels contrasts with customer acquisition efficiency in direct-to-consumer platforms.
- Online Retail:Subscription models automate recurring purchases from fitness enthusiasts and weight watchers in dense United States metropolitan clusters. This channel bypasses traditional wholesale margin structures through captive last-mile logistics.
- Supermarkets:Mainstream retail placement demands Non-GMO Project verification as baseline credential, forcing reformulation cycles on suppliers lacking certified ingredient streams.
- Convenience Stores:Direct-store-delivery infrastructure displaces warehouse-distributor models for no-fat chip lines.
- Health Food Stores:Premium positioning around organic certification and transparent supply chain documentation.
Supermarkets retain the volume anchor while online retail climbs the fastest through subscription automation.
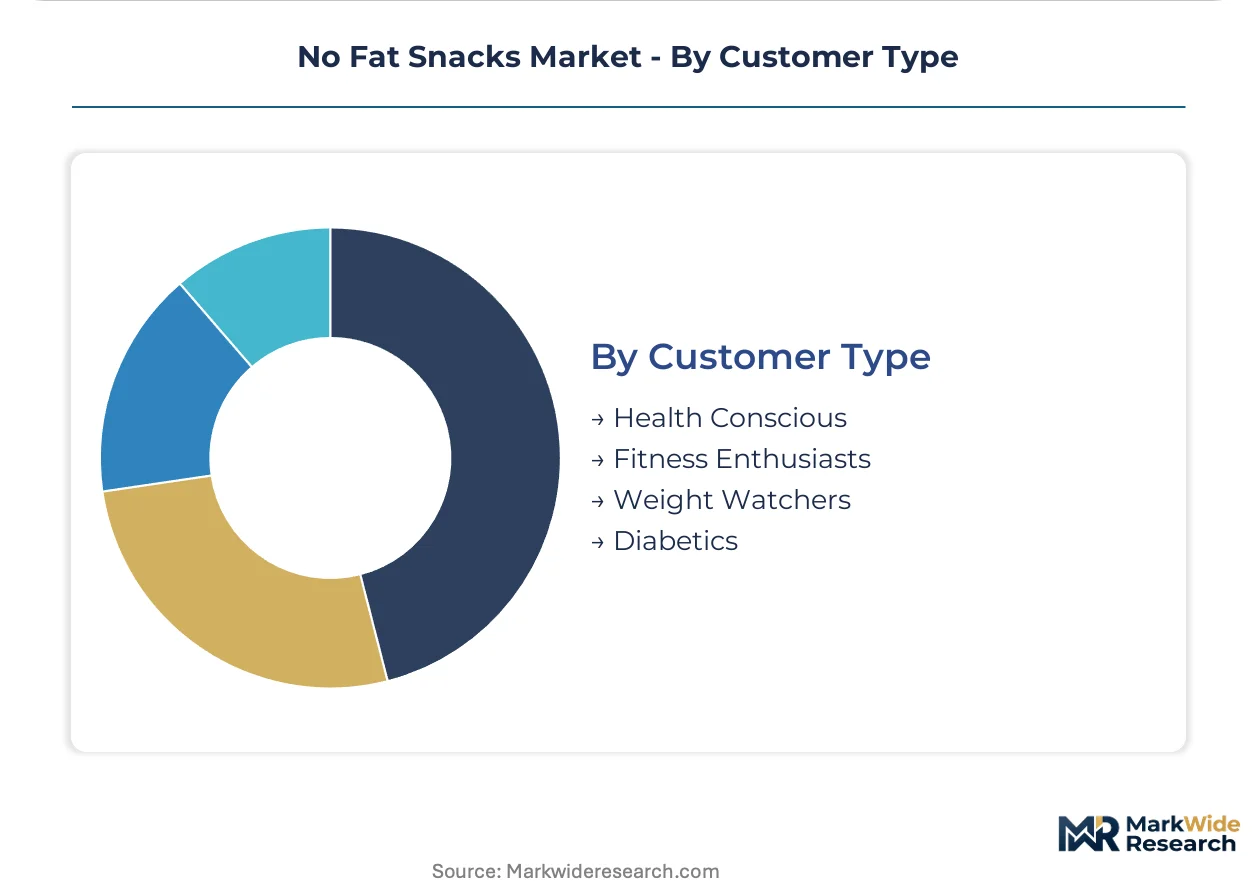
Customer Type:
Maturity gradients separate established diabetic and weight management segments from emerging fitness enthusiast demand with divergent price elasticity.
- Health Conscious:Urban United States consumers drive premium positioning for vegetable-based and grain-based alternatives through transparent label claims and clean-label credentials.
- Fitness Enthusiasts:Protein-fortified and macronutrient-optimized formats concentrate in subscription retail with automated replenishment cycles.
- Weight Watchers:Portion-controlled packaging and point-based nutritional scoring align with program protocols.
- Diabetics:Glycemic index labeling and sugar alcohol formulations address metabolic management requirements.
Health conscious consumers anchor current demand while fitness enthusiasts gain share fastest through platform-native purchasing behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA trans fat disclosure mandates and corporate wellness procurement incentives are concentrating no-fat snack manufacturing and demand across distinct national markets with divergent regulatory timelines and infrastructure maturity.
United States
Health-conscious urban clusters in New York, Los Angeles, and Chicago drive premium positioning for vegetable-based crisps through subscription retail models. The FDA enforces updated Nutrition Facts labeling standards that mandate trans fat disclosure and substantiate fat-free claims below 0.5 grams per serving. PepsiCo leverages direct-store-delivery infrastructure to capture convenience retail channel access for air-puffed chip lines in metropolitan markets.
Germany
Corporate wellness programs in Frankfurt and Munich are expanding procurement of validated fat-free snack options for employee pantries with transparent supply chain documentation requirements. The EU F-Gas Regulation restricts hydrofluorocarbon use in industrial refrigeration systems, compelling processors to select ammonia-based cooling infrastructure for baked snack production. Northern European baked-not-fried facilities experience acute equipment procurement pressure as greenfield investments outpace brownfield retrofits.
United Kingdom
London-based health food retailers concentrate demand for organic-certified grain-based crackers with non-GMO verification as baseline shelf placement credentials. EFSA sodium reduction mandates compound formulation complexity beyond fat removal alone, forcing simultaneous reformulation cycles. The Midlands manufacturing corridor hosts contract facilities retrofitting air-puffing extrusion lines with 18-month equipment order backlogs.
Japan
Tokyo and Osaka metropolitan consumers sustain mature demand for rice-derived crackers with established supplier relationships stabilizing oat and grain input pricing. METI industrial standards shape processing technology selection for enzymatic fat replacement systems in baked formats. The Kanto region concentrates R&D investment in lipase-modified starch texturizers that replicate fried mouthfeel without fat-mediated flavor delivery.
India
Mumbai and Delhi-NCR urban centers are emerging as demand clusters for portion-controlled no-fat snacks aligned with weight management protocols. FSSAI labeling requirements for nutritional disclosure are accelerating domestic reformulation toward sub-0.5g fat thresholds. Maharashtra-based processors are investing in air-puffing capacity to serve both domestic subscription retail and export markets seeking cost-competitive vegetable-based alternatives.
No Fat Snacks Market Competitive Landscape
Player mix skews toward diversified multinational food conglomerates with grain-based R&D pipelines and captive distribution infrastructure. Three to five large-scale processors command volume leadership through manufacturing scale across North American and European production networks. Strategic archetypes include: integrated snack manufacturers with direct-store-delivery capabilities, grain-specialist processors with validated fat-free claim expertise, and contract manufacturers retrofitting air-puffing lines for private-label brands. Dominant competitive moves encompass capacity expansion in enzymatic texturizer applications and backward integration into certified non-GMO grain streams.
Within the integrated multinational tier, General Mills, Mondelez International, and PepsiCo exemplify divergent competitive positioning. General Mills represents grain-based R&D leadership with validated fat-free claims in cracker and cookie segments. Mondelez International occupies a position anchored in North American and European manufacturing network scale. PepsiCo sits within the channel-control archetype, extending captive last-mile logistics into convenience retail for no-fat chip distribution.
| Leading Market Players |
|---|
| General Mills |
| Mondelez International |
| PepsiCo |
| Nestlé |
| Kellogg Company |
| Kraft Heinz |
| Jack Link's Snacks |
| Unilever |
| Blue Diamond Growers |
| Others |
Value Network & Pricing Analysis
Air-puffing extrusion technology replacing conventional frying infrastructure is redrawing procurement geography toward Southeast Asian equipment suppliers while compressing texture premiums and forcing margin recalibration across baked-format processors.
Pricing Analysis
Certification level creates the primary spread across no-fat snack tiers, with Non-GMO Project verification and organic USDA certification commanding shelf placement premiums in mainstream retail. Three-tier pricing structure across premium, standard, and economy levels segments by ingredient traceability depth and clean-label claim density. Cost compression in vegetable-based lines is intensifying because cassava starch harvest volatility in Southeast Asian sourcing regions feeds directly into input pricing. Corporate wellness procurement teams show lowest price sensitivity due to mandate-driven volume commitments, while convenience retail distributors face acute margin pressure from direct-store-delivery displacement.
Supply Chain Analysis
Container availability constraints on Southeast Asia-to-North America trade lanes are extending lead times for air-puffing extrusion equipment with 18-month order backlogs reported. Manufacturing concentrates in Thailand, Vietnam, and Indonesia for cassava starch processing, while oat and rice derivative milling anchors in the United States and Germany. Ingredient sourcing rests on certified non-GMO grain streams, lipase-modified starch texturizers, and ammonia-based refrigeration systems compliant with EU F-Gas Regulation. Single-source vulnerability concentrates in specialized extrusion technology suppliers. Distribution runs through direct-store-delivery networks for convenience retail penetration alongside subscription-platform last-mile capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
No-fat snack demand fragments across fitness enthusiasts, weight watchers, and corporate wellness channels, creating specialist positioning opportunities beyond multinational scale advantages.
For Market Incumbents: Consolidate grain-based R&D pipelines around validated fat-free claims to defend against private-label air-puffing entrants. Secure backward integration into certified non-GMO oat streams before procurement bottlenecks harden. Channel control through direct-store-delivery infrastructure remains the critical lever against subscription-platform disintermediation. For New Entrants and Emerging Players: Lead with enzymatic fat replacement systems in cookie and cracker formats where mouthfeel gaps still disadvantage baked alternatives. Target online subscription retail for fitness enthusiasts in dense United States metropolitan clusters where automated replenishment bypasses wholesale margin capture. Position around transparent supply chain documentation to satisfy corporate wellness procurement mandates. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors contract manufacturers with air-puffing capacity and greenfield cooling infrastructure. Long-term viability hinges on reformulation agility across simultaneous fat, sodium, and sugar reduction mandates. Acquisition focus should center on mid-tier processors with IT-enabled ingredient traceability systems. Watch FDA enforcement patterns on trans fat disclosure deadlines as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Air-Puffing Capacity Expansion | Equipment retrofitting captures private-label volume as frying infrastructure obsolesces. |
| Non-GMO Certification Investment | USDA organic and Non-GMO Project verification secures mainstream retail shelf placement. |
| Direct-to-Consumer Subscription Launch | Captive last-mile logistics bypasses wholesale margin compression in fitness segments. |
| Backward Integration into Oat Supply | In-house grain stream control insulates against certified ingredient procurement bottlenecks. |
| Ammonia-Based Cooling Infrastructure | EU F-Gas Regulation compliance creates first-mover positioning in Northern European production. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA labeling guidance documents, USDA organic certification databases, and EU F-Gas regulatory filings. Interviews conducted with snack category buyers at major retailers, R&D directors at grain-based processors, procurement leads at corporate wellness programs, and equipment suppliers for air-puffing extrusion technology. Secondary validation drew from Nielsen retail audit data, customs records on cassava starch trade flows, and SEC filings of diversified food conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across ingredient type and distribution channel dimensions.
Segmentation dimensions modeled include product format, ingredient source, distribution channel, and customer archetype across the analysis window. CAGRs derived from trend extrapolation of air-puffing technology adoption curves, corporate wellness procurement expansion rates, and subscription retail penetration patterns. Industry-specific inputs encompassed enzymatic texturizer cost trajectories, non-GMO certification timeline constraints, and refrigeration infrastructure capital allocation decisions under EU regulatory pressure.
Forecasts assume regulatory continuity in FDA trans fat disclosure enforcement and EU F-Gas implementation timelines; material policy acceleration or delay would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Roasted Snacks Market
Snacks
Europe Nuts and Cereal Snacks Bar Market
Snacks
North America Snack Pellets Market
Snacks
Thailand Snack Bar Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
United Kingdom Snack Bar Market
Snacks
Granola Market
Snacks
Europe Snacks Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
Organic Snack Food Market
Snacks
China Snack Bar Market
Snacks
Seafood Snacks Market
Snacks
India Snack Bar Market
Snacks
Organic Chips Market
Snacks
Asia-Pacific Snack Bar Market
Snacks
North America Frozen Snacks Market