
 Automatic Deboner Market | 2026-2036
Automatic Deboner Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Deboner Market Insights
EU Green Deal sustainability targets for food processing supply chains are shifting procurement criteria for automated meat processing equipment across European export markets. BAADER leverages its integrated system architecture to sustain long-term contracts with Nordic processors. Marel anchors its position through advanced vision-robotics integration for precision cutting operations. Mayekawa competes in Asian markets with compact hydraulic systems designed for high-throughput poultry facilities.
An automatic deboner is a mechanized food processing machine engineered to separate meat from bone using cutting blades, robotic arms, or pressurized force systems operating at throughputs exceeding 200 birds per hour. The equipment serves industrial processors by maximizing yield recovery while minimizing manual labor exposure to repetitive stress injuries and contamination risks. Mechanical technology still occupies the largest installed base due to lower capital requirements and simpler maintenance protocols. Electronic systems represent the fastest-expanding category as machine vision and adaptive algorithms improve cutting accuracy for irregular bone structures. Food Processing Plants dominate end-user demand, though Catering Services are emerging as a secondary growth channel for mid-scale automated units.
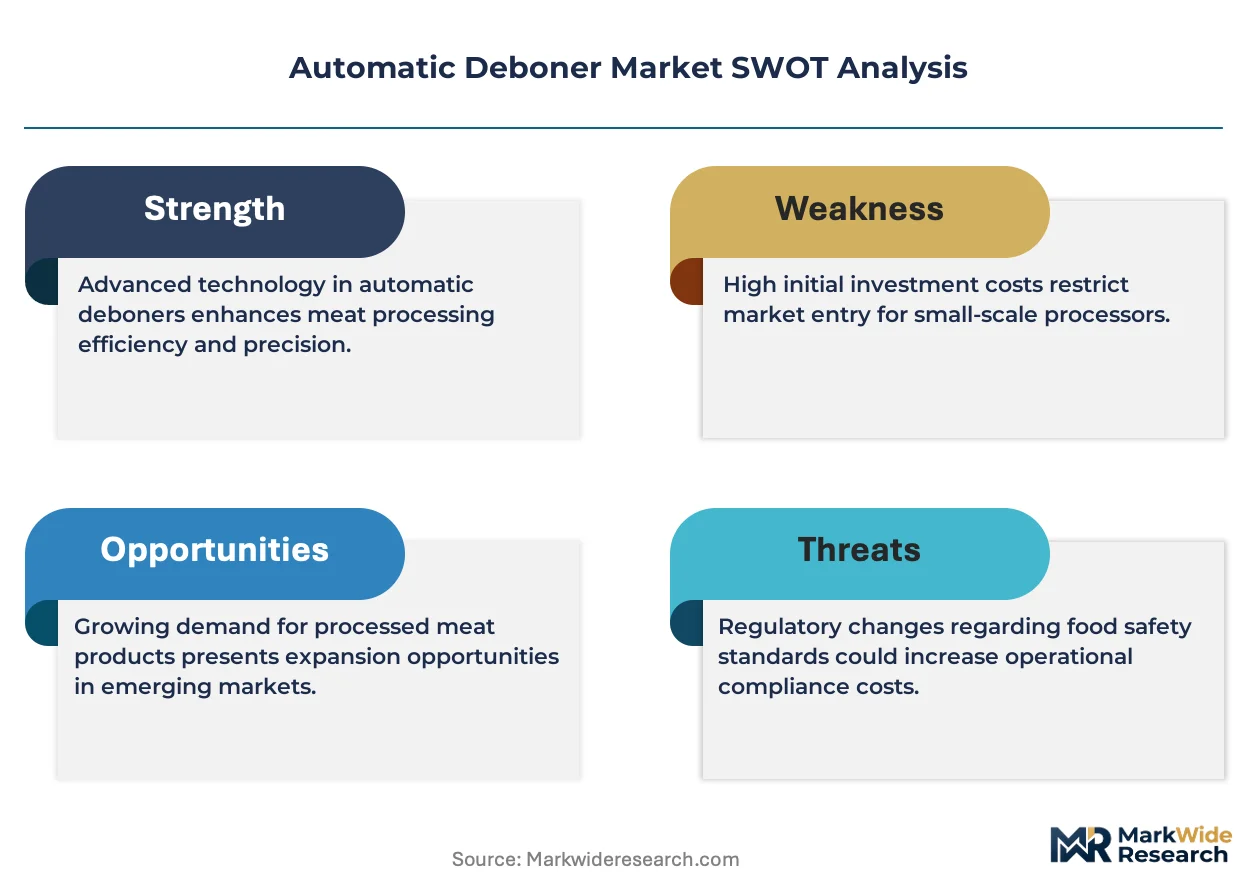
EU hygiene standards under EFSA and CE marking requirements shape equipment design specifications for any system entering European food processing facilities. USDA inspection protocols and OSHA workplace safety rules govern acceptable automation configurations in United States poultry and red meat plants. FDA Hazard Analysis and Critical Control Points frameworks further dictate sanitary design standards for contact surfaces and clean-in-place systems. Stakeholders must weigh capital intensity against labor arbitrage value as regulatory compliance costs and workforce availability diverge across major protein processing geographies.
Market Dynamics
Electronic vision-guided deboning systems are compressing the technology lifecycle in poultry processing as Southeast Asian exporters retool facilities to meet EU Green Deal compliance timelines and sanitary standards.
Growth Catalysts
- EU Green Deal supply chain mandates:Southeast Asian food processing plants are automating deboning lines to secure European export certifications and avoid carbon border adjustment penalties.
- Machine vision integration:Adaptive cutting algorithms improve yield recovery from irregular poultry bone structures, reducing manual trimming requirements in high-throughput facilities.
- Thailand and Vietnam:Government-backed food processing modernization programs accelerate capital deployment into electronic deboning systems for export-oriented poultry clusters.
Market Restraints
- Stainless steel and servo motor cost volatility:Input price swings for precision components compress equipment margins and extend payback periods for mid-scale processors.
- Technical limitation in red meat applications:Current electronic systems struggle with variable bone density in beef and pork carcasses, constraining addressable market expansion beyond poultry.
- CE marking friction:Extended conformity assessment timelines for novel vision-robotics configurations delay market entry for European-bound equipment.
Strategic Opportunities
- Catering services channel:Mid-scale automated units are penetrating institutional foodservice operations seeking labor arbitrage without full-scale plant investments.
- EU AI Act alignment:Early certification of autonomous cutting systems for high-risk food contact applications creates first-mover positioning in regulated European markets.
- Hydraulic-electronic hybrid convergence:Compact systems combining hydraulic force with vision guidance address throughput gaps in emerging market processing facilities.
Industry Challenges
- Mechatronics technician scarcity:Food processing regions lack sufficient trained personnel to maintain integrated vision-robotics deboning lines, extending downtime incidents.
- Legacy mechanical line integration:Retrofitting electronic cutting heads into existing plant layouts requires custom engineering that fragments deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Deboner Market |
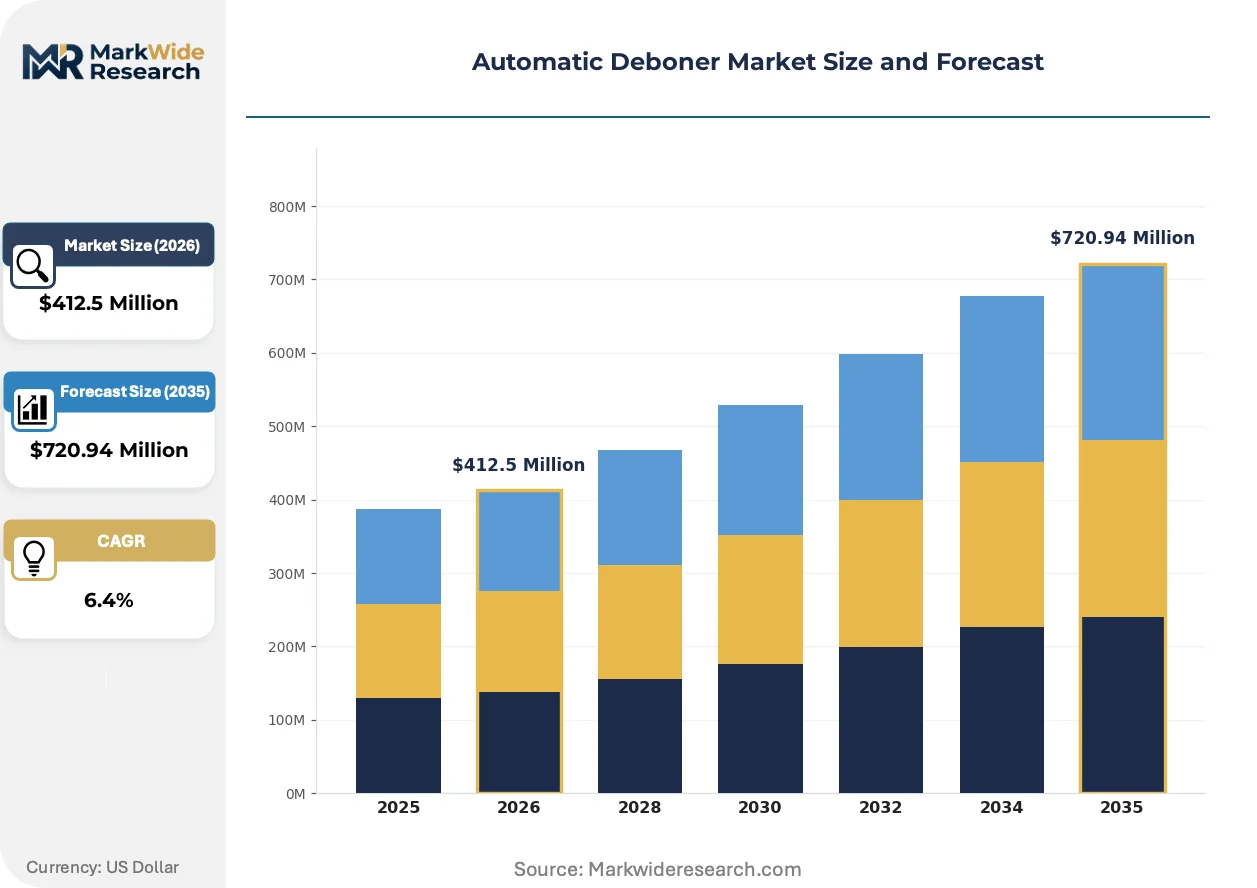
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Chicken, Chicken Thighs, Turkey Breast, Beef Cuts Technology: Mechanical, Hydraulic, Pneumatic, Electronic End User: Food Processing Plants, Restaurants, Catering Services, Supermarkets Installation: In-line, Standalone, Mobile, Integrated |
| Companies Covered | BAADER, Marel, Creminox, Mayekawa, GEA Group, JBT Corporation, Meyn, STEIN, Foodmate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Deboner Market Trends and Innovations
Automation architecture in meat processing is pivoting from mechanical reliability to adaptive precision, driven by export compliance pressures and labor cost divergence across protein processing geographies.
Hyperspectral imaging paired with robotic cutting arms is expanding into premium poultry processing operations seeking zero-defect deboning for retail-ready portions. Thai and Vietnamese exporters are deploying these systems at accelerated rates to satisfy EU retailer audit protocols. The technology is expanding into mid-tier processor segments previously served by mechanical lines, compressing the viable market for conventional equipment.
REACH chemical safety frameworks and F-Gas regulations are tightening material specifications for refrigerants and lubricants used in deboning system hydraulics. Equipment manufacturers are reformulating hydraulic fluids and cooling systems to eliminate restricted substances from food contact zones. European OEMs are responding fastest, redesigning compact poultry lines to preempt compliance-driven procurement exclusions.
Buyers are consolidating vendor relationships around integrated system providers capable of delivering cutting hardware, vision software, and regulatory documentation as unified packages. Fragmented mechanical equipment procurement is giving way to single-source contracts spanning installation through after-sales support. This pattern is most visible in Southeast Asian export plants where EU audit readiness requires documented traceability across entire processing lines.
Automatic Deboner Market Segmentation
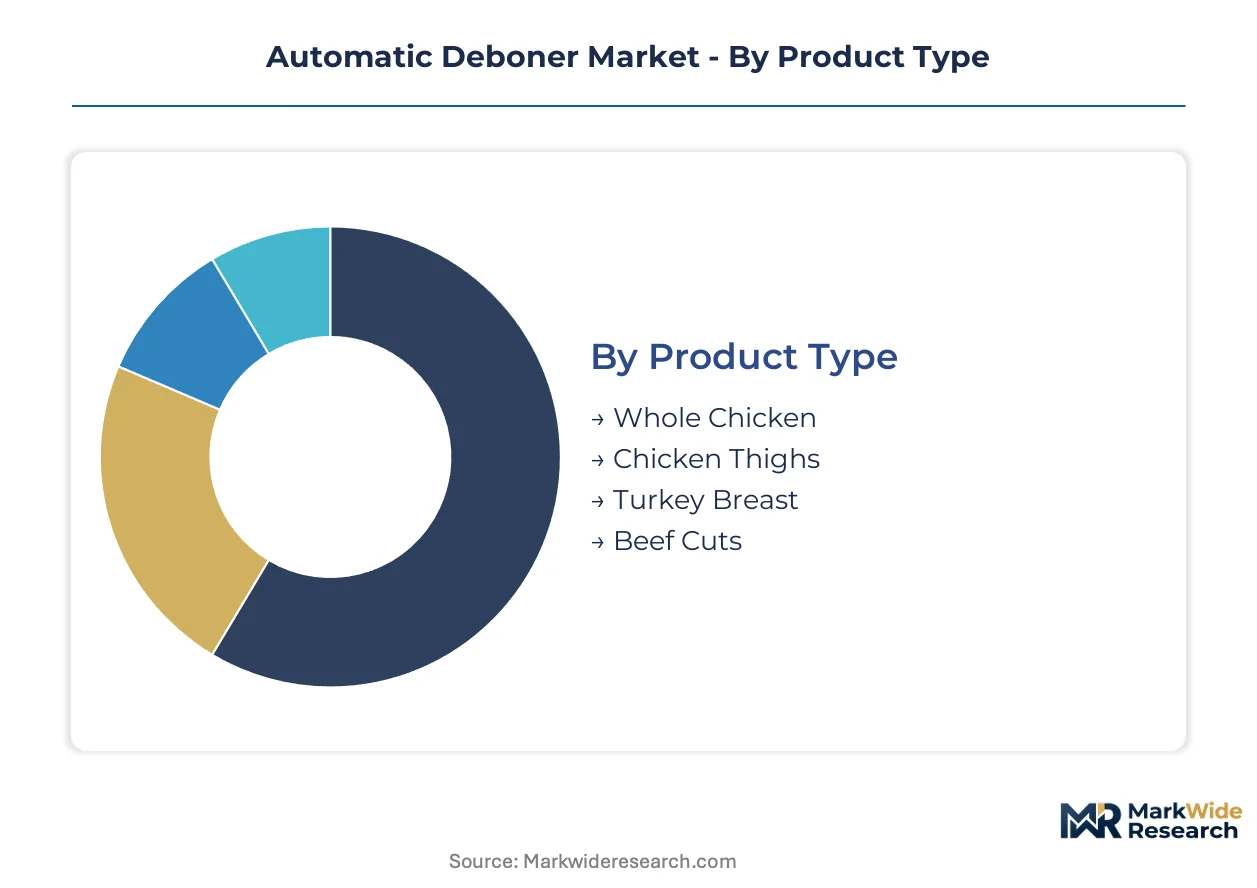
Equipment procurement patterns in protein processing diverge sharply across product categories, automation technologies, and facility scales. Understanding these fault lines reveals where capital deployment concentrates and where vendor margins compress.
Product Type:
Supply concentration in poultry deboning equipment manufacturing tilts procurement leverage toward processors handling standardized carcass geometries.
- Whole Chicken:Systems process intact birds through sequential cutting stations, maximizing yield recovery from breast and thigh portions simultaneously. Demand clusters in Thai and Vietnamese export plants seeking EU Green Deal compliance certification for retail-ready poultry exports.
- Chicken Thighs:Dedicated thigh deboners employ specialized blade geometries to navigate the hip joint and femur structure with minimal meat loss. Southeast Asian processors favor these units for their higher margin recovery on dark meat portions bound for European foodservice channels.
- Turkey Breast:Larger carcass dimensions require extended cutting envelopes and reinforced blade assemblies. North American processors deploy these systems for seasonal production surges.
- Beef Cuts:Variable bone density and connective tissue distribution constrain electronic system accuracy. Limited adoption outside Brazilian and Australian grass-fed processing facilities with consistent cattle genetics.
Today's leader: Whole Chicken. Tomorrow's challenger: Chicken Thighs.
Technology:
Cost tier stratification in automation hardware separates capital-intensive vision systems from maintenance-friendly mechanical alternatives.
- Mechanical:Cam-driven blade arrays and fixed cutting paths deliver consistent throughput at lower capital intensity. Established installed base across mid-scale Brazilian and Mexican poultry plants prioritizing uptime reliability over yield optimization.
- Electronic:Machine vision and adaptive algorithms adjust cutting trajectories to individual carcass variations. Thai and Vietnamese exporters accelerate deployment to satisfy EU retailer audit protocols for zero-defect portioning.
- Hydraulic:Pressurized force systems excel in high-throughput environments with uniform product streams. Mayekawa's compact configurations dominate Asian market share.
- Pneumatic:Compressed air actuation offers rapid cycling for lighter cutting operations. Limited penetration outside specialty seafood processing applications.
Mechanical systems anchor current installed capacity. Electronic configurations are climbing the fastest.
End User:
Application scale determines automation architecture, from continuous in-line systems to batch-oriented modular units.
- Food Processing Plants:High-volume continuous lines integrate deboning with upstream slaughter and downstream packaging operations. EU-bound export facilities in Thailand and Vietnam concentrate demand for electronic vision-guided systems.
- Catering Services:Mid-scale automated units penetrate institutional foodservice seeking labor arbitrage without full-scale plant investments. Government modernization programs in Southeast Asia subsidize procurement.
- Restaurants:Limited adoption due to throughput mismatch and floor space constraints. Premium steakhouse chains in Dubai and Singapore test compact units for signature cuts.
- Supermarkets:In-store processing requirements drive demand for compact, sanitary designs. European retail chains pilot integrated systems for private-label fresh poultry.
Food Processing Plants command capital deployment. Catering Services represent the steepest expansion trajectory.
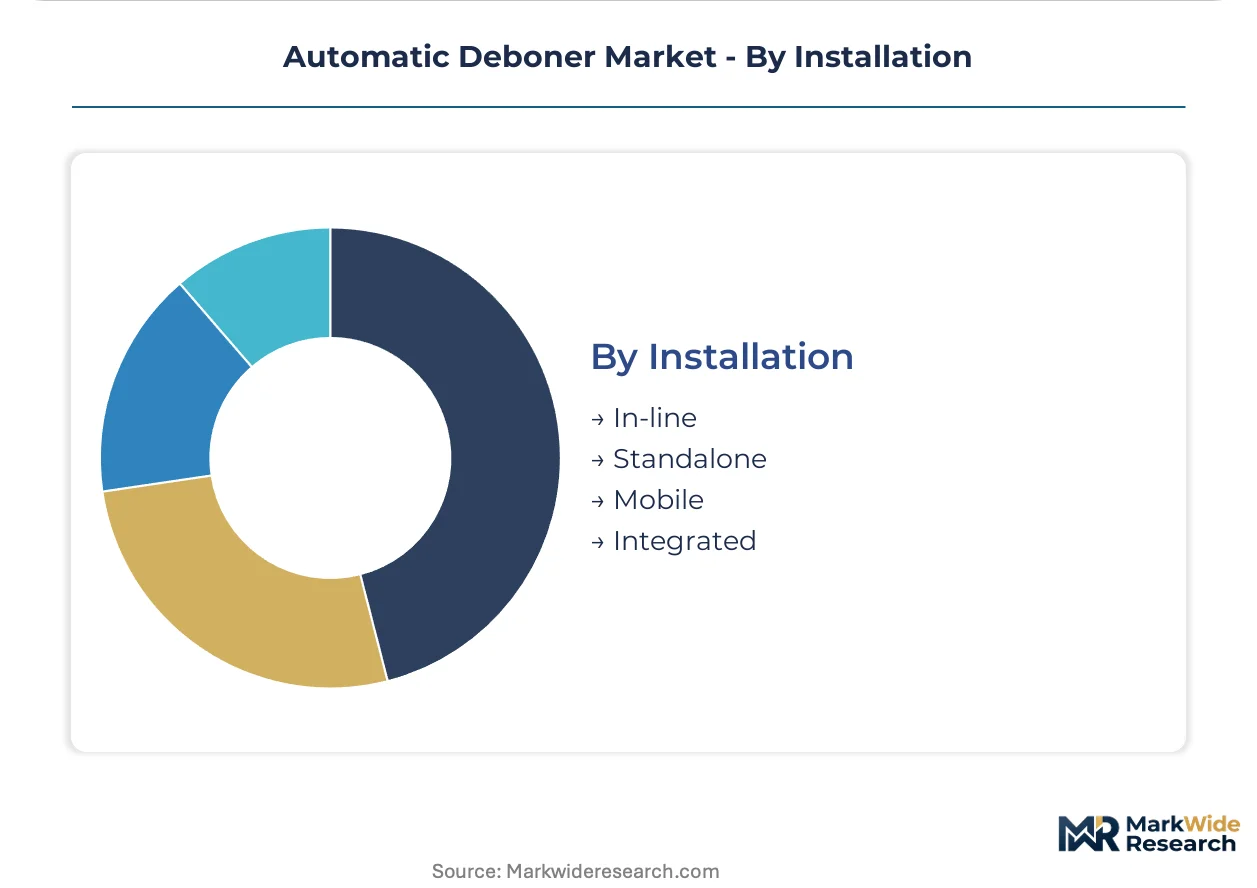
Installation:
Volume concentration in greenfield export facilities favors integrated architectures over retrofit-compatible alternatives.
- In-line:Continuous flow integration with shackling and evisceration lines maximizes throughput. New Vietnamese poultry export plants specify these configurations for EU audit readiness.
- Integrated:Unified control systems coordinate cutting, weighing, and packaging as single operational units. Preferred by Southeast Asian processors consolidating vendor relationships.
- Standalone:Self-contained units enable phased automation in legacy facilities. Brazilian processors deploy these for incremental capacity expansion.
- Mobile:Reconfigurable bases accommodate seasonal production shifts. Limited adoption outside Australian contract processing operations.
In-line configurations dominate greenfield investment. Integrated systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled mechatronics technicians concentrate in German and Nordic industrial corridors, anchoring precision equipment servicing networks for automated protein processing systems across European export markets.
Germany
Precision engineering clusters in Bavaria and Baden-Württemberg manufacture high-accuracy servo motors and vision systems for poultry deboning equipment. EFSA hygiene standards and CE marking requirements under EU Green Deal frameworks dictate sanitary design specifications for all systems entering German food processing facilities. Equipment integrators in Stuttgart coordinate pan-European distribution for electronic vision-guided deboning lines.
United States
USDA-inspected poultry plants in Georgia and Arkansas deploy automated deboning systems to maintain throughput amid labor availability constraints. OSHA workplace safety rules and FDA HACCP frameworks govern acceptable automation configurations and sanitary design standards for contact surfaces. Equipment suppliers in Chicago and Dallas-Fort Worth service seasonal production surges across the Southeast poultry belt.
Thailand
Government-backed food processing modernization programs accelerate capital deployment into electronic deboning systems for export-oriented poultry clusters in the Central Plains. EU Green Deal compliance requirements drive facility retooling to secure European retail certifications and avoid carbon border adjustment penalties. Bangkok-based equipment integrators coordinate vision-robotics installations for processors supplying EU supermarket chains.
Vietnam
Rising labor costs in the Mekong Delta and Red River Delta push processors toward automated thigh and breast deboning lines for European export contracts. National food safety modernization initiatives align facility upgrades with EFSA-equivalent standards for EU market access. Industrial zones in Long An and Binh Duong provinces concentrate greenfield investments in integrated in-line deboning configurations.
Brazil
Grass-fed beef processing facilities in São Paulo and Minas Gerais states test electronic deboning adaptations for consistent cattle genetics. ANVISA sanitary regulations and export certification requirements shape equipment procurement for protein processors serving Middle Eastern and Asian markets. Equipment distributors in Campinas support incremental automation through standalone unit deployment in legacy facilities.
Automatic Deboner Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the automatic deboner market, creating a tiered structure where integrated system architects hold pricing power over component suppliers. The vendor base separates into three strategic archetypes: Nordic full-line integrators commanding premium positioning through regulatory documentation bundling, Asian compact system specialists capturing throughput-sensitive emerging market accounts, and European precision component fabricators supplying vision and motion control subsystems. Competitive moves concentrate on vertical integration of software-hardware stacks and geographic expansion through localized assembly partnerships.
Within the integrated system tier, BAADER and Marel exemplify contrasting approaches to European export market positioning. Mayekawa occupies a distinct position among Asian-based fabricators serving high-throughput poultry facilities with compact hydraulic configurations. These three anchors illustrate how vendor origin and system architecture map to divergent procurement criteria across regulatory environments.
| Leading Market Players |
|---|
| BAADER |
| Marel |
| Creminox |
| Mayekawa |
| GEA Group |
| JBT Corporation |
| Meyn |
| STEIN |
| Foodmate |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators in Germany and Denmark anchor precision component supply for electronic deboning systems, translating concentrated engineering heritage into pricing discipline that resists commoditization pressure from Asian volume competitors.
Pricing Analysis
The bundled-vs-unbundled service split separates Nordic full-line integrators from component suppliers across the automatic deboner market. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking documentation depth and after-sales service bundling rather than hardware differentiation alone. Price differentiation rests on certification grade and geographic delivery cost, with EU-bound systems commanding substantial premiums over identical hardware shipped to domestic Southeast Asian buyers. Cost compression in standard-tier mechanical systems is intensifying because Brazilian and Mexican processors prioritize uptime reliability over yield optimization. Mid-scale catering services buyers exhibit highest price sensitivity, while EU export-oriented food processing plants demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Dual-sourcing requirements from EU-bound processors mandate multi-supplier qualification for servo motors and machine vision subsystems, fragmenting procurement leverage across German, Japanese, and South Korean component fabricators. Geographic supply concentration centers on Germany for precision motion control, Japan for compact hydraulic assemblies, and South Korea for industrial-grade optical sensors. Raw material dependencies draw from stainless steel for sanitary contact surfaces, rare-earth magnets for servo motors, and specialized optical glass for vision systems. Single-source vulnerability in precision servo motor supply chains exposes equipment OEMs to extended lead time volatility. Distribution runs through Bangkok-based integrators for Southeast Asian export markets and Stuttgart-coordinated networks for European food processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic deboner market functions as a geographic-arbitrage play where labor cost divergence between Southeast Asian processing clusters and European compliance requirements justifies premium pricing for certified electronic systems over mechanical alternatives.
For Market Incumbents: Anchor defensive positioning through backward integration into machine vision software stacks and captive supply of precision servo assemblies. Consolidate channel control by acquiring Bangkok-based equipment integrators serving EU-bound Thai and Vietnamese export processors. Threat substitution from hydraulic-electronic hybrid configurations by Mayekawa demands certification investment in EU AI Act alignment for autonomous cutting systems. For New Entrants and Emerging Players: Equipment leasing specialists offer the most penetrable channel for mid-scale catering services buyers seeking labor arbitrage without capital intensity. Target institutional foodservice operations in Southeast Asian government modernization programs as the least contested white-space segment. Pursue OEM partnerships with European retail chains piloting in-store poultry processing for private-label fresh offerings. For Investors and Strategic Acquirers: Protein processing conglomerates with vertical integration mandates are the most active acquirer in this space, seeking captive equipment supply for export-oriented facilities. Long-term viability over the projection horizon hinges on regulatory documentation capabilities rather than hardware differentiation alone. Signal to monitor: CE marking assessment timeline compression for novel vision-robotics configurations as inflection indicator for first-mover positioning.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Pathway | Early alignment with EFSA high-risk food contact protocols secures first-mover positioning in regulated European markets. |
| Backward Integration into Vision Software | In-house development of adaptive cutting algorithms reduces dependency on Japanese optical subsystem suppliers. |
| Joint Venture with Bangkok Integrators | Localized assembly partnerships compress delivery timelines for Thai and Vietnamese government modernization programs. |
| Hydraulic-Electronic Hybrid Development | Compact systems combining Mayekawa-style hydraulic force with machine guidance address emerging market throughput gaps. |
| Long-Term Service Contract Expansion | After-sales documentation bundling for EU Green Deal audit readiness locks in recurring revenue from export processors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at Thai and Vietnamese poultry export facilities, procurement leads at Nordic full-line integrators, aftermarket service heads at German component fabricators, and regulatory affairs specialists navigating CE marking pathways. Secondary validation drew from EFSA hygiene standard documentation, EU Green Deal supply chain compliance frameworks, customs records for poultry processing equipment trade flows, and SEC filings from listed food technology conglomerates. Bottom-up equipment shipment tallies and top-down protein processing capacity expansion estimates were triangulated to anchor market sizing.
Segment-weighting approaches distributed value across technology tiers, product categories from whole chicken to beef cuts, end-user scales from food processing plants to catering services, and installation configurations from in-line to standalone units. CAGRs were derived from fitted growth curves calibrated against documented capacity expansion in Mekong Delta and Red River Delta industrial zones, EU-bound export volume commitments, and government subsidy program disbursement trajectories. Stainless steel input cost volatility and servo motor supply lead times were modeled as scenario variables.
Revisions become necessary when EU carbon border adjustment mechanisms expand coverage scope, ANVISA sanitary regulations tighten equipment documentation requirements, or mechatronics technician scarcity extends downtime incidents beyond modeled thresholds. Deviation in CE marking assessment timelines for novel vision-robotics configurations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Fish Feed Pellet Making Machine Market
Food Processing Equipment
Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Fish Deboning Machine Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
Brewery Heat Exchanger Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Flakes Making Machine Market
Food Processing Equipment
Pan Feeder Market
Food Processing Equipment
Deaeration Machine Market
Food Processing Equipment
Refrigerated Vending Machines Market
Food Processing Equipment
Food Irradiation Equipment Market
Food Processing Equipment
Ice Cream Machine Market