
 North America Cold Storage Market | 2026-2036
North America Cold Storage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cold Storage Market Intelligence
The unbundling of full-pallet shipments into smaller, more frequent case-level orders for direct-to-consumer grocery fulfillment is consolidating demand for highly automated, flexible warehouse space. Lineage Logistics leverages its extensive network to manage these complex fulfillment requirements across North America. Americold Realty Trust positions its real estate portfolio to capture demand in primary US distribution hubs. VersaCold Logistics Services specializes in integrated solutions for the Canadian food sector.
North America Cold Storage refers to the infrastructure for preserving temperature-sensitive goods, typically from chilled (0°C to 10°C) to frozen (-18°C and below). These facilities primarily utilize industrial mechanical vapor compression systems to maintain precise environmental conditions. While frozen food storage constitutes a mature, high-volume segment, biopharmaceutical storage applications offer significant margin potential. Logistics providers and food retailers represent the dominant end-user categories driving facility investment.
Regulatory oversight from the US Food and Drug Administration (FDA) and the Department of Agriculture (USDA) dictates strict handling protocols for food products. In Canada, Health Canada enforces similar standards, shaping facility design for both food and pharmaceutical goods. Consequently, operators must decide between investing in new, automated greenfield sites or retrofitting existing infrastructure to meet evolving client demands.
Market Dynamics
The central dynamic shaping the North America cold storage market is the enforcement of stricter regulatory standards for food and pharmaceuticals. Mandates under the FDA's Food Safety Modernization Act (FSMA) are compelling investment in modern, traceable, and technologically advanced facilities over aging infrastructure.
Growth Catalysts
- Biopharmaceutical Expansion:Demand from the biopharmaceutical sector for specialized, temperature-controlled storage for vaccines, biologics, and clinical trial materials offers significant high-margin growth, requiring facilities compliant with stringent quality standards.
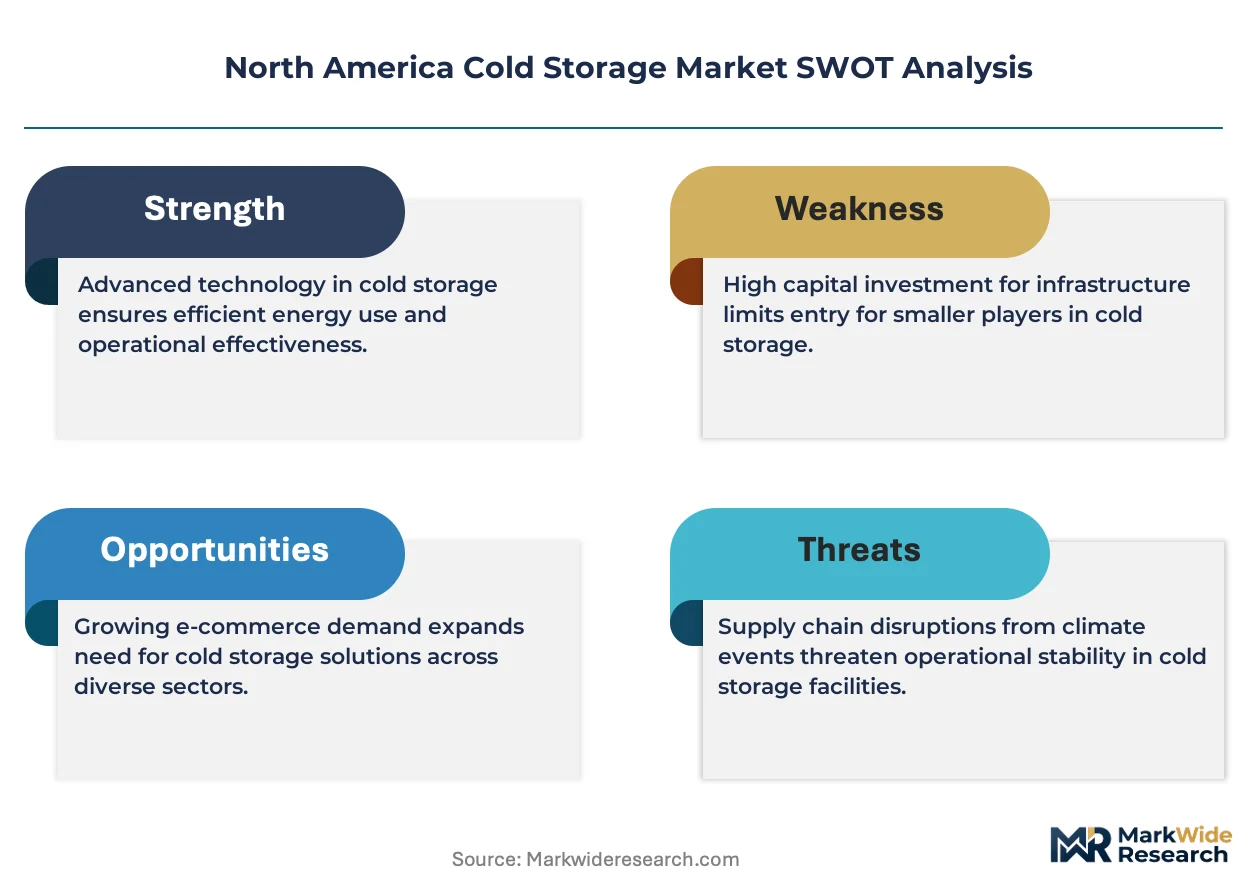
- Regulatory Mandates:The US FDA's Food Safety Modernization Act (FSMA) imposes strict requirements for temperature monitoring and traceability, driving operators to invest in new, compliant infrastructure and technology to avoid penalties.
- Direct-to-Consumer Fulfillment:The shift in grocery retail towards online ordering and direct home delivery consolidates demand for cold storage facilities, particularly automated micro-fulfillment centers located near urban population centers.
Market Restraints
- High Energy Costs:Industrial refrigeration systems are energy-intensive, exposing facility operators to volatile electricity and natural gas prices which can significantly compress operating margins if not managed through efficiency upgrades or hedging.
- Capital Intensity:The construction of new, automated greenfield facilities and the retrofitting of older warehouses represent a substantial capital expenditure, creating a high barrier to entry for smaller operators and slowing capacity expansion.
- Land Scarcity and Cost:A lack of available and affordable industrial-zoned land near key North American logistics hubs and major metropolitan areas constrains the development of new large-scale cold storage facilities where they are needed most.
Strategic Opportunities
- Automation Integration:Deploying Automated Storage and Retrieval Systems (AS/RS) and robotics presents a major opportunity to increase storage density, improve labor productivity, and efficiently manage complex, case-level picking for e-commerce fulfillment.
- Value-Added Services:Operators can move beyond basic storage by offering integrated services such as blast freezing, tempering, co-packing, labeling, and transportation management, capturing more of the value chain, especially for food and pharma clients.
- Secondary Market Expansion:Developing facilities in underserved secondary and tertiary markets across the US and Canada allows operators to capture new demand sources fueled by population shifts and the expansion of online grocery services beyond primary cities.
Industry Challenges
- Skilled Labor Shortage:A persistent shortage of qualified labor, including both warehouse workers and specialized technicians needed to maintain sophisticated refrigeration and automation systems, hampers operational efficiency and increases costs.
- Systems Integration Complexity:Integrating modern warehouse management systems (WMS) with a diverse array of client ERP systems and the operational technology within legacy facilities creates significant technical and implementation hurdles for operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cold Storage Market |
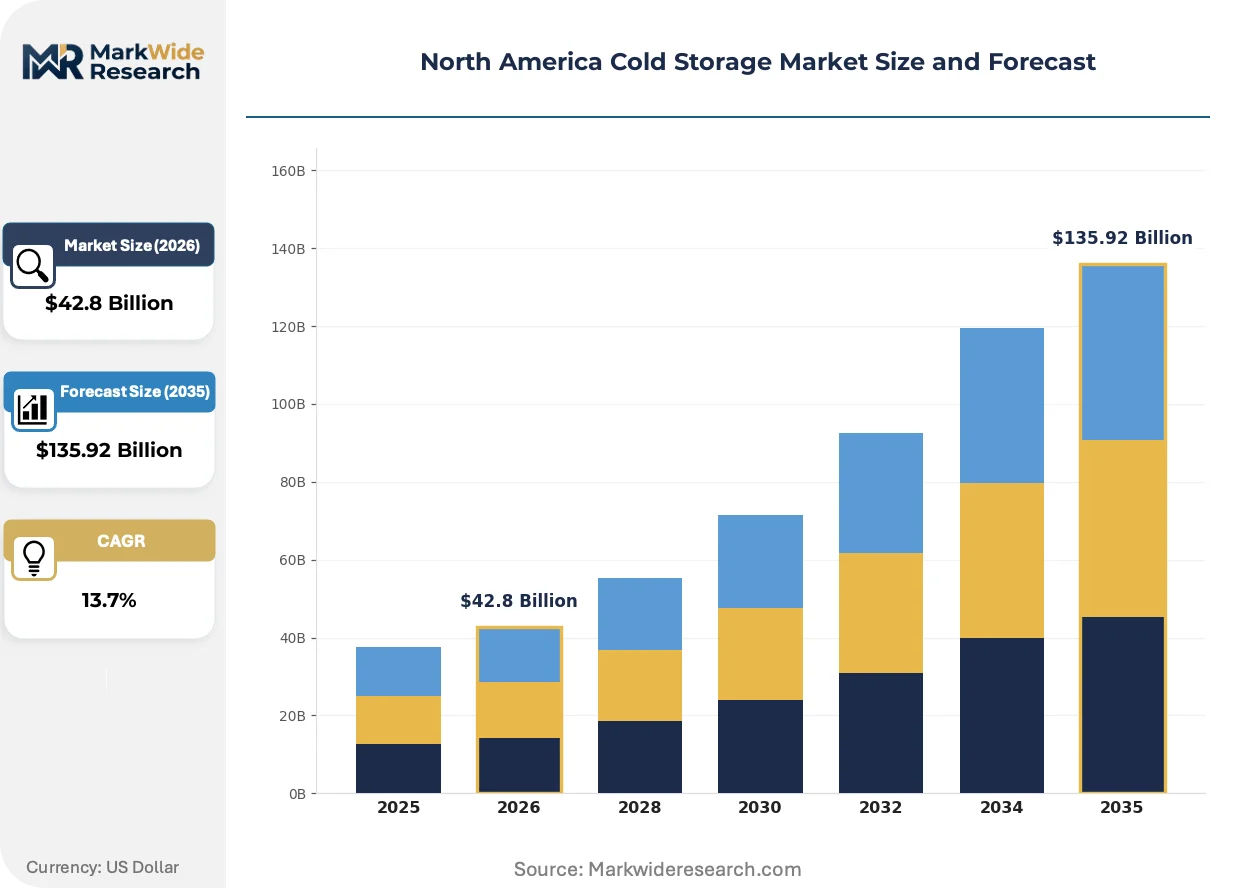
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $135.92 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Food Storage, Pharmaceutical Refrigeration, Perishable Goods Shelving, Ice Cream Freezers, Seafood Preservation, Floral Cooling Technology: Mechanical Vapor Compression, Cryogenic Cooling, Thermal Energy Storage, Solar Assisted Refrigeration, Magnetic Refrigeration, Absorption Systems Application: Food Processing, Biopharmaceutical Storage, Beverage Cooling, Agricultural Produce, Bakery Warehousing, Cold Chain Logistics End User: Logistics Providers, Food Retailers, Cold Storage Warehouses, Biotech Firms, Hospitality Chains, Meat Packing Firms |
| Companies Covered | Burris Logistics, Penske Logistics, Lineage Logistics, VersaCold Logistics Services, Conestoga Refrigerated Storage, Americold Realty Trust, Wabash National Corporation, NFI Industries, United States Cold Storage, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cold Storage Market Strategic Shifts & Innovations
The evolution from static, pallet-in/pallet-out storage to dynamic, high-velocity fulfillment is the defining theme. This transition is driven by technological advancements in automation and data management, which are necessary to meet new regulatory and consumer-driven service-level expectations.
Automated Storage and Retrieval Systems (AS/RS) provide high-density product storage and rapid, accurate order selection. Food retailers and third-party logistics providers are increasingly adopting this technology to manage the complexity of direct-to-consumer grocery orders. This technology is modularizing warehouse design, enabling flexible layouts that can be reconfigured to handle fluctuating demand for pallet, case, and item-level picking.
Regulatory pressure, particularly from the FDA's Food Safety Modernization Act (FSMA), now requires end-to-end temperature verification and detailed record-keeping. This rule compels operators to deploy Internet of Things (IoT) sensors and cloud-based data platforms for continuous monitoring and compliance reporting. The biopharmaceutical storage segment is most impacted, pushing investment toward facilities that meet both FSMA and cGMP standards.
A significant behavioral shift is the unbundling of full-pallet shipments into smaller, more frequent case-level orders for just-in-time inventory replenishment. This trend disrupts the traditional bulk storage model, creating demand for logistics partners with sophisticated sorting and cross-docking capabilities. This pattern is most visible in the dense distribution corridors of the US Midwest and along the coasts.
North America Cold Storage Market Segmentation
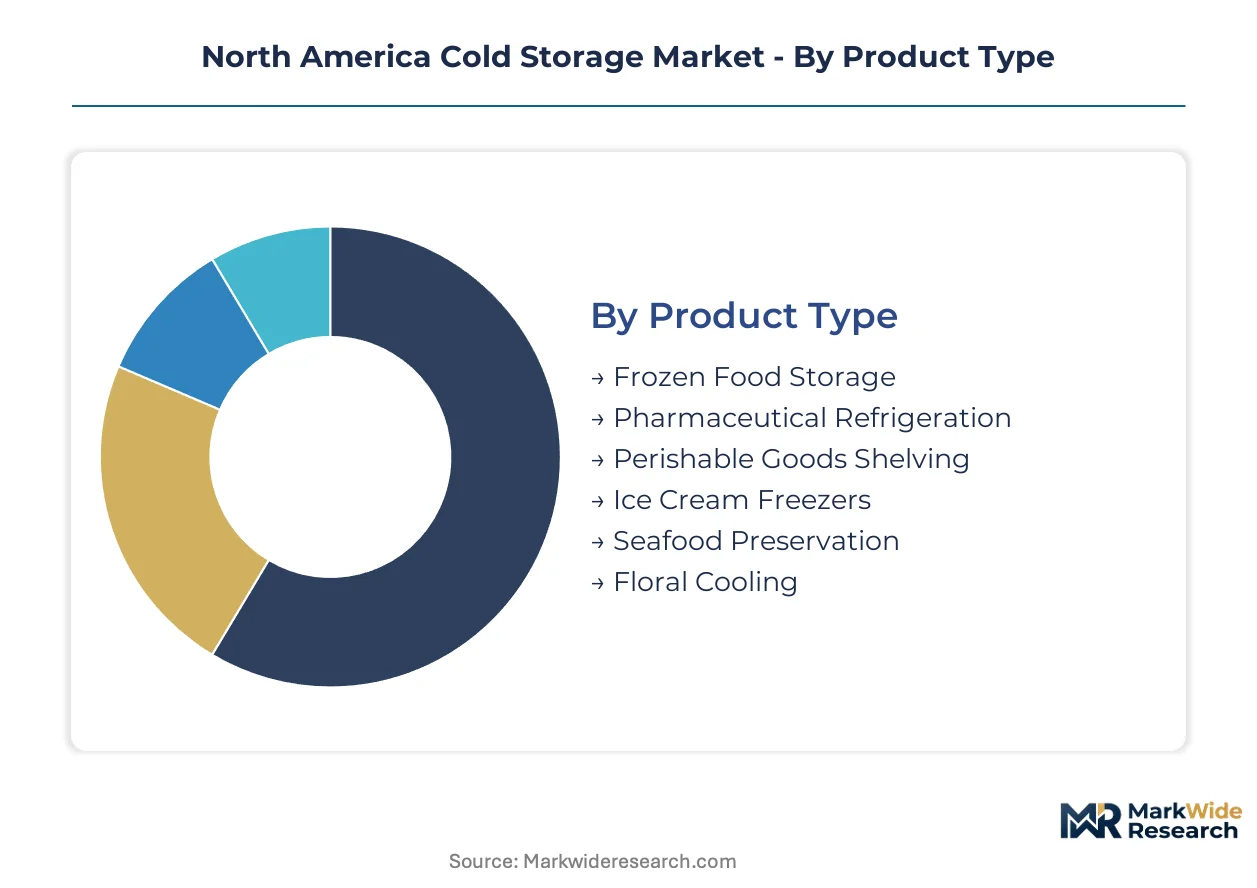
The North America cold storage market segments reflect diverse operational requirements and investment profiles. Understanding these distinctions helps operators target specific client needs, from high-volume food preservation to specialized biopharmaceutical handling. Each segment presents unique challenges and opportunities for infrastructure development and service provision across the United States and Canada.
Product Type:
The capital intensity of cold storage facilities varies significantly depending on the product types they are designed to accommodate.
- Pharmaceutical Refrigeration:These highly specialized facilities maintain precise temperature and humidity ranges, often requiring redundant systems and continuous monitoring for sensitive biologics and vaccines. Demand concentrates in key biopharmaceutical hubs across the US and Canada, driven by stringent FDA and Health Canada regulations.
- Frozen Food Storage:Large-scale warehouses designed for long-term preservation of bulk food items, typically operating at -18°C or below. This segment handles high volumes for food manufacturers and retailers across North America.
- Perishable Goods Shelving:Infrastructure optimized for fresh produce, dairy, and other chilled items, requiring consistent temperature control to extend shelf life. This segment supports grocery distribution networks in urban and suburban areas.
- Ice Cream Freezers:Specialized freezers maintaining ultra-low temperatures to prevent ice crystal formation and preserve product quality. These units are critical for retail and food service supply chains.
- Seafood Preservation:Facilities designed for fresh and frozen seafood, often requiring specific humidity levels and rapid freezing capabilities. Coastal regions and major distribution centers drive demand for this specialized storage.
- Floral Cooling:Controlled environments that maintain optimal temperature and humidity to extend the freshness and vase life of cut flowers. This niche segment serves florists and large-scale floral distributors.
Most installed capacity flows through Frozen Food Storage. Expansion is steepest in Pharmaceutical Refrigeration.
Technology:
Different cold storage technologies address varying application complexities and energy efficiency requirements in the North American market.
- Mechanical Vapor Compression:This ubiquitous technology utilizes refrigerants and compressors to achieve cooling across a broad temperature spectrum, forming the backbone of most large-scale cold storage facilities. Its reliability and established infrastructure make it critical for general cold chain logistics throughout the US and Canada.
- Cryogenic Cooling:Employing ultra-low temperatures, often using liquid nitrogen or carbon dioxide, this technology is essential for preserving highly sensitive biological materials and specialized pharmaceuticals. Demand for this precise, rapid cooling method concentrates in advanced research and biopharmaceutical manufacturing sites.
- Thermal Energy Storage:Systems that store cooling capacity during off-peak hours for use during peak demand, reducing energy costs and improving grid stability. This technology offers efficiency gains for large facilities in energy-conscious regions.
- Solar Assisted Refrigeration:Integrates solar power to supplement traditional refrigeration systems, reducing reliance on grid electricity and lowering operational expenses. This solution gains traction in regions with abundant sunlight and high energy costs.
- Magnetic Refrigeration:An emerging technology offering potentially higher energy efficiency and environmental benefits by using magnetic fields to produce cooling. Research and pilot projects are exploring its viability for future applications.
- Absorption Systems:These systems use a heat source, such as waste heat, to drive the refrigeration cycle, offering an alternative to mechanical compression. Industrial facilities with available waste heat streams can benefit from this technology.
The adoption of Mechanical Vapor Compression is critical for bulk capacity, while Cryogenic Cooling offers specialized solutions for high-value goods.
Application:
The margin potential varies across cold storage applications, with some segments offering higher returns due to specialized needs and regulatory burdens.
- Biopharmaceutical Storage:This application involves highly specialized, precise temperature and humidity control for vaccines, biologics, and clinical trial materials, often requiring cGMP compliance and continuous data logging. Its stringent requirements and high-value products command premium pricing and significant investment in compliant facilities across North America.
- Cold Chain Logistics:Comprehensive services encompassing storage, transportation, and distribution of temperature-sensitive goods, integrating multiple cold storage facilities and transport modes. This application supports the entire supply chain for food and pharmaceutical products, linking producers to end-users.
- Food Processing:Cold storage integral to manufacturing processes for prepared foods, meat, and dairy, ensuring product safety and quality before distribution. This application is foundational for the North American food industry.
- Beverage Cooling:Storage solutions for soft drinks, alcoholic beverages, and juices, maintaining optimal temperatures for quality and consumer enjoyment. This segment supports distribution networks for major beverage companies.
- Agricultural Produce:Facilities designed to store fruits, vegetables, and other fresh agricultural products, extending shelf life and managing seasonal harvests. Regional distribution centers for groceries rely heavily on this application.
- Bakery Warehousing:Cold storage for dough, finished baked goods, and ingredients, preventing spoilage and maintaining freshness. This application supports both industrial bakeries and retail food service.
Demand for Cold Chain Logistics dominates volume, but Biopharmaceutical Storage promises higher margins.
End User:
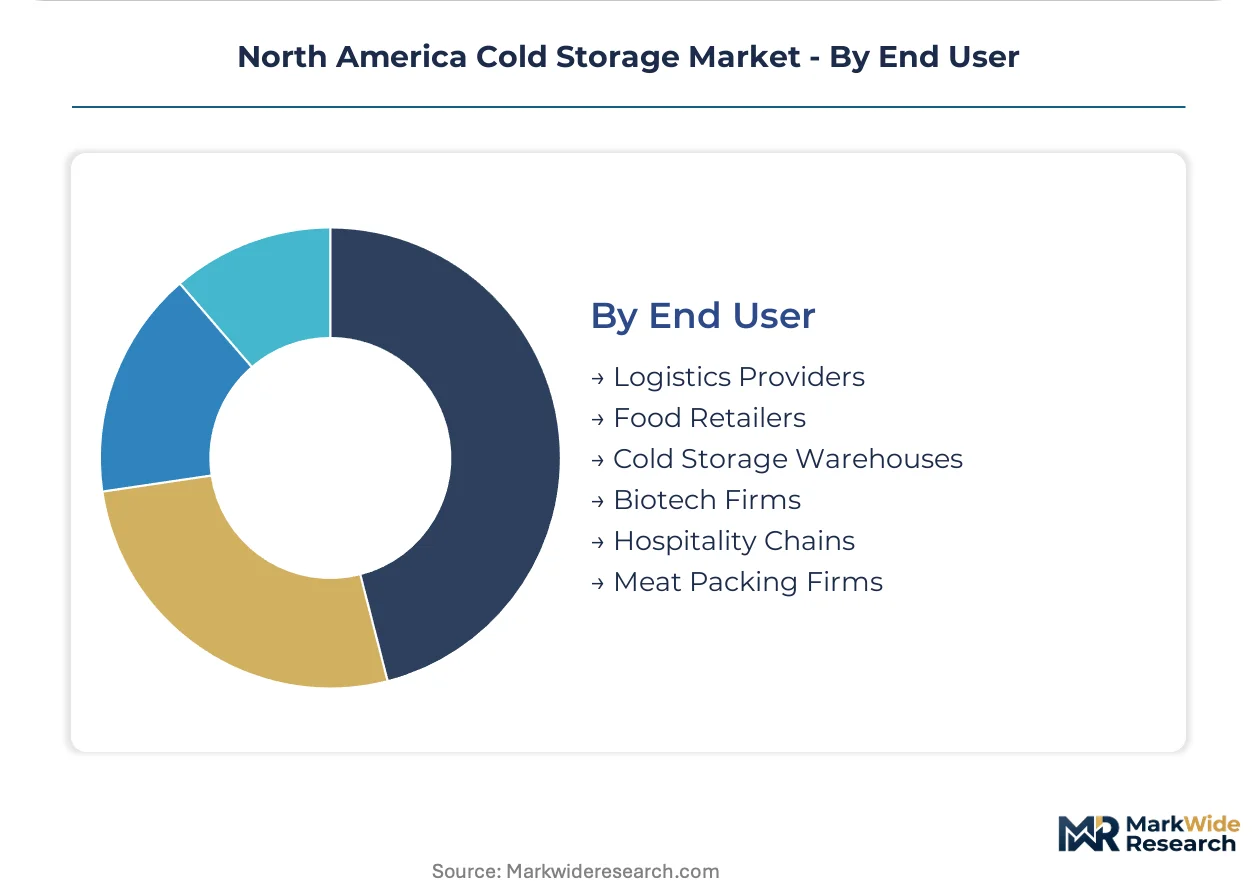
Different end-user categories concentrate demand for cold storage services based on their operational scale and specific logistical requirements.
- Logistics Providers:Third-party logistics (3PL) companies that manage cold storage, transportation, and distribution for multiple clients, offering scalable and integrated solutions. These firms consolidate demand for flexible and technologically advanced facilities across major North American corridors.
- Food Retailers:Grocery chains and food service distributors requiring extensive cold storage networks to manage inventory, fulfill online orders, and supply their retail outlets. Their demand focuses on facilities near urban centers and distribution hubs in the US and Canada.
- Cold Storage Warehouses:Dedicated facilities offering storage services on a contractual basis to various industries, often specializing in specific temperature ranges or product types. These independent operators provide critical infrastructure for the broader cold chain.
- Biotech Firms:Companies involved in biotechnology research, development, and manufacturing that require specialized cold storage for reagents, samples, and finished pharmaceutical products. These firms drive demand for cGMP-compliant and ultra-low temperature storage.
- Hospitality Chains:Hotels, restaurants, and catering services that utilize cold storage for perishable food ingredients, prepared meals, and beverages. Their demand is localized to urban and tourist-heavy areas.
- Meat Packing Firms:Industrial facilities requiring extensive cold storage for raw meat, processed meat products, and by-products, adhering to strict USDA and Health Canada regulations. This sector represents a significant, high-volume user of frozen storage.
Large-scale investment originates from Logistics Providers, with niche demand from Biotech Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American cold storage industry first scaled significantly in the United States, driven by large-scale food processing and distribution needs. This foundational demand established robust infrastructure for temperature-sensitive goods across the continent. Today, the region continues to expand its capacity to meet evolving consumer preferences and stricter regulatory requirements.
United States
Demand for cold storage in the United States stems from biopharmaceutical expansion and the growth of direct-to-consumer grocery fulfillment. The FDA's Food Safety Modernization Act (FSMA) mandates strict temperature control and traceability, driving facility upgrades. Major distribution hubs, particularly in California and Texas, see significant investment in advanced cold storage facilities to support these trends.
Canada
The Canadian cold storage market is driven by the specialized needs of its national food sector and increasing pharmaceutical storage requirements. Health Canada enforces stringent standards for both food and pharmaceutical goods, influencing facility design. Integrated solutions are developing in key Canadian logistics corridors, with significant activity around Toronto and Montreal.
Mexico
Mexico's cold storage demand is accelerating due to growing cross-border trade with the United States and rising domestic food consumption. Mexican health and safety regulations, often aligned with international standards, influence facility development and operations. Facilities near the US border, such as those in Tijuana and Monterrey, are expanding capacity to support export-oriented industries.
US Midwest
The US Midwest represents a critical cold storage region due to centralized food production and its role as a key logistics corridor for national distribution. USDA regulations for meat and poultry handling significantly influence cold storage design and operations in this area. Investment in highly automated greenfield sites is concentrating in cities like Chicago and Kansas City, bolstering regional capacity.
US Coasts
Coastal regions in the United States experience high cold storage demand from dense population centers, port-centric import/export activities, and local food distribution networks. State-level environmental regulations, alongside federal FDA mandates, impact facility development and operational compliance. Urban micro-fulfillment centers are emerging in metropolitan areas like Los Angeles and New York to efficiently service online grocery demand.
North America Cold Storage Market Key Industry Players
Premium-margin players sit above commodity-margin players across service specialization and technological sophistication. The North American cold storage market exhibits a tiered structure, with a few large, integrated logistics providers dominating volume. Strategic archetypes include large-scale third-party logistics firms offering comprehensive cold chain solutions, specialized biopharmaceutical storage operators, and regional warehousing firms. Dominant competitive moves involve capacity expansion through new facility development and strategic partnerships for network optimization.
Within the large-scale logistics provider archetype, Lineage Logistics and Americold Realty Trust exemplify firms with extensive North American networks. These companies leverage their vast infrastructure to manage complex fulfillment requirements, including direct-to-consumer grocery orders. VersaCold Logistics Services, a Canadian-based firm, occupies a position specializing in integrated solutions for the Canadian food sector, reflecting a regional focus within the broader market.
| Leading Market Players |
|---|
| Burris Logistics |
| Penske Logistics |
| Lineage Logistics |
| VersaCold Logistics Services |
| Conestoga Refrigerated Storage |
| Americold Realty Trust |
| Wabash National Corporation |
| NFI Industries |
| United States Cold Storage |
| Others |
Cost & Logistics Intelligence
Automated Storage and Retrieval Systems (AS/RS) integration reshapes cold storage cost economics by reducing labor dependency and increasing density. This technology simultaneously consolidates specialized facility demand around key logistics hubs in North America.
Pricing Analysis
Contract-based long-term agreements dominate cold storage pricing, reflecting the substantial capital investment required for specialized facilities. Price differentiation stems from precision temperature control for biopharmaceuticals and the volume scale of frozen food storage. High energy costs and significant capital intensity exert ongoing pricing pressure on operators. Food retailers exhibit higher price sensitivity compared to biotech firms, which prioritize regulatory compliance and specialized service levels.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke model characterize the North American cold storage supply chain. Supply capacity concentrates heavily in the US Midwest, California, Texas, and major Canadian corridors like Toronto and Montreal. The sector relies on refrigerants, specialized insulation materials, and advanced automation hardware. Land scarcity and high costs near key logistics hubs present a significant structural risk to expansion, impacting facility development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America cold storage market functions as a stable compounder, driven by continuous regulatory mandates under the FDA's Food Safety Modernization Act. This consistent oversight compels ongoing investment in advanced infrastructure and technology.
For Market Incumbents: Lock in market share through strategic capacity expansion in primary US distribution hubs and Canadian logistics corridors. Integrate advanced automation, like AS/RS, to counter skilled labor shortages and high energy costs. Further invest in cGMP certification for biopharmaceutical storage to differentiate from commodity players. Offer comprehensive value-added services to deepen client relationships and mitigate margin pressure. For New Entrants and Emerging Players: Enter via underserved secondary and tertiary markets across the US and Canada, where land costs are lower. Target niche product types, such as floral cooling or specialized seafood preservation, offering tailored solutions. The most penetrable segment involves urban micro-fulfillment centers, supporting direct-to-consumer grocery delivery. Focus on localized, flexible solutions that address specific client demands for smaller-scale operations. For Investors and Strategic Acquirers: Roll-up economics work for logistics providers because fragmented regional operators offer opportunities for network optimization and scale. The market demonstrates long-term viability, driven by increasing regulatory burdens and e-commerce expansion. Target mid-sized regional cold storage operators with specialized biopharmaceutical capabilities or strategic locations near distribution hubs. A key signal to watch is the sustained growth in demand for cGMP-compliant biopharmaceutical cold chain services.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Midwest | Bolsters national distribution networks for food products from the US Midwest. |
| Automation Integration | Increases storage density and labor productivity for complex e-commerce fulfillment. |
| Biopharmaceutical Certification | Captures high-margin demand from sensitive biologics requiring cGMP compliance. |
| Value-Added Services Development | Expands revenue streams beyond basic storage for food and pharmaceutical clients. |
| Secondary Market Entry | Accesses new demand sources in underserved regions across the United States. |
Research Approach
Direct dialogue with cold storage facility managers, logistics executives, and biopharmaceutical supply chain leads informed the primary research. This qualitative input was triangulated with extensive secondary validation from sources including FDA regulatory documents, USDA reports, and company financial filings. A bottom-up approach to market sizing was cross-referenced with top-down industry estimates. This comprehensive data gathering ensures robust market insights.
A bottom-up approach to market sizing underpinned the forecast framework, validated against top-down industry projections across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional demand patterns. Compound annual growth rates were derived from historical data and projected growth drivers, such as e-commerce penetration. Biopharmaceutical R&D pipelines served as a key industry-specific forecast input.
The model holds under current North American regulatory frameworks and economic stability; deviation in energy price volatility or land use policy changes would shift projections. Forecasts reflect assumptions regarding technological adoption and consumer behavior. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Sword Feeders Market
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Bread Processing Equipment Market
Food Processing Equipment
Commercial Tunnel Oven Market
Food Processing Equipment
India Household Flour Milling Machines Market
Food Processing Equipment
Commercial Panini Machine Market
Food Processing Equipment
Plastic Processing Machinery Market
Food Processing Equipment
Flake Ice Machines Market
Food Processing Equipment
Automatic Deboner Market
Food Processing Equipment
Shawarma Grill Machine Market
Food Processing Equipment
Commercial Wood Fired Pizza Oven Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Food Waste Composting Machine Market
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Micro Winery Equipment Market