
 Gas Convection Oven Market | 2026-2036
Gas Convection Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Convection Oven Market Foresight
The capital-intensity divergence between full-line manufacturers and specialized oven builders is redrawing competitive boundaries in gas convection equipment. Vulcan leverages captive metal fabrication and burner assembly operations to control input costs across its floor oven and conveyor oven ranges. Hobart sustains institutional kitchen dominance through extensive service infrastructure that locks in multi-year maintenance contracts with school districts and hospital networks. Bakers Pride specializes in compact countertop and wall mount configurations for independent pizzerias and food truck operators who prioritize footprint efficiency over throughput volume.
A gas convection oven is a commercial cooking appliance that circulates heated air via a fan-driven system around a gas-fired heat exchanger, typically achieving chamber temperatures between 150°F and 500°F with ±5°F uniformity for batch baking, roasting, and reheating operations. Floor ovens and rotary rack ovens command the largest installed base due to their centrality in high-volume bakeries and central commissaries, though countertop configurations are gaining traction in ghost kitchen and food truck deployments where real estate constraints dominate capital planning. Direct gas fired technology leads unit shipments because of its faster preheat cycles and lower capital cost, but dual fuel and infrared heating variants are capturing specification share among chains pursuing LEED certification and utility rebate eligibility.
The U.S. Department of Energy and EPA shape product development through efficiency mandates and emissions thresholds that determine eligibility for ENERGY STAR certification and state-level equipment rebates. NSF International standards govern sanitation design and material specifications, creating a compliance floor that excludes smaller import competitors from institutional procurement channels. Stakeholders must monitor evolving gas hookup moratoriums in California municipalities and New York City climate legislation that could accelerate electric conversion timelines or preserve gas infrastructure carve-outs for commercial kitchen equipment.
Market Dynamics
Energy-efficiency mandates from the U.S. Department of Energy are compressing product development cycles while electrification pressures in coastal municipalities create divergent technology roadmaps for gas convection equipment manufacturers.
Growth Catalysts
- Commercial catering replacement cycles:Food service operators are retiring aging floor ovens and rotary rack systems installed during the 2008-2012 expansion wave. Texas, California, and Florida account for the densest permit activity for restaurant construction and hotel renovations.
- ENERGY STAR certification pathways:Dual fuel and infrared heating variants qualify for utility rebate programs that reduce effective capital costs for chains pursuing LEED certification. The EPA's emissions thresholds determine eligibility for state-level equipment incentives.
- Ghost kitchen proliferation:Real estate-constrained delivery-only operations favor compact countertop configurations that prioritize footprint efficiency over throughput volume. Equipment specifiers in urban cores specify wall mount and undercounter formats.
Market Restraints
- Stainless steel input volatility:Captive metal fabrication operations at full-line manufacturers partially buffer against commodity swings, but specialized oven builders remain exposed to 304 and 430-grade sheet price fluctuations.
- Gas hookup moratoriums:California municipalities and New York City climate legislation restrict new natural gas infrastructure connections, forcing specification teams to model electric conversion timelines or preserve gas carve-outs for commercial kitchen equipment.
- Infrared heating technical ceilings:Temperature uniformity limitations above 450°F constrain infrared variants to specific roasting and reheating applications, excluding them from high-volume bakery specifications requiring ±5°F precision.
Strategic Opportunities
- Food truck and mobile catering white space:Independent pizzerias and mobile operators represent an underpenetrated buyer segment for compact gas convection configurations. NSF International certification unlocks institutional procurement channels currently dominated by full-line manufacturers.
- Dual fuel technology convergence:Gas-fired heat exchangers paired with electric booster elements capture specification share among operators seeking operational flexibility. The DOE's updated commercial cooking appliance standards reward hybrid thermal systems with enhanced rebate tiers.
- Maintenance contract unbundling:Multi-year service agreements represent a channel innovation beyond equipment sale margins. Hospital networks and school districts lock in predictable operating expenditures through captive service infrastructure.
Industry Challenges
- Combustion engineering talent scarcity:Gas burner assembly optimization and heat exchanger design expertise concentrates at legacy manufacturers. Specialized oven builders face recruitment friction for thermal systems engineers capable of meeting evolving emissions thresholds.
- NSF sanitation certification timelines:Material specification reviews and weld inspection protocols extend product launch schedules. Import competitors lacking established compliance documentation face exclusion from institutional procurement channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Convection Oven Market |
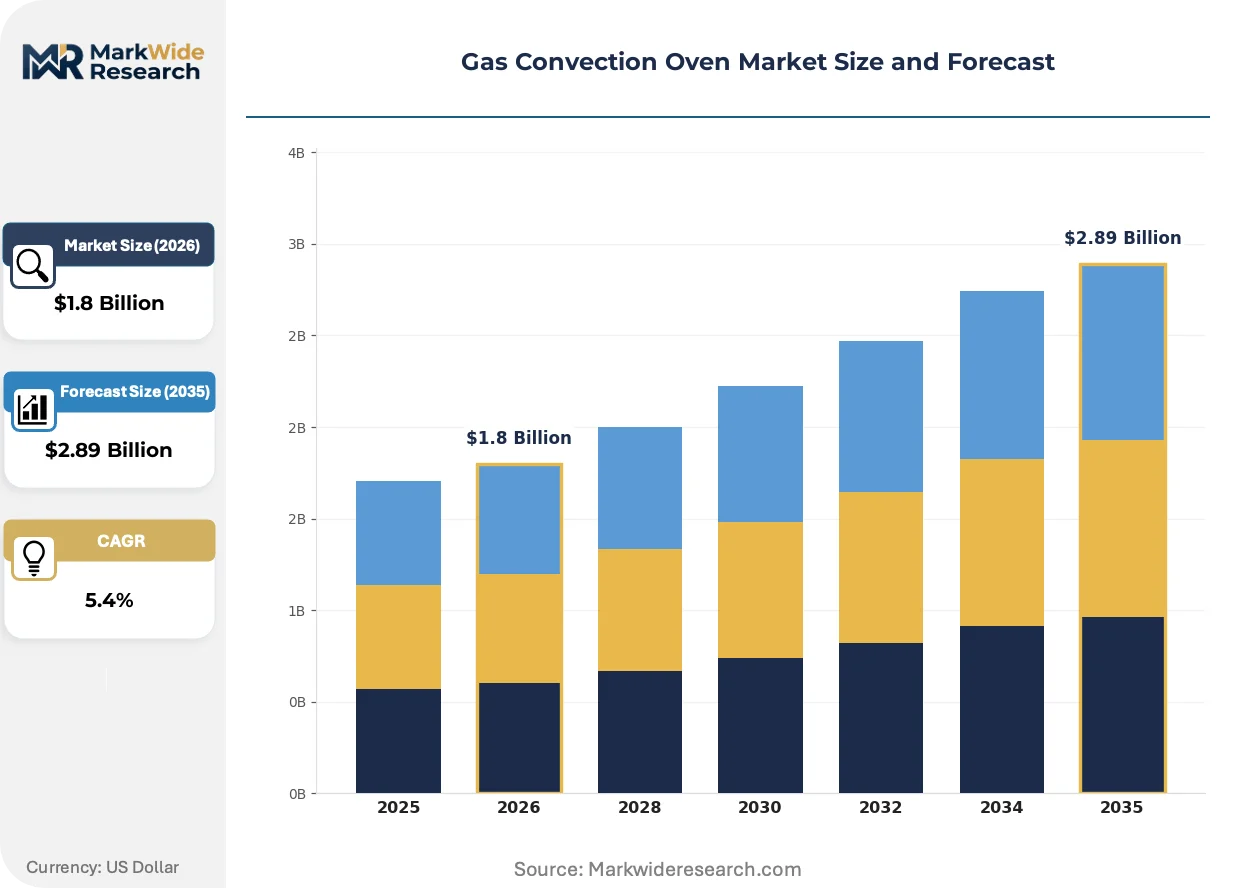
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Ovens, Wall Mount Ovens, Floor Ovens, Conveyor Ovens, Rotary Rack Ovens Technology: Direct Gas Fired, Indirect Gas Fired, Dual Fuel, Infrared Heating, Radiant Heating Application: Commercial Catering, Food Processing Units, Bakeries, Institutional Kitchens, Food Trucks End User: Restaurants, Hotels, Cafeterias, Event Catering Services, Food Retailers |
| Companies Covered | Alto-Shaam Inc., Vulcan, Hobart, Bakers Pride, BKI, Cadco, Duke Manufacturing, Garland Group, Lang World, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Convection Oven Market Shifts & Advancements
Product development in gas convection equipment is bifurcating between efficiency-maximizing thermal systems and connectivity-enabled operational intelligence, with regulatory pressure determining which trajectory dominates by buyer segment.
Infrared radiant heating technology is supplanting conventional forced-air convection in roasting-intensive applications where surface browning takes priority over chamber uniformity. Fast-casual chains with menu concentration in proteins specify infrared variants for faster cook cycles and reduced energy draw. The technology is compressing specification share for direct gas fired floor ovens in segments where throughput speed outweighs batch flexibility.
The EPA's commercial cooking appliance emissions thresholds are tightening allowable NOx and particulate outputs for gas-fired equipment seeking ENERGY STAR qualification. Manufacturers must redesign burner assemblies and heat exchanger geometries to maintain thermal performance under stricter combustion chemistry constraints. California's Air Resources Board implements the most aggressive implementation timeline, forcing specification teams in the state to model compliance-driven replacement cycles ahead of federal mandates.
Specification authority is migrating from equipment dealers to corporate sustainability offices and facilities engineering teams with mandate to hit utility reduction targets. Centralized procurement at multi-unit chains compresses switching cycles and privileges manufacturers with national service networks. The shift is most visible in hospital networks and university food service operations where capital planning integrates with institutional carbon accounting frameworks.
Gas Convection Oven Market Segmentation
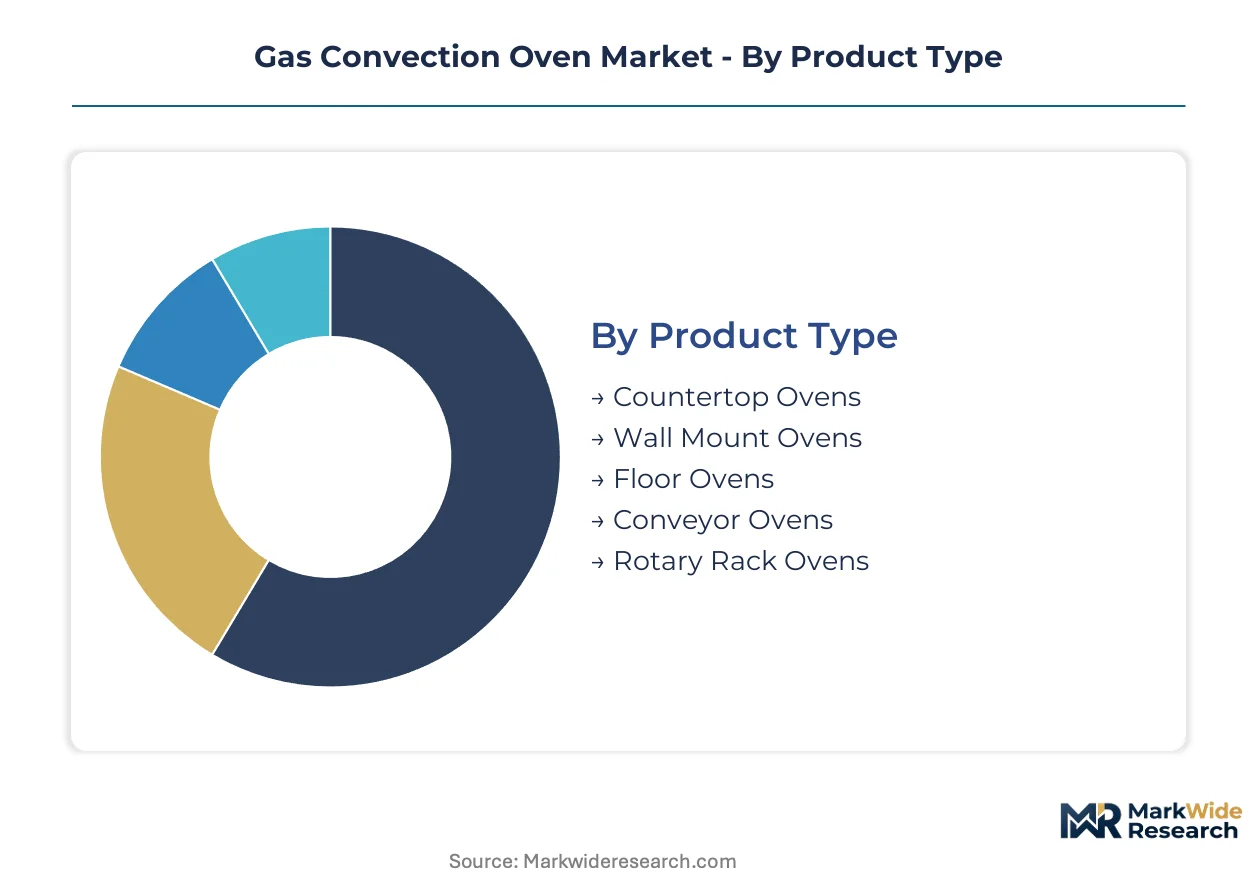
Equipment specification patterns in gas convection ovens diverge sharply between high-volume production environments and real estate-constrained operations. Understanding these fault lines reveals which configurations face displacement from electric alternatives and which retain durable demand.
Product Type:
Countertop and wall mount formats confront the strongest substitution pressure from electric convection and combination ovens, while floor-based systems defend their installed base through throughput economics.
- Countertop Ovens:Compact units with 0.5 to 1.5 cubic foot chamber capacity deploy single or double deck configurations for ghost kitchens and food trucks. Urban delivery-only operations in Texas and California specify these for footprint efficiency despite electric alternatives qualifying for deeper utility rebates.
- Floor Ovens:Full-height cabinet designs with 10 to 20 cubic foot chambers anchor high-volume bakery and central commissary workflows. Texas hotel renovation pipelines and Florida restaurant construction clusters sustain specification volume for these units.
- Wall Mount Ovens:Elevated installation formats free floor space in compact commercial kitchens. NSF certification requirements constrain import penetration.
- Conveyor Ovens:Continuous belt systems integrate with automated production lines for pizza and protein roasting. Fast-casual chains specify these for labor reduction.
- Rotary Rack Ovens:Rotating tray systems achieve ±5°F uniformity across 50 to 100 tray capacities for industrial bakery output. Central commissaries in California defend these against electric conversion mandates.
Floor ovens retain volume leadership; countertop configurations hold the steepest expansion curve.
Technology:
Cost tier stratification separates capital-efficient direct fired systems from premium dual fuel and infrared variants that capture utility rebate eligibility.
- Direct Gas Fired:Burner assemblies heat air directly within the cooking chamber, achieving 350°F preheat in under 10 minutes. Texas and Florida operators favor these for lower upfront capital and faster recovery times during peak service windows.
- Dual Fuel:Gas-fired heat exchangers pair with electric booster elements for operational flexibility across utility rate structures. California chains pursuing LEED certification specify these to capture enhanced rebate tiers from the DOE.
- Indirect Gas Fired:Sealed combustion chambers isolate flue gases from cooking air for improved humidity control. Institutional kitchens specify these for protein roasting applications.
- Infrared Heating:Radiant energy transfer accelerates surface browning but faces temperature uniformity limitations above 450°F. Fast-casual protein chains accept this tradeoff for speed.
- Radiant Heating:Ceramic or metal radiant panels distribute heat without forced air circulation. Specialty bakeries specify these for crust development.
Direct gas fired systems dominate unit shipments; dual fuel configurations are expanding most quickly among rebate-eligible buyers.
Application:
Customer type concentration determines margin structure, with institutional procurement channels demanding certified compliance and multi-year service contracts.
- Commercial Catering:Event-based and contract food service operations require portable or modular equipment configurations. California and Florida hotel renovation cycles drive replacement demand for rotary rack and floor oven systems.
- Bakeries:Artisan and industrial producers prioritize chamber uniformity and steam injection capability. Central commissaries specify NSF-certified units for institutional supply contracts.
- Food Processing Units:High-volume production environments integrate conveyor and rotary rack systems with automated handling equipment. USDA-inspected facilities require sanitation-compliant construction.
- Institutional Kitchens:School districts and hospital networks lock in predictable operating expenditures through captive service infrastructure. Hobart maintains dominance here through multi-year maintenance agreements.
- Food Trucks:Mobile operators prioritize compact footprint and rapid preheat over throughput volume. Countertop and undercounter formats penetrate this underdeveloped segment.
Commercial catering captures the largest revenue pool; food trucks present the steepest untapped expansion trajectory.
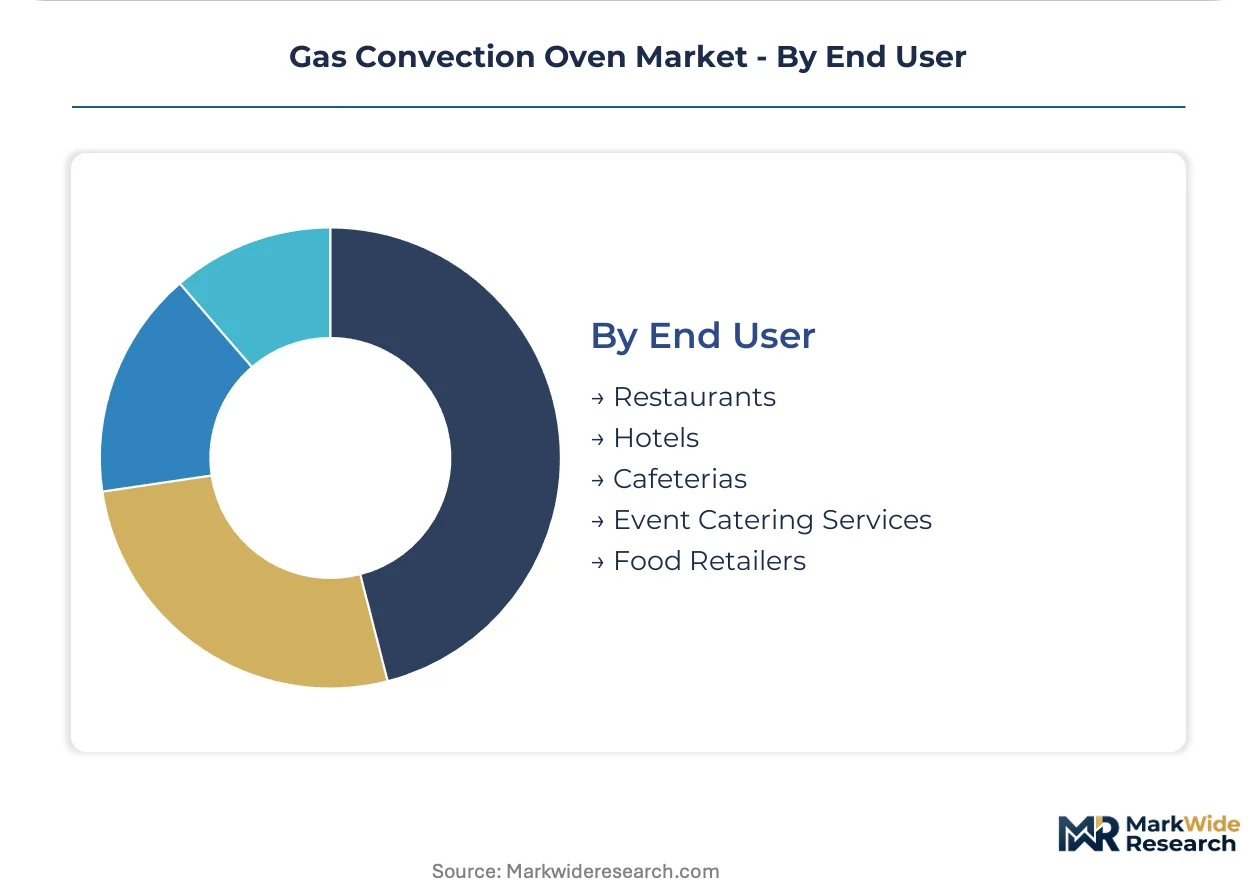
End User:
Application maturity varies across buyer segments, with restaurants and hotels defending gas infrastructure against electrification mandates while cafeterias face accelerated conversion timelines.
- Restaurants:Full-service and fast-casual operators balance throughput requirements against real estate constraints. Texas construction permits sustain floor oven demand; California operators model electric conversion timelines.
- Hotels:Property renovation cycles drive centralized kitchen equipment replacement. Florida and California renovation pipelines concentrate specification authority.
- Cafeterias:Corporate and educational feeding operations face compressed procurement cycles from sustainability mandates. Electric conversion pressure concentrates in California municipalities.
- Event Catering Services:Mobile and temporary kitchen deployments favor portable countertop and wall mount configurations. NSF certification unlocks institutional event contracts.
- Food Retailers:Supermarket in-store bakeries and prepared food counters specify compact systems for behind-counter installation. Utility rebate eligibility shapes technology selection.
Restaurants retain the deepest installed base; cafeterias face the most compressed technology transition curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas operators command pricing leverage over California buyers due to unrestricted gas infrastructure access, while coastal electrification mandates compress procurement cycles in high-regulation markets.
United States
Texas, California, and Florida concentrate restaurant construction permits and hotel renovation activity. The U.S. Department of Energy's updated commercial cooking appliance standards compress product development cycles for manufacturers serving multi-state chains. Dallas-Fort Worth and Houston metro areas sustain floor oven demand from centralized commissary expansions.
Germany
Industrial bakery automation drives rotary rack oven specifications in Baden-Württemberg and North Rhine-Westphalia. The EU Green Deal's commercial kitchen efficiency directives accelerate dual fuel technology adoption among Mittelstand equipment fabricators. Munich's hospitality sector balances gas retention against municipal decarbonization timelines.
Japan
Compact countertop formats penetrate Tokyo's ghost kitchen density and Osaka's food hall renovations. METI's commercial equipment efficiency standards privilege thermal systems achieving sub-10-minute preheat cycles. Nagoya's manufacturing belt supplies burner assembly components to domestic and Southeast Asian oven builders.
United Kingdom
London's contract catering sector specifies NSF-certified wall mount configurations for event infrastructure. The UK's net-zero building regulations force specification teams to model electric conversion timelines for central commissary equipment. Birmingham's food service distribution hub concentrates refurbishment demand for aging floor oven installations.
Australia
New South Wales and Victoria hotel renovation pipelines sustain rotary rack oven replacement cycles. The country's national energy efficiency program rewards ENERGY STAR-qualified gas equipment with state-level rebates. Melbourne's bakery sector defends gas infrastructure against municipal electrification pressures.
Gas Convection Oven Market Competitive Landscape
Concentration sits with full-line manufacturers controlling captive fabrication and national service networks. The vendor base stratifies across three tiers: integrated metal-forming operations, specialized compact-equipment builders, and import-dependent price competitors. Strategic differentiation follows two vectors—backward integration into burner assembly and heat exchanger production, and multi-year maintenance contract capture in institutional channels.
Within the full-line tier, Vulcan, Hobart, and Bakers Pride exemplify divergent specialization patterns. Vulcan anchors throughput-focused floor and conveyor configurations through in-house metal fabrication. Hobart occupies a position in institutional kitchen dominance via extensive service infrastructure locking in hospital and school district contracts. Bakers Pride represents the compact-specialist archetype targeting footprint-constrained independent operators.
| Leading Market Players |
|---|
| Alto-Shaam Inc. |
| Vulcan |
| Hobart |
| Bakers Pride |
| BKI |
| Cadco |
| Duke Manufacturing |
| Garland Group |
| Lang World |
| Others |
Supply & Pricing Matrix
Infrared burner assemblies displacing conventional forced-air heat exchangers in fast-casual protein chains simultaneously shift component sourcing from domestic metal-forming operations to specialized ceramic radiant panel suppliers concentrated in Japan and Germany, compressing margin structures for oven builders lacking captive burner production.
Pricing Analysis
The customization-premium spread separates configured-to-order rotary rack systems from standard floor oven SKUs by 35-45 percent, with NSF certification tier and burner assembly origin serving as primary price differentiation drivers. Three-tier pricing structure across premium dual-fuel, standard direct-fired, and economy countertop configurations reflects vertical integration depth at full-line manufacturers. Cost compression in economy tiers is intensifying because import competitors from Southeast Asia exploit stainless steel price volatility. Independent pizzerias and food truck operators exhibit highest price sensitivity, while hospital networks prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Busan to Long Beach and Savannah have compressed landed cost advantages for 304-grade stainless sheet sourced from Chinese mills versus domestic producers in Pennsylvania and Alabama. Captive metal fabrication at Vulcan and Hobart draws from North American steel service centers, while specialized oven builders rely on Taiwanese burner assemblies and Italian control systems. Single-source vulnerability concentrates in ceramic infrared panel supply from Nagoya manufacturing clusters. Distribution runs through manufacturer-direct institutional contracts and regional equipment dealer networks serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric convection and combination oven substitution threatens gas equipment incumbents most acutely in California municipalities and New York City, where hookup moratoriums accelerate procurement team modeling of conversion timelines.
For Market Incumbents: Fortify gas infrastructure defense by embedding dual-fuel flexibility into floor oven and rotary rack platforms, preserving specification share against electrification mandates. Deepen backward integration into burner assembly production to buffer against ceramic radiant panel supply concentration in Japan. Lock in multi-year maintenance contracts with Texas and Florida hotel renovation pipelines before rebate eligibility shifts favor electric alternatives. For New Entrants and Emerging Players: NSF certification fast-track through expedited material specification reviews unlocks institutional procurement channels currently dominated by Hobart's service infrastructure. Food truck and ghost kitchen countertop configurations in Texas urban cores represent the most penetrable white space, with undercounter formats addressing real estate constraints that electric alternatives cannot resolve. Pursue direct-to-operator digital specification tools bypassing traditional dealer networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed full-line manufacturers holding captive fabrication but lacking connectivity-enabled service platforms, presenting rollup opportunities for operational intelligence integration. Five-to-ten year viability hinges on gas infrastructure carve-out preservation in coastal climate legislation. Monitor California Air Resources Board implementation timelines as inflection signal for compliance-driven replacement cycle acceleration or compression.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Platform Development | Captures enhanced DOE rebate tiers for California LEED-certified chains. |
| Captive Burner Assembly Production | Insulates margin structures from Nagoya ceramic panel supply concentration. |
| NSF Certification Fast-Track Investment | Unlocks hospital and school district procurement channels for compact specialists. |
| Multi-Year Maintenance Contract Unbundling | Converts equipment sales into predictable recurring revenue from institutional kitchens. |
| Infrared Technology Licensing | Accelerates surface browning specifications for fast-casual protein chains. |
Research Methodology
A spread of perspectives from equipment procurement directors at multi-unit chains, thermal systems engineers at legacy manufacturers, NSF certification specialists, and regional equipment dealers converged on the working assumptions shaping demand elasticity and replacement cycle timing. Primary fieldwork combined structured interviews with secondary validation from EPA ENERGY STAR qualification databases, DOE commercial cooking appliance standard filings, and state-level utility rebate program documentation. Bottom-up shipment analysis triangulated against top-down construction permit data from Texas, California, and Florida.
Segmentation dimensions modeled include product configuration, heating technology architecture, buyer application type, and end-user operational scale across the analysis window. CAGRs derived from regression analysis against restaurant construction permit velocity and hotel renovation pipeline data, with cross-validation against manufacturer shipment disclosures. Industry-specific forecast inputs incorporated gas hookup moratorium implementation timelines and evolving EPA emissions threshold trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained gas infrastructure access in Texas and Florida and gradual electrification pressure in coastal municipalities; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Plastic Processing Equipment Market
Food Processing Equipment
Cookers and Ovens Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Vee Bee Consistometer Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Countertop Blast Chiller Market
Food Processing Equipment
Pan Feeder Market
Food Processing Equipment
Global Automatic Mask Production Equipment Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Mooncake Production Line Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Global Conveyor Oven Market