
 Food Extrusion Market | 2026-2036
Food Extrusion Market Size, Share, and Industry Trends Forecast 2026-2036
Food Extrusion Market Intelligence
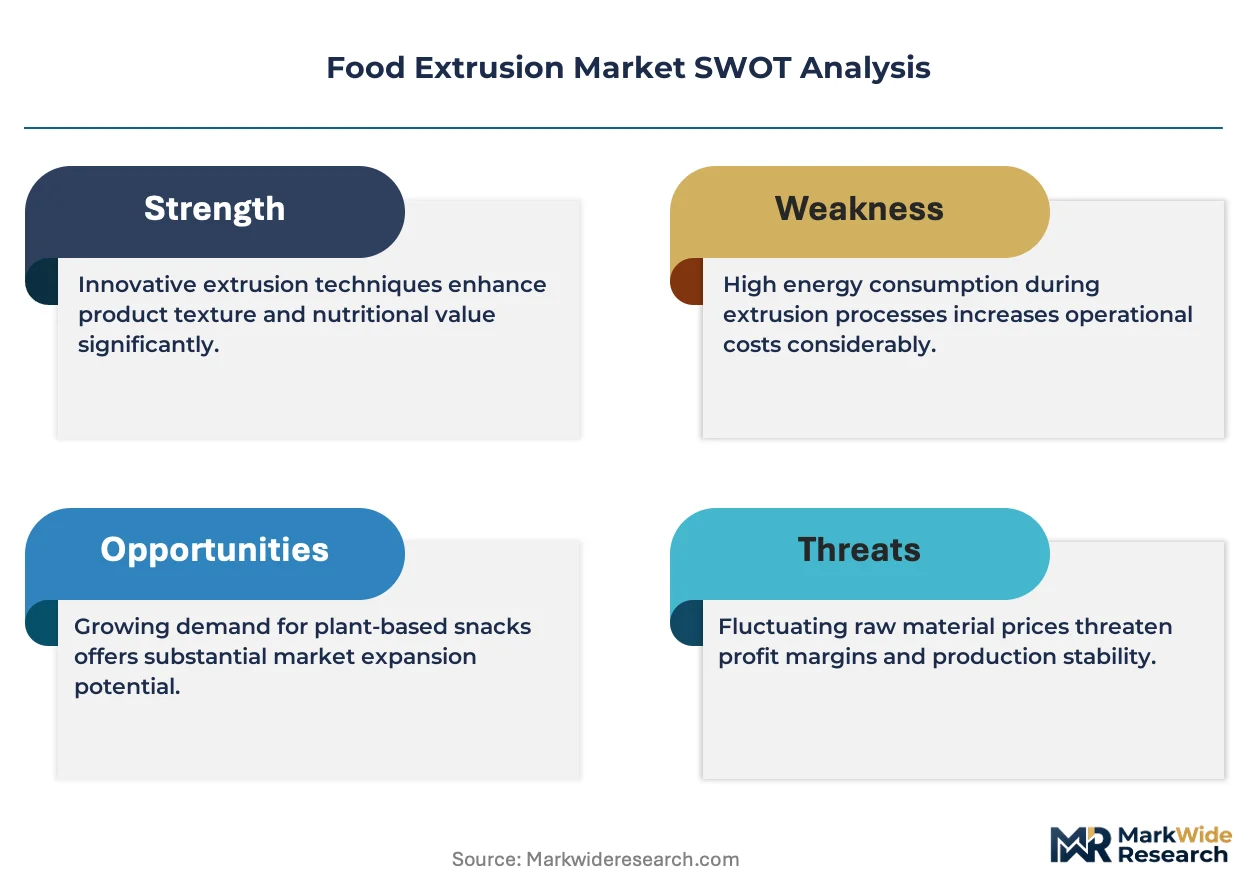
Clean-label and high-protein specification tiers is rotating demand toward equipment capable of precise thermal control and minimal ingredient degradation. Bühler leverages its Swiss engineering heritage to dominate premium twin-screw systems for plant-based proteins. Clextral sustains technology leadership through its co-rotating intermeshing screw designs optimized for textured vegetable protein. Wenger Manufacturing anchors North American supply with large-scale aquatic feed extrusion lines.
Food extrusion forces moistened, starchy, or proteinaceous materials through a heated barrel and shaped die under controlled shear and pressure, typically operating at 100-180°C and 20-200 bar to achieve gelatinization, expansion, or texturization. The process transforms raw ingredients into finished consumer foods, animal feeds, and nutritional intermediates with defined density, porosity, and digestibility profiles. Snacks and breakfast cereals command the largest volume positions, while textured vegetable protein attracts the fastest capacity investment as meat-alternative brands scale manufacturing. Twin-screw extrusion captures the highest-margin equipment sales due to its flexibility across ingredient rheologies and superior heat-transfer efficiency compared to single-screw alternatives.
FDA food safety modernization rules and USDA organic certification standards shape equipment design and validation protocols for manufacturers serving the US market. The EU's REACH chemicals framework and CE machinery directives constrain material selection and operator safety architecture for European deployments. Stakeholders must monitor how evolving protein fortification regulations and energy-efficiency mandates reshape capital allocation priorities across equipment generations.
Market Dynamics
Twin-screw extrusion systems are displacing single-screw alternatives as plant-based protein processors demand precise thermal control and ingredient flexibility, compressing equipment replacement cycles and reshaping capital allocation priorities across food manufacturing.
Growth Catalysts
- EU F-Gas Regulation:Equipment upgrades accelerate as manufacturers phase out hydrofluorocarbon-dependent cooling systems in favor of compliant thermal management architectures.
- Textured vegetable protein demand:Meat-alternative brands scale manufacturing capacity, pulling investment into high-shear extrusion lines capable of achieving fibrous mouthfeel profiles.
- Brazil processing modernization:Food manufacturers in São Paulo and Minas Gerais states deploy automated extrusion systems to serve expanding domestic and export snack markets.
Market Restraints
- Stainless steel input volatility:Barrel and screw material costs fluctuate with nickel pricing, squeezing equipment margins and extending quote validity periods.
- German precision component concentration:Critical gearbox and bearing suppliers cluster in Baden-Württemberg, creating single-source vulnerability for global equipment assemblers.
- REACH chemical compliance friction:ECHA substance restrictions on lubricants and coatings force reformulation cycles that delay European equipment certifications.
Strategic Opportunities
- India protein fortification mandates:FSSAI nutritional enrichment requirements for school feeding programs create installed base expansion for mid-capacity extrusion systems.
- Pulse protein extrusion:Lentil and chickpea isolate processing opens white space between commodity snack lines and premium meat-analog equipment tiers.
- Energy-efficiency retrofit incentives:Italy's Industry 4.0 tax credits accelerate replacement of thermal-inefficient legacy extruders in Emilia-Romagna food clusters.
Industry Challenges
- Thermal process engineering talent scarcity:Food science programs underproduce graduates with simultaneous expertise in rheology, heat transfer, and sanitary design.
- Legacy control system integration:Brownfield sites struggle to synchronize new twin-screw lines with existing SCADA architectures and batch management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Extrusion Market |
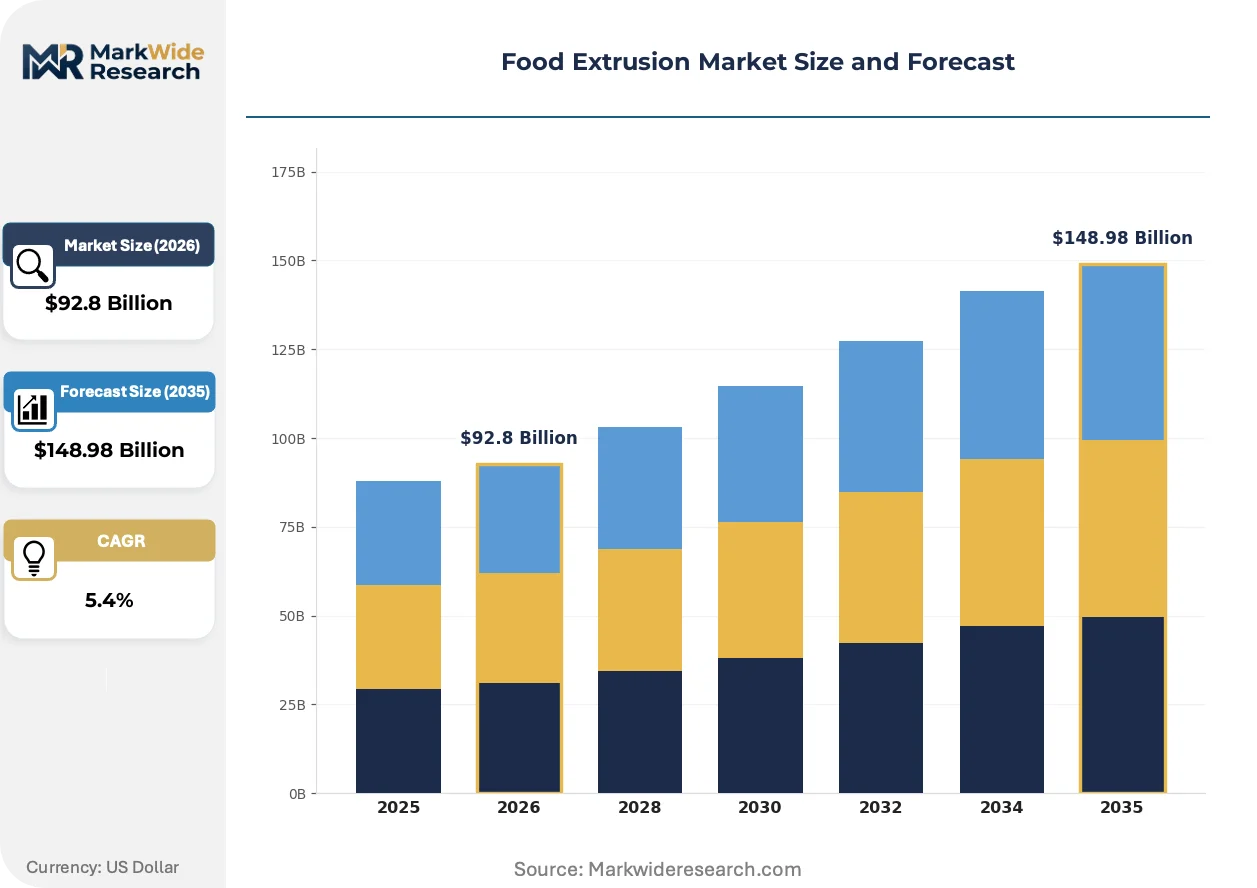
| Market Size in 2026 | $92.8 Billion |
| Market Size in 2035 | $148.98 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Breakfast Cereals, Pasta, Textured Vegetable Protein Technology: Single-Screw Extrusion, Twin-Screw Extrusion, Cold Extrusion, Hot Extrusion End User: Food Manufacturers, Retail Chains, Food Service Providers, Home Cooks Application: Animal Feed, Human Food, Nutraceuticals, Specialty Products |
| Companies Covered | GEA, Clextral, Bühler, Wenger Manufacturing, American Extrusion International, Coperion, KAHL Group, The Bonnot Company, Baker Perkins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Extrusion Market Strategic Shifts & Innovations
Extrusion technology is fragmenting into application-specific architectures as clean-label requirements and protein diversification force equipment makers to abandon generalist platforms in favor of purpose-built thermal and shear profiles.
Co-rotating intermeshing screw designs are displacing conventional single-screw configurations in textured protein applications. Plant-based meat manufacturers in Germany and the Netherlands adopt these systems at accelerated replacement cycles. The technology is displacing older equipment categories by enabling precise control over shear history and residence time distribution.
REACH framework amendments on persistent organic pollutants tighten lubricant specifications for European deployments. Equipment manufacturers must reformulate bearing greases and hydraulic fluids to maintain CE machinery directive compliance. Snack and breakfast cereal processors in Italy and France face the steepest compliance timelines.
Buyers now unbundle equipment procurement from proprietary aftermarket service contracts. Large food manufacturers in Brazil and Germany negotiate independent maintenance agreements and third-party spare part sourcing. This pattern concentrates among multinationals operating extrusion assets across multiple production sites.
Food Extrusion Market Segmentation
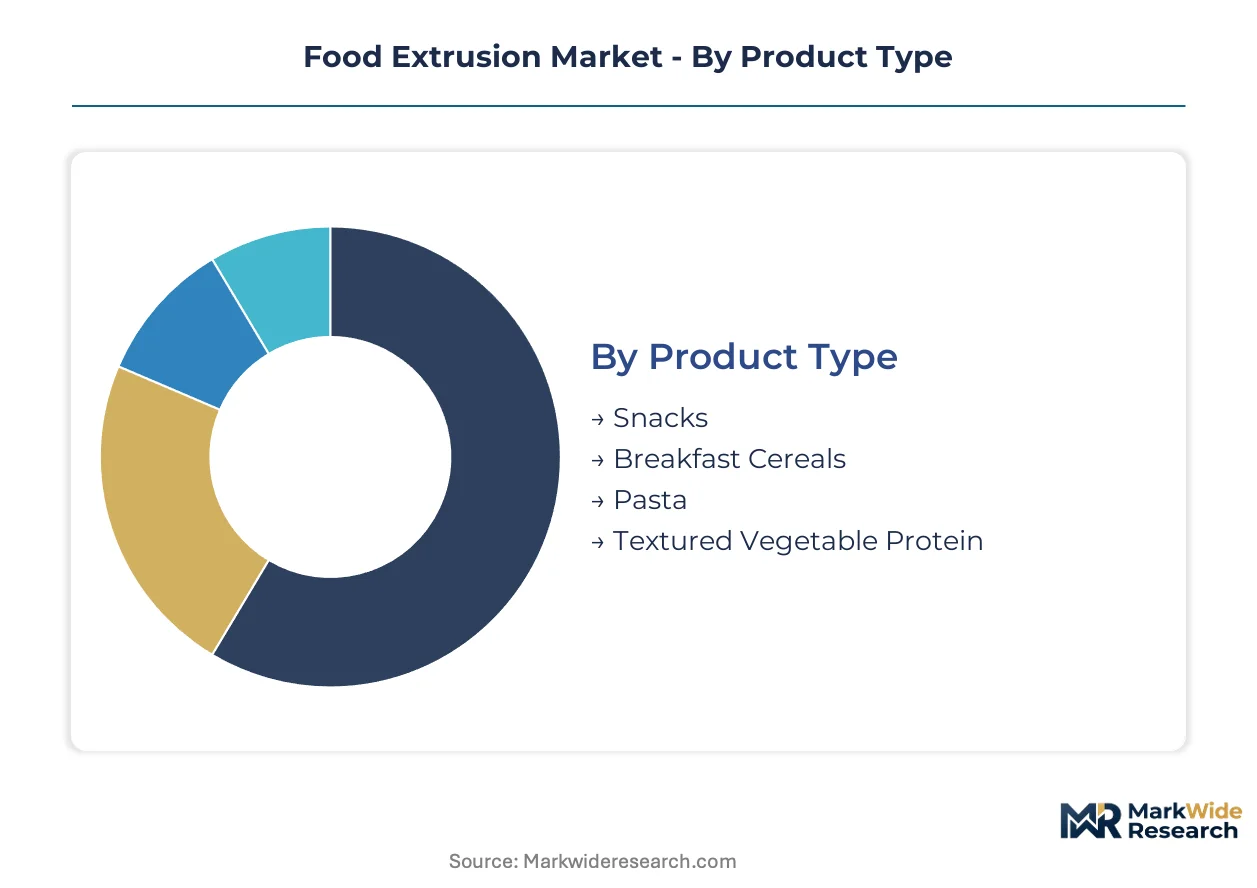
Equipment buyers segment procurement by thermal processing intensity and ingredient rheology. Margin pools concentrate where protein texturization demands precision engineering rather than commodity throughput.
Product Type:
Margin pools concentrate in protein texturization equipment where shear control determines finished-product quality premiums.
- Snacks:Corn and potato-based formulations require high-expansion dies operating at 150-180°C with rapid pressure drop for cellular structure formation. Demand clusters in São Paulo state as Brazilian manufacturers automate puffed snack lines for Mercosur export compliance.
- Textured Vegetable Protein:High-shear twin-screw systems align protein molecules into fibrous matrices mimicking meat mouthfeel through controlled thermal denaturation. Meat-alternative brands in Germany and the Netherlands are pulling capacity investment fastest as they scale beyond pilot production.
- Breakfast Cereals:Flaked and puffed grain processing uses lower-shear configurations with extended residence times for complete starch gelatinization.
- Pasta:Cold extrusion through bronze dies preserves semolina integrity for premium dried and fresh noodle categories.
The dominant share belongs to Snacks, while Textured Vegetable Protein is closing the gap fastest.
Technology:
Cost tier stratification separates precision-engineered systems from commodity single-screw alternatives.
- Twin-Screw Extrusion:Co-rotating intermeshing designs enable independent control of conveying, mixing, and shearing functions through modular screw configurations. Food manufacturers in Italy's Emilia-Romagna cluster prioritize these systems for clean-label snack diversification under Industry 4.0 retrofit incentives.
- Single-Screw Extrusion:Simpler architectures suit high-volume, low-variability applications where ingredient consistency permits fixed screw geometries. Brazilian processors in Minas Gerais deploy these for standard corn puff production where thermal efficiency outweighs formulation flexibility.
- Hot Extrusion:Elevated temperature processing achieves starch gelatinization and protein denaturation in single-pass configurations.
- Cold Extrusion:Ambient-temperature forming preserves heat-sensitive nutrients and volatile flavor compounds in pasta and certain nutraceutical applications.
Twin-Screw Extrusion commands the premium tier, with Single-Screw Extrusion retaining volume leadership in emerging markets.
End User:
Customer type determines service bundling preferences and aftermarket revenue potential.
- Food Manufacturers:Integrated processors operating multiple SKUs demand equipment with rapid changeover capability and validated CIP protocols. Large multinationals in Germany and Brazil increasingly unbundle procurement from proprietary service contracts, sourcing third-party maintenance and spare parts independently.
- Food Service Providers:Central kitchens and contract manufacturers require mid-capacity systems with standardized output for consistent portion control across distributed locations.
- Retail Chains:Private-label producers need flexible lines accommodating seasonal volume fluctuations and rapid product iteration cycles.
- Home Cooks:Niche tabletop extrusion represents minimal commercial significance, confined to specialty culinary equipment channels.
Food Manufacturers absorb the dominant equipment spend, while Food Service Providers are expanding capacity most aggressively.
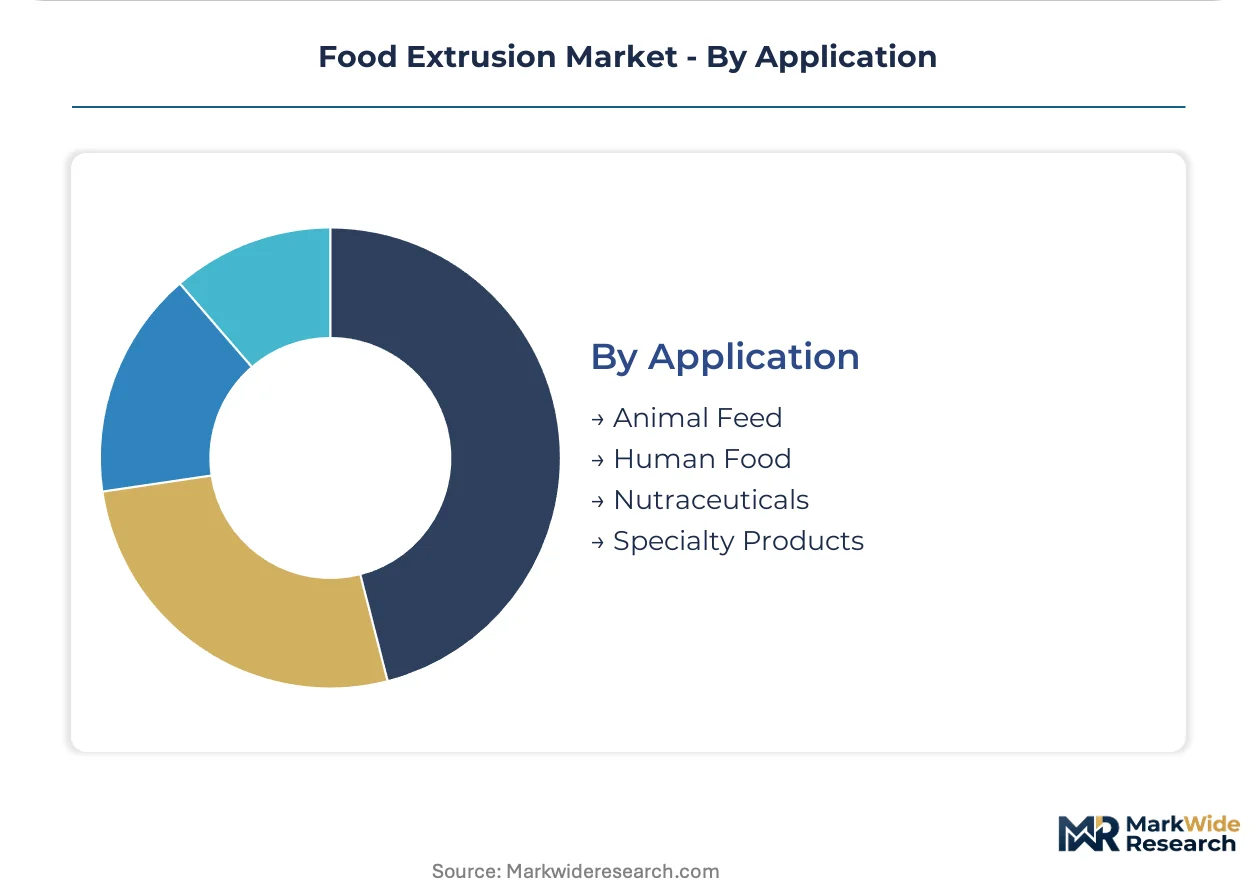
Application:
Volume distribution reflects divergence between commodity feed processing and value-added human nutrition systems.
- Human Food:Snack and cereal processors in Italy and France face compressed compliance timelines under REACH lubricant amendments while upgrading legacy thermal management architectures. Clean-label specifications rotate demand toward equipment with minimal ingredient degradation profiles.
- Animal Feed:Aquatic feed extrusion requires high-density sinking formulations with controlled oil absorption for species-specific nutritional delivery.
- Nutraceuticals:Encapsulation and bioavailability enhancement applications demand precise residence time control for sensitive active compounds.
- Specialty Products:Pet treats, industrial starches, and biodegradable packaging materials occupy fragmented niche positions.
Human Food maintains the dominant application share, with Nutraceuticals climbing fastest on protein fortification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil and India exhibit the highest price elasticity, prioritizing throughput over precision engineering, while German and Italian processors absorb premium equipment costs for clean-label compliance and protein texturization capabilities.
Germany
Meat-alternative brands in Berlin and Hamburg scale manufacturing capacity, pulling investment into high-shear extrusion lines. The EU's F-Gas Regulation accelerates equipment upgrades as manufacturers phase out hydrofluorocarbon-dependent cooling systems. The Baden-Württemberg precision component cluster concentrates critical gearbox and bearing suppliers, creating single-source vulnerability for global equipment assemblers.
Italy
Snack and breakfast cereal processors in Emilia-Romagna diversify clean-label portfolios under Industry 4.0 retrofit incentives. REACH framework amendments on persistent organic pollutants tighten lubricant specifications, forcing reformulation cycles. The Bologna-Modena food machinery corridor deploys automated extrusion systems to serve expanding domestic and export markets.
Brazil
Food manufacturers in São Paulo and Minas Gerais states automate puffed snack lines for Mercosur export compliance. ANVISA nutritional enrichment requirements create installed base expansion for mid-capacity extrusion systems. The Campinas technology cluster anchors processing modernization as domestic brands scale manufacturing.
United States
Integrated processors operating multiple SKUs demand equipment with rapid changeover capability and validated CIP protocols. FDA food safety modernization rules and USDA organic certification standards shape equipment design and validation protocols. The Midwest agricultural belt sustains large-scale aquatic feed extrusion deployments.
India
FSSAI protein fortification mandates for school feeding programs create installed base expansion for mid-capacity extrusion systems. Pulse protein extrusion opens white space between commodity snack lines and premium meat-analog equipment tiers. The Maharashtra-Gujarat industrial corridor attracts capacity investment as food manufacturers upgrade processing capabilities.
Food Extrusion Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with precision-engineered twin-screw systems commanding premium pricing against commodity single-screw alternatives. The vendor base stratifies across Swiss-German engineering specialists, North American scale operators, and emerging-market fabricators. Dominant archetypes include premium twin-screw specialists, large-scale aquatic feed suppliers, and mid-tier regional assemblers. Competitive moves concentrate on geographic expansion through local manufacturing partnerships and portfolio diversification into plant-based protein applications.
Within the premium engineering tier, Bühler and Clextral represent Swiss-European precision archetypes, while Wenger Manufacturing anchors North American supply capabilities. These three exemplify how heritage engineering credentials translate into sustained positioning across high-margin equipment categories. Regional specialists occupy positions between these anchors and emerging-market cost competitors.
| Leading Market Players |
|---|
| GEA |
| Clextral |
| Bühler |
| Wenger Manufacturing |
| American Extrusion International |
| Coperion |
| KAHL Group |
| The Bonnot Company |
| Baker Perkins |
| Others |
Cost & Logistics Intelligence
Twin-screw barrel assemblies displacing single-screw alternatives are redrawing supplier geography toward Baden-Württemberg precision engineering clusters while compressing margin structures across equipment tiers. This substitution dynamic concentrates pricing power with German gearbox and bearing specialists even as Brazilian and Indian buyers resist premium absorption.
Pricing Analysis
Aftermarket parts and field service contracts generate lifetime value multiples exceeding original equipment sales for premium twin-screw vendors. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-engineered systems with CE certification from mid-tier Italian assemblers and emerging-market fabricators. Cost compression in standard-grade equipment is intensifying because nickel price volatility squeezes stainless steel barrel margins. Food manufacturers in São Paulo and Minas Gerais exhibit highest price elasticity, while German meat-alternative brands absorb premium costs for fibrous texturization capability.
Supply Chain Analysis
Inventory buffers for precision gearboxes and intermeshing screw elements now stretch 16-20 weeks as Baden-Württemberg suppliers operate at capacity limits. Manufacturing concentration centers on Germany, Italy, and Switzerland for critical thermal management components, with Brazil and India emerging as regional assembly hubs. Component sourcing draws from Swedish specialty steel mills, Japanese bearing manufacturers, and Austrian hydraulic systems suppliers. Single-source vulnerability in German precision component clusters threatens equipment delivery timelines. Distribution runs through OEM-direct sales for large multinationals and regional distributor networks for mid-cap processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based protein texturization demand is disrupting equipment procurement patterns, with EU F-Gas Regulation mandates accelerating replacement cycles beyond historical norms.
For Market Incumbents: Secure captive supply relationships with Baden-Württemberg gearbox specialists before capacity constraints harden into structural bottlenecks. Deepen backward integration into barrel and screw manufacturing to offset nickel price volatility squeezing stainless steel input costs. Clextral and Bühler heritage positions in co-rotating intermeshing designs face emerging competition from Chinese equipment fabricators targeting mid-tier protein extrusion. For New Entrants and Emerging Players: Independent maintenance and spare parts sourcing represents the most penetrable service-layer gap, as large Brazilian and German multinationals increasingly unbundle procurement from proprietary aftermarket contracts. Target India's FSSAI protein fortification mandate-driven school feeding programs with mid-capacity twin-screw systems priced between commodity snack lines and premium meat-analog tiers. Establish Campinas or Maharashtra-based assembly partnerships to bypass import duty exposure and reduce logistics lead times. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European food machinery portfolios acquired during 2018-2021 platform rollups. Five-to-ten year viability hinges on plant-based protein capacity scaling sustaining equipment replacement velocity above historical 7-10 year cycles. Monitor ECHA REACH amendment timelines on persistent organic pollutants as inflection indicator for lubricant reformulation costs compressing European equipment margins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Captive supply of German-engineered gearboxes mitigates single-source vulnerability in Baden-Württemberg clusters. |
| Regional Manufacturing Partnership | Campinas or Maharashtra assembly reduces import exposure for Brazilian and Indian price-sensitive buyers. |
| Aftermarket Service Unbundling | Independent maintenance contracts capture margin pools as multinationals reject proprietary service捆绑. |
| Pulse Protein Application Development | Lentil and chickpea isolate processing opens white space between commodity snack and premium meat-analog tiers. |
| REACH Compliance Pre-certification | Reformulated lubricant portfolios secure CE machinery directive approval ahead of ECHA amendment deadlines. |
Research Approach
The analysis maps twin-screw extrusion systems, single-screw alternatives, hot and cold extrusion configurations, each validated through equipment procurement directors, plant engineers at integrated food manufacturers, aftermarket service heads, and thermal process engineering specialists. Primary interview findings triangulate against customs and trade data for stainless steel and precision component flows, SEC filings of publicly listed machinery vendors, EU ECHA substance restriction databases, and FSSAI regulatory notifications. Bottom-up equipment shipment tracking reconciles with top-down food manufacturer capex survey data.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user category, and application intensity. CAGRs derive from installed base expansion rates, replacement cycle compression factors, and protein texturization capacity scaling assumptions. Forecast inputs incorporate EU F-Gas Regulation compliance timelines, nickel price volatility scenarios, and Industry 4.0 retrofit incentive uptake curves.
Underlying assumptions cover sustained plant-based protein investment, regulatory enforcement consistency, and raw material price stabilization, with deviation risk concentrated in German precision component supply disruptions and REACH amendment scope expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Individual Quick Freezing Market
Food Processing Equipment
Smart Bread Machine Market
Food Processing Equipment
Countertop Blast Chiller Market
Food Processing Equipment
Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Global Food Sterilization Machines Market
Food Processing Equipment
Commercial Wood Fired Pizza Oven Market
Food Processing Equipment
Bread Processing Equipment Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Global Industrial Food Blanchers Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
Griddle Market
Food Processing Equipment
Global Food Deaerators Market
Food Processing Equipment
Yogurt Makers Market