
 Food Ultrasound Market | 2026-2036
Food Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
Food Ultrasound Market Analysis
High-frequency transducer architecture is fragmenting into modular, frequency-tunable platforms that accommodate batch-to-batch variation in food matrices. Hielscher Ultrasonics leverages its piezoelectric stack expertise to dominate laboratory-scale extraction systems. Emerson Electric anchors industrial throughput with integrated generator-transducer pairs rated for continuous liquid processing. Bosch competes through its hygiene-optimized transducer housings designed for clean-in-place protocols in dairy and beverage lines.
Food ultrasound applies acoustic cavitation—mechanical vibrations typically between 20 kHz and 100 kHz—to induce physical and chemical changes in food matrices without thermal degradation, primarily serving sterilization, extraction, emulsification, and texture modification purposes. Ultrasonic pasteurization leads technology adoption as beverage producers seek non-thermal alternatives to preserve heat-sensitive bioactive compounds in functional drinks. Solid foods processing represents the fastest-growing application segment, driven by meat tenderization and defrosting protocols that reduce processing time versus conventional methods. Food manufacturers occupy the deepest margin pools among end users, given their volume procurement of multi-kilowatt systems for integrated production lines.
The FDA oversees equipment safety under 21 CFR standards for food contact surfaces, while EFSA evaluates novel processing claims for European market authorization, and China's SAMR enforces GB standards for imported ultrasonic food equipment. These frameworks shape demand by mandating material certifications and process validation documentation that filter out low-specification suppliers. Stakeholders must monitor evolving thresholds for acoustic energy density reporting, as regulators tighten documentation requirements for label claims around "non-thermal" and "minimal processing" positioning.
Market Dynamics
Food ultrasound systems face mounting pressure from EFSA's novel processing certification timelines, which compress equipment validation windows while manufacturers race to deploy frequency-tunable platforms that accommodate batch-to-batch matrix variation in functional beverage lines.
Growth Catalysts
- EFSA Novel Food Framework:Accelerated equipment certification pathways in Europe reduce time-to-market for ultrasonic pasteurization systems in dairy and beverage applications.
- Functional Beverage Proliferation:Heat-sensitive bioactive compound preservation demands drive non-thermal sterilization adoption across probiotic and plant-based drink manufacturing.
- Meat Processing Automation:Solid food applications for tenderization and rapid defrosting compress processing time versus conventional thermal methods in industrial slaughterhouse operations.
Market Restraints
- Piezoelectric Material Concentration:High-purity ceramic stack sourcing concentrates among East Asian suppliers, exposing equipment manufacturers to input cost volatility and supply disruption.
- Acoustic Energy Density Reporting:Evolving FDA 21 CFR documentation thresholds for "non-thermal" label claims create compliance friction and filter out low-specification equipment vendors.
- Thermal Pasteurization Incumbency:Established steam and hot-fill infrastructure in legacy beverage plants creates switching cost barriers for ultrasonic system adoption.
Strategic Opportunities
- Clean-Label Positioning:China's SAMR enforcement of GB standards for imported equipment creates first-mover advantage for certified suppliers in Asia-Pacific functional food manufacturing.
- Modular Frequency Architecture:Convergence of IoT-enabled process monitoring with tunable transducer platforms enables real-time matrix adaptation in contract manufacturing environments.
- Pharmaceutical-Grade Extraction:Botanical and cannabinoid processing applications open adjacent revenue pools beyond conventional food and beverage verticals.
Industry Challenges
- Acoustic Engineering Talent Scarcity:Specialized expertise in cavitation physics and food matrix interaction remains concentrated among German and Swiss research clusters, constraining vendor scaling.
- Clean-in-Place Integration Complexity:Hygiene-optimized transducer housing design for dairy lines demands extensive reconfiguration of existing CIP protocols and validation documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Ultrasound Market |
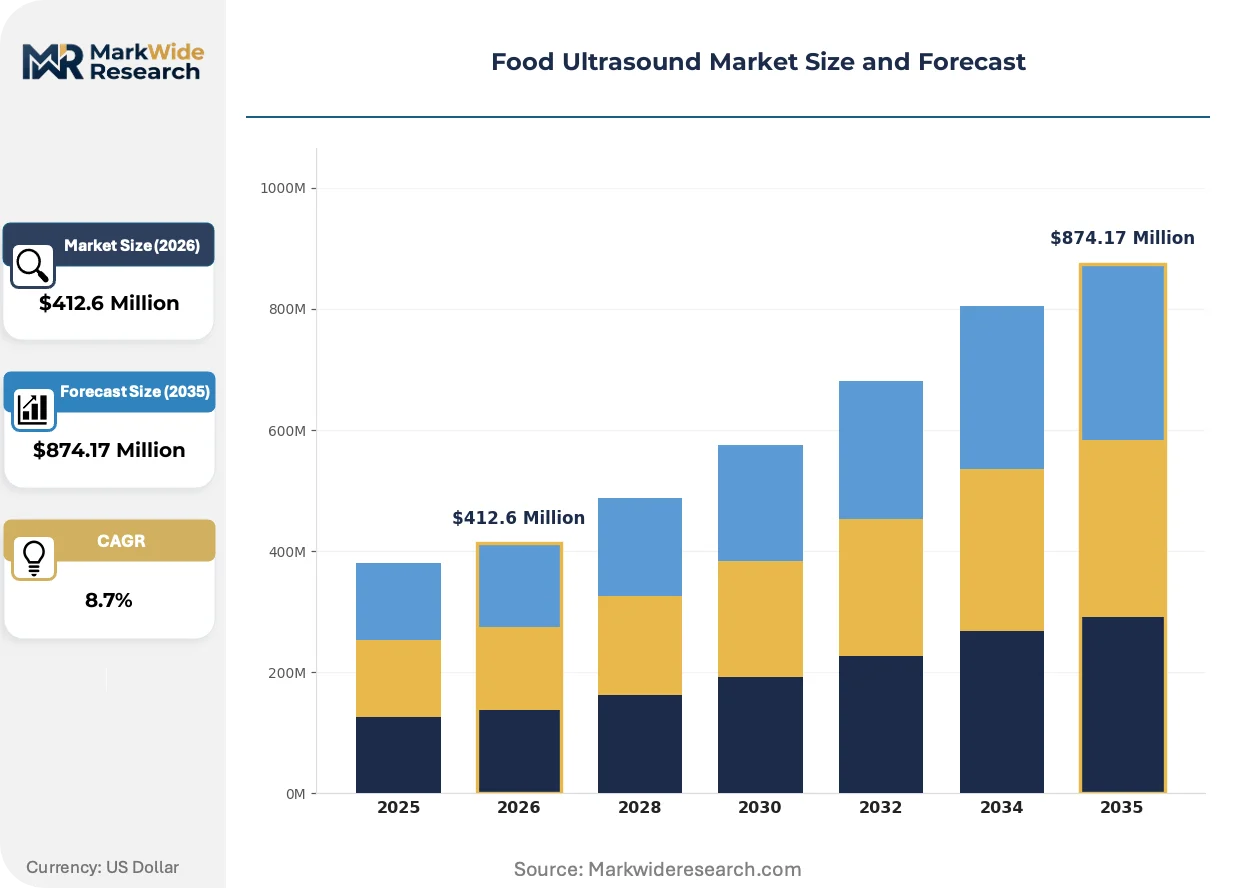
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ultrasonic Cleaning, Ultrasonic Homogenization, Ultrasonic Extraction, Ultrasonic Pasteurization Application: Liquids Processing, Solid Foods Processing, Emulsions, Food Preservation End User: Food Manufacturers, Beverage Producers, Research Institutions, Food Packaging Companies Form: Liquid, Powder, Granules, Semi-Solid |
| Companies Covered | Emerson Electric, Hielscher Ultrasonics, Rinco Ultrasonics, Dukane, Sonics & Materials, Bühler, Bosch, Marchant Schmidt, Cheersonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Ultrasound Market Emerging Trajectories
Frequency-tunable transducer platforms are compressing equipment differentiation cycles while regulatory documentation requirements tighten around acoustic energy density validation for non-thermal processing claims.
Modular generator-transducer pairs rated for continuous liquid processing are virtualizing the traditional separation between laboratory-scale extraction and industrial throughput systems. Beverage contract manufacturers adopt these platforms fastest, enabling single-line flexibility across heat-sensitive functional drink portfolios without dedicated equipment swaps.
REACH substance restrictions on piezoelectric ceramic compositions are forcing reformulation of high-frequency stack materials. Equipment suppliers in Germany and Switzerland accelerate alternative ceramic development to maintain export eligibility, while Asian component vendors face compliance timeline compression for European market access.
Certification-driven procurement now dominates multi-kilowatt system selection in integrated production lines. Food manufacturers in Germany prioritize EFSA-validated equipment documentation over capital cost minimization, shifting vendor evaluation criteria toward process validation support and regulatory filing assistance rather than unit economics alone.
Food Ultrasound Market Segmentation
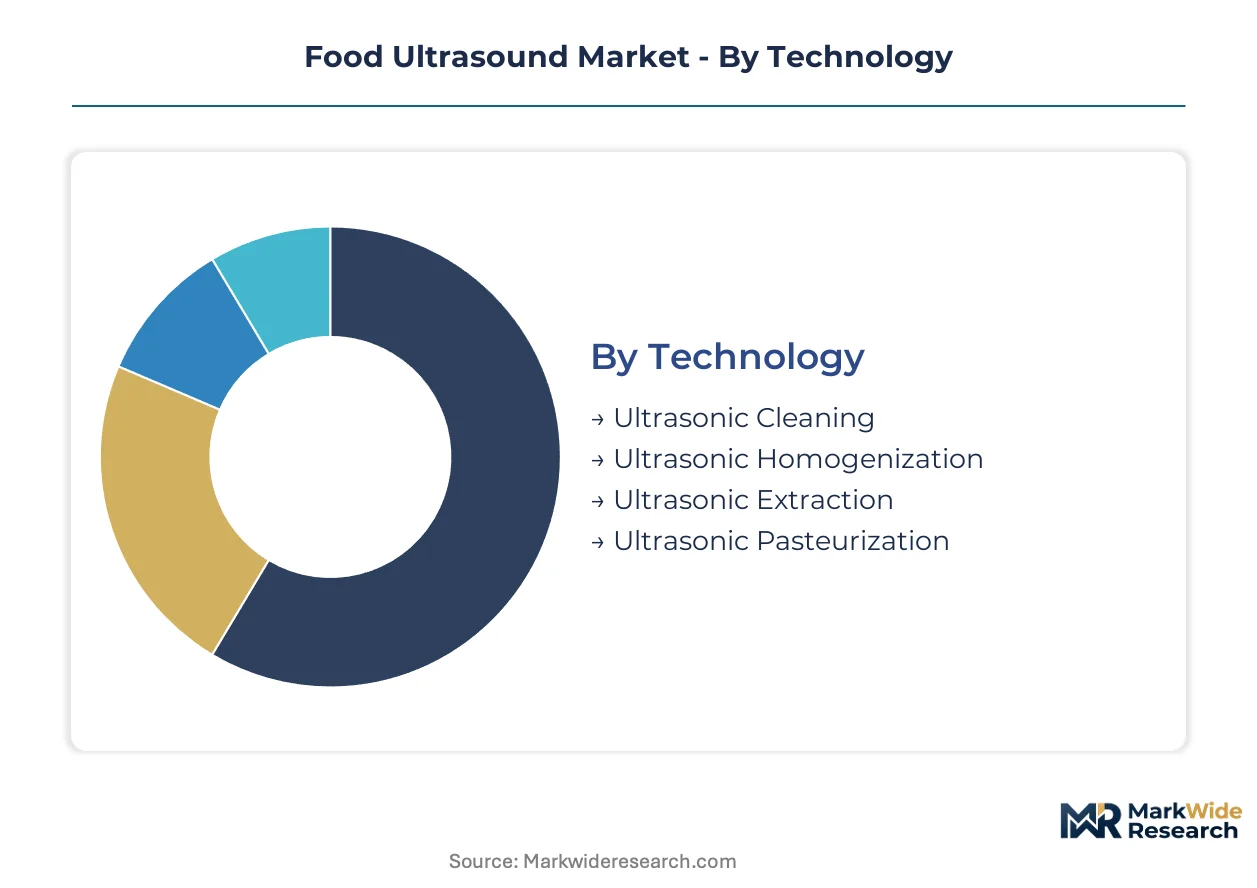
Segmentation in food ultrasound equipment reveals distinct procurement patterns across technology tiers and end-user scale. Technology selection varies sharply between continuous liquid processing lines and batch solid food operations, while end-user type determines specification depth and validation documentation requirements.
Technology:
Cost tier separates laboratory-scale extraction systems from industrial continuous processing infrastructure, with generator-transducer integration depth as the primary price determinant.
- Ultrasonic Pasteurization:Continuous-flow cavitation systems operating at 20-100 kHz replace thermal processing in beverage lines. Demand concentrates among German dairy and functional drink manufacturers seeking EFSA-validated non-thermal sterilization pathways for heat-sensitive bioactive preservation.
- Ultrasonic Extraction:Frequency-tunable platforms isolate botanical compounds and cannabinoids without solvent degradation. Research institutions in Switzerland and contract manufacturers in Germany anchor procurement, driven by pharmaceutical-grade purity specifications and REACH-compliant material certifications.
- Ultrasonic Homogenization:Emulsion stabilization for plant-based dairy alternatives and functional beverages.
- Ultrasonic Cleaning:Surface sanitation for processing equipment in clean-in-place protocols.
Ultrasonic pasteurization holds installed capacity. Ultrasonic extraction is rotating up the share rankings.
Application:
Application type dictates transducer architecture—liquid processing favors continuous inline systems while solid foods demand batch chambers with variable frequency modulation.
- Solid Foods Processing:Batch cavitation chambers tenderize meat matrices and accelerate defrosting protocols. Industrial slaughterhouse operations in Germany deploy these systems to compress processing time versus conventional thermal methods, with hygiene-optimized housings enabling clean-in-place validation.
- Liquids Processing:Inline generator-transducer pairs handle beverage sterilization and homogenization at throughput rates exceeding 10,000 liters per hour.
- Emulsions:Stabilization of plant-based dairy alternatives and functional drink formulations.
- Food Preservation:Shelf-life extension through non-thermal microbial inactivation in packaged goods.
Solid foods processing shows the steepest expansion trajectory. Liquids processing maintains the deepest equipment installed base.
End User:
Customer type determines procurement complexity—food manufacturers demand multi-kilowatt integrated lines with full validation documentation, while research institutions prioritize frequency tunability over throughput.
- Food Manufacturers:Multi-kilowatt continuous processing lines dominate procurement, with volume scale enabling margin capture across integrated production. German manufacturers prioritize EFSA-validated documentation over capital cost minimization, shifting vendor selection toward regulatory filing support.
- Beverage Producers:Functional drink specialists drive ultrasonic pasteurization adoption for probiotic and plant-based portfolios requiring heat-sensitive compound preservation.
- Research Institutions:Laboratory-scale extraction systems with modular frequency architecture for matrix adaptation studies.
- Food Packaging Companies:Surface treatment systems for material sterilization prior to filling operations.
Food manufacturers command the largest equipment procurement volumes. Beverage producers are gaining share fastest in new system installations.
Form:
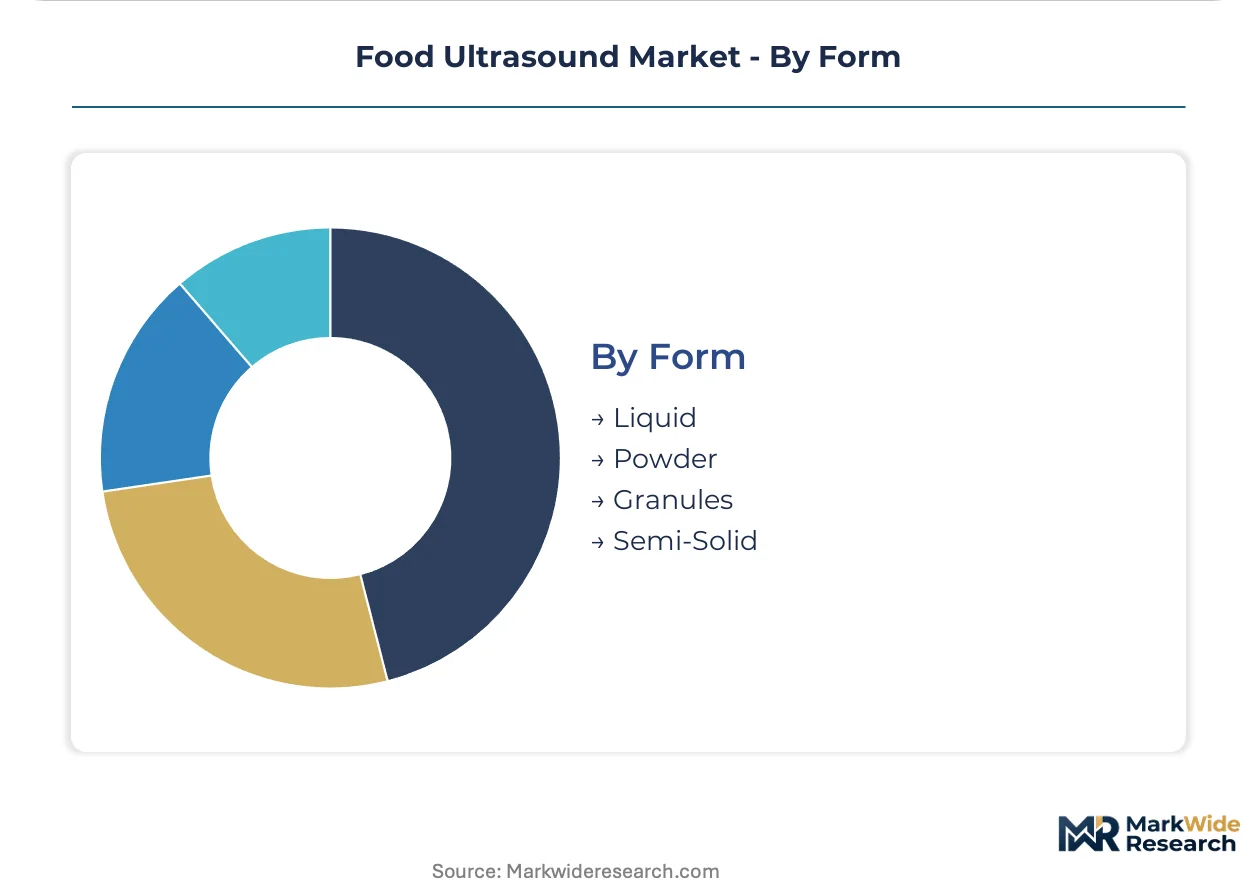
Physical state of the food matrix determines cavitation efficiency and transducer frequency selection, with liquid matrices enabling continuous processing advantages over solid or semi-solid formats.
- Liquid:Optimal cavitation efficiency enables highest throughput continuous processing. Beverage and dairy applications in Germany and Switzerland dominate, with SAMR-compliant systems penetrating Chinese functional drink manufacturing.
- Semi-Solid:Viscous matrices require specialized chamber design for uniform acoustic energy distribution. Meat processing and plant-based alternative manufacturers deploy batch systems with variable frequency modulation to accommodate texture variation.
- Powder:Reconstitution and dispersion applications in ingredient manufacturing.
- Granules:Surface treatment and coating protocols in confectionery and cereal processing.
Liquid form maintains the dominant installed base. Semi-solid applications are climbing the fastest in new equipment orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German food manufacturers command the deepest procurement volumes for multi-kilowatt ultrasonic pasteurization systems, while Swiss research institutions anchor laboratory-scale extraction demand and Chinese functional beverage producers drive Asia-Pacific adoption.
Germany
EFSA-validated equipment documentation now outweighs capital cost minimization in procurement decisions. REACH substance restrictions on piezoelectric ceramics are forcing reformulation of high-frequency stack materials among Bavarian and Baden-Württemberg suppliers. Stuttgart and Tübingen anchor industrial R&D clusters where Bosch and Hielscher Ultrasonics develop hygiene-optimized transducer housings for clean-in-place dairy protocols.
Switzerland
Pharmaceutical-grade botanical extraction specifications drive frequency-tunable platform adoption. Swissmedic oversight of novel processing equipment creates compliance barriers that filter low-specification vendors from cannabinoid and nutraceutical manufacturing contracts. Basel and Zurich research institutions concentrate expertise in cavitation physics, constraining vendor scaling beyond these clusters.
China
SAMR enforcement of GB standards for imported ultrasonic food equipment accelerates certification-driven procurement among functional drink manufacturers. Dual carbon goals are compressing validation timelines for non-thermal sterilization alternatives to energy-intensive thermal pasteurization. Yangtze River Delta beverage contract manufacturers prioritize EFSA-equivalent documentation to access European export markets.
United States
FDA 21 CFR documentation thresholds for "non-thermal" label claims are reshaping vendor evaluation criteria toward process validation support. Heat-sensitive bioactive compound preservation demands in probiotic beverage manufacturing drive ultrasonic pasteurization pilot programs. California and Pacific Northwest functional food clusters concentrate early adoption of frequency-tunable continuous processing lines.
Japan
METI industrial efficiency mandates are accelerating meat processing automation investments, including ultrasonic tenderization and rapid defrosting systems. JIS standards for food contact surfaces create material certification requirements that favor established equipment suppliers over new entrants. Osaka-Kobe industrial corridors deploy batch cavitation chambers to compress slaughterhouse processing times versus conventional thermal methods.
Food Ultrasound Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where integrated generator-transducer pairs for continuous liquid processing sit apart from modular laboratory-scale extraction systems. The market organizes around three strategic archetypes: industrial throughput specialists, frequency-tunable platform developers, and hygiene-optimized dairy equipment fabricators. Dominant competitive moves include strategic partnerships for regulatory filing assistance and technology licensing for piezoelectric stack alternatives compliant with REACH substance restrictions.
Within the industrial throughput tier, Emerson Electric and Bosch exemplify divergent positioning—Emerson anchors continuous liquid processing through integrated generator-transducer pairs, while Bosch occupies the hygiene-optimized segment with clean-in-place transducer housings for dairy lines. Hielscher Ultrasonics represents the frequency-tunable laboratory-scale archetype, leveraging piezoelectric stack expertise to serve research institutions and pharmaceutical-grade extraction demand.
| Leading Market Players |
|---|
| Emerson Electric |
| Hielscher Ultrasonics |
| Rinco Ultrasonics |
| Dukane |
| Sonics & Materials |
| Bühler |
| Bosch |
| Marchant Schmidt |
| Cheersonic |
| Others |
Supply Flow & Price Mechanics
East Asian high-purity piezoelectric ceramic stack suppliers concentrate upstream input control, anchoring margin capture in generator-transducer integration tiers while German equipment manufacturers absorb certification-driven cost premiums downstream.
Pricing Analysis
Cost-plus contracts with ceramic raw material indexation dominate procurement between stack suppliers and equipment manufacturers. Pricing stratifies across EFSA-validated premium systems, REACH-compliant standard platforms, and economy-grade laboratory units lacking regulatory documentation. Cost compression in standard-tier continuous processing lines intensifies as Bosch and Emerson Electric compete on generator-transducer integration depth. Research institutions exhibit lowest price sensitivity, prioritizing frequency tunability over unit economics, while beverage contract manufacturers negotiate hardest on per-liter processing cost.
Supply Chain Analysis
Contract manufacturing concentrates among Bavarian precision fabricators and Swiss electronics assemblers serving Hielscher Ultrasonics and Bosch production lines. High-purity lead zirconate titanate ceramics draw from Japanese and Chinese specialty ceramic foundries, with titanium diaphragm sourcing tethered to German metallurgical suppliers. Single-source vulnerability in high-frequency transducer stack production exposes equipment lead times to East Asian export licensing delays. Distribution runs through direct OEM sales for multi-kilowatt integrated lines and specialized laboratory equipment distributors for modular extraction platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
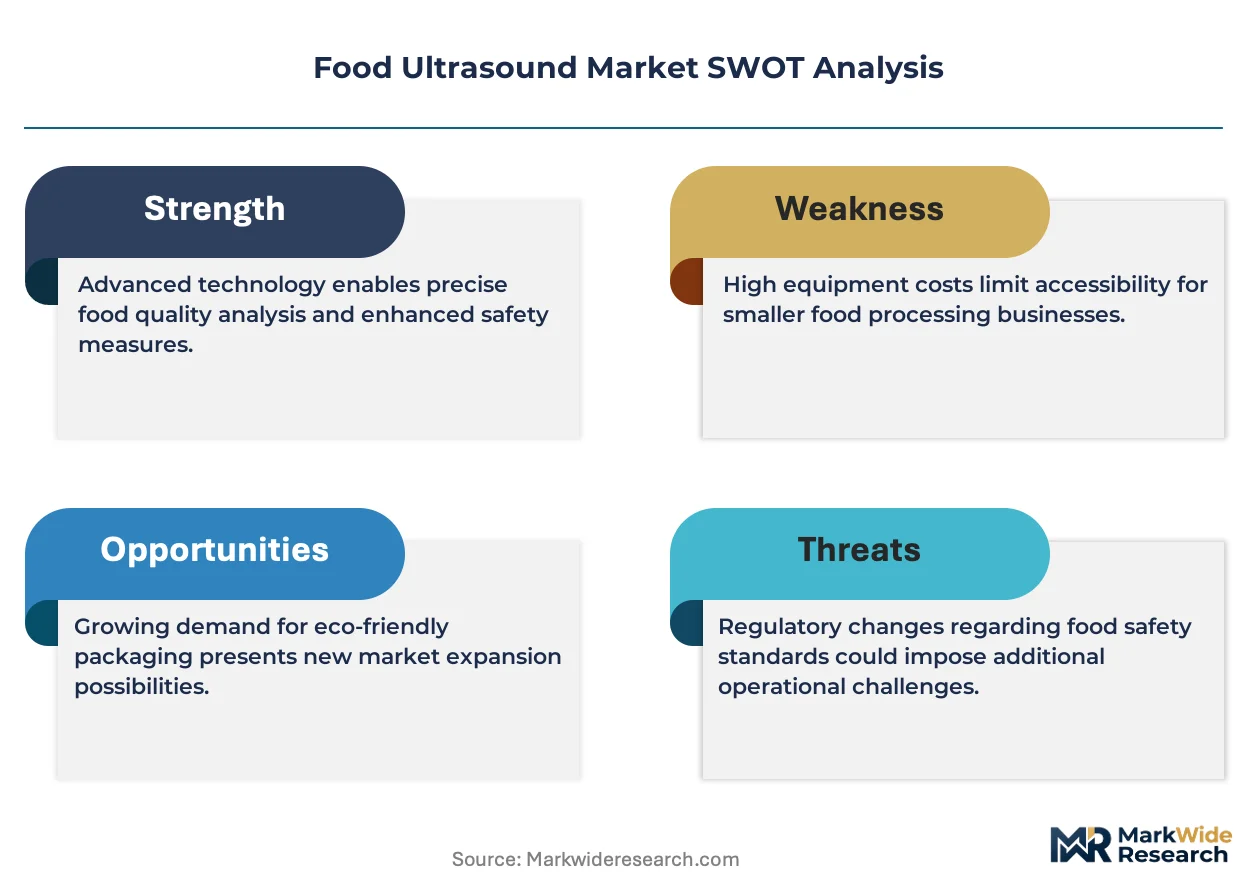
EFSA's novel processing certification acceleration creates a regulatory inflection point, compressing validation windows while expanding addressable market for documented non-thermal sterilization systems.
For Market Incumbents: Build regulatory filing assistance capabilities as a moat against emerging Asian competitors. Anchor clean-in-place validation documentation for dairy line deployments while expanding piezoelectric stack backward integration to offset East Asian ceramic supply volatility. Threats concentrate in SAMR-certified Chinese equipment vendors undercutting on capital cost. For New Entrants and Emerging Players: Chinese functional beverage contract manufacturing represents the most penetrable white-space target, with Yangtze River Delta producers seeking EFSA-equivalent documentation for European export access. Laboratory-scale extraction systems for cannabinoid processing offer secondary entry path with lower certification barriers. Go-to-market should emphasize regulatory filing partnership rather than equipment-only sales. For Investors and Strategic Acquirers: Capital is best deployed toward frequency-tunable platform developers with pharmaceutical-grade extraction credentials and existing EFSA validation portfolios. Long-term viability hinges on REACH-compliant ceramic stack alternatives and IoT-enabled process monitoring integration. Watch for SAMR enforcement intensity shifts as inflection signal for Asia-Pacific market access timing.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Validation Partnership | Accelerated equipment certification timelines compress competitive differentiation cycles for pasteurization systems. |
| REACH-Compliant Ceramic Development | Alternative piezoelectric stack materials maintain European market access amid substance restrictions. |
| IoT-Enabled Frequency Tuning | Real-time matrix adaptation capabilities capture contract manufacturing flexibility premiums. |
| Clean-in-Place Protocol Integration | Hygiene-optimized transducer housings defend dairy line market share against thermal pasteurization incumbents. |
| SAMR Certification Investment | GB standards compliance unlocks functional beverage manufacturing demand in China's Yangtze River Delta. |
Methodological Framework
A spread of perspectives from food manufacturing engineers, regulatory affairs specialists at EFSA-notified bodies, procurement directors at German dairy processors, and acoustic physics researchers converged on the working assumptions. Primary fieldwork with equipment vendors and contract manufacturers combined with secondary validation from FDA 21 CFR guidance documents, EFSA novel food opinions, SAMR GB standard filings, and REACH substance restriction updates. Bottom-up equipment shipment tracking and top-down food processing capital expenditure analysis provided triangulation anchors.
Demand-supply balance modeling across the projection horizon incorporated technology tier segmentation by generator-transducer integration depth, application segmentation by liquid versus solid food matrix, and end-user segmentation by procurement scale. CAGRs derived from equipment installation run-rates and replacement cycle analysis. Forecast inputs included EFSA validation pipeline velocity, REACH ceramic reformulation timelines, and SAMR enforcement intensity indicators.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese equipment vendors achieving EFSA equivalence would shift outcomes. Quarterly review of validation certification backlogs, ceramic raw material export licensing delays, and functional beverage contract manufacturing expansion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Food Processing Market
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
Spray Drying Market
Food Processing Equipment
China Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Griddle Market
Food Processing Equipment
North America Cold Storage Market
Food Processing Equipment
Nigeria Cocoa Processing Market
Food Processing Equipment
Bottled Water Processing Equipment Market
Food Processing Equipment
Double Stack Oven Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Pea Protein Processing Equipment Market
Food Processing Equipment
Brewery Equipment Market
Food Processing Equipment
Individual Quick Freezing Market