
 Global Colorectal Cancer Diagnostics Market | 2026-2036
Global Colorectal Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Colorectal Cancer Diagnostics Market Foresight
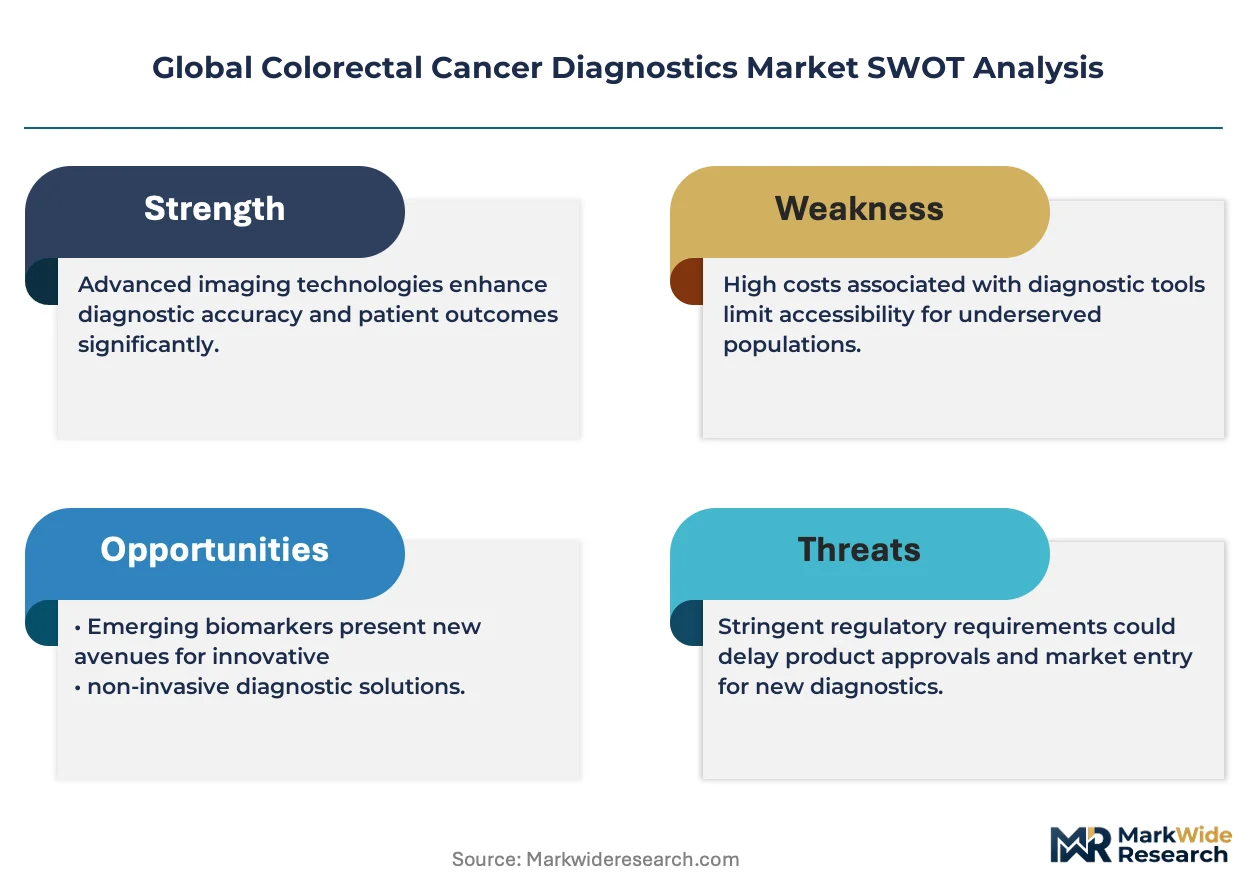
Reimbursement for non-invasive screening modalities is reconfiguring margin pools away from traditional colonoscopy services toward stool DNA and blood-based diagnostics. Exact Sciences Corporation leverages its CMS-backed Cologuard franchise to anchor recurring revenue from Medicare-aged populations. Quest Diagnostics sustains broad geographic coverage through its national laboratory network and direct-to-physician channel control. Danaher Corporation dominates life sciences instrumentation supply to molecular diagnostics labs, extending its position through consumables pull-through.
Colorectal cancer diagnostics encompasses molecular, immunological, imaging, and sample-based testing methods designed to detect oncogenic mutations, protein biomarkers, or structural abnormalities in colorectal tissue and biofluids, with polymerase chain reaction and next-generation sequencing platforms achieving sensitivity thresholds below 0.1% variant allele frequency for circulating tumor DNA detection. Molecular diagnostics leads product type revenue as laboratories scale NGS panel deployment for Lynch syndrome and RAS mutation profiling, while blood-based tests represent the fastest-growing category as multi-cancer early detection panels expand commercial validation. Diagnostic laboratories occupy the primary end-user margin pool, though home care settings are gaining reimbursement traction for stool collection kits that bypass clinical site visits.
FDA premarket approval pathways and EMA CE-IVD frameworks shape product development timelines and market access conditions for novel colorectal cancer assays in the United States and European Union, with Japan's PMDA adding distinct clinical trial requirements for Asian population validation. WHO cancer screening guidelines and national reimbursement decisions by CMS and Germany's Federal Joint Committee determine volume economics for population-scale testing programs. Stakeholders must monitor evolving regulatory acceptance of blood-based screening as a first-line modality versus confirmatory diagnostic use.
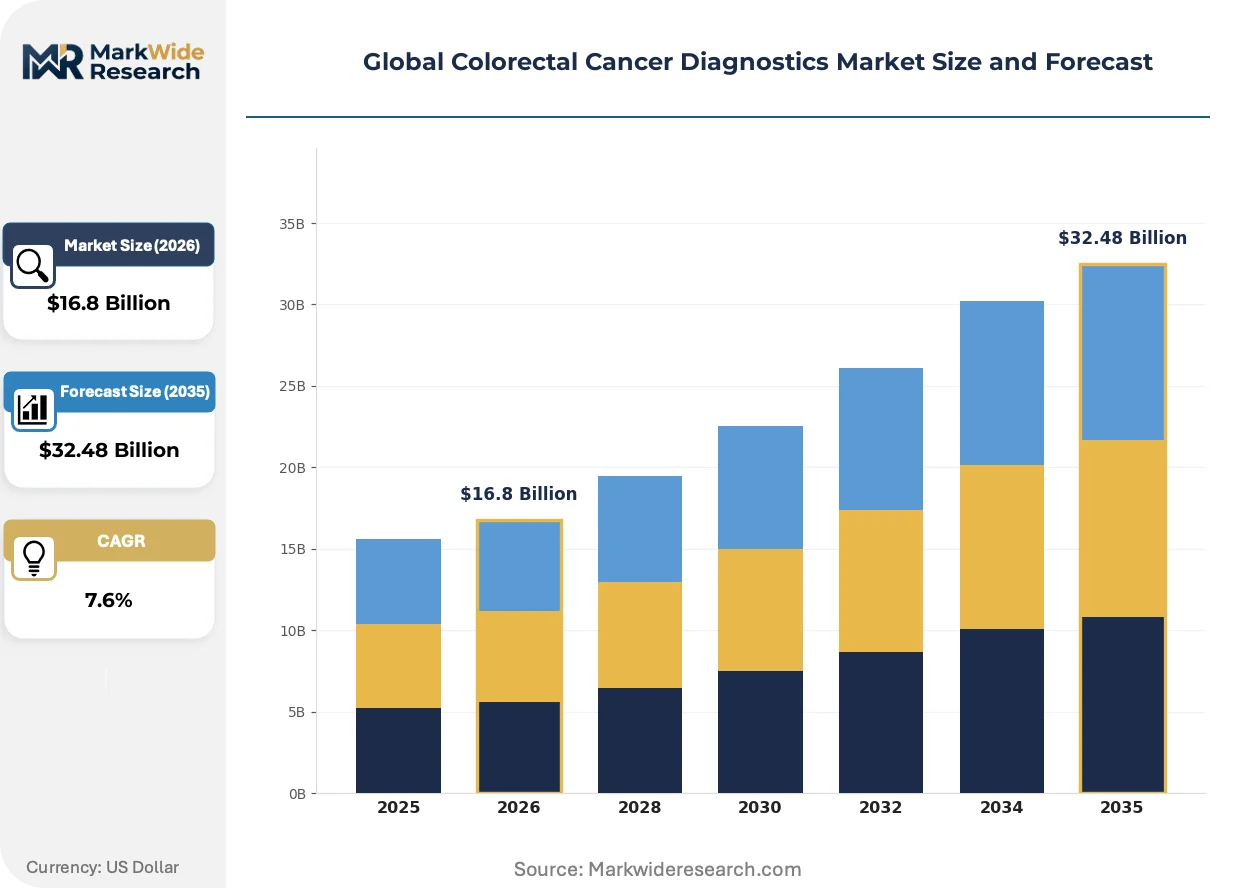
Market Dynamics
Reimbursement convergence between CMS and private payers on stool DNA and blood-based screening is compressing colonoscopy volume economics while redistributing margin pools toward molecular diagnostics platforms.
Growth Catalysts
- CMS National Coverage Determination:Medicare reimbursement for non-invasive colorectal cancer screening expands addressable patient populations beyond colonoscopy-accessible cohorts.
- Multi-cancer early detection panels:Blood-based liquid biopsy platforms achieve commercial validation for colorectal cancer signal detection alongside other malignancies.
- Japan:PMDA streamlined approval pathways for companion diagnostics accelerate biomarker-driven therapy selection in hospital-based oncology practices.
Market Restraints
- Reagent supply concentration:Polymerase chain reaction master mix production clusters with three contract manufacturers, exposing assay developers to input cost volatility.
- Colonoscopy substitution ceiling:Positive non-invasive screening mandates confirmatory endoscopy, creating workflow friction rather than full modality displacement.
- FDA premarket approval timelines:Blood-based screening assays face 18-24 month review cycles that compress commercialization windows against competitor entries.
Strategic Opportunities
- Germany:Federal Joint Committee reimbursement decisions pending for blood-based screening create first-mover positioning for validated assay submitters.
- Home collection logistics:Direct-to-consumer stool kit distribution bypasses clinical site bottlenecks and captures screening-hesitant populations.
- NGS-RAS convergence:Next-generation sequencing platforms integrate KRAS, NRAS, and BRAF profiling into single-workflow therapy selection panels.
Industry Challenges
- Bioinformatics specialist scarcity:Variant allele frequency interpretation below 0.1% sensitivity thresholds requires computational biology talent pools concentrated in Boston and San Diego metro areas.
- Laboratory Information System integration:Molecular diagnostics platforms face middleware compatibility gaps with legacy hospital electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Colorectal Cancer Diagnostics Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $32.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Molecular Diagnostics, Immunoassays, Imaging Diagnostics, Blood-Based Tests, Stool DNA Tests Application: Early Detection, Screening, Prognosis, Treatment Monitoring, Recurrence Detection End User: Diagnostic Laboratories, Research Institutes, Ambulatory Surgical Centers, Cancer Research Centers, Home Care Settings Technology: Polymerase Chain Reaction, Next Generation Sequencing, Fluorescence In Situ Hybridization, Immunohistochemistry, Mass Spectrometry |
| Companies Covered | FUJIFILM Holdings Corporation, Quest Diagnostics, Exact Sciences Corporation, Epigenomics AG, Mainz Biomed NV, Danaher Corporation, Olympus Corporation, Hologic Inc, Guardant Health, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Colorectal Cancer Diagnostics Market Shifts & Advancements
Colorectal cancer diagnostics is experiencing platform convergence where sequencing sensitivity advances and regulatory clarity on liquid biopsy standards are simultaneously expanding test menus and compressing reimbursement arbitrage between modalities.
Methylation-specific PCR for SEPT9 and NDRG4 biomarker detection is rendering obsolete single-marker fecal immunochemical tests in health system laboratory menus. Hospital-based pathology departments in the United States are adopting these multiplexed stool DNA panels at replacement pace for average-risk screening populations. The technology shift is compressing per-test reimbursement toward colonoscopy-equivalent economics while expanding screening compliance in previously non-adherent demographics.
EMA In Vitro Diagnostic Regulation implementation is forcing European molecular diagnostics manufacturers to recertify legacy assays under notified body supervision by 2026. The transition is consuming quality management resources and delaying new product introductions in Germany, France, and Italy. Smaller assay developers are responding by consolidating regulatory affairs functions and prioritizing CE-IVD submissions for highest-volume colorectal cancer screening SKUs.
Employer-sponsored wellness programs are contracting directly with national laboratory networks for annual colorectal cancer screening benefits, bypassing traditional physician referral channels. Large self-insured employers in the United States are negotiating capitated per-member-per-month rates that bundle stool DNA collection kits with compliance tracking. This channel innovation is most visible in Texas and California metropolitan markets where technology sector employers compete on preventive care coverage differentiation.
Global Colorectal Cancer Diagnostics Market Segmentation
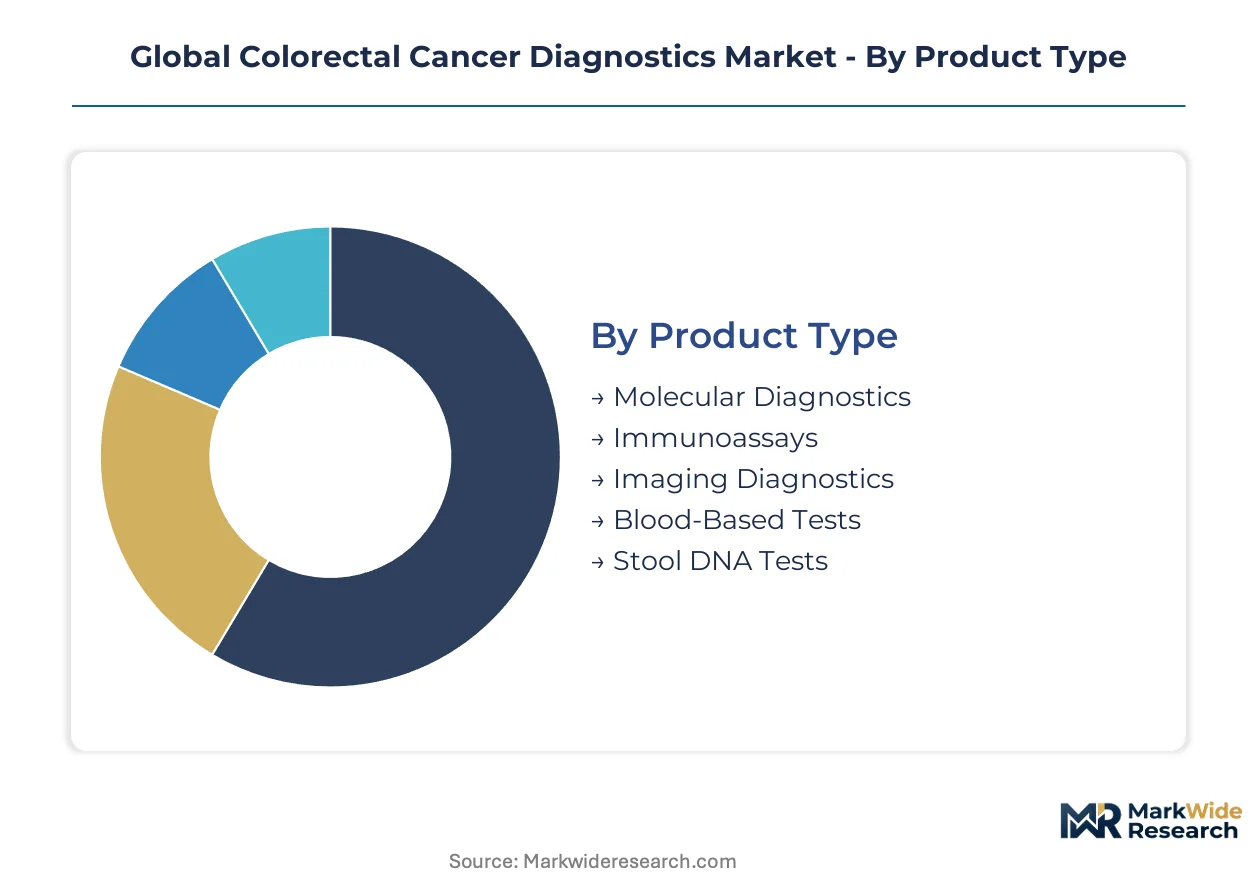
Segmentation in colorectal cancer diagnostics reveals how technology maturity, reimbursement pathways, and site-of-care economics partition revenue pools across molecular platforms, imaging modalities, and decentralized testing formats.
Product Type:
Mature platforms anchor current revenue while emerging formats capture growth from screening program expansion and liquid biopsy validation.
- Molecular Diagnostics:Polymerase chain reaction and next-generation sequencing platforms detect oncogenic mutations with variant allele frequency sensitivity below 0.1%. Hospital-based pathology departments in the United States and Germany concentrate demand as RAS profiling becomes mandatory for therapy selection.
- Stool DNA Tests:Methylation-specific PCR panels for SEPT9 and NDRG4 biomarkers multiplex detection beyond single-marker fecal immunochemical tests. CMS reimbursement decisions in the United States drive volume expansion among Medicare-aged populations.
- Immunoassays:Fecal immunochemical tests remain the workhorse for average-risk screening in cost-constrained health systems.
- Imaging Diagnostics:Computed tomography colonography and magnetic resonance imaging serve structural abnormality confirmation.
- Blood-Based Tests:Circulating tumor DNA assays are gaining regulatory traction as multi-cancer early detection panels expand colorectal cancer signal detection.
Molecular diagnostics handles the majority of throughput; blood-based tests are climbing the fastest on share.
Application:
Volume distribution tracks the patient journey from asymptomatic screening through surveillance monitoring, with reimbursement intensity varying sharply by clinical intent.
- Screening:Population-scale testing of asymptomatic average-risk adults dominates test volume. Japan's national screening program and Germany's Federal Joint Committee reimbursement decisions shape demand concentration.
- Early Detection:Symptomatic patient workups and positive screening follow-ups concentrate in hospital-based diagnostic laboratories. PMDA streamlined approval pathways in Japan accelerate companion diagnostic integration.
- Prognosis:Biomarker profiling for recurrence risk stratification supports adjuvant therapy decisions.
- Treatment Monitoring:Serial circulating tumor DNA measurement tracks therapeutic response and resistance emergence.
- Recurrence Detection:Post-treatment surveillance protocols drive periodic testing in oncology practices.
Screening commands the greatest test volume; early detection shows the steepest reimbursement expansion.
End User:
Site-of-care economics and sample logistics determine margin capture, with centralized laboratories maintaining scale advantages against decentralized alternatives.
- Diagnostic Laboratories:National laboratory networks and hospital-based pathology departments process high-throughput molecular testing. Quest Diagnostics and Exact Sciences leverage direct-to-physician channel control in the United States.
- Home Care Settings:Direct-to-consumer stool collection kits bypass clinical site visits and capture screening-hesitant populations. Employer-sponsored wellness programs in Texas and California metropolitan markets contract directly for annual screening benefits.
- Ambulatory Surgical Centers:Point-of-care testing supports pre-operative risk stratification.
- Cancer Research Centers:Academic medical centers drive biomarker discovery and clinical trial enrollment.
- Research Institutes:Preclinical and translational studies advance multi-cancer early detection panel validation.
Diagnostic laboratories retain the dominant throughput position; home care settings are expanding most quickly as logistics networks mature.
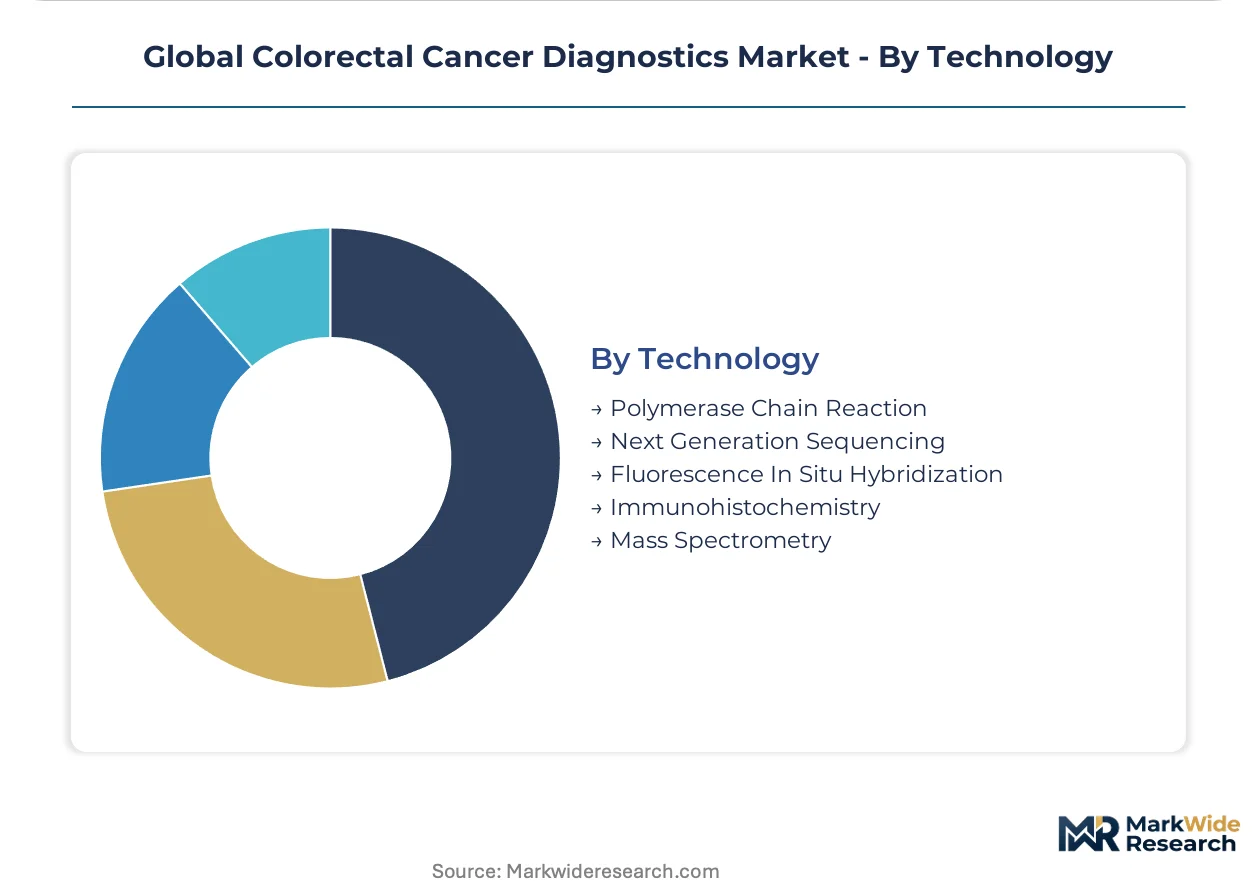
Technology:
Platform sophistication tiers separate research-grade sensitivity from routine clinical throughput, with workflow integration determining adoption velocity.
- Next Generation Sequencing:Parallel sequencing of multiple gene targets enables comprehensive RAS, BRAF, and Lynch syndrome profiling in single workflows. EMA In Vitro Diagnostic Regulation recertification requirements consume quality management resources through 2026.
- Polymerase Chain Reaction:Real-time quantitative methods remain the cost-optimized standard for single-gene mutation detection. Reagent supply concentration with three contract manufacturers exposes assay developers to input cost volatility.
- Immunohistochemistry:Protein expression analysis guides targeted therapy selection in solid tumor pathology.
- Fluorescence In Situ Hybridization:Chromosomal rearrangement detection supports HER2 and NTRK fusion assessment.
- Mass Spectrometry:Metabolomic and proteomic applications are emerging for biomarker discovery.
Polymerase chain reaction maintains the installed base; next generation sequencing shows the strongest share gain trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate limited price elasticity due to comprehensive reimbursement frameworks, while screening-hesitant populations in the United States and emerging markets exhibit higher sensitivity to out-of-pocket costs and access friction.
United States
Medicare-aged populations drive stool DNA test volume through CMS National Coverage Determination expansion. FDA premarket approval pathways for blood-based screening assays compress commercialization timelines against competitor entries. Boston and San Diego metro areas concentrate bioinformatics talent pools for variant allele frequency interpretation below 0.1% sensitivity thresholds.
Germany
Federal Joint Committee reimbursement decisions for blood-based screening create first-mover positioning for validated assay submitters. EMA In Vitro Diagnostic Regulation implementation forces molecular diagnostics manufacturers to recertify legacy assays under notified body supervision by 2026. Hospital-based pathology departments in Bavaria and North Rhine-Westphalia scale NGS panel deployment for Lynch syndrome profiling.
Japan
National screening program deepening drives demand concentration for non-invasive detection methods among asymptomatic average-risk adults. PMDA streamlined approval pathways for companion diagnostics accelerate biomarker-driven therapy selection in hospital-based oncology practices. Kanto and Kansai regions anchor molecular diagnostics platform adoption for RAS mutation profiling.
China
Expanding middle-class screening compliance creates addressable patient populations beyond colonoscopy-accessible cohorts. NMPA regulatory frameworks shape product development timelines for novel colorectal cancer assays entering the domestic market. Yangtze River Delta and Pearl River Delta clusters concentrate life sciences instrumentation supply and molecular diagnostics laboratory scale-up.
United Kingdom
NHS bowel cancer screening programme expansion redistributes test volume toward fecal immunochemical test and stool DNA modalities. MHRA convergence with EMA CE-IVD standards accelerates technology adoption timelines for European-cleared assays. London and Southeast England pathology networks integrate next-generation sequencing platforms for comprehensive RAS, BRAF, and Lynch syndrome profiling.
Global Colorectal Cancer Diagnostics Market Competitive Landscape
Capability concentration sits with specialized molecular diagnostics developers possessing multi-cancer early detection validation; scale advantage sits with national laboratory networks and diversified life sciences conglomerates. The competitive structure tiers across three archetypes: integrated diagnostic platform operators, specialized liquid biopsy developers, and instrumentation-and-consumables suppliers. Consolidation pressure runs through strategic partnerships between assay developers and distribution networks, plus technology licensing arrangements for biomarker detection methods.
Among diversified life sciences conglomerates, Danaher Corporation and FUJIFILM Holdings Corporation exemplify the instrumentation-and-consumables archetype through installed base leverage and recurring revenue pull-through. Exact Sciences Corporation occupies a specialized position representing the integrated diagnostic platform model anchored by CMS-backed screening franchise economics. Quest Diagnostics sits within the national laboratory network tier, sustaining broad geographic coverage through direct-to-physician channel control and employer-sponsored wellness program contracting.
| Leading Market Players |
|---|
| FUJIFILM Holdings Corporation |
| Quest Diagnostics |
| Exact Sciences Corporation |
| Epigenomics AG |
| Mainz Biomed NV |
| Danaher Corporation |
| Olympus Corporation |
| Hologic Inc |
| Guardant Health, Inc. |
| Others |
Supply & Pricing Matrix
Trans-Pacific air freight corridors connecting Shanghai Pudong and Memphis International anchor cost dynamics for temperature-controlled reagent shipments, with freight volatility amplifying margin compression for PCR master mix contract manufacturers while enabling price differentiation between hospital-based laboratories and direct-to-consumer kit distributors.
Pricing Analysis
Consumables pull-through revenue from sequencing reagents and assay kits drives lifetime value for instrumentation suppliers. Pricing stratifies across premium, standard, and economy tiers based on FDA premarket approval tier and laboratory accreditation status. Cost compression in fecal immunochemical tests is intensifying because methylation-specific PCR panels displace single-marker alternatives. Reference laboratories exhibit lowest price sensitivity due to CMS reimbursement anchoring; employer-sponsored wellness programs show highest sensitivity to per-member-per-month rate negotiations.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements between reagent contract manufacturers and molecular diagnostics platform operators. PCR master mix production clusters in the United States, Germany, and Singapore; plastic consumables fabrication feeds from Chinese injection molding specialists. Supply chains draw from fluorophore dyes, synthetic oligonucleotides, and medical-grade polypropylene as critical inputs. Single-source vulnerability concentrates in certified polymerase enzyme suppliers. Distribution runs through national laboratory networks and direct-to-physician channels for hospital-based pathology departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through FDA premarket approval and CMS National Coverage Determination creates defensive moats that compound over multi-year validation cycles, locking in incumbent positioning against emerging blood-based screening entrants.
For Market Incumbents: Pre-empt liquid biopsy substitution by accelerating SEPT9 and NDRG4 biomarker patent thickets around stool DNA multiplex panels. Secure backward integration into fluorophore dye supply through captive production facilities or exclusive offtake agreements with German and Singaporean chemical specialists. Channel control through direct-to-physician relationships remains the priority defensive lever against employer-sponsored wellness program disintermediation. For New Entrants and Emerging Players: Employer-sponsored wellness program penetration in Texas and California metropolitan markets represents the most penetrable white-space corridor for direct-to-consumer stool kit distribution. Federal Joint Committee reimbursement decisions pending in Germany create first-mover positioning for blood-based screening assay submitters with Asian population validation data. Go-to-market execution should prioritize capitated per-member-per-month contracting with self-insured technology sector employers. For Investors and Strategic Acquirers: Specialized liquid biopsy developers with multi-cancer early detection validation data represent the highest-conviction acquisition archetype for platform consolidation strategies. Long-term viability hinges on regulatory convergence between FDA and EMA on liquid biopsy screening standards versus confirmatory diagnostic use boundaries. Monitor PMDA streamlined approval pathway utilization rates in Japan's Kanto and Kansai regions as inflection indicator for biomarker-driven therapy selection adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | CMS reimbursement eligibility unlocks Medicare-aged population access for stool DNA franchises. |
| CE-IVD Recertification Under EMA IVDR | Notified body supervision by 2026 consumes quality management resources for European manufacturers. |
| Hospital System Partnership | Direct-to-physician channel control secures high-throughput molecular diagnostics placement. |
| Software Companion Development | Bioinformatics platforms for variant allele frequency interpretation address specialist scarcity in Boston and San Diego. |
| Reimbursement Strategy | Federal Joint Committee submissions in Germany and CMS National Coverage Determination expansions shape volume economics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital pathology directors, molecular diagnostics laboratory managers, regulatory affairs specialists at assay developers, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, EMA CE-IVD registration databases, CMS Medicare coverage determinations, and hospital procurement contract repositories. Bottom-up test volume modeling triangulated against top-down market sizing from instrument installed base estimates and reagent consumption rates.
Calibration against historical reimbursement decision timelines and technology adoption curves shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application, end user, technology platform, and regional regulatory cluster. CAGRs were derived from test volume elasticity to screening program expansion and pricing trajectory assumptions for liquid biopsy versus stool DNA modalities. Forecast inputs incorporated PMDA approval pathway velocity and employer-sponsored wellness program penetration rates.
Practitioners should monitor EMA IVDR implementation delays, CMS blood-based screening coverage decisions, and PCR master mix supply disruptions for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Nitric Oxide Asthma Testing Market
Clinical Diagnostics
Pediatric Cardiac Tumor Diagnostics Market
Clinical Diagnostics
Antenatal Screening Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Cardiology Genomic Testing Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Kidney Function Tests Market
Clinical Diagnostics
Global Monocyte Activation Tests Market