
 Pediatric Cardiac Tumor Diagnostics Market | 2026-2036
Pediatric Cardiac Tumor Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Cardiac Tumor Diagnostics Market Analytics
Asset-light leasing models for advanced imaging systems is narrowing the competitive field to operators with strong balance-sheet capacity. Siemens Healthineers AG leverages its installed base of cardiovascular MRI platforms to sustain recurring service revenue across pediatric centers. General Electric HealthCare anchors its position through proprietary contrast-agent protocols optimized for low-body-weight patients. Koninklijke Philips N.V. differentiates via integrated echocardiography workstations that streamline workflow in busy pediatric cardiology units.
Pediatric cardiac tumor diagnostics encompasses non-invasive and invasive procedures for detecting and characterizing neoplastic growths in the hearts of patients under eighteen years of age, employing modalities that resolve structures below five millimeters while minimizing radiation exposure. Echocardiography serves as the frontline screening tool due to its portability and absence of ionizing radiation, though MRI gains ground where tissue characterization demands superior soft-tissue contrast. Diagnostic laboratories represent a growing revenue pocket as centralized processing of cardiac biomarker panels reduces per-test costs for low-volume pediatric indications. Software solutions embedding AI-assisted image analysis command premium positioning by shortening interpretation time for non-specialist radiologists.
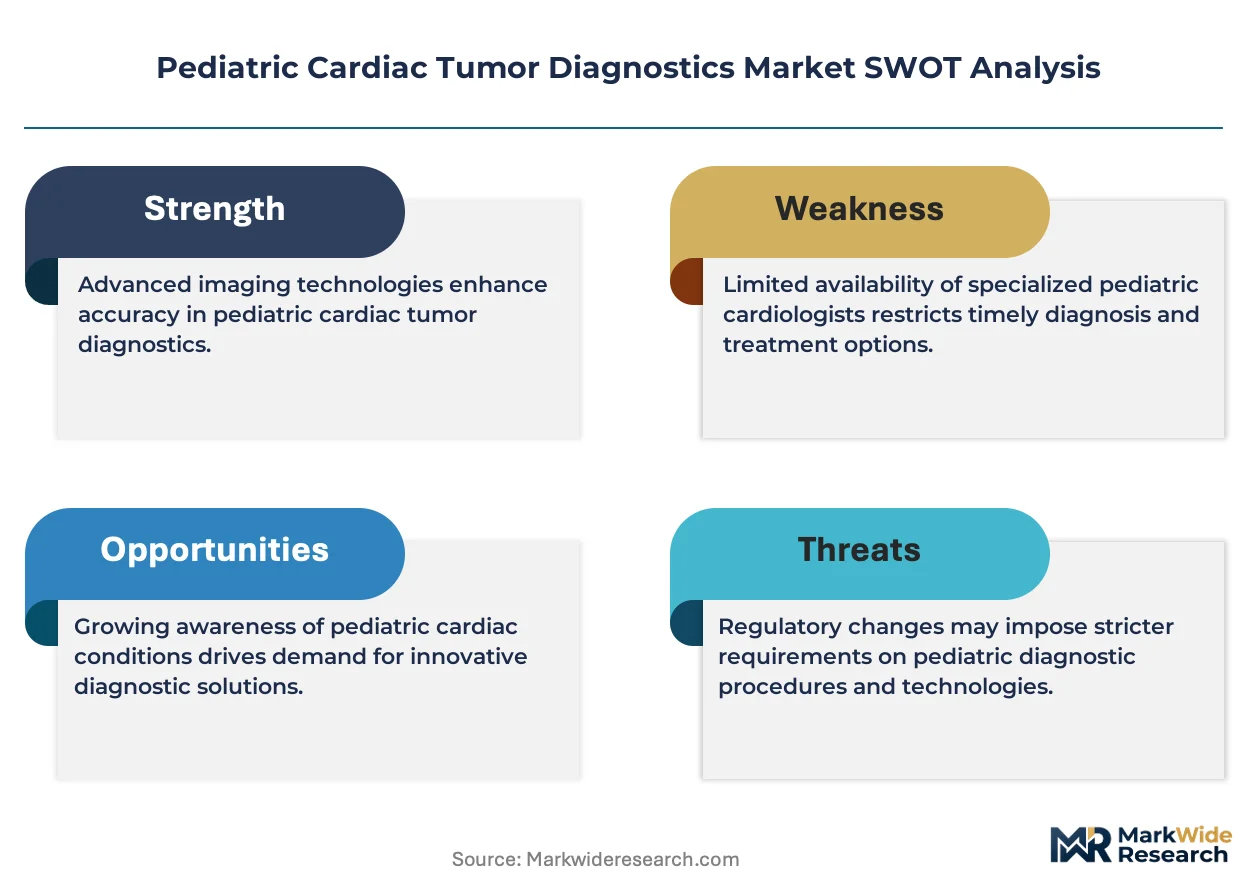
FDA premarket notification requirements and EMA medical device regulation frame clinical evidence thresholds for pediatric-specific labeling, directly shaping trial design and commercialization sequencing. ISO 13485 quality management standards govern manufacturing consistency across imaging agents and diagnostic kits, creating compliance barriers for new entrants lacking established quality systems. Stakeholders must weigh capital deployment toward hybrid imaging platforms against point-of-care biopsy innovations as reimbursement pathways for each modality diverge under shifting payer priorities.
Market Dynamics
AI-assisted echocardiography workstations are compressing interpretation timelines at tertiary pediatric centers, forcing incumbents to restructure service contracts around throughput guarantees rather than hardware leasing alone.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways for pediatric-specific cardiac MRI sequences are shortening commercialization timelines by 12-18 months for qualifying platforms.
- Centralized Biomarker Processing:Diagnostic laboratories in the United States are consolidating low-volume pediatric cardiac tumor panels, achieving per-test cost reductions that expand access to underserved referral networks.
- Contrast-Agent Optimization:Gadolinium-based formulations calibrated for neonatal renal clearance profiles are extending safe imaging windows to patients below 10 kilograms.
Market Restraints
- Helium Supply Concentration:Qatar and the United States control over 80% of global helium production, exposing MRI operators to price volatility for magnet cooling systems.
- Pediatric-Specific Labeling Requirements:EMA Medical Device Regulation mandates discrete clinical evidence for under-18 populations, doubling trial costs versus adult-equivalent submissions.
- Tissue Biopsy Substitution:Liquid biopsy platforms targeting circulating tumor DNA are capturing differential diagnosis cases previously referred to invasive cardiac catheterization.
Strategic Opportunities
- Telemedicine Integration:Remote echocardiography interpretation networks are penetrating rural India and Brazil, where pediatric cardiologist density falls below 0.5 per 100,000 children.
- Hybrid PET-MRI Deployment:Combined metabolic and anatomical imaging is opening staging protocols for rhabdomyomas and fibromas previously requiring sequential studies.
- PLI Scheme Alignment:India's production-linked incentive framework for medical electronics is attracting component manufacturing for portable ultrasound systems.
Industry Challenges
- Pediatric Radiologist Training Bottlenecks:Fellowship programs producing dual-certified cardiothoracic imagers number fewer than 15 annually across the United States, constraining throughput at expansion-stage centers.
- Legacy PACS Integration:AI-enabled workstations require DICOM conformance layers that 40% of installed pediatric cardiology IT infrastructures cannot support without middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Cardiac Tumor Diagnostics Market |
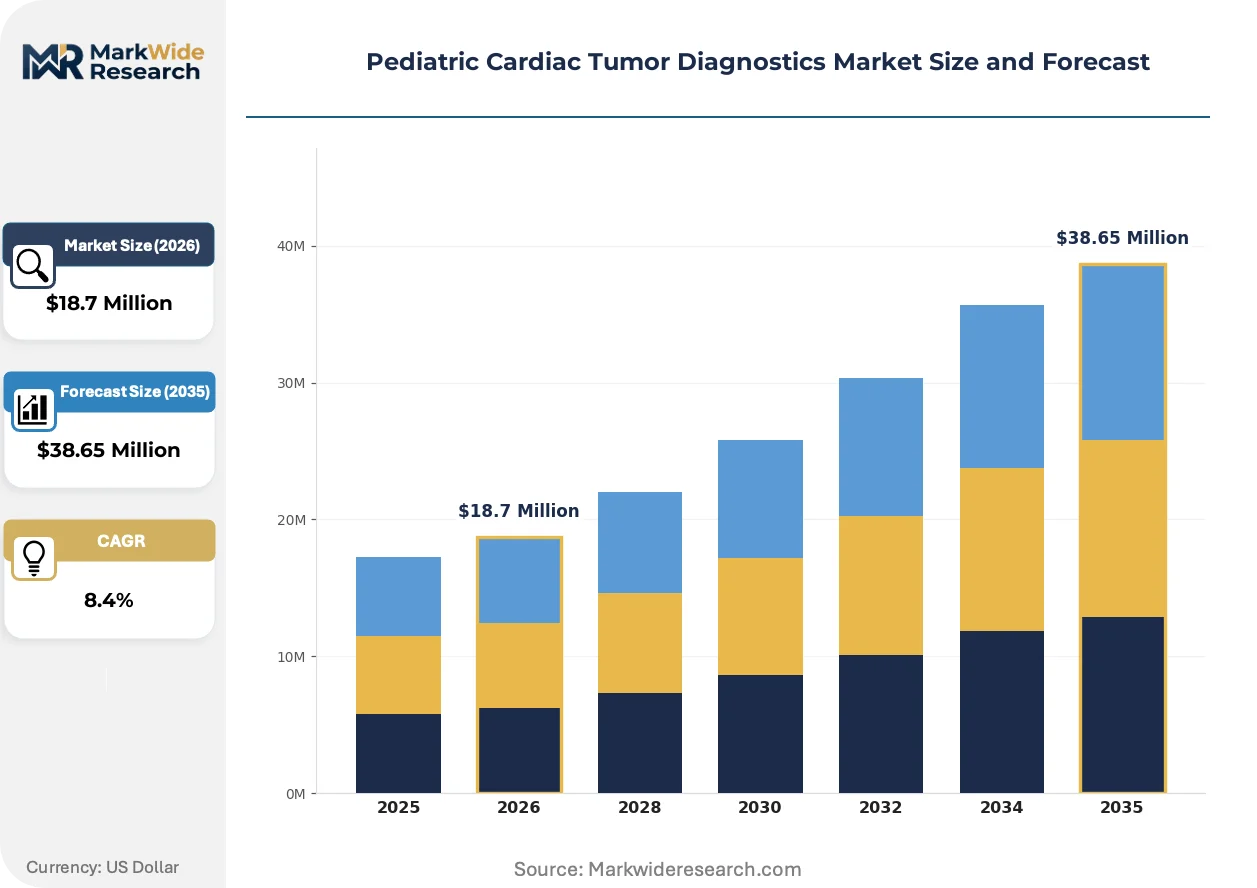
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $38.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Diagnostic Method: Echocardiography, MRI, CT Scan, Biopsy End User: Pediatric Hospitals, Cardiology Clinics, Research Institutions, Diagnostic Laboratories Product Type: Imaging Agents, Diagnostic Kits, Monitoring Equipment, Software Solutions Therapy Area: Oncology, Cardiology, Pediatric Medicine, Radiology |
| Companies Covered | General Electric HealthCare, Siemens Healthineers AG, Koninklijke Philips N.V., Canon Medical Systems Corporation, Abbott Laboratories, F. Hoffmann-La Roche Limited, Medtronic Public Limited Company, Boston Scientific Corporation, Lantheus Holdings Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Cardiac Tumor Diagnostics Market Evolving Landscape
Workflow automation and radiation-sparing protocols are redrawing capital allocation priorities across pediatric cardiac imaging departments, with software-enabled differentiation now matching hardware specifications in procurement evaluations.
Real-time three-dimensional echocardiography is migrating from research applications to standard-of-care protocols at congenital heart centers. Pediatric cardiologists at Boston Children's Hospital and similar institutions now deploy volumetric rendering for pre-surgical planning in 60% of cardiac tumor cases. The technology is migrating from high-cost MRI referrals toward frontline characterization, compressing diagnostic timelines from days to hours while preserving magnet capacity for complex tissue differentiation.
EMA Medical Device Regulation Article 61 is tightening clinical evidence requirements for pediatric orphan indications, forcing manufacturers to pool multi-site European data rather than relying on US-derived submissions. Device sponsors now face mandatory pediatric investigation plans before CE marking, with notified bodies demanding age-stratified safety cohorts. German and French regulatory consultants report 25% longer preparation cycles for cardiac imaging agents targeting under-five populations.
Academic medical centers are consolidating purchasing authority through shared service organizations, stripping individual hospitals of autonomous capital budgeting for imaging platforms. The University of California health system and similar entities now negotiate enterprise-wide MRI and echocardiography contracts, replacing equipment-by-equipment procurement. This concentration is most visible in the United States, where pediatric cardiology networks spanning 10+ facilities extract 15-20% price concessions from vendors seeking installed-base expansion.
Pediatric Cardiac Tumor Diagnostics Market Segmentation
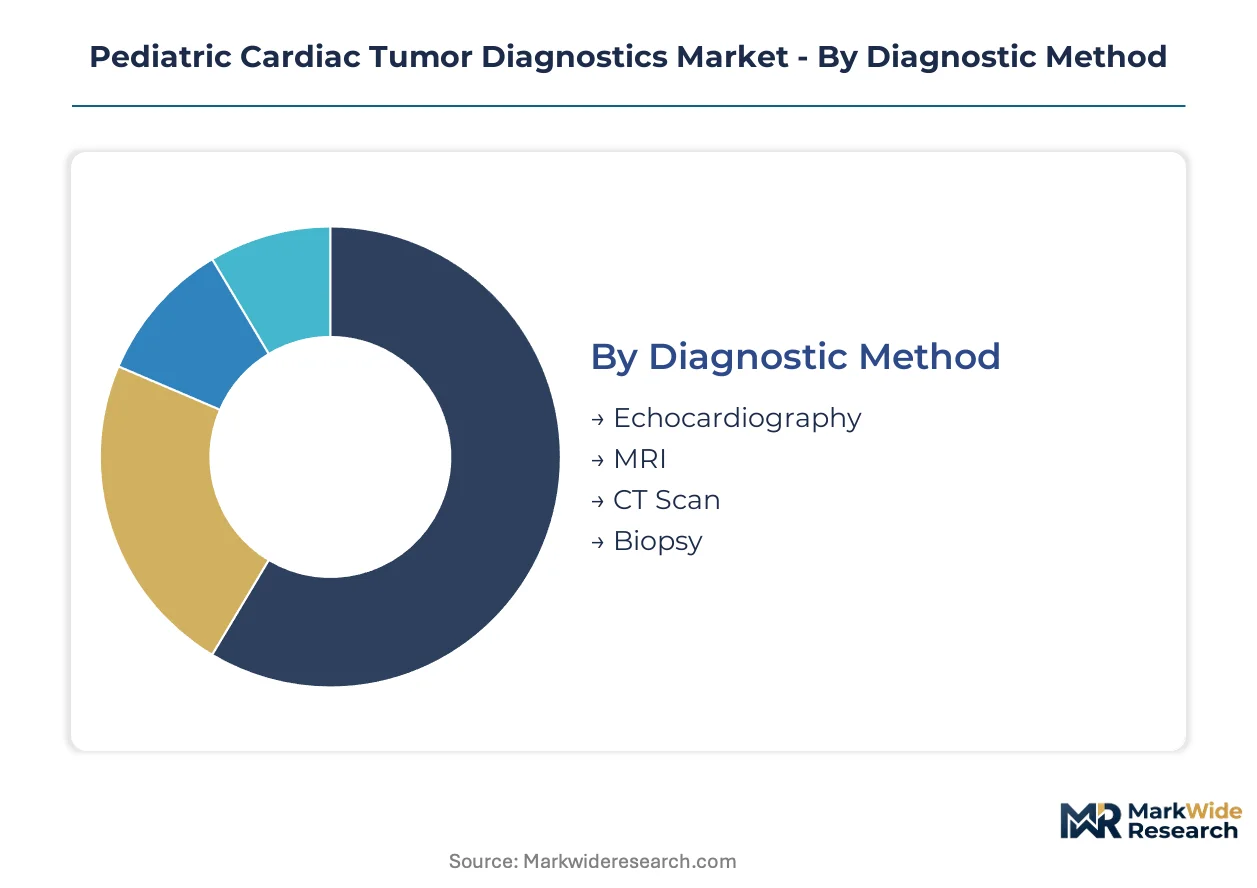
Pediatric cardiac tumor diagnostics fragment across four structural dimensions that reshape procurement patterns and vendor positioning. Each category carries distinct margin profiles, regulatory burdens, and concentration dynamics that determine competitive outcomes.
Diagnostic Method:
Cost tier stratification separates frontline screening from advanced tissue characterization, with capital intensity and reimbursement rates diverging sharply across modalities.
- Echocardiography:Portable ultrasound systems without ionizing radiation dominate initial screening protocols. Demand concentrates at tertiary pediatric centers in the United States where throughput requirements justify dedicated cardiac imaging suites. Workflow automation and AI-assisted interpretation are compressing radiologist labor costs per study.
- MRI:Magnetic resonance platforms deliver superior soft-tissue contrast for tumor characterization below five millimeters. Adoption accelerates where gadolinium-based agents have secured neonatal renal clearance labeling, extending safe imaging windows to patients below 10 kilograms. Helium supply concentration from Qatar and the United States creates operational cost volatility for magnet cooling systems.
- CT Scan:Computed tomography retains niche application for emergency staging where MRI access is constrained. Radiation exposure limits restrict repeat studies in this population.
- Biopsy:Invasive tissue sampling faces substitution pressure from liquid biopsy platforms targeting circulating tumor DNA. Cardiac catheterization laboratories maintain procedural volume for histopathological confirmation.
Echocardiography holds installed capacity. MRI is rotating up the share rankings.
End User:
Customer type determines contract structure, with consolidated purchasing authority stripping individual facilities of autonomous capital budgeting.
- Pediatric Hospitals:Congenital heart centers anchor demand for integrated imaging platforms capable of pre-surgical volumetric rendering. Enterprise-wide contracts spanning 10+ facilities now extract 15-20% price concessions from vendors.
- Cardiology Clinics:Outpatient settings prioritize portable ultrasound systems and remote interpretation networks. Telemedicine integration is penetrating rural India and Brazil where pediatric cardiologist density falls below 0.5 per 100,000 children.
- Research Institutions:Academic medical centers drive protocol development for hybrid PET-MRI staging and real-time three-dimensional echocardiography applications.
- Diagnostic Laboratories:Centralized biomarker processing achieves per-test cost reductions for low-volume pediatric cardiac tumor panels, expanding access to underserved referral networks.
Pediatric hospitals command volume concentration. Diagnostic laboratories are climbing the fastest.
Product Type:
Margin structure varies with regulatory pathway complexity, from commoditized hardware to software-enabled premium positioning.
- Imaging Agents:Gadolinium formulations and specialized contrast media require pediatric-specific labeling under EMA Medical Device Regulation Article 61. Age-stratified safety cohorts extend preparation cycles by 25% for under-five indications.
- Diagnostic Kits:Biomarker panels for cardiac tumor markers consolidate processing at reference laboratories to achieve scale economies.
- Monitoring Equipment:Echocardiography workstations and MRI platforms compete on throughput guarantees rather than hardware leasing alone.
- Software Solutions:AI-assisted image analysis commands premium positioning by shortening interpretation time for non-specialist radiologists. DICOM conformance requirements exclude 40% of legacy pediatric cardiology IT infrastructures without middleware investment.
Monitoring equipment holds installed base. Software solutions are gaining share fastest.
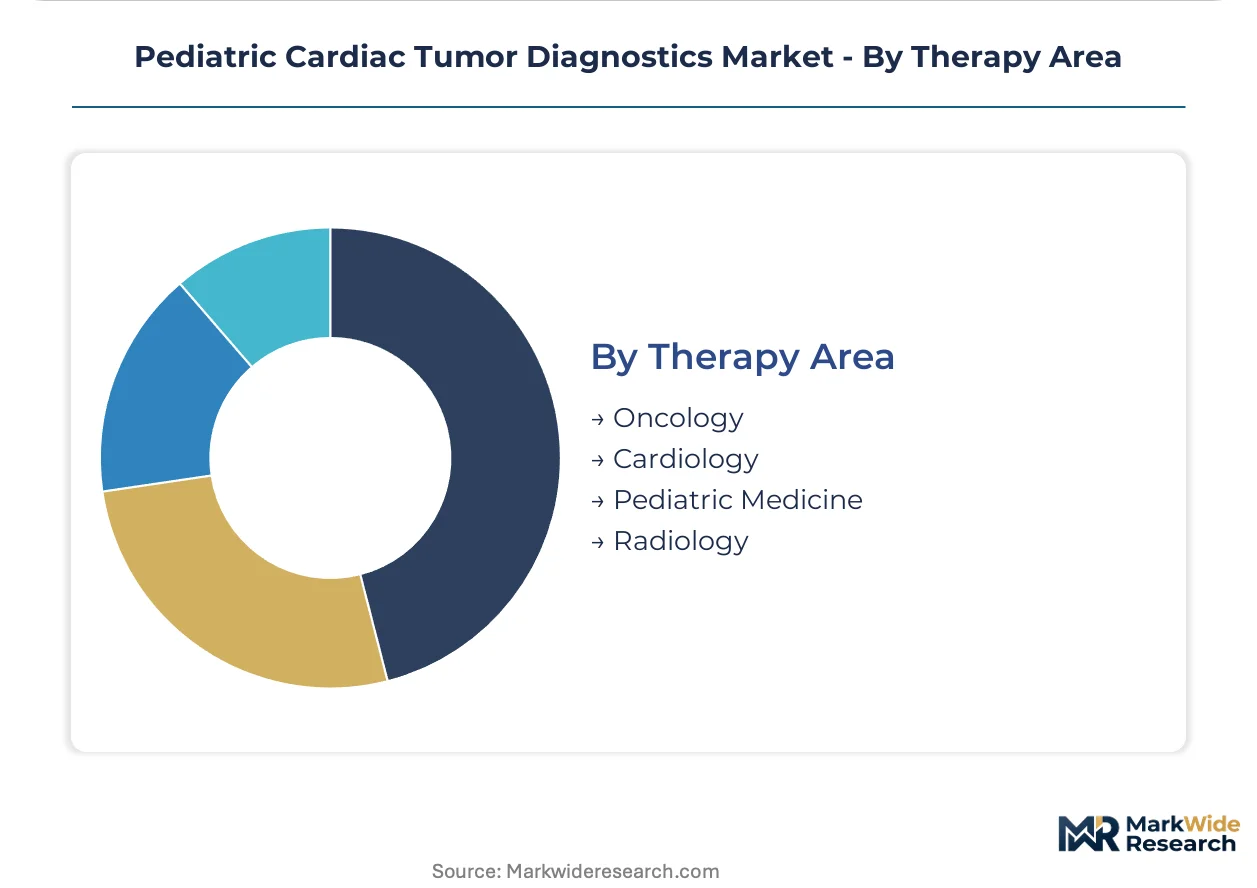
Therapy Area:
Application focus determines clinical evidence requirements and referral pathway integration.
- Oncology:Tumor staging protocols drive demand for hybrid imaging combining metabolic and anatomical resolution. Rhabdomyoma and fibroma characterization previously requiring sequential studies now consolidate to single-session PET-MRI.
- Cardiology:Congenital heart programs deploy volumetric rendering for pre-surgical planning in the majority of cardiac tumor cases. Boston Children's Hospital and peer institutions have compressed diagnostic timelines from days to hours.
- Pediatric Medicine:General pediatric services rely on frontline echocardiography screening with MRI referral for complex tissue differentiation.
- Radiology:Dual-certified cardiothoracic imagers number fewer than 15 annually across United States fellowship programs, constraining throughput at expansion-stage centers.
Cardiology anchors procedural volume. Oncology is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Referral networks for rare pediatric cardiac conditions concentrate demand in tertiary centers with advanced imaging suites. The United States anchors installed capacity for cardiac MRI platforms, while Germany and Japan sustain specialized manufacturing ecosystems. Emerging markets in India and Brazil are penetrating rural geographies through telemedicine-integrated networks.
United States
Pediatric hospitals with congenital heart programs drive procurement of hybrid PET-MRI systems for tumor staging protocols. FDA breakthrough device designation compresses review timelines for neonatal-optimized contrast agents by 12-18 months. Boston Children's Hospital and peer institutions in the Northeast corridor deploy real-time three-dimensional echocardiography for pre-surgical planning in the majority of cardiac tumor cases.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia consolidate purchasing authority through shared service organizations spanning 10+ facilities. EMA Medical Device Regulation Article 61 mandates discrete pediatric investigation plans before CE marking, extending preparation cycles for under-five indications. Siemens Healthineers AG leverages its cardiovascular MRI installed base across university hospitals in Baden-Württemberg to sustain recurring service revenue.
Japan
PMDA pediatric-specific labeling requirements shape clinical trial design for gadolinium-based agents calibrated for low-body-weight patients. METI funding for rare disease diagnostics supports development of AI-assisted echocardiography workstations at research institutions in the Kanto region. Tokyo-based congenital heart centers anchor demand for integrated imaging platforms capable of sub-five-millimeter resolution.
India
Telemedicine integration penetrates rural referral networks where pediatric cardiologist density falls below 0.5 per 100,000 children. The PLI scheme for medical electronics attracts component manufacturing for portable ultrasound systems to Karnataka and Tamil Nadu. Diagnostic laboratories in Maharashtra consolidate low-volume cardiac biomarker panels to achieve per-test cost reductions for underserved populations.
Brazil
Cardiology clinics in São Paulo and Rio de Janeiro prioritize portable ultrasound systems with remote interpretation capabilities. ANVISA regulatory pathways for pediatric orphan indications require age-stratified safety cohorts that extend submission preparation. Research institutions in Minas Gerais drive protocol development for non-invasive tumor characterization methods that minimize radiation exposure in repeat studies.
Pediatric Cardiac Tumor Diagnostics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Consolidated purchasing authority at academic medical center networks has compressed vendor margins by 15-20% at the enterprise-contract tier. Diversified imaging conglomerates, specialized diagnostic laboratories, and AI-enabled software developers represent the dominant strategic archetypes. Competitive moves concentrate on restructuring service contracts around throughput guarantees and securing proprietary contrast-agent formulations for low-body-weight populations.
Among diversified imaging conglomerates, General Electric HealthCare, Siemens Healthineers AG, and Koninklijke Philips N.V. occupy positions defined by installed-base scale and recurring revenue from cardiovascular MRI platforms. These manufacturers exemplify the channel-control archetype through enterprise-wide contracts that replace equipment-by-equipment procurement at multi-facility pediatric networks. Their positioning reflects balance-sheet capacity for asset-light leasing models that narrow the competitive field to operators capable of sustaining long-term service relationships.
| Leading Market Players |
|---|
| General Electric HealthCare |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Abbott Laboratories |
| F. Hoffmann-La Roche Limited |
| Medtronic Public Limited Company |
| Boston Scientific Corporation |
| Lantheus Holdings Incorporated |
| Others |
Value Network & Pricing Analysis
Qatar's helium production clusters anchor magnet cooling costs for MRI platforms worldwide, with downstream pricing power flowing directly to imaging system operators who can secure long-term offtake agreements. This concentration creates asymmetric cost pass-through dynamics where pediatric centers lacking procurement scale absorb volatility that consolidated health systems negotiate away.
Pricing Analysis
Cost-plus contracts with helium indexation dominate MRI service agreements, binding pediatric hospitals to pricing that fluctuates with Qatari supply quotas and US strategic reserve releases. Price differentiation rests on after-sales service bundling and ISO 13485 certification tier, with premium tiers capturing enterprise-wide contracts. Cost compression in the mid-market intensifies as diagnostic laboratories consolidate biomarker panels and extract volume discounts. Cardiology clinics in rural referral networks exhibit highest price sensitivity, while congenital heart centers with hybrid PET-MRI requirements show lowest elasticity due to procedural dependency.
Supply Chain Analysis
Contract manufacturing for portable ultrasound systems concentrates in Karnataka and Tamil Nadu under India's PLI scheme, with final assembly tethered to German and Japanese precision component suppliers. Gadolinium-based contrast agents draw from Chinese and US pharmaceutical manufacturing bases, while helium extraction remains concentrated in Qatar and the US. Single-source vulnerability in magnet cooling systems exposes operators to supply disruption from geopolitical events or export quota adjustments. Distribution runs through medical device distributors with GPO contracts at academic medical center networks, replacing direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market, with AI-assisted echocardiography penetration still below 40% at community pediatric centers despite proven throughput gains at tertiary institutions.
For Market Incumbents: Entrench installed-base positions by converting hardware leases to throughput-guaranteed service contracts that lock out substitution from liquid biopsy platforms. Deepen backward integration into gadolinium formulation production to capture margin from neonatal-optimized contrast agents. Prioritize DICOM conformance middleware investments that exclude AI-enabled competitors from legacy PACS integrations at expansion-stage centers. For New Entrants and Emerging Players: Pursue telemedicine-integrated remote interpretation networks in rural India and Brazil, where pediatric cardiologist scarcity creates immediate addressable demand. Target diagnostic laboratories consolidating low-volume cardiac biomarker panels, as these facilities lack in-house imaging expertise and seek software companions. Deploy SaaS-tiered pricing with per-study economics that undercuts capital-intensive hardware procurement. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified imaging conglomerates seeking to divest non-core pediatric portfolios, particularly software divisions with FDA breakthrough device designations but limited commercial infrastructure. Five-to-ten year viability hinges on reimbursement pathway capture for AI-assisted interpretation. Monitor FDA pediatric investigation plan submission volumes as inflection indicator for regulatory pathway clarity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review compresses commercialization timelines for neonatal-optimized MRI sequences by 12-18 months. |
| Hospital System Partnership | Enterprise-wide contracts spanning 10+ facilities extract 15-20% price concessions from imaging vendors. |
| Software Companion Development | AI-assisted image analysis commands premium positioning by shortening interpretation time for non-specialist radiologists. |
| CE Marking Pathway | EMA Article 61 mandates discrete pediatric investigation plans that extend preparation cycles for under-five indications. |
| Reimbursement Strategy | Centralized biomarker processing at diagnostic laboratories achieves per-test cost reductions for underserved referral networks. |
Research Methodology
Operator-level perspectives from pediatric cardiologists, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, EMA pediatric investigation plan submissions, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up demand modeling triangulated against top-down market sizing across diagnostic method, end user, and product type dimensions.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation modeling spanning diagnostic modality, customer facility type, product category, and therapy area. CAGRs derived from logistic diffusion curves fitted to adoption data for AI-assisted workstations and hybrid imaging platforms. Industry-specific inputs included helium price volatility indices, pediatric cardiologist fellowship graduation rates, and telemedicine reimbursement policy trajectories.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles or rare disease research funding allocations would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway timelines and contrast agent safety labeling progressions. Quarterly review of FDA breakthrough device designation grants and EMA notified body pediatric submission volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Global Hepatitis C Testing Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Kidney Function Tests Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
Chronic Hepatitis B Virus Testing Market
Clinical Diagnostics
Preimplantation Genetic Testing Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Angiogenesis Assays Market
Clinical Diagnostics
Food Allergy Diagnosis and Treatment Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market