
 Colorectal Cancer Screening Market | 2026-2036
Colorectal Cancer Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Colorectal Cancer Screening Market Intelligence
US-based molecular diagnostics manufacturers is repositioning production capacity toward next-generation sequencing platforms for colorectal cancer detection. Exact Sciences Corporation leverages its integrated lab services model to sustain high-throughput processing volumes for stool DNA assays. Guardant Health competes through liquid biopsy technology leadership, while Quest Diagnostics anchors its position through nationwide phlebotomy network access and payer contracts.
Colorectal cancer screening encompasses diagnostic and surveillance modalities designed to detect adenomatous polyps or malignant lesions in the large intestine and rectum, employing fecal occult blood detection, endoscopic visualization, radiographic imaging, or molecular biomarker analysis with sensitivity thresholds typically exceeding 90 percent for advanced neoplasia. The primary purpose is reducing mortality through early-stage detection when surgical intervention achieves curative outcomes. Fecal Immunochemical Test occupies the highest volume tier among screening test types due to low cost and broad primary care deployment, while Stool DNA Test captures expanding margin pools as commercial laboratories integrate epigenetic biomarker panels. Artificial Intelligence applications in optical imaging represent the fastest-growing technology segment, with computer-aided polyp detection systems gaining regulatory clearances and clinical validation.
FDA premarket approval requirements and Clinical Laboratory Improvement Amendments standards govern test accuracy claims and laboratory certification, directly shaping market access timelines and commercialization costs for new entrants. The EU Medical Device Regulation and In Vitro Diagnostic Regulation impose conformity assessment burdens that favor established manufacturers with notified body relationships and quality management systems. Stakeholders must monitor reimbursement determinations from CMS and private payers for emerging blood-based screening modalities, as coverage decisions will determine whether these technologies displace established stool and endoscopic protocols or expand the screened population.
Market Dynamics
FDA clearance pathways for blood-based multi-cancer detection assays are compressing commercialization timelines and forcing established stool DNA and endoscopic screening providers to accelerate biomarker platform investments. This regulatory acceleration is redrawing competitive boundaries between liquid biopsy developers and traditional fecal testing laboratories.
Growth Catalysts
- Medicare reimbursement expansion:CMS coverage determinations for non-invasive colorectal screening modalities are extending patient access beyond colonoscopy-dependent populations. Rural and underserved demographics gain screening entry points through stool-based and blood-based alternatives.
- Epigenetic biomarker advancement:Methylation panel sensitivity improvements for stool DNA assays are narrowing the performance gap with optical colonoscopy. Clinical validation studies demonstrating 90-plus percent detection rates for advanced neoplasia are accelerating physician acceptance.
- Commercial payer contract expansion:UnitedHealth, Anthem, and Aetna are adding blood-based screening to preventive care benefit tiers. Employer-sponsored health plans are driving volume through wellness program integration and zero-cost-sharing designs.
Market Restraints
- Colonoscopy capacity constraints:Gastroenterologist supply shortages in the United States are creating procedure backlogs exceeding 12 weeks in metropolitan markets. This bottleneck limits surveillance follow-through for positive non-invasive screening results.
- Reagent supply concentration:Nucleic acid extraction chemistries and polymerase enzyme production concentrate among three global suppliers. Pandemic-era supply chain disruptions exposed vulnerability in high-throughput laboratory operations.
- False-positive rate burden:Stool DNA and blood-based assays generate 10-15 percent positive predictive values requiring diagnostic colonoscopy confirmation. This cascade imposes cost and capacity burdens on already constrained endoscopy services.
Strategic Opportunities
- Average-risk population expansion:Lowering screening initiation age to 45 under USPSTF guidelines is adding 20 million Americans to eligible cohorts. Laboratories can capture this volume through primary care channel partnerships and direct-to-consumer marketing.
- AI-augmented colonoscopy:Computer-aided polyp detection systems from Medtronic and Olympus are reducing adenoma miss rates. Integration with standard endoscopy platforms creates service revenue streams for device manufacturers.
- Multi-cancer early detection convergence:Blood-based assays targeting colorectal, lung, and pancreatic malignancies simultaneously are entering clinical trials. Single-draw screening panels could displace organ-specific testing protocols and expand total addressable market.
Industry Challenges
- Bioinformatics talent scarcity:Computational biology and machine learning expertise for variant interpretation and assay optimization commands premium compensation. Academic pipelines are not producing sufficient PhD-level analysts for commercial laboratory demand.
- CLIA certification timelines:Laboratory-developed test validation and state licensing processes extend 18-24 months for novel biomarker platforms. This duration compresses effective patent life and delays revenue recognition for development-stage companies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colorectal Cancer Screening Market |
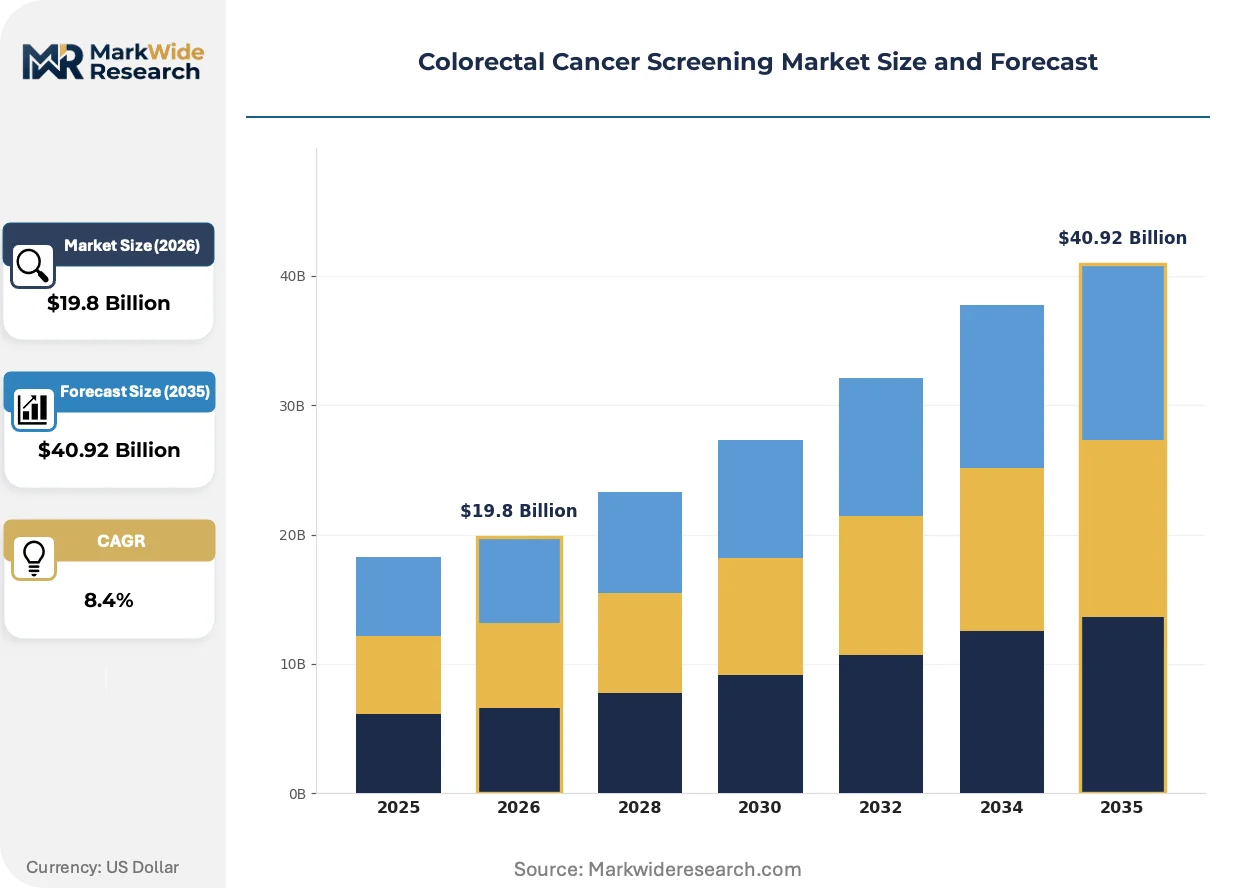
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $40.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Screening Test Type: Colonoscopy, Fecal Immunochemical Test, Stool DNA Test, Flexible Sigmoidoscopy, CT Colonography Screening Setting: Clinics, Diagnostic Centers, Ambulatory Surgical Centers, Mobile Screening Units End User: Hospitals, Specialist Clinics, Primary Care Providers, Cancer Research Institutes Technology: Optical Imaging, Biomarker Detection, Artificial Intelligence, Molecular Diagnostics, Non-invasive Testing |
| Companies Covered | Exact Sciences Corporation, Olympus Corporation, Quest Diagnostics, Fujifilm Holdings Corporation, Danaher Corporation, Guardant Health, Abbott Laboratories, Epigenomics AG, Clinical Genomics Technologies Pty Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colorectal Cancer Screening Market Strategic Shifts & Innovations
Artificial intelligence applications are penetrating every screening modality from image interpretation to risk stratification, compressing the gap between non-invasive and invasive detection performance. This technological convergence is enabling new competitive entry points for software-native diagnostics developers.
Multi-omics biomarker platforms combining circulating tumor DNA, protein, and metabolite signatures are consolidating the fragmented early-detection landscape into integrated screening solutions. Academic medical centers and commercial laboratories are adopting these panels for high-risk patient stratification. The technology is consolidating vendor relationships around platforms capable of simultaneous multi-cancer signal detection.
FDA breakthrough device designation pathways are accelerating premarket review timelines for blood-based colorectal screening assays. This regulatory efficiency is compressing the commercialization gap between proof-of-concept and Medicare coverage determination. Liquid biopsy developers are responding by front-loading clinical validation investments to secure parallel payer engagement.
Employer-sponsored health plans are unbundling preventive screening from traditional medical benefit administration. Large self-insured corporations are contracting directly with laboratory networks for workforce screening programs, bypassing health plan intermediaries. This channel shift is most visible in technology and financial services sectors with concentrated white-collar populations.
Colorectal Cancer Screening Market Segmentation
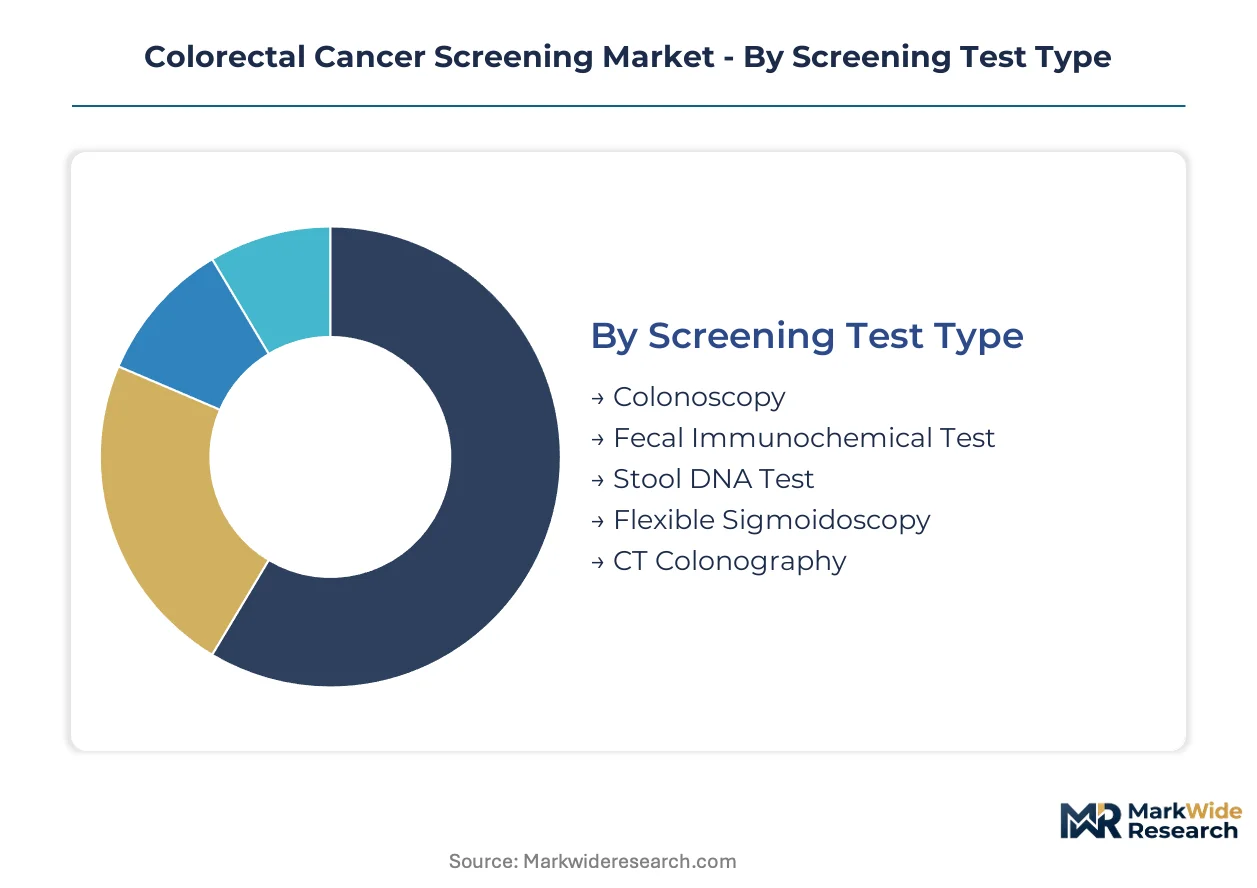
Colorectal cancer screening markets fragment across five distinct dimensions, each governed by divergent regulatory pathways and reimbursement structures. Test modality, care setting, and technology platform determine FDA premarket requirements, CLIA certification burdens, and CMS coverage timelines.
Screening Test Type:
FDA premarket approval pathways vary sharply by invasiveness level, with optical procedures requiring PMA submission while stool-based assays navigate 510(k) clearance or LDT frameworks under CLIA oversight.
- Colonoscopy:Optical visualization via flexible endoscope remains the diagnostic gold standard with 90-plus percent sensitivity for advanced neoplasia. Gastroenterology practices in the United States concentrate procedure volume, though capacity constraints now extend wait times beyond 12 weeks in major metropolitan markets.
- Fecal Immunochemical Test:Antibody-based hemoglobin detection enables low-cost annual screening through primary care distribution. Medicare coverage and zero-cost-sharing preventive benefit designs drive volume concentration among federally qualified health centers and large health system laboratories.
- Stool DNA Test:Epigenetic biomarker panels combining methylation markers with hemoglobin detection.
- Flexible Sigmoidoscopy:Limited optical examination of distal colon with reduced sedation requirements.
- CT Colonography:Computed tomography with virtual reconstruction requiring radiologist interpretation and follow-up colonoscopy for positive findings.
Fecal Immunochemical Test sits at the top of the volume ranking, with Stool DNA Test climbing the fastest.
Screening Setting:
Site-of-care economics stratify sharply, with fixed-cost ambulatory surgical centers commanding premium reimbursement for endoscopic procedures while mobile units capture rural access gaps at compressed margins.
- Clinics:Primary care and specialty clinics anchor non-invasive test distribution through established physician-patient relationships. United States health systems are integrating point-of-care FIT processing to reduce referral leakage.
- Diagnostic Centers:High-throughput laboratories process stool DNA and blood-based assays with automated extraction platforms. Commercial payer contracts with Quest Diagnostics and LabCorp concentrate national volume.
- Ambulatory Surgical Centers:Endoscopy-focused facilities optimize colonoscopy throughput through dedicated anesthesia and recovery protocols.
- Mobile Screening Units:Federally funded programs and employer wellness initiatives deploy van-based FIT distribution and telemedicine follow-up.
Diagnostic Centers capture the highest revenue per encounter, with Mobile Screening Units expanding most quickly.
End User:
Prescription authority and risk stratification capabilities determine end-user segmentation, with primary care physicians managing average-risk population entry and specialists handling diagnostic confirmation.
- Hospitals:Integrated delivery networks coordinate screening outreach, diagnostic colonoscopy, and surgical oncology referral within single tax identification. Academic medical centers anchor clinical trial recruitment for novel biomarker validation.
- Specialist Clinics:Gastroenterology practices concentrate colonoscopy capacity and surveillance protocols for high-risk cohorts. United States metropolitan markets show pronounced specialist concentration.
- Primary Care Providers:Family medicine and internal medicine physicians initiate screening conversations and order non-invasive tests.
- Cancer Research Institutes:National Cancer Institute-designated centers validate emerging technologies through prospective cohort studies.
Specialist Clinics dominate diagnostic procedure volume, with Primary Care Providers driving the steepest expansion trajectory in screening initiation.
Technology:
Platform maturity spans decades, with optical imaging representing 50-year-old technology and artificial intelligence applications gaining FDA breakthrough device designations within the past 36 months.
- Optical Imaging:White-light and narrow-band endoscopy systems from Olympus and Medtronic constitute installed base. AI-augmented polyp detection modules are retrofitting existing platforms.
- Biomarker Detection:Protein and nucleic acid assays for circulating and stool-based markers. FDA 510(k) clearance pathways dominate regulatory strategy.
- Artificial Intelligence:Computer-aided detection algorithms for polyp identification and histology prediction. Regulatory clearances from FDA and CE marking under EU MDR accelerate commercial deployment.
- Molecular Diagnostics:Next-generation sequencing platforms for multi-cancer early detection panels. CLIA laboratory certification and CMS coverage determination timelines constrain commercialization.
- Non-invasive Testing:Blood-based liquid biopsy approaches for circulating tumor DNA detection. Medicare national coverage determinations remain pending for colorectal-specific applications.
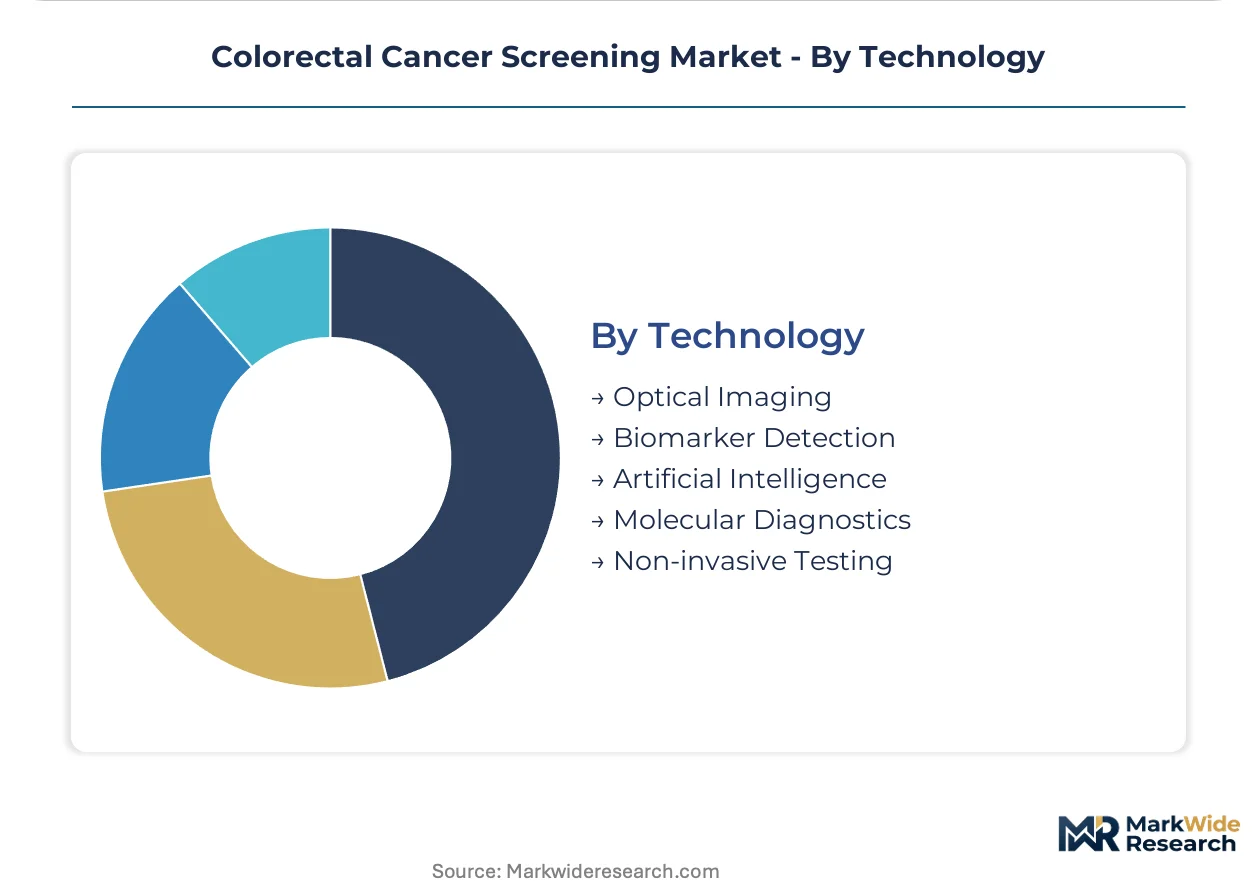
Optical Imaging retains the largest installed base, with Artificial Intelligence gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping laboratory capacity deployment as manufacturers seek jurisdictions with streamlined CLIA-equivalent certification pathways and favorable reimbursement timelines. Production gravity is shifting toward regions with integrated diagnostic networks and concentrated gastroenterology specialist pools.
United States
Medicare national coverage determinations and commercial payer contract expansions drive stool DNA and blood-based assay volumes. FDA breakthrough device designations for multi-cancer detection platforms compress premarket review timelines. The Greater Boston corridor anchors molecular diagnostics R&D concentration, with Exact Sciences and Guardant Health maintaining headquarters and high-throughput processing facilities.
Germany
Statutory health insurance reimbursement for fecal immunochemical testing sustains primary care screening penetration above European averages. EU Medical Device Regulation conformity assessment requirements favor established IVD manufacturers with notified body relationships. The Munich-Stuttgart axis concentrates endoscopy device engineering, with Olympus and Fujifilm operating European headquarters and training centers.
Japan
National cancer screening program mandates and aging demographics expand eligible populations for non-invasive alternatives. PMDA regulatory harmonization with FDA standards accelerates approval pathways for liquid biopsy platforms. The Tokyo-Osaka corridor hosts centralized laboratory networks processing FIT and stool DNA volumes for prefectural health systems.
China
Rising colorectal cancer incidence in urban cohorts and health insurance expansion for preventive services create demand inflection. NMPA priority review pathways for innovative diagnostics reduce registration timelines for epigenetic biomarker assays. The Yangtze River Delta cluster concentrates domestic IVD manufacturing, with Shanghai and Suzhou hosting contract research organizations supporting clinical validation studies.
United Kingdom
NHS England bowel cancer screening programme procurement contracts determine volume allocation between FIT and colonoscopy capacity. MHRA post-Brexit regulatory autonomy enables divergence from EU MDR timelines for domestic manufacturers. The Cambridge-London corridor anchors academic-industry partnerships validating AI-augmented polyp detection systems.
Colorectal Cancer Screening Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue blood-based multi-cancer detection and AI-augmented imaging modalities. The market structure consolidates around three vertical domains: molecular diagnostics laboratories, endoscopy device manufacturers, and commercial reference laboratories. Strategic archetypes include integrated platform developers, specialty biomarker laboratories, and diversified diagnostic conglomerates. Dominant competitive moves encompass regulatory pre-submission investments to secure breakthrough device designations and payer engagement partnerships preceding CMS national coverage determinations.
Among integrated molecular diagnostics specialists, Exact Sciences Corporation and Guardant Health exemplify contrasting platform strategies—stool DNA versus liquid biopsy—while Quest Diagnostics anchors the commercial laboratory tier through phlebotomy network scale. Olympus Corporation represents the endoscopy device archetype, with Danaher Corporation occupying the diversified life sciences conglomerate position spanning reagent supply and analytical instrumentation.
| Leading Market Players |
|---|
| Exact Sciences Corporation |
| Olympus Corporation |
| Quest Diagnostics |
| Fujifilm Holdings Corporation |
| Danaher Corporation |
| Guardant Health |
| Abbott Laboratories |
| Epigenomics AG |
| Clinical Genomics Technologies Pty Ltd. |
| Others |
Cost & Logistics Intelligence
Medicare and commercial payer concentration as the dominant buyer archetype anchors contract-based pricing models across stool DNA and blood-based screening modalities. This procurement structure rewards laboratories with CLIA-certified high-throughput capacity and established reimbursement coding, while squeezing margin flexibility for emerging entrants lacking payer contracts.
Pricing Analysis
Distributor and laboratory service markups layer atop manufacturer list prices, with three-tier pricing structure across premium, standard, and economy levels differentiating by biomarker panel complexity and turnaround speed. Price differentiation hinges on FDA breakthrough device designation status and Medicare coverage determination timing, with covered assays commanding premium positioning. Pricing pressure stems from colonoscopy capacity constraints forcing payers toward lower-cost non-invasive alternatives. Federally qualified health centers exhibit highest price sensitivity, while self-insured employer plans show lowest sensitivity due to wellness program budgets.
Supply Chain Analysis
PhD-level computational biologist scarcity in the Greater Boston and San Francisco Bay Area corridors constrains assay development velocity for emerging liquid biopsy platforms. Nucleic acid extraction chemistries and polymerase enzyme production concentrate in the United States, Germany, and China, with reagent supply drawing from three global suppliers. Single-source vulnerability in enzyme manufacturing exposes high-throughput laboratories to pandemic-era disruption recurrence. Distribution runs through integrated laboratory networks and direct hospital system contracts, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with demand shifting toward blood-based multi-cancer detection panels that promise single-draw screening efficiency over organ-specific protocols.
For Market Incumbents: Acquire CLIA-certified laboratory capacity in underserved metropolitan markets to secure colonoscopy follow-through capacity for positive screening cascades. Consolidate epigenetic biomarker patent estates to defend against liquid biopsy substitution, while deepening payer engagement partnerships ahead of Medicare national coverage determinations for blood-based assays. For New Entrants and Emerging Players: Capture mobile screening unit channel partnerships with federally funded programs and employer wellness initiatives, where regulatory barriers are lowest and volume aggregation is fastest. Target rural primary care access gaps through telemedicine-integrated stool DNA distribution, leveraging zero-cost-sharing preventive benefit designs to bypass specialist referral bottlenecks. For Investors and Strategic Acquirers: Diversified diagnostic conglomerates with existing phlebotomy networks are the most active acquirer in this space, seeking molecular diagnostics capabilities to fill portfolio gaps. Long-term viability over the extended horizon rests on Medicare coverage determination timing for blood-based screening. Signal to watch: FDA breakthrough device designation grants for multi-cancer early detection platforms, which compress premarket timelines and trigger parallel payer engagement.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates premarket review timelines for blood-based colorectal screening assays against standard PMA pathways. |
| Medicare Coverage Determination Strategy | Secures national reimbursement coding that determines commercial viability of novel biomarker platforms. |
| CLIA Laboratory Certification Investment | Enables high-throughput processing capacity for stool DNA and liquid biopsy volumes under federal quality standards. |
| Hospital System Partnership | Locks in colonoscopy referral volume for positive screening follow-through in capacity-constrained markets. |
| AI-Augmented Detection Software Development | Reduces adenoma miss rates in optical colonoscopy, creating service revenue streams for device manufacturers. |
Research Approach
Bottom-up screening test volume modeling reconciled against top-down laboratory capacity tracking forms the analytical core of this study. Primary interviews with gastroenterologists, clinical laboratory directors, payer formulary managers, and biomedical procurement officers combined with secondary validation from FDA 510(k) and PMA filings, CMS national coverage determination records, and CLIA laboratory certification databases. Triangulation across stakeholder perspectives and regulatory documentation ensures convergence on volume and pricing estimates.
Historical trendline analysis of test utilization rates by modality and payer type informed projection frameworks across the analysis window. Segmentation dimensions modeled include screening test type, care setting, technology platform, and end-user category, with CAGRs derived from regression analysis of volume trajectories and reimbursement expansion schedules. Forecast inputs incorporate epigenetic biomarker sensitivity improvements and artificial intelligence regulatory clearance timelines.
Regulatory approval delays, reimbursement determination reversals, and supply chain disruptions in nucleic acid extraction chemistries are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding Medicare coverage expansion and commercial payer contract velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Throat Cancer Market
Oncology
North America Veterinary Oncology Market
Oncology
Pancreatic Cancer Market
Oncology
Cancer API Market
Oncology
Cancer Cachexia Market
Oncology
Colorectal Cancer Market
Oncology
Ewing Sarcoma Treatment Market
Oncology
Adrenocortical Carcinoma Treatment Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Global Proton Therapy Market
Oncology
Head and Neck Cancer Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Metastatic Breast Cancer Market
Oncology
Australia Cancer Treatment Market
Oncology
Cancer Supportive Care Products Market
Oncology
Cancer/Tumor Profiling Market