
 Genetic Disease Diagnostic Market | 2026-2036
Genetic Disease Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Genetic Disease Diagnostic Market Analysis
Biotech manufacturing clusters in San Diego and Boston are decoupling from legacy instrument supply chains as regional production capacity for sequencing consumables expands. Illumina leverages its installed base of NovaSeq systems to sustain revenue continuity across clinical and research accounts. Thermo Fisher Scientific anchors its position through integrated workflow solutions spanning sample preparation to data analysis. Roche Holding competes by embedding diagnostic content within its automated platform ecosystem.
Genetic disease diagnostic testing encompasses molecular assays that detect pathogenic variants in DNA or RNA to identify inherited conditions, utilizing technologies with analytical sensitivity thresholds below one percent variant allele frequency. The primary commercial purpose centers on enabling treatment decisions, reproductive planning, and newborn intervention before symptom onset. Carrier screening and prenatal testing command mature revenue pools with established reimbursement pathways, while whole genome sequencing and CRISPR-based diagnostics attract capital inflows as margin frontiers. Next-generation sequencing dominates technology-based value capture, though SNP analysis retains cost advantages in high-volume screening contexts.
FDA oversight of laboratory-developed tests and CLIA certification requirements shape product development timelines and commercial access for diagnostic developers in the United States. EMA's In Vitro Diagnostic Regulation and the EU AI Act impose conformity assessment burdens on algorithm-dependent variant interpretation tools entering European markets. Stakeholders must monitor evolving payer coverage determinations for exome and genome sequencing as the central uncertainty affecting adoption velocity.
Market Dynamics
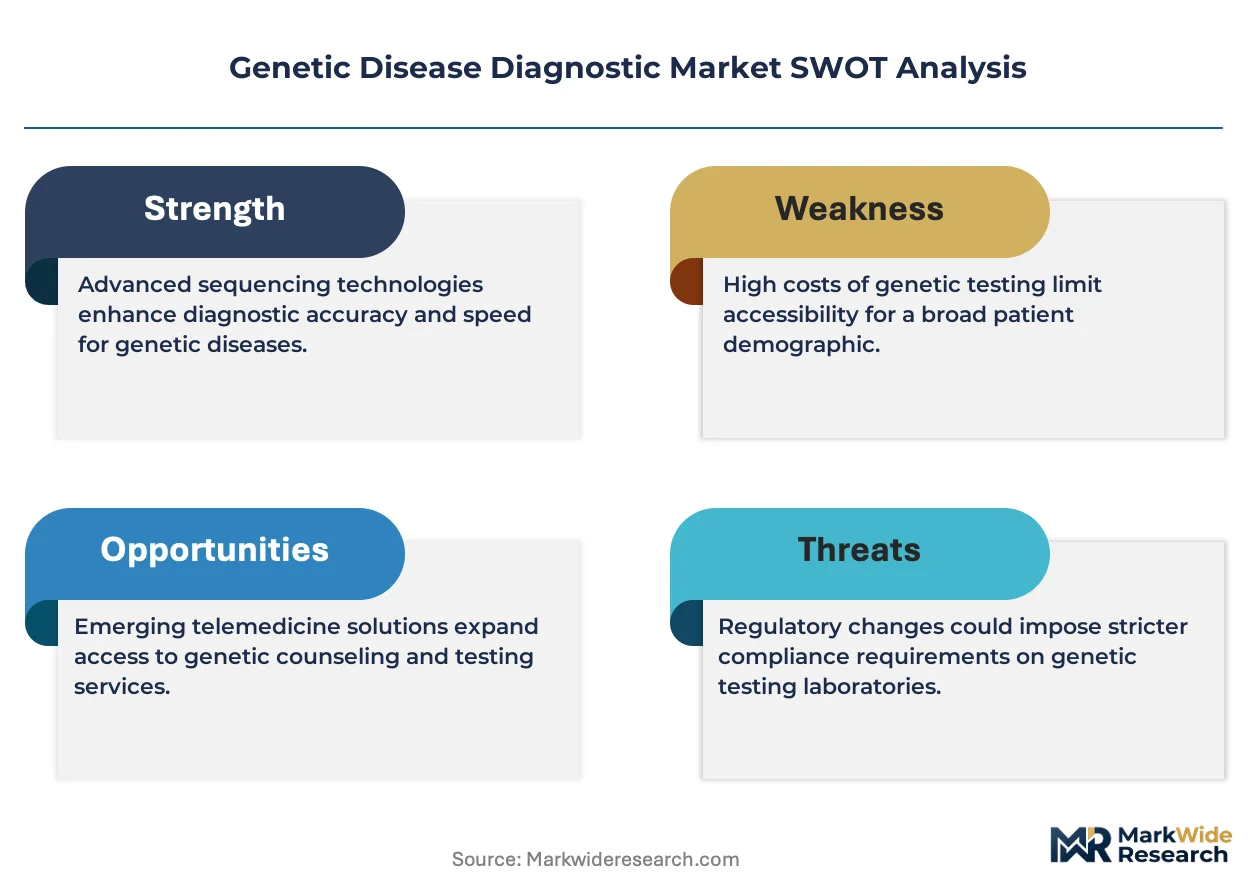
Next-generation sequencing platforms are compressing turnaround times for pathogenic variant detection while FDA oversight of laboratory-developed tests extends compliance timelines for commercial entry.
Growth Catalysts
- Statutory reimbursement mandates:Germany's statutory health insurance system covers genomic diagnostic services, removing cost barriers for carrier screening and prenatal testing expansion.
- Clinical laboratory network expansion:United States laboratories are scaling carrier screening programs under CLIA certification requirements, creating installed base for sequencing consumables.
- CRISPR-based diagnostic platforms:CRISPR-Cas systems enable point-of-care detection of inherited conditions with minimal equipment requirements, opening access in resource-limited settings.
Market Restraints
- Sequencing consumable supply concentration:Reagent manufacturing clusters in San Diego and Boston create geographic vulnerability to regional logistics disruptions.
- EMA conformity assessment burdens:The EU AI Act and In Vitro Diagnostic Regulation impose algorithm validation requirements for variant interpretation software, extending European market entry timelines.
- Cytogenetic method obsolescence costs:Clinical laboratories face stranded asset risk from karyotyping and FISH equipment as NGS platforms capture molecular testing volume.
Strategic Opportunities
- Newborn screening program expansion:Whole genome sequencing integration into state-mandated newborn panels in the United States creates reimbursement precedent for preemptive genomic medicine.
- Pharmacogenomic convergence:Integration of genetic diagnostic data with therapeutic decision support systems enables personalized dosing protocols for inherited metabolic disorders.
- Direct-to-consumer channel development:Telehealth platforms are bundling carrier screening with genetic counseling services, bypassing traditional clinical laboratory referral pathways.
Industry Challenges
- Bioinformatics talent scarcity:Variant interpretation pipelines require computational biologists with dual training in clinical genetics and machine learning, a skill combination concentrated in Boston and San Diego clusters.
- Legacy EHR integration friction:Genomic data formats lack standardization with electronic health record systems, forcing manual curation of structured variant reports into patient records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetic Disease Diagnostic Market |
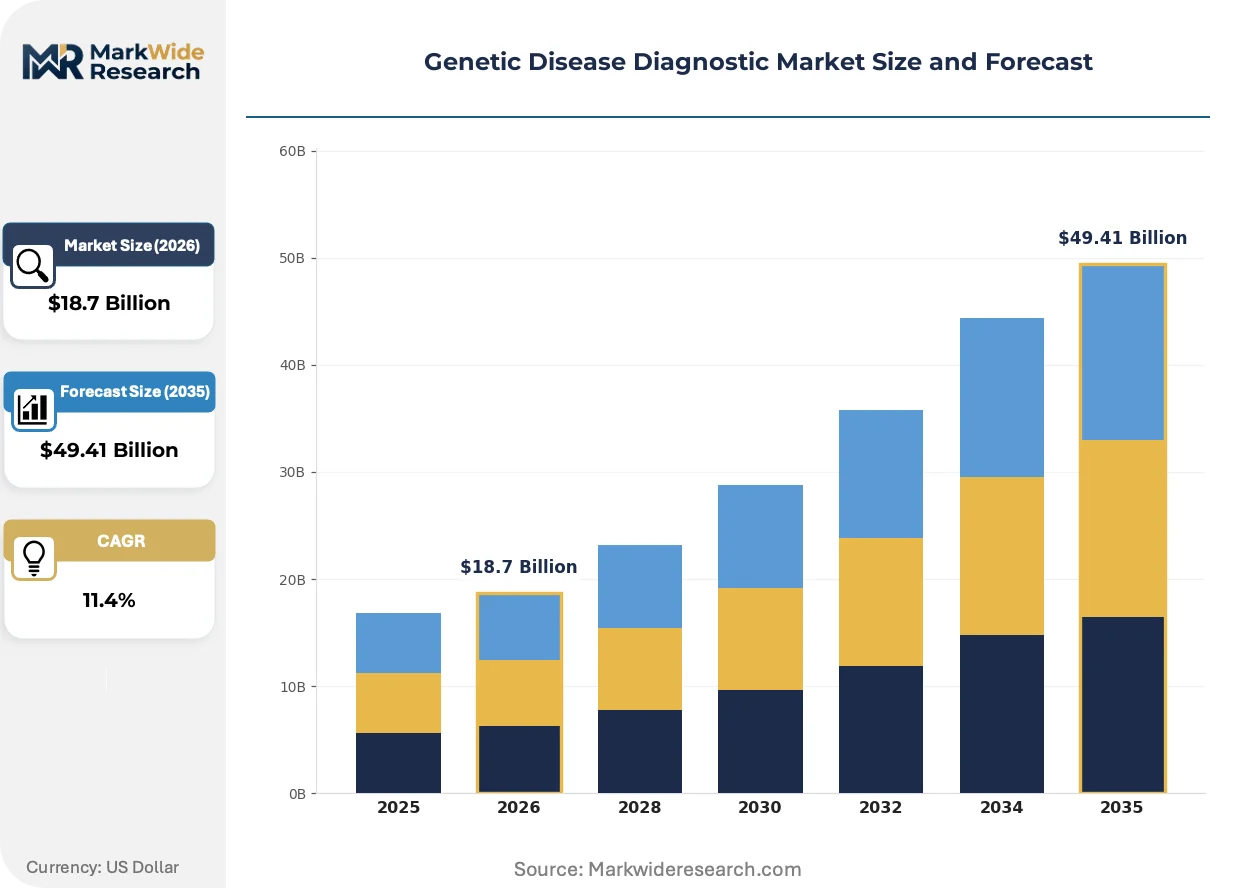
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Carrier Screening, Prenatal Testing, Newborn Screening, Diagnostic Testing Technology: SNP Analysis, Whole Genome Sequencing, Next-Generation Sequencing, CRISPR End User: Hospitals, Diagnostic Labs, Research Institutes, Clinics Gene Type: Single-Gene Disorders, Multigenic Disorders, X-Linked Disorders, Mitochondrial Disorders |
| Companies Covered | Illumina, Roche Holding, Thermo Fisher Scientific, Abbott Laboratories, Quest Diagnostics, Myriad Genetics, QIAGEN, Eurofins Scientific, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetic Disease Diagnostic Market Emerging Trajectories
Artificial intelligence tools are restructuring variant classification workflows while regulatory frameworks adapt to algorithm-dependent diagnostic outputs. Three developments are compressing development cycles and reshaping competitive positioning.
Multi-omics platforms are integrating transcriptomic and epigenetic data layers with DNA sequencing to resolve variants of uncertain significance. Academic medical centers in Germany and the United States are deploying these systems for rare disease diagnosis, compressing the diagnostic odyssey from years to weeks. The technology is integrating proteomic biomarker discovery with germline variant detection, enabling functional validation of pathogenicity predictions.
The EU AI Act's risk classification system for medical device software is mandating conformity assessment procedures for automated variant interpretation tools. Developers must document training data provenance and algorithmic performance across ancestry groups before CE marking. European laboratories are responding by consolidating procurement around vendors with established notified body relationships, privileging integrated workflow providers.
Health system purchasing committees are unbundling sequencing services from data analysis contracts, creating separate vendor relationships for wet lab processing and clinical interpretation. This fragmentation is most visible in United States academic medical centers, where pathology departments retain sequencing infrastructure while contracting bioinformatics pipelines to specialized software vendors. The shift compresses switching costs and intensifies price competition at the analysis layer.
Genetic Disease Diagnostic Market Segmentation
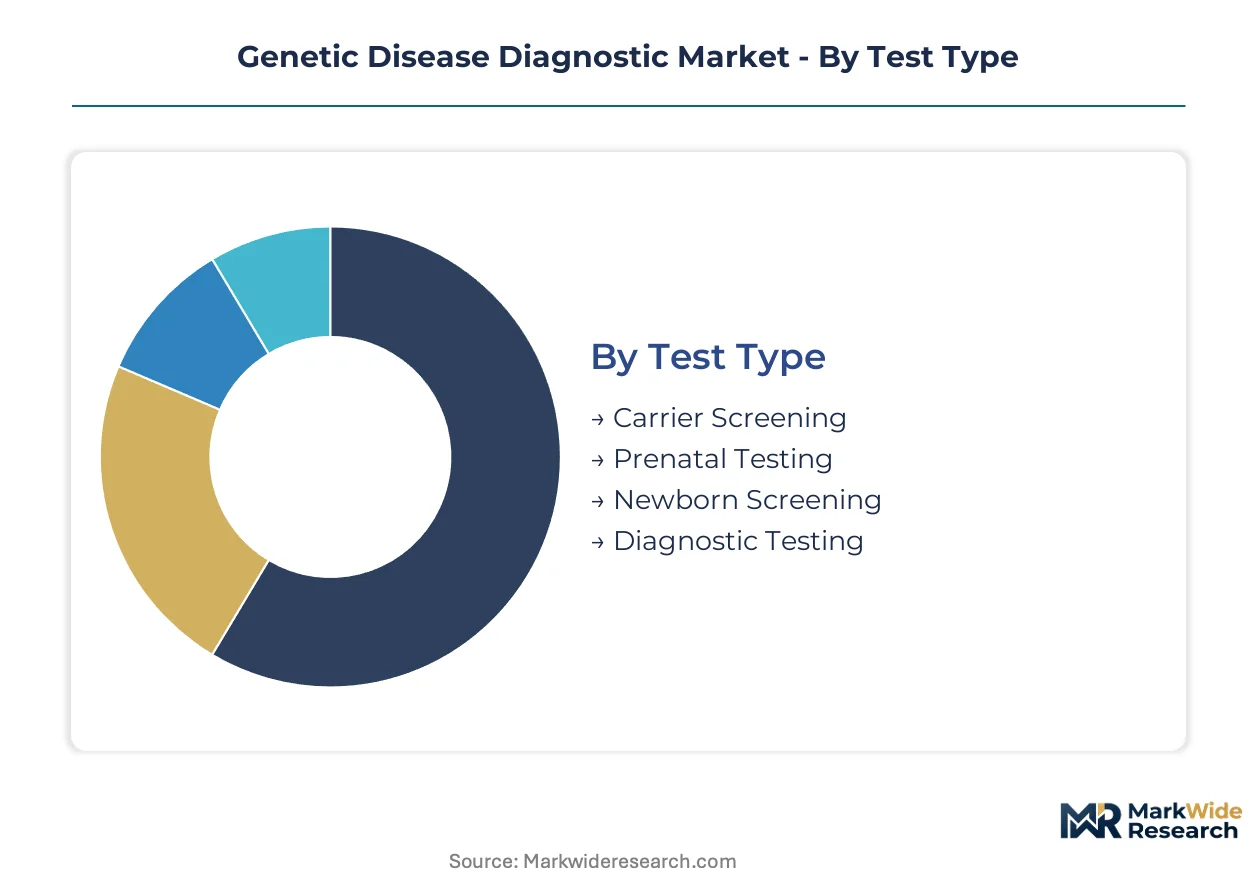
Segmentation in genetic disease diagnostics reveals how reimbursement pathways, technology maturity, and clinical workflow integration determine where capital deploys. Test type and technology selections drive margin structures, while end-user channel choices shape go-to-market economics.
Test Type:
Customization intensity spans from standardized population screening panels to highly individualized diagnostic workups for symptomatic patients.
- Carrier Screening:Population-scale panels assess heterozygous carrier status for autosomal recessive conditions in prospective parents. Demand concentrates in United States commercial laboratories expanding under FDA oversight of laboratory-developed tests, with statutory reimbursement in Germany removing cost barriers for panel expansion.
- Prenatal Testing:Non-invasive cell-free DNA analysis and invasive diagnostic procedures detect fetal chromosomal abnormalities and monogenic disorders. United States academic medical centers are integrating these services into maternal-fetal medicine workflows, though ethical frameworks vary by state jurisdiction.
- Newborn Screening:State-mandated heel-prick panels identify treatable metabolic and endocrine disorders before symptom onset.
- Diagnostic Testing:Symptom-driven molecular workups confirm suspected genetic etiologies in pediatric and adult patients.
Leading the category by volume: Carrier Screening. Growing fastest: Newborn Screening.
Technology:
Cost tier stratification separates high-throughput platforms with dedicated infrastructure from portable systems deployable at point-of-care.
- Next-Generation Sequencing:Massively parallel sequencing platforms dominate clinical and research volume, with analytical sensitivity below one percent variant allele frequency. Illumina's NovaSeq installed base across United States and German laboratories sustains consumable revenue continuity.
- Whole Genome Sequencing:Comprehensive germline analysis captures coding and non-coding variation without prior hypothesis. Academic medical centers in Germany and the United States deploy these systems for rare disease diagnosis, compressing diagnostic timelines from years to weeks.
- SNP Analysis:Targeted genotyping arrays retain cost advantages in high-volume screening contexts with known variant catalogs.
- CRISPR:Cas-mediated detection enables point-of-care diagnostic platforms with minimal equipment requirements for resource-limited settings.
Highest volume capture: Next-Generation Sequencing. Steepest expansion trajectory: Whole Genome Sequencing.
End User:
Customer type determines procurement complexity, with integrated health systems favoring bundled contracts versus independent laboratories prioritizing reagent flexibility.
- Diagnostic Labs:CLIA-certified facilities process high-throughput screening and diagnostic volumes under United States regulatory oversight, with regional production clusters in San Diego and Boston decoupling from legacy instrument supply chains.
- Hospitals:Academic medical centers deploy multi-omics platforms integrating transcriptomic and epigenetic data layers for rare disease diagnosis.
- Research Institutes:Basic and translational genomics programs drive technology adoption ahead of clinical validation.
- Clinics:Outpatient settings increasingly bundle carrier screening with telehealth-delivered genetic counseling services.
Dominant procurement volume: Diagnostic Labs. Channel expanding most quickly: Clinics.
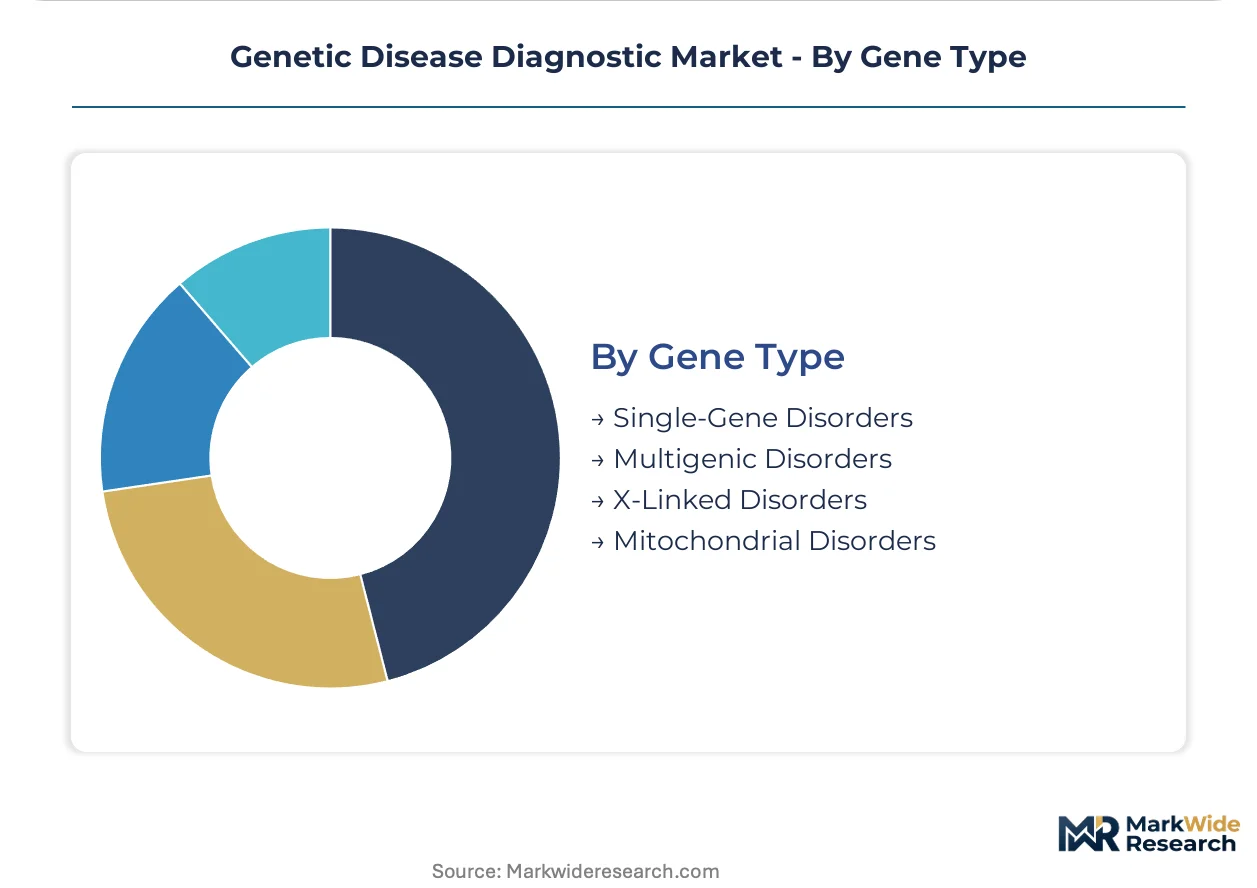
Gene Type:
Application focus distinguishes monogenic conditions with clear Mendelian inheritance from complex disorders requiring polygenic risk modeling.
- Single-Gene Disorders:Pathogenic variants in individual genes cause conditions such as cystic fibrosis and sickle cell disease with well-established clinical actionability. Carrier screening panels and newborn screening programs concentrate demand here.
- X-Linked Disorders:Hemizygous expression in males and carrier status in females create distinctive inheritance patterns for conditions such as Duchenne muscular dystrophy and fragile X syndrome.
- Multigenic Disorders:Polygenic architectures complicate risk stratification for common conditions such as type 2 diabetes and cardiovascular disease.
- Mitochondrial Disorders:Heteroplasmic mutation loads in maternally inherited genomes require specialized sequencing approaches and interpretation frameworks.
Greatest clinical utility penetration: Single-Gene Disorders. Gaining share fastest: X-Linked Disorders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Diego and Boston anchor consumable manufacturing for sequencing platforms, while clinical demand concentrates in jurisdictions with statutory reimbursement frameworks.
United States
Clinical laboratories scale carrier screening programs under FDA oversight of laboratory-developed tests and CLIA certification requirements. The national pharmaceutical regulator maintains stringent validation standards for genomic diagnostic commercial entry. San Diego and Boston biotech clusters decouple from legacy instrument supply chains as regional reagent production capacity expands.
Germany
Statutory health insurance covers genomic diagnostic services, eliminating cost barriers for carrier screening and prenatal testing panel expansion. EMA's In Vitro Diagnostic Regulation imposes conformity assessment burdens on algorithm-dependent variant interpretation tools entering European markets. Academic medical centers in Bavaria and Baden-Württemberg deploy multi-omics platforms for rare disease diagnosis.
United Kingdom
NHS Genomic Medicine Service integrates whole genome sequencing into clinical pathways for rare disease and cancer. The national pharmaceutical regulator aligns with post-Brexit regulatory autonomy frameworks for diagnostic device approval. London and Cambridge research clusters concentrate bioinformatics talent for variant interpretation pipeline development.
China
NMPA accelerates review pathways for innovative sequencing platforms targeting hereditary disease screening. The national pharmaceutical regulator implements clinical trial data requirements for germline variant detection assays. Shanghai and Shenzhen manufacturing hubs expand domestic production capacity for sequencing consumables and instruments.
Japan
PMDA reimbursement decisions for next-generation sequencing panels shape adoption timelines in academic medical centers. The national pharmaceutical regulator mandates local clinical evidence generation for genomic diagnostic registration. Tokyo and Osaka hospital networks integrate pharmacogenomic data with therapeutic decision support systems.
Genetic Disease Diagnostic Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue point-of-care diagnostic platforms and AI-enabled variant interpretation. The vendor base stratifies across integrated workflow providers, sequencing platform specialists, and clinical laboratory service operators. Three archetypes dominate: consumable-anchored incumbents leveraging installed bases, automated platform integrators embedding diagnostic content, and bioinformatics pure-plays contracting analysis services to health systems. Competitive moves concentrate on strategic partnerships for algorithm validation and capacity expansion in regional manufacturing clusters.
Among United States-based platform developers, Illumina and Thermo Fisher Scientific exemplify contrasting archetypes within the sequencing technology tier. Swiss-incorporated Roche Holding occupies a position representing automated diagnostic ecosystem integration. These three entities anchor the competitive structure through divergent approaches to workflow capture: consumable revenue continuity, integrated sample-to-analysis solutions, and embedded platform content respectively.
| Leading Market Players |
|---|
| Illumina |
| Roche Holding |
| Thermo Fisher Scientific |
| Abbott Laboratories |
| Quest Diagnostics |
| Myriad Genetics |
| QIAGEN |
| Eurofins Scientific |
| PerkinElmer |
| Others |
Supply Flow & Price Mechanics
United States academic medical centers and German statutory health insurance systems concentrate procurement volume, anchoring a contract-based pricing model where reagent bundles and bioinformatics interpretation services are unbundled into separate vendor relationships.
Pricing Analysis
Service-bundling decisions separate sequencing consumables from variant interpretation software, with wet-lab processing and clinical analysis increasingly contracted to distinct vendors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation between CLIA-certified laboratories, research-grade facilities, and point-of-care deployments. Pricing pressure stems from health system purchasing committees fragmenting vendor relationships and intensifying competition at the analysis layer. Independent diagnostic laboratories exhibit highest price sensitivity due to reagent flexibility priorities, while integrated health systems prioritize workflow continuity over unit cost.
Supply Chain Analysis
Domestic-content mandates in China's NMPA framework and India's PLI scheme for medical devices are reshaping sourcing patterns for sequencing instruments and consumables. Manufacturing concentrates in the United States, Germany, and China, with San Diego and Boston clusters anchoring reagent production while Shanghai and Shenzhen expand domestic instrument capacity. Supply chains draw from specialized biochemical precursors, semiconductor components for detection systems, and synthetic oligonucleotide libraries. Single-source vulnerability concentrates in Illumina's flow-cell chemistry patents, creating exposure to licensing restrictions. Distribution runs through CLIA-certified laboratory networks, hospital system procurement committees, and direct-to-consumer telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The genetic disease diagnostic market operates as a cost-of-compliance story where FDA oversight of laboratory-developed tests and EMA's In Vitro Diagnostic Regulation create substantial barrier-to-entry moats favoring established players with notified body relationships and CLIA certification infrastructure.
For Market Incumbents: Acquire bioinformatics pure-plays with established machine learning variant interpretation pipelines to defend against health system unbundling of sequencing and analysis contracts. Deepen backward integration into reagent manufacturing within San Diego and Boston clusters to reduce geographic logistics vulnerability. Prioritize CE marking investment under EU AI Act algorithm validation requirements to capture European laboratory procurement consolidation. For New Entrants and Emerging Players: Capture direct-to-consumer carrier screening bundled with telehealth genetic counseling, the fastest-expanding channel bypassing traditional clinical laboratory referral pathways. Target point-of-care CRISPR-based diagnostic platforms for resource-limited settings where minimal equipment requirements offset incumbent installed-base advantages. Pursue pharmacogenomic convergence partnerships with therapeutic decision support system developers as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors bioinformatics pure-plays with dual-trained computational biologists and clinical geneticists, concentrated in Boston and San Diego talent clusters. Long-term viability hinges on algorithm-dependent diagnostic software vendors achieving CE marking under EU AI Act conformity assessment procedures. Watch EMA reimbursement determinations for whole genome sequencing in rare disease diagnosis as the critical inflection signal for adoption velocity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU AI Act conformity assessment unlocks European laboratory procurement consolidation. |
| Hospital System Partnership | Academic medical center integration secures installed base for multi-omics platform deployment. |
| Reimbursement Strategy | Statutory coverage determination in Germany removes cost barriers for panel expansion. |
| Software Companion Development | AI-enabled variant interpretation tools compress diagnostic timelines from years to weeks. |
| Regulatory Approval Pathway | FDA laboratory-developed test oversight extends compliance timelines for commercial entry. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with clinical laboratory directors, hospital purchasing committee members, bioinformatics pipeline developers, and genetic counseling service operators. FDA 510(k) submissions, EMA In Vitro Diagnostic Regulation guidance documents, CMS Medicare coverage determinations, and GPO contract databases provided secondary validation. Bottom-up sequencing platform installed-base estimates triangulated against top-down genomic diagnostic service revenue projections.
Granularity-level modeling captured test type, technology platform, end-user channel, and gene type dimensions at the country-regulator level across the projection horizon. CAGRs derived from segmented volume and value build-ups incorporating instrument placement trajectories, consumable pull-through rates, and reimbursement pathway evolution. Forecast inputs included CLIA certification capacity expansion timelines, EU AI Act implementation schedules, and newborn screening program legislative mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to payer coverage determinations for exome and genome sequencing, algorithm validation requirements under evolving regulatory frameworks, and bioinformatics talent scarcity in computational biology. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Global Apoptosis Assays Market
Clinical Diagnostics
Global Biomarkers Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
Global Nasopharyngeal Swab Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Global High-Resolution Melting Analysis Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Cervical Cancer Screening Market
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Clinical Microbiology Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
Chronic Hepatitis B Virus Testing Market