
 Angiogenesis Assays Market | 2026-2036
Angiogenesis Assays Market Size, Share, and Industry Trends Forecast 2026-2036
Angiogenesis Assays Market Outlook
Recombinant protein substrates and engineered endothelial cell lines are pivoting assay economics away from primary cell dependence. Thermo Fisher Scientific leverages its reagent manufacturing scale to anchor supply security for high-throughput screening workflows. Bio-Techne sustains R&D intensity across growth factor and antibody portfolios that support tube formation and migration readouts. Merck KGaA dominates European distribution channels for validated angiogenesis assay kits deployed in pharmaceutical toxicology programs.
Angiogenesis assays comprise laboratory methods that quantify blood vessel formation through tube formation, sprouting, or proliferation endpoints using human umbilical vein endothelial cells or co-culture systems, with readouts measured by fluorescence microscopy or high-content imaging platforms to evaluate pro- or anti-angiogenic compound activity. These assays serve drug discovery pipelines targeting tumor vascularization, diabetic retinopathy, and tissue regeneration therapies. In vitro assays occupy the largest volume share due to lower per-test cost and compatibility with automated liquid handling, while high-content screening represents the fastest-expanding technology segment as pharmaceutical companies demand multiplexed morphometric data from single experiments. Cell-based assays command premium positioning where physiological relevance outweighs throughput requirements in late-stage candidate validation.
FDA oncology drug review standards and EMA's ICH S9 guidance on anticancer nonclinical evaluation shape assay validation requirements for regulatory submission packages. ISO 10993 biocompatibility testing protocols and REACH chemical safety regulations in Europe further dictate material qualification for assay components contacting living cells. Stakeholders must monitor evolving FDA guidance on organoid-based models and the EU AI Act's implications for automated image analysis algorithms used in angiogenesis quantification.
Market Dynamics
Pharmaceutical toxicology programs are compressing validation timelines for angiogenesis assays, forcing suppliers to pre-qualify reagent lots and standardize endothelial cell sourcing across distributed manufacturing networks.
Growth Catalysts
- FDA Oncology Drug Review Standards:Accelerated approval pathways for anti-angiogenic cancer therapies mandate validated in vitro vascularization data, expanding contract research organization demand for standardized tube formation assays.
- High-Content Screening Platforms:Multiplexed morphometric readouts from single experiments reduce compound screening costs, driving replacement of low-throughput manual microscopy in pharmaceutical discovery pipelines.
- Boston-Cambridge Biotech Cluster:Concentrated venture funding for vascular-targeted oncology startups sustains procurement of engineered endothelial cell lines and recombinant growth factor substrates.
Market Restraints
- Primary HUVEC Supply Volatility:Umbilical cord tissue collection logistics and donor variability create lot-to-lot inconsistency, increasing qualification costs for GMP-compliant therapeutic development workflows.
- Reagent Import Dependence:European pharmaceutical toxicology programs rely on trans-Atlantic shipments for validated Matrigel alternatives, exposing assay schedules to customs clearance friction and cold-chain failures.
- ISO 10993 Biocompatibility Testing Burden:Material qualification requirements for assay components contacting living cells extend validation timelines, particularly for novel synthetic hydrogel substrates.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore are building GLP-compliant angiogenesis capabilities to capture outsourced pharmaceutical screening from Western sponsors.
- Organoid-Vascular Co-Culture Convergence:Integration of patient-derived tumor organoids with perfusable microvascular networks enables mechanistic studies of anti-angiogenic resistance, opening premium pricing for physiologically complex models.
- EU AI Act Compliance Services:Automated image analysis algorithms for tube formation quantification require algorithmic transparency documentation, creating advisory revenue streams for assay platform vendors.
Industry Challenges
- Cross-Platform Data Harmonization:Inconsistent endpoint definitions between fluorescence microscopy systems and high-content imagers complicate multi-site pharmaceutical studies, delaying regulatory submission packages.
- Specialized Cell Culture Technologist Shortage:Primary endothelial cell maintenance and angiogenesis endpoint interpretation require expertise that outpaces training program output in contract research hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angiogenesis Assays Market |
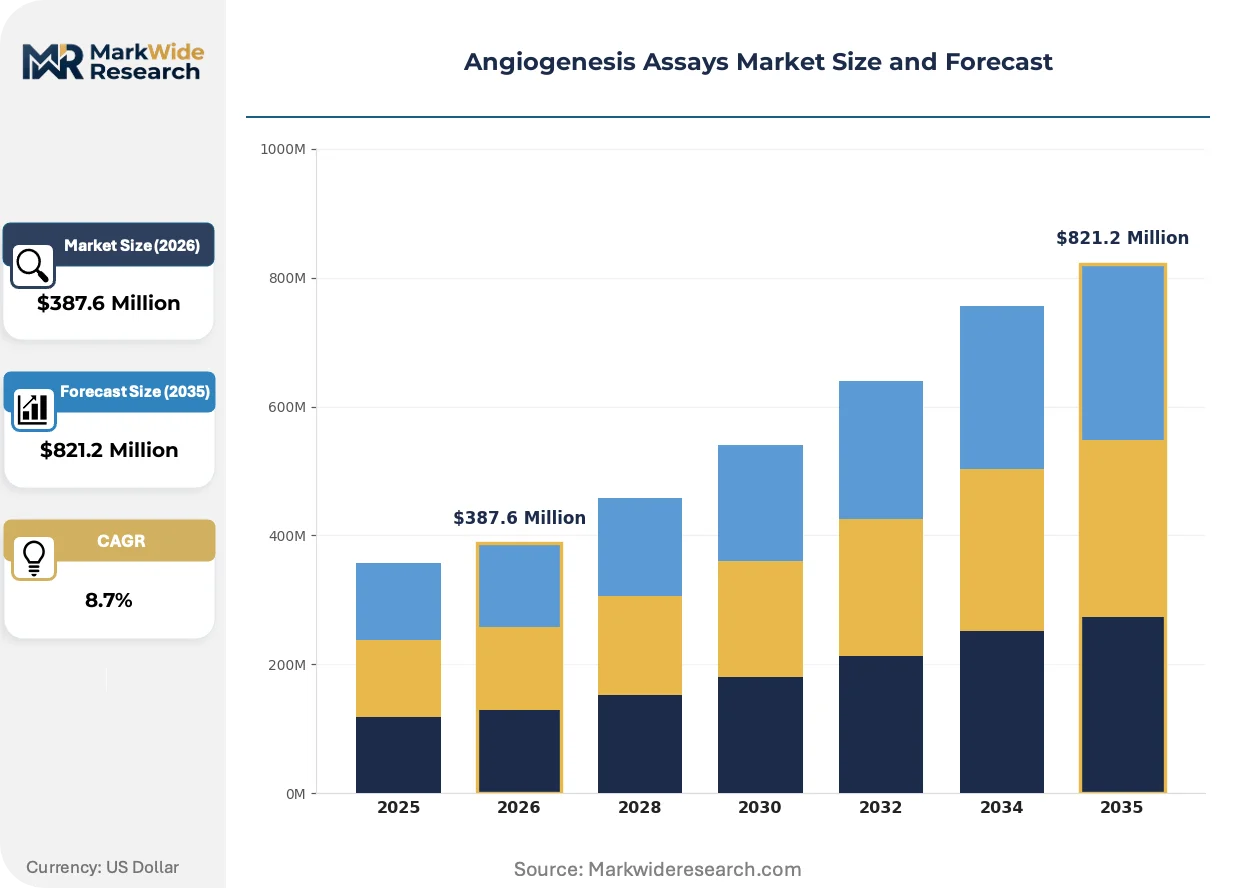
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In Vitro Assays, In Vivo Assays, Protein-Based Assays, Cell-Based Assays Technology: Fluorescence Microscopy, High-Content Screening, Imaging Systems, Microarrays Application: Drug Discovery, Cancer Research, Cardiovascular Studies, Toxicology Testing End User: Pharmaceutical Companies, Research Institutions, Clinical Laboratories, Biotechnology Firms |
| Companies Covered | Thermo Fisher Scientific, Bio-Techne, Merck KGaA, Abcam, Cell Biolabs, BioVision, PromoCell GmbH, Sartorius, Kollodis BioSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angiogenesis Assays Market Strategic Shifts
Microphysiological systems and computational image analysis are compressing the trade-off between assay throughput and physiological relevance, enabling earlier prediction of clinical vascular toxicity.
Organ-on-chip platforms incorporating perfusable endothelial-lined microchannels are decentralizing angiogenesis screening from centralized high-content imaging facilities toward distributed discovery teams. Mid-tier biotechnology companies in Research Triangle Park and Basel are adopting these systems for target validation studies. The shift is compressing the addressable market for traditional multiwell plate tube formation assays while expanding consumable revenue for microfluidic cartridge suppliers.
EMA's ICH S9 guidance on anticancer nonclinical evaluation now explicitly encourages mechanistic vascularization data beyond standard proliferation endpoints. European pharmaceutical toxicology programs are responding by integrating sprouting angiogenesis models into IND-enabling study designs. German regulatory consultants report compressed timelines for assay validation documentation as sponsors prepare for centralized procedure submissions.
Biotechnology procurement departments are unbundling angiogenesis assay reagent sourcing from integrated platform contracts, creating direct purchasing relationships with recombinant protein manufacturers. This disintermediation pressures distributors holding exclusive kit agreements with legacy endothelial cell suppliers. The pattern is most pronounced in San Diego and South San Francisco, where venture-backed oncology startups prioritize supply chain flexibility over vendor consolidation rebates.
Angiogenesis Assays Market Segmentation
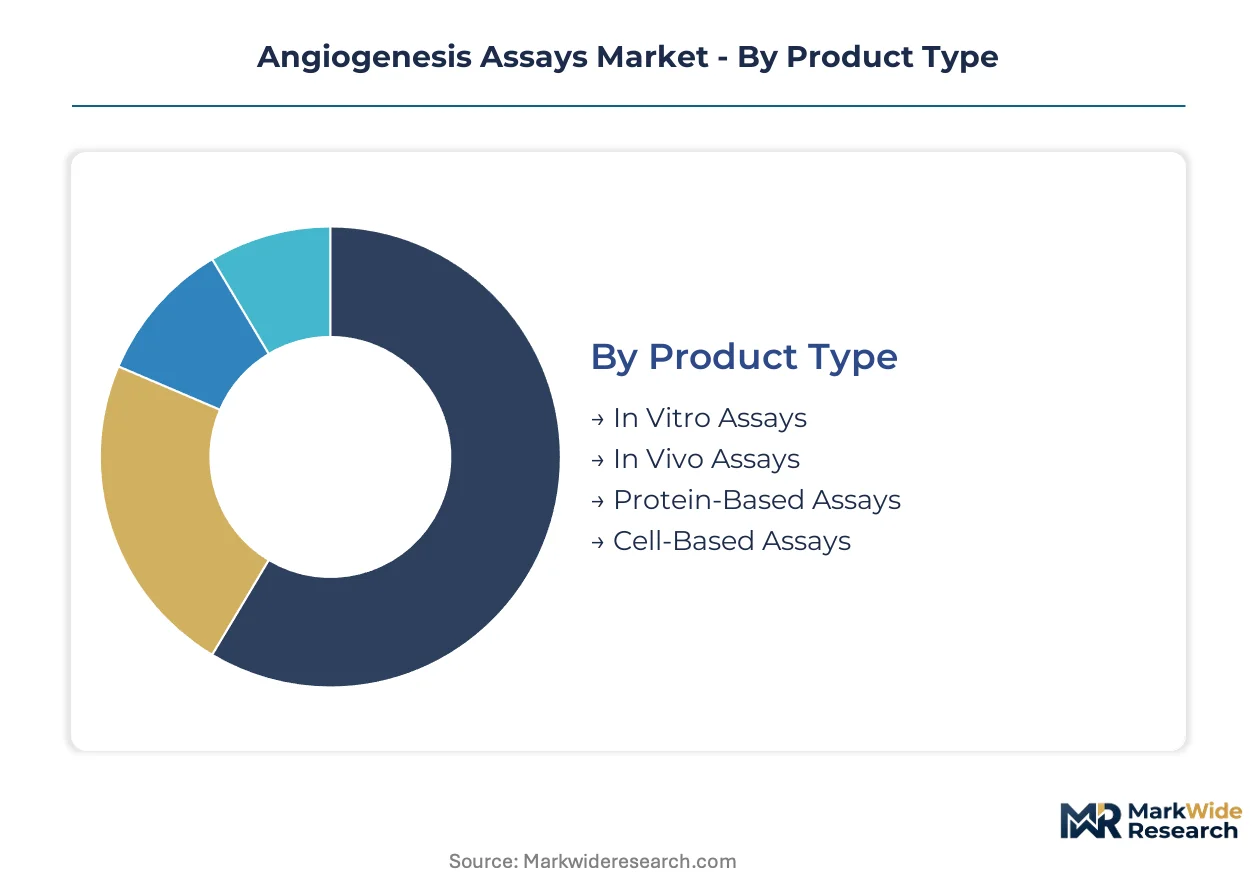
Segmentation in angiogenesis assays reflects divergent buyer priorities across pharmaceutical discovery workflows. Procurement teams balance per-test economics against regulatory validation requirements when selecting platforms for oncology pipeline screening.
Product Type:
Buyers segment primarily by the trade-off between physiological fidelity and operational throughput in their screening cascades.
- In Vitro Assays:Multiwell plate formats using endothelial cell monolayers or co-culture systems deliver tube formation and migration readouts at scale. Pharmaceutical toxicology programs in Germany and Japan favor these for early-stage compound triage where cost-per-data-point dominates selection criteria.
- Cell-Based Assays:Engineered endothelial lines and primary HUVEC cultures command premium positioning for late-stage candidate validation requiring mechanistic depth. Demand concentrates in Boston-Cambridge and Basel biotech clusters where physiological relevance outweighs automation compatibility.
- In Vivo Assays:Matrigel plug and corneal micropocket models using rodent hosts provide whole-organism vascularization data for IND submissions.
- Protein-Based Assays:Soluble growth factor binding and receptor phosphorylation formats offer biochemical specificity for target validation studies.
Volume sits with in vitro formats; growth tilts toward cell-based systems as regulatory agencies demand more mechanistic vascularization data.
Technology:
Technology selection tracks the automation maturity of buyer facilities and their multiplexing requirements.
- High-Content Screening:Automated imagers capturing multi-parametric morphometric data from single experiments compress screening timelines for large compound libraries. Pharmaceutical companies in San Diego and South San Francisco deploy these platforms to replace manual microscopy in hit-to-lead transitions.
- Fluorescence Microscopy:Widefield and confocal systems remain standard for specialized endpoint validation where custom antibody panels or novel fluorophore combinations exceed commercial high-content menu availability.
- Imaging Systems:Live-cell microscopy enclosures with environmental control support kinetic angiogenesis studies tracking tube formation dynamics over 24-72 hour windows.
- Microarrays:Miniaturized spot formats enable parallel screening of growth factor combinations or extracellular matrix compositions on single glass substrates.
Adoption clusters in high-content screening; fluorescence microscopy retains share in academic and boutique CRO settings.
Application:
Application segmentation mirrors the therapeutic area priorities of end-user R&D portfolios.
- Drug Discovery:Target identification through lead optimization workflows consume the highest assay volumes as sponsors screen anti-angiogenic and vascular-normalizing compounds across oncology indications. FDA accelerated approval pathways for anti-angiogenic cancer therapies mandate validated vascularization data, expanding contract research organization procurement.
- Cancer Research:Mechanistic studies of tumor angiogenesis, vascular co-option, and resistance to anti-angiogenic therapy drive demand for complex co-culture and organoid-vascular integration models.
- Cardiovascular Studies:Ischemia-driven therapeutic angiogenesis and vascular regeneration research programs utilize similar endothelial platforms with modified growth factor stimulation protocols.
- Toxicology Testing:EMA ICH S9 guidance on anticancer nonclinical evaluation explicitly encourages mechanistic vascularization data beyond proliferation endpoints, integrating sprouting models into IND-enabling study designs.
Drug discovery commands the largest absolute spend; cancer research shows the steepest expansion trajectory as organoid-vascular co-culture methods mature.
End User:
End-user segmentation reflects divergent procurement authority and validation requirements across organizational types.
- Pharmaceutical Companies:Integrated discovery and development organizations specify pre-qualified reagent lots and standardized cell sourcing across distributed manufacturing networks. Internal toxicology groups compress validation timelines, forcing suppliers to anchor supply security for high-throughput workflows.
- Biotechnology Firms:Venture-backed oncology startups in Research Triangle Park and Basel unbundle reagent sourcing from integrated platform contracts, prioritizing supply chain flexibility over vendor consolidation rebates.
- Research Institutions:Academic laboratories emphasize publication-grade imaging data and methodological innovation over regulatory submission packages.
- Clinical Laboratories:Diagnostic service providers represent emerging demand for angiogenesis biomarker quantification in patient stratification for anti-angiogenic therapy selection.
Pharmaceutical companies anchor procurement volume; biotechnology firms are expanding most quickly as vascular-targeted startup formation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical R&D procurement concentrates in the United States, Germany, and Japan, where biopharma clusters and regulatory frameworks for cancer drug development drive validated angiogenesis testing system demand.
United States
FDA accelerated approval pathways for anti-angiogenic cancer therapies mandate validated in vitro vascularization data, expanding contract research organization procurement of standardized tube formation assays. The agency's oncology drug review standards shape assay validation requirements for regulatory submission packages. Boston-Cambridge and San Diego biotech clusters sustain demand for engineered endothelial cell lines and recombinant growth factor substrates.
Germany
EMA's ICH S9 guidance on anticancer nonclinical evaluation explicitly encourages mechanistic vascularization data beyond standard proliferation endpoints. REACH chemical safety regulations dictate material qualification for assay components contacting living cells. Basel-adjacent pharmaceutical toxicology programs in Baden-Württemberg integrate sprouting angiogenesis models into IND-enabling study designs.
Japan
PMDA alignment with ICH S9 guidance drives adoption of mechanistic vascularization endpoints in oncology drug development workflows. METI industrial policy supports domestic biotechnology infrastructure for cell-based assay manufacturing. Tokyo-Yokohama and Osaka-Kobe biopharma corridors concentrate procurement of high-content screening platforms for multiplexed morphometric readouts.
India
CDSCO regulatory convergence with ICH standards positions contract development and manufacturing organizations for GLP-compliant angiogenesis capability expansion. Hyderabad and Bangalore CDMOs are building screening infrastructure to capture outsourced pharmaceutical work from Western sponsors. Karnataka and Telangana biotech parks attract venture funding for vascular-targeted oncology startup formation.
United Kingdom
Medicines and Healthcare products Regulatory Agency implementation of ICH S9 shapes toxicology program requirements for mechanistic vascularization data. London-Oxford-Cambridge golden triangle research institutions emphasize publication-grade imaging data and methodological innovation. South San Francisco-modeled venture ecosystems in Greater London prioritize supply chain flexibility over vendor consolidation rebates.
Angiogenesis Assays Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors holding procurement relationships in pharmaceutical toxicology programs while reagent manufacturers capture direct purchasing from unbundling biotechnology procurement departments. Thermo Fisher Scientific leverages reagent manufacturing scale to anchor supply security for high-throughput screening workflows. Three strategic archetypes dominate: diversified life science conglomerates with reagent manufacturing scale, specialized cell biology reagent developers with growth factor and antibody portfolios, and European distribution channel holders for validated assay kits. Competitive moves concentrate on pre-qualified reagent lot standardization and endothelial cell sourcing network expansion.
Among diversified life science conglomerates, Thermo Fisher Scientific exemplifies the scale-driven archetype through reagent manufacturing infrastructure. Bio-Techne occupies a position within specialized cell biology reagent development, representing portfolio intensity across growth factor and antibody categories. Merck KGaA anchors the European distribution-focused tier, sitting within validated assay kit deployment for pharmaceutical toxicology programs. These three entities collectively represent the competitive structure without exhausting the vendor base.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Techne |
| Merck KGaA |
| Abcam |
| Cell Biolabs |
| BioVision |
| PromoCell GmbH |
| Sartorius |
| Kollodis BioSciences |
| Others |
Value Chain & Pricing Dynamics
ISO 10993 biocompatibility testing protocols gate qualified supply of GMP-compliant assay substrates while anchoring premium-tier pricing for validated reagent lots deployed in pharmaceutical toxicology programs. Buyers face tiered access determined by material qualification documentation depth, with pre-certified hydrogel alternatives commanding substantial markups over standard research-grade formats.
Pricing Analysis
Volume concentrates in economy-grade in vitro assay kits where per-test economics dominate pharmaceutical procurement decisions, while margins accrue to premium cell-based systems with pre-qualified endothelial cell sourcing and mechanistic validation packages. Price differentiation hinges on ISO certification tier and reagent lot traceability depth, with GMP-compliant workflows sustaining premium positioning. Cost compression in standard multiwell plate formats is intensifying as biotechnology procurement departments unbundle reagent sourcing from integrated platform contracts. Contract research organizations exhibit highest price sensitivity due to throughput scaling pressures, whereas late-stage pharmaceutical toxicology groups prioritize validation depth over unit economics.
Supply Chain Analysis
Direct-to-pharmaceutical channels handle validated assay kit distribution for toxicology programs, while specialized reagent manufacturers serve unbundling biotechnology procurement through direct purchasing relationships. Manufacturing concentrates in the United States, Germany, and Japan where biopharma R&D clusters anchor demand. Raw material dependencies include recombinant growth factor substrates, engineered endothelial cell lines, and synthetic hydrogel alternatives to Matrigel. Single-source vulnerability around umbilical cord tissue collection for primary HUVEC sourcing creates lot-to-lot inconsistency risks. Distribution runs through European channel holders for validated kits and direct manufacturer relationships for recombinant protein components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around suppliers capable of anchoring supply security for high-throughput workflows, with primary HUVEC supply volatility forcing weaker reagent vendors toward specialty niche positioning or exit.
For Market Incumbents: Hedge against biotechnology procurement unbundling by deepening captive supply of recombinant growth factor substrates and expanding pre-qualified endothelial cell sourcing networks across distributed manufacturing footprints. Anchor high-throughput screening relationships through supply security guarantees while building advisory capabilities around EU AI Act compliance documentation for automated image analysis algorithms. For New Entrants and Emerging Players: Launch via direct-to-biotechnology reagent sourcing models targeting venture-backed oncology startups in Research Triangle Park and Basel, where supply chain flexibility priorities override vendor consolidation rebates. Target organoid-vascular co-culture convergence as the most penetrable premium segment, exploiting capability gaps among legacy platform vendors in perfusable microvascular network integration. For Investors and Strategic Acquirers: CDSCO regulatory convergence with ICH standards in India is the leading indicator that GLP-compliant angiogenesis capability expansion will capture accelerating outsourced pharmaceutical screening from Western sponsors. Long-term viability favors contract development and manufacturing organizations with validated toxicology program relationships and backward integration into recombinant protein manufacturing. Watch for European pharmaceutical toxicology programs compressing validation timelines as the signal for supply-constrained premium pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Qualified Reagent Lot Standardization | Thermo Fisher Scientific anchors supply security for FDA-mandated oncology drug review packages. |
| Endothelial Cell Sourcing Network Expansion | Bio-Techne sustains R&D intensity across engineered lines supporting mechanistic vascularization data. |
| EU AI Act Compliance Service Development | Merck KGaA builds advisory revenue streams for algorithmic transparency documentation in tube formation quantification. |
| Organoid-Vascular Co-Culture Platform Launch | Specialized cell biology developers capture premium pricing for physiologically complex resistance models. |
| India CDMO GLP Capability Buildout | Hyderabad and Bangalore facilities capture outsourced pharmaceutical screening from Western sponsors. |
Study Parameters
Independent corroboration across drug development executives at pharmaceutical toxicology programs, regulatory affairs leads navigating FDA and EMA submission pathways, and contract research organization procurement managers underwrites the qualitative findings in this study. Secondary validation draws from FDA oncology drug review filings, EMA ICH S9 guidance documentation, ClinicalTrials.gov vascular-targeted therapy protocols, and ISO 10993 biocompatibility testing standards. Bottom-up demand modeling across assay platform deployments triangulates with top-down pharmaceutical R&D spending allocation estimates.
Rate-of-change decomposition across technology adoption curves, regulatory validation timeline compression, and biotechnology procurement pattern shifts structures the analytical framework throughout the forecast period. Segmentation dimensions span product type trade-offs between physiological fidelity and throughput, technology automation maturity tiers, application therapeutic area priorities, and end-user organizational procurement authority levels. CAGRs derive from compound annual trajectory fitting across validated assay kit volume projections and premium cell-based system value expansion, with inputs including high-content screening platform deployment rates and organoid-vascular co-culture method maturation timelines.
Primary HUVEC supply disruption, EU AI Act implementation delays for automated image analysis, and CDSCO regulatory enforcement variance in India are the dominant revision risks that could compress or extend forecast trajectories. Forecasts reflect assumptions around sustained pharmaceutical toxicology program outsourcing trends and biotechnology venture formation rates in vascular-targeted oncology. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Antenatal Screening Market
Clinical Diagnostics
Cervical Cancer Screening Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Global Breast Cancer Screening Test Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Global Biomarkers Market
Clinical Diagnostics
Genetic Disease Diagnostic Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
Bone Metabolism Test Market
Clinical Diagnostics
Kidney Function Tests Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Chronic Hepatitis B Virus Testing Market