
 Cell Free DNA Testing Market | 2026-2036
Cell Free DNA Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Free DNA Testing Market Intelligence
The shift toward Next-Generation Sequencing platforms with higher throughput and lower costs is tilting the competitive landscape for cfDNA testing. Illumina, Inc. sustains its market position through its dominance in sequencing hardware and consumables. Natera, Inc. specializes in reproductive health and organ transplant rejection testing. Meanwhile, Guardant Health, Inc. focuses on liquid biopsy tests for oncology, competing on clinical data and proprietary analytics.
Cell free DNA testing analyzes short, fragmented DNA molecules circulating in bodily fluids like plasma. These tests detect genetic and epigenetic alterations non-invasively for diagnostic and monitoring purposes. While oncology applications for therapy selection and recurrence monitoring are expanding rapidly, prenatal screening represents a mature, high-volume segment. Next-Generation Sequencing is the predominant technology, with digital PCR used for targeted, high-sensitivity applications.
Regulatory frameworks, including the US FDA's oversight of laboratory developed tests and the EU's In Vitro Diagnostic Regulation, dictate market access pathways. China's NMPA also imposes stringent approval requirements for diagnostic kits. These regulations directly influence clinical validation standards and commercialization timelines. The ability to generate robust clinical utility data to support reimbursement decisions remains the critical hurdle for market participants.
Market Dynamics
The central force shaping the cell free DNA testing market is the dual pressure of rapid technological advancement in sequencing and the stringent demands for clinical utility data from regulators and payors. This dynamic dictates research priorities, investment in large-scale trials, and market access strategies.
Growth Catalysts
- Oncology Application Expansion:The use of cfDNA for non-invasive cancer screening, therapy selection, and recurrence monitoring provides a substantial growth engine beyond the mature prenatal testing segment.
- Technological Sensitivity Gains:Advances in Next-Generation Sequencing and digital PCR technologies are improving detection limits for low-frequency genetic and epigenetic alterations, unlocking new diagnostic applications.
- Regulatory Pathway Clarification:Evolving frameworks like the US FDA's oversight for LDTs and the EU's IVDR, while demanding, create clearer pathways for manufacturers to achieve validated, marketable diagnostic products.
Market Restraints
- Reimbursement Hurdles:Securing consistent reimbursement from public and private payors remains a primary obstacle, as coverage decisions are contingent on extensive and costly clinical utility studies.
- Fragmented Regulatory Landscape:Divergent requirements between the US FDA, the EU's IVDR, and China's NMPA increase compliance costs and complicate global commercialization strategies for test developers.
- Analytical Sensitivity Limits:Detecting cfDNA from very early-stage tumors or in minimal residual disease settings remains technically challenging due to low tumor fraction, risking false-negative results.
Strategic Opportunities
- Minimal Residual Disease Monitoring:MRD testing in oncology represents a high-value opportunity for personalized patient management, guiding decisions on adjuvant therapy and detecting relapse earlier than imaging.
- Expansion into Non-Oncology Fields:There is significant potential for cfDNA applications in neurology for monitoring neurodegenerative diseases and in cardiology for assessing cardiovascular risk and organ transplant rejection.
- Underpenetrated Geographic Markets:Developing healthcare systems in certain Asia-Pacific and Latin American countries offer long-term growth potential as diagnostic infrastructure and reimbursement capabilities improve.
Industry Challenges
- Clinical Trial Execution:The high cost and logistical complexity of conducting large, prospective clinical trials necessary to demonstrate clinical utility and secure regulatory approval is a major barrier for market entrants.
- Bioinformatics Skill Gap:A persistent shortage of bioinformaticians and data scientists capable of developing and validating complex algorithms for cfDNA analysis creates a significant operational bottleneck.
- Pre-analytical Standardization:A lack of universally accepted standards for blood collection, sample handling, and cfDNA extraction protocols can lead to variability in test results and complicates inter-laboratory comparisons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Free DNA Testing Market |
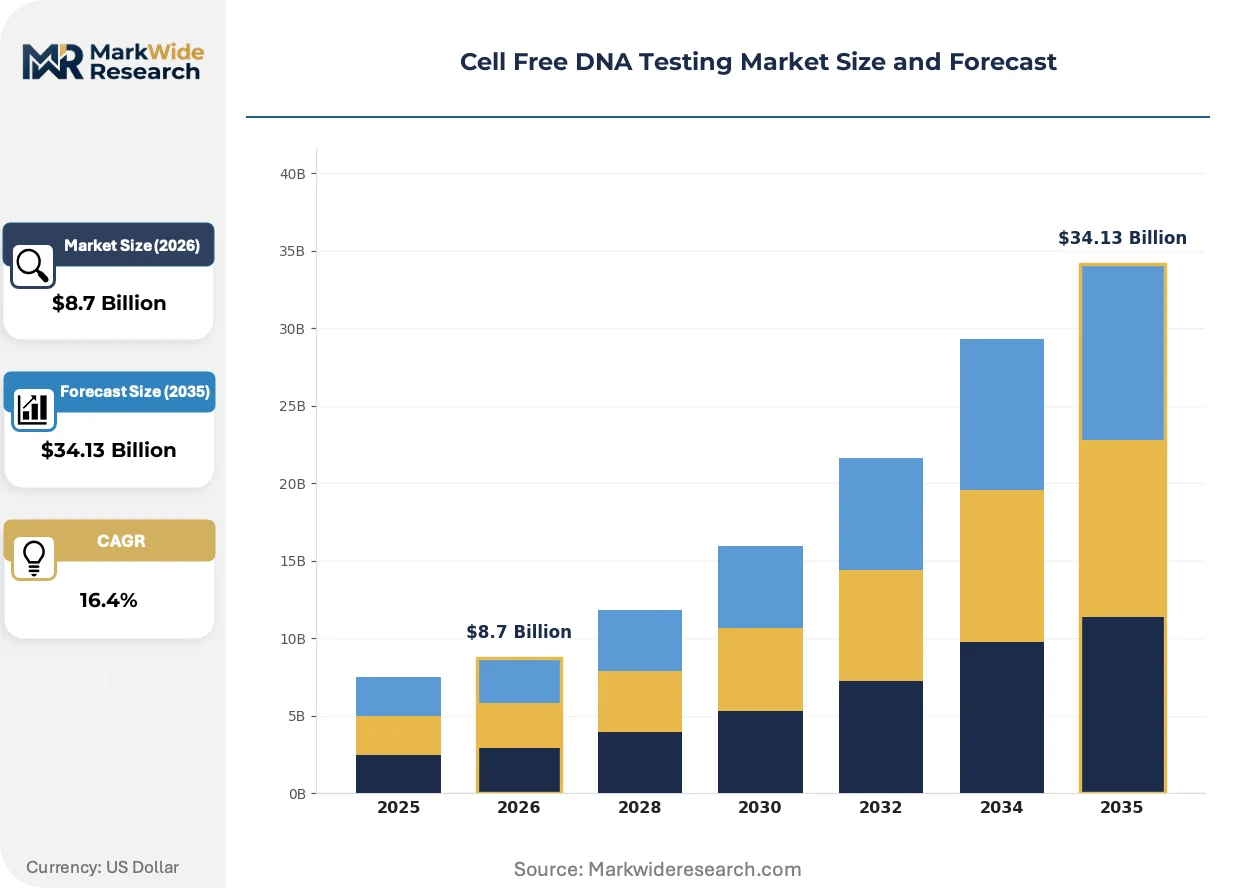
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Oncology, Prenatal Screening, Organ Transplantation, Infectious Diseases Technology: Next-Generation Sequencing, PCR, Digital PCR, Microarrays End User: Hospitals, Diagnostic Laboratories, Research Institutes, Clinics Sample Type: Plasma, Serum, Urine, Tissue |
| Companies Covered | Illumina, Inc., Natera, Inc., Guardant Health, Inc., F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Biocept, Inc., CareDx, Inc., Biodesix, Inc., Berry Genomics Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Free DNA Testing Market Strategic Shifts & Innovations
Innovation in the cell free DNA market is accelerating the transition of liquid biopsy from a research tool to a routine component of clinical care. This shift is underpinned by improvements in analytical performance and the integration of multi-omic data to enhance diagnostic accuracy.
Multi-modal analysis combines genomic data like mutations with epigenomic information such as methylation patterns from a single cfDNA sample. Oncology and reproductive health segments are rapidly adopting this for improved test performance and accuracy. The integration of these disparate data types is collapsing the boundary between targeted assays and comprehensive molecular profiling, providing a holistic view of disease from one blood draw.
The European Union's In Vitro Diagnostic Regulation (IVDR) is a significant policy shift impacting the market. It mandates more stringent requirements for clinical evidence, performance evaluation, and post-market surveillance for all diagnostic tests. Laboratory Developed Tests (LDTs), which are prevalent in academic centers in Germany and France, are most affected as they now face a higher validation burden to remain on the market.
Patient demand for direct access to health information is altering traditional diagnostic pathways. The established model where specialists are the exclusive gatekeepers for advanced testing is being supplemented by primary care physicians ordering tests and even direct-to-consumer platforms. This behavioral shift is most advanced in the United States, where a culture of consumer genetics and evolving care models encourage broader test accessibility.
Cell Free DNA Testing Market Segmentation
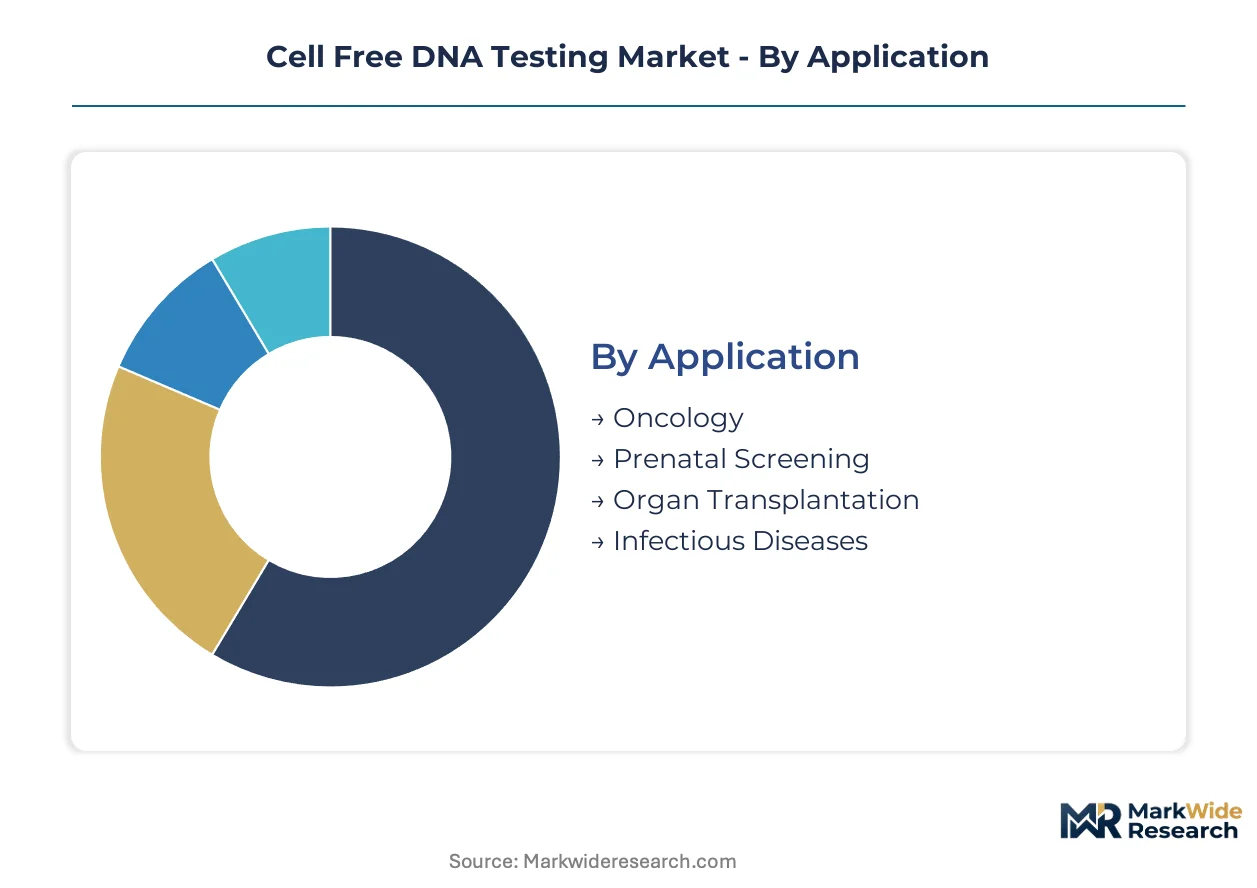
The cell free DNA testing market is precisely segmented to reflect the diverse applications, technological underpinnings, end-user profiles, and biological sample types driving its expansion. Understanding these distinct segments illuminates where innovation and commercial growth are most concentrated, guiding strategic investments across the diagnostic landscape.
Application:
The use-case spectrum for cell free DNA testing ranges from established screening programs to rapidly emerging diagnostic and monitoring tools in complex diseases.
- Oncology:This segment includes applications for non-invasive cancer screening, early detection, therapy selection, and recurrence monitoring. Demand concentrates heavily in the United States and key European markets, driven by the imperative for personalized cancer care and reduced invasiveness.
- Prenatal Screening:Encompassing non-invasive prenatal testing (NIPT) for chromosomal abnormalities, this represents a mature, high-volume segment. Established healthcare systems in countries like Germany and France show sustained demand due to strong clinical guidelines and patient acceptance.
- Organ Transplantation:cfDNA testing in this area monitors organ rejection non-invasively, providing an alternative to biopsy.
- Infectious Diseases:This application involves detecting pathogen DNA in bodily fluids for diagnosis and monitoring of infections.
Established volume favors Prenatal Screening; emerging adoption favors Oncology.
Technology:
The technological platforms underpinning cfDNA analysis vary in their throughput, sensitivity, and cost, influencing their suitability for different clinical applications.
- Next-Generation Sequencing:This high-throughput technology enables comprehensive genomic profiling of cfDNA, detecting a broad range of genetic and epigenetic alterations. Its scalability and falling costs drive widespread adoption in both research and clinical settings, particularly in the United States.
- Digital PCR:Offering ultra-high sensitivity for targeted detection of low-frequency genetic variants, digital PCR is crucial for applications like minimal residual disease monitoring. Demand for this precision technology is growing in specialized diagnostic laboratories in Europe.
- PCR:Polymerase Chain Reaction (PCR) provides a rapid and cost-effective method for amplifying specific DNA sequences.
- Microarrays:These platforms allow for parallel analysis of thousands of DNA sequences, historically used for genetic screening.
The versatility of Next-Generation Sequencing underpins broad utility, while Digital PCR drives specialized high-sensitivity applications.
End User:
Different healthcare providers and research entities leverage cfDNA testing based on their operational models, patient populations, and diagnostic capabilities.
- Hospitals:These institutions integrate cfDNA tests into routine clinical practice for a range of diagnostic and monitoring applications, often for immediate patient management. Hospital systems in countries with established healthcare infrastructure, such as the United States and Germany, represent significant end-users.
- Diagnostic Laboratories:Centralized diagnostic laboratories perform high-volume cfDNA testing, offering specialized services to hospitals, clinics, and physicians. These labs, particularly in Europe, benefit from economies of scale and advanced analytical capabilities.
- Research Institutes:These organizations utilize cfDNA testing for discovery, validation, and development of new diagnostic biomarkers.
- Clinics:Smaller clinics and specialized practices adopt cfDNA tests for specific patient populations, often referring complex cases to larger labs.
Demand from Hospitals reflects direct patient care, while Diagnostic Laboratories focus on large-scale processing and specialized testing.
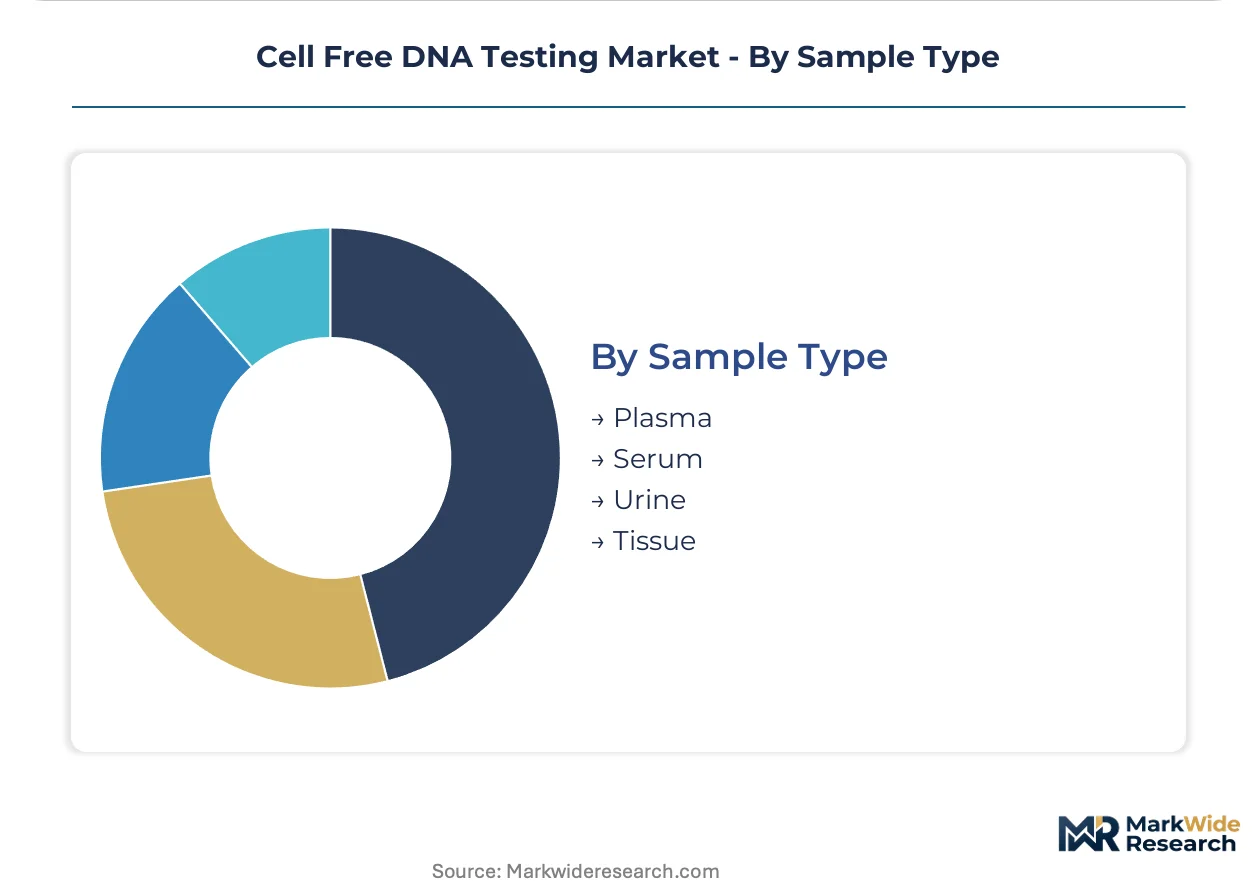
Sample Type:
The choice of biological sample for cfDNA testing is dictated by the specific clinical application, invasiveness, and the concentration of target DNA fragments.
- Plasma:As the most common sample type, plasma offers a non-invasive source of cfDNA for a wide array of applications, including oncology and prenatal screening. Its ease of collection and high utility make it a primary choice across global markets.
- Serum:Similar to plasma, serum is another blood-derived sample type used for cfDNA analysis, though it requires slightly different processing. It finds utility in various diagnostic contexts, particularly in research.
- Urine:Urine samples are gaining traction for specific applications, especially in urological cancers and infectious disease detection.
- Tissue:While not cell-free, tissue biopsies remain the gold standard for definitive diagnosis and are often complemented by cfDNA tests.
The accessibility of Plasma makes it a primary choice, contrasting with Urine's utility in specific diagnostic contexts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for cell free DNA testing concentrates in regions with advanced healthcare systems and established reimbursement pathways. Hospitals and diagnostic laboratories in these areas are primary adopters, integrating cfDNA tests into routine clinical practice. This buyer concentration is particularly evident in developed economies.
United States
The United States exhibits strong demand for cfDNA testing, particularly in oncology for therapy selection and recurrence monitoring. The US FDA's evolving oversight for laboratory developed tests shapes market access for new diagnostic products. California's life science clusters, including the Bay Area, actively advance next-generation sequencing applications.
Germany
German healthcare providers show sustained demand for non-invasive prenatal testing and emerging oncology applications. The EU's IVDR imposes stringent requirements for clinical evidence, impacting diagnostic laboratories in the country. Berlin's research institutions collaborate on advanced digital PCR techniques for high-sensitivity detection.
France
French clinicians prioritize prenatal screening due to established clinical guidelines and patient acceptance. The ANSM, France's national agency for medicine and health products, influences diagnostic kit approvals. Paris-based medical centers actively integrate cfDNA testing for early disease detection.
Japan
Japanese medical institutions increasingly adopt cfDNA for non-invasive diagnostics in oncology and prenatal screening. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates the introduction of new diagnostic technologies. Tokyo's research hospitals lead clinical trials for novel cfDNA biomarkers.
China
China presents a substantial growth opportunity, driven by expanding healthcare infrastructure and rising demand for advanced diagnostics. The NMPA imposes stringent approval requirements for diagnostic kits, influencing market entry strategies. Shanghai's biotechnology parks foster local development of cfDNA sequencing platforms.
Cell Free DNA Testing Market Key Industry Players
Channel-controlling players compete with product-specialist players, shaping the cell free DNA testing market structure. The market exhibits a tiered competitive landscape, with established technology providers alongside agile diagnostic developers. Strategic archetypes include comprehensive platform providers, niche application specialists, and integrated liquid biopsy solution providers. Companies often pursue strategic partnerships to expand market reach or diversify their diagnostic portfolios.
Specialists in comprehensive sequencing platforms and consumables include Illumina, Inc., anchoring the market's technological infrastructure. Natera, Inc. represents a focused archetype, emphasizing reproductive health and organ transplant rejection testing within specific clinical areas. Guardant Health, Inc. exemplifies a liquid biopsy solution provider, concentrating on oncology applications and proprietary analytics for early detection and monitoring. These entities collectively illustrate the varied strategic approaches within the cfDNA testing ecosystem, each leveraging distinct strengths for market penetration.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Natera, Inc. |
| Guardant Health, Inc. |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Biocept, Inc. |
| CareDx, Inc. |
| Biodesix, Inc. |
| Berry Genomics Co. Ltd |
| Others |
Cost & Logistics Intelligence
Dominance in Next-Generation Sequencing (NGS) hardware and consumables, particularly by Illumina, concentrates significant margin pools upstream, influencing the cost structures for downstream cfDNA diagnostic service providers.
Pricing Analysis
Cost-plus contract patterns, often indexed to the complexity of genetic analysis and regulatory validation, largely define pricing in cfDNA testing. Value-based pricing models are emerging, tying test cost to demonstrated clinical utility and patient outcomes. Price differentiation stems from the breadth of genetic alterations detected and the level of regulatory approval, such as FDA clearance or IVDR compliance. Reimbursement hurdles from public and private payors create significant pricing pressure. Research institutes exhibit higher price sensitivity compared to hospitals, which prioritize immediate patient management.
Supply Chain Analysis
Upstream feedstock for cfDNA testing, primarily Next-Generation Sequencing reagents and specialized enzymes, largely originates from the United States and, increasingly, China. Key dependencies include high-purity DNA extraction kits and advanced bioinformatics software for data interpretation. Single-source vulnerability for essential sequencing components, like those from Illumina, poses a structural supply chain risk. Distribution typically runs through centralized diagnostic laboratories, which then provide services to hospitals and clinics. Germany's research institutions also contribute to specialized component development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defending against substitution is critical for the cfDNA testing market. Incumbents must navigate the threat of traditional invasive biopsies remaining the gold standard for definitive diagnosis in many clinical contexts.
For Market Incumbents: Harden market position by investing heavily in large-scale clinical trials to generate robust utility data, countering the threat from less-validated laboratory developed tests. Acquire specialized bioinformatics firms to enhance proprietary analytics and data interpretation capabilities. Prioritize R&D in multi-modal analysis to improve diagnostic accuracy and broaden application scope. This strategic investment strengthens competitive advantage against agile diagnostic developers.
For New Entrants and Emerging Players: Underpenetration in Asia-Pacific and Latin American markets offers significant entry points for cfDNA testing. Target non-oncology fields like neurology and cardiology, where established solutions are less dominant. Develop cost-effective, high-sensitivity tests tailored to specific regional disease burdens. Partner with local diagnostic laboratories and healthcare providers to navigate regulatory complexities and build trust, leveraging localized clinical data.
For Investors and Strategic Acquirers: Capital is best deployed toward niche application specialists demonstrating clear clinical utility and strong regulatory compliance in high-growth segments. The market offers long-term viability, driven by expanding oncology applications and emerging non-oncology fields. Acquire companies specializing in minimal residual disease monitoring or multi-modal analysis platforms. The signal to watch is expanding reimbursement coverage for novel cfDNA indications, indicating broader market acceptance and revenue pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Securing FDA/IVDR approval validates test performance for broader clinical adoption. |
| Platform Integration | Combining genomic and epigenomic data enhances diagnostic accuracy in oncology. |
| Strategic Partnership | Collaborating with regional diagnostic labs expands market reach and localized data generation. |
| Acquisition of Specialist Firm | Integrating proprietary analytics strengthens competitive advantage in specific disease areas. |
| Reimbursement Strategy | Proactively engaging payors ensures broader access and sustainable revenue streams for new tests. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary validation. Primary research included conversations with diagnostic lab directors, hospital oncologists, regulatory affairs specialists, and cfDNA test developers. Secondary sources encompassed FDA filings, EU IVDR guidance documents, NMPA approval databases, and peer-reviewed scientific literature. This approach enabled bottom-up data collection, triangulated with top-down market sizing for accuracy.
Forecast inputs considered market size, historical growth, and projected technological advancements across the analysis window. The analytical framework segmented the market by application, technology, end-user, sample type, and specific disease indication. Compound Annual Growth Rates were derived from historical trends and anticipated shifts in regulatory approval timelines and reimbursement policies. This comprehensive modeling captures the market's evolving dynamics over the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by comprehensive platform providers or niche specialists would shift outcomes. Forecasts reflect documented assumptions, but unforeseen regulatory changes or rapid technological breakthroughs in sequencing could revise projections. Cross-checking against external clinical trial outcomes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Cell-Free Fetal DNA Testing Market
Clinical Diagnostics
Bacterial and Viral Specimen Collection Market
Clinical Diagnostics
Global Cardiac Marker Testing Market
Clinical Diagnostics
Kidney Function Tests Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Clinical Diagnostic Equipment Market
Clinical Diagnostics
Renal Function Test Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Bone Metabolism Test Market
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
Lab Automation in Clinical Diagnostics Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market