
 Mitochondrial Myopathy Diagnosis and Treatment Market | 2026-2036
Mitochondrial Myopathy Diagnosis and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Mitochondrial Myopathy Diagnosis and Treatment Market Outlook
Genetic counseling subscription services is restructuring how diagnosis and treatment decisions get bundled across care pathways. Ultragenyx Pharmaceutical leverages its rare disease infrastructure to anchor North American distribution of mitochondrial therapies. Sarepta Therapeutics sustains competitive pressure through its gene therapy development engine. Khondrion specializes in small-molecule mitochondrial modulators, occupying a distinct niche against larger biopharma rivals.
Mitochondrial myopathy diagnosis and treatment encompasses the clinical identification and therapeutic management of disorders caused by mitochondrial DNA mutations or nuclear DNA defects affecting oxidative phosphorylation, typically assessed through muscle biopsy histochemistry, respiratory chain enzyme assays, and molecular genetic analysis with threshold mutant load quantification. Its primary purpose centers on halting disease progression, managing multisystem complications, and extending functional independence for patients with energy metabolism failure. Genetic testing now leads product type segmentation due to its non-invasive sample requirements and expanding gene panel coverage, while enzyme replacement therapy represents the fastest-growing margin pool as novel biologics advance through late-stage pipelines. Next-generation sequencing dominates technology adoption, though metabolomics is gaining traction for unresolved cases requiring functional profiling beyond static genotype data.
The FDA orphan drug program shapes therapeutic development economics through tax credits and market exclusivity provisions, while the EMA's parallel designation streamlines European access for mitochondrial therapies. HIPAA governs genetic data portability across US care settings, directly influencing how diagnostic platforms integrate with hospital electronic records. Stakeholders must monitor how payer coverage policies for whole exome sequencing evolve relative to targeted mitochondrial gene panels.
Market Dynamics
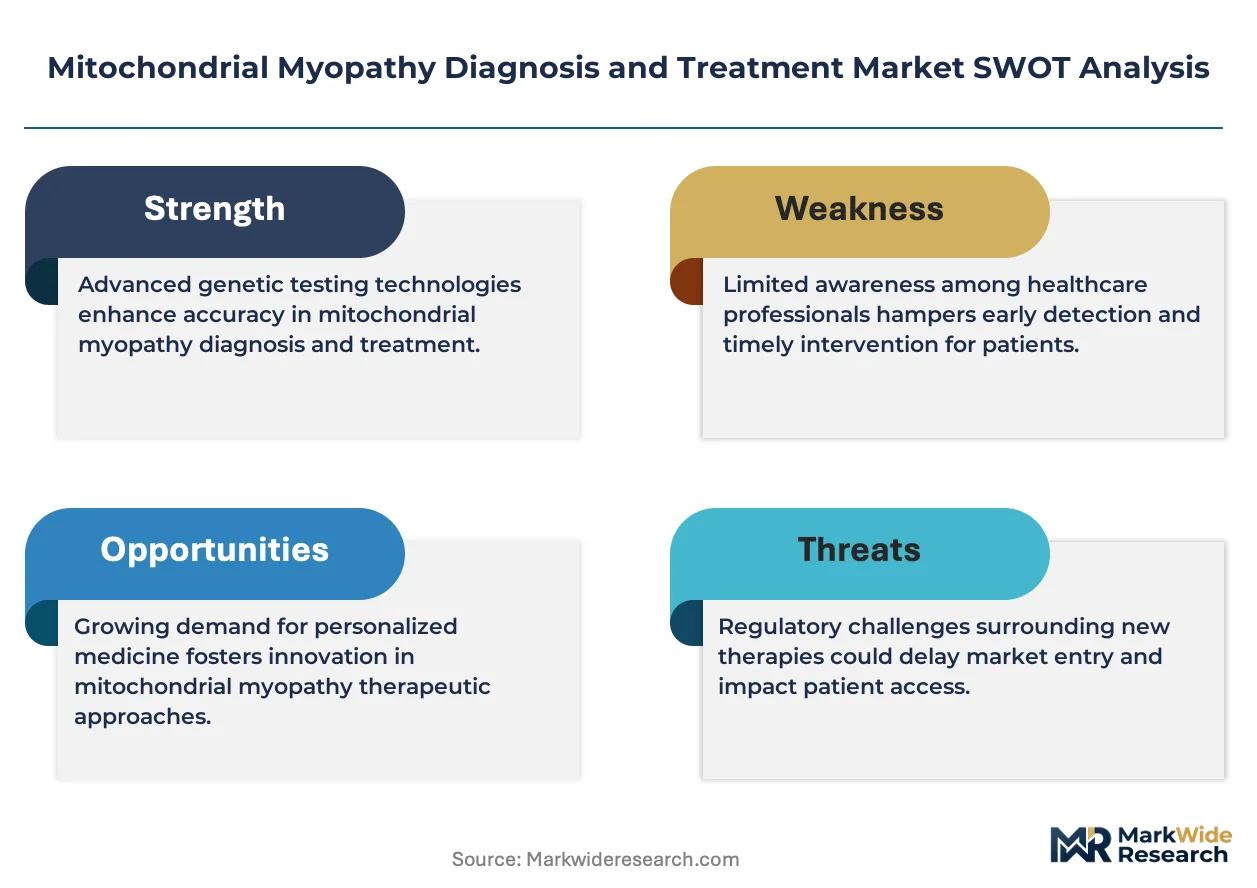
The orphan drug designation pipeline is compressing development timelines for mitochondrial therapies while simultaneously concentrating R&D investment among rare disease specialists with existing regulatory infrastructure.
Growth Catalysts
- EMA Parallel Designation:The European Medicines Agency's streamlined orphan pathway accelerates European market entry for therapies already cleared through FDA programs. Biopharma firms leverage this regulatory bridge to compress multi-territory launch schedules.
- Metabolic Center Expansion:Hospital-based neurology departments in the United States are building dedicated mitochondrial disorder screening programs. These specialized units create concentrated demand nodes that anchor regional treatment networks.
- Next-Generation Sequencing:NGS platforms are automating mutant load quantification at diagnostic laboratories. The technology reduces turnaround times for complex mitochondrial DNA analysis from weeks to days.
Market Restraints
- Specialized Biopsy Infrastructure:Muscle biopsy histochemistry requires frozen tissue processing capabilities available only at tertiary academic centers. This geographic concentration limits diagnostic access outside major metropolitan clusters.
- Respiratory Chain Enzyme Volatility:Assay reproducibility depends on tissue handling protocols that vary across collection sites. Inconsistent pre-analytical conditions degrade result reliability and trigger repeat testing cycles.
- Gene Therapy Manufacturing Bottlenecks:Viral vector production capacity concentrates at contract manufacturing organizations in the United States and Europe. This supply tightness extends lead times for clinical-grade material.
Strategic Opportunities
- Metabolomics Integration:Functional profiling technologies are penetrating unresolved diagnostic cases where static genotype data proves inconclusive. Laboratories combining metabolomics with NGS capture premium pricing for complex phenotyping.
- Genetic Counseling Subscription Models:Bundled decision-support services are restructuring how diagnosis and treatment pathways align across care continuums. Health systems in the United States pilot annual contracts covering pre-test counseling through post-result management.
- Whole Exome Sequencing Reimbursement:Payer coverage policies for comprehensive genomic testing are expanding relative to targeted mitochondrial panels. Diagnostic platforms capturing this reimbursement shift gain volume in undiagnosed patient populations.
Industry Challenges
- HIPAA-Compliant Data Integration:Genetic data portability requirements constrain how diagnostic platforms interface with hospital electronic records. Vendors must rebuild data architectures to satisfy both security mandates and clinical workflow demands.
- Multisystem Care Coordination:Mitochondrial myopathy management spans cardiology, neurology, endocrinology, and ophthalmology. Siloed specialty practices fragment patient journeys and complicate outcomes measurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mitochondrial Myopathy Diagnosis and Treatment Market |
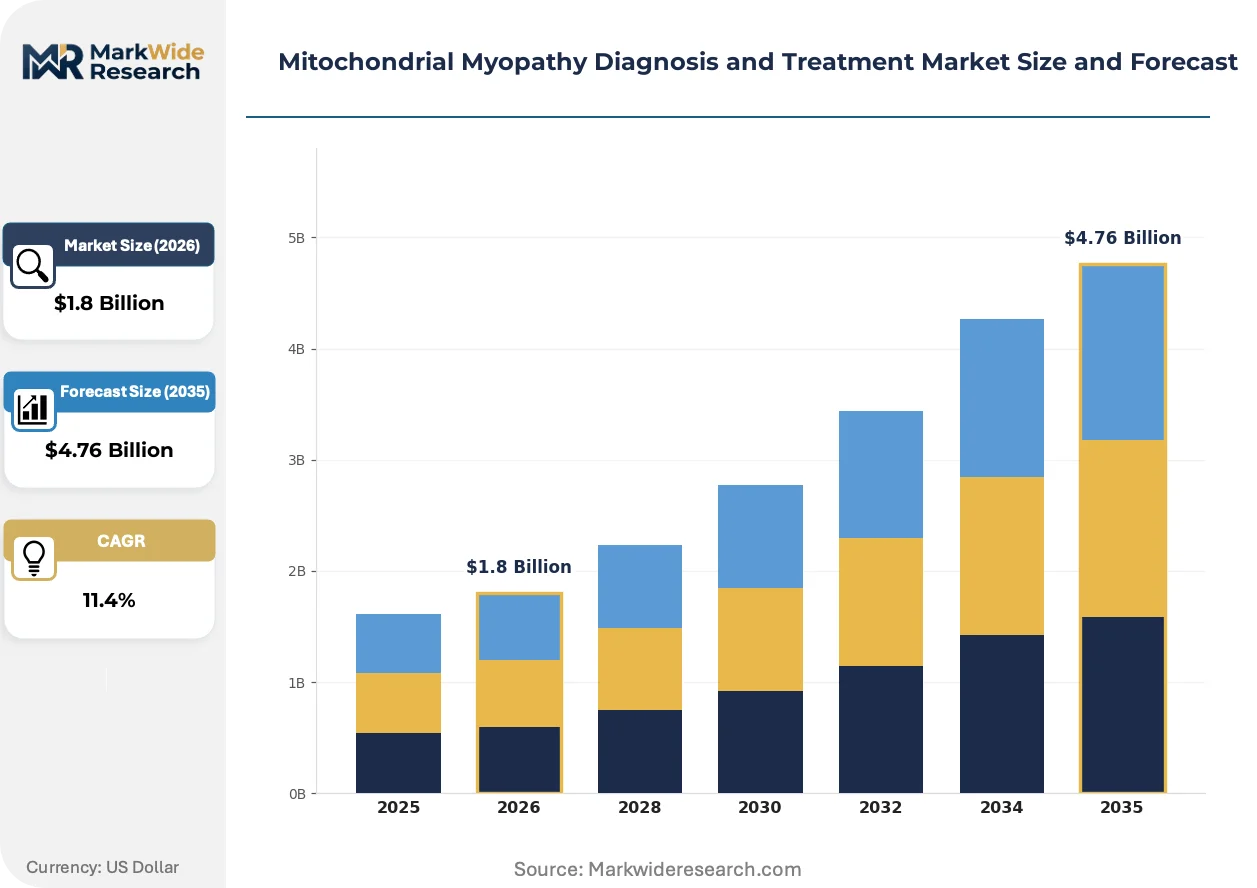
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Enzyme Replacement Therapy, Supplements, Genetic Testing End User: Hospitals, Outpatient Clinics, Home Care, Research Laboratories Technology: Next-Generation Sequencing, PCR, Microarray Analysis, Metabolomics Delivery Mode: Oral, Intravenous, Subcutaneous, Intranasal |
| Companies Covered | Ultragenyx Pharmaceutical, Pfizer, Sarepta Therapeutics, Khondrion, Sanofi, PTC Therapeutics, Astellas Pharma, GeneDx, Stealth BioTherapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mitochondrial Myopathy Diagnosis and Treatment Market Strategic Shifts
Artificial intelligence tools are compressing variant interpretation timelines while regulatory harmonization efforts reshape multi-territory commercialization strategies. These forces intersect with evolving procurement patterns that favor integrated diagnostic service bundles over transactional testing arrangements.
Artificial intelligence variant classification systems are automating the triage of ambiguous mitochondrial DNA findings. Diagnostic laboratories at Massachusetts General Hospital and Stanford Medicine deploy these platforms to prioritize cases requiring manual review. The technology is automating preliminary pathogenicity scoring that previously consumed genetic counselor hours.
The FDA's orphan drug tax credit provisions are restructuring therapeutic development economics for rare mitochondrial conditions. Developers now front-load clinical investment knowing market exclusivity protections extend revenue horizons. Small-molecule programs targeting oxidative phosphorylation defects capture disproportionate benefit from this incentive structure.
Hospital procurement committees are consolidating vendor relationships around end-to-end diagnostic service contracts. Academic medical centers in Boston and San Francisco now negotiate multi-year agreements covering sequencing, interpretation, and genetic counseling. This bundling displaces transactional per-test pricing that dominated the 2015-2020 period.
Mitochondrial Myopathy Diagnosis and Treatment Market Segmentation
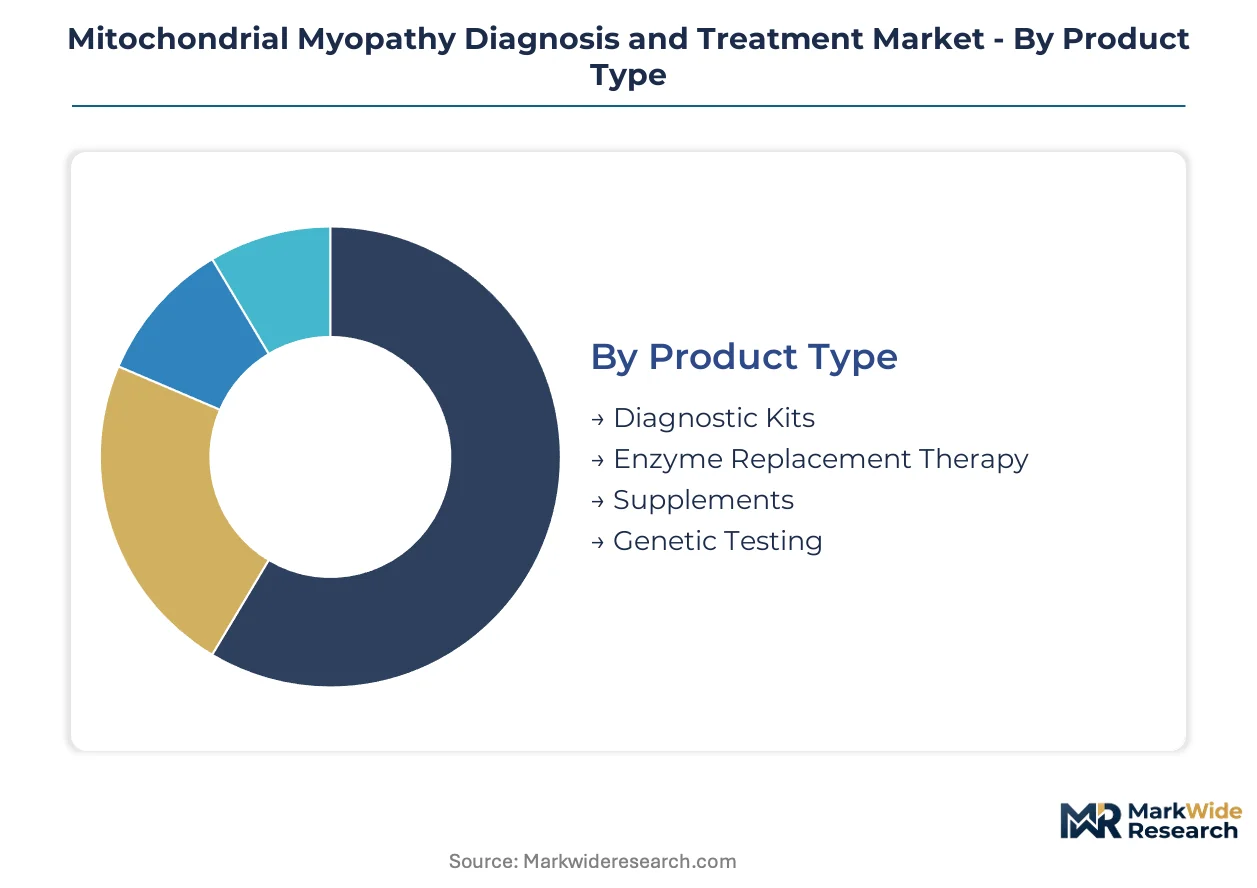
Segmentation in mitochondrial myopathy care reveals how diagnostic workflows diverge from therapeutic administration. Each category reflects distinct procurement patterns, regulatory pathways, and site-of-service economics that shape vendor positioning.
Product Type:
Customization spans from commoditized biochemical assays to patient-specific genetic interpretations, with standardization concentrated in high-volume screening tools.
- Genetic Testing:Non-invasive sample requirements and expanding gene panel coverage drive hospital laboratory adoption. Demand concentrates in United States metabolic centers where whole exome sequencing reimbursement outpaces targeted panels. The FDA's orphan drug tax credits indirectly accelerate companion diagnostic development for emerging therapies.
- Enzyme Replacement Therapy:Novel biologics targeting oxidative phosphorylation defects advance through late-stage pipelines. Intravenous administration infrastructure at tertiary academic centers anchors regional distribution networks. Manufacturing bottlenecks at contract organizations extend clinical-grade material lead times.
- Diagnostic Kits:Respiratory chain enzyme assay platforms automate mutant load quantification for frozen tissue analysis.
- Supplements:Coenzyme Q10 and mitochondrial cofactor formulations occupy over-the-counter and prescription channels.
Leading the category by volume: Genetic Testing. Growing fastest: Enzyme Replacement Therapy.
End User:
Patient acuity and care coordination complexity determine site selection, with high-complexity cases clustering where multispecialty integration exists.
- Hospitals:Neurology departments at Massachusetts General Hospital and Stanford Medicine deploy integrated diagnostic service contracts covering sequencing through genetic counseling. Bundled annual agreements displace transactional per-test pricing. HIPAA-compliant data architectures constrain electronic record integration.
- Research Laboratories:Artificial intelligence variant classification systems automate triage of ambiguous mitochondrial DNA findings. Academic medical centers in Boston and San Francisco pilot metabolomics-NGS combinations for unresolved phenotyping. Functional profiling commands premium pricing where static genotype data proves inconclusive.
- Outpatient Clinics:Community neurology practices refer complex cases to tertiary screening programs.
- Home Care:Oral supplement regimens and subcutaneous enzyme administration shift selected therapies outside institutional settings.
Highest patient volume flows through Hospitals. Steepest expansion trajectory: Research Laboratories.
Technology:
Throughput economics and interpretive depth create tiered adoption patterns across laboratory infrastructure investment levels.
- Next-Generation Sequencing:Automated platforms reduce mitochondrial DNA analysis turnaround from weeks to days. NGS dominates diagnostic laboratory capital expenditure with standardized workflows. The EMA's parallel orphan designation streamlines European access for companion diagnostics developed alongside FDA-cleared therapies.
- Metabolomics:Functional profiling penetrates unresolved cases requiring dynamic assessment beyond static genotype data. Laboratories combining metabolomics with NGS capture complex phenotyping premiums. Pre-analytical handling protocols vary across collection sites, degrading result reliability.
- PCR:Targeted amplification remains cost-effective for known mutation hotspots.
- Microarray Analysis:Comparative genomic hybridization detects large-scale mitochondrial DNA rearrangements.
Dominant installed base: Next-Generation Sequencing. Gaining share fastest: Metabolomics.
Delivery Mode:
Route selection balances bioavailability requirements against patient self-administration capacity and site-of-care economics.
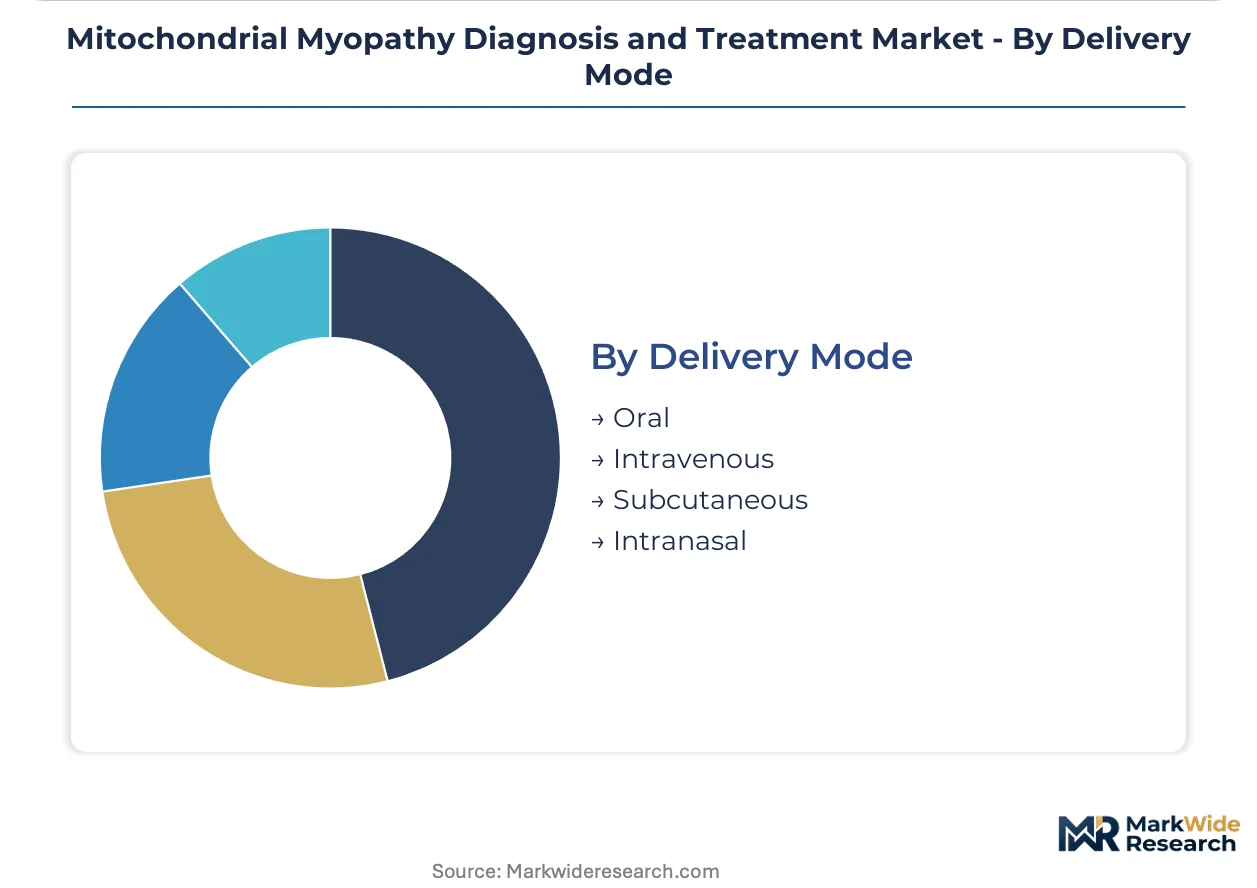
- Intravenous:Enzyme replacement biologics require infusion center infrastructure concentrated at academic medical centers. Viral vector gene therapies under development specify intravenous administration protocols. Supply tightness at contract manufacturing organizations extends clinical-grade material availability.
- Oral:Small-molecule mitochondrial modulators from Khondrion and similar developers target patient self-administration. Coenzyme Q10 and cofactor supplements distribute through retail pharmacy and direct-to-consumer channels. Bioavailability limitations drive formulation innovation.
- Subcutaneous:Emerging enzyme therapies explore depot formulations for reduced infusion frequency.
- Intranasal:Experimental delivery routes target central nervous system penetration for neurodegenerative mitochondrial phenotypes.
Primary administration route: Intravenous. Climbing the fastest: Oral.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic capacity concentrates in tertiary academic centers while therapeutic demand spreads across regional hospital networks. The United States hosts the densest cluster of specialized metabolic centers, though Germany and Japan maintain comparable per-capita screening infrastructure.
United States
Massachusetts General Hospital and Stanford Medicine anchor integrated diagnostic service contracts covering sequencing through genetic counseling. HIPAA governs genetic data portability across care settings, constraining how platforms interface with hospital electronic records. Boston and San Francisco academic medical centers pilot metabolomics-NGS combinations for unresolved phenotyping.
Germany
University hospital networks in Munich and Heidelberg expand mitochondrial disorder screening programs with bundled annual agreements. The EMA's parallel orphan designation streamlines European market entry for therapies cleared through FDA programs. Bavaria's metabolic centers concentrate frozen tissue processing capabilities unavailable elsewhere in Central Europe.
Japan
PMDA's expedited review pathway for rare diseases compresses approval timelines for mitochondrial therapies. Tokyo and Osaka academic hospitals deploy next-generation sequencing platforms automating mutant load quantification. The country's centralized healthcare system enables rapid diffusion of diagnostic protocols from tertiary centers to regional networks.
United Kingdom
NHS England's specialized commissioning framework concentrates complex mitochondrial diagnostics at designated supra-regional centers. London and Cambridge genetic laboratories capture premium pricing for whole exome sequencing relative to targeted panels. Genomics England's infrastructure supports population-scale variant interpretation for unresolved cases.
Canada
Health Canada's regulatory alignment with FDA orphan drug provisions accelerates therapeutic access for rare mitochondrial conditions. Toronto and Montreal academic hospitals maintain frozen tissue processing capabilities for respiratory chain enzyme assays. Provincial health plans expand reimbursement for comprehensive genomic testing beyond targeted gene panels.
Mitochondrial Myopathy Diagnosis and Treatment Market Competitive Environment
Top-tier vendors anchor rare disease infrastructure, while mid-cap specialists occupy distinct technology niches. The market structures around regulatory capability, manufacturing scale, and therapeutic modality expertise. Three archetypes dominate: gene therapy developers, small-molecule modulators, and integrated diagnostic service providers. Consolidation pressures favor players with existing FDA orphan drug designation experience and viral vector production relationships.
Among North American rare disease specialists, Ultragenyx Pharmaceutical and Sarepta Therapeutics represent the gene therapy development archetype, while Khondrion exemplifies the small-molecule mitochondrial modulator position. These companies occupy differentiated competitive terrain against larger biopharma rivals with broader therapeutic portfolios.
| Leading Market Players |
|---|
| Ultragenyx Pharmaceutical |
| Pfizer |
| Sarepta Therapeutics |
| Khondrion |
| Sanofi |
| PTC Therapeutics |
| Astellas Pharma |
| GeneDx |
| Stealth BioTherapeutics |
| Others |
Value Chain & Pricing Dynamics
Specialized reagent costs for respiratory chain enzyme assays cascade through diagnostic service bundles into tiered pricing structures across United States metabolic centers. Contract manufacturing capacity for viral vector gene therapies concentrates pricing power among select biologics producers serving late-stage clinical pipelines.
Pricing Analysis
Cost-down pressure on genetic testing services accelerates because hospital procurement committees consolidate vendor relationships around multi-year bundled agreements. Three-tier pricing structure across premium, standard, and economy levels separates comprehensive metabolomics-NGS combinations from basic panel screening and research-grade sequencing. Quality grade and certification level—specifically CAP/CLIA laboratory accreditation—drive price differentiation between academic medical center laboratories and commercial reference labs. Pricing pressure stems from frozen tissue processing infrastructure scarcity, which limits competitive entry and sustains premium capture at tertiary centers. Community neurology practices exhibit highest price sensitivity, while integrated health systems with captive laboratory assets demonstrate least sensitivity due to cost absorption across care continuums.
Supply Chain Analysis
Direct-to-hospital channels handle complex diagnostic demand from United States academic medical centers, while specialty distributor networks serve outpatient clinic and research laboratory segments. Viral vector production concentrates in the United States, Germany, and Switzerland among contract manufacturing organizations with established gene therapy infrastructure. Raw material dependencies include synthetic nucleotides for NGS platforms, specialized histochemical stains for muscle biopsy analysis, and clinical-grade plasmids for gene therapy manufacturing. Supply chain risk centers on single-source vulnerability for rare isotope-labeled metabolites essential to functional profiling assays. Distribution runs through regional metabolic center networks that anchor patient referral patterns and concentrate demand nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into viral vector manufacturing and captive diagnostic laboratory capacity represents the decisive competitive race in mitochondrial therapeutics. Players securing upstream biologics production or downstream testing infrastructure capture margin otherwise lost to contract manufacturing premiums.
For Market Incumbents: Anchor rare disease regulatory expertise through expanded FDA orphan drug designation portfolios and EMA parallel pathway submissions. Gene therapy developers face manufacturing bottlenecks at contract organizations; backward integration into viral vector production secures clinical-grade material availability. Incumbents should consolidate genetic counseling subscription capabilities to lock in hospital system relationships before bundled annual agreements mature. For New Entrants and Emerging Players: Enter via metabolomics-NGS combination platforms targeting unresolved diagnostic cases where static genotype data proves inconclusive. Research laboratories at academic medical centers in Boston and San Francisco represent the most penetrable segment due to pilot program expansion and premium pricing tolerance for functional phenotyping. A direct-to-laboratory sales model bypassing hospital procurement committees accelerates initial traction. For Investors and Strategic Acquirers: Distressed-cycle entries favor small-molecule mitochondrial modulator developers in the Netherlands and United Kingdom facing late-stage clinical funding gaps. Long-term viability over the next decade hinges on successful navigation of gene therapy manufacturing scale-up and reimbursement negotiation for whole exome sequencing. The signal to watch is payer coverage policy expansion for comprehensive genomic testing relative to targeted panels.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA tax credits and market exclusivity provisions restructure development economics for rare mitochondrial conditions. |
| Metabolomics Platform Integration | Laboratories combining functional profiling with NGS capture premium pricing for unresolved phenotyping cases. |
| Genetic Counseling Subscription Launch | Annual bundled contracts displace transactional per-test pricing across United States health systems. |
| Viral Vector Manufacturing Scale-Up | Captive production capacity at contract organizations reduces clinical-grade material lead times for gene therapies. |
| HIPAA-Compliant Data Architecture Investment | Rebuilt platform interfaces satisfy genetic data portability mandates while preserving hospital electronic record integration. |
Study Parameters
FDA orphan drug filings, ClinicalTrials.gov records, and hospital procurement databases formed the secondary backbone for market sizing and competitive positioning. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers validated secondary findings and informed demand assumptions. Bottom-up and top-down triangulation across patient population estimates and service revenue flows anchored volume and value projections.
Bottom-up modeling of genetic testing volumes, enzyme replacement therapy administration rates, and diagnostic kit utilization across United States, German, and Japanese metabolic centers generated segment-level outputs. Top-down cross-checks against national health expenditure data and rare disease research funding allocations confirmed order-of-magnitude alignment. Segmentation dimensions included product type, end user, technology platform, and delivery mode across the projection horizon. CAGRs derived from fitted growth curves incorporating regulatory approval timelines and reimbursement policy trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under gene therapy manufacturing delays or payer coverage reversals for comprehensive genomic testing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Colorectal Cancer Molecular Diagnostics Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Preimplantation Genetic Testing Market
Clinical Diagnostics
Chronic Hepatitis B Virus Testing Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Global Biomarkers Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
Global Breast Cancer Screening Test Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Nitric Oxide Asthma Testing Market