
 Welded Blisters Market | 2026-2036
Welded Blisters Market Size, Share, and Industry Trends Forecast 2026-2036
Welded Blisters Market Analytics
Asset-light leasing models for thermoforming equipment are rewriting competitive entry dynamics in welded blister production. Amcor leverages captive resin supply chains to sustain margin control across multiple continents. Sonoco Products Company anchors its position through specialized pharmaceutical-grade cleanroom manufacturing capacity. Berry Global differentiates via high-speed laser welding platforms that serve electronics and medical device clients.
Welded blisters are thermoformed plastic cavities sealed to a backing card or foil through heat, pressure, or electromagnetic welding, typically achieving seal strengths of 6-15 N/15mm for pharmaceutical applications. The primary purpose is tamper-evident product protection with visible seal integrity for regulated consumer goods. PVC retains volume leadership in material type due to established tooling compatibility and cost structure, though PET is displacing incumbent positions where recyclability premiums command buyer preference. Blister packs dominate packaging type revenue pools, while clamshells compete aggressively in retail theft-deterrence applications. High-frequency welding leads technology deployment for medical packaging, with laser welding extending into precision electronics where heat-affected zones must minimize.
FDA serialization requirements under the Drug Supply Chain Security Act and EU MDR traceability mandates are reshaping material selection and seal-verification protocols for pharmaceutical welded blisters. REACH restrictions on plasticizers and California's Proposition 65 labeling obligations are forcing reformulation of PVC-based structures across export-bound production. ISO 15378 standards for medicinal product packaging further constrain supplier qualification pathways. Stakeholders must monitor evolving extended producer responsibility frameworks in Germany and France, where packaging recovery targets will soon penalize non-recyclable multi-material constructions.
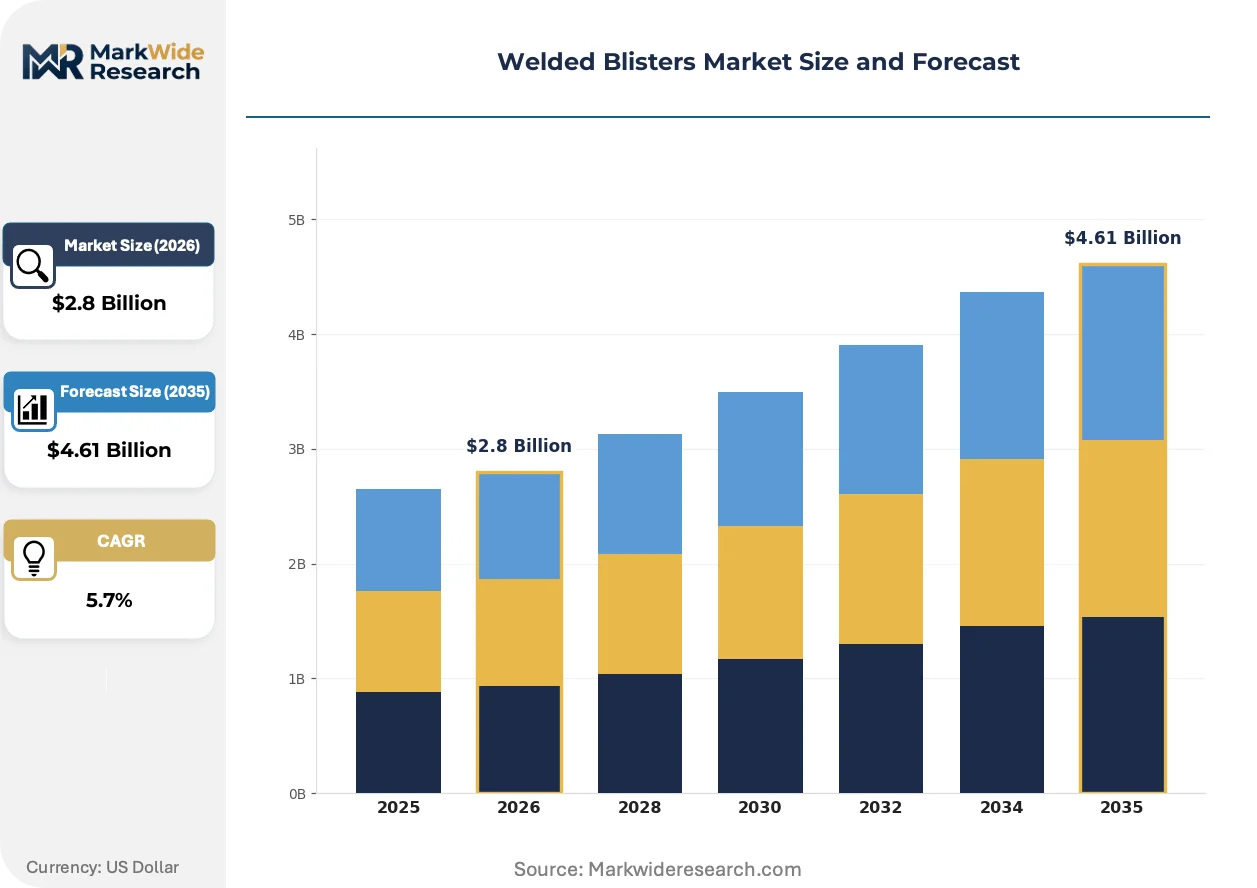
Market Dynamics
Pharmaceutical serialization mandates from FDA and EU MDR are compressing supplier qualification timelines while forcing capital redeployment toward laser welding and track-and-trace infrastructure. Contract packagers in Germany's pharmaceutical corridor now face 18-month certification windows versus historical 6-month cycles.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers across Germany, France, and Italy must implement unit-dose welded blisters with unique device identifiers by regulatory deadlines, pulling demand from secondary packaging formats.
- PET material substitution:Recyclability premiums from German and French extended producer responsibility frameworks are accelerating PET displacement of PVC in export-bound pharmaceutical packaging.
- High-frequency welding technology:Cleanroom-grade pharmaceutical manufacturing in Switzerland and Germany is adopting electromagnetic sealing platforms to achieve 6-15 N/15mm seal strengths required for moisture-sensitive biologics.
Market Restraints
- Resin supply concentration:Captive PVC and PET resin production by integrated packaging conglomerates limits independent converter margin control, particularly in European markets where energy costs have elevated polymer processing economics.
- REACH plasticizer restrictions:Phthalate-based plasticizer bans under ECHA authorization lists are forcing reformulation of legacy PVC blister structures, extending qualification timelines for pharmaceutical customers.
- Laser welding capital intensity:Precision electronics applications requiring minimal heat-affected zones demand equipment investments that exclude mid-tier contract packagers from medical device segments.
Strategic Opportunities
- Asset-light equipment leasing:Thermoforming platform rental models are lowering entry barriers for regional pharmaceutical packagers in Eastern European markets previously dominated by integrated multinationals.
- Electronics precision packaging:Miniaturized semiconductor and sensor components are creating demand for laser-welded micro-blisters with sub-millimeter seal tolerances, a white space adjacent to pharmaceutical core competencies.
- California Proposition 65 compliance services:Export-bound producers require reformulation consulting and alternative material validation to access US West Coast markets without warning label obligations.
Industry Challenges
- Cleanroom certification bottlenecks:ISO 15378 pharmaceutical packaging material standards require 12-24 month facility validation cycles, constraining capacity expansion for contract manufacturers serving EU and Swissmedic-regulated markets.
- Multi-material recycling incompatibility:PVC-foil-PET laminated constructions face technical barriers in European mechanical recycling streams, forcing design-for-recycling investments ahead of 2025 EPR penalty phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welded Blisters Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PVC, PET, Polystyrene, Polypropylene Packaging Type: Blister Packs, Clamshells, Skin Packs, Carded Packaging End User: Pharmaceuticals, Consumer Goods, Electronics, Food Industry Technology: Thermoforming, Vacuum Forming, High-Frequency Welding, Laser Welding |
| Companies Covered | Amcor, AptarGroup, Sonoco Products Company, Berry Global, Sealed Air Corporation, Mondi Group, WestRock Company, Huhtamaki, Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welded Blisters Market Evolving Landscape
Active materials, digital traceability integration, and hybrid welding processes are converging to redefine seal integrity verification and supply chain transparency. These developments compress traditional equipment replacement cycles while elevating technical barriers to supplier qualification.
Laser welding platforms for precision electronics are hybridizing with pharmaceutical-grade cleanroom protocols to serve medical device manufacturers requiring both minimal heat-affected zones and ISO 15378 compliance. Swiss and German cleanroom operators are adopting these dual-use configurations fastest, collapsing the historical separation between electronics contract manufacturing and pharmaceutical packaging services. The convergence is compressing equipment vendor addressable markets while expanding per-customer revenue capture through integrated qualification support.
REACH authorization procedures for plasticizer chemistries are forcing PVC reformulation across European pharmaceutical export production. ECHA's sunset date mechanisms for ortho-phthalates are triggering 18-24 month material revalidation cycles that freeze incumbent supplier relationships. German contract packagers serving both domestic and export markets are responding with parallel PET qualification tracks to maintain EU and California market access without interruption.
Unit-dose compliance packaging procurement from hospital pharmacy networks is consolidating toward integrated track-and-trace capable suppliers. German hospital purchasing cooperatives are disintermediating standalone blister converters unable to serialize at line speed. The shift is most visible in North Rhine-Westphalia's pharmaceutical distribution cluster, where three-tier supplier rationalization programs now mandate DSCSA-equivalent traceability for all unit-dose entrants.
Welded Blisters Market Segmentation
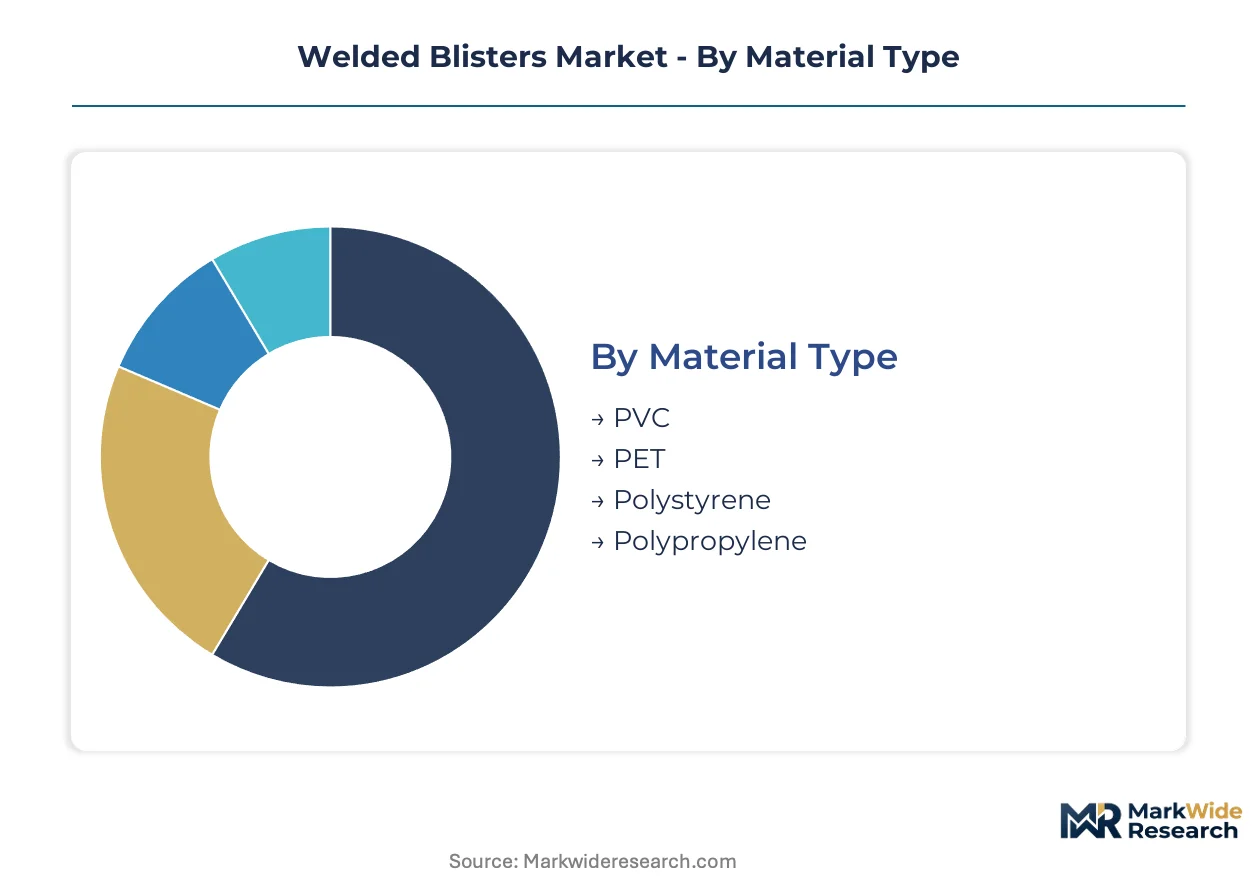
Welded blister segmentation reveals divergent investment cycles across material, packaging format, and sealing technology. Procurement patterns in pharmaceutical corridors favor qualification-heavy segments with extended supplier lock-in, while consumer goods applications permit faster switching between material and technology alternatives.
Material Type:
PVC and PET command the longest qualification timelines in pharmaceutical applications, whereas polystyrene and polypropylene serve shorter-cycle consumer markets where reformulation flexibility outweighs regulatory documentation burdens.
- PVC:Chlorinated polymer structure with established tooling compatibility across legacy thermoforming platforms. Pharmaceutical manufacturers in Germany's contract packaging corridor specify PVC for moisture-barrier applications despite REACH plasticizer authorization pressures forcing 18-24 month reformulation cycles.
- PET:Polyester resin delivering recyclability premiums under French and German extended producer responsibility frameworks. Swissmedic-regulated cleanroom operators are accelerating PET displacement of PVC to preempt California Proposition 65 labeling obligations on export-bound production.
- Polystyrene:Amorphous thermoplastic serving cost-sensitive consumer goods with faster material validation cycles than pharmaceutical-grade alternatives.
- Polypropylene:Semi-crystalline olefin preferred for high-temperature sterilization compatibility in medical device secondary packaging.
PVC dominates installed base across European pharmaceutical production. PET is where expansion concentrates as EPR penalty phases approach.
Packaging Type:
Cost tier separation runs deepest here: blister packs and clamshells occupy capital-intensive pharmaceutical and retail-theft-deterrence applications, while skin packs and carded packaging serve promotional and lower-unit-value segments.
- Blister Packs:Thermoformed cavity sealed to lidding foil or card through heat or electromagnetic welding, achieving 6-15 N/15mm seal strengths for unit-dose compliance. FDA DSCSA serialization mandates are compressing supplier qualification timelines toward integrated track-and-trace capable converters in Germany's North Rhine-Westphalia distribution cluster.
- Clamshells:Hinged two-piece thermoformed shells sealed at the perimeter, dominant in retail theft-deterrence for consumer electronics and high-value consumables where visible seal integrity deters shelf-level pilferage.
- Skin Packs:Film draped over product and sealed to printed card, common in hardware and automotive aftermarket segments with minimal barrier requirements.
- Carded Packaging:Heat-sealed film-to-card construction for promotional multipacks and trial-size distribution in mass retail channels.
Blister packs capture the steepest expansion trajectory from EU MDR unit-dose mandates. Clamshells defend position in retail loss-prevention procurement.
End User:
Customer type determines margin structure: pharmaceutical and electronics buyers fund qualification-intensive supplier relationships, while consumer goods and food industry procurement prioritizes unit cost and line-speed flexibility.
- Pharmaceuticals:Unit-dose compliance packaging for prescription solids and biologics, subject to FDA serialization and EU MDR traceability mandates. German hospital purchasing cooperatives are consolidating procurement toward converters with ISO 15378 certification and line-speed serialization capability.
- Electronics:Precision packaging for miniaturized semiconductors and sensors requiring laser-welded micro-blisters with sub-millimeter seal tolerances and minimal heat-affected zones.
- Consumer Goods:Tamper-evident retail packaging for cosmetics, batteries, and hardware with shorter qualification cycles and price-driven material selection.
- Food Industry:Modified-atmosphere and portion-control applications with hygiene-focused material specifications distinct from pharmaceutical barrier requirements.
Pharmaceuticals anchor revenue per square meter of cleanroom capacity. Electronics is climbing the fastest as semiconductor miniaturization drives precision welding demand.
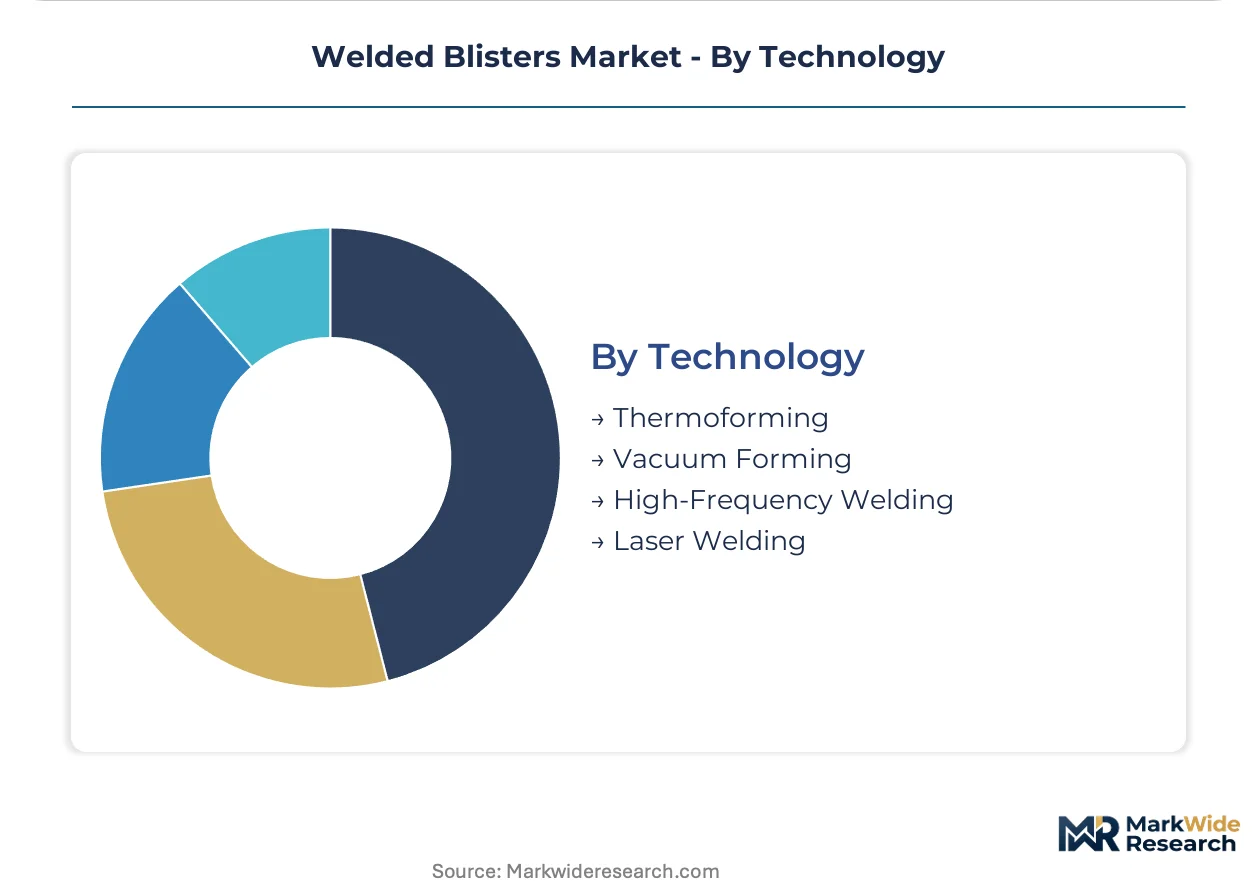
Technology:
Supply concentration separates established thermoforming and vacuum forming platforms from capital-intensive high-frequency and laser welding systems that exclude mid-tier contract packagers.
- Thermoforming:Pressure- or vacuum-assisted plastic sheet forming into cavity molds, the baseline technology for high-volume pharmaceutical and consumer blister production with mature equipment leasing models lowering regional entry barriers.
- High-Frequency Welding:Electromagnetic sealing generating molecular friction at material interfaces, specified for cleanroom-grade pharmaceutical manufacturing in Switzerland and Germany where 6-15 N/15mm seal strengths protect moisture-sensitive biologics.
- Vacuum Forming:Suction-based sheet forming for shallow-draw applications with lower capital requirements than pressure thermoforming.
- Laser Welding:Precision electromagnetic sealing with localized heat input, required for electronics micro-blisters where heat-affected zones must minimize to protect sensitive components.
Thermoforming holds the broadest installed base across material categories. Laser welding is gaining share fastest as medical device and electronics specifications converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract packagers and medical device manufacturers concentrate procurement power across Germany, Switzerland, and the United States, with secondary demand emerging from electronics precision packaging clusters in East Asia.
Germany
North Rhine-Westphalia's pharmaceutical distribution corridor drives welded blister demand from hospital purchasing cooperatives requiring DSCSA-equivalent serialization. ECHA's REACH authorization timelines for ortho-phthalate plasticizers are forcing 18-24 month PVC reformulation cycles. Contract packagers in Düsseldorf and Cologne now face compressed 18-month supplier qualification windows versus historical 6-month cycles.
Switzerland
Swissmedic-regulated cleanroom operators are accelerating PET displacement of PVC to preempt California Proposition 65 labeling obligations on export-bound production. The country's national pharmaceutical regulator maintains stringent ISO 15378 facility validation requirements. Basel's pharmaceutical packaging cluster is adopting hybrid laser welding platforms that serve both medical device and precision electronics specifications.
United States
FDA serialization mandates under the Drug Supply Chain Security Act are reshaping material selection and seal-verification protocols for pharmaceutical welded blisters. The agency's traceability requirements are compressing supplier qualification timelines toward integrated track-and-trace capable converters. New Jersey's pharmaceutical manufacturing corridor is consolidating procurement toward converters with line-speed serialization capability.
France
Extended producer responsibility frameworks are accelerating PET displacement of PVC in export-bound pharmaceutical packaging as 2025 EPR penalty phases approach. ANSM pharmaceutical packaging standards constrain supplier qualification pathways for domestic and export markets. The Île-de-France region's contract packaging sector is investing in design-for-recycling capabilities to address multi-material recycling incompatibility.
China
NMPA traceability requirements for pharmaceutical packaging are elevating technical barriers to supplier qualification in the domestic market. The national medical products regulator's serialization mandates are pulling demand toward integrated track-and-trace capable converters. Yangtze River Delta pharmaceutical manufacturing clusters are expanding cleanroom-grade welded blister capacity for both domestic consumption and export markets.
Welded Blisters Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where integrated resin suppliers and equipment-leasing platforms shape entry economics. The vendor base separates into three strategic archetypes: captive resin-integrated conglomerates, cleanroom-certified pharmaceutical specialists, and precision electronics-focused laser welding operators. M&A activity concentrates on track-and-trace capability acquisition, while asset-light equipment leasing models expand regional contract packaging access.
Among resin-integrated packaging conglomerates, Amcor and Berry Global exemplify the captive supply chain archetype that sustains margin control across multiple continents. Sonoco Products Company occupies a position within the cleanroom-certified pharmaceutical specialist tier, anchoring market presence through specialized manufacturing capacity. These three entities represent the dominant competitive positioning vectors: upstream material control, regulatory-certified production infrastructure, and precision technology platforms.
| Leading Market Players |
|---|
| Amcor |
| AptarGroup |
| Sonoco Products Company |
| Berry Global |
| Sealed Air Corporation |
| Mondi Group |
| WestRock Company |
| Huhtamaki |
| Constantia Flexibles |
| Others |
Value Network & Pricing Analysis
Rhine-Alpine freight corridor cost volatility is compressing margins for German contract packagers while amplifying price differentiation between resin-integrated conglomerates and independent converters serving pharmaceutical and electronics end users.
Pricing Analysis
Cost-plus contracts indexed to ethylene and PTA feedstock benchmarks dominate pharmaceutical-grade welded blister procurement. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15378-certified cleanroom production from general industrial grades. Pricing pressure stems from energy cost pass-through clauses in European polymer processing. Hospital purchasing cooperatives exhibit lowest price sensitivity due to regulatory compliance requirements, while consumer goods buyers drive hardest bargain on per-unit rates.
Supply Chain Analysis
Export control restrictions on high-frequency welding equipment limit technology transfer to non-allied manufacturing jurisdictions. Resin supply concentrates in Germany, Belgium, and the Netherlands, with PVC and PET pellet production drawing from naphtha crackers along the ARA refining hub. Phthalate-based plasticizer availability rests on ECHA authorization timelines. Single-source vulnerability runs through specialized cleanroom film extrusion. Distribution runs through pharmaceutical contract packaging clusters in North Rhine-Westphalia and Basel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Welded blister demand is recovering from cyclical compression in capital equipment procurement, with pharmaceutical serialization mandates and EU MDR traceability deadlines restocking order pipelines.
For Market Incumbents: Pre-empt PET displacement acceleration by locking multi-year resin supply agreements ahead of 2025 EPR penalty phases. Secure ISO 15378 recertification ahead of competitor capacity additions in Switzerland. Backward integration into laser welding equipment servicing expands addressable market into precision electronics. For New Entrants and Emerging Players: Establish a beachhead in Eastern European pharmaceutical contract packaging through asset-light thermoforming equipment leasing. Target mid-tier medical device manufacturers in Poland and Czechia seeking Swissmedic-equivalent quality without Basel-area cost structures. Lead with design-for-recycling consulting to differentiate from legacy PVC-dependent incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core pharmaceutical units. Five-to-ten year viability hinges on track-and-trace infrastructure ownership rather than commodity thermoforming capacity. Monitor ECHA sunset date announcements for ortho-phthalate plasticizers as inflection signal for accelerated PET substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Welding Platform Acquisition | Captures medical device-electronics convergence demand in Basel and Swiss corridor. |
| PET Resin Backward Integration | Insulates margin from EPR penalty-driven material substitution cycles. |
| Cleanroom Certification Expansion | Opens access to Swissmedic and FDA-regulated biologics packaging contracts. |
| Track-and-Trace Infrastructure Partnership | Meets DSCSA-equivalent serialization mandates from German hospital cooperatives. |
| Design-for-Recycling Consulting Launch | Addresses multi-material incompatibility in French and German EPR frameworks. |
Research Methodology
Cross-validation between primary interviews with pharmaceutical packaging engineers, contract manufacturing procurement leads, cleanroom operations managers, and EHS compliance officers anchors the qualitative findings. Secondary sources span FDA DSCSA guidance documents, ECHA authorization lists, Swissmedic GMP inspections, and EU MDR technical documentation. Bottom-up capacity modeling triangulates against top-down pharmaceutical production forecasts.
Calibration against historical qualification timeline data and resin price elasticity patterns shapes the analytical framework. Segmentation spans material type, packaging format, end-use industry, sealing technology, and regional regulatory cluster. CAGRs derive from installed equipment base depreciation schedules and replacement cycle acceleration factors. Forecast inputs incorporate laser welding adoption curves and EPR penalty phase implementation schedules.
Stress conditions across resin price volatility, cleanroom certification delays, and serialization mandate enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory timeline adherence and technology substitution elasticities. Material shifts in ECHA plasticizer authorization pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Blister Paper Market
Blister Packaging
Global Blister Packaging Market
Blister Packaging
Ampoules and Blister Packaging Market
Blister Packaging
Liquid Blister Pack Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
Blister Packs Market
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
North America Pharmaceutical Blister Packaging Market
Blister Packaging
Global Cold Form Blister Packaging Market
Blister Packaging
Pharma Blister Packaging Machines Market
Blister Packaging
Pharma Blisters Packaging Market
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
United States Blister Packaging Market
Blister Packaging
Latin America Pharmaceutical Blister Packaging Market
Blister Packaging
Europe Blister Packaging Market
Blister Packaging
Alu Alu Blister Packaging Machine Market