
 Rotogravure Printing Machine Market | 2026-2036
Rotogravure Printing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Rotogravure Printing Machine Market Analysis
Flexible packaging is broadening its share of rotogravure press installations as snack, confectionery, and pet food brands shift from rigid formats. Uteco anchors European demand through its large-format CI flexo-gravure hybrid lines for high-barrier films. Bobst Group SA dominates narrow-web decorative applications with integrated coating and metallization modules. Jiangyin Huitong Packaging Machinery Co. Ltd. competes aggressively on delivery speed and localized service for Southeast Asian converters.
Rotogravure printing machines employ engraved copper cylinders carrying ink in recessed cells, transferring images onto substrates at speeds exceeding 400 meters per minute with consistent tonal reproduction for long runs. Photopolymer technology leads cylinder preparation for flexible packaging, while laser engraving is displacing mechanical etching in premium label and wallpaper segments where finer line screens command margin premiums. Paper-based applications remain mature, with corrugated cardboard representing a smaller but stable replacement-driven pool.
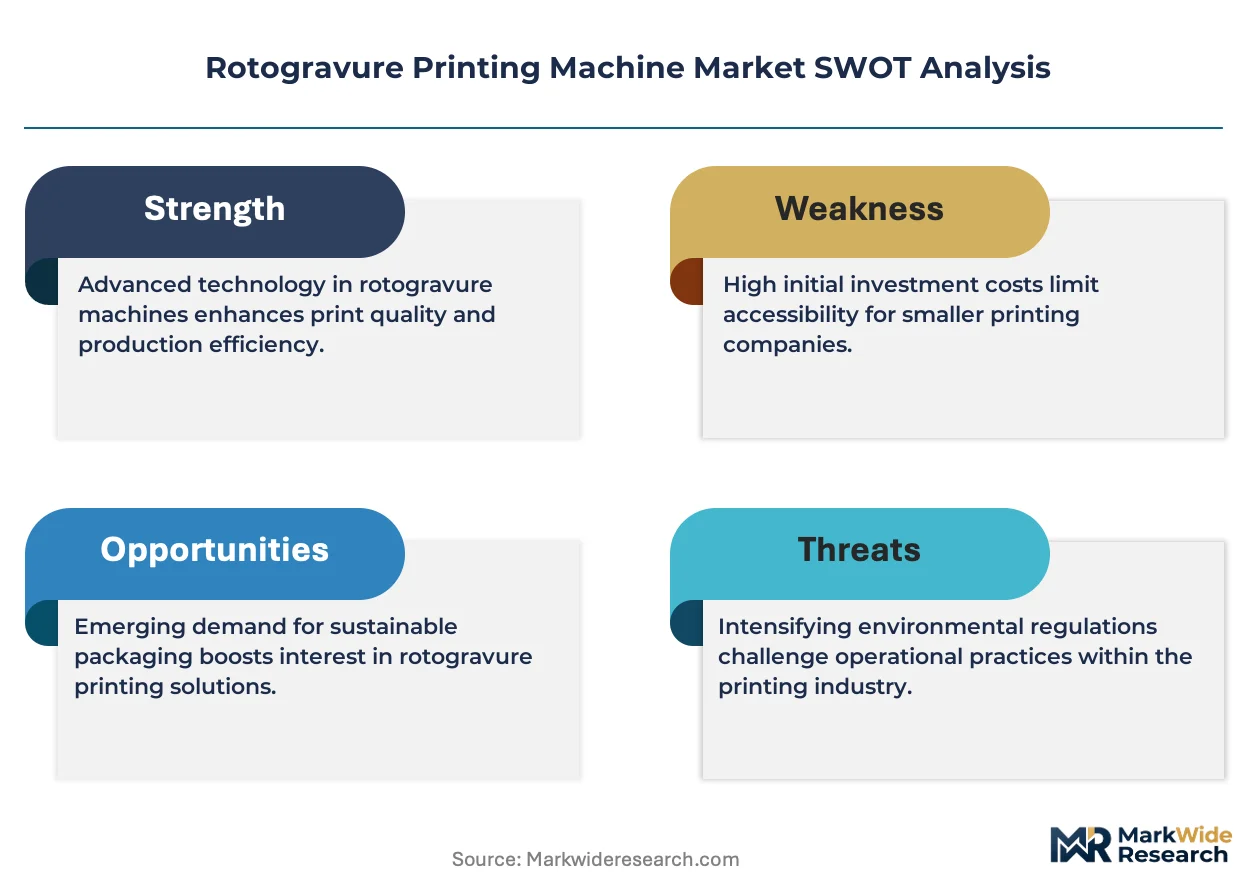
EPA air quality standards and OSHA solvent exposure limits constrain volatile organic compound emissions from gravure ink drying systems in the United States, pressuring converters toward regenerative thermal oxidizers and water-based alternatives. ECHA REACH restrictions on chromium trioxide in cylinder plating are accelerating non-hexavalent chrome and ceramic coating adoption across European installed bases. Stakeholders must monitor how China's GB standards on packaging recyclability reshape substrate specifications and press compatibility requirements.
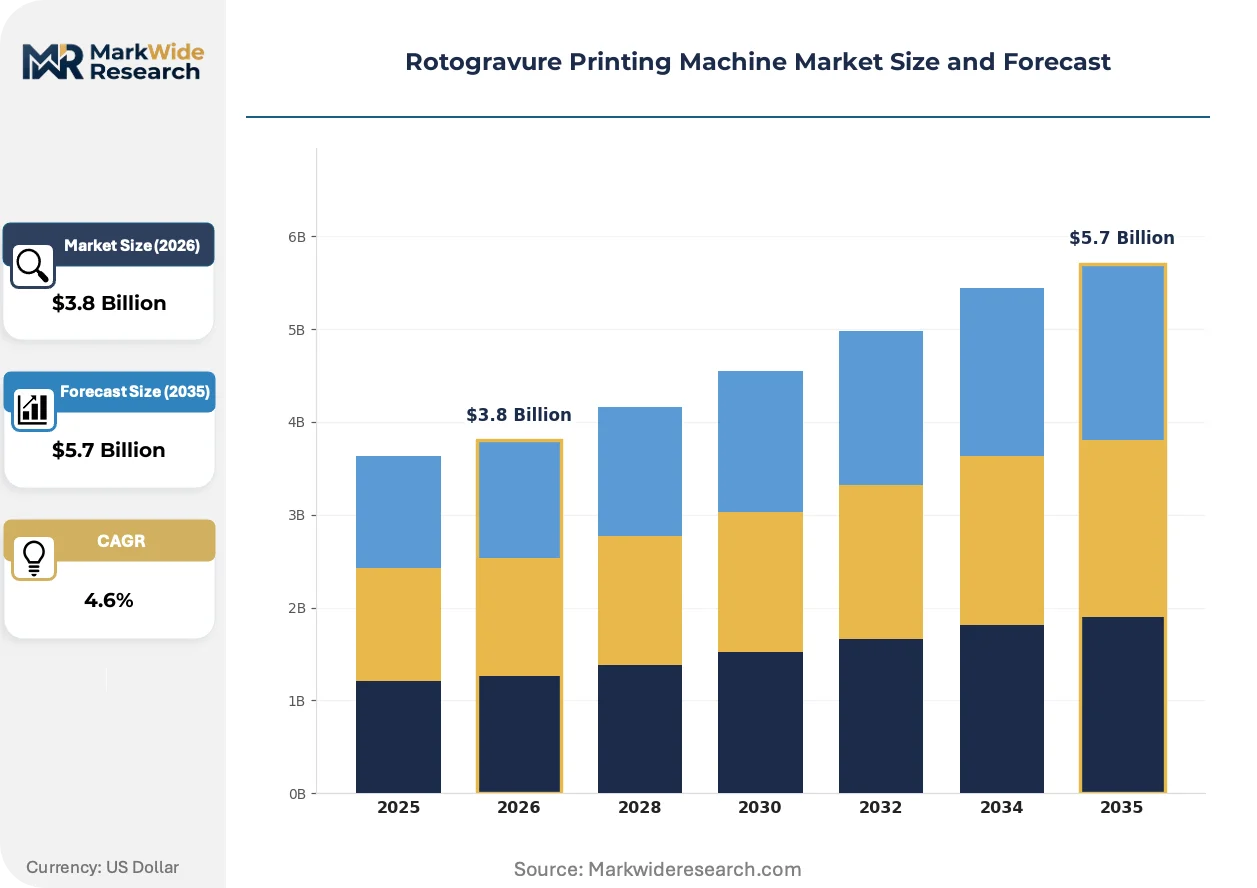
Market Dynamics
Flexible packaging converters in food and beverage are accelerating gravure press orders as snack and pet food brands abandon rigid formats for high-barrier films. This demand migration is compressing equipment replacement cycles and reshaping competitive positioning among machinery builders.
Growth Catalysts
- REACH compliance mandates:ECHA restrictions on chromium trioxide in cylinder plating are forcing European converters toward non-hexavalent chrome and ceramic coatings, creating replacement demand across installed bases.
- Photopolymer cylinder preparation:This technology dominates flexible packaging applications for its speed and consistency, pulling mid-speed segment investment away from mechanical etching systems.
- China domestic machinery capture:Jiangyin Huitong and comparable builders are winning Southeast Asian converter contracts through delivery speed advantages and localized service networks.
Market Restraints
- Copper and chromium input volatility:Cylinder engraving relies on copper substrate and chrome plating chemistry; metal price swings compress margin predictability for equipment financing.
- Laser engraving substitution threat:Premium label and wallpaper segments are migrating to laser systems for finer line screens, eroding gravure's historical dominance in high-margin decorative work.
- EPA air quality constraints:OSHA solvent exposure limits and EPA volatile organic compound rules in the United States add capital burden through mandated regenerative thermal oxidizer installation.
Strategic Opportunities
- Water-based ink convergence:Formulation chemistry advances are enabling water-based alternatives to solvent systems, opening compliance pathways for converters in regulated North American markets.
- India packaging expansion:FSSAI food safety enforcement and BIS packaging standards are driving organized sector investment in gravure-equipped flexible packaging lines.
- CI flexo-gravure hybrid technology:Large-format integration of flexographic and gravure units on single presses is capturing high-barrier film contracts from standalone equipment buyers.
Industry Challenges
- Engraved cylinder skill scarcity:Photopolymer and laser preparation techniques require different technician competencies than legacy mechanical etching, constraining workforce mobility across installed bases.
- Legacy press integration friction:Retrofitting drying systems for water-based ink compatibility demands substantial capital outlay and extended downtime, slowing converter transition timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotogravure Printing Machine Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Labels, Wallpaper, Corrugated Cardboard Material: Paper, Plastic, Film, Foil End User: Packaging Industry, Publishing, Textile, Advertising Technology: Digital, Photopolymer, Laser, Hybrid |
| Companies Covered | Uteco, Shibaura Machine Co. Ltd., Cerutti Group, DCM ATN SAS, Jiangyin Huitong Packaging Machinery Co. Ltd., Bobst Group SA, Hsing Wei Machine Industry Co. Ltd., Star Flex International, Comexi Group Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotogravure Printing Machine Market Emerging Trajectories
Equipment architecture and regulatory chemistry are the dominant forces reshaping competitive positioning. Machinery builders are reconfiguring press designs while cylinder preparation and ink formulation undergo parallel transformation.
Electromechanical tension control systems with distributed servo drives are modularizing press architecture for flexible packaging lines. High-volume converters in snack food and pet food are adopting these configurations to enable rapid job changeover without mechanical rethreading. This modularization is compressing the economic viability window for fixed-geometry mechanical tension systems in mid-speed segments.
ECHA REACH Annex XIV restrictions on chromium trioxide are mandating transition to trivalent chrome and ceramic-coated cylinder alternatives across European installed bases. Plating shops and machinery OEMs are requalifying surface preparation protocols to maintain cell geometry precision under new chemistry constraints. Flexible packaging converters in Germany and Italy face the steepest compliance timelines, accelerating cylinder replacement schedules ahead of typical wear cycles.
Converter procurement of gravure capacity is consolidating toward integrated coating and metallization modules rather than standalone printing units. Brand owners in confectionery and personal care are specifying barrier performance at contract initiation, forcing equipment buyers to specify multi-process lines from single vendors. This bundling pattern is most pronounced in China, where domestic machinery builders are packaging gravure units with in-house metallizer production to capture full-line contracts.
Rotogravure Printing Machine Market Segmentation
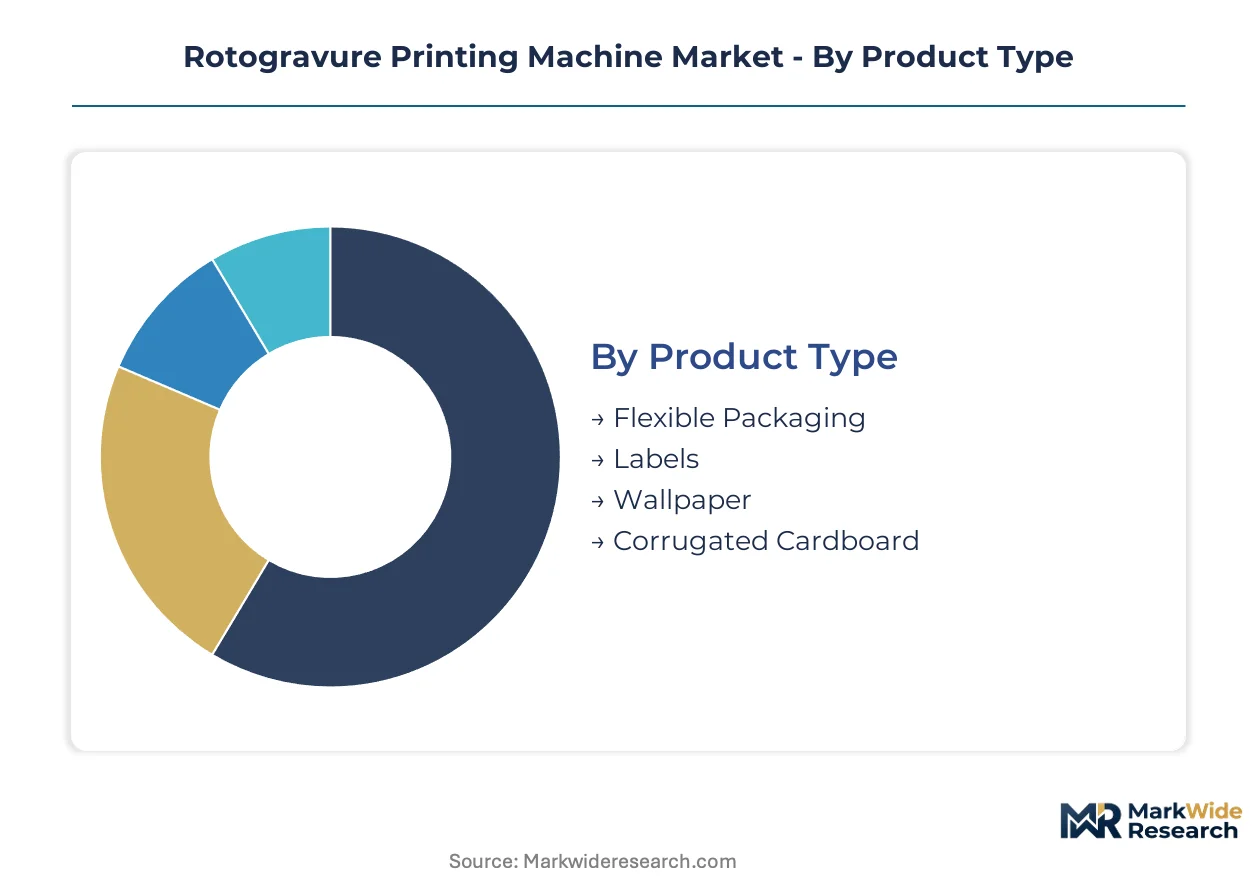
Segmentation in rotogravure printing machines reveals how substrate requirements, cylinder preparation methods, and end-use specifications drive equipment configuration choices. Understanding these dimensions helps machinery builders align press architecture with converter operational priorities.
Product Type:
Customization intensity varies sharply across this category, from standardized narrow-web units for wallpaper to highly configured wide-format systems for multi-layer flexible packaging.
- Flexible Packaging:Wide-format presses with integrated drying and tension control systems process high-barrier films for snack, confectionery, and pet food applications. Demand concentrates in China and Southeast Asia where domestic machinery builders compete on delivery speed for mid-speed segment contracts.
- Labels:Narrow-web configurations with precision registration systems serve premium decorative segments where laser engraving is displacing mechanical etching for finer line screens. European converters in Germany and Italy face compressed replacement cycles due to ECHA REACH cylinder plating restrictions.
- Wallpaper:Heavy-duty cylinder designs handle thick paper stocks with deep cell engraving for high-ink-volume coverage.
- Corrugated Cardboard:Specialized large-format units address mature replacement demand with limited new capacity expansion.
Most installed capacity flows through Flexible Packaging. Expansion is steepest in Labels.
Material:
Cost tier stratification separates commodity substrate handling from precision film processing requiring advanced tension and thermal management.
- Plastic:Multi-layer coextruded structures demand precise ink adhesion control and specialized drying profiles for high-barrier food packaging applications. Converters in North America face EPA air quality compliance costs for solvent-based systems processing these substrates.
- Film:Biaxially oriented polypropylene and polyethylene terephthalate require electromechanical tension systems with distributed servo drives for wrinkle-free handling at speeds exceeding 400 meters per minute.
- Paper:Mature segment with standardized press configurations and established drying protocols.
- Foil:Metallized substrates for premium personal care and confectionery packaging need specialized coating modules and extended drying tunnels.
Plastic carries the heaviest installed base. Film is gaining share fastest in new equipment procurement.
End User:
Application maturity shapes equipment specification complexity, from standardized publishing units to highly integrated packaging lines with coating and metallization modules.
- Packaging Industry:Food and beverage converters dominate order books with CI flexo-gravure hybrid specifications for high-barrier film contracts. Brand owners now specify barrier performance at contract initiation, forcing bundled multi-process line procurement.
- Publishing:Long-run magazine and catalog production favors gravure's tonal consistency, though digital substitution pressures volume growth in developed markets.
- Textile:Transfer paper printing for fabric decoration requires specialized cylinder preparation and extended color gamut capabilities.
- Advertising:Point-of-sale display materials and outdoor signage drive demand for wide-format units with UV-curable ink compatibility.
Packaging Industry commands dominant installed capacity. Advertising shows the steepest expansion trajectory among smaller segments.
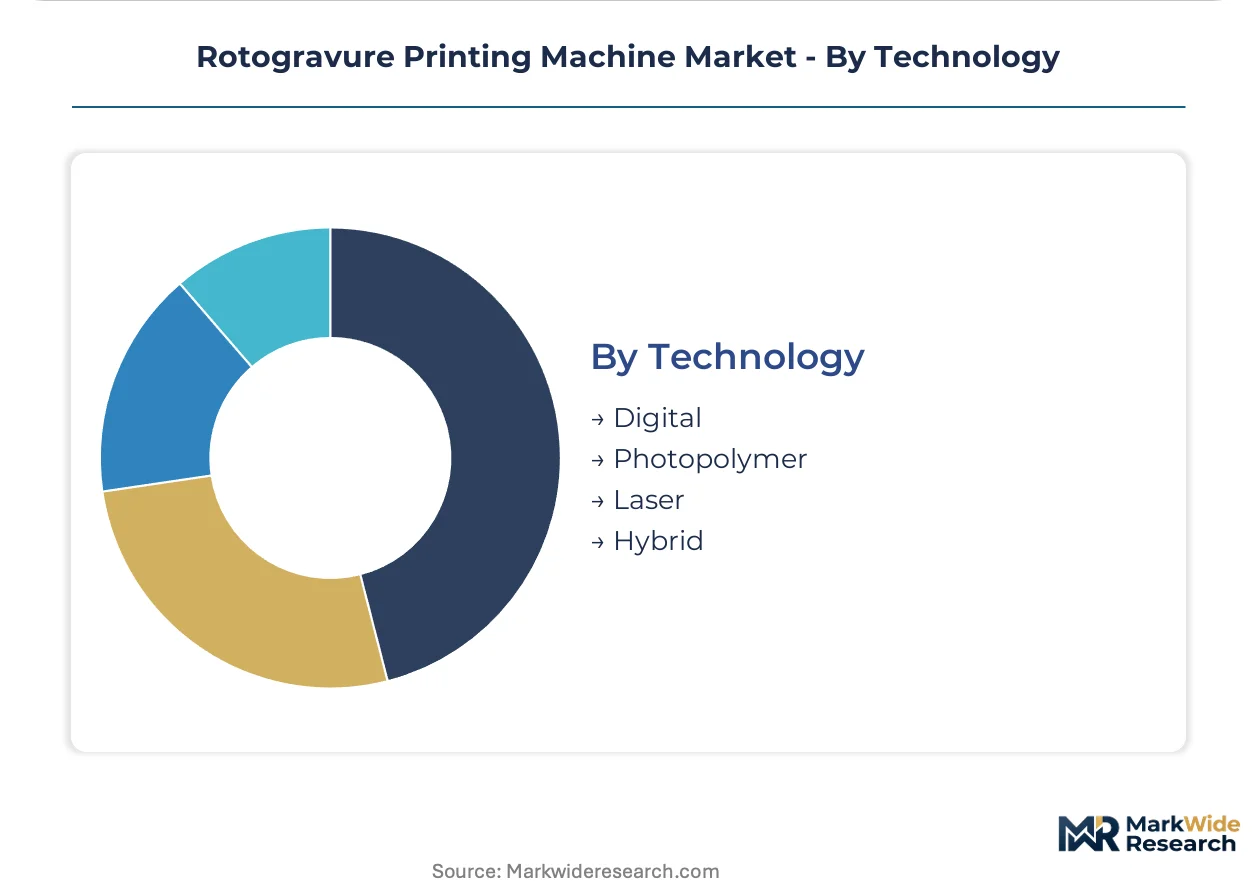
Technology:
Volume concentration favors photopolymer preparation for flexible packaging, while margin capture shifts toward laser and hybrid systems in premium applications.
- Photopolymer:Dominant cylinder preparation method for flexible packaging with speed and consistency advantages over mechanical etching. Mid-speed segment investment is pulling toward this technology as European plating shops requalify protocols under ECHA REACH trivalent chrome mandates.
- Laser:Direct cell engraving systems enable finer line screens for premium label and wallpaper segments where mechanical etching cannot achieve required resolution.
- Digital:Short-run and variable data applications compete with gravure in narrow-web segments, though speed limitations constrain penetration in high-volume flexible packaging.
- Hybrid:CI flexo-gravure integration captures high-barrier film contracts from standalone equipment buyers, particularly in China where domestic builders package gravure units with in-house metallizer production.
Photopolymer represents the largest installed base. Hybrid configurations are expanding most quickly in new equipment specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting gravure press procurement toward jurisdictions with lower compliance friction, while cylinder plating chemistry restrictions in Europe accelerate replacement demand across installed bases.
China
Domestic machinery builders capture mid-speed segment contracts through delivery speed advantages and localized service networks. GB standards on packaging recyclability reshape substrate specifications and press compatibility requirements. Jiangyin Huitong Packaging Machinery anchors production clusters in the Yangtze River Delta, bundling gravure units with in-house metallizer production for full-line contracts.
Germany
Flexible packaging converters face compressed cylinder replacement cycles under ECHA REACH Annex XIV restrictions on chromium trioxide. Trivalent chrome and ceramic coating adoption accelerates across installed bases, forcing plating shops to requalify surface preparation protocols. Industrial concentration in Baden-Württemberg and North Rhine-Westphalia drives CI flexo-gravure hybrid specifications for high-barrier film contracts.
United States
EPA air quality standards and OSHA solvent exposure limits constrain volatile organic compound emissions from gravure ink drying systems. Regenerative thermal oxidizer mandates add capital burden, pressuring converters toward water-based formulation alternatives. Equipment procurement concentrates in the Midwest packaging corridor and Southeast converting clusters where snack food brands drive flexible packaging expansion.
India
FSSAI food safety enforcement and BIS packaging standards drive organized sector investment in gravure-equipped flexible packaging lines. Mid-speed segment demand expands as confectionery and personal care brands specify barrier performance at contract initiation. Maharashtra and Gujarat host the densest converter clusters, with machinery procurement shifting toward integrated coating and metallization modules.
Italy
Photopolymer cylinder preparation dominates flexible packaging applications, pulling investment away from mechanical etching systems. ECHA REACH compliance timelines accelerate cylinder replacement ahead of typical wear cycles, particularly in Emilia-Romagna and Lombardy converting centers. Narrow-web decorative applications sustain demand for precision registration systems in premium label segments.
Rotogravure Printing Machine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with machinery builders competing on bundled multi-process line configurations rather than standalone press specifications. The vendor base organizes into three tiers: European incumbents with CI flexo-gravure hybrid portfolios, Chinese domestic builders capturing mid-speed share through delivery velocity, and narrow-web specialists serving decorative wallpaper and label niches. Competitive moves concentrate on vertical integration into metallization modules and geographic expansion through localized service networks.
Among European-based fabricators, Uteco and Bobst Group SA occupy positions at the premium-tier vector for large-format hybrid configurations, while Jiangyin Huitong Packaging Machinery Co. Ltd. represents the delivery-speed archetype for Southeast Asian converter contracts. Cerutti Group and Comexi Group Industries exemplify narrow-web specialists serving decorative segments where laser engraving compatibility commands specification priority.
| Leading Market Players |
|---|
| Uteco |
| Shibaura Machine Co. Ltd. |
| Cerutti Group |
| DCM ATN SAS |
| Jiangyin Huitong Packaging Machinery Co. Ltd. |
| Bobst Group SA |
| Hsing Wei Machine Industry Co. Ltd. |
| Star Flex International |
| Comexi Group Industries |
| Others |
Supply Flow & Price Mechanics
European REACH-compliant cylinder plating bifurcation separates trivalent chrome and ceramic-coated premium configurations from legacy hexavalent chrome systems, with that certification ladder driving 40-60% cost spreads at the equipment tier while simultaneously concentrating plating shop capacity in Germany and Italy under requalification timelines.
Pricing Analysis
Distributor margins on gravure press components compress most acutely in mid-speed flexible packaging segments where Chinese domestic builders bypass channel layers entirely. Three-tier pricing structure across premium CI flexo-gravure hybrids, standard photopolymer-equipped units, and economy mechanical-etching legacy systems stratifies buyer segments, with Southeast Asian converters exhibiting highest price sensitivity due to delivery-speed prioritization over specification depth. Cost compression in standard-tier equipment intensifies because Jiangyin Huitong and comparable builders absorb freight and installation overhead into turnkey quotes.
Supply Chain Analysis
China's GB standards on packaging recyclability and domestic-content preferences for state-backed converter projects reshape sourcing toward Yangtze River Delta machinery clusters. Copper substrate and chromium plating chemistry draw from concentrated Belgian and German specialty chemical suppliers, while high-precision servo drives and tension control systems feed from Japanese and German automation component manufacturers. Single-source vulnerability concentrates in engraved cylinder preparation equipment where European plating technology providers dominate trivalent chrome transition protocols. Distribution runs through machinery OEM direct sales for large-format hybrids and regional distributor networks for narrow-web replacement units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rotogravure equipment procurement has shifted toward premium CI flexo-gravure hybrid specifications as brand owners mandate barrier performance guarantees at contract initiation, elevating late-cycle quality requirements over volume throughput.
For Market Incumbents: Anchor defensive positioning through captive cylinder plating capacity in Germany and Italy to capture REACH-driven replacement cycles ahead of independent plating shop requalification delays. Prioritize R&D investment in water-based ink drying system retrofits to offset EPA compliance cost burdens pressuring Midwest and Southeast US converter margins. Laser engraving substitution in premium label segments demands specification lock-in through integrated coating-metallization module bundling. For New Entrants and Emerging Players: Enter via India's Maharashtra and Gujarat converter clusters where FSSAI enforcement drives organized sector gravure adoption with limited incumbent service infrastructure. Target mid-speed flexible packaging segments in Vietnam and Indonesia where delivery velocity outweighs European brand recognition. Pursue metallizer-gravure bundling partnerships with domestic Chinese builders lacking in-house vacuum coating capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where cylinder preparation skill scarcity intersects with REACH compliance capital requirements, squeezing independent plating shops and small-format press specialists. Five-to-ten year viability favors machinery builders with backward integration into tension control servo systems and metallization modules. Watch ECHA Annex XIV enforcement acceleration and China's GB recyclability standard expansion as inflection triggers for replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallization Modules | Bundled gravure-metallizer lines capture high-barrier film contracts from standalone equipment buyers in China. |
| Trivalent Chrome Plating Capacity Expansion | European plating shop requalification under ECHA REACH creates first-mover margin capture in cylinder replacement cycles. |
| Water-Based Ink Drying System Retrofit Programs | EPA air quality compliance pathways unlock Midwest and Southeast US converter segments constrained by oxidizer capital burdens. |
| Localized Service Network Buildout in Southeast Asia | Delivery speed and technical response time displace European incumbents in mid-speed flexible packaging procurement. |
| Photopolymer Cylinder Preparation Technology Licensing | Speed and consistency advantages over mechanical etching pull investment toward licensed preparation protocol adoption. |
Methodological Framework
Coverage spans China, Germany, the United States, India, and Italy, with primary inputs from each market informing demand assessment and competitive positioning. The analysis combines structured interviews with gravure press procurement directors at flexible packaging converters, cylinder plating shop technical managers, and machinery OEM regional sales heads with secondary validation from customs trade data, SEC filings of listed equipment manufacturers, and ECHA regulatory enforcement notices. Bottom-up equipment shipment tracking and top-down packaging industry capacity expansion analysis triangulate market sizing across the projection horizon.
Rate-of-change decomposition separates volume drivers from value migration patterns across the analysis window. Segmentation dimensions modeled include product type, cylinder preparation technology, substrate material, and end-use application intensity. CAGRs derive from equipment replacement cycle analysis, regulatory compliance deadline mapping, and converter capital expenditure intention surveys. Industry-specific forecast inputs incorporate ECHA REACH Annex XIV phase-out schedules and China's GB packaging recyclability standard implementation timelines.
The model holds under steady regulatory enforcement timelines and stable copper-chromium input cost corridors; deviation in REACH acceleration or raw material price volatility would shift replacement demand timing and equipment tier mix. Forecasts reflect documented assumptions regarding converter consolidation rates and technology substitution thresholds. A small set of named triggers—ECHA enforcement acceleration, EPA water-based ink mandate expansion, and Chinese domestic machinery export financing availability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
LAMEA Label Printing Software Market
Packaging Printing
Rotogravure Printing Cylinder Market
Packaging Printing
Digital Label Printing Market
Packaging Printing
Asia-Pacific Digital Printing Packaging Market
Packaging Printing
Global Electrophotographic Printing in Packaging Market
Packaging Printing
Pre-Press for Packaging Market
Packaging Printing
Digital Label Printers Market
Packaging Printing
Pad Printing Machine Market
Packaging Printing
Heat Transfer Press Printing Machine Market
Packaging Printing
Europe Printed Packaging Market
Packaging Printing
Lithographic Printing for Packaging Market
Packaging Printing
Stamping Foils Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Electrophotography Printing for Packaging Market
Packaging Printing
Stack Flexo Printing Press Market
Packaging Printing
Flex Banner Market