
 North America Pharmaceutical Blister Packaging Market | 2026-2036
North America Pharmaceutical Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pharmaceutical Blister Packaging Market Insights
The premium-commodity split in North America pharmaceutical blister packaging is shifting toward high-barrier cold form and aluminum-laminate structures versus standard PVC configurations. Amcor plc leverages its integrated film and converting footprint to dominate barrier-grade supply for oncology and cardiovascular doses. WestRock Company anchors the paperboard-backed segment through retail pharmacy and hospital channel control. Klöckner Pentaplast specializes in rigid PVC and PET films, competing on scale for generic oral solid dosages.
Pharmaceutical blister packaging denotes pre-formed plastic, aluminum, or laminate cavities sealed with lidding foil to unit-dose oral medications, typically achieving moisture vapor transmission rates below 0.5 g/m²/day for hygroscopic drugs. The primary purpose is patient adherence assurance, child resistance, and shelf-life extension for tablets and capsules. Cold form blister leads in value terms due to complete moisture and oxygen barrier properties demanded by FDA-regulated NDA products, while PET blister captures fastest volume growth as brand owners substitute PVC to meet USP <661.1> extractables scrutiny. Contract packaging organizations represent the fastest-growing end user segment as Big Pharma outsources secondary packaging to reduce fixed asset intensity.
FDA 21 CFR Part 211 cGMP requirements, USP <661> plastic packaging system standards, and Health Canada ICH Q1A stability guidelines collectively dictate material selection, validation protocols, and supplier audit frequency across North America. The US Drug Supply Chain Security Act serialization mandates are forcing line upgrades that favor thermoform-fill-seal integrators with track-and-trace software compatibility. Stakeholders must monitor evolving state-level extended producer responsibility bills in California and New York that could impose post-consumer recovery obligations on blister format designs.
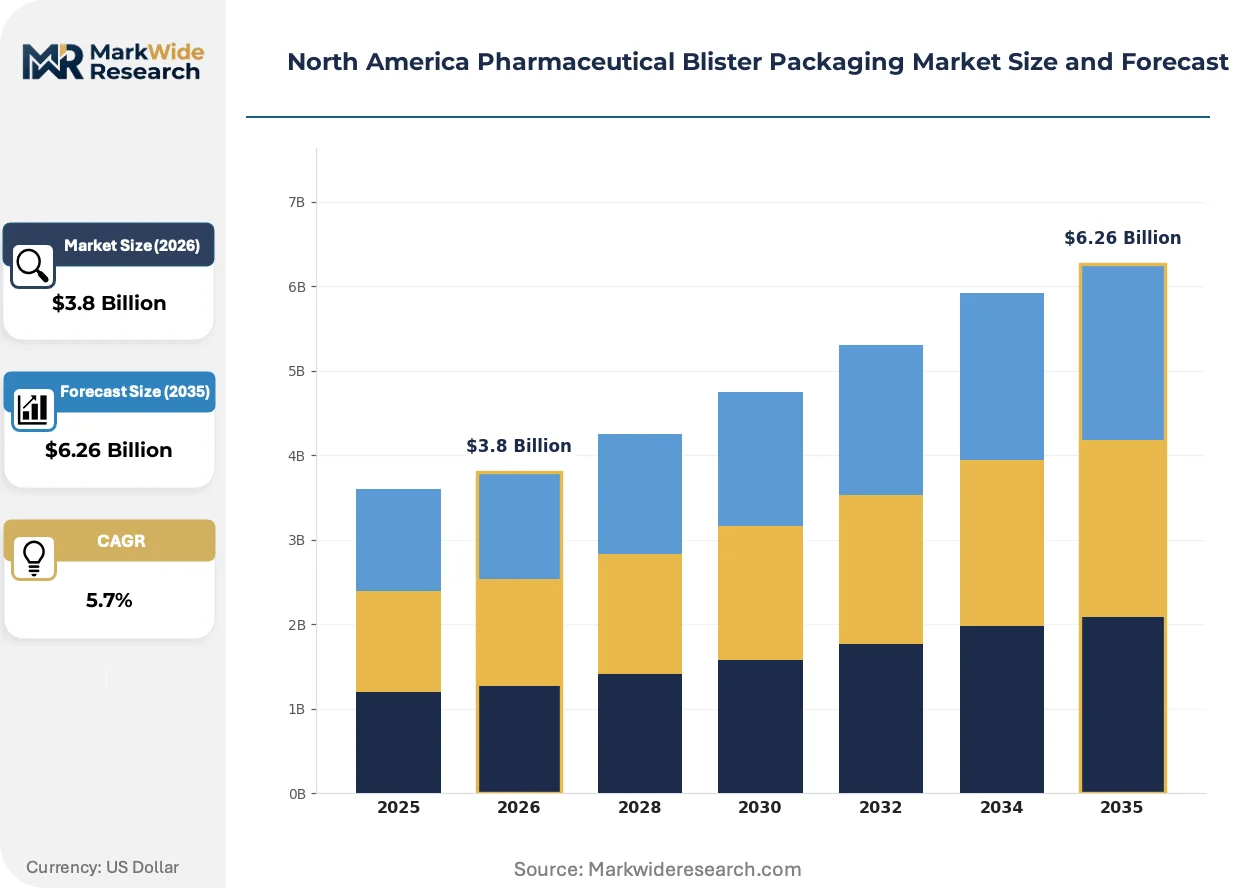
Market Dynamics
FDA 21 CFR Part 211 cGMP mandates and USP <661> material standards are compressing supplier qualification timelines while forcing capital-intensive line upgrades across the United States and Canada. This regulatory convergence is accelerating consolidation among contract packaging organizations capable of integrated serialization and barrier-grade conversion.
Growth Catalysts
- Oral solid dosage demand:Chronic disease patient populations in the United States Midwest and Southeast manufacturing corridors are expanding unit-dose packaging requirements for cardiovascular and oncology therapies.
- FDA serialization mandates:The Drug Supply Chain Security Act is compelling track-and-trace infrastructure investments that favor thermoform-fill-seal integrators with compatible software ecosystems.
- Aluminum-laminate barrier migration:Hygroscopic drug formulations are displacing standard PVC configurations with cold form structures achieving moisture vapor transmission rates below 0.5 g/m²/day.
Market Restraints
- Aluminum foil cost volatility:Primary aluminum price fluctuations from Canadian smelter supply constraints are compressing margins for cold form blister producers.
- Rigid PVC supply concentration:Domestic film extrusion capacity clusters in the Ohio River Valley, creating geographic single-source risk for generic oral solid dosage packagers.
- Health Canada ICH Q1A stability validation:Extended testing protocols for northern climate zones are elongating product launch timelines by eight to fourteen months.
Strategic Opportunities
- Contract packaging organization expansion:Big Pharma outsourcing of secondary packaging operations is creating white space for track-and-trace-capable integrators in the Research Triangle and New Jersey corridors.
- California extended producer responsibility:Pending state legislation on post-consumer blister recovery obligations is opening design-for-recycling service contracts ahead of mandate implementation.
- PET substitution acceleration:USP <661.1> extractables scrutiny is converging with thermoforming efficiency gains to displace PVC in brand-owner portfolios.
Industry Challenges
- Serialization engineering talent scarcity:Qualified validation specialists for FDA 21 CFR Part 211 compliance are concentrated among legacy pharmaceutical equipment vendors, constraining CPO scaling.
- Legacy thermoform line retrofit capex:DSCSA-compatible track-and-trace module integration requires six-figure capital commitments per production lane.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pharmaceutical Blister Packaging Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Form Blister, PVC Blister, PP Blister, PET Blister Therapy Area: Cardiovascular, Oncology, Neurology, Antidiabetic End User: Pharmaceutical Manufacturers, Contract Packaging Organizations, Hospitals, Clinics Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Pharmacies |
| Companies Covered | Amcor plc, Constantia Flexibles, WestRock Company, Sonoco Products Company, Klöckner Pentaplast, WINPAK LTD., Honeywell International Inc., CCL Healthcare, ACG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pharmaceutical Blister Packaging Market Trends and Innovations
Active and intelligent packaging systems are penetrating North American pharmaceutical supply chains, driven by patient adherence monitoring requirements and cold chain integrity demands for temperature-sensitive biologics. These embedded technologies are restructuring competitive advantage around data capture capabilities rather than commodity barrier performance.
Cold form aluminum-laminate structures with integrated desiccant films are electrifying moisture protection standards for hygroscopic oral solid dosages. Oncology and cardiovascular drug packagers in the United States are adopting these configurations at accelerating rates to secure FDA NDA approvals. This electrifying technology is compressing competitive differentiation toward complete barrier systems rather than incremental film improvements.
Health Canada ICH Q1A stability guidelines are tightening validation requirements for packaging systems exposed to northern climate zone temperature excursions. Canadian regulators now mandate accelerated aging protocols that exceed FDA baseline standards for moisture and oxygen ingress. Generic manufacturers serving the Canadian market are responding by qualifying higher-barrier structures originally developed for United States NDA products.
Big Pharma procurement functions are consolidating secondary packaging spend under single-source contract packaging organization agreements with embedded serialization capabilities. Brand owners in New Jersey and Massachusetts corridors are displacing fragmented supplier bases with multi-year partnerships that bundle thermoforming, lidding, and track-and-trace verification. This consolidation is most visible among mid-cap pharmaceutical companies lacking in-house packaging engineering resources.
North America Pharmaceutical Blister Packaging Market Segmentation
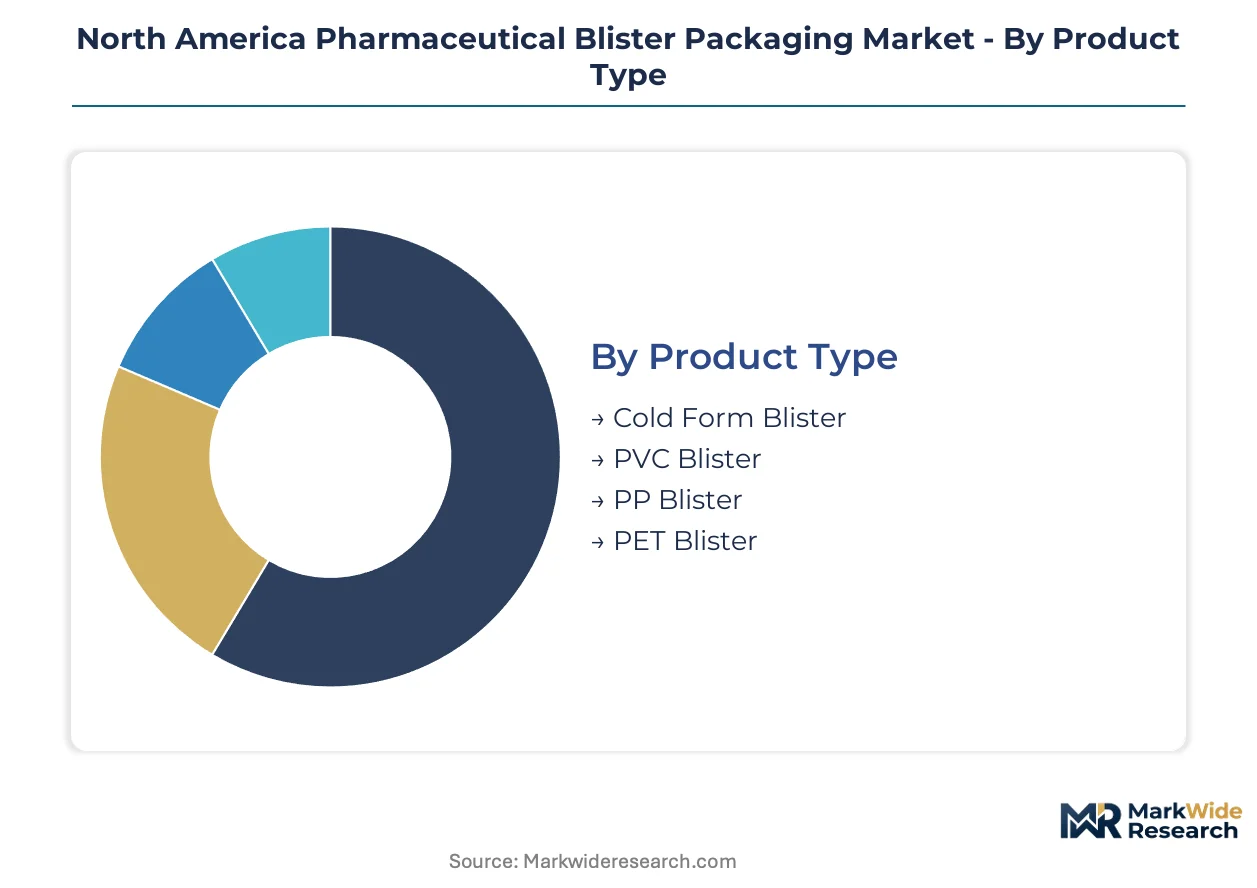
Pharmaceutical blister packaging segmentation in North America tracks regulatory burden intensity across material grades, therapy-specific barrier requirements, and channel-specific serialization mandates. Each dimension carries distinct FDA 21 CFR Part 211 and USP <661> compliance obligations that reshape supplier economics.
Product Type:
Cold form structures require FDA NDA-level validation protocols, while thermoformed alternatives face USP <661.1> extractables scrutiny that compresses qualification timelines.
- Cold Form Blister:Aluminum-laminate cavities with complete moisture and oxygen barriers achieve moisture vapor transmission rates below 0.5 g/m²/day. Oncology and cardiovascular drug packagers in the United States Midwest corridor specify these configurations for hygroscopic formulations requiring FDA NDA stability data.
- PVC Blister:Rigid polyvinyl chloride thermoforms dominate generic oral solid dosage volumes through cost-efficient high-speed production. Ohio River Valley extrusion clusters supply domestic capacity, though USP <661> plasticizer migration concerns are accelerating displacement in brand-owner portfolios.
- PP Blister:Polypropylene films offer intermediate barrier performance with superior thermoforming efficiency versus PVC. Limited adoption concentrates in Canadian generic manufacturers seeking Health Canada ICH Q1A stability compliance at reduced material cost.
- PET Blister:Polyethylene terephthalate structures satisfy USP <661.1> extractables scrutiny with clarity matching PVC. Brand owners in the United States Southeast manufacturing corridor are substituting PET at accelerating rates for retail pharmacy visibility requirements.
Cold Form Blister sits at the top of the volume ranking, with PET Blister climbing the fastest.
Therapy Area:
Barrier-grade specifications concentrate in chronic disease categories with extended dosing regimens and moisture-sensitive active pharmaceutical ingredients.
- Cardiovascular:Beta-blockers and statin formulations demand unit-dose adherence packaging with child-resistant lidding. United States Southeast manufacturing corridors generate concentrated demand for aluminum-laminate structures securing twelve-month shelf-life claims.
- Oncology:Cytotoxic oral solid dosages require the highest barrier protection plus tamper-evident features. Cold form configurations with integrated desiccant films dominate this segment as FDA mandates escalate packaging integrity standards for patient safety.
- Neurology:Antiepileptic and antipsychotic medications utilize standard PVC or PET blisters with senior-friendly opening features. Compliance packaging innovations are penetrating this segment slower than cardiovascular due to generic price compression.
- Antidiabetic:Metformin and DPP-4 inhibitor packaging balances moisture protection with cost constraints. Contract packaging organizations in the Research Triangle corridor capture disproportionate volume through Big Pharma outsourcing agreements.
Cardiovascular commands the largest share of packaging spend, with Oncology expanding most quickly.
End User:
Capital intensity and serialization capability requirements fragment the customer base across in-house manufacturing and outsourced operations.
- Pharmaceutical Manufacturers:Big Pharma in-house operations in New Jersey and Massachusetts corridors maintain captive blister lines for NDA products. These facilities carry the highest regulatory audit frequency and barrier-grade material specifications.
- Contract Packaging Organizations:Track-and-trace-integrating secondary packaging specialists are capturing outsourcing volume from mid-cap pharmaceutical companies. The Research Triangle and New Jersey corridors host the fastest-scaling CPO capacity.
- Hospitals:Unit-dose repackaging for inpatient pharmacy automation drives demand for barcoded blisters with integrated medication identification. Health system consolidation is concentrating purchasing through group purchasing organizations.
- Clinics:Sample packaging and short-course therapies generate smaller batch requirements with faster turnaround needs. Regional contract packagers serve this segment through flexible production scheduling.
Contract Packaging Organizations are gaining share fastest, with Pharmaceutical Manufacturers retaining the largest absolute volume position.
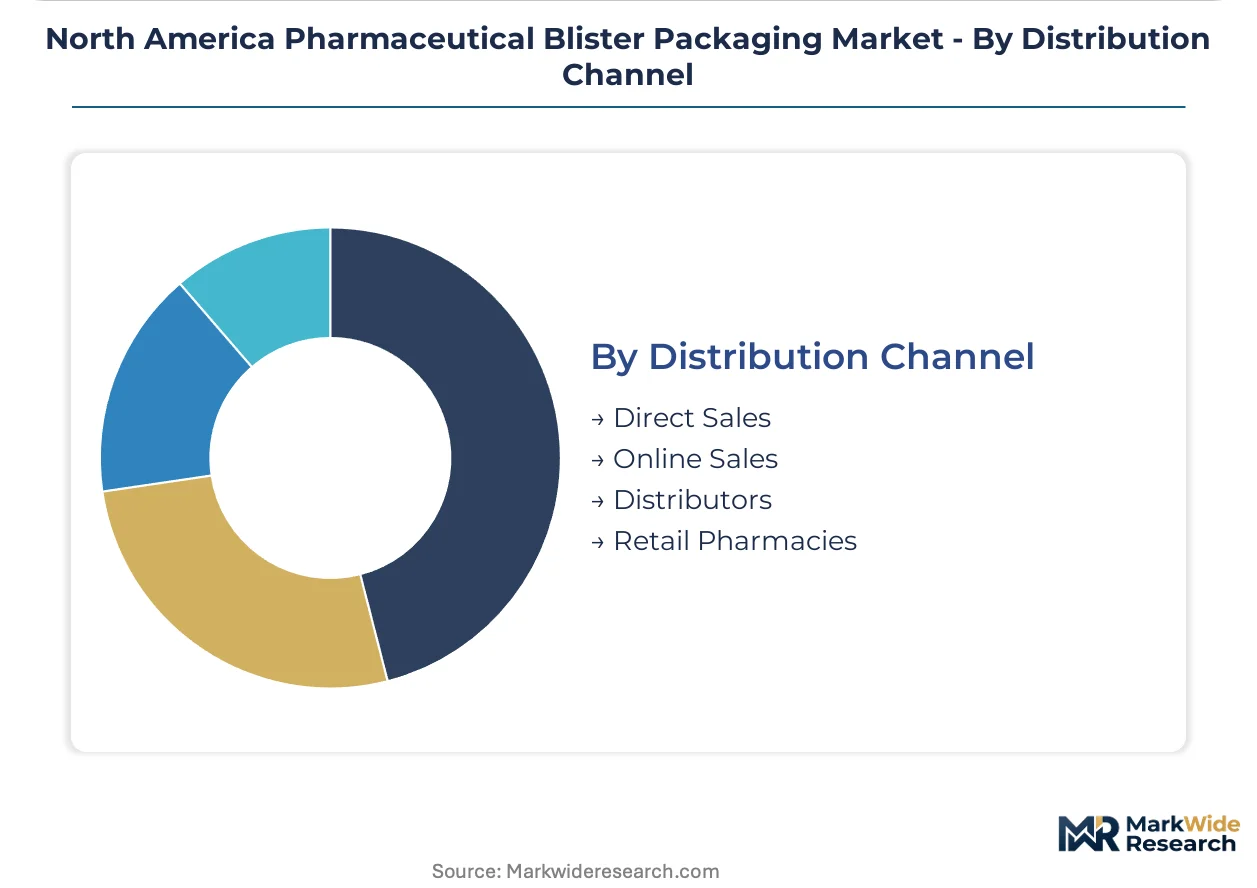
Distribution Channel:
Channel selection determines serialization data handoff requirements and lot-level traceability obligations under DSCSA mandates.
- Direct Sales:Manufacturer-to-pharmaceutical company relationships dominate barrier-grade cold form supply. These contracts bundle thermoforming, lidding, and validation documentation with multi-year supply agreements.
- Online Sales:E-procurement platforms for standard PVC and PET films are penetrating generic manufacturer purchasing functions. Digital channels reduce procurement overhead for high-volume, specification-stable materials.
- Distributors:Regional packaging material distributors serve mid-tier pharmaceutical companies with fragmented SKU requirements. Inventory pooling mitigates geographic concentration risk in Ohio River Valley film supply.
- Retail Pharmacies:Private-label over-the-counter blister packaging generates distinct demand for paperboard-backed configurations. WestRock Company anchors this channel through retail pharmacy and hospital network control.
Direct Sales maintains volume leadership, with Online Sales showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers and validation specialists concentrate in the United States Midwest and Northeast corridors, anchoring North American pharmaceutical blister packaging capacity. FDA serialization mandates and USP material standards reshape where qualified labor pools command premium wages. Geographic proximity to pharmaceutical manufacturing clusters determines supplier site selection.
United States
Oncology and cardiovascular drug packagers in the Midwest manufacturing corridor drive cold form blister demand for hygroscopic formulations. FDA 21 CFR Part 211 cGMP requirements and DSCSA serialization mandates compress supplier qualification timelines. New Jersey and Massachusetts host Big Pharma captive operations with the highest regulatory audit frequency.
Canada
Generic manufacturers serving northern climate zones accelerate barrier-grade adoption under Health Canada ICH Q1A stability guidelines. Extended testing protocols for temperature excursion validation elongate product launch timelines. Ontario-based contract packagers capture outsourcing volume from mid-cap pharmaceutical companies seeking serialization integration.
Mexico
Nearshore manufacturing expansion for US-bound oral solid dosages generates thermoformed blister demand in Baja California and Mexico City metro areas. COFEPRIS alignment with FDA standards facilitates cross-border supply chain integration. Maquiladora operations concentrate PVC and PET film converting for generic export markets.
North America Pharmaceutical Blister Packaging Market Competitive Landscape
Top-tier vendors anchor integrated film-to-converting operations, while mid-scale specialists compete on regulatory compliance speed and flexible batch sizing. The vendor base stratifies across barrier-grade cold form suppliers, commodity thermoform converters, and track-and-trace-integrating contract packaging organizations. Three archetypes dominate: integrated material-converting conglomerates, pure-play barrier film specialists, and serialization-capable CPOs. M&A activity concentrates among contract packaging targets, while capacity expansion favors thermoform-fill-seal line upgrades with DSCSA-compatible software ecosystems.
Within the integrated material-converting tier, Amcor plc and WestRock Company occupy positions spanning film extrusion through finished blister supply. Klöckner Pentaplast exemplifies the scale-driven thermoform specialist archetype with rigid PVC and PET film dominance. These three anchors represent distinct competitive vectors: complete barrier systems, retail pharmacy channel control, and generic oral solid dosage cost efficiency.
| Leading Market Players |
|---|
| Amcor plc |
| Constantia Flexibles |
| WestRock Company |
| Sonoco Products Company |
| Klöckner Pentaplast |
| WINPAK LTD. |
| Honeywell International Inc. |
| CCL Healthcare |
| ACG |
| Others |
Pricing and Supply Chain Analysis
PET thermoforming line conversions are compressing unit economics for brand owners while simultaneously dispersing film extrusion capacity beyond traditional Ohio River Valley clusters. This technology transition rewards early movers with qualification speed advantages while penalizing legacy PVC-dependent converters with stranded asset risk.
Pricing Analysis
Bundled serialization-plus-barrier service contracts command premiums against unbundled film-and-converting procurement. Price differentiation hinges on FDA NDA validation documentation depth and DSCSA track-and-trace software integration maturity. Pricing pressure stems from aluminum foil cost volatility originating in Canadian smelter supply constraints. Generic oral solid dosage manufacturers exhibit highest price sensitivity, while oncology drug packagers prioritize barrier performance over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Big Pharma procurement functions are fragmenting film supply across United States, Canada, and Mexico. Primary aluminum draws from Canadian smelters, rigid PVC film feeds from Ohio River Valley extruders, and PET resin sources from Gulf Coast petrochemical complexes. Single-source vulnerability concentrates in Health Canada ICH Q1A stability validation bottlenecks. Distribution runs through direct manufacturer relationships for barrier-grade cold form, with regional distributors handling commodity thermoform volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
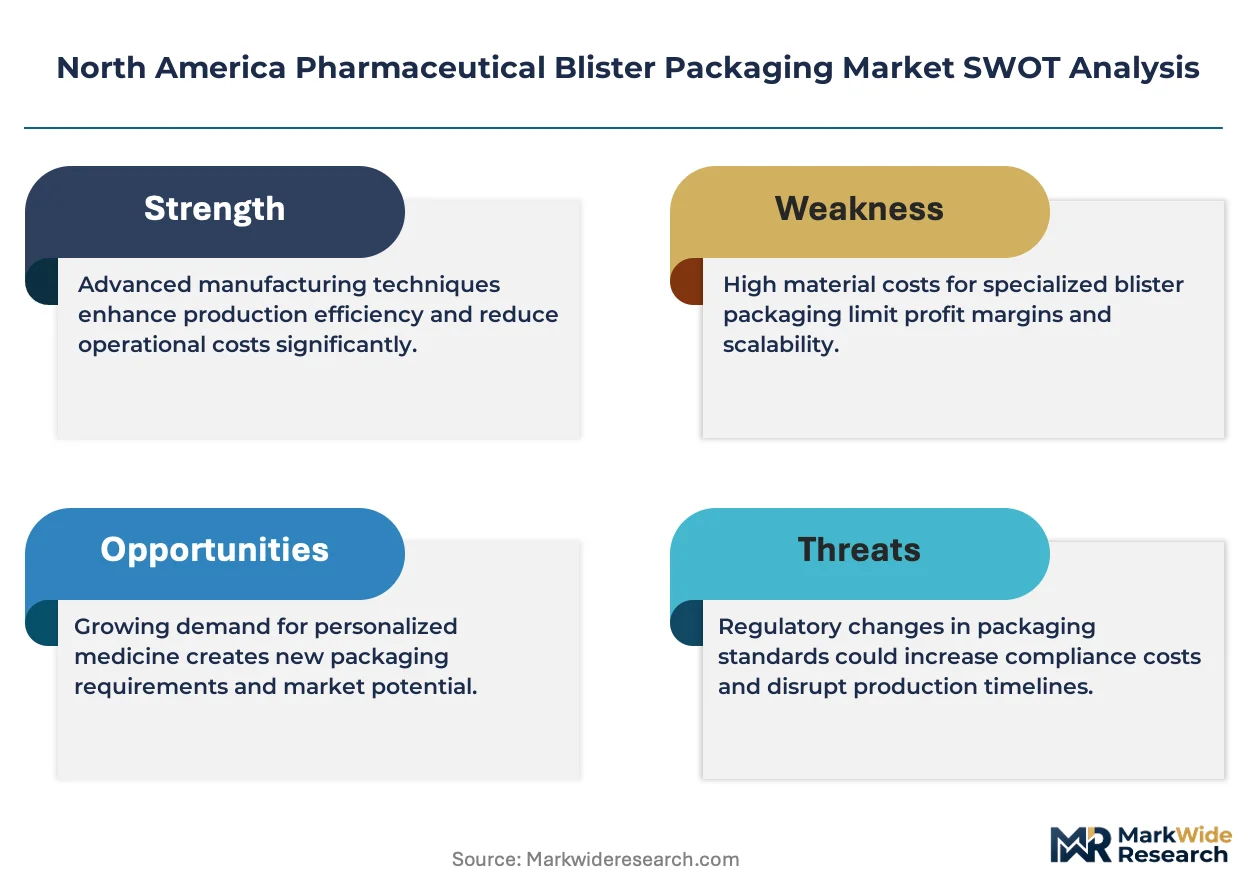
North America pharmaceutical blister packaging functions as a stable compounder anchored by chronic disease patient population expansion and irreplaceable oral solid dosage adherence requirements.
For Market Incumbents: Deepen backward integration into PET film extrusion to capture USP <661.1> substitution tailwinds and defend against commodity PVC margin erosion. Consolidate serialization engineering talent pools through targeted hiring in New Jersey and Research Triangle corridors to maintain DSCSA compliance speed advantages. For New Entrants and Emerging Players: Launch via contract packaging organization partnerships targeting mid-cap pharmaceutical companies lacking in-house barrier validation capabilities. White space concentrates in California extended producer responsibility design-for-recycling services and Canadian generic manufacturers seeking Health Canada ICH Q1A fast-track qualification. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play barrier film specialists lacking integrated serialization capabilities. Long-term viability favors track-and-trace-integrating CPOs with multi-year Big Pharma outsourcing contracts. Watch California and New York extended producer responsibility implementation timelines as inflection signals for recycling infrastructure investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Film Extrusion Capacity Expansion | Captures PET substitution demand from FDA-regulated brand owners seeking USP <661.1> compliance. |
| Serialization Software Integration | Aligns thermoform-fill-seal lines with DSCSA mandates and Big Pharma track-and-trace requirements. |
| Design-for-Recycling Service Launch | Positions ahead of California extended producer responsibility mandates for post-consumer blister recovery. |
| Contract Packaging Organization Acquisition | Consolidates fragmented secondary packaging spend under integrated barrier-plus-serialization offerings. |
| Health Canada ICH Q1A Validation Investment | Accelerates product launch timelines for generic manufacturers serving northern climate zone requirements. |
Research Methodology
Coverage spans United States, Canada, and Mexico, with primary inputs from each national regulatory cluster. The analysis combines structured interviews with packaging engineers, regulatory affairs specialists, contract packaging operations directors, and pharmaceutical procurement managers with secondary validation against FDA 21 CFR Part 211 guidance documents, USP <661> plastic packaging standards, Health Canada ICH Q1A stability guidelines, and DSCSA implementation records. Bottom-up unit demand modeling triangulates against top-down pharmaceutical production value estimates.
Granularity extends to product type, therapy area, end user, and distribution channel dimensions, with additional modeling of regional regulatory cluster effects across the projection horizon. CAGRs derive from segment-level volume and value buildups incorporating oral solid dosage demand trajectories, serialization infrastructure investment cycles, and material substitution elasticities. Industry-specific forecast inputs include aluminum price volatility indices and contract packaging organization capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated California extended producer responsibility implementation or prolonged Canadian smelter supply disruptions. Deviation in FDA serialization enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Blister Foil Market
Blister Packaging
Asia Pacific Pharmaceutical Blister Packaging Market
Blister Packaging
PVC Blister Packaging Market
Blister Packaging
Global Blister Packaging Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
Holographic Blister Foil Market
Blister Packaging
Ampoules and Blister Packaging Market
Blister Packaging
Blister Packs Market
Blister Packaging
High Barrier Pharmaceutical Packaging Films for Blister Market
Blister Packaging
Healthcare Blister Packaging Market
Blister Packaging
Global Cold Form Blister Packaging Market
Blister Packaging
Liquid Blister Pack Market
Blister Packaging
Middle East and Africa Blister Packaging Market
Blister Packaging
Alu Alu Blister Packaging Machine Market
Blister Packaging
Welded Blisters Market
Blister Packaging
Blister Paper Market