
 Blister Cards Market | 2026-2036
Blister Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Blister Cards Market Outlook
Modular dose-configuration packaging is rebalancing buyer choice across chronic-therapy categories as pharmaceutical brands seek patient adherence formats that integrate directly with pharmacy automation. Amcor plc leverages its global film and converting footprint to supply integrated blister solutions across multiple continents. WestRock Company anchors North American demand through its paperboard-backed blister platforms that bridge sustainability targets with child-resistance compliance. Sonoco Products Company specializes in high-barrier specialty films for moisture-sensitive formulations, competing on technical performance rather than commodity volume.
Blister cards are thermoformed or cold-formed plastic cavities sealed to a lidding substrate, typically constructed from PVC, PET, or paperboard composites, designed to protect individual product units from environmental degradation while enabling precise unit-dose dispensing. The primary commercial purpose spans pharmaceutical tablet protection, cosmetic sample presentation, and consumer electronics tamper-evident retail display. PVC retains dominance in cost-sensitive pharmaceutical applications where clarity and formability outweigh sustainability concerns, while PET is gaining structural share as brand owners respond to recyclability mandates and retailer plastic-reduction commitments. Thermoforming technology occupies the largest process share due to its speed and tooling flexibility, though cold forming commands premium positioning for moisture-sensitive active pharmaceutical ingredients requiring aluminum-barrier protection.
The US FDA enforces child-resistant packaging standards under 16 CFR 1700 and drug supply chain security requirements through the Drug Supply Chain Security Act, directly shaping blister card design specifications and authentication layer integration. The EU Green Deal and REACH chemical restrictions are forcing material transitions away from certain PVC plasticizers, compelling converters to validate alternative substrates without sacrificing barrier performance. Stakeholders must monitor evolving extended producer responsibility frameworks and pharmaceutical serialization deadlines to align capital investment with compliance-driven specification changes.
Market Dynamics
Pharmaceutical serialization mandates are compressing design-to-delivery cycles across the blister card supply chain, forcing converters to integrate authentication layers at the tooling stage rather than as downstream add-ons. This regulatory pressure is reshaping capital allocation toward inline printing and track-and-trace capabilities.
Growth Catalysts
- Unit-dose compliance packaging:Pharmaceutical manufacturers in North America are expanding adherence programs that require precise cavity configurations and patient-friendly tear-notches, pulling demand toward specialized thermoforming lines.
- REACH chemical restrictions:The EU Green Deal is accelerating substrate transitions away from legacy PVC plasticizers, creating replacement demand for PET and paperboard composite structures that maintain barrier performance.
- Moisture-sensitive formulations:Cold-formed aluminum-barrier blisters are gaining traction for hygroscopic active pharmaceutical ingredients, particularly among contract packaging organizations serving European markets.
Market Restraints
- Resin price volatility:PVC and PET feedstock costs fluctuate with crude oil and recycled flake availability, compressing converter margins on long-term pharmaceutical supply contracts.
- Tooling lead times:Custom thermoform molds for complex cavity geometries require 12-16 week fabrication cycles, creating bottlenecks for brand owners launching serialized packaging redesigns.
- Substitution by bottles:High-volume chronic therapies in cost-sensitive markets continue defaulting to HDPE containers with induction seals, limiting blister card penetration in oral solid dose categories.
Strategic Opportunities
- Pharmacy automation integration:Modular blister cards designed for robotic dispensing systems represent underpenetrated white space as US and German retail pharmacy chains upgrade fulfillment infrastructure.
- Extended producer responsibility frameworks:Emerging packaging waste regulations in France and Italy are creating first-mover advantages for converters offering take-back programs and mono-material recyclable structures.
- Cosmetic sample formats:Premium beauty brands are adopting unit-dose blister presentations for serum and mask samples, opening non-pharmaceutical volume channels with shorter qualification cycles.
Industry Challenges
- Serialization compliance timelines:The US FDA's Drug Supply Chain Security Act deadlines require line-level hardware upgrades and software validation that strain mid-cap converter technical resources.
- Multi-layer film expertise:High-barrier lidding structures combining aluminum, polymer, and heat-seal coatings demand specialized lamination knowledge that remains concentrated among a narrow supplier base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blister Cards Market |
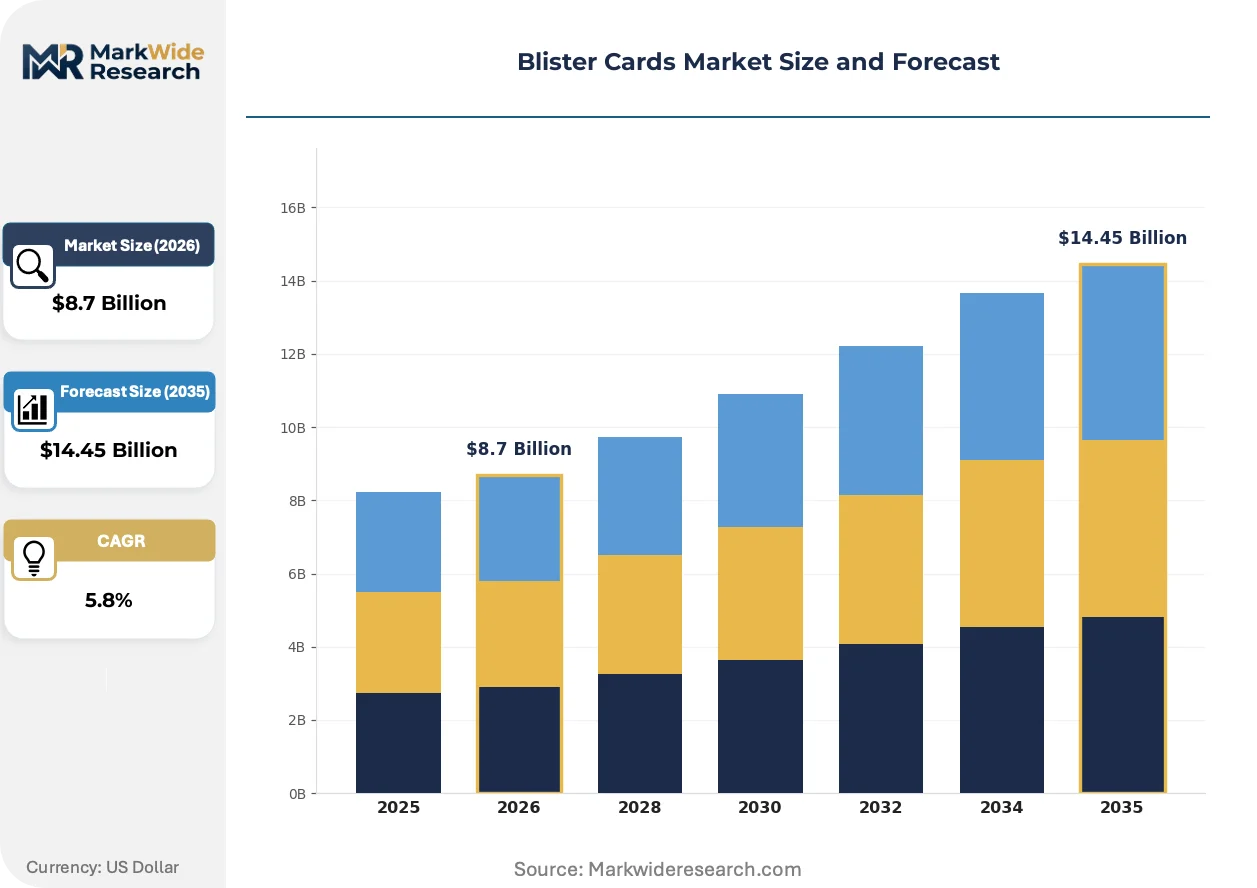
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, PET, Paperboard, Polyethylene End User: Pharmaceuticals, Cosmetics, Food & Beverage, Electronics Technology: Thermoforming, Cold Forming, Injection Molding, Hybrid Packaging Type: Standard Blister, Clamshell, Skin Pack, Others |
| Companies Covered | Amcor plc, WestRock Company, Sonoco Products Company, SupplyOne, Inc., Rohrer Corporation, Constantia Flexibles, Winpak Ltd., Honeywell International Inc., Tekni-Plex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blister Cards Market Strategic Shifts
Digital printing and smart packaging technologies are converging to transform blister cards from passive containers into interactive adherence tools, embedding sensors and variable data directly at the point of formation.
Near-field communication chips embedded in blister lidding are unifying dose-verification with patient engagement platforms. Chronic disease management programs at US health systems are piloting these connected formats to capture real-time adherence data. The technology is compressing the boundary between packaging and digital therapeutics, creating new revenue streams for converters willing to partner with health technology vendors.
REACH restrictions on phthalate plasticizers are forcing rapid substrate validation across European pharmaceutical packaging lines. Converters must demonstrate equivalent barrier performance and seal integrity for alternative PVC formulations or PET replacements without disrupting existing registration files. German contract packaging organizations are bearing the highest compliance burden, serving as technical validators for substrate transitions across the continent.
Retail pharmacy chains are consolidating procurement specifications around child-resistant senior-friendly formats that satisfy 16 CFR 1700 while accommodating aging patient populations. This specification convergence is displacing fragmented regional designs with standardized push-through and peel-open structures. The shift is most visible in US Medicare Part D fulfillment channels, where mail-order volume growth favors automation-compatible geometries.
Blister Cards Market Segmentation
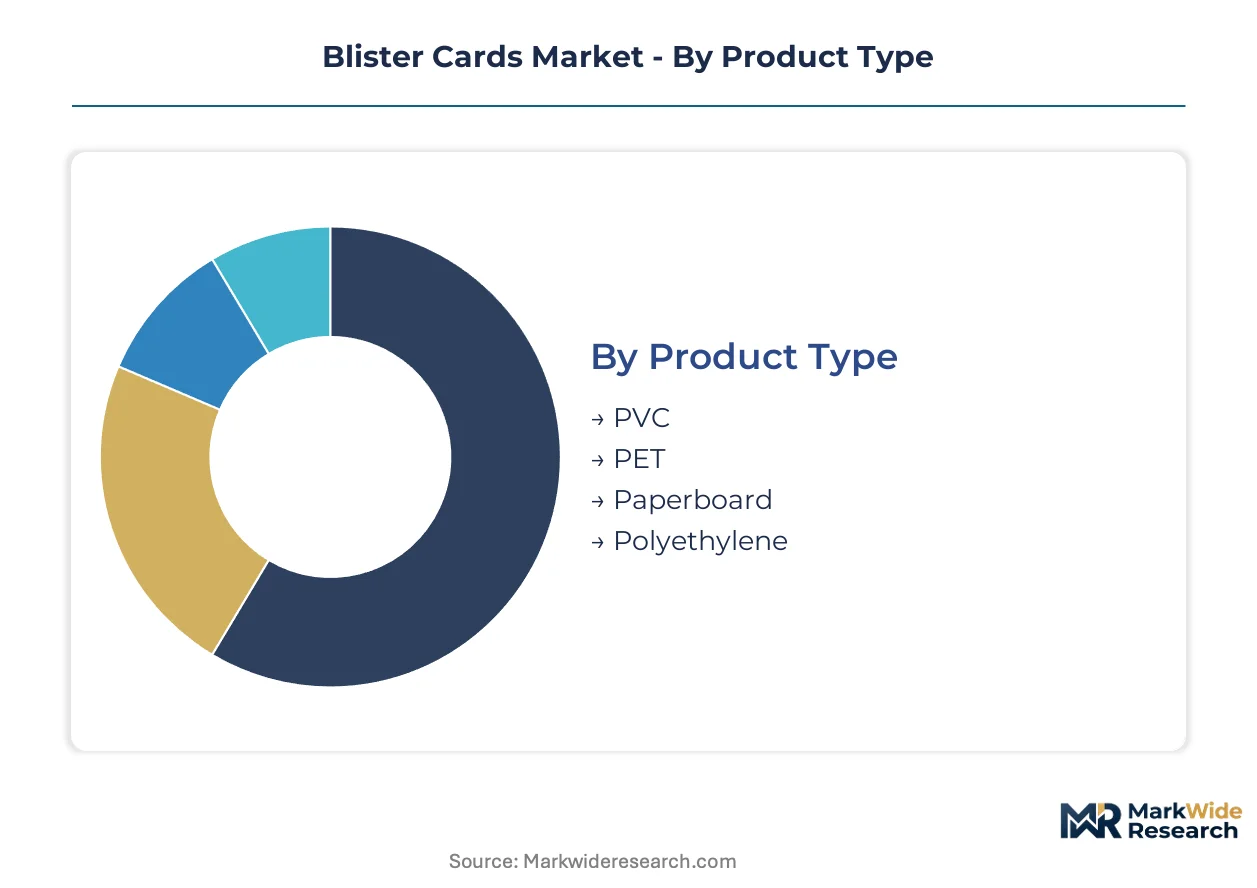
Blister card specifications diverge sharply across substrate chemistry, forming process, and end-use compliance requirements. Pharmaceutical serialization mandates and retailer sustainability commitments are compressing the viable specification range, rewarding converters with validated multi-substrate capabilities.
Product Type:
Substrate selection pivots on barrier performance, recyclability positioning, and regulatory clearance for direct pharmaceutical contact.
- PVC:Polyvinyl chloride dominates cost-sensitive pharmaceutical applications through superior thermoformability and optical clarity. Demand concentrates in US generic oral solid dose packaging where FDA 16 CFR 1700 child-resistance compliance takes precedence over sustainability metrics.
- PET:Polyethylene terephthalate is displacing PVC in European markets responding to ECHA REACH restrictions on phthalate plasticizers. German contract packaging organizations are validating PET alternatives to maintain registration files without barrier degradation.
- Paperboard:Fiber-based substrates with polymer barrier coatings serve sustainability-forward cosmetic sampling and premium electronics retail display. WestRock Company anchors North American supply for paperboard-backed blister platforms.
- Polyethylene:Lower-barrier PE structures occupy food-contact and short-shelf-life consumer goods where moisture protection requirements are modest.
PVC leads on scale; PET leads on momentum.
End User:
Application-driven specifications create distinct performance tiers across regulated and non-regulated sectors.
- Pharmaceuticals:Unit-dose compliance packaging for chronic therapies demands precise cavity tolerances, child-resistant senior-friendly opening features, and integrated serialization layers. US Medicare Part D mail-order fulfillment is accelerating automation-compatible format standardization.
- Cosmetics:Premium beauty brands are adopting unit-dose blister presentations for serum and mask samples, opening non-pharmaceutical volume channels with shorter qualification cycles and higher graphic embellishment tolerance.
- Food & Beverage:Modified-atmosphere blister structures for portion-controlled confectionery and nutritional supplements occupy a mid-tier specification band with moderate barrier requirements.
- Electronics:Tamper-evident clamshell and skin-pack formats for consumer electronics accessories prioritize theft deterrence and retail display impact over environmental protection.
Pharmaceuticals command specification intensity; cosmetics are expanding most quickly.
Technology:
Forming process selection locks in capital equipment, cycle economics, and barrier class for the production run.
- Thermoforming:Vacuum and pressure thermoforming occupies the largest process share through speed and tooling flexibility across PVC and PET substrates. Amcor plc leverages global thermoforming footprints to supply integrated blister solutions.
- Cold Forming:Aluminum-barrier cold forming commands premium positioning for hygroscopic active pharmaceutical ingredients requiring maximum moisture protection. European contract packaging organizations concentrate technical expertise here.
- Injection Molding:Rigid cavity injection molding serves high-unit-count pharmaceutical formats and durable goods packaging where dimensional precision exceeds thermoforming capability.
- Hybrid:Combined thermoform-injection processes enable complex multi-cavity configurations for combination therapies and medical device blisters.
Thermoforming leads on scale; cold forming leads on technical premium capture.
Packaging Type:
Structural format determines opening mechanics, protection level, and retail presentation geometry.
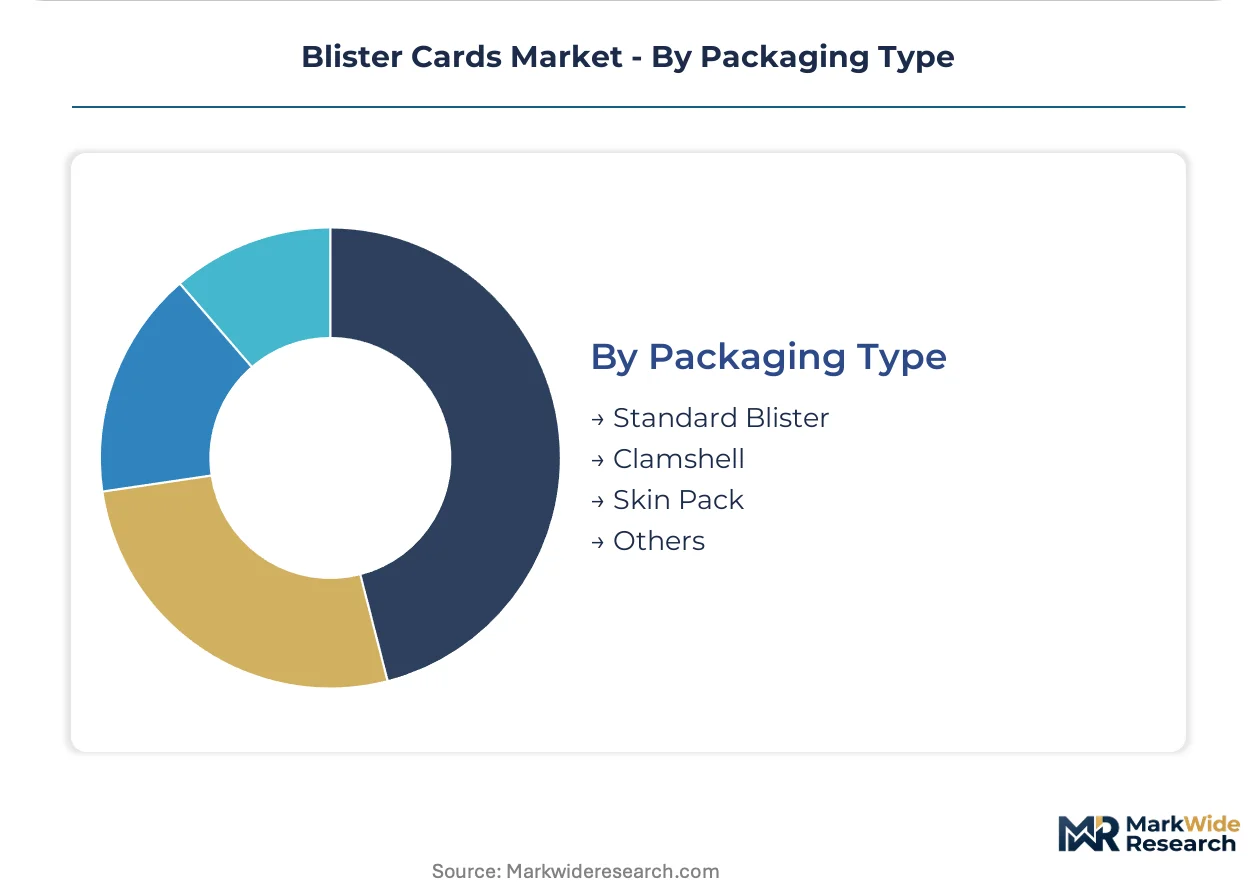
- Standard Blister:Push-through and peel-open carded blisters constitute the pharmaceutical default, with lidding substrate selection driving child-resistance and senior-friendliness tradeoffs.
- Clamshell:Two-piece hinged thermoformed shells dominate electronics retail display and high-theft-risk consumer goods, with heat-seal and friction-lock closure variants.
- Skin Pack:Film vacuum-formed tightly over product and card backing serves hardware and automotive aftermarket applications requiring product visibility and handling protection.
- Others:Specialty formats including trapped blister and slide blister configurations address specific retail fixture and automation requirements.
Standard blister leads on pharmaceutical volume; clamshell leads on retail loss prevention applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blister card manufacturing originated in post-war Germany and the United States, where pharmaceutical packaging automation first scaled unit-dose formats for mass distribution. Today production concentrates in industrial clusters spanning Germany, the United States, China, India, and Switzerland.
Germany
Contract packaging organizations in Baden-Württemberg and Bavaria serve as Europe's technical hub for cold-formed aluminum-barrier blisters. ECHA REACH restrictions on phthalate plasticizers are accelerating substrate validation programs across Rhine-Main manufacturing corridors. Stuttgart-area converters are piloting PET alternatives to maintain registration files for moisture-sensitive formulations.
United States
FDA serialization mandates under the Drug Supply Chain Security Act are compressing design-to-delivery cycles for Medicare Part D mail-order fulfillment. New Jersey and Pennsylvania host the densest concentrations of thermoforming capacity serving North American pharmaceutical demand. Chicago-area converters are integrating inline printing capabilities to meet authentication layer requirements.
China
NMPA traceability regulations are driving adoption of serialized blister formats for domestic pharmaceutical distribution. Yangtze River Delta manufacturing zones around Shanghai and Suzhou concentrate export-oriented PVC and PET thermoforming capacity. Zhejiang province converters are expanding cold-forming expertise for hygroscopic active pharmaceutical ingredients.
India
CDSCO packaging regulations and the PLI scheme for pharmaceuticals are pulling investment toward compliance-grade blister infrastructure. Gujarat and Maharashtra host the majority of domestic contract packaging capacity for oral solid dose exports. Hyderabad's pharmaceutical cluster is validating child-resistant senior-friendly formats for US and European markets.
Switzerland
Swissmedic quality standards sustain premium positioning for high-barrier specialty films serving biologic and precision-dose applications. Basel's pharmaceutical corridor demands cold-formed aluminum structures with validated seal integrity for moisture-critical formulations. Zurich-area converters specialize in small-batch clinical trial packaging with rapid tooling turnaround.
Blister Cards Market Competitive Environment
Premium-margin players sit above commodity-margin players across barrier performance and regulatory validation capabilities. The market exhibits tiered concentration, with global film suppliers and regional converters occupying distinct specification bands. Three archetypes dominate: integrated multinationals with captive resin and converting assets; mid-cap specialists focused on high-barrier pharmaceutical applications; and regional job shops serving cost-sensitive generic markets. Competitive moves concentrate on strategic partnerships for serialization technology and geographic expansion into pharmacy automation corridors.
Among integrated multinationals, Amcor plc exemplifies global film and converting footprint across multiple continents. WestRock Company anchors North American positioning through paperboard-backed platforms. Sonoco Products Company occupies the specialty-film tier, with technical performance positioning rather than commodity volume. These three represent distinct competitive vectors: resin-to-package integration, sustainable substrate leadership, and high-barrier formulation expertise.
| Leading Market Players |
|---|
| Amcor plc |
| WestRock Company |
| Sonoco Products Company |
| SupplyOne, Inc. |
| Rohrer Corporation |
| Constantia Flexibles |
| Winpak Ltd. |
| Honeywell International Inc. |
| Tekni-Plex |
| Others |
Value Chain & Pricing Dynamics
Barrier-performance certification tiers separate cold-formed aluminum structures from commodity PVC thermoforms, with that divergence mapping directly onto supply chain sourcing strategies and buyer procurement hierarchies across German contract packaging corridors and North American mail-order pharmacy channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates blister card procurement, with cold-formed aluminum-barrier formats commanding substantial premiums over PVC thermoforms due to validated moisture protection and serialization-ready substrate integration. Price differentiation hinges on EMA regulatory validation status and volume scale commitments under long-term pharmaceutical supply contracts. Cost compression in standard-grade PVC segments is intensifying because resin feedstock volatility and converter overcapacity in Asian export markets. Generic oral solid dose manufacturers exhibit highest price sensitivity, while biologic and precision-dose formulators prioritize barrier performance over unit cost.
Supply Chain Analysis
FDA and EMA qualification requirements gate supply chain participation, restricting validated cold-forming capacity to converters with demonstrated seal-integrity protocols and registration file maintenance capabilities. Manufacturing concentrates in Germany, the United States, and China, with raw material dependencies spanning aluminum foil from European rolling mills, PVC and PET resin from petrochemical complexes, and specialty heat-seal coatings from concentrated chemical suppliers. Single-source vulnerability in high-barrier lidding film lamination creates bottleneck risk for moisture-sensitive pharmaceutical formulations. Distribution runs through contract packaging organizations serving as technical intermediaries between substrate converters and finished-dose pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blister cards market functions as a stable compounder anchored by irreversible pharmaceutical serialization mandates that permanently elevate specification requirements and lock in replacement demand cycles across regulated packaging formats.
For Market Incumbents: Anchor defensive positioning through backward integration into specialty film lamination capabilities, eliminating single-source vulnerability in high-barrier lidding structures that European contract packaging organizations currently monopolize. Prioritize capacity addition in Stuttgart-area manufacturing corridors to capture substrate validation workflows driven by ECHA REACH restrictions on legacy PVC plasticizers. Certification investment in child-resistant senior-friendly formats secures Medicare Part D mail-order procurement specifications against emerging regional competitors. For New Entrants and Emerging Players: Launch via pharmacy automation integration partnerships targeting robotic dispensing system compatibility, a specification tier where incumbent converters lack dedicated tooling investment. Cosmetic sample formats for premium beauty brands represent the most penetrable white-space channel, offering shorter qualification cycles and higher graphic embellishment tolerance than pharmaceutical validation pathways. Direct-to-brand sampling programs bypass entrenched contract packaging intermediaries. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap converters possess validated cold-forming expertise but lack capital for inline serialization hardware upgrades required under FDA Drug Supply Chain Security Act enforcement timelines. Long-term viability favors acquisition targets with demonstrated multi-substrate capabilities spanning PVC, PET, and paperboard composites across German and North American regulatory jurisdictions. The signal to watch is acceleration in pharmacy chain procurement standardization around automation-compatible geometries.| Strategic Initiative | Industry Significance |
|---|---|
| Inline Serialization Hardware Upgrade | Enables compliance with FDA Drug Supply Chain Security Act mandates at the tooling stage. |
| PET Substrate Validation Program | Maintains registration file continuity as ECHA REACH restrictions displace legacy PVC plasticizers. |
| Pharmacy Automation Partnership | Captures modular blister specifications for robotic dispensing systems in US and German retail chains. |
| Extended Producer Responsibility Program | Creates first-mover advantage under emerging French and Italian packaging waste regulations. |
| Cosmetic Sample Channel Expansion | Diversifies revenue into premium beauty unit-dose formats with faster qualification cycles. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with contract packaging executives, pharmaceutical regulatory affairs leads, substrate converter plant managers, and retail pharmacy procurement directors alongside secondary validation through FDA 510(k) filings, EMA packaging authorization databases, SEC 10-K disclosures from listed packaging converters, and customs trade data on PVC and PET resin flows. Bottom-up demand modeling from pharmaceutical dosage form projections triangulates against top-down packaging spend estimates across chronic therapy categories.
Rate-of-change decomposition separates volume growth from mix-shift effects across the analysis window, with segmentation dimensions spanning substrate chemistry, forming process technology, end-use regulatory intensity, and regional compliance cluster. CAGRs derive from modeled unit-dose packaging penetration rates in oral solid dose categories, cross-referenced against pharmaceutical serialization deadline enforcement patterns and pharmacy automation infrastructure investment cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt resin price spikes or accelerated ECHA chemical restriction timelines. Forecasts reflect assumptions regarding regulatory enforcement continuity and pharmaceutical outsourcing propensity. A model refresh is warranted upon material change in FDA serialization deadline enforcement or European extended producer responsibility framework implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Blister Foil Market
Blister Packaging
Asia Pacific Pharmaceutical Blister Packaging Market
Blister Packaging
Blister Packaging Equipment Market
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
Pharma Blisters Packaging Market
Blister Packaging
Ampoules and Blister Packaging Market
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market
Blister Packaging
Europe Blister Packaging Market
Blister Packaging
Global Cold Form Blister Packaging Market
Blister Packaging
Liquid Blister Pack Market
Blister Packaging
Holographic Blister Foil Market
Blister Packaging
Carded Blister Packaging Market
Blister Packaging
Alu Alu Blister Packaging Machine Market
Blister Packaging
PVC Blister Packaging Market
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
Welded Blisters Market