
 Middle East and Africa Blister Packaging Market | 2026-2036
Middle East and Africa Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Blister Packaging Market Foresight
Market Context
Pharmaceutical manufacturers are bifurcating from consumer goods buyers as the dominant demand archetype in the Middle East and Africa blister packaging landscape. Amcor plc leverages its regional manufacturing footprint to supply multi-layer cold-form blisters for temperature-sensitive drug formats. Constantia Flexibles anchors its position through specialized aluminum-PVC laminates that meet stringent barrier requirements for the Gulf pharmaceutical sector. ACG Pharmapack Pvt. Ltd. competes on cost-optimized thermoforming lines tailored to emerging African markets with limited capital expenditure budgets.
Technical Definition and Segment Structure
Blister packaging in this region consists of pre-formed plastic cavities sealed to lidding material—typically aluminum foil or paperboard—through heat-sealing or cold-forming processes, with cavity depths ranging from 0.5 to 12 millimeters depending on unit dose or multi-count requirements. Its primary purpose is to protect unit-dose pharmaceuticals, medical devices, and high-value consumer electronics from moisture, oxygen ingress, and tampering across extended supply chains with variable climate conditions. The pharmaceutical product type dominates value generation due to serialization compliance costs and barrier-grade material specifications, while cold-forming technology captures expanding share as biologics and moisture-sensitive generics proliferate. Plastic material—particularly PVC and PET—sustains volume leadership, though aluminum lidding concentrates margin pools given specialized coating requirements and supply constraints.
Regulatory Environment
Saudi Arabia's SFDA and South Africa's SAHPRA enforce escalating traceability standards that mandate unique identifiers on pharmaceutical primary packs, directly shaping converter investment in integrated printing and verification systems. Egypt's drug authority and Nigeria's NAFDAC are adopting serialization roadmaps that align with WHO prequalification standards, creating compliance-driven demand for upgraded blister lines. The EU MDR's extraterritorial influence on Gulf-based medical device exporters further tightens material biocompatibility and sterility documentation requirements. Stakeholders must monitor divergent national implementation timelines for track-and-trace mandates to calibrate capacity additions against regulatory enforcement readiness.
Market Dynamics
Serialization mandates from Saudi Arabia's SFDA and South Africa's SAHPRA are forcing pharmaceutical converters to retool entire production lines, creating a bifurcation between compliance-ready suppliers and legacy operators facing stranded capacity.
Growth Catalysts
- SFDA Track-and-Trace Mandates:Saudi Arabia's pharmaceutical localization programs require serialized primary packaging for domestic drug production, pulling investment into integrated blister lines with printing and verification systems.
- Cold-Forming Technology Migration:Biologics and moisture-sensitive generics are proliferating across Gulf markets, expanding demand for aluminum-PVC laminates with superior barrier properties.
- NAFDAC Prequalification Alignment:Nigeria's drug authority is adopting WHO serialization roadmaps, creating compliance-driven upgrade cycles for blister packaging converters serving West African distribution networks.
Market Restraints
- Aluminum Lidding Supply Concentration:Specialized coating-grade aluminum foil for pharmaceutical applications sources primarily from European and Asian refiners, exposing regional converters to currency volatility and shipping disruptions.
- Integrated Line Capex Intensity:Full serialization compliance requires capital outlays for vision systems, aggregation stations, and software integration that exceed typical African converter balance sheet capacity.
- PVC Substitution Pressure:Environmental scrutiny of chlorinated plastics is accelerating inquiries into PET and PP alternatives, though tooling conversion costs slow material transitions.
Strategic Opportunities
- Egyptian Localization Incentives:The country's drug authority is expanding domestic manufacturing requirements, creating first-mover advantage for blister converters establishing integrated printing and forming capacity near Cairo pharmaceutical clusters.
- Medical Device Export Compliance:Gulf-based device manufacturers serving EU markets must meet MDR biocompatibility documentation standards, opening specialized demand for sterilizable barrier blisters with validated sealing protocols.
- Digital Press Convergence:Combination of UV inkjet printing with cold-forming lines enables lot-specific customization without plate changeover, compressing lead times for short-run generic launches.
Industry Challenges
- Serialization Integration Complexity:Legacy thermoforming equipment requires substantial retrofitting to accommodate camera verification and reject systems, extending downtime during compliance transitions.
- Qualified Technician Scarcity:Operation of integrated blister lines with PLC-controlled sealing parameters and vision system calibration demands skill sets concentrated in South Africa and the UAE, constraining expansion in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Blister Packaging Market |
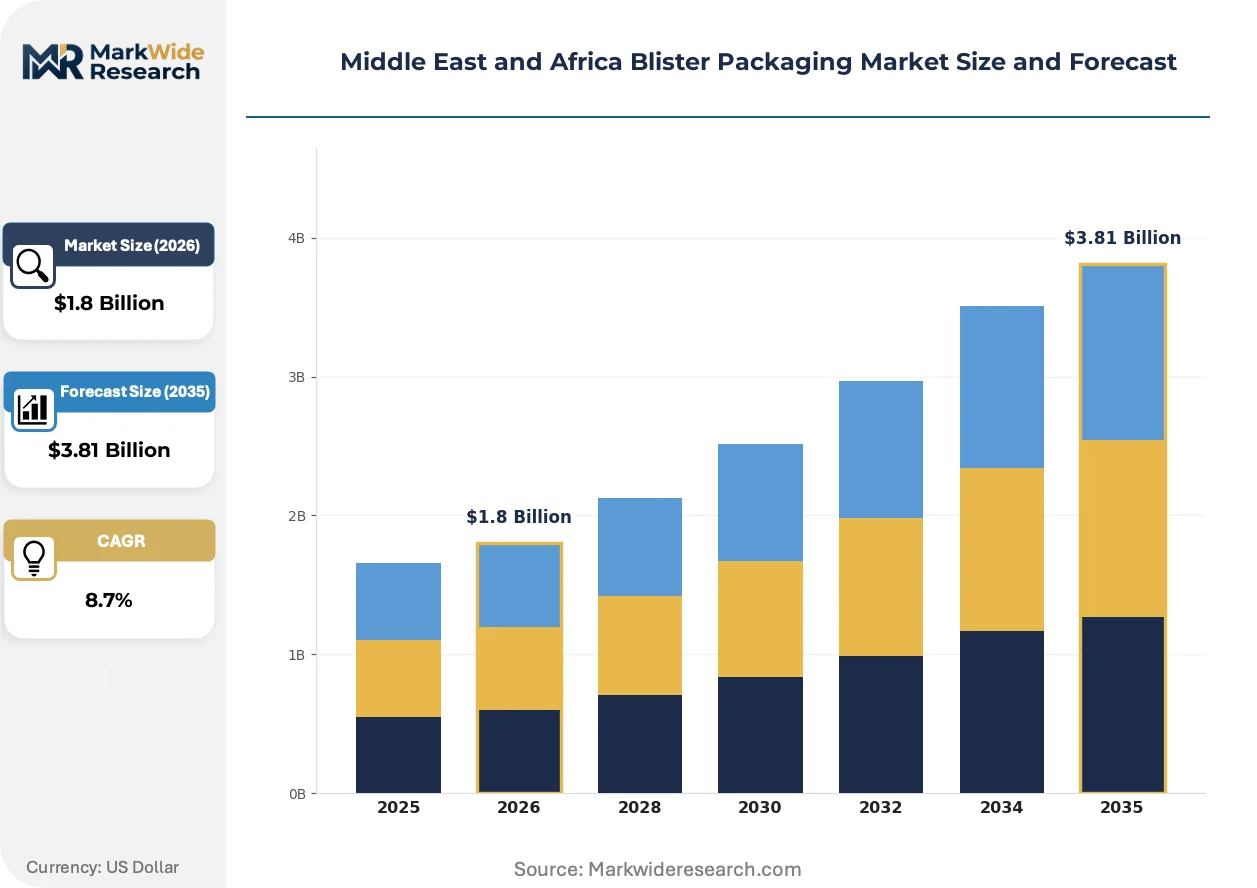
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Electronics, Consumer Goods, Food & Beverages Material: Plastic, Aluminum, PVC, PET Technology: Roll-Fed, Heat-Sealing, Cold-Forming, Vacuum-Forming End User: Healthcare, Retail, Manufacturing, Logistics |
| Companies Covered | Amcor plc, Constantia Flexibles, Sonoco Products Company, Klöckner Pentaplast, ACG Pharmapack Pvt. Ltd., Tekni-Plex, Inc., Uflex Limited, WestRock Company, Winpak Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Blister Packaging Market Shifts & Advancements
Heat-sealing technology architectures are fragmenting as regional converters balance barrier performance against energy costs and line speed requirements in variable climate conditions.
Multi-layer coextruded films with embedded desiccant layers are decomposing traditional separate-pouch moisture protection approaches. Saudi pharmaceutical manufacturers are adopting these integrated formats for humidity-sensitive solid doses. The technology is decomposing margin pools previously captured by secondary packaging suppliers.
EU MDR extraterritorial enforcement is reshaping material documentation requirements for Gulf-based medical device exporters. Sterility validation and biocompatibility testing protocols now accompany every blister shipment to European distributors. High-value device categories—implantable sensors and diagnostic cartridges—face the steepest compliance escalation.
Buyer consolidation among Gulf pharmaceutical distributors is compressing supplier negotiation cycles. Large procurement groups now mandate direct-to-warehouse delivery with vendor-managed inventory terms, displacing traditional converter-to-wholesaler relationships. Saudi Arabia's concentrated hospital and pharmacy chains exhibit the most aggressive procurement centralization.
Middle East and Africa Blister Packaging Market Segmentation
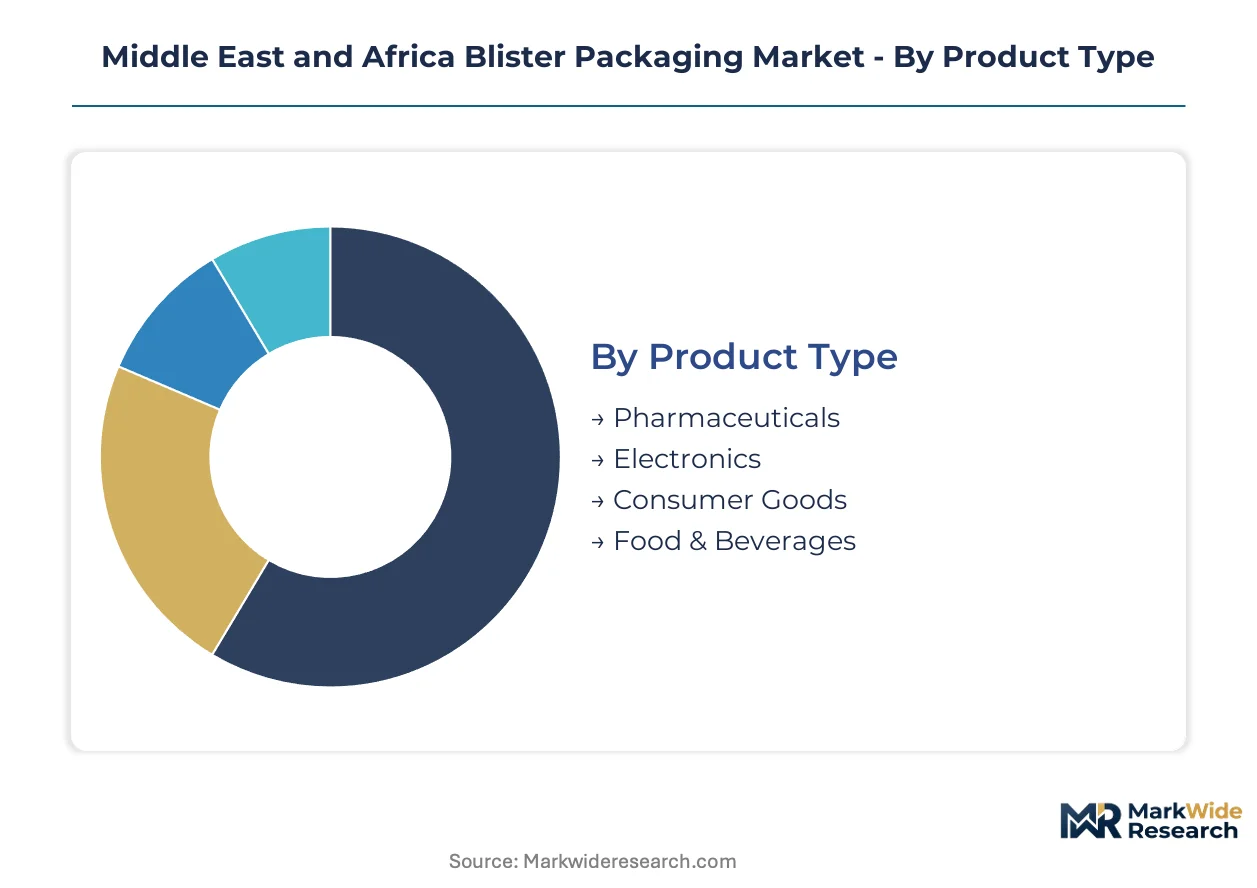
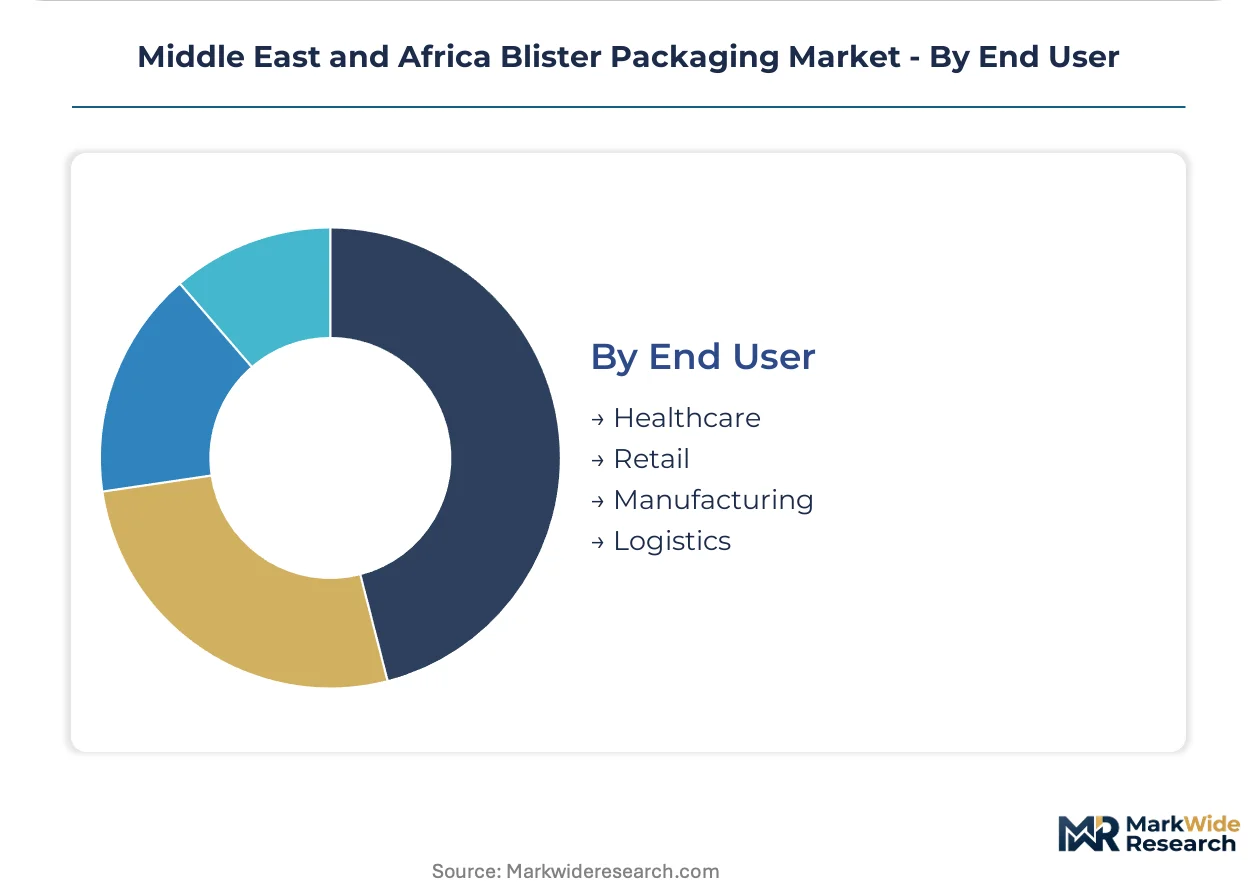
Blister packaging demand across the Middle East and Africa fragments sharply across end-use requirements, with pharmaceutical serialization mandates and consumer goods cost pressures driving divergent specification trajectories. Understanding segment-level substitution threats and technology migration patterns enables converters to prioritize capacity investments against regulatory enforcement timelines and material transition costs.
Product Type:
Substitution pressure from flexible pouch formats and bottle packaging varies dramatically by product category, with moisture-sensitive pharmaceuticals facing the lowest viable alternatives due to barrier requirements.
- Pharmaceuticals:Unit-dose solid doses and biologics demand aluminum-PVC cold-form laminates with embedded desiccant layers. Saudi Arabia's SFDA serialization mandates and South Africa's SAHPRA track-and-trace requirements concentrate investment in integrated printing and verification systems across domestic drug production facilities.
- Electronics:Anti-static PET blisters with conductive coatings protect semiconductors and consumer devices during Gulf-to-Africa distribution. Demand clusters in UAE logistics hubs serving re-export markets, though flexible anti-static pouches capture share for lower-value components.
- Consumer Goods:PVC and PET thermoforms package cosmetics, batteries, and hardware across Nigerian and Egyptian retail channels. Cost pressure from shrink-wrap alternatives limits specification upgrades.
- Food & Beverages:Modified atmosphere blisters for confectionery and portioned dairy face competition from flow-wrap and cup formats. Limited penetration outside South African premium retail.
Pharmaceuticals anchors the volume base while Electronics gains share at the steepest rate.
Material:
Cost tiers stratify sharply between commodity thermoplastics and specialized barrier substrates, with converter margins concentrating in coating-grade aluminum supply chains.
- Plastic:PVC and PET thermoforms dominate high-volume pharmaceutical and consumer applications through roll-fed and vacuum-forming lines. Nigerian and Kenyan converters favor PVC for tooling cost amortization across short production runs.
- Aluminum:Hard-temper foil with heat-seal lacquer coatings forms lidding and cold-form cavities for moisture-sensitive drugs. Supply concentrates in European and Asian refiners, exposing regional converters to currency volatility.
- PVC:Rigid calendered sheet remains the default for thermoforming across North and West African markets. Environmental scrutiny from EU MDR spillover and domestic sustainability pressures accelerates substitution inquiries.
- PET:Amorphous and crystalline grades offer clarity and recyclability advantages for electronics and food visibility applications. Gulf pharmaceutical manufacturers specify PET for secondary barrier layers in multi-laminate structures.
PVC captures the highest shipment volumes while PET expands most quickly amid substitution dynamics.
Technology:
Application requirements and capital intensity fragment technology adoption, with biologics proliferation and serialization integration reshaping equipment procurement priorities.
- Roll-Fed:Continuous thermoforming from reel stock maximizes throughput for high-volume pharmaceutical and consumer goods. Saudi and South African converters deploy roll-fed lines with integrated vision systems for compliance-ready output.
- Heat-Sealing:Rotary and platen-based systems seal thermoformed cavities to aluminum or paperboard lidding. Energy costs and climate variability drive efficiency investments across Egyptian and Moroccan facilities.
- Cold-Forming:Aluminum-PVC laminate stamping creates zero-permeability cavities for moisture-sensitive generics and biologics. SFDA localization programs pull capacity expansion in Riyadh and Jeddah pharmaceutical clusters.
- Vacuum-Forming:Simplified tooling and lower capital barriers suit Nigerian and Ghanaian converters serving fragmented retail distribution. Limited barrier performance constrains pharmaceutical adoption.
Heat-Sealing maintains installed base dominance while Cold-Forming climbs the fastest on biologics demand.
End User:
Customer type determines specification stringency and procurement consolidation, with healthcare sector compliance requirements diverging sharply from retail cost optimization.
- Healthcare:Hospital pharmacies, clinics, and drug manufacturers mandate serialized, barrier-grade blisters with full traceability documentation. SAHPRA and SFDA enforcement timelines calibrate converter readiness investments.
- Retail:Pharmacy chains and consumer electronics distributors prioritize shelf visibility and theft deterrence. Saudi Arabia's consolidated hospital and pharmacy procurement groups compress supplier negotiation cycles.
- Manufacturing:Medical device and electronics producers require validated sterilization protocols and MDR-compliant biocompatibility documentation for EU export shipments.
- Logistics:Third-party distributors and freight forwarders specify protective formats for climate-variable Africa-to-Gulf supply corridors. Limited direct influence on primary packaging design.
Healthcare commands specification leadership while Retail captures the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jeddah Islamic Port anchors pharmaceutical distribution across the Red Sea corridor, with cold-chain infrastructure expansion underwriting blister packaging demand for temperature-sensitive drug formats.
Saudi Arabia
Domestic pharmaceutical manufacturing clusters in Riyadh and Jeddah drive cold-forming capacity expansion. SFDA serialization mandates require integrated printing and verification systems for all locally produced drugs. The King Abdullah Economic City pharmaceutical zone attracts converters establishing compliant blister lines near domestic drug production facilities.
United Arab Emirates
Re-export logistics through Dubai's Jebel Ali Free Zone concentrate demand for anti-static electronics blisters serving African distribution networks. MOHAP pharmaceutical traceability standards align with Gulf Cooperation Council harmonization roadmaps. Sharjah's industrial corridor hosts converters supplying barrier-grade packaging to regional medical device manufacturers.
South Africa
SAHPRA track-and-trace enforcement timelines calibrate converter investment in serialization-ready thermoforming equipment. Biologics manufacturing in Gauteng's pharmaceutical corridor expands aluminum-PVC laminate demand. The Durban port cluster processes imported lidding materials for distribution into Sub-Saharan markets.
Egypt
Government localization incentives for domestic drug production create first-mover positioning for blister converters near Cairo pharmaceutical clusters. The national drug authority adopts WHO prequalification standards for export-oriented manufacturers. Alexandria's industrial zones attract integrated printing and forming capacity to serve North African distribution networks.
Nigeria
NAFDAC serialization roadmaps drive compliance upgrade cycles for converters serving West African markets. Fragmented retail distribution favors vacuum-forming technologies with lower capital barriers. Lagos pharmaceutical importers specify barrier-grade blisters for humidity-sensitive drug formats transiting variable climate corridors.
Middle East and Africa Blister Packaging Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and compliance capability dimensions. The vendor base stratifies between multinational converters with integrated serialization systems and regional operators serving cost-sensitive segments. Three archetypes dominate: barrier-grade specialists, scale-driven thermoformers, and emerging-market cost optimizers. Consolidation pressure intensifies through M&A activity targeting serialization-ready assets, while capacity expansion concentrates in Saudi pharmaceutical clusters.
Within the multinational converter tier, Amcor plc and Constantia Flexibles occupy positions as archetypal barrier-grade specialists with regional manufacturing footprints. ACG Pharmapack Pvt. Ltd. exemplifies the private specialist model serving emerging African markets with capital-efficient equipment configurations. These three anchors represent divergent strategic postures: integrated compliance leadership, European aluminum-PVC laminate specialization, and cost-optimized thermoforming for price-sensitive procurement environments.
| Leading Market Players |
|---|
| Amcor plc |
| Constantia Flexibles |
| Sonoco Products Company |
| Klöckner Pentaplast |
| ACG Pharmapack Pvt. Ltd. |
| Tekni-Plex, Inc. |
| Uflex Limited |
| WestRock Company |
| Winpak Ltd. |
| Others |
Supply & Pricing Matrix
PET substitution for PVC across Egyptian and Nigerian thermoforming lines simultaneously redraws raw material sourcing maps and compresses tooling amortization economics for converters serving price-sensitive consumer goods channels. This material migration concentrates procurement leverage with Gulf-based resin distributors while fragmenting legacy PVC converter margins across West African markets.
Pricing Analysis
Three-tier pricing structure across premium serialization-compliant, standard barrier-grade, and economy thermoform levels dominates contract negotiations between Saudi pharmaceutical manufacturers and regional converters. Price differentiation hinges on SFDA certification status and integrated vision system capability, with premium tiers commanding substantial markups for track-and-trace readiness. Cost compression in economy segments intensifies as Kenyan and Ghanaian converters deploy refurbished European equipment to undercut Egyptian rivals. Hospital procurement groups in Riyadh and Jeddah exhibit lowest price sensitivity due to localization mandates, while Lagos-based generic importers face acute margin pressure from flexible pouch alternatives.
Supply Chain Analysis
Container availability constraints on Asia-to-Jeddah and Europe-to-Durban lanes inflate inbound aluminum foil and specialized lacquer coating costs for regional blister manufacturers. Supply concentrates in Germany, India, and China for coating-grade aluminum, while PVC and PET resin flows from Saudi petrochemical complexes and Asian polymer exporters. Single-source vulnerability pervades heat-seal lacquer formulations, with European specialty chemical producers commanding disproportionate leverage. Distribution runs through Jebel Ali Free Zone consolidators for re-export into Sub-Saharan markets, bypassing direct converter-to-manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA serialization enforcement creates a high-growth disruption as compliance-ready capacity scarcity reshapes competitive boundaries across the Gulf pharmaceutical corridor. This regulatory inflection compresses supplier selection timelines while elevating technical qualification thresholds for regional converters.
For Market Incumbents: Secure backward integration into aluminum lidding coating capabilities to insulate margin pools from European refiner pricing volatility. Anchor serialization-ready capacity expansions in Riyadh pharmaceutical clusters before Egyptian localization incentives mature, defending against emerging African cost optimizers with integrated printing and verification systems that exceed SAHPRA compliance baselines.
For New Entrants and Emerging Players: Anchor in Cairo's pharmaceutical manufacturing corridor ahead of full Egyptian drug authority localization enforcement, exploiting first-mover positioning for integrated cold-forming and printing lines. Target vacuum-forming equipment refurbishment services for Nigerian converters facing NAFDAC upgrade cycles, leveraging technical partnerships with Indian machinery suppliers to compress capital barriers for fragmented West African buyers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European packaging specialists holding underutilized Gulf manufacturing footprints and dormant SFDA compliance certifications. Long-term viability centers on serialization integration depth rather than geographic expansion velocity, with acquisition premiums flowing to converters possessing validated vision system architectures. Monitor Saudi pharmaceutical localization program acceleration as the decisive inflection signal for capacity utilization inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Coating | Captive lacquer formulation supply secures margin pools against European refiner currency volatility. |
| Serialization-Ready Capacity Expansion | Integrated vision system deployment in Riyadh clusters locks in SFDA-mandated pharmaceutical procurement. |
| Digital Press Convergence Investment | UV inkjet-cold-forming line combinations compress generic launch lead times for Saudi manufacturers. |
| Egyptian Localization Joint Venture | Cairo pharmaceutical corridor positioning captures government incentive windows before full enforcement. |
| NAFDAC Compliance Service Bureau | Technical consultancy and equipment retrofitting address Nigerian converter upgrade cycle demand. |
Research Methodology
Desk research of pharmaceutical regulatory filings, customs trade databases, and equipment manufacturer technical specifications preceded structured interviews with blister line operations managers, pharmaceutical packaging procurement directors, and SFDA compliance officers across the analysis window. Primary fieldwork with Saudi and South African converters validated secondary estimates of cold-forming capacity utilization and serialization investment timelines. Bottom-up shipment data from resin distributors and lidding material importers triangulated against top-down pharmaceutical production forecasts from national drug authority statistics.
Variance decomposition across product type, material grade, technology architecture, and end-user procurement channel shaped the analytical framework over the projection horizon. Modeled dimensions encompassed pharmaceutical versus consumer goods demand split, aluminum-PVC laminate versus commodity thermoplastic specification tiers, and healthcare versus retail customer concentration patterns. CAGRs derived from regression analysis of historical capacity additions against regulatory enforcement phase-in schedules, with biologics proliferation rates and serialization compliance cost curves as industry-specific forecast inputs.
Material uncertainties — regulatory enforcement delays, aluminum supply disruptions, and PET substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding SFDA and SAHPRA implementation adherence without contingency for policy reversal. Recalibration cycles align with material shifts in serialization mandate timelines and biologics manufacturing capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Ampoules and Blister Packaging Market
Blister Packaging
Carded Blister Packaging Market
Blister Packaging
North America Pharmaceutical Blister Packaging Market
Blister Packaging
PVC Blister Packs Market
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
PVC Blister Packaging Market
Blister Packaging
Blister Packaging Equipment Market
Blister Packaging
Healthcare Blister Packaging Market
Blister Packaging
United States Blister Packaging Market
Blister Packaging
Asia Pacific Pharmaceutical Blister Packaging Market
Blister Packaging
Alu Alu Blister Packaging Machine Market
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market
Blister Packaging
Asia Pacific Blister Packaging Market
Blister Packaging
Latin America Pharmaceutical Blister Packaging Market
Blister Packaging
Holographic Blister Foil Market