
 Carded Blister Packaging Market | 2026-2036
Carded Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Carded Blister Packaging Market Outlook
Market Context
Skilled thermoforming technician availability is collapsing across Eastern European converting hubs, forcing automation investments that favor capital-rich suppliers. Amcor Plc leverages integrated film extrusion and printing assets to secure pharmaceutical qualification timelines. WestRock Company anchors North American demand through captive paperboard supply and retail-ready design services. Sonoco Products Company competes via specialized cold-seal adhesive technologies for temperature-sensitive product lines.
Technical Definition and Segment Structure
Carded blister packaging thermoforms a clear plastic cavity—typically 0.25–0.50 mm PVC or PET—onto a printed paperboard backing card, creating a visible, tamper-evident unit that protects and displays individual products. The format serves retail theft deterrence, pharmaceutical child-resistance compliance, and electronics electrostatic shielding in one integrated structure. Pharmaceutical applications dominate value pools due to serialization mandates and barrier-grade specifications, while electronics demand in PET variants accelerates fastest as OEMs replace clamshells with slimmer carded formats. Cardboard-backed configurations retain margin strength in cosmetics and premium retail segments where print quality and shelf differentiation command price premiums.
Regulatory Frame and Outlook
FDA 21 CFR Part 211 and EU MDR shape pharmaceutical blister validation requirements, while REACH and RoHS restrict plasticizer and additive chemistries across European and US supply chains. The EU Green Deal's packaging waste directives are forcing substrate transitions that favor recyclable PET and fiber-based barrier coatings over legacy PVC. Stakeholders must monitor evolving ECHA substance restrictions and state-level extended producer responsibility laws to anticipate material cost shifts and qualification burdens.
Market Dynamics
EU Green Deal packaging waste directives and F-Gas Regulation are forcing substrate transitions from legacy PVC toward recyclable PET and fiber-based barrier coatings, restructuring converter capital allocation and supplier qualification timelines across pharmaceutical and retail supply chains.
Growth Catalysts
- EU MDR serialization mandates:Pharmaceutical manufacturers are scaling carded blister formats for unit-dose compliance packaging to satisfy track-and-trace requirements across European distribution networks.
- Electronics OEM format migration:Device manufacturers in Germany and Japan are replacing bulky clamshells with slimmer PET carded variants to reduce shipping cube and retail shelf footprint.
- Skilled thermoforming technician scarcity:Labor availability is collapsing across Eastern European converting hubs, accelerating automation investments that favor capital-rich suppliers with integrated extrusion assets.
Market Restraints
- Substrate cost volatility:Virgin PET and specialty barrier films face price pressure from energy-intensive polymer production tied to European natural gas benchmarks.
- REACH additive restrictions:ECHA substance evaluations are narrowing the plasticizer and stabilizer chemistries available for pharmaceutical-grade PVC formulations.
- Paperboard supply concentration:North American linerboard capacity is tightening around a handful of integrated pulp-and-paper operators, squeezing converter margin on cardboard-backed configurations.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO-aligned contract manufacturers are qualifying high-barrier carded formats for regulated markets, creating demand for EU-MDR-certified substrate supply.
- Cold-chain biologics expansion:Temperature-sensitive cell therapies are driving specification of specialized cold-seal adhesive technologies that maintain seal integrity across cryogenic-to-ambient transitions.
- Extended producer responsibility tailwinds:Germany's Verpackungsgesetz and France's AGEC law are mandating recyclable mono-material structures that favor PET-lidding-to-PET-cavity designs over multi-material laminates.
Industry Challenges
- Pharmaceutical qualification timelines:FDA 21 CFR Part 211 validation protocols require 18-24 month stability testing for new substrate combinations, compressing product development windows.
- Thermoforming automation integration:Legacy forming lines lack the vision systems and robotic handling modules necessary for high-speed pharmaceutical serialization without substantial retrofit capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carded Blister Packaging Market |
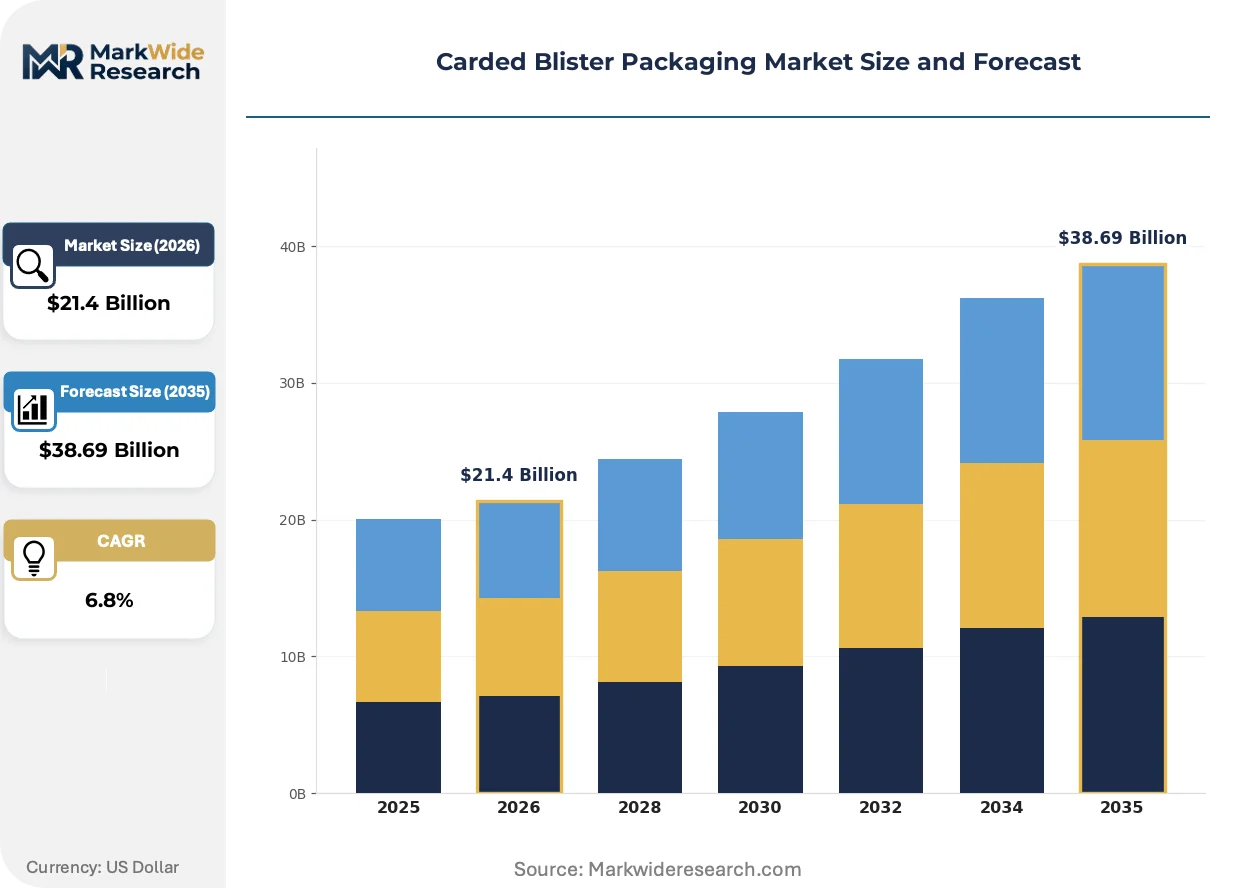
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $38.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Consumer Goods, Electronics, Food Material: PVC, PET, Aluminum, Cardboard Application: Medical Devices, Food Packaging, Cosmetic Packaging, Retail Products Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Amcor Plc, WestRock Company, Sonoco Products Company, Bemis Company, Inc., Constantia Flexibles, Winpak Ltd., UFlex Limited, Klöckner Pentaplast Group, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carded Blister Packaging Market Strategic Shifts
Active substrate substitution and regulatory-driven material science are compressing the technology lifecycle for barrier films, while buyer consolidation in retail and pharmaceutical distribution is reshaping procurement specifications.
Recyclable PET mono-material structures with plasma-deposited silicon oxide barrier coatings are displacing legacy PVC-PVDC laminates in medium-barrier pharmaceutical applications. German medical device exporters and retail chains are jointly specifying these specifications to preempt EPR compliance costs. The shift is compressing demand for conventional multi-layer films and forcing coating equipment investments at mid-tier converters.
REACH Annex XVII restrictions on phthalate plasticizers are tightening the formulation window for flexible PVC films used in child-resistant pharmaceutical blisters. ECHA evaluations are disqualifying legacy plasticizer chemistries faster than alternative bio-based stabilizers can achieve pharmaceutical-grade extraction and migration testing. Pediatric and geriatric dosage formats in France and Benelux markets are experiencing the most acute formulation recertification burdens.
Retail pharmacy chains are consolidating carded blister specifications around pre-qualified supplier lists that bundle design, print, and barrier testing services. This procurement concentration is displacing fragmented spot-buying relationships with local converters in Germany and the United Kingdom. The model is most visible in supermarket pharmacy operations where private-label OTC portfolios require synchronized packaging artwork and serialization data management.
Carded Blister Packaging Market Segmentation
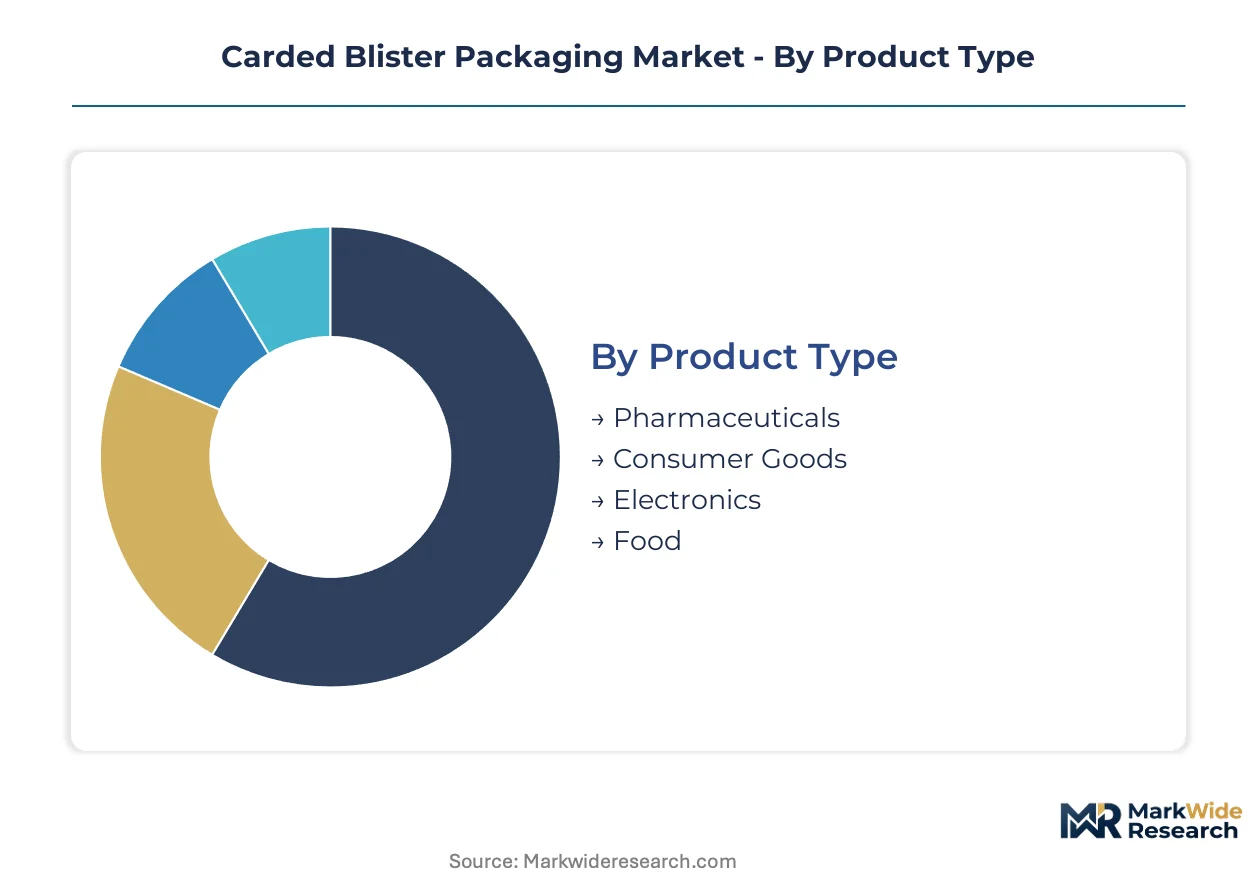
Carded blister packaging serves divergent performance requirements across pharmaceutical serialization, retail theft deterrence, and temperature-sensitive logistics. Segmentation reveals how substrate specifications and channel access determine margin capture for converters with integrated barrier film capabilities.
Product Type:
Margin pools concentrate in pharmaceutical applications where EU MDR serialization mandates and FDA 21 CFR Part 211 validation create qualification barriers that filter out commodity converters.
- Pharmaceuticals:Unit-dose compliance packaging demands high-barrier PVC-PVDC or silicon oxide-coated PET films with integrated track-and-trace serialization. German medical device exporters and retail pharmacy chains are jointly specifying these formats to preempt EPR compliance costs under the Verpackungsgesetz.
- Electronics:PET carded variants with electrostatic discharge protection are displacing bulky clamshells among OEMs in Germany and Japan seeking reduced shipping cube and retail shelf footprint. Slimmer formats accelerate fastest as sustainability specifications tighten.
- Consumer Goods:Cardboard-backed configurations with premium print quality serve cosmetics and personal care segments where shelf differentiation commands price premiums.
- Food:Modified atmosphere barrier specifications for fresh and convenience applications face slower adoption due to cost sensitivity and competing flexible formats.
Pharmaceuticals holds installed capacity. Electronics is rotating up the share rankings.
Material:
Substrate selection determines capital intensity and regulatory exposure, with recyclability mandates compressing demand for legacy multi-material laminates.
- PET:Recyclable mono-material structures with plasma-deposited silicon oxide barrier coatings are displacing PVC-PVDC laminates in medium-barrier pharmaceutical applications. EPR laws in Germany and France mandate mono-material designs that favor PET-lidding-to-PET-cavity configurations.
- Cardboard:Printed paperboard backing cards with fiber-based barrier coatings anchor retail-ready and premium cosmetic segments. North American linerboard capacity tightens around integrated pulp-and-paper operators, squeezing converter margins.
- PVC:Legacy pharmaceutical-grade formulations face REACH Annex XVII phthalate restrictions that disqualify plasticizer chemistries faster than bio-based alternatives achieve migration testing compliance.
- Aluminum:Cold-form foil laminates serve highest-barrier pharmaceutical applications where moisture and oxygen ingress specifications are most stringent.
PVC retains legacy pharmaceutical qualification. PET is climbing the fastest as converters retool for EPR compliance.
Application:
End-use specifications fragment by barrier performance tier and child-resistance requirements, with medical device and pharmaceutical convergence creating hybrid qualification demands.
- Medical Devices:Sterile barrier systems with Tyvek or fiber-based lidstock serve surgical instrument and diagnostic kit packaging. German exporters specify these formats for regulated markets requiring CE marking under EU MDR.
- Retail Products:Theft-deterrent clamshell replacements and visible product display formats concentrate in mass merchant and electronics specialty channels.
- Cosmetic Packaging:Premium print quality and tactile finishing on cardboard-backed configurations support brand differentiation in department store and duty-free retail.
- Food Packaging:Modified atmosphere and moisture barrier specifications for fresh produce and convenience foods face competition from flow-wrap and tray-seal alternatives.
Medical Devices holds installed capacity. Retail Products is rotating up the share rankings.
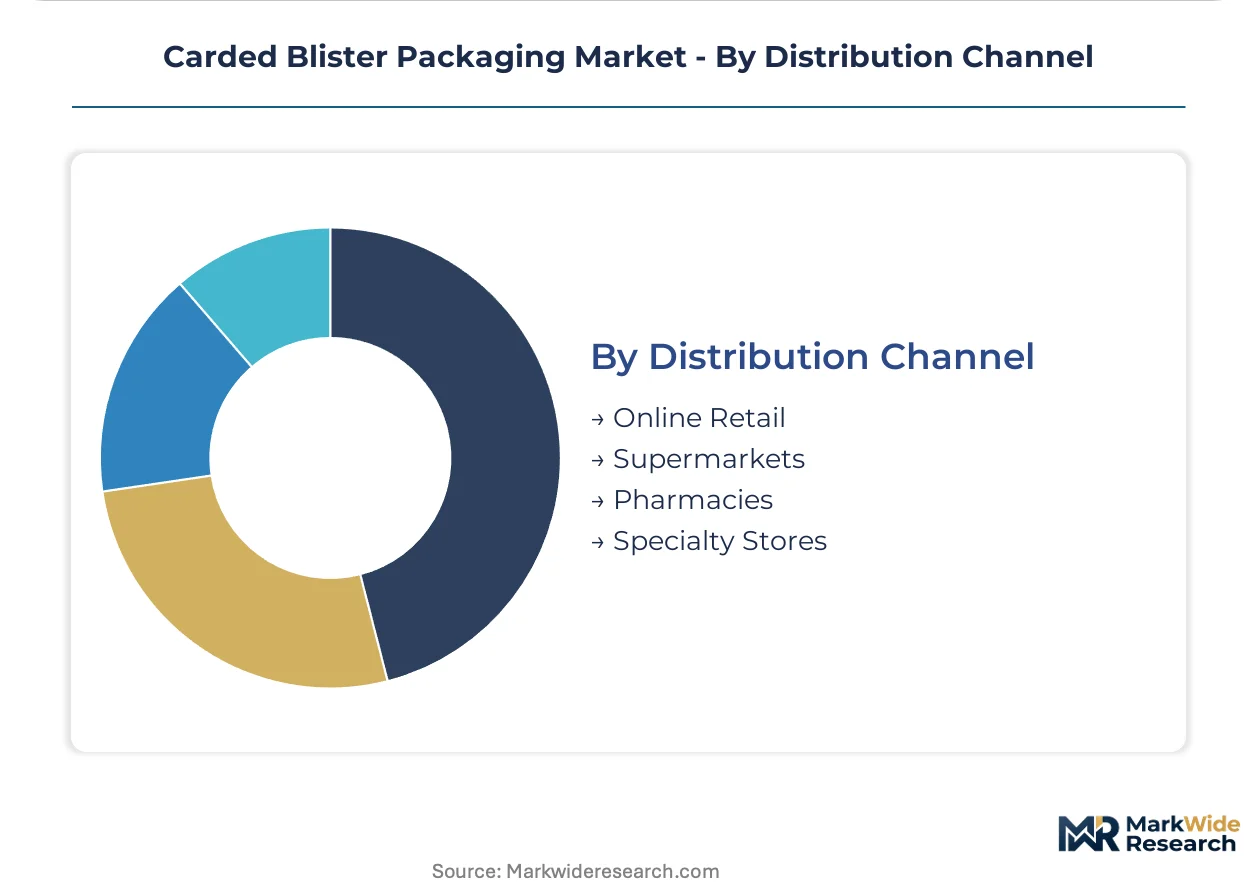
Distribution Channel:
Channel consolidation is reshaping procurement specifications around bundled design, print, and serialization services that favor integrated suppliers.
- Pharmacies:Retail pharmacy chains in Germany and the United Kingdom are consolidating specifications around pre-qualified supplier lists that bundle artwork and serialization data management for private-label OTC portfolios.
- Supermarkets:Mass merchant private-label programs demand synchronized packaging artwork across high-volume SKUs with rapid turnaround requirements.
- Specialty Stores:Electronics and cosmetics boutiques specify premium finishes and smaller production runs that favor agile converters with digital print capabilities.
- Online Retail:E-commerce fulfillment requirements for damage resistance and returns-friendly opening features are emerging specifications for direct-to-consumer electronics and cosmetics brands.
Pharmacies holds installed capacity. Online Retail is expanding most quickly as DTC brand packaging requirements mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH Annex XVII restrictions on phthalate plasticizers are forcing substrate transitions across European converting hubs, while FDA 21 CFR Part 211 validation protocols govern pharmaceutical qualification timelines in North America. German medical device exporters and retail chains are jointly specifying high-barrier carded blister specifications to preempt EPR compliance costs.
Germany
Medical device exporters in Baden-Württemberg and Bavaria are scaling PET mono-material structures with silicon oxide barrier coatings. The Verpackungsgesetz mandates recyclable packaging designs that favor PET-lidding-to-PET-cavity configurations over legacy PVC laminates. Stuttgart and Munich clusters host integrated converters serving pharmaceutical and electronics OEMs with synchronized design and serialization services.
United States
FDA serialization mandates for unit-dose pharmaceuticals are accelerating qualification of high-barrier carded formats across New Jersey and North Carolina manufacturing corridors. EPA and state-level extended producer responsibility laws in California and New York are pressuring substrate transitions toward recyclable PET. The Research Triangle and Philadelphia suburbs concentrate cold-seal adhesive specialists serving temperature-sensitive biologics logistics.
India
CDSCO-aligned contract manufacturers in Maharashtra and Gujarat are qualifying high-barrier carded formats for regulated export markets. The PLI scheme for pharmaceuticals incentivizes packaging localization to serve EU and US distribution networks. Mumbai-Pune and Ahmedabad-Vadodara corridors host converters integrating barrier film extrusion with pharmaceutical-grade printing and track-and-trace serialization.
Japan
METI sustainability guidelines and PMDA pharmaceutical packaging standards are converging to favor slimmer PET carded variants in electronics and medical device applications. Osaka-Kobe and Nagoya industrial zones concentrate thermoforming operations serving automotive electronics OEMs replacing clamshell formats. Tokyo-based retail chains are specifying mono-material structures to align with 2030 plastic circulation targets.
China
NMPA pharmaceutical packaging regulations and MIIT green manufacturing standards are tightening substrate specifications for domestic and export markets. The Yangtze River Delta and Pearl River Delta host integrated converters with captive film extrusion serving global electronics and pharmaceutical brands. Shenzhen and Shanghai clusters are investing in plasma-deposited barrier coating equipment to displace imported multi-layer laminates.
Carded Blister Packaging Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in carded blister packaging, with capital-rich suppliers capturing pharmaceutical qualification timelines through captive film extrusion and serialization capabilities. Mid-tier converters face automation investment burdens as skilled thermoforming technician availability contracts across Eastern European hubs. Two strategic archetypes dominate: integrated film-to-package suppliers with barrier coating capabilities, and design-service converters bundling print, artwork, and track-and-trace data management. Competitive moves concentrate on substrate qualification partnerships with pharmaceutical OEMs and cold-seal technology licensing for temperature-sensitive applications.
Among integrated packaging conglomerates, Amcor Plc and WestRock Company exemplify the capital-intensive archetype with upstream control over film extrusion and paperboard supply. Sonoco Products Company occupies a position within the specialized adhesive tier, representing converters competing through cold-seal technologies for cryogenic-to-ambient logistics. These three anchors illustrate how supplier consolidation around pre-qualified lists is displacing fragmented spot-buying relationships in German and British retail pharmacy procurement.
| Leading Market Players |
|---|
| Amcor Plc |
| WestRock Company |
| Sonoco Products Company |
| Bemis Company, Inc. |
| Constantia Flexibles |
| Winpak Ltd. |
| UFlex Limited |
| Klöckner Pentaplast Group |
| Sealed Air Corporation |
| Others |
Value Chain & Pricing Dynamics
Silicon oxide-coated PET displacing legacy PVC-PVDC laminates simultaneously relocates barrier film production toward German and Chinese coating equipment hubs while compressing converter margins through capital-intensive retooling requirements and extended pharmaceutical qualification timelines.
Pricing Analysis
European PET mono-material structures command 15-25% premiums over North American equivalents due to energy-intensive polymer production tethered to regional natural gas benchmarks. Pricing stratifies across pharmaceutical-grade barrier certifications, retail-ready print quality tiers, and commodity spot-buying for non-regulated applications. Cost compression in standard-grade PVC configurations intensifies because REACH Annex XVII disqualifies legacy plasticizer chemistries faster than bio-based alternatives achieve migration testing compliance. Mass merchant private-label buyers exhibit highest price sensitivity, while cold-chain biologics specialists accept premium positioning for validated cold-seal adhesive technologies.
Supply Chain Analysis
Germany and China anchor plasma-deposited barrier coating equipment manufacturing, with Stuttgart and Shenzhen clusters feeding converter retooling demand across European and Asia-Pacific pharmaceutical networks. Virgin PET resin, specialty adhesive formulations, and pharmaceutical-grade paperboard lidstock constitute critical input dependencies. Single-source vulnerability concentrates in European linerboard supply following pulp-and-paper operator consolidation. Distribution runs through pre-qualified supplier lists bundling design, print, and serialization services that retail pharmacy chains in Germany and the United Kingdom have consolidated around integrated packaging conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled thermoforming technician availability is collapsing across Eastern European converting hubs, creating a durable capability gap that favors capital-rich suppliers with integrated extrusion assets and automated forming lines over fragmented local competitors.
For Market Incumbents: Secure pharmaceutical qualification timelines through captive film extrusion investments in Germany and India, insulating against CDSCO-aligned contract manufacturers qualifying high-barrier formats for regulated export markets. Deepen upstream control over silicon oxide barrier coating equipment to preempt mid-tier converter automation investments. Anchor North American demand through retail-ready design services bundling artwork and serialization data management for consolidated pharmacy procurement lists. For New Entrants and Emerging Players: Differentiate on specialized cold-seal adhesive technologies serving temperature-sensitive cell therapies across cryogenic-to-ambient logistics transitions. Target Indian pharmaceutical export packaging as the most penetrable geography, where PLI scheme incentives localize packaging supply for EU and US distribution networks. Pursue licensing partnerships with established barrier film specialists to bypass 18-24 month FDA validation protocols. For Investors and Strategic Acquirers: The market sits at a substrate-transition phase that favors integrated film-to-package suppliers with barrier coating capabilities over design-service converters lacking extrusion assets. Long-term viability hinges on qualification partnerships with pharmaceutical OEMs and EPR compliance positioning under Germany's Verpackungsgesetz and France's AGEC law. Monitor ECHA substance evaluation timelines as inflection indicators for plasticizer chemistry obsolescence and replacement cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Equipment Investment | Plasma-deposited silicon oxide capabilities displace imported multi-layer laminates in German medical device supply chains. |
| Pharmaceutical Qualification Partnership | FDA 21 CFR Part 211 validation protocols compress development windows for substrate combinations with proven stability data. |
| Cold-Seal Technology Licensing | Temperature-sensitive biologics logistics demand specialized adhesives maintaining seal integrity across cryogenic transitions. |
| Automation Retrofit Program | Vision systems and robotic handling modules address skilled thermoforming technician scarcity in Eastern European hubs. |
| Mono-Material Structure Certification | EPR compliance under EU Green Deal packaging waste directives favors recyclable PET-lidding-to-PET-cavity designs. |
Study Parameters
The analysis maps pharmaceutical-grade barrier films, retail-ready cardboard-backed configurations, electronics PET variants, and cold-seal adhesive technologies, each validated through thermoforming operations managers, pharmaceutical packaging engineers, retail pharmacy procurement directors, and barrier film R&D specialists. Primary interview data triangulates against secondary sources including FDA 21 CFR Part 211 guidance documents, ECHA REACH Annex XVII substance evaluations, EU MDR technical documentation requirements, and customs trade flows for polymer resin and paperboard inputs. Bottom-up capacity assessments at converter facilities cross-reference top-down demand modeling from end-use sector consumption patterns.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon, with segmentation modeling disaggregating by product type, material substrate, end-use application, and distribution channel. CAGRs derive from regression analysis of historical capacity utilization, substrate substitution elasticities, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporate pharmaceutical serialization mandate implementation schedules and EPR law phase-in timelines affecting substrate specifications.
Material uncertainties — ECHA plasticizer restriction accelerations, natural gas price volatility affecting polymer production economics, and paperboard supply disruptions from pulp-and-paper operator consolidation — sit outside the modeled envelope. Forecasts reflect assumptions regarding qualification timeline durations and automation adoption rates at mid-tier converters. Recalibration cycles align with material shifts in regulatory substance evaluations and extended producer responsibility law enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
Pharma Blisters Packaging Market
Blister Packaging
Blister Foil Market
Blister Packaging
Welded Blisters Market
Blister Packaging
Alu Alu Blister Packaging Machine Market
Blister Packaging
Liquid Blister Pack Market
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market
Blister Packaging
Global Blister Packaging Market
Blister Packaging
Latin America Pharmaceutical Blister Packaging Market
Blister Packaging
PVC Blister Packaging Market
Blister Packaging
North America Blister Packaging Market
Blister Packaging
Asia Pacific Blister Packaging Market
Blister Packaging
Europe Blister Packaging Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
Blister Packs Market
Blister Packaging
Blister Cards Market