
 Pharma Blisters Packaging Market | 2026-2036
Pharma Blisters Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma Blisters Packaging Market Outlook
Modular dose-unit packaging is restructuring how pharmaceutical buyers evaluate total cost of ownership against compliance risk. Amcor Plc leverages its multi-continental film extrusion network to anchor supply security for thermoformed blister programs. Sonoco Products Company specializes in integrated primary and secondary packaging lines that reduce handoff complexity for contract packaging organizations. Constantia Flexibles competes through aluminum-barrier expertise that addresses moisture-sensitive biologics and generics alike.
Pharma blisters packaging denotes thermoformed or cold-formed cavity-and-lidding assemblies that create individual dose-unit enclosures, typically using PVC, PVDC, aluminum, or composite substrates sealed by heat or adhesive bonding to protect drug stability from oxygen ingress and moisture vapor transmission. The primary commercial purpose centers on ensuring patient adherence, product authentication, and shelf-life extension for oral solid dosage forms across retail pharmacy and hospital channels. Cold formed blisters occupy the premium margin tier due to their near-zero moisture vapor transmission rates demanded by hygroscopic formulations, while thermoformed blisters sustain volume leadership through cost efficiency in high-run generic production. Push-through blisters dominate retail pharmacy dispensing workflows, though multi-dose customized packs are gaining traction among pharmaceutical companies managing combination therapies.
The FDA enforces child-resistant and senior-friendly packaging standards under Poison Prevention Packaging Act guidelines that directly shape blister lidding design and peel-push configuration requirements. EMA and national EU regulators apply MDR traceability mandates and REACH substance restrictions that accelerate substitution of chlorinated films with aluminum and composite alternatives. Stakeholders must monitor evolving serialization integration timelines and material compliance deadlines to align capital allocation between thermoforming and cold-forming asset bases.
Market Dynamics
The EU F-Gas Regulation and REACH substance restrictions are forcing material substitutions across the value chain, compressing PVC demand while elevating aluminum-barrier and high-barrier composite films as the default specification for moisture-sensitive oral solid dosage forms.
Growth Catalysts
- Cold-formed blister technology:Hygroscopic formulations and biologics requiring near-zero moisture vapor transmission rates are pulling investment toward cold-forming assets. Oral solid dosage manufacturers in Germany and Switzerland are expanding capacity to serve European distribution.
- Poison Prevention Packaging Act compliance:FDA-mandated child-resistant and senior-friendly standards are redesigning lidding configurations and peel-push mechanisms. Contract packaging organizations are retrofitting lines to meet these dispensing workflow requirements.
- Contract packaging concentration:Procurement gravity centers on Germany-based contract packaging organizations serving as primary channels for European pharmaceutical distribution. These intermediaries aggregate volume and standardize specifications across generic and branded portfolios.
Market Restraints
- Aluminum supply concentration:Cold-formed blister production depends on rolled aluminum supply with limited qualified suppliers in Europe. Input cost volatility and lead time extension constrain margin flexibility for mid-tier packaging converters.
- REACH substance restriction timelines:Accelerated phase-out schedules for chlorinated films are stranding thermoforming assets before replacement materials achieve cost parity. ECHA compliance deadlines compress capital recovery windows for incumbent equipment.
- Technical limitation of thermoformed barriers:PVC and PVDC substrates cannot achieve moisture vapor transmission rates below cold-formed thresholds. This performance ceiling excludes thermoformed options from hygroscopic formulation contracts regardless of price competitiveness.
Strategic Opportunities
- Underpenetrated biologics packaging:Moisture-sensitive biologics and biosimilars represent an emerging application segment with limited established cold-forming capacity. Switzerland and Germany host development pipelines requiring specialized barrier expertise.
- Serialization integration services:EU MDR traceability mandates are creating white space for packaging vendors offering integrated serialization and aggregation solutions. Contract packaging organizations are outsourcing compliance infrastructure rather than building in-house.
- High-barrier composite film convergence:Co-extruded multilayer films combining polyethylene and aluminum are displacing monolayer alternatives. Material science advances are enabling thermoforming-equivalent processing with cold-formed performance characteristics.
Industry Challenges
- Cold-forming equipment capex intensity:Precision stamping presses and deep-draw tooling require capital allocation that strains mid-cap converters. Asset specificity limits redeployment flexibility if demand shifts back toward thermoformed alternatives.
- Multi-site serialization integration:EU MDR traceability mandates require line-level hardware and software coordination across distributed contract packaging networks. Legacy MES systems in German packaging facilities create integration friction with aggregation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma Blisters Packaging Market |
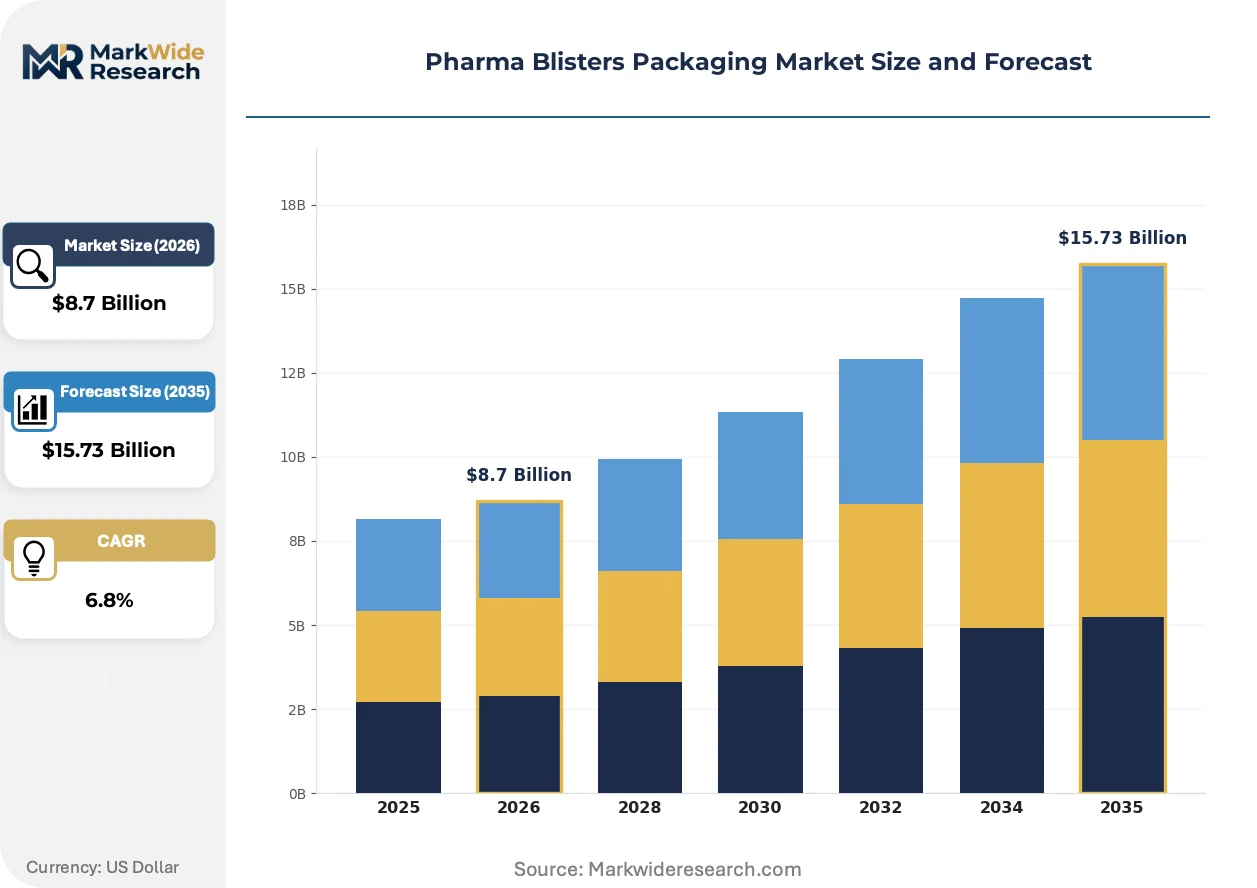
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PVC, PVDC, Aluminum, Composite End User: Pharmaceutical Companies, Contract Packaging Organizations, Hospitals, Retail Pharmacies Product Type: Cold Formed Blisters, Thermoformed Blisters, Push-Through Blisters, Blister Cards Packaging Type: Single Dose, Multi-Dose, Customized Packs, Standard Packs |
| Companies Covered | Sonoco Products Company, Winpak Ltd, Amcor Plc, Bilcare Limited, Bemis Company, Inc., Klöckner Pentaplast, WestRock Company, ACG Pharmapack, Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma Blisters Packaging Market Strategic Shifts
Material science advances and regulatory compliance automation are restructuring competitive positioning across the European pharmaceutical packaging value chain. Technology vendors and converters are racing to align specification capabilities with evolving barrier requirements.
High-barrier co-extruded composite films are achieving moisture vapor transmission rates approaching cold-formed aluminum specifications while retaining thermoforming process compatibility. Generic manufacturers in Germany and the Netherlands are qualifying these substrates for medium-sensitivity formulations. This convergence is modularizing the traditional premium-economy segmentation between cold-formed and thermoformed alternatives.
EMA and national EU regulators are enforcing MDR traceability mandates that require unit-level serialization and aggregation through distribution. Packaging lines must integrate vision systems, track-and-trace software, and verification hardware. Contract packaging organizations serving German pharmaceutical distribution are consolidating supplier relationships to reduce qualification burden across multi-site networks.
Pharmaceutical procurement teams are consolidating vendor panels and demanding outcome-based packaging performance guarantees rather than material specifications alone. Contract packaging organizations are absorbing inventory risk and compliance liability from originators. This transfer is most visible in Germany, where packaging service contracts now incorporate shelf-life extension penalties and recall cost allocation clauses.
Pharma Blisters Packaging Market Segmentation
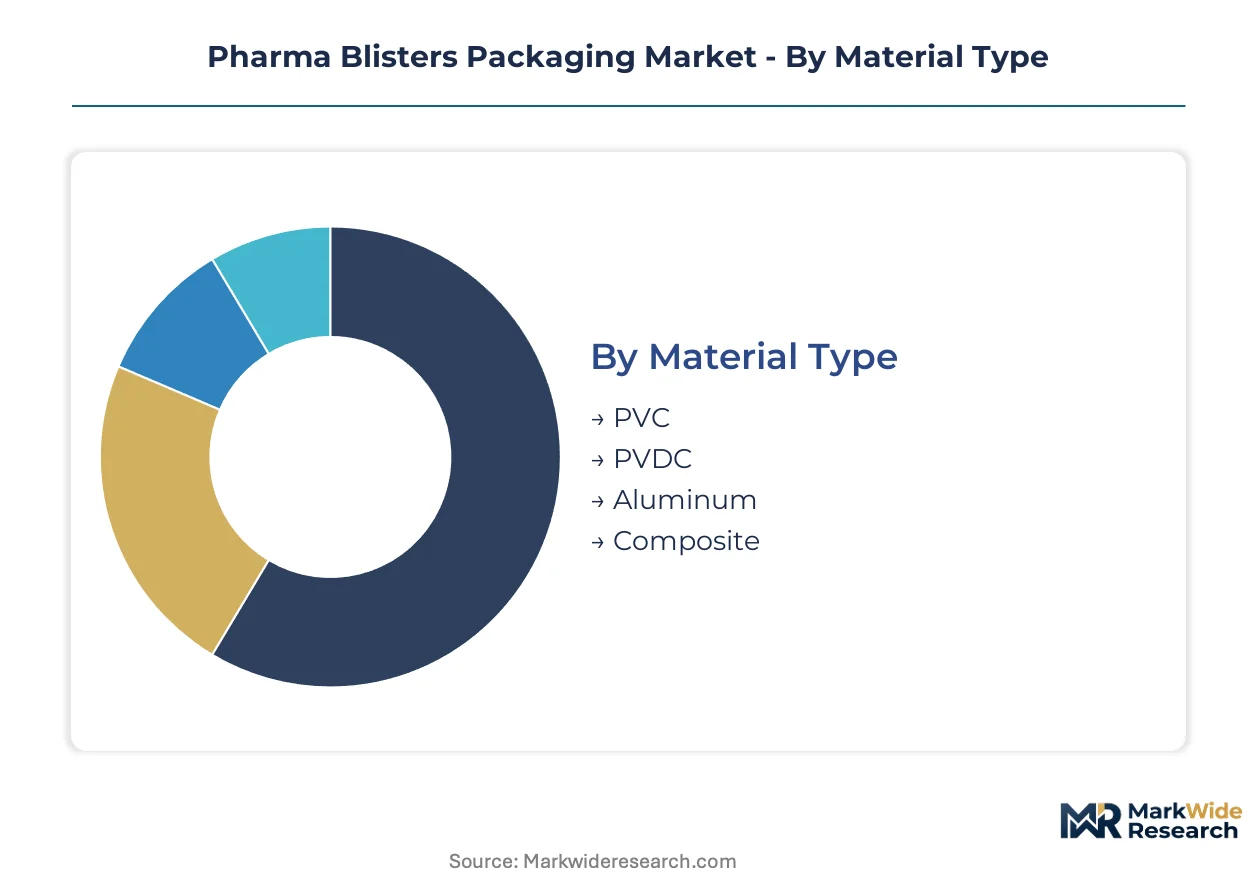
Pharma blisters packaging segmentation reflects divergent capital requirements across material conversion, forming technology, and dispensing configuration. Each dimension carries distinct equipment intensity and regulatory compliance burdens that reshape vendor economics and buyer procurement patterns.
Material Type:
Capital intensity peaks with aluminum-barrier substrates requiring precision rolling and annealing equipment, while thermoplastic extrusion lines represent lower entry thresholds for mid-tier converters.
- Aluminum:Cold-forming grade aluminum demands specialized rolling mills and surface treatment lines to achieve moisture vapor transmission rates below 0.01 g/m²/day. German pharmaceutical manufacturers specify this substrate for hygroscopic generics and moisture-sensitive biologics, though qualified European suppliers remain concentrated among three major rolling mills.
- Composite:Co-extruded multilayer films combining polyethylene, aluminum foil, and adhesive tie layers bridge thermoforming process compatibility with cold-formed barrier performance. Dutch and German generic manufacturers are qualifying these substrates for medium-sensitivity oral solid dosage forms as REACH substance restrictions accelerate PVC displacement.
- PVC:Conventional chlorinated film faces phasedown pressure under EU F-Gas Regulation and REACH frameworks, stranding thermoforming assets before replacement materials achieve cost parity.
- PVDC:High-barrier homopolymer and copolymer grades offer intermediate moisture protection but cannot match cold-formed aluminum specifications for the most sensitive formulations.
Most installed capacity flows through PVC and PVDC thermoforming lines. Expansion is steepest in aluminum and composite high-barrier substrates.
End User:
Procurement concentration varies sharply by customer type, with contract packaging organizations aggregating volume and standardizing specifications across fragmented originator portfolios.
- Contract Packaging Organizations:Germany-based CPOs serve as the primary procurement channel for European pharmaceutical distribution, absorbing inventory risk and compliance liability from originators. These intermediaries demand integrated serialization and aggregation solutions to meet EU MDR traceability mandates across multi-site networks.
- Pharmaceutical Companies:Large originators with captive packaging operations in Switzerland and Germany maintain direct specifications for cold-formed blisters serving moisture-sensitive biologics pipelines, though outsourcing trends are eroding this segment.
- Retail Pharmacies:Dispensing workflows favor push-through blister configurations with child-resistant lidding, driving standardized pack sizes for high-volume generic substitution.
- Hospitals:Unit-dose packaging requirements for medication administration safety create demand for single-dose blisters with barcode verification compatibility.
Contract packaging organizations command the largest share of specification authority. Pharmaceutical companies with captive operations are gaining share fastest in biologics packaging.
Product Type:
Forming technology defines the premium-economy segmentation, with cold-forming assets requiring precision stamping presses that strain mid-cap converter balance sheets.
- Cold Formed Blisters:Deep-draw aluminum forming achieves near-zero moisture vapor transmission rates through cavity-and-lidding assemblies without plastic deformation limits. Swiss and German oral solid dosage manufacturers are expanding capacity to serve European distribution of hygroscopic formulations and moisture-sensitive biologics.
- Thermoformed Blisters:PVC, PVDC, and composite substrate heating and vacuum forming sustains volume leadership through cost efficiency in high-run generic production, though performance ceilings exclude this technology from the most demanding barrier contracts.
- Push-Through Blisters:Standard retail pharmacy dispensing configuration with heat-sealed lidding foil, redesigned under FDA Poison Prevention Packaging Act guidelines for child-resistant and senior-friendly peel-push mechanisms.
- Blister Cards:Secondary presentation formats combining multiple dose units with printed adherence information for chronic disease management and combination therapies.
Thermoformed blisters retain the largest installed base. Cold formed blisters are climbing the fastest as biologics pipelines mature.
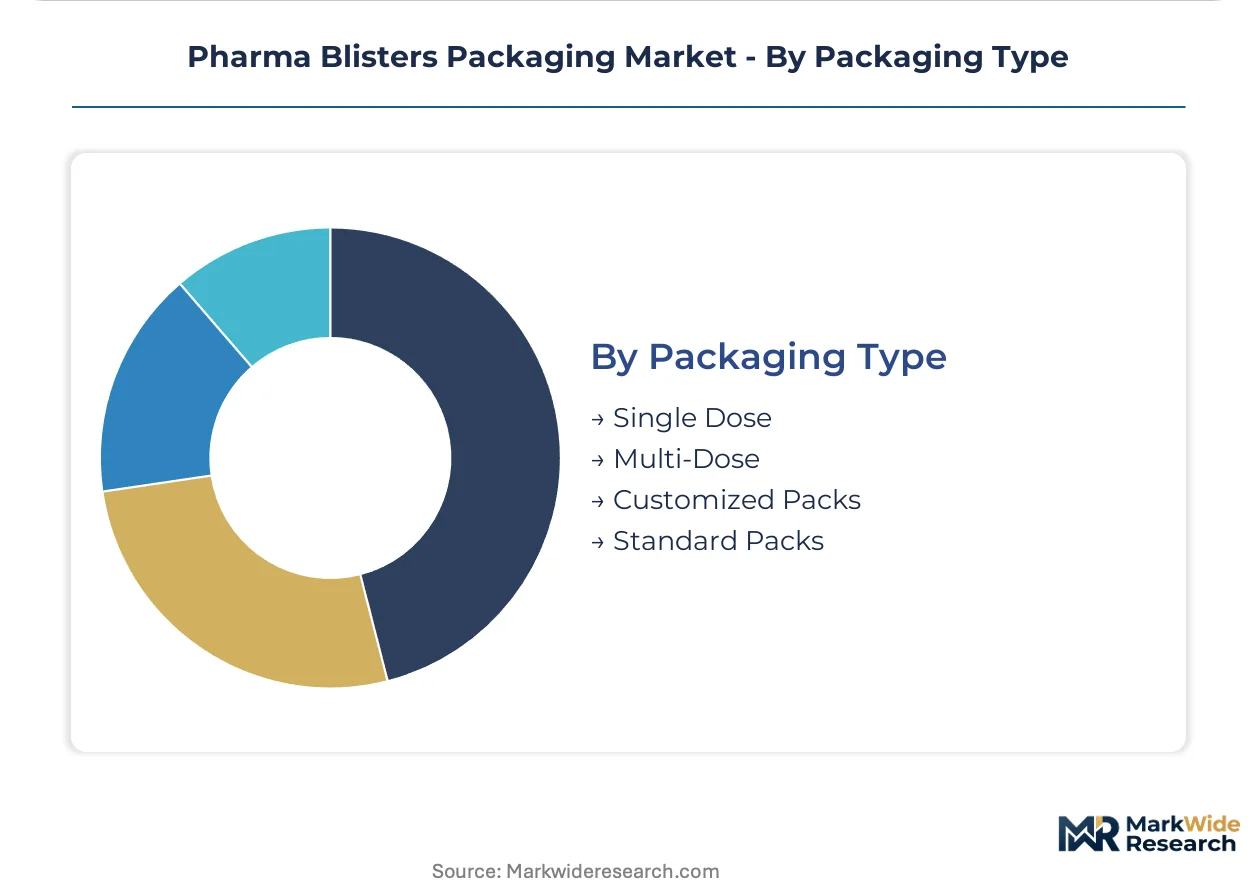
Packaging Type:
Configuration complexity correlates with customization premiums, as multi-dose and customized packs require flexible tooling and shorter production runs.
- Single Dose:Individual cavity enclosures for unit-dose dispensing in hospital and long-term care settings, with serialization integration at the dose-unit level for EU MDR compliance.
- Multi-Dose:Consolidated packaging for chronic disease regimens and combination therapies, gaining traction among pharmaceutical companies managing patient adherence programs.
- Customized Packs:Patient-specific configurations with variable dosing schedules and printed adherence prompts, requiring digital printing and flexible forming equipment with higher per-unit costs.
- Standard Packs:High-volume generic formats with fixed cavity counts and standardized lidding specifications, optimized for thermoforming line efficiency and minimal changeover downtime.
Standard packs dominate volume throughput. Customized packs are expanding most quickly as personalized medicine protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical blister packaging originated in mid-20th century Europe, where Swiss and German engineering developed cold-forming aluminum technology to protect moisture-sensitive drugs. This foundation established the Rhine-Rhône corridor as the industry's technical center of gravity.
Germany
Contract packaging organizations in Baden-Württemberg and North Rhine-Westphalia aggregate procurement volume for European pharmaceutical distribution. The EMA's MDR traceability mandates drive serialization infrastructure investment across multi-site packaging networks. Stuttgart and Düsseldorf host the continent's densest concentration of cold-forming capacity serving hygroscopic generics.
Switzerland
Swissmedic regulates moisture-sensitive biologics packaging requirements that exceed standard barrier specifications. Basel's pharmaceutical cluster demands near-zero moisture vapor transmission rates for biosimilar pipelines. The country's precision metalworking heritage supports specialized aluminum rolling and deep-draw tooling capabilities.
United States
FDA Poison Prevention Packaging Act compliance redesigns lidding configurations for child-resistant and senior-friendly dispensing. New Jersey and Pennsylvania host contract packaging corridors serving branded and generic oral solid dosage manufacturers. Serialization integration timelines accelerate ahead of DSCSA enforcement milestones.
India
CDSCO regulations align with ICH stability guidelines for moisture protection in tropical distribution environments. Maharashtra and Gujarat pharmaceutical manufacturing clusters import cold-forming equipment to serve export markets. Mumbai-based packaging converters expand thermoforming capacity for high-volume generic production.
China
NMPA stability testing requirements for oral solid dosage forms drive barrier specification upgrades across domestic pharmaceutical production. Yangtze River Delta pharmaceutical packaging clusters transition from PVC toward aluminum-barrier alternatives. Shanghai converters invest in composite film co-extrusion lines to meet evolving export standards.
Pharma Blisters Packaging Market Competitive Environment
Premium-margin players sit above commodity-margin players across barrier performance and regulatory compliance capabilities. The market structures around three tiers: integrated multinational converters with multi-continental film extrusion networks, regional specialists with aluminum-barrier expertise, and mid-cap thermoforming operators facing stranded asset risk from REACH phase-outs. Consolidation pressures concentrate among mid-tier players lacking cold-forming capacity or serialization integration services. Strategic moves center on M&A for barrier technology acquisition and capacity expansion in Germany and Switzerland.
Among the named players, Amcor Plc and Constantia Flexibles exemplify integrated multinational archetypes with film extrusion and aluminum processing capabilities spanning multiple continents. Sonoco Products Company occupies a position emphasizing integrated primary and secondary packaging lines. ACG Pharmapack represents the India-based specialist segment serving high-volume generic export markets.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Winpak Ltd |
| Amcor Plc |
| Bilcare Limited |
| Bemis Company, Inc. |
| Klöckner Pentaplast |
| WestRock Company |
| ACG Pharmapack |
| Constantia Flexibles |
| Others |
Value Chain & Pricing Dynamics
Rolled aluminum feedstock for cold-forming grade substrates flows from qualified European rolling mills through three pricing tiers before reaching German contract packaging organizations. This concentration of qualified suppliers anchors premium tier pricing for moisture-sensitive biologics while compressing margins for mid-tier converters lacking backward integration into aluminum processing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates cold-formed aluminum specifications from thermoformed composite alternatives from legacy PVC formats. Price differentiation tracks barrier performance certification and volume commitment scale, with German CPOs commanding lowest unit costs through aggregated procurement. Cost compression in the standard tier is intensifying because REACH substance restrictions are accelerating PVC phase-outs before replacement materials achieve cost parity. Generic manufacturers in the Netherlands exhibit highest price sensitivity, while Swiss biologics originators accept premium pricing for near-zero moisture vapor transmission guarantees.
Supply Chain Analysis
Cold-forming grade aluminum supply rests on German, Austrian, and Swiss rolling mills with specialized annealing and surface treatment capabilities. Raw material dependencies span primary aluminum ingot, lubricant formulations for deep-draw stamping, and precision tooling alloys for cavity formation. Single-source vulnerability concentrates in qualified aluminum suppliers serving EMA-regulated pharmaceutical packaging. Distribution runs through Germany-based contract packaging organizations that aggregate volume across fragmented European originator portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by pharmaceutical procurement teams consolidating vendor panels around outcome-based performance guarantees rather than material specifications alone.
For Market Incumbents: Anticipate stranded asset risk from REACH chlorinated film phase-outs by accelerating composite film co-extrusion capacity additions in Germany. Prioritize serialization integration services as EU MDR traceability mandates create outsourcing demand from contract packaging organizations. Backward integration into aluminum rolling secures supply security against limited qualified European suppliers. For New Entrants and Emerging Players: Begin with moisture-sensitive biologics packaging white space in Switzerland where Swissmedic regulations exceed standard barrier specifications. Target medium-sensitivity generic segments in the Netherlands transitioning from PVC under F-Gas Regulation pressure. Lead with high-barrier composite film offerings that bridge thermoforming process compatibility with cold-formed performance characteristics. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap thermoforming converters because REACH compliance deadlines compress capital recovery windows and force distressed exits. Five-to-ten year viability hinges on barrier technology acquisition and German/Swiss geographic positioning. Watch ECHA substance restriction timeline acceleration as the inflection signal for asset impairment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling | Captive supply of cold-forming grade substrate mitigates qualified supplier concentration risk in Germany and Austria. |
| Composite Film Co-Extrusion Capacity Expansion | REACH-compliant alternatives displace PVC while retaining thermoforming line compatibility for generic manufacturers. |
| Serialization Integration Service Launch | EU MDR traceability mandates drive outsourcing demand from German contract packaging organizations managing multi-site networks. |
| Biologics Barrier Certification Investment | Swissmedic specifications for near-zero moisture vapor transmission rates open premium pricing tiers for biosimilar pipelines. |
| Contract Packaging Organization Partnership | Procurement gravity centers on Germany-based CPOs absorbing inventory risk and compliance liability from originators. |
Study Parameters
Multiple input streams — primary interviews with packaging procurement managers, regulatory affairs leads at contract packaging organizations, and aluminum rolling mill technical directors; secondary validation through EMA MDR implementation timelines, ECHA REACH substance restriction databases, and German pharmaceutical trade association capacity surveys — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across material type, forming technology, end-user channel, and regional regulatory cluster segmentation dimensions produced volume and value outputs over the projection horizon. CAGRs were derived from fitted growth curves incorporating cold-forming asset expansion announcements, PVC displacement velocity under F-Gas Regulation, and biologics pipeline maturity indicators.
Caveats apply where aluminum supply disruption, REACH compliance deadline acceleration, or thermoforming asset impairment velocity could materially shift the outlook. A small set of named triggers — ECHA substance restriction timeline changes, qualified supplier consolidation, and serialization mandate enforcement intensity — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Blister Paper Market
Blister Packaging
Pharma Blister Packaging Machines Market
Blister Packaging
Middle East and Africa Blister Packaging Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
Holographic Blister Foil Market
Blister Packaging
North America Pharmaceutical Blister Packaging Market
Blister Packaging
Global Blister Packaging Market
Blister Packaging
PVC Blister Packs Market
Blister Packaging
North America Blister Packaging Market
Blister Packaging
United States Blister Packaging Market
Blister Packaging
Alu Alu Blister Packaging Machine Market
Blister Packaging
Ampoules and Blister Packaging Market
Blister Packaging
Liquid Blister Pack Market
Blister Packaging
Welded Blisters Market
Blister Packaging
Blister Foil Market
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market