
 North America Blister Packaging Market | 2026-2036
North America Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Blister Packaging Market Analytics
Market Context
Skilled thermoforming technician availability is bifurcating the competitive landscape between automated capital-intensive producers and labor-dependent regional shops. Amcor plc leverages integrated film-to-package manufacturing across multiple North American sites to sustain cost advantages in high-volume pharmaceutical contracts. WestRock Company anchors its position through paperboard-backed blister platforms that serve retail-ready display requirements. Sonoco Products Company specializes in sustainable substrate combinations that navigate evolving extended producer responsibility frameworks in California and New York.
Technical Definition and Segment Structure
North America blister packaging denotes a pre-formed plastic, aluminum, or composite cavity sealed to a lidding substrate, typically achieving oxygen transmission rates below 0.1 cc per square meter per day in cold-formed aluminum configurations, designed primarily for product protection, unit-dose dispensing, and shelf visibility. Thermoforming dominates pharmaceutical applications due to cycle speed and tooling flexibility, while cold forming captures high-barrier oncology and hormone therapies where moisture and light exclusion command premium positioning. Composite materials represent the fastest-growing material category as brand owners balance barrier performance against recyclability targets set by Walmart and CVS Health sustainable packaging commitments.
Regulatory Framework and Outlook
FDA 21 CFR Part 211 cGMP requirements and USP <661> plastic packaging system standards shape material qualification timelines and supplier validation burdens across the United States. Health Canada's ICH Q1A stability testing guidelines and EPA Toxic Substances Control Act reporting obligations for novel polymers add parallel compliance layers for cross-border suppliers. Stakeholders must monitor state-level extended producer responsibility legislation progression in California, Oregon, and Colorado to determine whether recycled content mandates will restructure material sourcing economics before the forecast horizon concludes.
Market Dynamics
Serialization mandates from the FDA are forcing pharmaceutical manufacturers to rebuild packaging lines around track-and-trace infrastructure, compressing equipment replacement cycles and reshaping supplier qualification protocols across the Great Lakes manufacturing corridor.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Unit-dose serialization requirements are mandating blister format conversion from bulk bottles across generic and specialty drug portfolios.
- Oncology pipeline expansion:Cold-formed aluminum demand is accelerating as moisture-sensitive biologics and hormone therapies require oxygen transmission rates below 0.1 cc per square meter per day.
- Great Lakes cluster concentration:Contract packaging infrastructure in Michigan, Ohio, and Illinois is creating density economies that lower per-unit validation costs for mid-size pharmaceutical launches.
Market Restraints
- Aluminum foil supply concentration:Domestic cold-forming substrate production is concentrated among three integrated suppliers, exposing converters to input cost volatility and allocation risk during demand spikes.
- Extended producer responsibility timelines:California and New York legislative frameworks are creating compliance uncertainty before recycled content mandates crystallize, freezing long-term material commitments.
- Thermoforming barrier limitations:Polyvinyl chloride and polyethylene terephthalate substrates cannot achieve cold-form oxygen exclusion, restricting their use in high-humidity stability categories.
Strategic Opportunities
- Quebec and Ontario contract packaging:Health Canada's alignment with ICH stability guidelines is attracting US biopharma companies seeking dual-market qualification through single packaging runs.
- Paperboard-backed retail formats:WestRock-style display-ready platforms are penetrating over-the-counter and supplement channels where shelf visibility commands placement premiums.
- Recyclable mono-material structures:Walmart and CVS Health sustainable packaging commitments are creating specification pull for polyethylene and polypropylene cavity-lidding combinations that bypass multi-layer sorting complexity.
Industry Challenges
- Thermoforming technician scarcity:Automated capital-intensive producers are capturing high-volume contracts as regional shops face skilled labor gaps in die alignment, cavity forming, and seal integrity validation.
- USP 661 plastic qualification timelines:Extractables and leachables testing protocols are extending material approval cycles to 18-24 months, compressing product launch windows for novel polymer introductions.
Report Scope
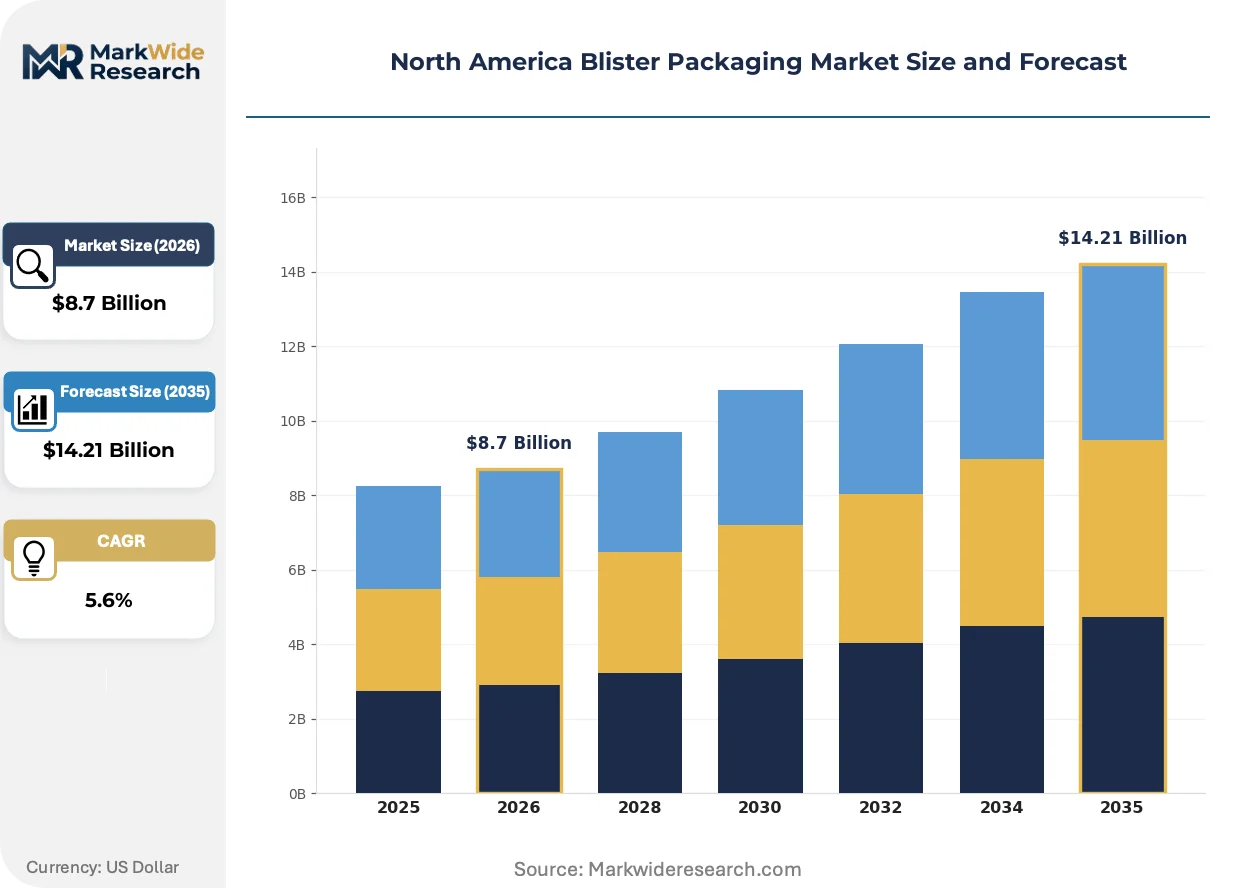
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Blister Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Consumer Electronics, Food, Personal Care Material: Plastic, Aluminum, Paper, Composite End User: Pharmaceutical Companies, Electronics Manufacturers, Food Producers, Retailers Technology: Thermoforming, Cold Forming, Vacuum Forming, Blister Sealing |
| Companies Covered | Amcor plc, WestRock Company, Sonoco Products Company, Honeywell International Inc., Constantia Flexibles, Klöckner Pentaplast, WINPAK Ltd., TekniPlex, Berry Global Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Blister Packaging Market Evolving Landscape
Digital printing and smart packaging integration are redefining how blister packs communicate compliance data and brand authentication, shifting value capture from substrate suppliers to systems integrators.
High-definition digital printing on lidding foils is bifurcating the market between short-run personalized campaigns and high-volume pre-printed stock. Specialty pharmaceutical marketers in the United States are adopting lot-specific variable data for clinical trial materials and compliance packaging. This technology is compressing minimum order quantities from hundreds of thousands to tens of thousands of units, enabling targeted patient adherence programs.
California's extended producer responsibility legislation is mandating post-consumer recycled content thresholds and producer financing of end-of-life collection infrastructure. Packaging converters are restructuring supply agreements to secure certified recycled polyethylene and polypropylene streams before 2030 compliance deadlines. Pharmaceutical brands with direct retail distribution are most exposed, as their packaging volumes fall under scope faster than hospital-administered products.
Retail pharmacy consolidation is concentrating procurement authority among CVS Health, Walgreens Boots Alliance, and Walmart's pharmaceutical divisions. These buyers are unbundling packaging specification from drug product supply, appointing preferred converter panels with pre-qualified sustainability and serialization capabilities. The shift is most visible in generic drug categories where private-label equivalent competition intensifies shelf placement negotiations.
North America Blister Packaging Market Segmentation
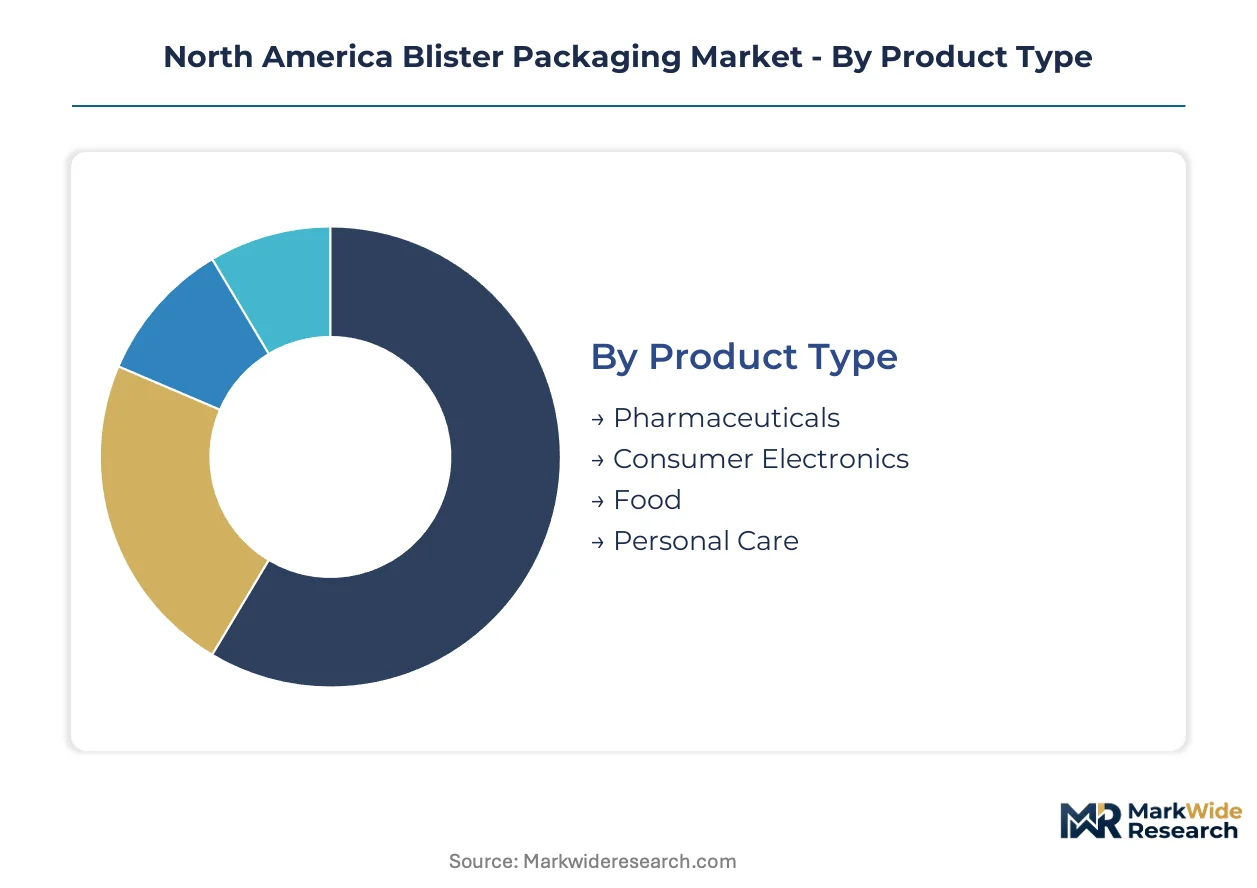
Blister packaging demand fragments across four distinct structural dimensions, each with divergent barrier specifications and regulatory qualification burdens. Material selection and forming technology choices cascade through end-use applications, creating segment-specific competitive moats.
Product Type:
Pharmaceuticals face the strongest substitution pressure from bottle-and-cap alternatives where unit-dose compliance is less critical, while electronics and food segments compete against clamshell and tray formats.
- Pharmaceuticals:Unit-dose cavity configurations achieve oxygen transmission rates below 0.1 cc per square meter per day in cold-formed aluminum. FDA serialization mandates are compressing equipment replacement cycles across Michigan, Ohio, and Illinois manufacturing corridors.
- Consumer Electronics:Anti-static thermoformed trays protect sensitive components during distribution. Demand concentrates in Mexico border maquiladora operations serving US assembly plants, driven by nearshoring acceleration and tariff exposure mitigation.
- Food:Modified atmosphere configurations extend shelf life for protein and produce applications. California extended producer responsibility frameworks are forcing material transitions away from multi-layer structures.
- Personal Care:High-visibility display formats dominate retail placement negotiations. Walmart and CVS Health sustainable packaging commitments are pulling specification toward mono-material polyethylene structures.
Pharmaceuticals anchors the volume base while personal care gains share at the steepest rate.
Material:
Cost tier stratification separates premium barrier substrates from commodity thermoformable films, with composite materials commanding mid-tier positioning.
- Plastic:Polyvinyl chloride and polyethylene terephthalate dominate high-speed thermoforming with cycle speeds exceeding 30 strokes per minute. Polypropylene cavity-lidding combinations are climbing fastest as recyclability specifications harden.
- Aluminum:Cold-forming foils deliver moisture and light exclusion for oncology and hormone therapies. Domestic production concentrates among three integrated suppliers, exposing converters to allocation risk during demand spikes.
- Paper:Paperboard-backed platforms serve retail-ready display requirements in over-the-counter channels. WestRock Company anchors positioning through integrated fiber and forming operations.
- Composite:Multi-layer structures balance barrier performance against sustainability targets. California and New York legislative uncertainty is freezing long-term material commitments until recycled content mandates crystallize.
Plastic retains the dominant volume position while composite structures expand most quickly amid sustainability transition pressures.
End User:
Customer type determines validation intensity, with pharmaceutical companies imposing 18-24 month material qualification timelines versus faster-track retail specifications.
- Pharmaceutical Companies:USP 661 extractables and leachables testing protocols compress product launch windows. Serialization infrastructure rebuilds are reshaping supplier qualification protocols across contract packaging networks.
- Electronics Manufacturers:ESD-sensitive component protection drives specification toward conductive coating technologies. Mexico border operations are capturing share from Asian supply sources.
- Food Producers:Modified atmosphere and vacuum skin formats extend distribution reach for perishables. California SB 54 compliance deadlines are restructuring sourcing agreements.
- Retailers:Private-label procurement authority concentrates among CVS Health, Walgreens Boots Alliance, and Walmart pharmaceutical divisions. Preferred converter panels with pre-qualified sustainability capabilities are displacing fragmented supplier bases.
Pharmaceutical companies dominate value capture while retailers are gaining procurement leverage fastest through consolidation.
Technology:
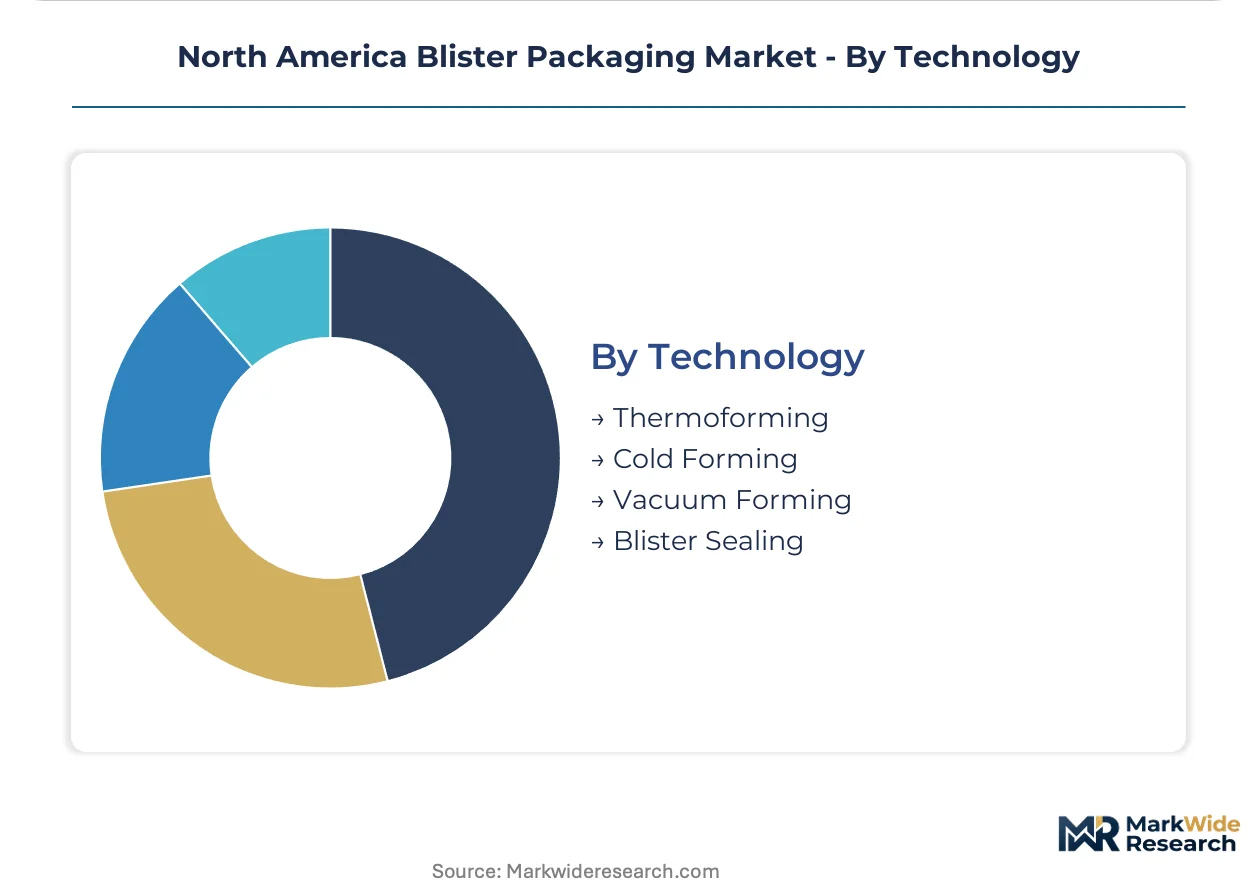
Volume scale separates capital-intensive automated lines from labor-dependent regional operations, with thermoforming capturing the broadest application range.
- Thermoforming:Cycle speed and tooling flexibility dominate pharmaceutical and consumer goods applications. Skilled technician scarcity is bifurcating competitive positioning between automated producers and regional shops.
- Cold Forming:Aluminum cavity formation delivers superior barrier performance for moisture-sensitive biologics. Health Canada ICH Q1A alignment is attracting US biopharma dual-market qualification through Quebec and Ontario operations.
- Vacuum Forming:Lower tooling costs serve short-run and prototype requirements. Regional job shops maintain positioning where minimum order quantities exceed digital printing compression thresholds.
- Blister Sealing:Heat-seal and cold-seal lidding attachment methods determine line speed and integrity validation. FDA 21 CFR Part 211 cGMP requirements shape equipment qualification burdens.
Thermoforming commands the installed base while cold forming posts the steepest expansion trajectory driven by oncology pipeline growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates and USP barrier standards anchor the United States as the dominant geography, with Health Canada and Mexico's maquiladora operations completing the North American demand triangle.
United States
Pharmaceutical contract packaging clusters in Michigan, Ohio, and Illinois drive thermoforming demand for unit-dose compliance. FDA 21 CFR Part 211 cGMP requirements compress equipment replacement cycles across the Great Lakes manufacturing corridor. Serialization infrastructure rebuilds are reshaping supplier qualification protocols in these states.
Canada
Quebec and Ontario contract packaging operations attract US biopharma companies seeking dual-market qualification through single packaging runs. Health Canada's alignment with ICH Q1A stability testing guidelines accelerates cross-border material approvals. Toronto and Montreal packaging hubs specialize in cold-formed aluminum for moisture-sensitive biologics.
Mexico
Border maquiladora operations capture electronics blister tray demand from nearshoring acceleration and tariff exposure mitigation. Tijuana and Ciudad Juárez thermoforming facilities serve US assembly plants with anti-static configurations. Mexican packaging converters leverage USMCA trade provisions for integrated North American supply chains.
North America Blister Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with film-to-package manufacturers commanding cost advantages in high-volume pharmaceutical contracts. The market structure separates automated capital-intensive producers from labor-dependent regional shops facing skilled thermoforming technician scarcity. Three archetypes dominate: integrated material-package manufacturers, paperboard-backed retail platform specialists, and sustainable substrate innovators. Competitive moves center on backward integration into film extrusion and pre-qualification for retailer preferred converter panels.
Among integrated packaging leaders, Amcor plc exemplifies the film-to-package archetype through multi-site North American manufacturing. WestRock Company occupies a position in paperboard-backed blister platforms serving retail-ready display requirements. Sonoco Products Company represents sustainable substrate specialization navigating extended producer responsibility frameworks.
| Leading Market Players |
|---|
| Amcor plc |
| WestRock Company |
| Sonoco Products Company |
| Honeywell International Inc. |
| Constantia Flexibles |
| Klöckner Pentaplast |
| WINPAK Ltd. |
| TekniPlex |
| Berry Global Group, Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day aluminum foil inventory cycles at cold-forming converters translate directly into pricing power concentration among three domestic integrated suppliers, compressing margins for regional thermoforming shops while amplifying cost pass-through leverage at the barrier-substrate tier.
Pricing Analysis
Geographic price spreads of 15-20 percent separate Great Lakes contract packaging hubs from Southwest and Southeast regional operations, reflecting density economies in Michigan, Ohio, and Illinois validation corridors. Contract-based long-term offtake agreements dominate pharmaceutical blister procurement, with price differentiation hinging on FDA 21 CFR Part 211 certification tier and serialization infrastructure readiness. Cost compression in commodity thermoforming grades is intensifying because PVC and PET substrate oversupply is colliding with technician scarcity premiums. Retail pharmacy procurement panels exhibit highest price sensitivity, while oncology cold-forming buyers prioritize barrier performance over unit economics.
Supply Chain Analysis
Strategic stockpiling of aluminum foils and specialty films dominates pharmaceutical converter inventory strategy, contrasting with just-in-time resin procurement in commodity thermoforming operations. Domestic supply concentrates in the United States, Canada, and Mexico under USMCA integration, drawing from aluminum rolling mills in Kentucky and Tennessee, film extrusion complexes in Ontario and Quebec, and border maquiladora thermoforming facilities. Raw material dependencies rest on pharmaceutical-grade aluminum foil, high-barrier polymer films, and paperboard lidding substrates. Single-source vulnerability in cold-forming foil allocation creates exposure during oncology pipeline demand spikes. Distribution runs through contract packaging networks anchored to pharmaceutical manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across material tiers and geographic validation corridors is creating specialist niches as FDA serialization mandates and state-level extended producer responsibility frameworks splinter procurement specifications.
For Market Incumbents: Fortify barrier-substrate supply positions through captive aluminum foil sourcing or exclusive tolling arrangements with the three domestic integrated suppliers, defending against margin compression from technician-scarcity-driven automation gaps. Deepen serialization infrastructure pre-qualification across CVS Health, Walgreens Boots Alliance, and Walmart pharmaceutical procurement panels to lock in preferred converter status before retailer consolidation hardens. For New Entrants and Emerging Players: Sustainable substrate qualification services represent the most penetrable service-layer gap, as incumbent converters freeze long-term material commitments pending California and New York recycled content mandate crystallization. Quebec and Ontario contract packaging corridors offer lowest barriers to dual-market US-Canada qualification under Health Canada ICH Q1A alignment. A go-to-market angle targeting mid-size biopharma launches with 18-24 month USP 661 fast-track consulting bypasses high-volume incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because technician scarcity and equipment replacement cycles are forcing regional shop exits into automated capital-intensive platforms. Acquisition targets should profile film-to-package integrated manufacturers with FDA serialization pre-qualification and Great Lakes corridor density. The signal to watch is California SB 54 recycled content threshold announcements triggering material sourcing agreement restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive supply of pharmaceutical-grade PVC and PET reduces input cost volatility from resin spot markets. |
| Serialization Infrastructure Pre-Qualification | FDA Drug Supply Chain Security Act compliance positions converters for CVS Health and Walmart preferred panel inclusion. |
| Dual-Market US-Canada Qualification | Health Canada ICH Q1A alignment enables single-run packaging for US biopharma companies seeking cross-border access. |
| Sustainable Substrate Certification | California and New York extended producer responsibility frameworks pull specification toward recyclable mono-material structures. |
| Technician Training Pipeline Development | Skilled thermoforming labor scarcity is bifurcating competitive positioning between automated and regional producers. |
Research Methodology
Operator-level perspectives from pharmaceutical packaging engineers, contract manufacturing organization procurement directors, thermoforming equipment specialists, and retail pharmacy supply chain managers anchored the qualitative base, cross-validated against FDA 21 CFR Part 211 guidance documents, USP plastic packaging system standards, Health Canada ICH stability guidelines, and state-level extended producer responsibility legislative tracking across California, Oregon, and Colorado. Bottom-up demand modeling triangulated with top-down market sizing across material, technology, and end-user segmentation dimensions.
Sensitivity analysis tested forecast robustness across aluminum foil price volatility bands, serialization equipment replacement cycle timing, and recycled content mandate implementation scenarios. Segmentation dimensions modeled included product type, material substrate, forming technology, and end-user category across the projection horizon. CAGRs were derived from installed base depreciation schedules, pipeline conversion rates for oncology and hormone therapies, and retailer sustainable packaging commitment penetration curves.
Underlying assumptions cover FDA serialization mandate adherence timelines, Health Canada ICH Q1A guideline stability, and USMCA trade provision continuity, with deviation risk concentrated in state-level extended producer responsibility implementation pacing and aluminum foil supply allocation during demand spikes. Revision becomes warranted when recycled content mandate thresholds cross compliance feasibility boundaries for multi-layer composite structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
Healthcare Blister Packaging Market
Blister Packaging
Pharma Blister Packaging Machines Market
Blister Packaging
PVC Blister Packaging Market
Blister Packaging
Alu Alu Blister Packaging Machine Market
Blister Packaging
Latin America Pharmaceutical Blister Packaging Market
Blister Packaging
Blister Packs Market
Blister Packaging
Blister Packaging Equipment Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
High Barrier Pharmaceutical Packaging Films for Blister Market
Blister Packaging
Blister Cards Market
Blister Packaging
Middle East and Africa Blister Packaging Market
Blister Packaging
Blister Foil Market
Blister Packaging
Blister Paper Market
Blister Packaging
Welded Blisters Market