
 Ampoules and Blister Packaging Market | 2026-2036
Ampoules and Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Ampoules and Blister Packaging Market Outlook
The capital-intensity divergence between automated high-speed blister lines and manual ampoule forming is unwinding as contract packers consolidate capacity. Gerresheimer sustains leadership in tubular glass ampoules through captive borosilicate sourcing and pharmaceutical-grade furnace operations. Amcor leverages its global film extrusion network to dominate cold-form aluminum blister supply for moisture-sensitive oral solids. Klöckner Pentaplast Group specializes in multi-layer PVC barrier films, anchoring its position in high-humidity markets.
Ampoules and blister packaging encompass sealed, single-unit containment systems: ampoules are thin-walled glass or plastic vessels heat-sealed at the neck for sterile liquid or powder dosing, while blister packs consist of thermoformed plastic cavities sealed to lidding foil for individual tablet or capsule protection. Blister lidding typically employs 20-25 micron aluminum foil with heat-seal lacquer to achieve child-resistance and moisture barriers below 0.5 g/m²/day. Plastic blisters lead unit volume due to cost efficiency in mass-market oral dosage, yet aluminum blisters command premium positioning for hygroscopic oncology drugs. Glass ampoules retain dominance in parenteral applications where USP Type I borosilicate inertness prevents drug-container interaction.
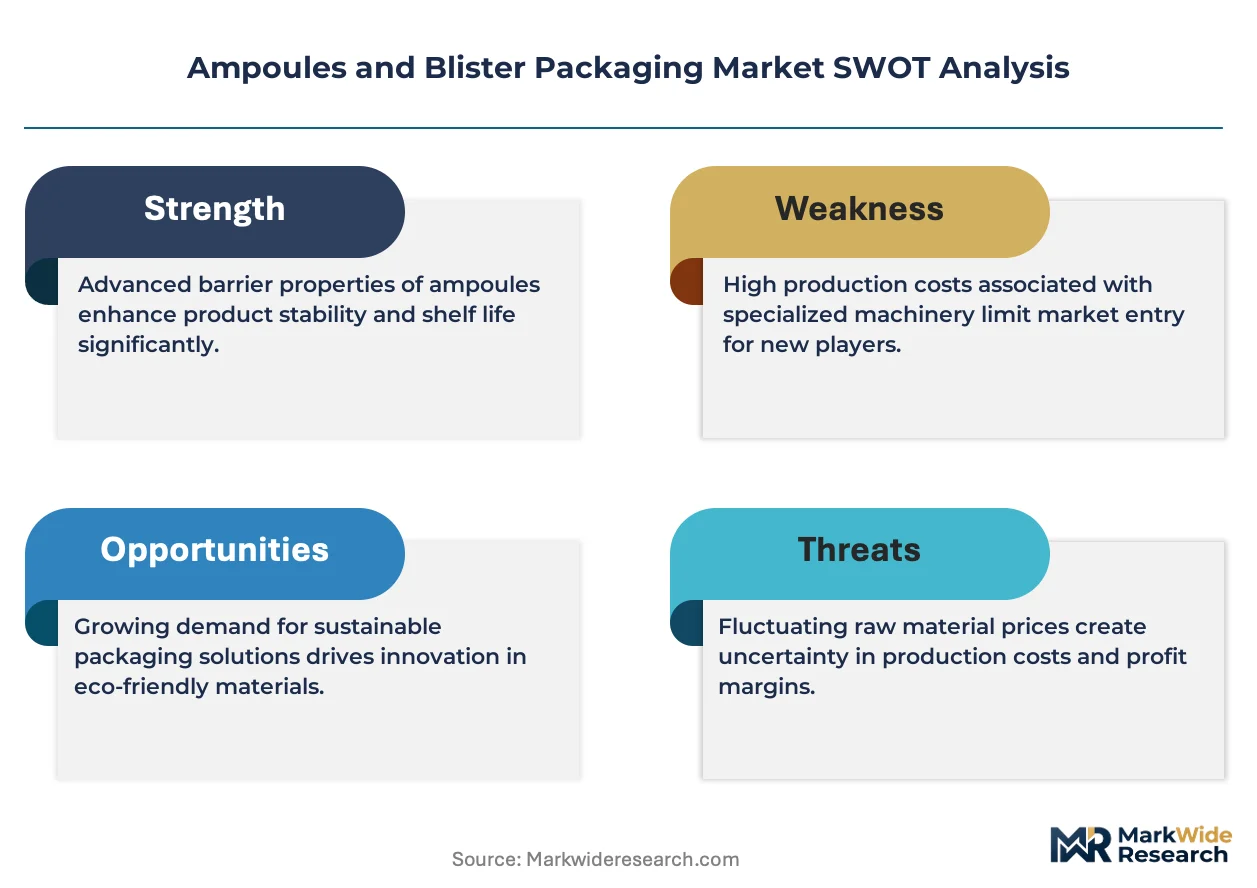
FDA serialization requirements under the Drug Supply Chain Security Act and EU MDR unique device identification rules are reshaping demand for integrated blister printing and aggregation capabilities. The EPA and ECHA jointly push PVC phase-out assessments, pressuring converters toward polyethylene and polypropylene alternatives in non-barrier applications. Stakeholders must monitor evolving pharmacopeial chapters on container closure integrity, as USP <1207> and EP 3.2.9 revisions will determine acceptable leak-test methodologies for both ampoule and blister formats.
Market Dynamics
Pharmaceutical serialization mandates are compressing packaging line upgrade cycles as manufacturers race to comply with unit-level traceability requirements before enforcement deadlines hit.
Growth Catalysts
- EU MDR and FDA DSCSA serialization:Mandates for unique device identification and drug supply chain security are forcing pharmaceutical manufacturers to retrofit blister lines with integrated printing and aggregation stations.
- Temperature-sensitive biologics expansion:Cold-chain logistics networks for monoclonal antibodies and mRNA vaccines are standardizing blister formats with validated thermal barriers.
- Germany's injectable cluster:Dense concentration of parenteral drug manufacturers and packaging machinery specialists in Baden-Württemberg and Bavaria is sustaining specialized ampoule demand.
Market Restraints
- Borosilicate glass supply concentration:Captive furnace operations in Germany and India control premium USP Type I tubular glass, limiting second-source options for sterile ampoule buyers.
- PVC regulatory pressure:ECHA and EPA phase-out assessments are forcing converters to validate polyethylene and polypropylene alternatives, extending qualification timelines.
- High-speed line capex barriers:Automated blister systems requiring cleanroom integration and vision inspection modules demand capital commitments that exclude mid-volume contract packers.
Strategic Opportunities
- India's domestic pharma growth:CDSCO quality mandates and PLI scheme incentives for active pharmaceutical ingredients are expanding local blister and ampoule conversion capacity.
- Child-resistant lidding innovation:Push-through and peel-push formats with senior-friendly compliance are opening over-the-counter segments previously locked to bottles.
- Pre-filled polymer ampoules:Cyclic olefin polymer vessels for biologics are penetrating ophthalmic and emergency injection applications where glass breakage risk is unacceptable.
Industry Challenges
- Container closure integrity validation:USP Chapter 1207 and EP 3.2.9 revisions on leak-test methodologies are forcing packagers to requalify existing ampoule and blister formats.
- Multi-material recycling complexity:Aluminum-PVC blister laminates face circular economy compliance gaps as extended producer responsibility schemes expand across European member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ampoules and Blister Packaging Market |
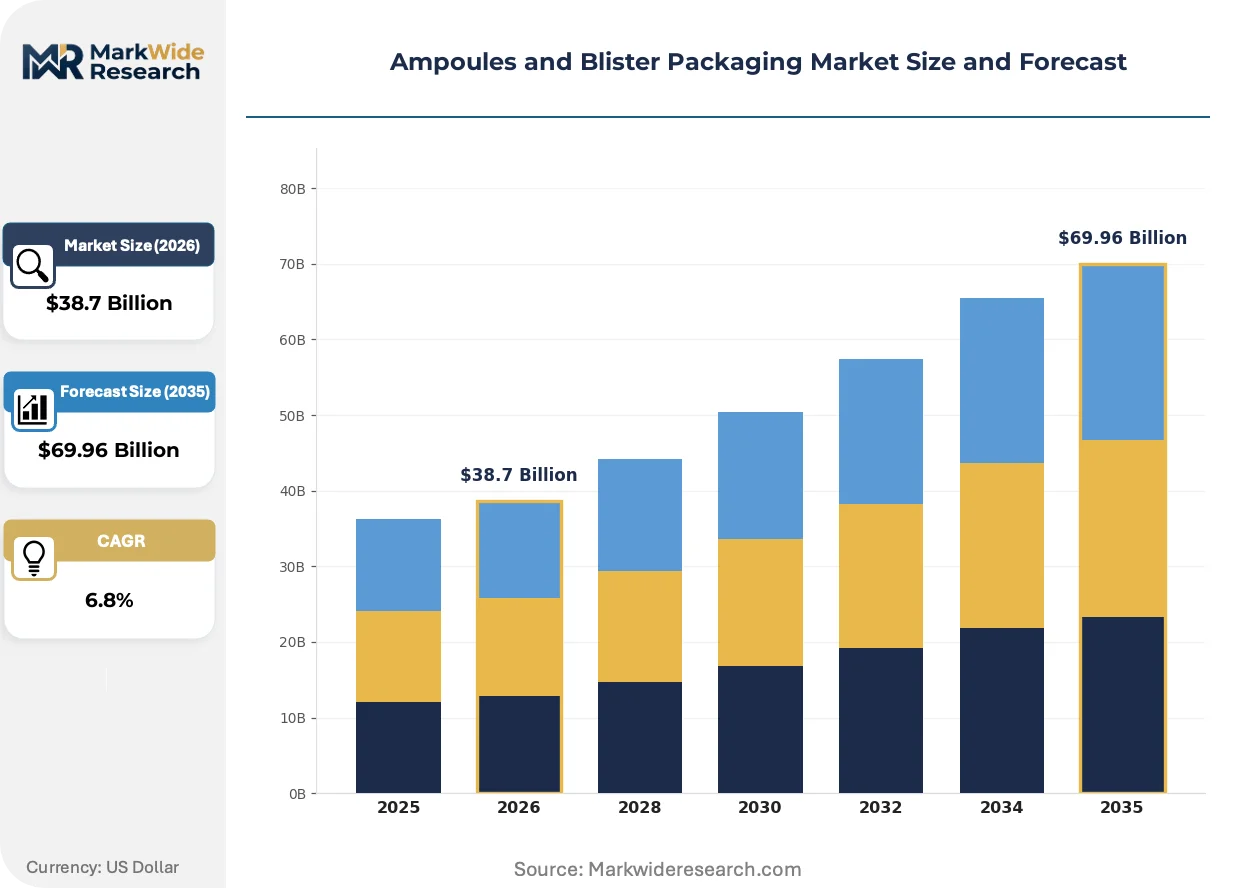
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Plastic Blisters, Aluminum Blisters, Glass Ampoules, Plastic Ampoules Material: Polyethylene, Polyvinyl Chloride, Glass, Aluminum End User: Pharmaceuticals, Cosmetics, Food & Beverages, Diagnostics Form: Liquid, Powder, Gel, Tablets |
| Companies Covered | Amcor, Gerresheimer, WestRock Company, Constantia Flexibles International, Sonoco Products Company, Klöckner Pentaplast Group, Schott AG, Nipro Corporation, J.Penner Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ampoules and Blister Packaging Market Strategic Shifts
Cold-form aluminum blisters and pre-filled polymer ampoules are converging with digital traceability layers, reshaping how pharmaceutical packaging delivers both physical protection and supply chain visibility.
Polymer-based pre-filled ampoules are displacing traditional glass formats in emergency medicine and ophthalmic applications where weight reduction and breakage elimination outweigh premium pricing. Military medical services and emergency response units in North America and Western Europe are standardizing cyclic olefin polymer syringe-ampoule hybrids for field deployment. This displacement is compressing glass ampoule volume in trauma care while expanding polymer penetration into hospital pharmacy automation systems.
REACH restrictions on PVC plasticizers and the EU Green Deal circular packaging targets are accelerating converter migration toward polyethylene and polypropylene barrier films. Pharmaceutical manufacturers with European distribution are qualifying multi-layer coextruded alternatives to maintain moisture vapor transmission rates below 0.5 g/m²/day. High-humidity markets in Southern Europe and Southeast Asia are experiencing the most acute formulation rework as existing blister specifications face regulatory sunset timelines.
Direct-to-pharmacy distribution models are compressing wholesaler intermediation in specialty oncology and rare disease segments. Hospital systems and specialty pharmacies in Germany and the United States are consolidating procurement through preferred manufacturer agreements that specify unit-dose blister formats with embedded serialization. This channel consolidation is elevating technical service capabilities as a competitive differentiator among packaging converters serving high-value biologics.
Ampoules and Blister Packaging Market Segmentation
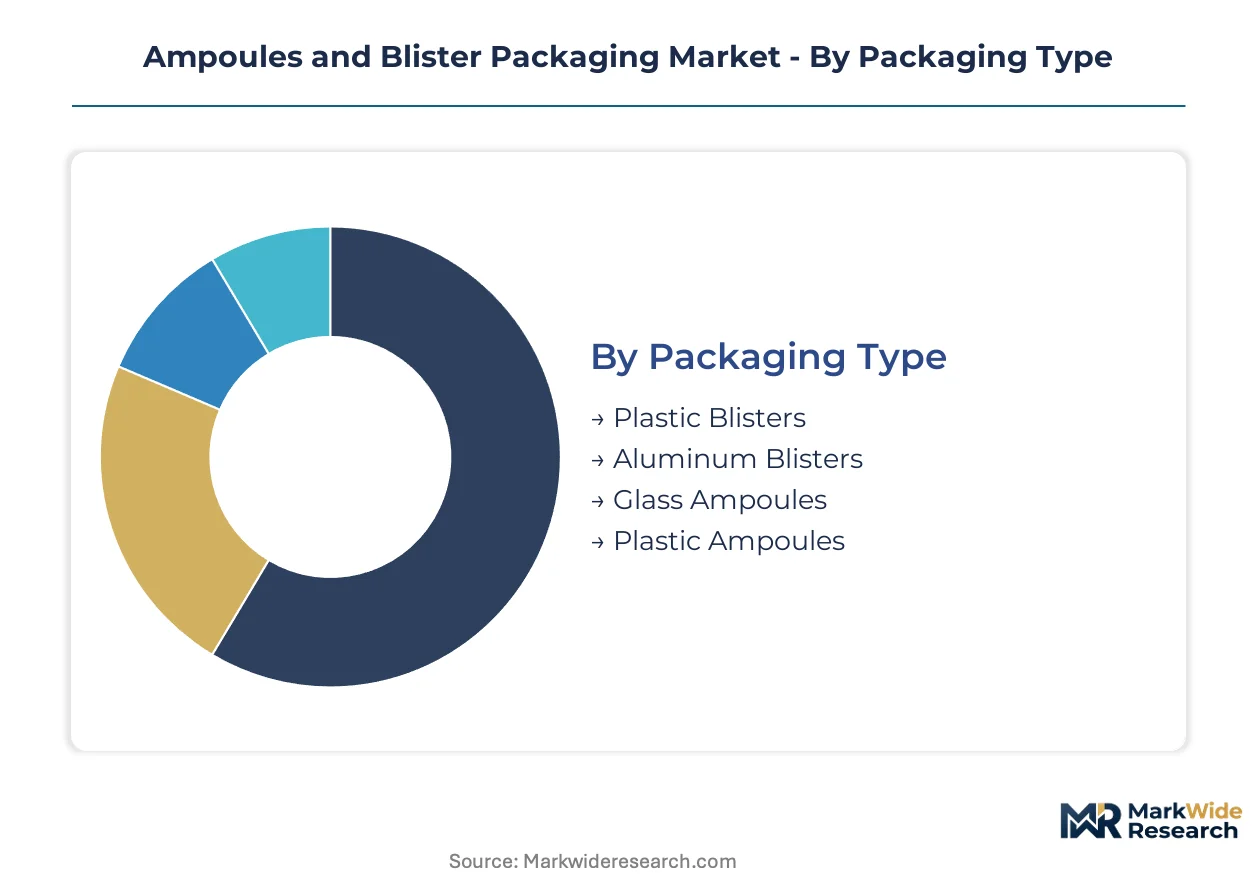
Segmentation in ampoules and blister packaging reveals divergent margin profiles across material science tiers and regulatory compliance burdens. Pharmaceutical end-users command premium positioning through USP Type I certification requirements, while food and cosmetic applications compete on cycle time and decoration flexibility.
Packaging Type:
Margin pools concentrate in aluminum blisters and glass ampoules where barrier performance justifies qualification-intensive supply relationships.
- Plastic Blisters:Thermoformed PVC or polyethylene cavities sealed to aluminum lidding dominate oral solid volume. Demand concentrates in India's domestic pharmaceutical sector, where CDSCO quality mandates and PLI scheme incentives are expanding conversion capacity for export-grade generics.
- Glass Ampoules:USP Type I borosilicate tubular vessels heat-sealed at the neck for sterile parenteral dosing retain inertness advantages. Germany's Baden-Württemberg and Bavaria clusters sustain specialized demand through dense concentrations of injectable drug manufacturers and packaging machinery specialists.
- Aluminum Blisters:Cold-form aluminum cavities deliver moisture barriers below 0.5 g/m²/day for hygroscopic oncology drugs. Premium positioning in European and North American specialty pharma segments offsets slower line speeds versus thermoformed alternatives.
- Plastic Ampoules:Cyclic olefin polymer vessels eliminate glass breakage risk in emergency medicine and ophthalmic applications. Military medical services in North America and Western Europe are standardizing these formats for field deployment.
Glass ampoules hold installed capacity. Plastic ampoules are rotating up the share rankings.
Material:
Cost tier stratification separates commodity thermoplastics from pharmaceutical-grade barrier substrates with pharmacopeial certification overhead.
- Polyvinyl Chloride:Standard thermoforming substrate for mass-market oral solids offers clarity and process efficiency. ECHA and EPA phase-out assessments are forcing converters toward polyethylene and polypropylene alternatives, extending qualification timelines.
- Glass:Borosilicate and soda-lime compositions differentiated by USP and EP chapter compliance. Captive furnace operations in Germany and India control premium USP Type I tubular supply, limiting second-source options.
- Aluminum:20-25 micron foil with heat-seal lacquer achieves child-resistance and moisture barriers. Cold-form grades command material cost premiums against push-through lidding specifications.
- Polyethylene:Multi-layer coextruded barrier films are gaining qualification for European distribution as REACH restrictions on PVC plasticizers accelerate. High-humidity markets in Southern Europe face acute formulation rework.
Glass commands specification premiums. Polyethylene is climbing the fastest among qualified alternatives.
End User:
Application-driven demand splits between validated pharmaceutical supply chains and cost-optimized consumer segments with divergent regulatory exposure.
- Pharmaceuticals:Unit-dose formats with embedded serialization serve specialty oncology and rare disease distribution. FDA DSCSA and EU MDR mandates are compressing packaging line upgrade cycles for traceability compliance.
- Diagnostics:Single-test containment for point-of-care devices requires moisture barriers and reagent stability. Demand concentrates in automated laboratory systems and decentralized testing networks.
- Cosmetics:Ampoule formats for serums and active ingredients leverage breakage risk elimination in travel retail. Decoration flexibility and premium unboxing experience drive specification decisions.
- Food & Beverages:Portion-control blisters for confectionery and nutritional supplements compete on cycle time and shelf impact. Lower barrier requirements permit thinner film gauges versus pharmaceutical grades.
Pharmaceuticals anchor volume value. Diagnostics is gaining share fastest through point-of-care expansion.
Form:
Physical state determines containment geometry, seal integrity methodology, and compatibility testing protocols across liquid, solid, and semi-solid applications.
- Tablets:Push-through and peel-push blister formats with senior-friendly compliance open over-the-counter segments previously locked to bottles. Child-resistant lidding innovation is reshaping competitive positioning in North American retail pharmacy.
- Liquid:Glass and polymer ampoules for sterile parenteral, ophthalmic, and emergency injection applications. Pre-filled formats are penetrating hospital pharmacy automation systems where dose accuracy and contamination control are critical.
- Powder:Ampoule formats for lyophilized biologics and reconstitution dosing require inert headspace and seal integrity validation. USP Chapter 1207 and EP 3.2.9 revisions on leak-test methodologies are forcing requalification cycles.
- Gel:Semi-solid containment in unit-dose sachets and ampoules serves topical pharmaceutical and cosmetic applications. Viscosity-specific discharge characteristics influence orifice and closure design.
Tablets hold installed capacity. Liquid formats are rotating up the share rankings through biologics expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's Baden-Württemberg and Bavaria clusters, where captive borosilicate furnace operations command premiums over Indian converters facing extended PVC-alternative qualification timelines.
United States
FDA DSCSA serialization deadlines and military medical procurement are driving polymer ampoule adoption for emergency field deployment. The EPA's PVC phase-out assessments are pressuring converters toward polyethylene alternatives. Boston and Research Triangle Park host dense concentrations of biologics manufacturers specifying cold-form aluminum blisters for hygroscopic oncology drugs.
Germany
EU MDR unique device identification rules and the EU Green Deal circular packaging targets are compressing packaging line upgrade cycles. ECHA restrictions on PVC plasticizers are accelerating multi-layer coextruded barrier film qualification. Stuttgart and Munich anchor the injectable drug manufacturing cluster sustaining specialized USP Type I glass ampoule demand.
India
CDSCO quality mandates and PLI scheme incentives for active pharmaceutical ingredients are expanding domestic blister and ampoule conversion capacity. The country's national pharmaceutical regulator is tightening traceability standards for export-grade generics. Ahmedabad and Hyderabad host expanding contract packaging operations serving European and North American distribution.
China
NMPA serialization requirements and dual carbon goals are reshaping converter investment toward recyclable polyethylene and polypropylene films. The Ministry of Ecology and Environment is accelerating PVC sunset assessments in coastal manufacturing zones. Shanghai and Suzhou concentrate pharmaceutical packaging machinery specialists integrating vision inspection and aggregation modules.
Switzerland
Swissmedic pharmacopeial standards and proximity to European specialty pharma headquarters sustain premium positioning for barrier-grade aluminum blister supply. The country's national environmental agency is enforcing extended producer responsibility schemes for multi-material laminates. Basel anchors pharmaceutical packaging R&D concentration serving global biologics manufacturers.
Ampoules and Blister Packaging Market Competitive Environment
Concentration sits with integrated material suppliers controlling captive borosilicate sourcing and global film extrusion networks. The competitive structure tiers between furnace-owning glass specialists, multi-layer film converters, and diversified packaging conglomerates with pharmaceutical-grade certification depth. Strategic archetypes include upstream-integrated material players, regional contract packaging specialists, and serialization-technology integrators. Dominant competitive moves encompass backward integration into pharmaceutical-grade raw materials and geographic expansion through preferred manufacturer agreements with hospital systems.
Among furnace-owning specialists, Gerresheimer and Schott AG exemplify the premium-tier archetype through captive control over USP Type I tubular glass supply. Amcor occupies a position representing the diversified conglomerate model with global cold-form aluminum blister capabilities. Klöckner Pentaplast Group sits within the multi-layer barrier film specialist tier serving high-humidity market qualification requirements.
| Leading Market Players |
|---|
| Amcor |
| Gerresheimer |
| WestRock Company |
| Constantia Flexibles International |
| Sonoco Products Company |
| Klöckner Pentaplast Group |
| Schott AG |
| Nipro Corporation |
| J.Penner Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day furnace commissioning lead times for USP Type I borosilicate glass compress inventory flexibility and anchor pricing power with Germany's captive furnace operators against Indian converters wrestling with PVC-alternative qualification delays.
Pricing Analysis
The customization-premium spread separates configured-to-order cold-form aluminum blisters from standard thermoformed PVC formats. Three-tier pricing structure across premium, standard, and economy levels reflects USP Type I certification grade, volume scale, and geographic delivery cost. Pricing pressure stems from REACH-driven PVC phase-out assessments forcing extended qualification timelines. Mid-volume contract packers exhibit highest price sensitivity due to high-speed line capex barriers, while specialty oncology drug manufacturers show lowest sensitivity given moisture barrier performance requirements.
Supply Chain Analysis
Just-in-time inventory strategies dominate pharmaceutical end-users with validated cold-chain networks, while strategic stockpiling persists among military medical services standardizing polymer ampoules for field deployment. Supply concentrates in Germany, India, and China for borosilicate glass furnaces, multi-layer film extrusion, and packaging machinery integration respectively. Raw material dependencies rest on pharmaceutical-grade PVC resins, aluminum foil with heat-seal lacquer, and cyclic olefin polymer pellets. Single-source vulnerability concentrates in Germany's captive USP Type I tubular glass operations. Distribution runs through direct-to-pharmacy channels for specialty biologics and wholesaler networks for mass-market oral solids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ampoules and blister packaging market sits in early-cycle expansion as pre-filled polymer ampoules penetrate emergency medicine and ophthalmic applications previously locked to glass formats.
For Market Incumbents: Fortify backward integration into pharmaceutical-grade raw materials and expand cleanroom-integrated high-speed line capacity in Baden-Württemberg to defend against polymer ampoule substitution in trauma care. Prioritize certification investment for USP Chapter 1207 container closure integrity validation ahead of pharmacopeial revisions. For New Entrants and Emerging Players: Differentiate on multi-layer polyethylene barrier films for European distribution as ECHA PVC restrictions accelerate. Target India's domestic pharmaceutical sector where CDSCO quality mandates and PLI scheme incentives expand conversion capacity for export-grade generics. Pursue preferred manufacturer agreements with hospital systems consolidating procurement through direct-to-pharmacy distribution. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates spinning non-pharmaceutical film extrusion assets. Long-term viability over the next decade hinges on serialization-technology integration capabilities and barrier film qualification depth. Watch for inflection when EU MDR enforcement deadlines compress packaging line upgrade cycles beyond converter capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Sourcing | Captive furnace operations in Germany secure USP Type I supply against Indian second-source limitations. |
| Multi-Layer Barrier Film Qualification | Polyethylene alternatives to PVC meet REACH restrictions while maintaining moisture barriers below 0.5 g/m²/day. |
| Serialization-Technology Integration | FDA DSCSA and EU MDR mandates force retrofit of blister lines with printing and aggregation stations. |
| Pre-Filled Polymer Ampoule Scale-Up | Cyclic olefin polymer formats penetrate military medical procurement for field deployment weight reduction. |
| Direct-to-Pharmacy Distribution Partnerships | Hospital system consolidation elevates technical service capabilities as competitive differentiator in specialty biologics. |
Study Parameters
The analysis maps glass ampoules, plastic and aluminum blisters, and pre-filled polymer formats, each validated through packaging line engineers, pharmaceutical procurement managers, regulatory affairs specialists, and contract packaging executives. Primary interviews with these stakeholders combined secondary validation from FDA DSCSA guidance documents, EMA MDR implementation reports, ECHA restriction proposals, and USP chapter revision notices. Bottom-up and top-down triangulation cross-checked installed capacity data against end-user demand signals.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include packaging type, material grade, end-user application, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections incorporating pharmacopeial compliance timelines, serialization mandate enforcement schedules, and cold-chain logistics expansion rates.
Material uncertainties — regulatory acceleration on PVC phase-outs, furnace commissioning delays, and polymer ampoule breakage-risk validation — sit outside the modeled envelope. Forecasts reflect assumptions about compliance deadline adherence and qualification timeline norms. Revision becomes warranted when EU MDR enforcement intensity or ECHA restriction finalization crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Liquid Blister Pack Market
Blister Packaging
High Barrier Pharmaceutical Packaging Films for Blister Market
Blister Packaging
United States Blister Packaging Market
Blister Packaging
Blister Cards Market
Blister Packaging
North America Pharmaceutical Blister Packaging Market
Blister Packaging
Asia Pacific Pharmaceutical Blister Packaging Market
Blister Packaging
Carded Blister Packaging Market
Blister Packaging
Pharma Blister Packaging Machines Market
Blister Packaging
Global Cold Form Blister Packaging Market
Blister Packaging
Welded Blisters Market
Blister Packaging
North America Blister Packaging Market
Blister Packaging
PVC Blister Packaging Market
Blister Packaging
Blister Foil Market
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market
Blister Packaging
Holographic Blister Foil Market
Blister Packaging
Sliding Blister Packaging Market