
 Metal Cosmetic Packaging Market | 2026-2036
Metal Cosmetic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Cosmetic Packaging Market Outlook
Tool-and-die craftsmanship is collapsing across Western European packaging hubs, constraining capacity for precision metal forming. AptarGroup Inc. leverages its integrated aluminum extrusion capabilities to secure long-term contracts with prestige beauty brands. Crown Holdings Inc. anchors North American supply through captive steel-tinplate rolling operations. Silgan Holdings Inc. competes on cost by sustaining high-volume aerosol can output for mass-market hair care lines.
Metal cosmetic packaging comprises rigid containers fabricated from aluminum, steel, tinplate, or stainless steel through deep drawing, impact extrusion, or three-piece welding, engineered to protect volatile fragrance compounds and viscous emulsions from oxidation, UV degradation, and mechanical damage. Aluminum bottles lead value contribution due to lightweighting advantages and infinite recyclability credentials, while aerosol cans face structural pressure from propellant-phaseout regulations in multiple jurisdictions. Stainless steel jars occupy the fastest-growing niche as clean-beauty brands prioritize inert material contact surfaces and extended shelf stability for preservative-free formulations.
REACH restricts chromium VI in tinplate passivation layers, forcing European suppliers to migrate toward trivalent chromium or chrome-free alternatives. FDA color additive regulations under 21 CFR 73 and 74 govern anodized aluminum surface treatments for direct skin-contact applications, creating compliance bottlenecks for Asian exporters. Stakeholders must monitor evolving extended producer responsibility frameworks and alloy traceability requirements as decisive variables for supplier selection and capital allocation.
Market Dynamics
REACH compliance deadlines are compressing supplier qualification timelines across European aluminum extrusion networks, forcing fragrance houses to consolidate procurement around vertically integrated metal forming specialists with captive trivalent chromium passivation capabilities.
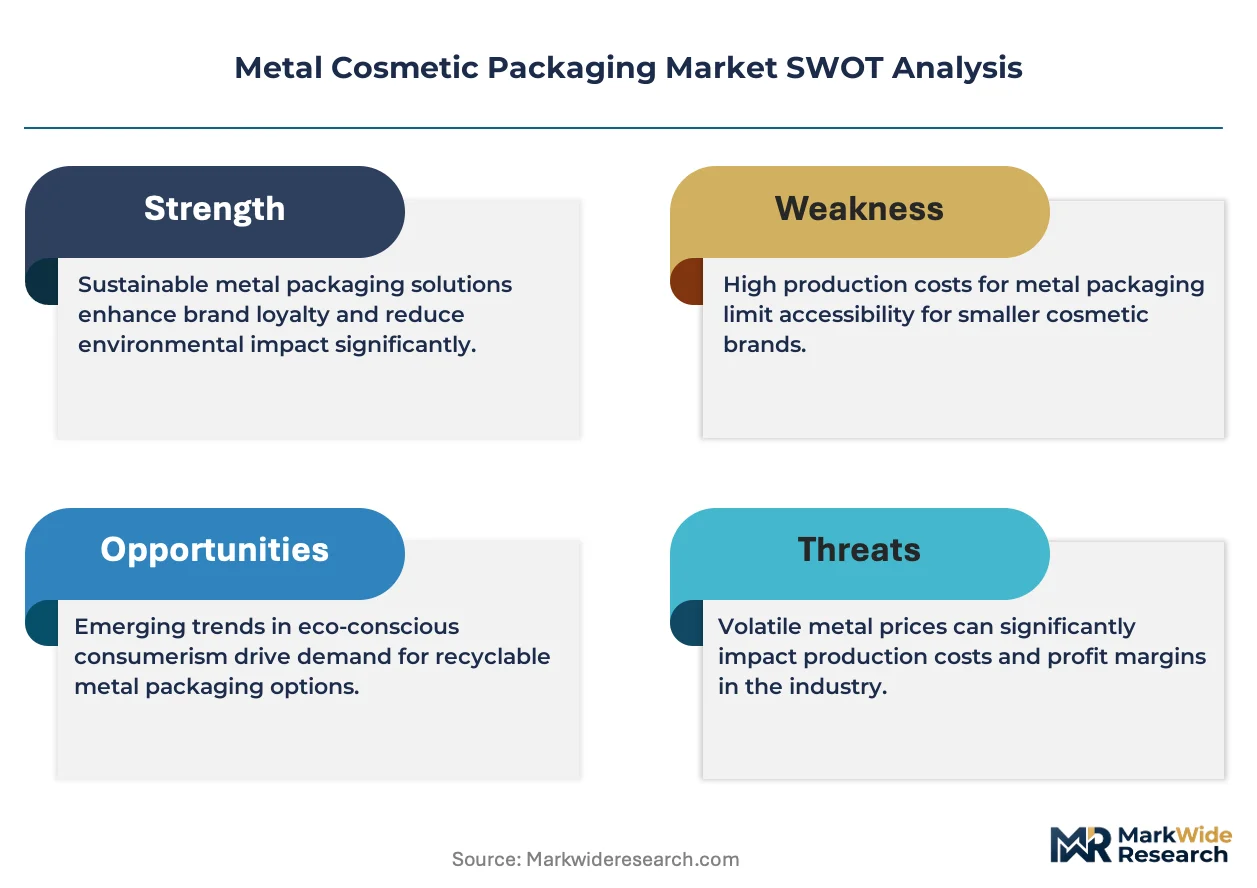
Growth Catalysts
- EU Green Deal packaging mandates:Refillable aluminum flacon requirements in France, Germany, and Italy are accelerating capital deployment into precision impact extrusion lines.
- Clean-beauty formulation chemistry:Preservative-free emulsions require inert stainless steel contact surfaces, opening premium jar applications for metal packaging converters.
- Extended Producer Responsibility frameworks:Germany's Verpackungsgesetz and France's AGEC law impose recyclability quotas that favor infinitely recyclable aluminum over polymer alternatives.
Market Restraints
- Aluminum alloy price volatility:LME aluminum futures swings above fifteen percent annually compress margin predictability for aerosol can manufacturers serving mass-market hair care.
- Tool-and-die craftsmanship attrition:Western European precision metal forming hubs face generational skill loss, constraining capacity expansion for deep-drawn cosmetic containers.
- Propellant-phaseout regulations:F-Gas Regulation restrictions on hydrofluorocarbon propellants threaten structural demand for traditional steel-tinplate aerosol formats.
Strategic Opportunities
- India personal care manufacturing:BIS certification alignment and CDSCO cosmetic regulations create entry pathways for aluminum bottle exporters serving Mumbai and Bangalore formulation clusters.
- Anodized color customization:FDA 21 CFR 73 and 74 compliance for direct skin-contact surface treatments enables premium differentiation in North American prestige fragrance.
- Digital printing convergence:UV-cured inkjet integration with metal deco lines permits batch-size-one customization for direct-to-consumer beauty brands.
Industry Challenges
- REACH SVHC documentation:Alloy traceability requirements demand supply chain digitization investments that mid-tier European converters struggle to fund.
- Chromium VI elimination timelines:Chrome-free passivation technology qualification delays risk contract losses for tinplate suppliers serving German cosmetic manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Cosmetic Packaging Market |
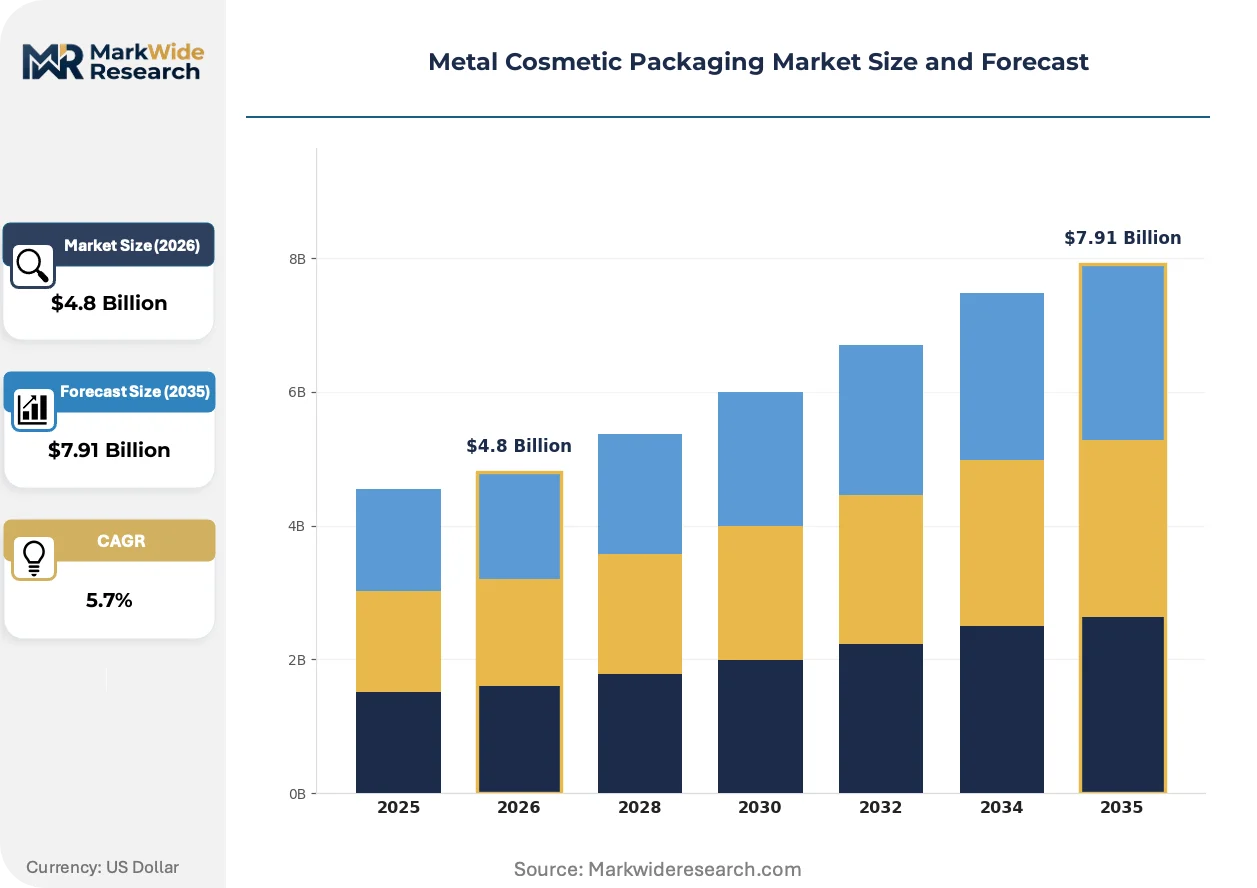
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tins, Aerosol Cans, Bottles, Jars Material: Aluminum, Steel, Tinplate, Stainless Steel Closure Type: Screw Caps, Press Caps, Flip Caps, Spouts Application: Face Products, Hair Products, Body Products, Fragrances |
| Companies Covered | AptarGroup Inc., Crown Holdings Inc., Silgan Holdings Inc., Albea S.A., Quadpack Industries, HCP Packaging, Libo Cosmetics Company Ltd, Ball Corporation, Anomatic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Cosmetic Packaging Market Strategic Shifts
Material science advances and regulatory chemistry mandates are rewriting specification sheets across aluminum, steel, and stainless steel packaging formats. The convergence of sustainability accounting and precision manufacturing is creating new capability thresholds for supplier survival.
Monobloc aluminum bottles with internal lacquer systems are decomposing the traditional glass-dominated prestige fragrance refill segment. L'Oréal and Estée Lauder procurement teams have accelerated aluminum flacon trials for 2026 fragrance launches. This transition is compressing demand for borosilicate glass molding capacity while expanding requirements for impact extrusion tooling with sub-micron surface finish control.
ECHA's 2024 restriction proposal on chromium VI in metal passivation layers forces immediate process migration across European tinplate rolling operations. German and Italian cosmetic packaging suppliers face eighteen-month qualification windows for trivalent chromium or silicon-based alternatives. Aerosol can manufacturers serving Southern European markets report the highest compliance cost exposure due to legacy chromium VI inventory and customer specification lag.
Beauty brands now mandate lot-level alloy provenance documentation as a procurement gate. Direct material traceability from bauxite smelter to finished container is replacing certificate-based compliance across French and German luxury houses. This behavioral shift is most visible in fragrance procurement, where LVMH and Kering sustainability audits now include upstream mining jurisdiction verification.
Metal Cosmetic Packaging Market Segmentation
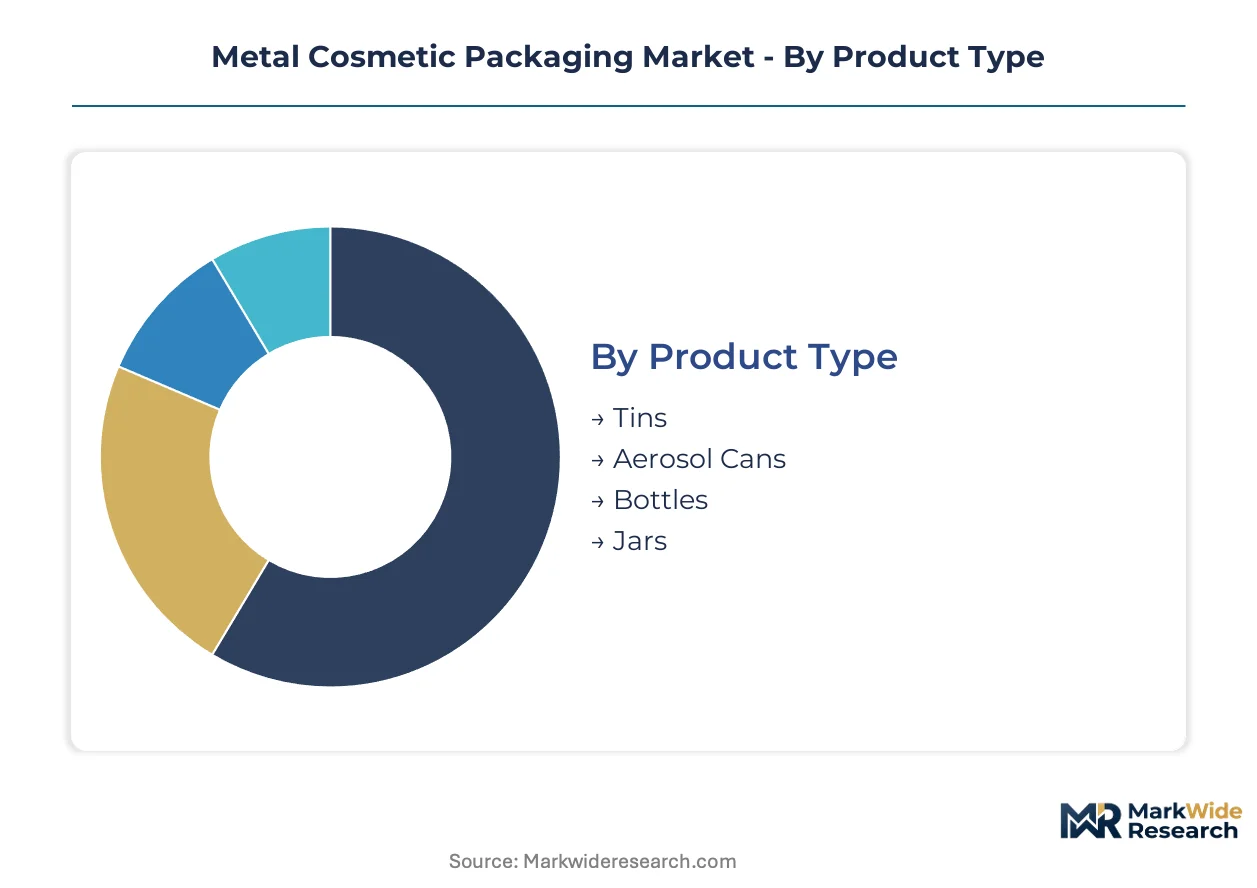
Metal cosmetic packaging specifications diverge sharply across product categories, with regulatory chemistry mandates and end-use performance requirements dictating material selection and forming processes. Each segmentation dimension carries distinct compliance burdens and margin structures that reshape supplier capabilities.
Product Type:
REACH substance restrictions and F-Gas Regulation propellant phaseouts create asymmetric compliance costs across rigid container formats, fragmenting competitive positioning by product type.
- Bottles:Monobloc aluminum construction via impact extrusion delivers sub-micron surface finish control for volatile fragrance compounds. L'Oréal and Estée Lauder procurement teams in France are accelerating aluminum flacon trials for prestige fragrance launches, displacing borosilicate glass molding capacity.
- Jars:Deep-drawn stainless steel or tinplate configurations protect viscous emulsions from oxidation. Clean-beauty brands in Germany prioritize inert contact surfaces for preservative-free formulations, opening premium applications for metal packaging converters.
- Aerosol Cans:Three-piece welded steel-tinplate formats face structural demand pressure from hydrofluorocarbon propellant restrictions under EU F-Gas Regulation.
- Tins:Shallow-drawn tinplate containers serve solid balm and pressed powder applications with lower barrier requirements than liquid formulations.
Established volume favors aerosol cans; emerging adoption favors bottles.
Material:
Alloy traceability mandates and extended producer responsibility frameworks are concentrating procurement around materials with verifiable circularity credentials.
- Aluminum:Infinite recyclability and lightweighting advantages dominate sustainability accounting for prestige brands. LVMH and Kering sustainability audits in France now require lot-level provenance documentation from bauxite smelter to finished container.
- Stainless Steel:Inert surface chemistry provides extended shelf stability for preservative-free emulsions. Italian clean-beauty manufacturers specify 316L grade for direct skin-contact applications.
- Tinplate:Steel substrate with tin coating faces chromium VI elimination timelines under ECHA restrictions, forcing migration to trivalent chromium or silicon-based passivation.
- Steel:Captive rolling operations anchor North American supply for high-volume aerosol can output serving mass-market hair care lines.
Procurement is shifting toward aluminum; stainless steel commands the steepest expansion trajectory.
Closure Type:
Dispensing precision requirements and child-safety mandates determine closure specification complexity across cosmetic applications.
- Screw Caps:Threaded aluminum or polypropylene-over-steel designs dominate fragrance flacon and hair care bottle applications requiring resealable containment.
- Press Caps:Aerosol actuation mechanisms face redesign pressure as F-Gas Regulation restricts hydrofluorocarbon propellants.
- Flip Caps:Hinged polypropylene closures on aluminum bottles serve body wash and lotion dispensing with single-hand operation.
- Spouts:Directional pour controls on oil and serum bottles demand precision metal forming for orifice dimension consistency.
Volume concentration sits with screw caps; functional differentiation favors spouts.
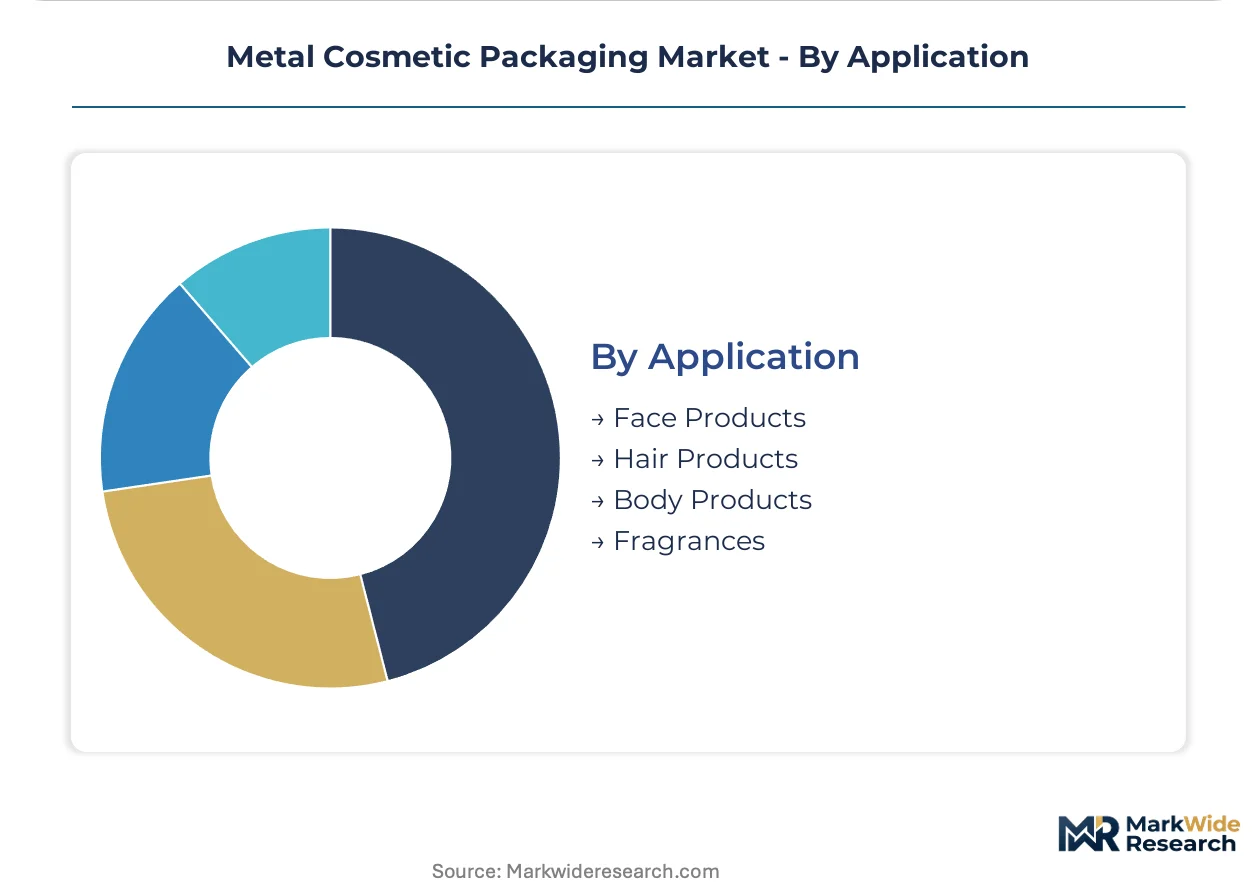
Application:
Formulation chemistry volatility and shelf stability requirements segment demand by end-use performance specifications.
- Fragrances:Volatile aromatic compounds require impermeable aluminum monobloc construction with internal lacquer systems. Refillable flacon mandates under France's AGEC law and Germany's Verpackungsgesetz accelerate metal substitution for glass.
- Hair Products:Aerosolized delivery formats for styling sprays and dry shampoos sustain steel-tinplate can demand despite propellant-phaseout headwinds.
- Face Products:Serum and essence bottles favor aluminum construction with anodized surface treatments compliant with FDA 21 CFR 73 and 74 for North American export.
- Body Products:Lotion and cream jars utilize tinplate or stainless steel depending on preservative content and shelf stability requirements.
Fragrance applications drive premium specification; hair products anchor mass-market volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance deadlines are compressing supplier qualification timelines across European aluminum extrusion networks, forcing fragrance houses to consolidate procurement around vertically integrated metal forming specialists with captive trivalent chromium passivation capabilities.
France
LVMH and Kering sustainability audits now mandate lot-level alloy provenance documentation from bauxite smelter to finished container. France's AGEC law imposes refillable packaging quotas that accelerate aluminum flacon substitution for borosilicate glass. The Grasse fragrance manufacturing cluster drives precision impact extrusion demand for 2026 prestige launches.
Germany
Germany's Verpackungsgesetz recyclability quotas favor infinitely recyclable aluminum over polymer alternatives for cosmetic applications. ECHA's chromium VI restriction forces eighteen-month qualification windows for trivalent chromium passivation migration. Stuttgart and Hamburg metal forming hubs face generational tool-and-die craftsmanship attrition that constrains capacity expansion.
Italy
Italian clean-beauty manufacturers specify 316L stainless steel for direct skin-contact preservative-free emulsion jars. The Lombardy and Piedmont packaging corridors concentrate deep-drawn tinplate and stainless steel forming operations. Southern European aerosol can manufacturers report highest compliance cost exposure from legacy chromium VI inventory.
United States
FDA 21 CFR 73 and 74 color additive regulations govern anodized aluminum surface treatments for direct skin-contact cosmetic applications. North American supply anchors through captive steel-tinplate rolling operations serving mass-market hair care aerosol demand. Greater Chicago and New Jersey industrial corridors concentrate metal deco and printing capabilities.
India
BIS certification alignment and CDSCO cosmetic regulations create entry pathways for aluminum bottle exporters serving Mumbai and Bangalore formulation clusters. Personal care manufacturing expansion in Maharashtra and Karnataka drives demand for screw-cap aluminum bottles in body wash and lotion segments. Domestic converters compete on cost for mass-market hair care aerosol can output.
Metal Cosmetic Packaging Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the metal cosmetic packaging value chain. The market structure consolidates around vertically integrated aluminum extrusion specialists, captive steel-tinplate rolling operations, and high-volume aerosol can manufacturers serving distinct tier requirements. Three archetypes dominate: precision impact extrusion specialists with sustainability credentials, scale-driven steel-tinplate converters, and diversified packaging conglomerates with cross-material portfolios. Competitive moves concentrate on backward integration into alloy supply and strategic partnerships with fragrance houses for refillable flacon development.
Among North American metal packaging conglomerates, AptarGroup Inc., Crown Holdings Inc., and Silgan Holdings Inc. exemplify the tiered competitive structure. AptarGroup represents the precision extrusion archetype with integrated aluminum capabilities serving prestige beauty procurement consolidation. Crown Holdings anchors the steel-tinplate segment through captive rolling operations. Silgan Holdings occupies the high-volume aerosol position competing on cost for mass-market personal care lines.
| Leading Market Players |
|---|
| AptarGroup Inc. |
| Crown Holdings Inc. |
| Silgan Holdings Inc. |
| Albea S.A. |
| Quadpack Industries |
| HCP Packaging |
| Libo Cosmetics Company Ltd |
| Ball Corporation |
| Anomatic Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between French fragrance houses and aluminum extrusion specialists lock in both REACH-compliant alloy supply and five-year price visibility against LME volatility. These arrangements concentrate procurement power among vertically integrated metal formers with captive trivalent chromium passivation, squeezing spot-market converters out of premium fragrance flacon supply.
Pricing Analysis
Price spreads between European and Indian aluminum bottle markets reflect compliance cost differentials under REACH versus BIS certification regimes. Three-tier pricing structure across premium, standard, and economy levels separates LVMH-grade lot-traceable aluminum from mass-market hair care tinplate and unbranded Asian exports. Pricing pressure stems from ECHA's chromium VI elimination timelines forcing accelerated passivation technology migration. Mass-market aerosol can manufacturers serving hair care lines exhibit highest price sensitivity; prestige fragrance houses prioritize sustainability credentialing over unit cost.
Supply Chain Analysis
Strategic stockpiling of aluminum alloy prevails among German and Italian converters facing eighteen-month qualification windows for chrome-free passivation alternatives. Supply concentrates in France, Germany, and Italy for precision impact extrusion; India and China anchor high-volume aerosol can output. Raw material dependencies include LME-traded aluminum ingot, tinplate coil from European rolling mills, and trivalent chromium chemicals. Single-source vulnerability sits with German tool-and-die craftsmen whose generational attrition constrains deep-drawn capacity expansion. Distribution runs through fragrance manufacturing clusters in Grasse, Stuttgart, and Lombardy for premium tiers; mass-market lines feed through Mumbai and Bangalore formulation plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: REACH compliance timelines and alloy traceability mandates create switching costs that lock fragrance houses into qualified supplier relationships for multi-year fragrance development cycles.
For Market Incumbents: Consolidate around backward integration into aluminum alloy supply and captive trivalent chromium passivation to defend against emerging Asian exporters with BIS-certified cost advantages. Prioritize capacity addition in France's Grasse corridor where AGEC law refillable mandates concentrate demand. Tool-and-die apprenticeship programs counter generational skill loss threatening deep-drawn jar output. For New Entrants and Emerging Players: Differentiate on anodized color customization compliant with FDA 21 CFR 73 and 74 for North American prestige fragrance exports rather than competing on cost in saturated European aluminum bottle supply. Target India's Maharashtra and Karnataka personal care manufacturing clusters where CDSCO regulations create entry pathways for certified aluminum bottle exporters. Pursue direct-to-consumer beauty brand partnerships requiring batch-size-one digital printing capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated aluminum extrusion specialists with REACH-compliant passivation and lot-level traceability systems already operational. Long-term viability hinges on sustainability audit readiness as LVMH and Kering procurement teams tighten upstream mining jurisdiction verification. Watch for inflection signals in ECHA restriction enforcement timelines that could accelerate chromium VI elimination and strand legacy tinplate inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive aluminum extrusion secures REACH-compliant material access against LME volatility and qualification delays. |
| Chrome-Free Passivation Migration | ECHA restriction compliance preserves European supplier eligibility for German and Italian cosmetic manufacturers. |
| Digital Printing Convergence | UV-cured inkjet integration enables batch-size-one customization for direct-to-consumer beauty brand contracts. |
| India Market Entry Certification | BIS alignment and CDSCO compliance unlock Mumbai and Bangalore formulation cluster procurement channels. |
| Tool-and-Die Apprenticeship Programs | Generational skill transfer counters capacity constraints in Western European precision metal forming hubs. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with fragrance procurement directors, aluminum extrusion plant managers, cosmetic formulation chemists, and metal packaging regulatory affairs specialists. Secondary validation drew from ECHA restriction proposals, FDA 21 CFR color additive filings, EU Green Deal packaging mandate texts, and French AGEC law implementation guidance. Customs data on aluminum alloy trade flows and SEC filings from packaging conglomerates provided volume triangulation. Bottom-up unit economics and top-down market sizing were reconciled across the analysis window.
Across the projection horizon, the analytical framework modeled demand by product type, material grade, closure mechanism, and application end-use with regional regulatory cluster overlays. CAGRs were derived from segment-level growth trajectory blending and input-output coefficient analysis. Forecast inputs included LME aluminum futures volatility assumptions, REACH SVHC documentation adoption curves, and fragrance house sustainability audit penetration rates.
Forecasts assume regulatory continuity in EU REACH, FDA color additive regimes, and India's BIS certification frameworks; material policy shifts would require re-modeling of supplier qualification timelines and alloy traceability cost structures. Practitioners should keep alternative scenarios live as ECHA enforcement intensity and F-Gas Regulation propellant phaseout deadlines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Middle East and Africa Cosmetic Packaging Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
US Personal Care Packaging Market
Cosmetic Packaging
Europe Cosmetic Packaging Market
Cosmetic Packaging
Beauty and Personal Care Packaging Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Lip Care Packaging Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Lotion Tubes Market
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
Cosmetic and Toiletry Containers Market
Cosmetic Packaging
Lip Gloss Tube Market
Cosmetic Packaging
Global Cosmetic Packaging Market
Cosmetic Packaging
Europe Plastic Cosmetic Packaging Market
Cosmetic Packaging
North America Cosmetic Packaging Market
Cosmetic Packaging
Plastic Cosmetic Packaging Market