
 United Kingdom Container Glass Market | 2026-2036
United Kingdom Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Container Glass Market Insights
Premium lightweight specifications is redrawing competitive boundaries across the United Kingdom container glass sector. Ardagh Group leverages its integrated furnace network to supply major beverage accounts with reduced-weight bottles. Beatson Clark specializes in pharmaceutical-grade amber glass, occupying a defensible niche against commodity producers. Encirc anchors the market through its large-scale Elton facility, which serves spirits and beer brands with high-volume output.
Container glass consists of silica sand, soda ash, limestone, and recycled cullet melted at approximately 1,500°C to form rigid, chemically inert vessels for liquid and solid storage. The material offers impermeability, UV protection, and infinite recyclability without quality degradation, making it indispensable for oxygen-sensitive contents. Bottles dominate volume throughput across UK manufacturing lines, while pharmaceutical vials command the strongest margin pools due to stringent purity certifications and low substitution risk. Jars sustain steady demand from premium food preserves and spreads, though growth rates trail beverage applications.
The UK Environment Agency enforces packaging waste recovery targets that elevate cullet collection and closed-loop recycling economics for domestic producers. BSI standards for glass container mechanical strength and thermal shock resistance shape product qualification protocols for food contact and pharmaceutical applications. Stakeholders must monitor how the UK Emissions Trading Scheme affects natural gas-fired furnace operating costs and whether electric melting pilots at Encirc and Ardagh achieve commercial scale.
Market Dynamics
The UK Environment Agency's tightening recycled content mandates are forcing furnace operators to reconfigure cullet supply chains and melting protocols. This regulatory pressure intersects with natural gas cost volatility under the UK Emissions Trading Scheme, compressing operating margins for Midlands-based manufacturers.
Growth Catalysts
- Packaging Waste Regulations:The UK Environment Agency's escalating recovery targets create closed-loop economics that favor domestic cullet processing over imported virgin materials.
- Spirits Premiumization:Super-premium and craft spirit brands are specifying lightweight decorated bottles to differentiate shelf presence while meeting carbon reduction commitments.
- Pharmaceutical Packaging:Amber glass demand from injectable drug manufacturers is accelerating due to European Medicines Agency stability requirements for light-sensitive biologics.
Market Restraints
- Natural Gas Dependency:Furnace operators face input cost volatility from UK Emissions Trading Scheme carbon pricing, which disproportionately affects continuous-batch melting operations.
- Cullet Supply Concentration:Quality-sorted recycled glass availability clusters around England's urban corridors, leaving Scottish and Welsh producers with higher logistics burdens.
- Aluminum Substitution:Lightweight aluminum bottles are capturing share in ready-to-drink cocktail segments where oxygen transmission tolerance permits material switching.
Strategic Opportunities
- Electric Melting Pilots:Grid-decarbonization trajectories position UK furnace operators to pioneer all-electric melting ahead of continental competitors.
- Pharmaceutical Expansion:Cell and gene therapy manufacturing growth in Oxford-Cambridge corridor creates demand for borosilicate vials with ultra-low extractable profiles.
- Deposit Return Schemes:Scottish and impending English deposit-return frameworks will structurally lower cullet collection costs for participating manufacturers.
Industry Challenges
- Furnace Rebuild Cycles:Eight-to-ten-year refractory rebuild timelines create capex cliffs that misalign with shorter regulatory compliance windows.
- Color-Sorting Precision:Amber-to-flint cullet contamination thresholds below 0.5% require optical sorting investments that smaller recyclers cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Container Glass Market |
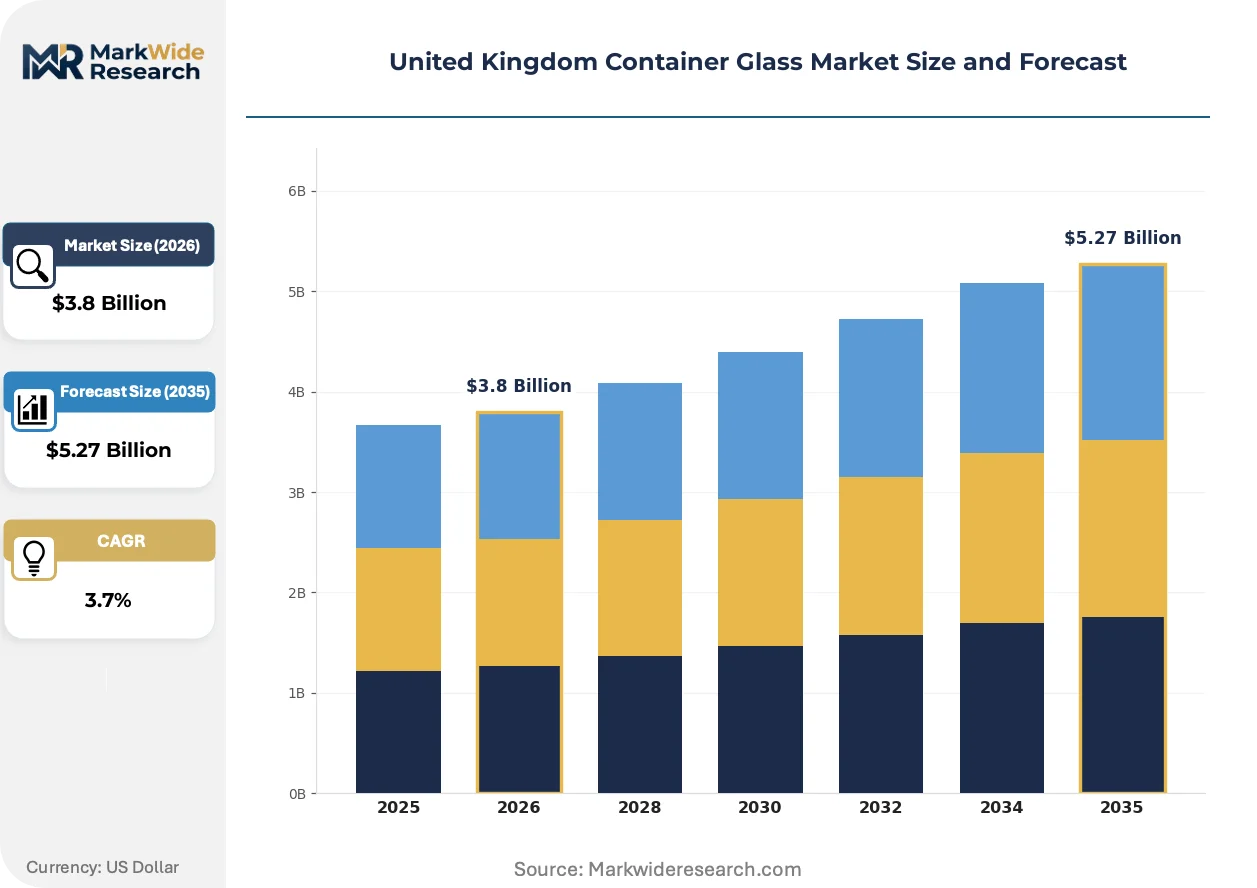
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.27 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End User: Food & Beverages, Pharmaceuticals, Cosmetics, Household Capacity: Small, Medium, Large, Extra Large Decoration Type: Screen Printing, Labeling, Etching, Coating |
| Companies Covered | Stoelzle Flaconnage Limited, Ardagh Group, O-I Glass Inc., Croxsons, Encirc, Verallia UK Limited, Gerresheimer UK Ltd, Beatson Clark, Vidrala S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Container Glass Market Trends and Innovations
Electrification of melting technology and digital decoration techniques are converging to redefine competitive capabilities across UK container glass manufacturing. These shifts intersect with tightening pharmaceutical purity standards and spirits brand carbon accounting requirements.
Plasma-assisted melting technology is decomposing the traditional natural gas furnace model by enabling batch electrification without full rebuild capital. Spirits manufacturers in Scotland are piloting plasma-heated lightweight bottles for export markets. This technology is decomposing the historical link between furnace scale and energy efficiency, permitting smaller flexible production runs.
The UK Environment Agency's packaging waste recovery targets are mandating minimum recycled content thresholds that escalate through 2030. Domestic producers must certify closed-loop cullet provenance to qualify for extended producer responsibility relief. Pharmaceutical amber glass faces the steepest compliance burden due to color-purity constraints that limit cullet incorporation rates.
Brand-level carbon accounting is reshaping procurement specifications across beverage categories. Major spirits houses are requesting product-level lifecycle assessments from Midlands suppliers, with Scope 3 emissions now weighted in supplier scorecards. This behavioral shift is most pronounced among London-headquartered premium brands with Science Based Targets initiative commitments.
United Kingdom Container Glass Market Segmentation
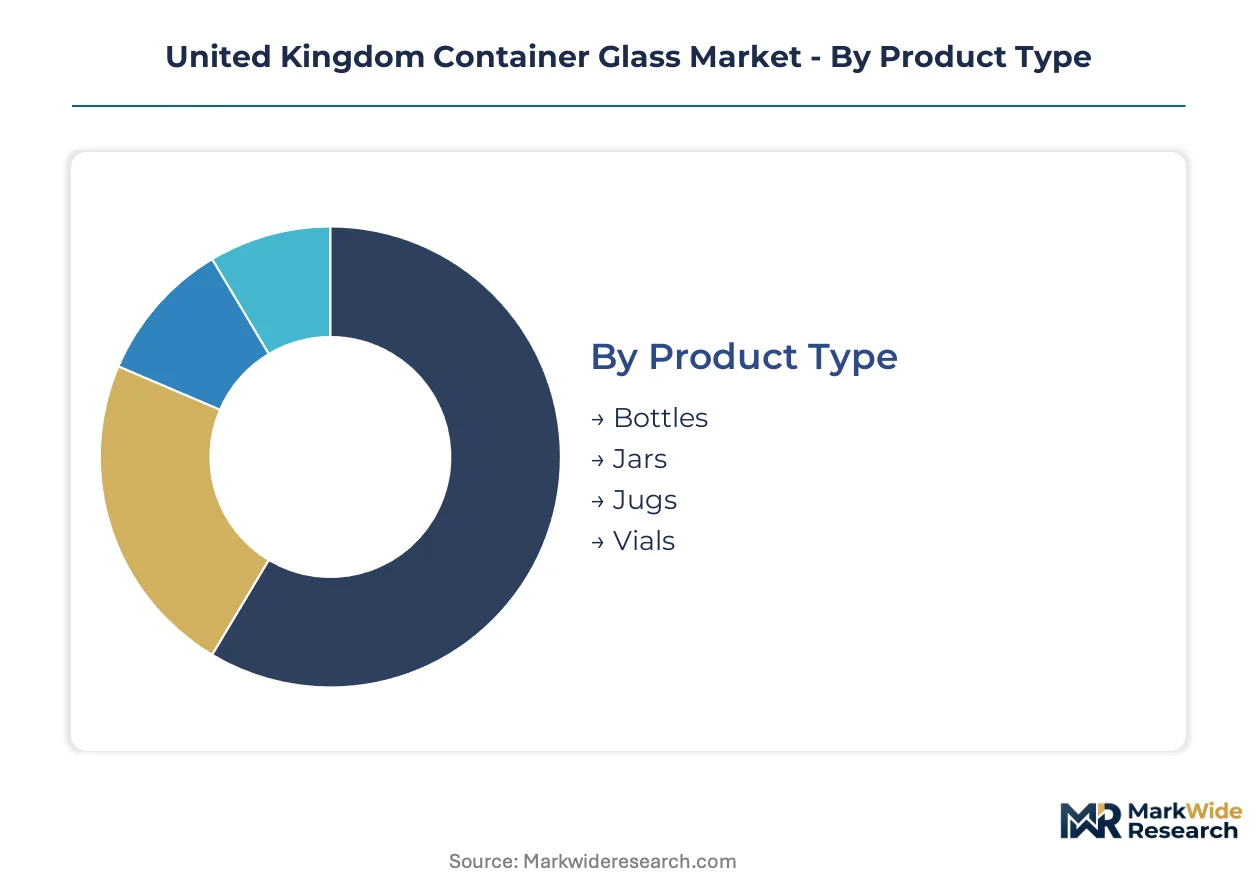
Container glass segmentation in the United Kingdom reflects divergent pressure points from substitute materials and regulatory compliance. Understanding how substitution threats concentrate across product configurations enables furnace operators to prioritize capital allocation and defend margin pools.
Product Type:
Aluminum and PET substitution pressures vary sharply across container formats, with beverage-facing segments bearing the heaviest competitive threat from lightweight alternatives.
- Bottles:Silica-soda-lime formulations dominate UK furnace output, with narrow-neck configurations optimized for carbonated and still beverages. Spirits brands in Scotland's distilling belt specify lightweight decorated bottles to meet Science Based Targets initiative commitments while resisting aluminum incursion in premium positioning.
- Jars:Wide-mouth vessels with continuous-thread finishes serve preserves, spreads, and condiments. Premium food manufacturers in England's Midlands specify heavier wall sections for tactile differentiation, though private-label retailers are piloting PET alternatives for economy-tier positioning.
- Jugs:Large-format containers with handle attachments accommodate bulk liquid dispensing. Industrial chemical and food service applications in northern England sustain demand despite limited growth.
- Vials:Small-diameter pharmaceutical containers with controlled wall thickness and extractable profiles. Injectable drug manufacturers along the Oxford-Cambridge corridor specify amber and borosilicate grades where EMA stability requirements eliminate substitution risk.
Bottles retain volume leadership across UK manufacturing lines; vials hold the steepest expansion curve amid biologics manufacturing growth.
End User:
Regulatory stringency and oxygen sensitivity requirements create tiered substitution barriers across customer verticals.
- Food & Beverages:The largest demand pool spans beer, spirits, wine, sauces, and preserves. Carbonated soft drink bottlers face acute PET and aluminum competition, while premium spirits brands leverage glass for shelf differentiation and carbon accounting compliance.
- Pharmaceuticals:EMA light-stability and extractable regulations mandate amber and borosilicate glass for injectable and oral solid dosages. Cell and gene therapy manufacturing expansion in southern England drives borosilicate vial demand with ultra-low contamination thresholds.
- Cosmetics:Fragrance and skincare brands specify heavy-wall flint bottles for premium positioning. Indie beauty brands are testing aluminum and post-consumer recycled PET for sustainability messaging, pressuring mid-tier glass specifications.
- Household:Cleaning product and candle containers face commodity competition from HDPE and tinplate. Private-label concentration in UK retail channels favors lower-cost substitutes.
Food & Beverages commands absolute volume; Pharmaceuticals is climbing the fastest on biologics packaging demand.
Capacity:
Scale economies and logistics cost structures segment furnace output by fill volume.
- Small:Sub-100ml formats for pharmaceuticals, spirits miniatures, and sample cosmetics. High per-unit decoration costs and premium positioning resist substitution despite higher manufacturing complexity.
- Medium:100ml-500ml range covering standard wine, spirits, and sauce bottles. This segment faces the most intense aluminum bottle competition in ready-to-drink cocktail applications.
- Large:500ml-1.5L containers for wine, beer, and bulk food preserves. Logistics efficiency favors domestic production for UK supermarket private-label programs.
- Extra Large:Above 1.5L formats for food service, industrial, and specialty beverage applications. Limited substitution pressure due to low volume and handling requirements.
Medium capacity maintains shipment volume dominance; Small capacity is gaining share fastest on pharmaceutical and premium spirits miniaturization.
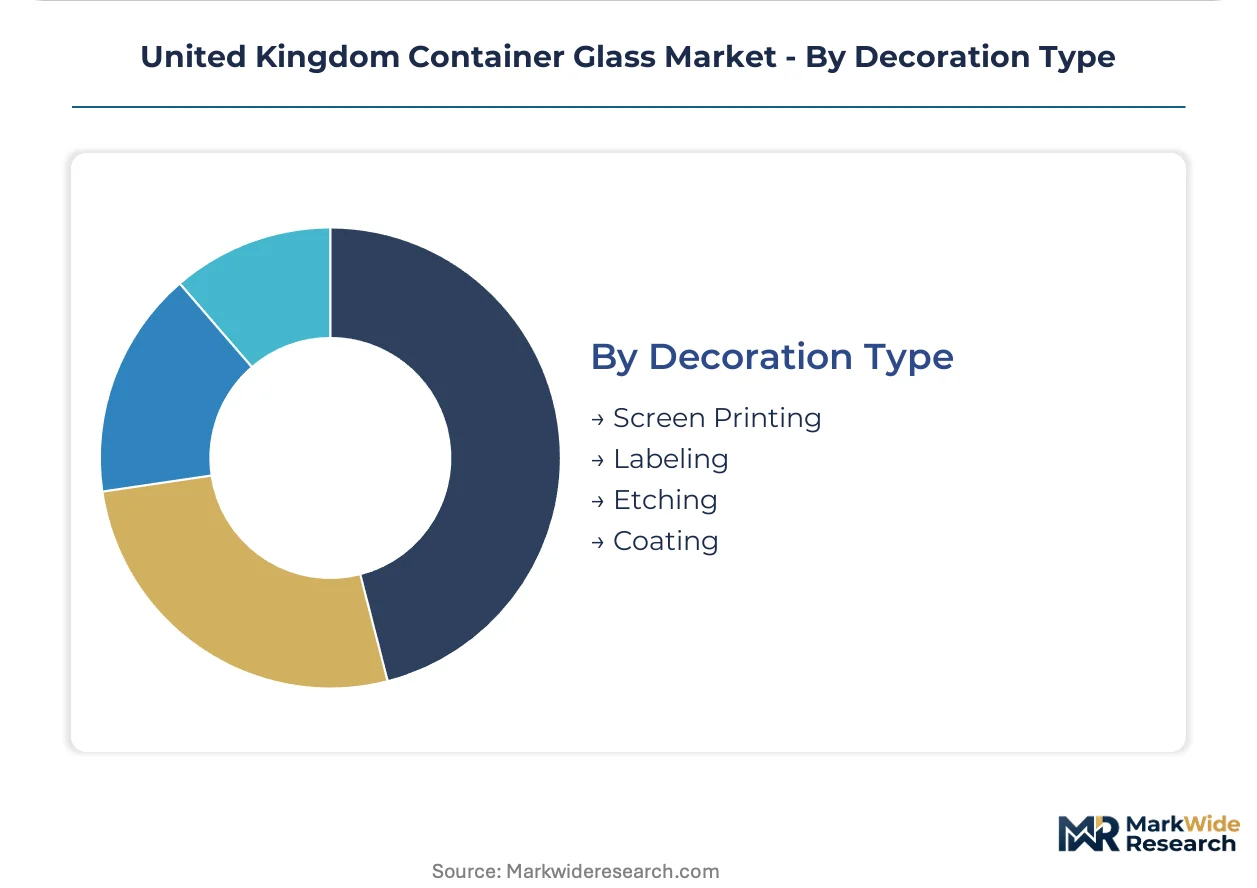
Decoration Type:
Brand differentiation investments concentrate in techniques that carbon accounting frameworks can quantify and communicate.
- Screen Printing:Direct ceramic ink application enables complex multi-color designs with durability through washing and reuse cycles. Scottish spirits brands specify screen-printed lightweight bottles to eliminate label substrate weight from Scope 3 calculations.
- Labeling:Pressure-sensitive and cut-and-stack paper or film substrates remain standard for mid-tier beverage and food applications. Paper label supply chain decarbonization is becoming a procurement scoring factor.
- Etching:Acid or laser surface treatment creates permanent matte or textured effects for ultra-premium positioning. Limited volume but high margin contribution in gift and limited-edition releases.
- Coating:Organic and metallic spray coatings enable color shifting and protective barrier properties. UV-curable coating chemistry is evolving to meet UK Environment Agency volatile organic compound restrictions.
Labeling retains volume leadership across UK container glass decoration; Screen Printing is expanding most quickly on carbon reduction-driven specification changes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom container glass market maintains a modest export surplus in specialty pharmaceutical and premium spirits formats, though bulk beverage containers face competitive pressure from European imports. Regional production clusters align with historic industrial corridors and proximate customer bases.
Midlands
England's central manufacturing corridor hosts the densest concentration of natural gas-fired furnaces serving beer and spirits brands. The UK Environment Agency's packaging waste regulations enforce escalating recycled content thresholds that operators here must integrate into continuous-batch protocols. Birmingham and Sheffield anchor this cluster, with Encirc's Elton facility supplying high-volume output to major beverage accounts.
Scotland
Scottish distilleries generate concentrated demand for lightweight decorated bottles to meet Science Based Targets initiative carbon commitments. The Scottish Government's deposit return scheme creates structural advantages for domestic cullet collection versus English producers. Glasgow and Edinburgh distilling belts source specialty flint and amber glass from Midlands suppliers, though logistics costs elevate landed prices.
North England
Traditional glassmaking heritage centers in Yorkshire and Lancashire sustain mid-scale furnace operations for food jars and industrial containers. The UK Emissions Trading Scheme disproportionately burdens older natural gas infrastructure common in this sub-region. Sheffield retains specialized capability for pharmaceutical-grade amber glass, serving northern England's generic drug manufacturing base.
Wales
Welsh container glass consumption concentrates in food and beverage packaging with limited domestic furnace capacity. Cullet supply constraints force Welsh bottlers to source pre-sorted recycled glass from England's urban collection networks. Cardiff and Newport distribution hubs face higher inbound logistics costs that compress margins on commodity glass categories.
London and Southeast
Brand headquarters concentration in London drives specification-setting for premium spirits and cosmetics packaging. Procurement teams at Science Based Targets initiative signatories weight Scope 3 emissions in supplier scorecards. The absence of local furnace capacity forces complete reliance on Midlands and continental European supply chains for all container glass categories.
United Kingdom Container Glass Market Competitive Landscape
Concentration sits with integrated multinational groups operating large-scale furnace networks alongside specialized domestic producers serving niche pharmaceutical and premium beverage segments. Three archetypes define competitive positioning: global packaging conglomerates with UK manufacturing assets, mid-scale domestic specialists leveraging technical differentiation, and European importers competing on commodity beverage formats. Capacity expansion and lightweight specification development represent the dominant competitive moves as carbon accounting reshapes procurement criteria.
Among UK-based specialists, Beatson Clark occupies a position exemplifying pharmaceutical-grade technical capability, while Encirc anchors the scale-driven tier through its large-volume furnace operations. Ardagh Group represents the integrated multinational archetype with network advantages across multiple European production sites. These three companies illustrate how competitive positioning stratifies between commodity scale, technical specialization, and continental network reach.
| Leading Market Players |
|---|
| Stoelzle Flaconnage Limited |
| Ardagh Group |
| O-I Glass Inc. |
| Croxsons |
| Encirc |
| Verallia UK Limited |
| Gerresheimer UK Ltd |
| Beatson Clark |
| Vidrala S.A. |
| Others |
Pricing and Supply Chain Analysis
The UK Environment Agency's packaging waste regulations gate both supplier qualification and price differentiation simultaneously, mandating closed-loop cullet provenance that separates certified domestic producers from import-dependent competitors. Premium spirits brands now weight Scope 3 emissions in supplier scorecards, compressing margins for Midlands furnace operators unable to document recycled content thresholds.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across UK container glass procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with pharmaceutical amber glass commanding the strongest position due to EMA stability requirements. Cost compression in commodity beverage tiers is intensifying because aluminum substitution in ready-to-drink segments forces defensive pricing. Private-label retailers exhibit highest price sensitivity, while injectable drug manufacturers show least sensitivity due to low substitution risk.
Supply Chain Analysis
Port congestion on North Sea trade lanes elevates inbound logistics costs for Scottish and Welsh producers sourcing pre-sorted cullet from England's urban collection networks. Supply concentrates in England's Midlands manufacturing corridor, with secondary dependence on continental European specialty glass imports. Raw material feeds draw from silica sand deposits in Cheshire, soda ash from synthetic production, and recycled cullet from England's deposit return schemes. Single-source vulnerability sits with natural gas supply for continuous-batch furnace operations. Distribution runs through beverage brand consolidation centers and pharmaceutical cold-chain logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK container glass market sits at a platform-economics inflection where deposit return scheme interoperability between Scottish and English frameworks will restructure cullet collection economics and supplier access.
For Market Incumbents: Shield pharmaceutical-grade amber glass margins through backward integration into optical sorting technology that maintains color-purity thresholds below 0.5% contamination. Fortify Midlands furnace positions against electric melting disruption by piloting plasma-assisted batch electrification ahead of UK Emissions Trading Scheme carbon price escalations. Prioritize certification investment for closed-loop provenance documentation to qualify for extended producer responsibility relief. For New Entrants and Emerging Players: Service-layer gaps in borosilicate vial manufacturing for Oxford-Cambridge cell and gene therapy corridors offer the most penetrable white-space target. Specialty pharmaceutical packaging commands pricing power that commodity beverage glass lacks. Target geographic expansion into Welsh and Scottish markets where cullet supply constraints disadvantage incumbent logistics networks. Pursue direct partnerships with biologics CDMOs rather than competing for established spirits brand accounts. For Investors and Strategic Acquirers: The UK Emissions Trading Scheme's trajectory toward full auctioning reshapes the acquisition landscape, favoring targets with electric melting pilot programs or grid-decarbonization-advantaged locations. Five-to-ten year viability hinges on furnace operators' capex flexibility to align eight-to-ten year refractory rebuild cycles with shorter regulatory compliance windows. Target acquisition archetype: mid-scale domestic specialists with pharmaceutical certification and undeveloped electric melting capabilities. Monitor Scottish deposit return scheme participation rates as inflection indicator for structural cullet cost advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Melting Pilot Scale-Up | Grid-decarbonization positions UK operators ahead of continental competitors on Scope 3 compliance. |
| Pharmaceutical Certification Investment | EMA stability requirements for light-sensitive biologics create defensible margin pools in amber glass. |
| Backward Integration into Cullet Sorting | Optical sorting capability secures closed-loop provenance for UK Environment Agency compliance relief. |
| Lightweight Specification Development | Science Based Targets initiative commitments from London-headquartered brands drive procurement specification changes. |
| Deposit Return Scheme Participation | Scottish and impending English frameworks structurally lower collection costs for participating manufacturers. |
Research Methodology
Operator-level perspectives from furnace plant managers, spirits brand procurement directors, pharmaceutical packaging engineers, and cullet collection network coordinators anchored the qualitative base. Primary fieldwork combined with secondary validation from UK Environment Agency regulatory filings, British Standards Institution certification databases, and trade flow records from HM Revenue and Customs. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across the analysis window.
Sensitivity analysis framed the quantitative approach, modeling product type, end-user vertical, capacity tier, and decoration technology as core segmentation dimensions. CAGRs derived from weighted average of historical trajectory and forward-looking regulatory scenario analysis. Forecast inputs incorporated UK Emissions Trading Scheme carbon price assumptions and electric melting technology adoption curves specific to container glass furnace operations.
Material uncertainties — natural gas price volatility, electric melting pilot commercialization timelines, and deposit return scheme implementation scope — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and brand-level carbon accounting adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Netherlands Container Glass Market
Glass Packaging
Glass Logistics Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Ecuador Container Glass Market
Glass Packaging
Glass Bottles Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Glass Packaging Market
Glass Packaging
Argentina Container Glass Market
Glass Packaging
Glass Growlers Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Glass Frosting for Packaging Market
Glass Packaging
Spain Container Glass Market
Glass Packaging
Africa Glass Bottles and Containers Market