
 Blister Packs Market | 2026-2036
Blister Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Blister Packs Market Outlook
Packaging engineering talent is rotating toward thermoforming and barrier-coating specializations as substrate complexity rises. Amcor plc leverages its integrated film-to-packaging platform to sustain cost leadership in high-barrier pharmaceutical formats. Sonoco Products Company anchors North American supply through rigid paperboard-blister hybrids. WestRock Company competes on recycled-content specifications that meet emerging sustainability procurement criteria.
Blister packs are thermoformed or cold-formed cavity-and-lidding structures, typically comprising PVC, PVDC, alu-foil, or paperboard substrates sealed with heat or adhesive to create individual unit-dose compartments. They protect moisture-sensitive tablets, capsules, and medical devices from oxidation, light, and mechanical damage while enabling precise dosing verification. PVC dominates current pharmaceutical volumes due to cost and process familiarity, though alu-foil laminates command premium positioning in tropical-climate markets where moisture vapor transmission rates must fall below specific thresholds. Child-resistant blisters represent the fastest-growing packaging type segment as WHO patient-safety protocols and DEA scheduling requirements tighten access controls for opioid and pediatric formulations.
FDA 21 CFR Part 211 cGMP guidelines and EU MDR technical documentation requirements shape validation protocols for sterile barrier integrity and seal-strength testing. EPA and REACH restrictions on chlorinated plasticizers are forcing reformulation timelines for PVC suppliers serving multinational pharmaceutical clients. Stakeholders must monitor evolving EPR legislation in Germany, France, and California, where extended producer responsibility fees increasingly differentiate total cost of ownership across substrate choices and recycling infrastructure readiness.
Market Dynamics
EU F-Gas Regulation and the EU Green Deal are forcing pharmaceutical packaging suppliers to abandon chlorinated substrates ahead of recyclability mandates, compressing reformulation timelines and rewiring raw-material procurement.
Growth Catalysts
- Unit-dose adherence packaging:Chronic disease management programs in Germany and France are expanding patient-compliance packaging across cardiovascular and diabetes portfolios.
- REACH restrictions on plasticizers:ECHA-driven phase-outs of phthalate additives are accelerating migration to alu-foil and paperboard laminates in pediatric and geriatric formulations.
- Child-resistant format demand:DEA scheduling requirements for opioid packaging and WHO patient-safety protocols are tightening access-control specifications across North American and European markets.
Market Restraints
- Aluminum price volatility:Cold-formed alu-foil barrier laminates face input cost swings that compress margin structures for tropical-climate pharmaceutical exports.
- PVC supply concentration:Chlorinated substrate production clusters in China create geopolitical exposure for multinational pharmaceutical clients with ESG procurement criteria.
- Recycling infrastructure gaps:Multi-layer barrier films lack compatible waste-stream processing in most European and North American municipal systems, limiting circular-economy claims.
Strategic Opportunities
- Paperboard-blister hybrids:Rigid fiber-based cavity structures paired with heat-seal coatings offer pharmaceutical brands a recyclable alternative to PVC for moisture-stable oral solids.
- Indian contract manufacturing expansion:CDSCO-aligned packaging facilities in Gujarat and Maharashtra are capturing export volumes from European generic-drug sponsors seeking cost-advantaged sourcing.
- California EPR legislation:Extended producer responsibility fee structures favor substrates with established recycling pathways, rewarding early movers on mono-material and fiber-based formats.
Industry Challenges
- Thermoforming and barrier-coating skill scarcity:Packaging engineering talent pools are insufficient for substrate complexity escalation, particularly in high-barrier coating deposition and cavity-form precision.
- Validation timeline compression:FDA 21 CFR Part 211 cGMP and EU MDR technical documentation requirements are extending seal-integrity and sterile-barrier qualification cycles for new material introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blister Packs Market |
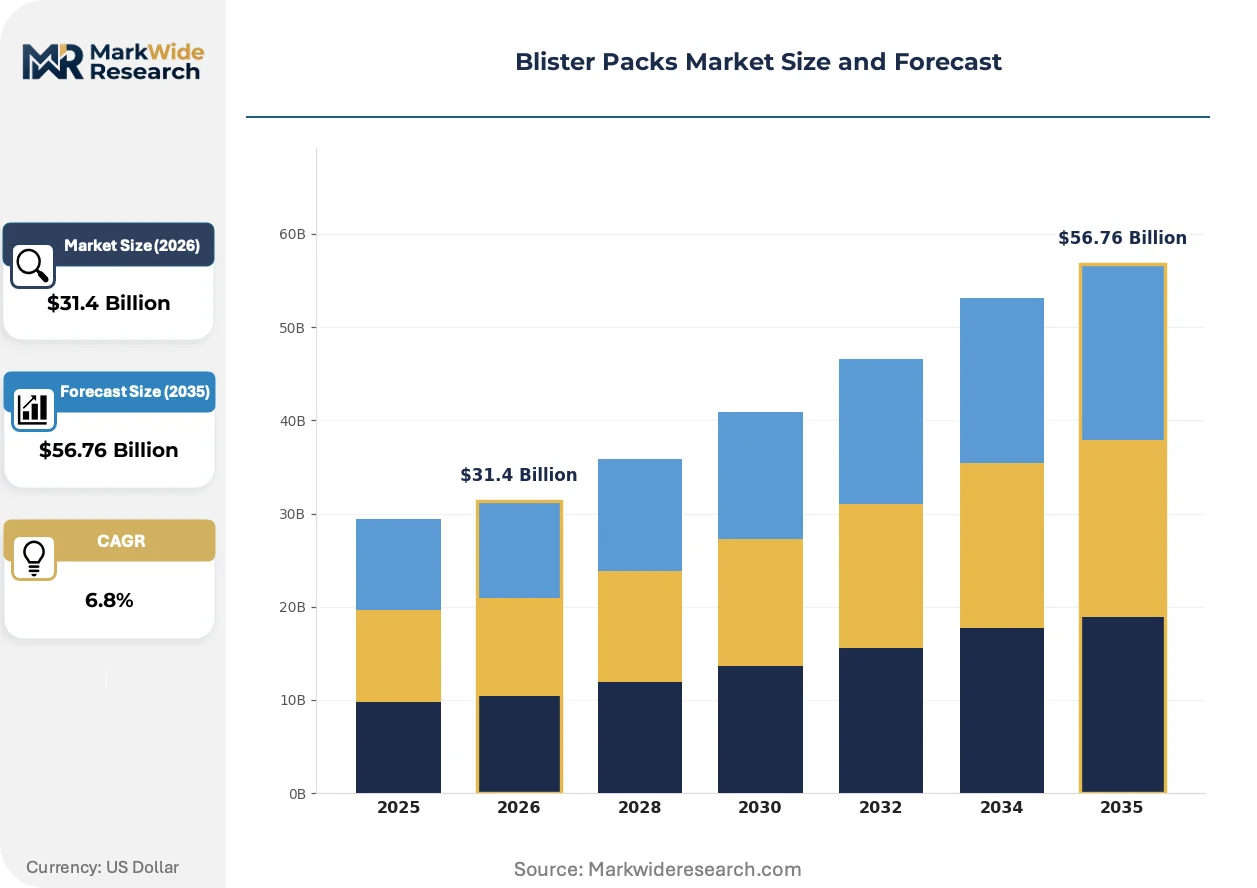
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $56.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, PVDC, Alu-Foil, Paperboard End User: Pharmaceutical Companies, Consumer Goods, Medical Device Manufacturers, Nutraceuticals Packaging Type: Standard Blisters, Child Resistant Blisters, Thermoformed Blisters, Customized Blisters Technology: Die-Cut, Form-Fill-Seal, Flexographic Printing, Injection Molding |
| Companies Covered | Amcor plc, Sonoco Products Company, WestRock Company, Constantia Flexibles, WINPAK Ltd., Klöckner Pentaplast, UFlex Limited, Tekni-Plex, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blister Packs Market Strategic Shifts
Active substitution of incumbent substrates, tightening pharmacovigilance protocols, and compressed pharmaceutical procurement cycles are reconfiguring how packaging value is captured and certified.
Polyethylene furanoate (PEF) bio-based barrier films are displacing conventional PVDC-coated PVC in moisture-sensitive oral solid dosage applications. Mid-tier generic manufacturers in Germany and Switzerland are piloting PEF lidding at commercial scale. The structural shift is compressing incumbent suppliers' pricing power in premium barrier segments.
The EU Green Deal's packaging waste directive and F-Gas Regulation are mandating fluorinated gas phase-outs and recyclability targets for pharmaceutical primary packaging. Industrial consequence includes forced reformulation of cold-form alu-foil adhesives and lidding sealants. High-barrier tropical-market formats face the steepest compliance cost escalation.
Consolidated buying by pharmacy benefit managers and hospital procurement alliances is compressing supplier switching cycles and unbundling technical service from material supply contracts. Traditional distributor-led sourcing in France and Italy is yielding to direct pharmaceutical-manufacturer negotiations. The behavior shift is most visible in oncology and rare-disease portfolios where batch-size flexibility commands premium positioning.
Blister Packs Market Segmentation
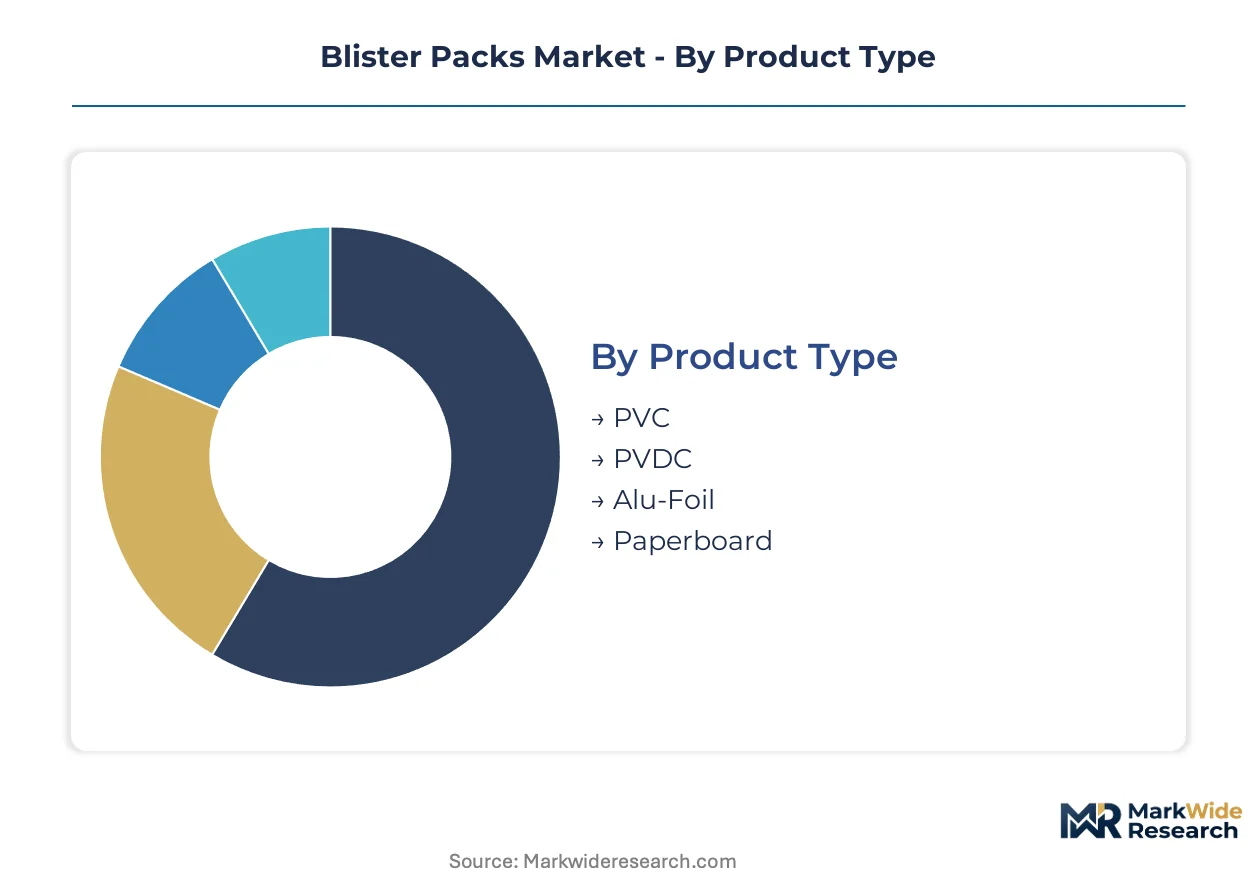
Segmentation in blister packaging reveals how substrate selection, regulatory requirements, and end-use specifications channel demand toward distinct manufacturing capabilities and certification standards. Pharmaceutical compliance mandates and sustainability procurement criteria are fragmenting what was historically a commodity supply base into specialized tier structures.
Product Type:
PVC and alu-foil formats flow through distinct procurement channels, with chlorinated substrates dominating high-volume generic contracts and barrier laminates capturing tropical-climate and pediatric portfolios.
- PVC:Thermoformed polyvinyl chloride cavities sealed with heat-activated lidding dominate current pharmaceutical volumes due to process familiarity and line-speed economics. Demand concentrates in German contract packaging networks serving domestic cardiovascular and diabetes portfolios where unit-dose adherence programs are expanding.
- Alu-Foil:Cold-formed aluminum barrier laminates deliver moisture vapor transmission rates below critical thresholds for oxidation-sensitive formulations. Tropical-climate exports from Indian CDSCO-aligned facilities in Gujarat and Maharashtra are driving specification tightening as European sponsors seek cost-advantaged sourcing with proven barrier integrity.
- PVDC:Polyvinylidene chloride coatings on PVC substrates provide intermediate barrier performance for moisture-stable oral solids.
- Paperboard:Rigid fiber-based cavity structures paired with heat-seal coatings offer recyclable alternatives meeting California EPR legislation and EU Green Deal recyclability targets.
PVC dominates installed base. Alu-foil is where expansion concentrates.
End User:
Customer-type segmentation maps directly to validation burden and batch-size flexibility, with pharmaceutical manufacturers demanding cGMP documentation and consumer goods buyers prioritizing line-speed compatibility.
- Pharmaceutical Companies:FDA 21 CFR Part 211 and EU MDR technical documentation requirements shape sterile barrier integrity testing and seal-strength validation protocols. Chronic disease management programs in France and Germany are expanding patient-compliance packaging specifications across cardiovascular and diabetes portfolios.
- Consumer Goods:High-speed form-fill-seal compatibility and shelf-impact graphics drive substrate selection for electronics and personal care applications.
- Medical Device Manufacturers:Sterile barrier requirements and ISO 11607 compliance dictate material qualification timelines for device containment applications.
- Nutraceuticals:Moisture-sensitive probiotic and omega-3 formulations are migrating toward alu-foil and high-barrier paperboard laminates as REACH restrictions on phthalate plasticizers tighten.
Pharmaceutical companies absorb the highest validation costs. Nutraceuticals are climbing the fastest as wellness positioning demands premium barrier claims.
Packaging Type:
Format selection tracks regulatory enforcement intensity, with access-control specifications tightening fastest in jurisdictions with active pharmacovigilance mandates.
- Child Resistant Blisters:Push-through and peel-open mechanisms meeting DEA scheduling requirements for opioid packaging and WHO patient-safety protocols. German and Swiss mid-tier generic manufacturers are piloting commercial-scale production as access-control specifications tighten across North American and European markets.
- Standard Blisters:Conventional cavity-and-lidding structures for non-controlled substances where cost minimization dominates procurement criteria.
- Thermoformed Blisters:Heat-shaped cavity structures produced on continuous roll-fed equipment for high-volume oral solid dosage applications.
- Customized Blisters:Bespoke cavity geometries and lidding configurations for rare-disease portfolios where batch-size flexibility commands premium positioning.
Standard blisters dominate installed base. Child-resistant formats are where expansion concentrates.
Technology:
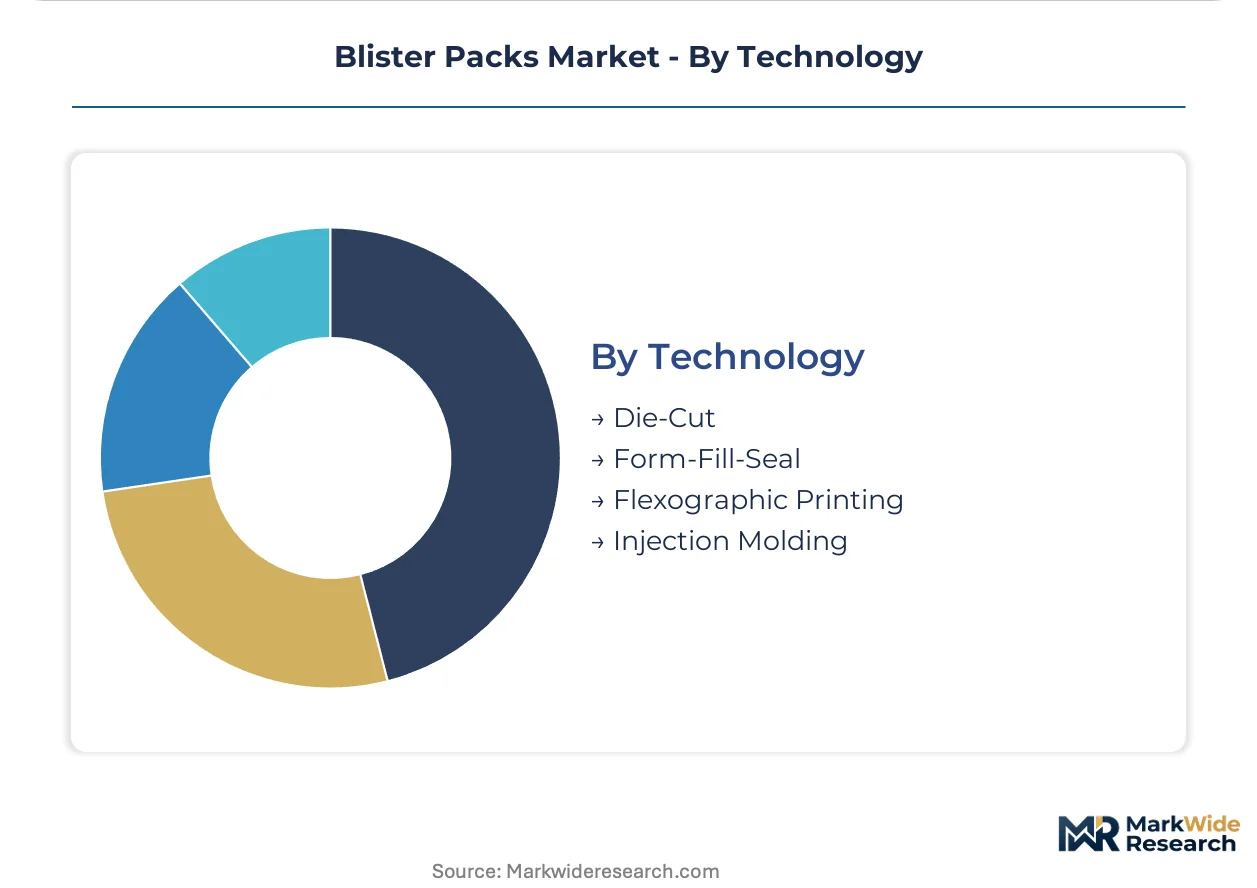
Process technology segmentation separates capital-intensive continuous operations from flexible batch production, with equipment selection locking in substrate compatibility and changeover economics.
- Form-Fill-Seal:Integrated thermoforming, product placement, and lidding sealing on continuous roll-fed systems. Indian contract manufacturing expansion in Maharashtra and Gujarat is concentrating demand for high-speed equipment serving European generic-drug sponsors.
- Die-Cut:Precision cavity punching for paperboard-blister hybrids and fiber-based formats gaining share under EU Green Deal packaging waste directives.
- Flexographic Printing:Water-based and UV-cured ink systems for lidding graphics compliance with EPA and REACH restrictions on solvent emissions.
- Injection Molding:Rigid cavity production for medical device containment requiring dimensional precision beyond thermoforming tolerances.
Form-fill-seal dominates installed base. Die-cut is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 211 cGMP guidelines anchor pharmaceutical packaging demand in the United States, while ECHA REACH restrictions and EU Green Deal mandates accelerate substrate transitions across European manufacturing networks. Contract packaging clusters in Germany, India, and Switzerland are capturing volume shifts as sponsors seek regulatory-aligned production capacity.
United States
DEA scheduling requirements for opioid packaging and WHO patient-safety protocols are tightening access-control specifications across pharmaceutical manufacturing. EPA restrictions on chlorinated plasticizers are forcing reformulation timelines for PVC suppliers serving multinational clients. New Jersey and Pennsylvania contract packaging corridors are absorbing expanded unit-dose adherence packaging volumes for cardiovascular portfolios.
Germany
EU F-Gas Regulation and packaging waste directive mandates are compressing reformulation timelines for cold-form alu-foil adhesives. Extended producer responsibility fee structures under national EPR legislation favor substrates with established recycling pathways. Bavaria and North Rhine-Westphalia contract packaging networks serve both domestic and export pharmaceutical volumes for chronic disease management programs.
India
CDSCO-aligned packaging facilities are capturing export volumes from European generic-drug sponsors seeking cost-advantaged sourcing with proven barrier integrity. Tropical-climate pharmaceutical exports from Gujarat and Maharashtra are driving specification tightening for moisture vapor transmission rates. Mumbai and Ahmedabad thermoforming clusters are expanding high-speed form-fill-seal capacity for oral solid dosage applications.
Switzerland
Swissmedic technical documentation requirements are extending seal-integrity validation cycles for new material introductions in high-barrier formats. Mid-tier generic manufacturers are piloting PEF bio-based barrier films at commercial scale. Basel and Zurich packaging engineering centers are rotating talent toward thermoforming and barrier-coating specializations as substrate complexity rises.
China
NMPA sterile barrier requirements and GB standards for medical device containment are dictating material qualification timelines. PVC supply concentration in coastal manufacturing zones creates geopolitical exposure for multinational pharmaceutical clients with ESG procurement criteria. Shanghai and Jiangsu province thermoforming clusters dominate chlorinated substrate production serving Asia-Pacific generic-drug volumes.
Blister Packs Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with film-to-packaging platforms commanding cost leadership in high-barrier pharmaceutical formats. The market structure rewards backward integration into substrate production and captive coating capabilities. Three archetypes dominate: integrated multinationals with global film supply networks, regional rigid-paperboard specialists, and mid-tier barrier-coating technology licensors. Competitive moves concentrate on M&A for substrate technology access and capacity expansion in CDSCO-aligned contract manufacturing zones.
Within the integrated multinational tier, Amcor plc and Sonoco Products Company exemplify divergent geographic anchoring strategies. Amcor occupies a position representing film-to-packaging platform integration, while Sonoco anchors North American supply through rigid paperboard-blister hybrid specialization. WestRock Company sits within the recycled-content specification tier, competing on emerging sustainability procurement criteria compliance.
| Leading Market Players |
|---|
| Amcor plc |
| Sonoco Products Company |
| WestRock Company |
| Constantia Flexibles |
| WINPAK Ltd. |
| Klöckner Pentaplast |
| UFlex Limited |
| Tekni-Plex |
| Honeywell International Inc. |
| Others |
Value Chain & Pricing Dynamics
Sixty-day raw-material lead times for PVDC-coated PVC substrates concentrate pricing power among German and Chinese chlorinated-film suppliers, compressing margin buffers for European contract packagers facing EU Green Deal reformulation mandates. Inventory carrying costs for alu-foil barrier laminates amplify geographic price spreads between tropical-climate export markets and temperate-zone domestic consumption.
Pricing Analysis
Geographic price spreads between Indian CDSCO-aligned contract manufacturers and German domestic packagers exceed transport-cost differentials alone, reflecting certification-grade premiums for EU MDR technical documentation. Three-tier pricing structure across premium barrier laminates, standard PVC formats, and economy paperboard hybrids tracks moisture vapor transmission rate thresholds. Cost compression in chlorinated substrates is intensifying as REACH restrictions on phthalate plasticizers force reformulation investments. Generic-drug sponsors in cardiovascular and diabetes portfolios exhibit highest price sensitivity; rare-disease and oncology sponsors absorb premium positioning for batch-size flexibility.
Supply Chain Analysis
China and Germany anchor chlorinated substrate production, with Shanghai and Jiangsu province thermoforming clusters feeding Asia-Pacific generic-drug volumes while Bavaria contract packaging networks serve European chronic disease management programs. Raw material flows draw from Saudi petrochemical feedstocks for PVC resin, Australian bauxite for cold-form alu-foil, and Finnish pulp for paperboard-blister hybrid fiber bases. Single-source vulnerability concentrates in Chinese PVDC coating deposition capacity. Distribution runs through pharmaceutical contract packaging networks rather than distributor-led channels in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substrate complexity escalation fragments what was historically commodity supply, creating specialized tier structures around barrier-coating capabilities and recyclability certification. Sustainability procurement criteria and tightening pharmacovigilance protocols generate defendable niches for technical-service-anchored positioning.
For Market Incumbents: Consolidate backward integration into captive coating capabilities to defend margin structures against PEF bio-based barrier film displacement. Acquire thermoforming engineering talent pools in Switzerland and Germany to address skill scarcity for high-barrier deposition precision. Prioritize certification investment for California EPR legislation compliance ahead of extended producer responsibility fee implementation.
For New Entrants and Emerging Players: Differentiate on paperboard-blister hybrid recyclability claims targeting European generic-drug sponsors with EU Green Deal procurement mandates. Penetrate Indian CDSCO-aligned contract manufacturing expansion in Gujarat and Maharashtra where European sponsors seek cost-advantaged sourcing. Lead with direct pharmaceutical-manufacturer negotiations rather than distributor-led channel structures.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because substrate transitions under F-Gas Regulation and REACH restrictions will revalue barrier-coating technology licensors over commodity thermoformers. Target mid-tier specialists with validated PEF or high-barrier paperboard formats. Watch for inflection when California EPR fee structures materially alter total cost of ownership calculations across substrate choices.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Capabilities | Captive PVDC and barrier deposition control insulates margin compression from REACH-driven reformulation cycles. |
| PEF Bio-Based Barrier Film Commercialization | Swiss and German pilot programs validate moisture-sensitive oral solid dosage applications against incumbent laminates. |
| CDSCO-Aligned Contract Manufacturing Expansion | Gujarat and Maharashtra facilities capture European generic-drug sponsor volumes seeking tropical-climate export compliance. |
| Child-Resistant Format Capacity Addition | DEA scheduling requirements and WHO patient-safety protocols tighten access-control specifications across opioid portfolios. |
| Recyclability Certification Investment | California EPR legislation and EU Green Deal mandates reward substrates with established municipal waste-stream pathways. |
Study Parameters
Cross-validation between primary interviews with packaging engineering directors, pharmaceutical procurement leads, contract manufacturing executives, and regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from FDA 21 CFR Part 211 guidance documents, ECHA REACH restriction dossiers, EU F-Gas Regulation implementing acts, and CDSCO facility inspection records. Bottom-up capacity assessments for thermoforming and cold-form equipment installations triangulate against top-down pharmaceutical packaging demand modeling across cardiovascular, diabetes, and oncology portfolios.
Sensitivity analysis around aluminum price volatility, PVC supply concentration risk, and EPR fee structure implementation timing tests forecast robustness across the projection horizon. Segmentation dimensions include substrate type, barrier performance tier, packaging format complexity, end-use regulatory cluster, and geographic manufacturing hub. CAGRs derive from installed equipment capacity utilization rates, sponsor pipeline expansion patterns, and substitution elasticity estimates between chlorinated and recyclable substrates. Forecast inputs incorporate EU MDR technical documentation timeline compression and Indian CDSCO alignment acceleration for export-oriented facilities.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity, aluminum price band stability, or CDSCO inspection capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding reformulation timeline adherence and recycling infrastructure development pace. Recalibration cycles align with material shifts in EPR legislation implementation, F-Gas Regulation phase-out schedules, and pharmacovigilance protocol tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Welded Blisters Market
Blister Packaging
Asia Pacific Blister Packaging Market
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market
Blister Packaging
North America Blister Packaging Market
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
Asia Pacific Pharmaceutical Blister Packaging Market
Blister Packaging
North America Pharmaceutical Blister Packaging Market
Blister Packaging
Pharma Blister Packaging Machines Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
Healthcare Blister Packaging Market
Blister Packaging
Ampoules and Blister Packaging Market
Blister Packaging
Middle East and Africa Blister Packaging Market
Blister Packaging
Global Blister Packaging Market
Blister Packaging
Global Cold Form Blister Packaging Market
Blister Packaging
PVC Blister Packaging Market
Blister Packaging
Holographic Blister Foil Market