
 Alu Alu Blister Packaging Machine Market | 2026-2036
Alu Alu Blister Packaging Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Alu Alu Blister Packaging Machine Market Outlook
Shortage of servo-motion engineers and cold-forming technicians is redrawing competitive boundaries among packaging machinery specialists. Uhlmann Group leverages deep apprenticeship pipelines in Germany to sustain complex machine commissioning capabilities. Syntegon Technology GmbH anchors its position through backward integration into control-system software. ACG competes aggressively on total cost of ownership for mid-speed lines across emerging Asian pharma markets.
An Alu Alu Blister Packaging Machine forms multi-layer aluminum-polyamide-PVC laminates into cavity pockets without heat, creating near-zero moisture and oxygen transmission barriers for hygroscopic pharmaceuticals. Cold forming operates at 25–35°C versus 120–180°C thermoforming, preserving heat-labile active ingredients. Fully automatic lines command the dominant share of capital deployment as large pharmaceutical manufacturers pursue line-integration efficiencies. Cold forming technology leads growth among technology segments because regulators in moisture-sensitive markets now mandate aluminum-barrier compliance for certain drug categories.
FDA 21 CFR Part 211 cGMP requirements and EU MDR Annex I general safety standards govern barrier-integrity validation, forcing machine builders to integrate in-process seal-testing modules. India's CDSCO Schedule M guidelines and China's NMPA GMP annex for pharmaceutical packaging equipment create parallel compliance obligations for exporters. Stakeholders must monitor whether evolving pharmacopeial moisture-permeability thresholds will obsolete legacy thermoforming assets before end-of-life depreciation cycles conclude.
Market Dynamics
Cold-forming capacity shortages among contract manufacturers in India and Southeast Asia are forcing pharmaceutical packagers to pre-book machine slots eighteen months ahead, compressing decision timelines for capital deployment.
Growth Catalysts
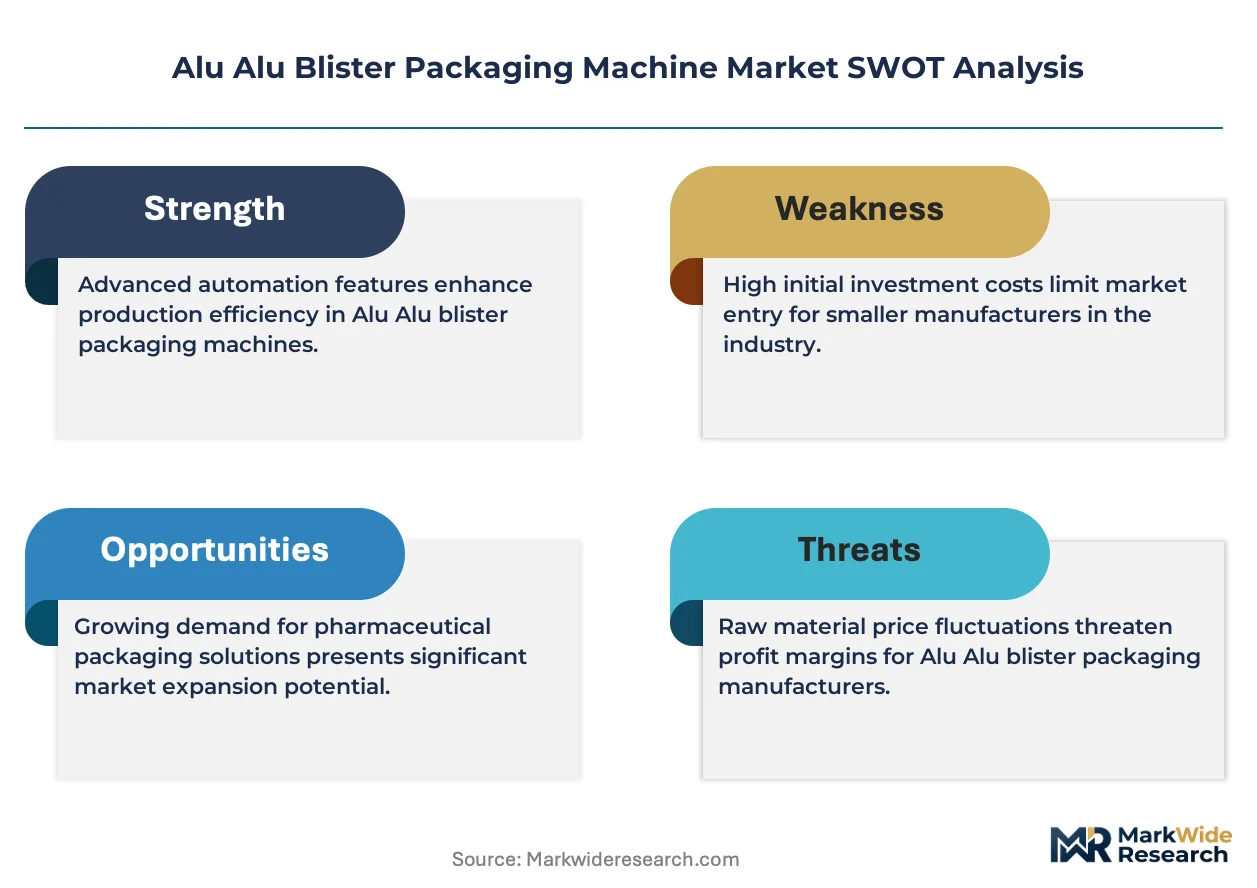
- EU MDR barrier mandates:Annex I general safety standards now require aluminum-barrier compliance for moisture-sensitive oral solid dosages, compelling packagers to upgrade from thermoforming assets.
- Hyderabad and Ahmedabad cluster expansion:Indian pharmaceutical contract manufacturers are scaling export-oriented production lines to serve regulated European and North American markets.
- Cold-forming technology:Operating temperatures of 25–35°C versus 120–180°C thermoforming preserve heat-labile active ingredients, opening formulation categories previously excluded from blister packaging.
Market Restraints
- Aluminum-polyamide laminate cost volatility:Raw material prices for multi-layer barrier films fluctuate with petrochemical feedstock indices, squeezing margin predictability for mid-speed line operators.
- German and Italian import dependence:High-speed precision cold-forming modules concentrate among European machine builders, exposing Asian pharmaceutical clusters to currency and logistics risk.
- FDA 21 CFR Part 211 validation timelines:Extended stability-testing protocols for barrier-integrity certification delay revenue recognition on new line deployments by six to twelve months.
Strategic Opportunities
- Indonesia and Vietnam pharmaceutical manufacturing:Underpenetrated Southeast Asian markets lack domestic cold-forming capacity, creating first-mover advantages for equipment lessors with local service presence.
- Biologic oral solid dosages:Emerging hygroscopic formulations require near-zero moisture transmission barriers that only Alu Alu configurations reliably deliver.
- India PLI scheme for pharmaceutical machinery:Production-linked incentive structures subsidize domestic machine tool manufacturing, lowering total cost of ownership for regional buyers.
Industry Challenges
- Servo-motion engineering scarcity:Complex multi-axis control systems for precision cavity forming require specialized technicians concentrated in Germany and Switzerland, constraining commissioning speed.
- Legacy thermoforming asset stranding:Pharmacopeial moisture-permeability threshold revisions risk obsoleting installed equipment before depreciation cycles conclude, complicating capital planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alu Alu Blister Packaging Machine Market |
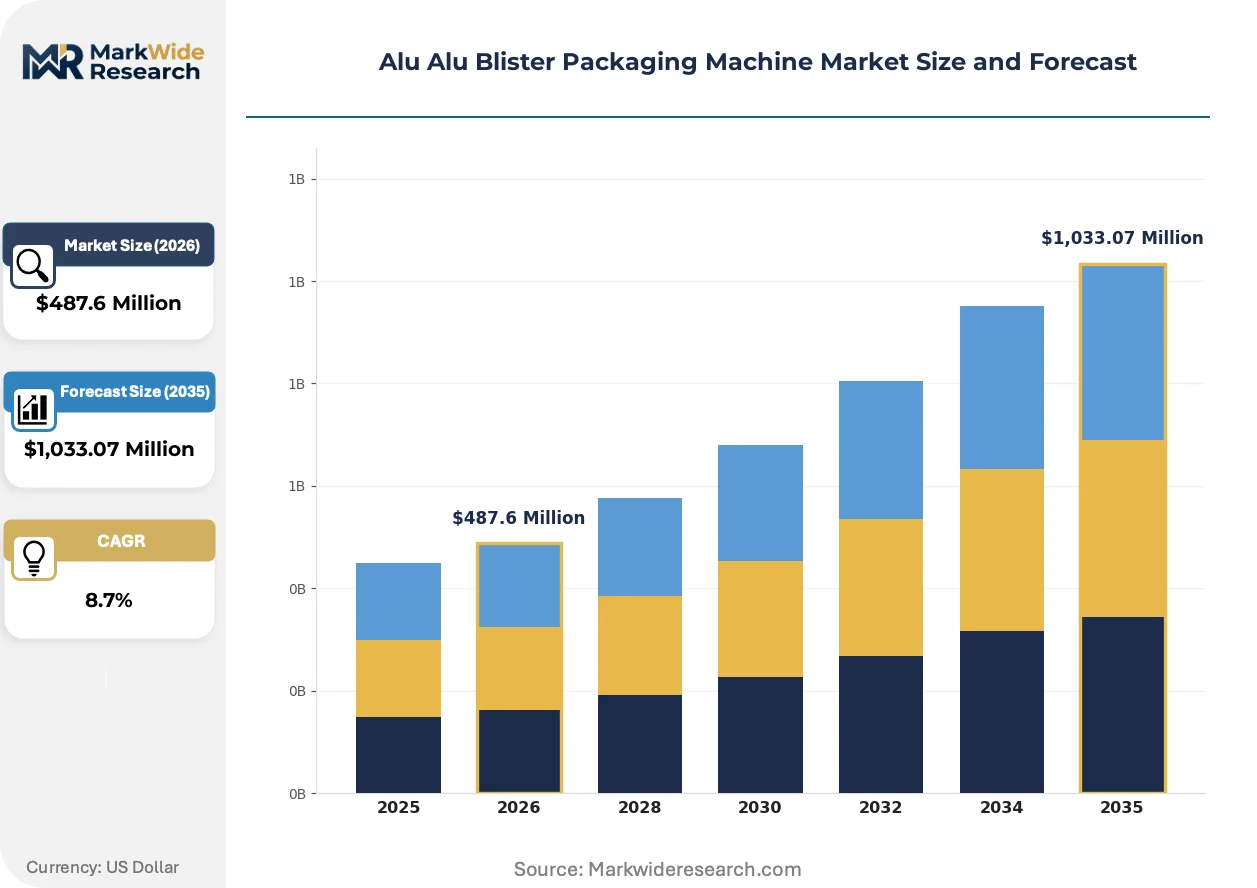
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Semi-Automatic, Fully Automatic End User: Pharmaceuticals, Food, Cosmetics, Electronics Technology: Thermoforming, Cold Forming, Continuous, Batch Material: Aluminum Foil, Polyvinyl Chloride, Polyethylene, Paper |
| Companies Covered | Uhlmann Group, Syntegon Technology GmbH, Romaco Group, Marchesini Group, IMA Group, ACG, Bosch Packaging Technology, Mediseal GmbH, Hoonga, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alu Alu Blister Packaging Machine Market Strategic Shifts
Machine architecture is fragmenting as pharmaceutical packagers demand modular lines that integrate seal-testing, serialization, and track-and-trace without custom engineering for each deployment.
Artificial vision systems for in-process cavity inspection are decomposing the traditional separation between forming and quality-control stations. Large pharmaceutical manufacturers in Germany and Switzerland are adopting these modules at replacement-cycle pace. This convergence is decomposing the standalone machine market into component-substitution economics where software upgrades extend physical asset life.
EU MDR Annex I general safety standards and FDA 21 CFR Part 211 cGMP requirements are tightening in parallel on barrier-integrity validation, forcing synchronous compliance investments across export-oriented facilities. Machine builders now pre-integrate seal-testing modules rather than offering them as optional add-ons. Indian and Chinese exporters to regulated markets face the steepest compliance cost escalation, accelerating preference for validated turnkey lines over component assembly.
After-sales service contracts are unbundling from hardware sales as pharmaceutical manufacturers seek predictive maintenance tied to output guarantees rather than time-based service intervals. German and Italian equipment vendors face pressure from Asian competitors offering performance-based uptime commitments. This shift is most visible in India's Gujarat and Maharashtra clusters, where domestic machine builders compete on total cost of ownership through captive service networks.
Alu Alu Blister Packaging Machine Market Segmentation
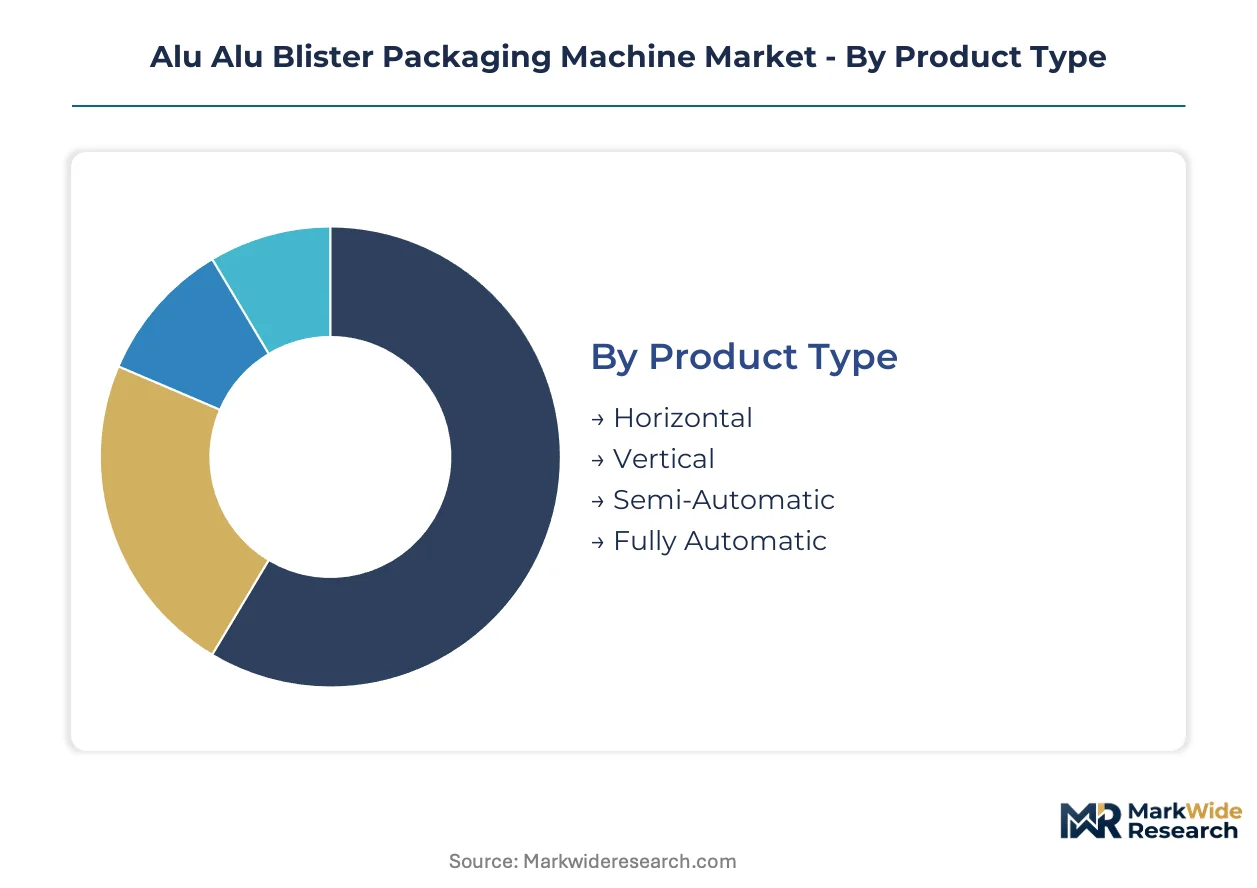
Segmentation in the Alu Alu Blister Packaging Machine market reveals divergent investment patterns between regulated export corridors and domestic production clusters. Machine specifications vary sharply by whether packagers serve FDA-audited facilities or local generic markets. Understanding these divides illuminates where capital deployment concentrates and where technology gaps persist.
Product Type:
Horizontal configurations dominate European and North American pharmaceutical exports, while vertical formats concentrate in Indian and Southeast Asian contract manufacturing facilities serving cost-sensitive domestic markets.
- Fully Automatic:Integrated lines combine forming, sealing, and serialization in continuous operation for high-volume pharmaceutical manufacturers. Demand clusters in Germany's Baden-Württemberg pharmaceutical belt and India's Gujarat export corridors where CDSCO Schedule M compliance requires validated throughput documentation.
- Horizontal:Side-loading cavity formation enables parallel processing of multiple product SKUs with minimal changeover downtime. European packagers in Switzerland and Italy specify these for biologic oral solid dosages requiring aluminum-barrier validation under EU MDR Annex I.
- Vertical:Top-down forming suits space-constrained facilities in Vietnam and Indonesia where real estate costs pressure floorplan efficiency.
- Semi-Automatic:Operator-fed configurations serve Indian regional generic manufacturers in Madhya Pradesh and Uttar Pradesh with lower capital budgets and batch-scale flexibility needs.
Fully automatic lines command the established base. The steepest expansion runs through horizontal configurations.
End User:
End-use concentration tracks regulatory stringency, with moisture-sensitive oral solid dosage requirements segmenting investment tiers across customer categories.
- Pharmaceuticals:Hygroscopic tablet and capsule packaging drives barrier-performance specifications for FDA 21 CFR Part 211 cGMP compliance. Indian contract manufacturers in Hyderabad and Ahmedabad deploy Alu Alu systems for European and North American export contracts.
- Food:Moisture-sensitive confectionery and nutritional supplements adopt pharmaceutical-grade cold-forming for extended shelf stability. Japanese manufacturers specify these for premium functional food exports.
- Cosmetics:Single-dose ampoule and serum packaging uses modified cold-forming with aesthetic finishing requirements.
- Electronics:Static-sensitive component packaging employs aluminum-barrier properties for moisture and electromagnetic shielding.
Pharmaceuticals anchors the installed base. Food applications are climbing the fastest.
Technology:
Technology selection divides along heat-lability requirements and regulatory barrier mandates, with cold-forming premiums widening against legacy thermoforming.
- Cold Forming:Aluminum-polyamide-PVC lamination at ambient temperatures eliminates moisture and oxygen transmission without thermal stress on active ingredients. EU MDR barrier mandates for moisture-sensitive categories now require this technology for certain oral solid dosage registrations.
- Thermoforming:PVC or aluminum heating to 120–180°C suits non-hygroscopic generics with lower barrier requirements and faster cycle economics.
- Continuous:Non-stop web feeding maximizes output for high-volume blockbusters with stable demand forecasts.
- Batch:Indexed stopping enables formulation changeovers for clinical trial materials and short-run specialty products.
Thermoforming retains the legacy footprint. Cold forming delivers the steepest expansion trajectory.
Material:
Material specifications cascade from barrier-performance requirements, with multi-layer laminates commanding premium positioning against monolayer alternatives.
- Aluminum Foil:Primary barrier layer providing near-zero moisture vapor transmission rates. German and Italian machine builders optimize forming mechanics for specific alloy gauges and temper grades.
- Polyvinyl Chloride:Thermoforming substrate with established recycling infrastructure in European markets.
- Polyethylene:Sealant layer compatibility varies by regional pharmaceutical packaging pharmacopeia requirements.
- Paper:Emerging fiber-based alternatives for sustainability-positioned overwrap applications with limited barrier function.
Aluminum foil structures dominate revenue. Polyethylene sealant specifications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys Alu Alu systems for export-oriented contract manufacturing, while Germany and Switzerland optimize them for high-value biologic formulations. Japan applies pharmaceutical-grade cold-forming to functional food exports. This consumption-mix differential shapes regional investment priorities and technology specifications.
Germany
Baden-Württemberg's pharmaceutical belt drives demand for validated horizontal configurations serving EU MDR Annex I compliance. German machine builders leverage deep apprenticeship pipelines to sustain complex commissioning capabilities. The Uhlmann Group anchors precision cold-forming module production in this region.
India
Hyderabad and Ahmedabad clusters scale export-oriented production lines for European and North American markets. CDSCO Schedule M guidelines create parallel compliance obligations for pharmaceutical exporters. Domestic machine builders compete aggressively on total cost of ownership through captive service networks in Gujarat and Maharashtra.
Switzerland
Biologic oral solid dosage manufacturers specify aluminum-barrier validation under Swissmedic requirements. Large pharmaceutical manufacturers adopt artificial vision systems for in-process cavity inspection at replacement-cycle pace. Swiss facilities integrate seal-testing modules as standard rather than optional configurations.
Japan
Moisture-sensitive confectionery and nutritional supplement manufacturers adopt pharmaceutical-grade cold-forming for extended shelf stability. METI standards govern equipment validation for premium functional food exports. Japanese pharmaceutical companies specify near-zero moisture transmission barriers for hygroscopic formulations.
Vietnam
Space-constrained facilities in Ho Chi Minh City and Hanoi deploy vertical configurations where real estate costs pressure floorplan efficiency. Underpenetrated Southeast Asian markets lack domestic cold-forming capacity, creating first-mover advantages for equipment lessors with local service presence. The national pharmaceutical regulator imposes emerging GMP requirements on packaging equipment imports.
Alu Alu Blister Packaging Machine Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Alu Alu Blister Packaging Machine market. German and Italian equipment vendors concentrate high-speed precision cold-forming capabilities, while Asian competitors challenge on total cost of ownership through regional service networks. Three archetypes dominate: vertically integrated European majors with captive control-system software, mid-speed specialists targeting emerging market contract manufacturers, and domestic Indian builders leveraging PLI scheme subsidies. Competitive moves center on backward integration into control-system software and performance-based uptime commitments replacing time-based service contracts.
Among Germany-based fabricators, Uhlmann Group and Syntegon Technology GmbH exemplify the integrated leader archetype, occupying positions sustained by deep apprenticeship pipelines and in-house software development. ACG represents the mid-speed specialist tier competing aggressively across emerging Asian pharma markets. These three anchors illustrate how geographic origin and company structure correlate with strategic positioning in barrier-performance validation and total cost of ownership economics.
| Leading Market Players |
|---|
| Uhlmann Group |
| Syntegon Technology GmbH |
| Romaco Group |
| Marchesini Group |
| IMA Group |
| ACG |
| Bosch Packaging Technology |
| Mediseal GmbH |
| Hoonga |
| Others |
Value Chain & Pricing Dynamics
High-volume cold-forming capacity utilization in Gujarat and Maharashtra clusters compresses unit economics for mid-speed line operators while sustaining premium pricing for validated high-speed German configurations. This scale asymmetry stratifies procurement budgets across export-oriented contract manufacturers and domestic generic producers.
Pricing Analysis
Long-term offtake contracts dominate capital equipment procurement for large pharmaceutical manufacturers, while spot purchasing persists among regional Indian generic producers with irregular batch requirements. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-validated German systems from mid-speed Asian alternatives and refurbished legacy thermoforming assets. Cost compression in mid-speed tiers is intensifying because domestic Indian builders leverage PLI scheme subsidies to undercut European import pricing. Regional generic manufacturers in Madhya Pradesh and Uttar Pradesh exhibit highest price sensitivity, whereas FDA-audited export facilities in Hyderabad prioritize barrier-validation certification over acquisition cost.
Supply Chain Analysis
Eighteen-month lead times for precision servo-motion components from Germany and Switzerland force pharmaceutical packagers to pre-book machine slots before facility commissioning schedules firm. Multi-layer aluminum-polyamide-PVC laminate supply concentrates in Germany, Italy, and Japan, with sealant layer chemistry anchored in South Korean petrochemical feedstock streams. Single-source vulnerability pervades high-speed cold-forming module production, where Uhlmann Group and Syntegon Technology GmbH control proprietary forming mechanics intellectual property. Distribution runs through direct manufacturer sales for validated lines and regional equipment lessors for emerging market vertical configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from pandemic-delayed capital deployment cycles as EU MDR barrier mandates force replacement of legacy thermoforming assets ahead of depreciation conclusions.
For Market Incumbents: Compound barrier-performance validation capabilities through backward integration into control-system software rather than relying on third-party automation vendors. Deepen apprenticeship pipelines in Germany and Switzerland to sustain commissioning speed advantages as Asian competitors expand local technician training. Capacity addition in India through licensed assembly partnerships defends margin position against PLI-subsidized domestic builders. For New Entrants and Emerging Players: Anchor in Vietnam and Indonesia vertical configuration markets where real estate constraints and emerging GMP requirements create first-mover equipment leasing opportunities. Indonesia pharmaceutical manufacturing remains the most penetrable geography due to absence of domestic cold-forming capacity and underdeveloped aftermarket service networks. Performance-based uptime commitments rather than time-based service contracts differentiate against established European vendors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors control-system software specialists over pure hardware fabricators as artificial vision integration and predictive maintenance modules capture expanding value share. Five-to-ten year viability hinges on regulatory barrier mandates persisting through pharmacopeial moisture-permeability threshold revisions. Acquisition target archetype: mid-speed specialists with captive Southeast Asian service networks and validated CDSCO Schedule M compliance documentation. The signal to watch is FDA stability-testing protocol amendments that could accelerate thermoforming asset obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control-System Software | Syntegon Technology GmbH's captive software development anchors premium positioning against component-assembled competitors. |
| Performance-Based Uptime Commitments | ACG's output guarantees in Gujarat and Maharashtra clusters displace German time-based service contract conventions. |
| EU MDR Validation Pre-Integration | Swissmedic-compliant seal-testing modules now ship as standard rather than optional on Swiss pharmaceutical lines. |
| Licensed Assembly Partnerships | Domestic Indian builders leverage PLI scheme subsidies to lower total cost of ownership for regional export corridors. |
| Artificial Vision System Integration | German and Swiss manufacturers adopt in-process cavity inspection at replacement-cycle pace, decomposing standalone machine economics. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical packaging engineers, contract manufacturing procurement directors, CDSCO regulatory compliance officers, and cold-forming equipment aftermarket service heads. Secondary validation drew from FDA 21 CFR Part 211 guidance documents, EU MDR Annex I technical standards, CDSCO Schedule M facility inspection reports, and Indian PLI scheme disbursement disclosures. Bottom-up unit economics for machine deployments were triangulated against top-down capital expenditure tracking across Gujarat, Maharashtra, Hyderabad, and Ahmedabad pharmaceutical clusters.
Across the analysis window, volume and value outputs were modeled through segmented demand forecasting incorporating technology type, automation level, end-use regulatory stringency, and regional export corridor positioning. CAGRs were derived from installed base replacement cycles, capacity expansion announcements, and barrier-mandate compliance deadlines. Forecast inputs included aluminum-polyamide laminate cost indices, servo-motion engineering labor availability by geography, and pharmacopeial moisture-permeability threshold revision probabilities.
Material uncertainties — raw material cost volatility, regulatory timeline shifts, and currency fluctuation exposure for European machine imports — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EU MDR enforcement consistency and Indian PLI scheme continuation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Middle East and Africa Blister Packaging Market
Blister Packaging
PVC Blister Packaging Market
Blister Packaging
Blister Paper Market
Blister Packaging
United States Blister Packaging Market
Blister Packaging
Welded Blisters Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
Asia Pacific Blister Packaging Market
Blister Packaging
Blister Cards Market
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
North America Pharmaceutical Blister Packaging Market
Blister Packaging
North America Blister Packaging Market
Blister Packaging
Asia Pacific Pharmaceutical Blister Packaging Market
Blister Packaging
Liquid Blister Pack Market
Blister Packaging
Blister Foil Market
Blister Packaging
Pharma Blister Packaging Machines Market