
 Electronic Protection Device (EPD) Coatings Market | 2026-2036
Electronic Protection Device (EPD) Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Protection Device (EPD) Coatings Market Analysis
Specialized formulation chemist availability is collapsing across Western Europe and parts of North America as polymer science programs contract and experienced technicians retire. Henkel Corporation leverages its adhesives heritage to anchor conformal coating supply chains for automotive PCB assemblies. P2i Ltd competes through plasma-enhanced chemical vapor deposition technology leadership in smartphone waterproofing tiers. Chase Corporation sustains diversified manufacturing scale across potting compounds and encapsulants for industrial and aerospace end users.
Electronic Protection Device coatings constitute thin-film or bulk polymer barriers applied to printed circuit boards and electronic components, typically ranging from 25 to 250 microns in dry-film thickness, to insulate against moisture, ionic contamination, thermal shock, and mechanical vibration. Their primary commercial purpose is extending operational lifespan in harsh-environment electronics across automotive underhood, aerospace avionics, and outdoor industrial control systems. Conformal coatings dominate value capture due to established qualification protocols in aerospace and military supply chains, while coating resins represent the fastest-expanding category as OEMs seek customizable viscosity and cure profiles for automated dispense lines. Dip coating maintains volume leadership in high-throughput consumer electronics assembly, though chemical vapor deposition commands premium positioning in miniature wearable and medical device applications where uniform sub-micron coverage proves critical.
EPA oversight of volatile organic compound emissions shapes formulation chemistry decisions for US-based coating operations, particularly affecting solvent-borne acrylic and urethane lines. ECHA enforces REACH substance restrictions and SVHC disclosure requirements that filter material choices across European supply chains. RoHS and evolving CE marking under the EU Green Deal pressure manufacturers to eliminate hazardous additives and document carbon footprints for market access. Stakeholders must monitor regulatory divergence between California Air Resources Board thresholds and EU F-Gas Regulation limits on fluorinated precursors used in some high-performance barrier films.
Market Dynamics
Automotive electrification is compressing coating qualification cycles as EV powertrain thermal loads push material specifications beyond legacy aerospace benchmarks. Tier suppliers now face parallel validation tracks for solvent-borne, UV-curable, and bio-based chemistries under divergent regulatory regimes.
Growth Catalysts
- EV Powertrain Thermal Management:Battery module and inverter assemblies require conformal coatings rated above 150°C continuous operation. Automotive OEMs in Germany are consolidating procurement specifications around polyimide and silicone-modified acrylic platforms.
- REACH SVHC Disclosure Mandates:ECHA substance restrictions are accelerating formulation replacements across European coating operations. Suppliers holding pre-registered dossiers for UV oligomers capture preferential qualification status with Stuttgart-based automotive electronics clusters.
- Plasma-Enhanced Deposition:P2i Ltd's nanocoating technology is penetrating smartphone waterproofing tiers. Medical device manufacturers are adapting this process for hearing aid and continuous glucose monitor hermetic sealing.
Market Restraints
- Specialized Chemist Scarcity:Polymer science program contractions across Western Europe and North America have collapsed technician availability. Coating laboratories report 18-month backlogs for formulation optimization projects.
- Fluorinated Precursor Supply Concentration:EU F-Gas Regulation limits on perfluorinated compounds constrain high-performance barrier film production. Japanese and Chinese suppliers dominate remaining precursor manufacturing capacity.
- Acrylic Urethane Cost Volatility:Isocyanate and specialty monomer feedstock prices swing with crude oil and natural gas benchmarks. Coating manufacturers lack pricing power to pass through input cost spikes to automotive contract customers.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and PCB assembly are creating coating demand in Karnataka and Tamil Nadu. Domestic formulation capabilities remain underdeveloped relative to projected volume requirements.
- UV-Curable Bio-Based Convergence:Formulators combining plant-derived acrylates with LED cure systems are targeting RoHS-compliant automotive applications. Henkel Corporation's adhesives heritage provides raw material sourcing advantages for this platform.
- Direct OEM Coating Centers:Automotive electronics suppliers are bypassing merchant coaters by installing captive dip and selective coating lines. Equipment vendors report rising inquiry volumes from tier-two suppliers in Bavaria and Baden-Württemberg.
Industry Challenges
- Aerospace Qualification Timeline Compression:IPC-CC-830 and MIL-STD-202G certification cycles extend 24-36 months. Dual-use coating suppliers struggle to synchronize automotive speed requirements with military validation protocols.
- Legacy Dispense System Retrofit Complexity:High-volume consumer electronics assemblers operate solvent-borne acrylic lines with fixed capital investments. UV conversion requires parallel tank, pump, and nozzle infrastructure that disrupts production continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Protection Device (EPD) Coatings Market |
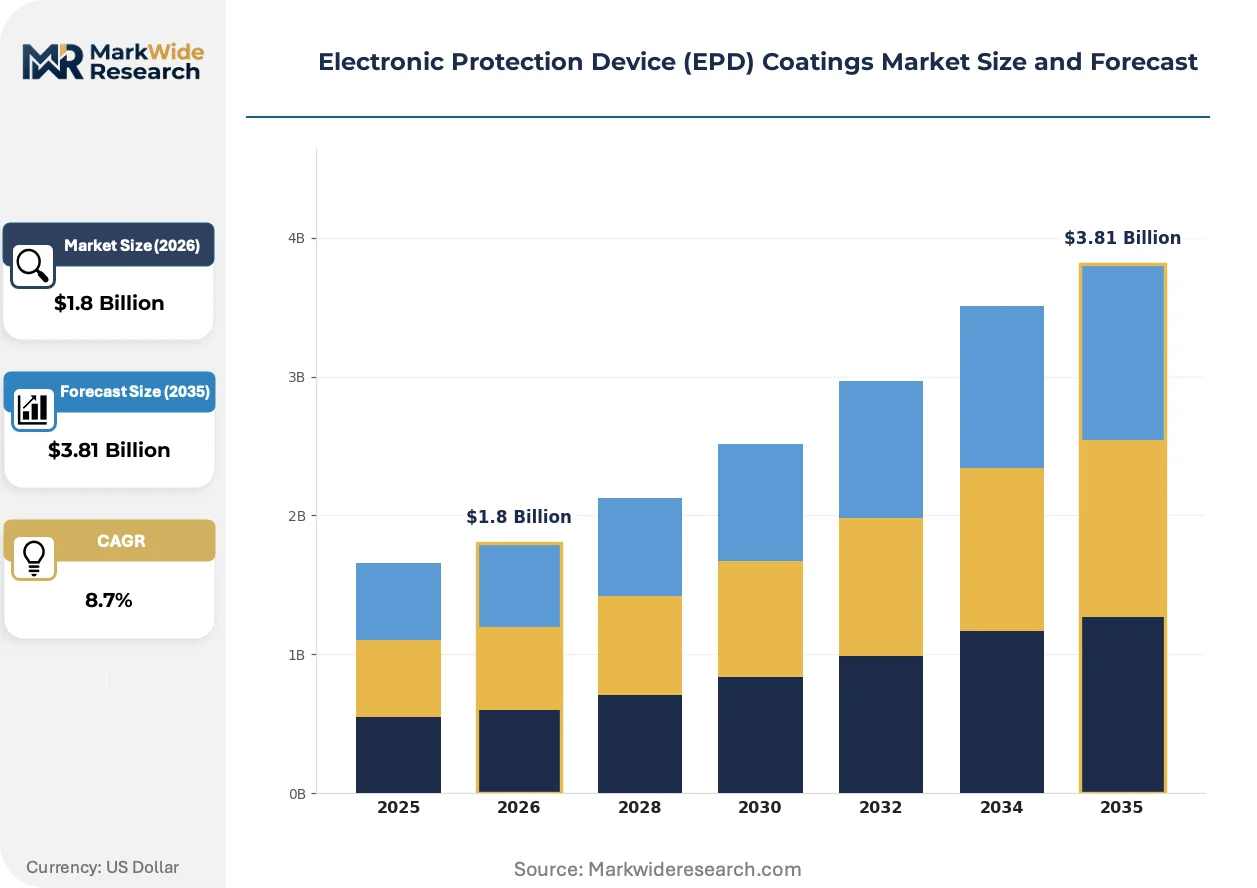
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Conformal Coatings, Potting Compounds, Coating Resins, Adhesives Technology: Chemical Vapor Deposition, Electrostatic Spray, Dip Coating, Roll Coating End User: Consumer Electronics, Automotive, Aerospace, Industrial Equipment Application: PCB Protection, Component Sealing, Corrosion Prevention, Moisture Barrier |
| Companies Covered | Electrolube, P2i Ltd, 3M, Dymax Corporation, Electronic Coating Technologies, Henkel Corporation, Chase Corporation, H.B. Fuller Company, Specialty Coating Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Protection Device (EPD) Coatings Market Emerging Trajectories
Coating technology trajectories are diverging between high-throughput automotive electronics and precision miniature applications. Formulation chemistry, deposition physics, and supply chain geography are decoupling across these demand poles.
Hybrid silicone-epoxy chemistries are fragmenting thermal management coating categories. These materials combine polyimide temperature resistance with epoxy adhesion to printed circuit board substrates. Automotive inverter manufacturers in Germany and South Korea are qualifying these platforms for 800-volt architectures. The resulting specification proliferation is compressing economies of scale for single-chemistry suppliers.
EPA volatile organic compound emission thresholds are forcing solvent-borne line conversions across US-based coating operations. Acrylic and urethane formulations above 340 grams per liter VOC content face facility-level permitting restrictions. Aerospace and military suppliers with grandfathered equipment configurations are absorbing disproportionate compliance costs relative to greenfield UV-curable installations.
Automotive tier suppliers are consolidating coating procurement under single-source technical service agreements. Previously fragmented purchasing across plant-level engineers is centralizing at regional commodity managers. This concentration is most visible in Germany's Stuttgart production corridor, where BMW, Mercedes-Benz, and Porsche electronics suppliers have aligned vendor qualification protocols.
Electronic Protection Device (EPD) Coatings Market Segmentation
EPD coating procurement patterns diverge sharply across deposition physics and end-use reliability requirements. Automotive and aerospace verticals impose incompatible qualification timelines, forcing suppliers to maintain parallel formulation portfolios.
Coating Type:
Domestic consumption dominates potting compounds and adhesives in Germany and South Korea, while conformal coatings and coating resins flow through export-led supply chains serving North American and Southeast Asian contract manufacturers.
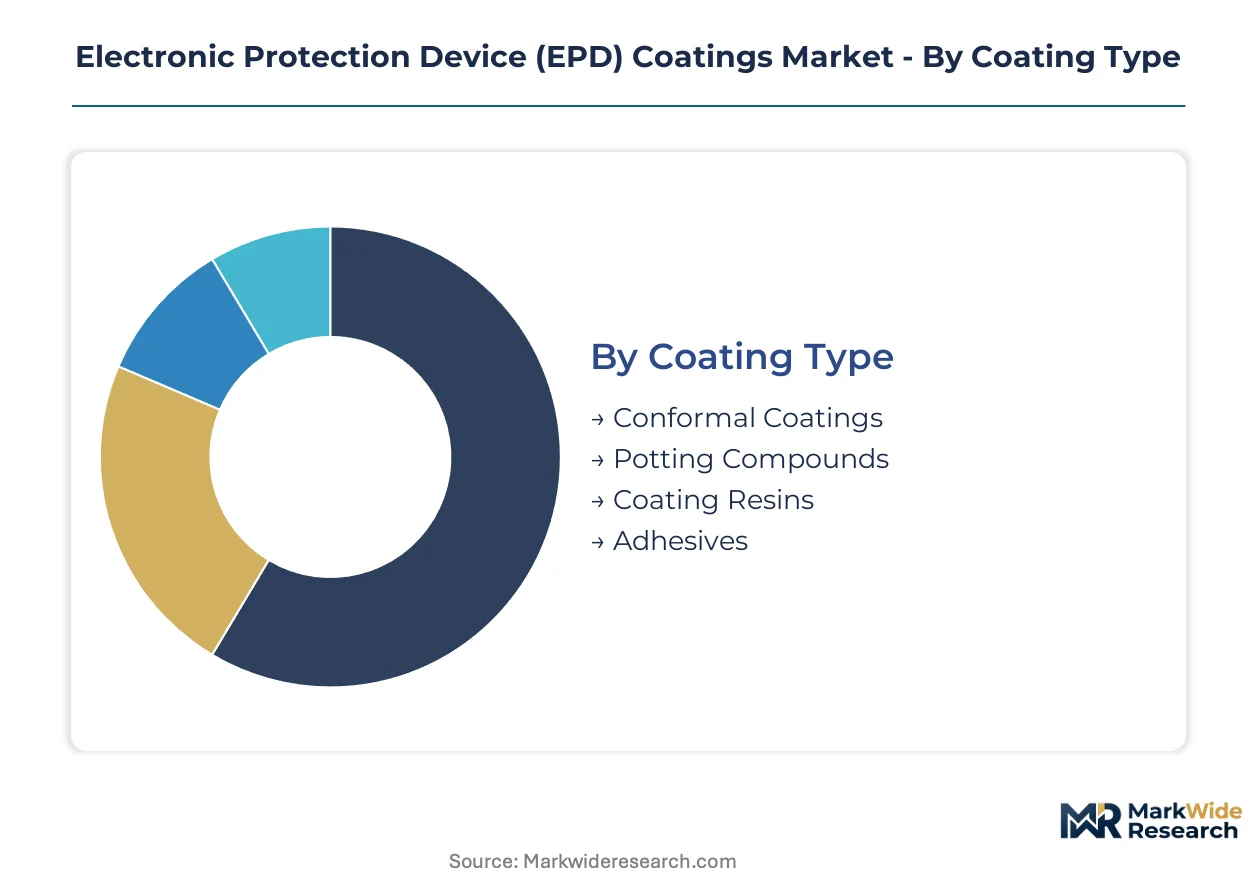
- Conformal Coatings:Thin-film polymer barriers ranging 25-250 microns dry-film thickness insulate PCBs against moisture and ionic contamination. Demand concentrates in Stuttgart automotive electronics clusters where BMW, Mercedes-Benz, and Porsche suppliers enforce IPC-CC-830 qualification protocols.
- Coating Resins:Customizable viscosity and cure profile platforms enable automated dispense line integration. Formulators in Germany and Japan are capturing preferential qualification status as OEMs seek RoHS-compliant UV oligomer alternatives to solvent-borne acrylics.
- Potting Compounds:Bulk encapsulation materials protect high-voltage battery modules and industrial power supplies. Chase Corporation maintains diversified manufacturing scale across North American industrial and aerospace end users.
- Adhesives:Henkel Corporation leverages its adhesives heritage to anchor conformal coating supply chains for automotive PCB assemblies in Bavaria and Baden-Württemberg production corridors.
Conformal coatings hold the largest share; momentum sits with coating resins as formulation customization accelerates.
Technology:
Cost tier stratification separates high-volume dip coating installations from premium chemical vapor deposition systems requiring cleanroom infrastructure.
- Dip Coating:High-throughput immersion systems dominate consumer electronics assembly in China and Vietnam. Fixed capital investments in solvent-borne acrylic lines complicate UV conversion for legacy operators.
- Chemical Vapor Deposition:Plasma-enhanced systems deliver uniform sub-micron coverage critical for hearing aids and continuous glucose monitors. P2i Ltd's nanocoating technology commands premium positioning in smartphone waterproofing tiers.
- Electrostatic Spray:Selective coating systems target automotive inverter assemblies requiring precise material placement. Equipment vendors report rising inquiry volumes from tier-two suppliers installing captive production lines.
- Roll Coating:Continuous web processing serves flexible circuit and membrane switch applications. Japanese equipment manufacturers dominate precision coating head supply for medical device producers.
Dip coating maintains volume leadership; chemical vapor deposition climbs the fastest as miniaturization demands intensify.
End User:
Application maturity separates established aerospace qualification protocols from compressed automotive electrification cycles and emerging consumer electronics specifications.
- Automotive:EV powertrain thermal loads push material specifications beyond legacy benchmarks. Battery module and inverter assemblies require coatings rated above 150°C continuous operation in Germany and South Korea.
- Aerospace:MIL-STD-202G certification cycles extend 24-36 months. Dual-use suppliers struggle to synchronize military validation protocols with automotive speed requirements.
- Consumer Electronics:Smartphone waterproofing drives plasma-enhanced deposition adoption. Assembly lines in China and Vietnam prioritize throughput over sub-micron precision for standard-tier devices.
- Industrial Equipment:Outdoor control systems and harsh-environment sensors demand moisture barrier performance. European REACH compliance accelerates shift from solvent-based to bio-based formulations.
Automotive commands the largest procurement volume; aerospace maintains the steepest expansion trajectory as satellite electronics proliferate.
Application:
Customer type fragmentation separates high-reliability military-specification buyers from cost-sensitive commercial electronics assemblers.
- PCB Protection:Conformal coating coverage of printed circuit board traces and solder joints dominates commercial value. Polyimide and silicone-modified acrylic platforms consolidate procurement specifications in Germany.
- Component Sealing:Individual device encapsulation protects sensors, connectors, and discrete semiconductors. Medical device manufacturers adapt plasma-enhanced processes for hermetic sealing of hearing aids.
- Corrosion Prevention:Salt spray and chemical resistance specifications govern marine and oilfield electronics. Industrial equipment OEMs in Norway and the United Kingdom specify fluorinated barrier films constrained by EU F-Gas Regulation limits.
- Moisture Barrier:Water vapor transmission rate specifications determine coating thickness and chemistry selection. Consumer electronics assemblers balance performance against material cost in high-volume smartphone production.
PCB protection holds the largest share; component sealing gains share fastest as wearable device miniaturization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA substance restrictions anchor European formulation chemistry decisions, while EPA volatile organic compound thresholds reshape North American coating operations. Automotive electrification and REACH SVHC disclosure mandates concentrate procurement power in specific industrial clusters.
Germany
Automotive OEMs and tier suppliers in Stuttgart and Munich production corridors are consolidating procurement specifications around polyimide and silicone-modified acrylic platforms. REACH and RoHS compliance accelerate the shift from solvent-based to UV-curable and bio-based formulations. Coating qualification labs are co-locating near Bavaria and Baden-Württemberg electronics manufacturing zones to compress validation cycles.
United States
EPA oversight of volatile organic compound emissions affects solvent-borne acrylic and urethane lines at facility level. Aerospace and military suppliers with grandfathered equipment absorb disproportionate compliance costs relative to greenfield UV-curable installations. California Air Resources Board thresholds diverge from federal benchmarks, creating state-level formulation complexity for multi-site operators.
China
High-throughput consumer electronics assembly in Guangdong and Jiangsu provinces sustains dip coating volume leadership. NMPA and MIIT regulations on industrial chemical emissions are tightening feedstock availability for traditional formulations. Domestic equipment vendors report rising inquiry volumes for captive coating lines serving smartphone and wearable device manufacturers.
South Korea
MFDS medical device regulations and automotive electrification are driving dual qualification tracks for conformal coating suppliers. Battery module and inverter manufacturers in Gyeonggi and Chungcheong provinces specify coatings rated above 150°C continuous operation. Local formulators are capturing preferential status with Hyundai and Kia electronics clusters seeking RoHS-compliant alternatives.
India
PLI scheme incentives for semiconductor and PCB assembly are creating coating demand in Karnataka and Tamil Nadu manufacturing corridors. BIS standards for electronics reliability are elevating qualification requirements for imported formulations. Domestic formulation capabilities remain underdeveloped relative to projected volume requirements from Bengaluru and Chennai production zones.
Electronic Protection Device (EPD) Coatings Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across deposition physics and formulation chemistry. The vendor base separates between plasma-enhanced deposition specialists, diversified adhesives and coatings conglomerates, and focused conformal coating merchants. Three archetypes dominate: equipment-integrated technology licensors, multi-platform formulation suppliers, and captive coating service operators. Competitive moves concentrate on strategic partnerships for regulatory pre-qualification and geographic expansion into automotive electronics clusters.
Within the technology-licensor tier, P2i Ltd occupies a position exemplifying plasma-enhanced chemical vapor deposition leadership for miniature device applications. Among diversified formulation suppliers, Henkel Corporation and Chase Corporation represent archetypes of multi-platform coating and encapsulant portfolios serving divergent end-use reliability requirements. These named entities anchor commentary on how supplier heritage in adjacent materials categories shapes competitive positioning across automotive, aerospace, and consumer electronics verticals.
| Leading Market Players |
|---|
| Electrolube |
| P2i Ltd |
| 3M |
| Dymax Corporation |
| Electronic Coating Technologies |
| Henkel Corporation |
| Chase Corporation |
| H.B. Fuller Company |
| Specialty Coating Systems Inc. |
| Others |
Supply Flow & Price Mechanics
REACH SVHC disclosure mandates gate both supplier qualification status and price tier placement across European EPD coating procurement. Automotive OEMs in Stuttgart and Munich corridors restrict approved vendor lists to formulators holding pre-registered dossiers, compressing price competition among qualified suppliers while excluding unregistered competitors from premium contract tiers.
Pricing Analysis
German automotive electronics clusters command 15-25% price premiums over Southeast Asian contract manufacturers for equivalent polyimide formulations. Three-tier pricing structure across aerospace-qualified, automotive-specified, and consumer-grade tiers separates procurement pools, with IPC-CC-830 certification tier capturing sustained margin premiums. Cost compression in solvent-borne acrylic segments runs through isocyanate feedstock volatility and automotive contract pricing power. Tier-two automotive suppliers exhibit highest price sensitivity due to fixed OEM pricing agreements, while medical device manufacturers show lowest sensitivity given hermetic sealing performance requirements.
Supply Chain Analysis
Japanese and Chinese suppliers dominate fluorinated precursor manufacturing capacity, creating single-source vulnerability for EU-based high-performance barrier film production. Raw material dependencies center on specialty acrylate monomers from South Korea, silicone resins from Germany, and UV photoinitiators from Japan. Distribution runs through qualified distributor networks serving automotive electronics clusters in Bavaria and Baden-Württemberg, with direct OEM coating center installations bypassing merchant coaters in select accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification is compressing coating qualification cycles into platform-economics inflection, where UV-curable and bio-based formulation interoperability determines supplier survival. Tier suppliers consolidating under single-source technical service agreements are reshaping competitive access rules.
For Market Incumbents: Shield formulation portfolios against REACH substance restriction cascades by accelerating UV oligomer pre-registration dossiers with ECHA. Deepen backward integration into specialty acrylate feedstocks to offset isocyanate cost volatility. Capture automotive procurement centralization by anchoring technical service agreements in Stuttgart and Munich corridor qualification labs. For New Entrants and Emerging Players: Differentiate on plasma-enhanced deposition equipment-integrated service models for medical device miniaturization tiers. Target Karnataka and Tamil Nadu electronics manufacturing corridors where domestic formulation capabilities lag PLI-scheme demand creation. Pursue qualification lab co-location partnerships with Indian BIS standards bodies to compress market entry timelines. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules reshape the acquisition landscape toward fluorinated precursor-independent coating platforms. Long-term viability favors formulators with bio-based acrylate sourcing advantages and LED cure system integration capabilities. Watch ECHA SVHC candidate list expansion velocity as inflection indicator for formulation replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomers | Henkel Corporation's adhesives heritage secures captive acrylate supply for UV-curable automotive platforms. |
| Plasma-Enhanced Deposition Licensing | P2i Ltd's nanocoating technology commands premium positioning in smartphone waterproofing and medical device hermetic sealing tiers. |
| Coating Qualification Lab Co-location | Chase Corporation sustains diversified manufacturing scale across potting compounds for aerospace MIL-STD-202G validation protocols. |
| UV-Curable Bio-Based Formulation Convergence | REACH and RoHS compliance accelerates shift from solvent-based formulations in Stuttgart automotive electronics clusters. |
| Direct OEM Coating Center Installation | Tier-two suppliers in Bavaria bypass merchant coaters with captive dip and selective coating lines for inverter assemblies. |
Methodological Framework
Operator-level perspectives from coating formulators, automotive tier supplier procurement managers, aerospace certification engineers, and electronics manufacturing services plant directors anchored the qualitative base. Primary fieldwork combined with secondary validation from ECHA SVHC candidate list publications, EPA VOC emission threshold documentation, SEC 10-K filings from diversified coating suppliers, and customs trade data for specialty monomer flows. Bottom-up coating consumption estimates triangulated against top-down automotive electronics production forecasts.
Sensitivity analysis tested forecast robustness across regulatory acceleration scenarios and feedstock price volatility assumptions. Segmentation dimensions modeled include coating type, deposition technology, end-use vertical, application method, and regional regulatory cluster. CAGRs derived from regression analysis of historical qualification cycle compression and EV powertrain thermal load specifications. Industry-specific inputs encompassed IPC-CC-830 revision timelines and EU F-Gas Regulation phase-down schedules.
The analysis sits within stated boundaries; outcomes outside REACH SVHC disclosure mandate enforcement intensity or automotive electrification pace assumptions would require recalibration. Forecasts reflect documented assumptions regarding formulation substitution elasticities and tier supplier consolidation trajectories. Practitioners should keep alternative scenarios live as ECHA candidate list expansion and EPA VOC threshold divergence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Sputter Coater Market
Coatings
Thermal Barrier Coatings Market
Coatings
Global Nanocoatings Market
Coatings
South America Thermal Spray Market
Coatings
ASEAN Protective Coatings Market
Coatings
Global Optical Coating Market
Coatings
North America Hydrocarbon Fire Intumescent Coating Services Market
Coatings
Coating Agents for Synthetic Leather Market
Coatings
Fire Retardant Coatings Market
Coatings
Automotive Refinish Coatings Market
Coatings
Anti-Corrosion Nanocoatings Market
Coatings
OEM Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
Global Battery Coating Market
Coatings
Europe Coil Coatings Market
Coatings
Global Surface Protection Films Market