
 Nigeria Protective Coatings Market | 2026-2036
Nigeria Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Protective Coatings Market Foresight
Preventive maintenance contracts bundled with coating application services is repositioning how Nigerian industrial buyers procure corrosion protection. Akzo Nobel N.V. leverages its global technical service network to anchor premium marine and offshore accounts across the Niger Delta. Berger Paints Nigeria Plc sustains domestic manufacturing scale that competes aggressively on lead times for construction sector projects. Ultimate Paint and Coatings Limited specializes in customized alkyd formulations for the automotive refinishing segment in Lagos and Kano.
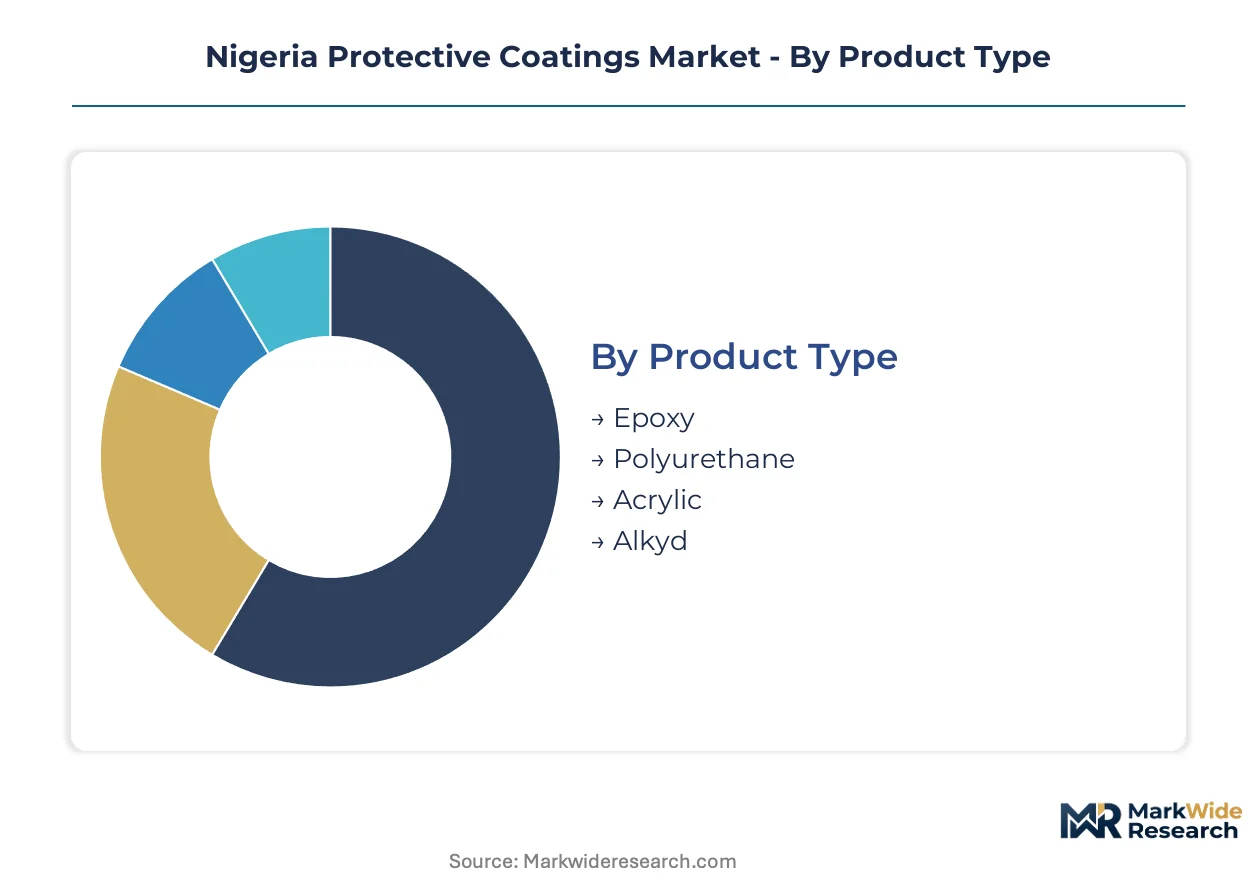
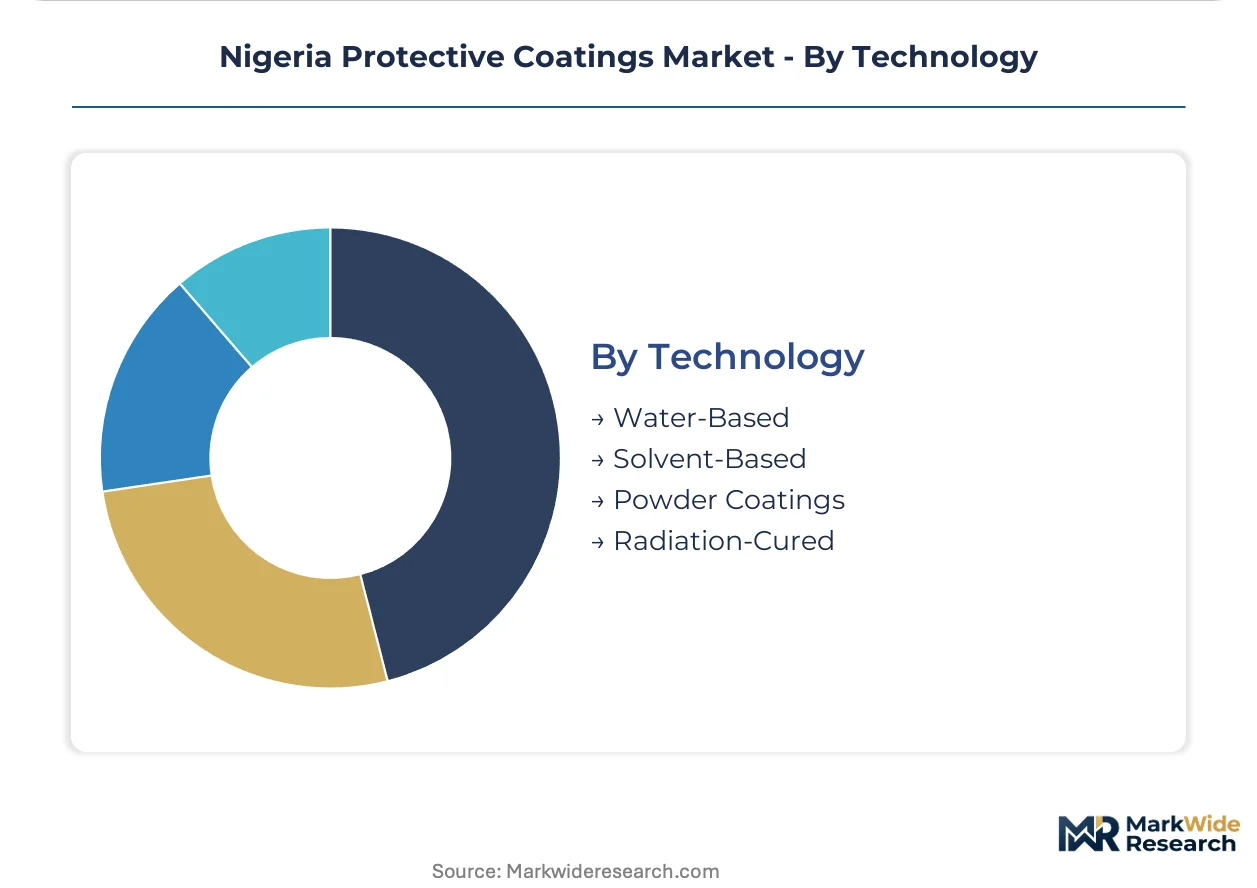
Nigeria protective coatings comprise resin-based formulations—epoxy, polyurethane, acrylic, and alkyd systems—engineered to form adherent barrier films that shield substrates from moisture, chemical attack, and ultraviolet degradation, typically applied at dry film thicknesses ranging from 75 to 500 microns depending on service environment. Epoxy coatings dominate the product type structure due to their superior adhesion and chemical resistance in petrochemical and marine exposures, while polyurethane variants command premium positioning in applications demanding flexibility combined with weatherability. Water-based technology represents the fastest-growing formulation category as SON environmental enforcement and industrial buyer sustainability mandates displace solvent-borne systems in interior and light-duty metal coating applications.
The Standards Organisation of Nigeria (SON) enforces product certification and VOC emission limits that directly shape formulation choices and import qualification pathways for coating suppliers. The Department of Petroleum Resources (DPR), now integrated into the Nigerian Upstream Petroleum Regulatory Commission (NUPRC), mandates offshore asset integrity standards that specify coating performance criteria for platform and pipeline operators. Stakeholders must monitor regulatory alignment between SON technical committees and evolving NUPRC asset integrity rules to anticipate compliance-driven product reformulation requirements and certification timeline adjustments.
Market Dynamics
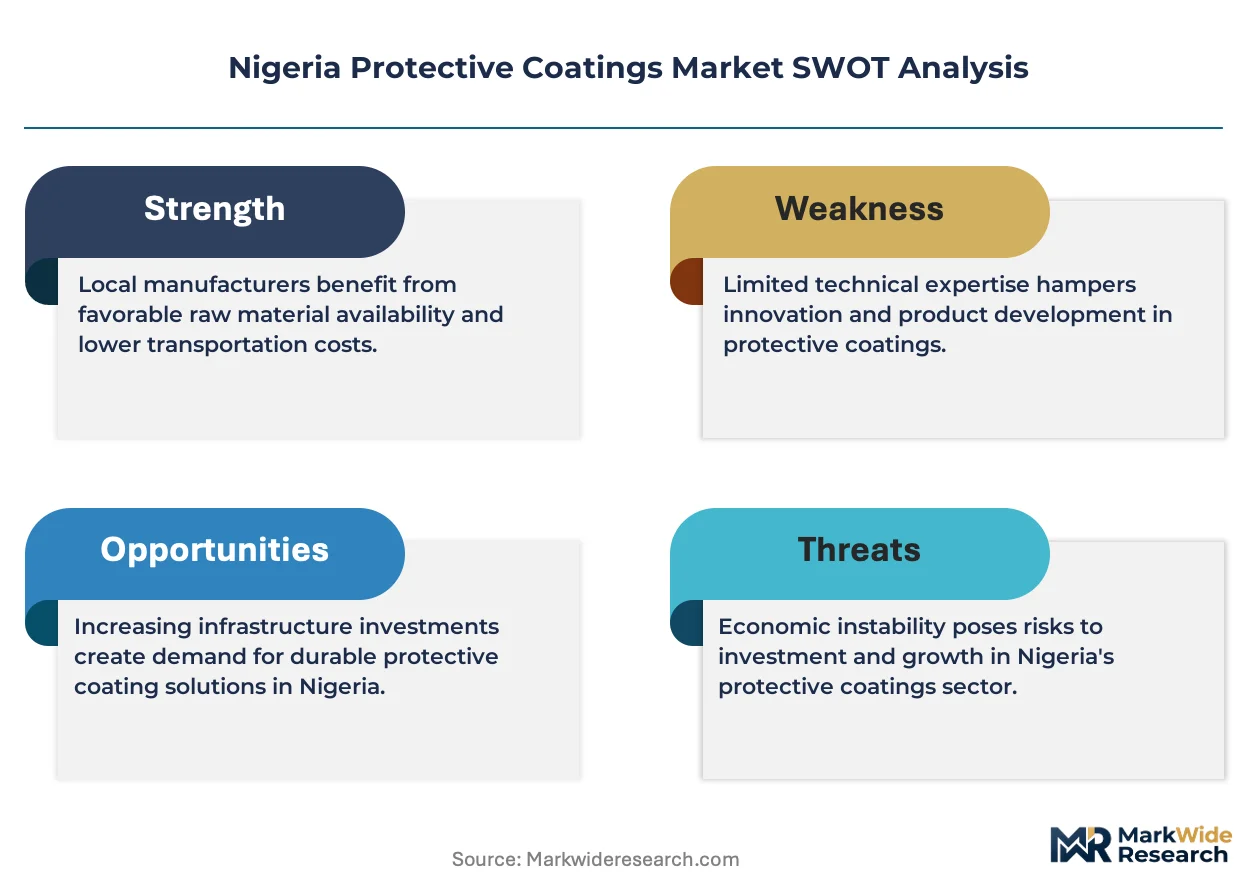
SON's VOC emission mandates are compressing solvent-borne formulation margins while accelerating water-based technology substitution across industrial and architectural coating procurement. This regulatory compression is redrawing competitive positioning between domestic blenders and import-dependent distributors.
Growth Catalysts
- NUPRC Asset Integrity Mandates:Offshore platform operators in the Niger Delta must demonstrate coating performance compliance, creating recurring demand for epoxy and polyurethane marine systems.
- Lagos-Port Harcourt Infrastructure Rehabilitation:Bridge deck and pipeline renewal projects specify high-build epoxy coatings, anchoring volume for construction-grade formulations.
- Water-Based Technology Migration:SON enforcement of VOC limits is displacing solvent-borne alkyd interior coatings in light-duty metal applications across manufacturing facilities.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy resin and isocyanate prices fluctuate with naphtha and propylene supply, squeezing formulation margins for domestic blenders.
- Import Dependency for Specialty Additives:Corrosion inhibitors and high-performance pigments concentrate in European and Asian supplier bases, exposing buyers to currency and shipping cost swings.
- Technical Limitation in Humid Application:Water-based systems face extended cure times and adhesion risks during Nigeria's rainy season, restricting deployment windows.
Strategic Opportunities
- Kano Automotive Refinishing Cluster:Northern Nigeria's commercial vehicle repair density remains underpenetrated by organized coating distributors, offering channel expansion potential.
- Preventive Maintenance Contract Bundling:Industrial buyers increasingly procure coating application as integrated service packages rather than standalone material purchases.
- SON Certification Acceleration:Fast-track product registration pathways for low-VOC formulations create first-mover advantage for compliant suppliers.
Industry Challenges
- Skilled Applicator Shortage:Surface preparation and spray application expertise for high-performance marine coatings remains concentrated in Port Harcourt and Lagos, limiting project scalability.
- Certification Timeline Compression:SON laboratory testing backlogs and documentation requirements delay product launch schedules by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Protective Coatings Market |
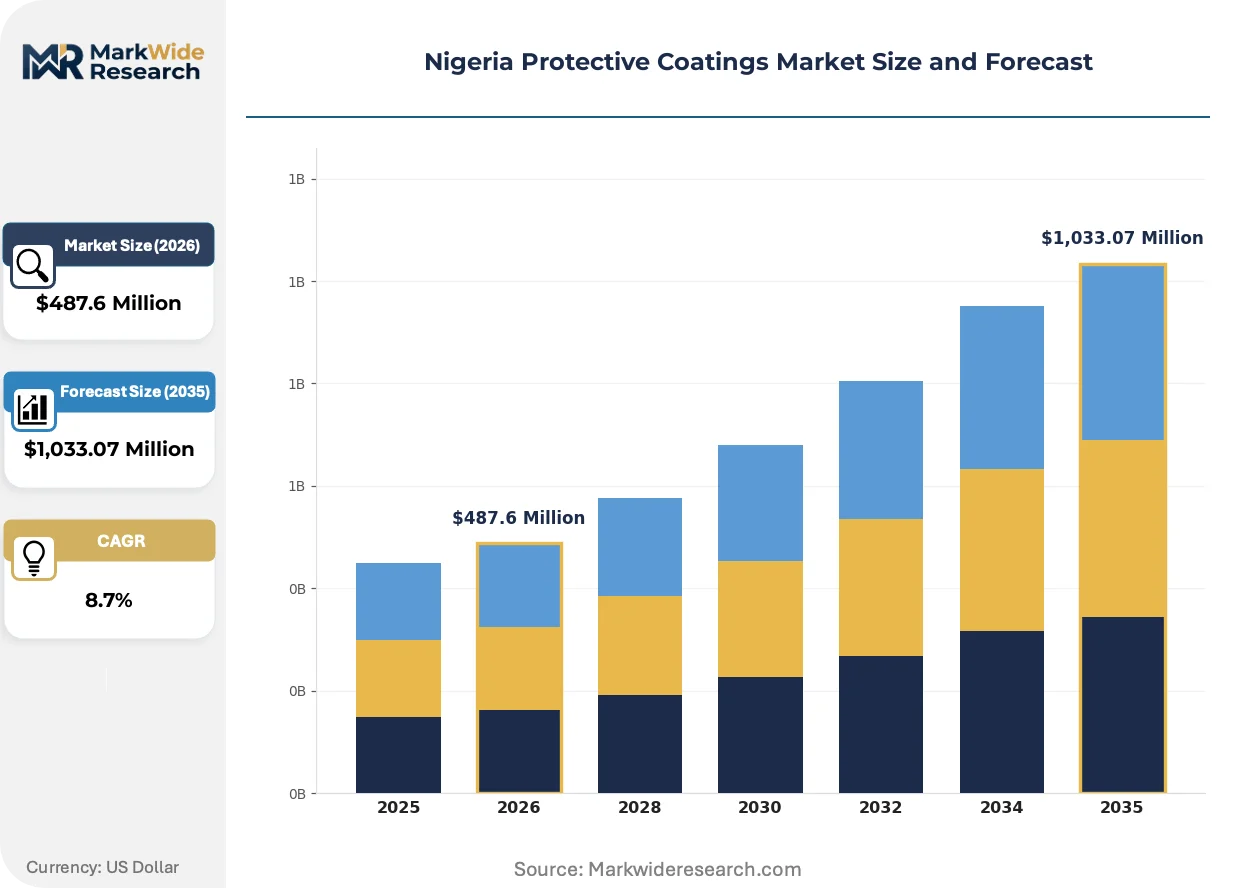
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Alkyd End User: Construction, Automotive, Marine, Industrial Application: Floor Coatings, Protective Metal Coatings, Wall Coatings, Wood Coatings Technology: Water-Based, Solvent-Based, Powder Coatings, Radiation-Cured |
| Companies Covered | Akzo Nobel N.V., Ultimate Paint and Coatings Limited, Berger Paints Nigeria Plc, First Paint and Coating Industries Limited, PPAN Paints and Coatings Limited, CAP Plc, Jotun Powder Coatings, Meyer Plc, PPG Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Protective Coatings Market Shifts & Advancements
Formulation chemistry and application economics are converging around environmental compliance and service integration, compressing traditional product-centric business models.
Hybrid epoxy-siloxane technology is unifying chemical resistance and UV durability in single-coat systems for offshore platform topsides. Nigerian marine contractors are specifying these formulations to reduce maintenance cycle frequency. The technology is unifying previously separate primer and topcoat procurement into simplified material packages.
SON's phased VOC emission limits for architectural and industrial coatings are forcing reformulation of solvent-borne alkyd and polyurethane product lines. Domestic manufacturers face capital expenditure for water-borne production equipment or import qualification for compliant finished goods. Light-duty metal coating applications in consumer goods manufacturing show fastest compliance migration.
Integrated coating-plus-application contracts are displacing material-only procurement in petrochemical maintenance. Nigerian industrial buyers now specify performance warranties rather than dry film thickness metrics, transferring technical risk to applicator-contractors. This shift concentrates most visibly in Niger Delta offshore maintenance procurement.
Nigeria Protective Coatings Market Segmentation
Protective coatings procurement in Nigeria diverges sharply across asset types, with petrochemical operators prioritizing chemical resistance specifications while construction buyers optimize for application speed and humidity tolerance. Understanding these segment-specific decision hierarchies reveals where formulation investments convert to contracted volume.
Product Type:
Buyers select resin chemistry based on substrate exposure severity and recoat interval requirements, with marine and petrochemical procurement favoring systems that withstand cyclic immersion.
- Epoxy:Two-component amine-cured systems deliver superior adhesion to blast-cleaned steel and resistance to hydrocarbon exposure. Demand concentrates in Niger Delta offshore platform maintenance and Lagos bridge rehabilitation, where NUPRC asset integrity mandates specify epoxy performance criteria for subsea and splash-zone applications.
- Polyurethane:Aliphatic isocyanate-based formulations combine UV stability with flexibility for dynamic structures. Procurement clusters in Port Harcourt pipeline exteriors and Kano automotive refinishing, driven by requirements for gloss retention and abrasion resistance in high-UV environments.
- Acrylic:Thermoplastic emulsions serve decorative and light-duty protective applications across consumer goods manufacturing facilities in Lagos and Ibadan.
- Alkyd:Oil-modified polyester resins retain share in interior metal priming where solvent-borne drying speed outweighs VOC compliance pressure.
Epoxy leads on scale through offshore and infrastructure anchoring; polyurethane leads on momentum through automotive refinishing expansion and UV-durability specification upgrades.
End User:
Customer procurement sophistication varies with asset criticality, with marine and industrial buyers demanding certified applicator networks while construction segments prioritize material availability.
- Construction:Bridge deck, commercial building, and pipeline contractors specify high-build systems for concrete and steel protection. Volume concentrates in Lagos-Port Harcourt corridor rehabilitation projects, where SON-compliant water-based interior coatings are displacing solvent-borne alkyds in light-duty metal applications.
- Marine:Offshore platform operators and shipyard maintenance facilities procure specialty systems for immersion service. Niger Delta petrochemical corridor drives procurement of hybrid epoxy-siloxane and pure epoxy formulations, with NUPRC regulations mandating documented coating performance for asset integrity compliance.
- Automotive:Commercial vehicle repair density in Kano and Lagos supports refinishing demand for polyurethane clearcoats and alkyd enamels.
- Industrial:Manufacturing facilities across Ogun and Anambra states apply protective metal coatings to process equipment and structural steel.
Marine commands premium pricing through regulatory compliance burden; construction delivers volume through infrastructure renewal acceleration.
Application:
Surface-specific formulation requirements dictate dry film thickness targets and cure chemistry selection, with horizontal traffic-bearing surfaces demanding hardest-wearing systems.
- Protective Metal Coatings:Steel substrate protection dominates expenditure across all end-use sectors. Petrochemical pipelines, offshore platforms, and bridge structures specify 250-500 micron epoxy and polyurethane systems, with procurement bundled into preventive maintenance contracts that transfer technical risk to applicator-contractors.
- Floor Coatings:Epoxy and polyurethane self-leveling systems serve manufacturing and warehousing facilities. SON VOC enforcement is accelerating water-based epoxy migration in Lagos industrial parks where interior air quality standards tighten.
- Wall Coatings:Acrylic emulsions and alkyd systems protect concrete and masonry in commercial and institutional buildings.
- Wood Coatings:Preservative and decorative finishes serve limited demand in furniture manufacturing and marine decking applications.
Protective metal coatings anchor revenue through asset-critical infrastructure exposure; floor coatings are expanding most quickly through manufacturing facility compliance upgrades.
Technology:
Formulation platform selection increasingly reflects regulatory pressure rather than purely technical optimization, with SON VOC limits compressing solvent-borne deployment windows.
- Water-Based:Acrylic and epoxy emulsions displace solvent-borne systems in interior and light-duty metal applications. Manufacturing facilities in Lagos and Port Harcourt are migrating fastest due to combined SON enforcement and corporate sustainability procurement mandates.
- Solvent-Based:High-solids epoxy and polyurethane systems retain necessity for high-performance marine and petrochemical exposure where water-based cure reliability falters in humid conditions.
- Powder Coatings:Thermoset epoxy and polyester powders serve factory-applied metal finishing for consumer goods and automotive components.
- Radiation-Cured:UV-curable acrylics occupy niche wood and plastic coating applications with limited Nigerian manufacturing presence.
Solvent-based retains share in high-performance marine specification; water-based claims steepest expansion trajectory through regulatory compliance and interior application growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ghana's protective coatings sector lags Nigeria's scale but mirrors its regulatory trajectory, while South Africa's mature industrial base offers a contrasting demand profile anchored by mining and automotive manufacturing rather than petrochemical infrastructure.
Lagos State
Bridge rehabilitation along the Lagos-Ibadan Expressway and port modernization at Apapa anchor epoxy coating procurement. SON's VOC enforcement accelerates water-based formulation migration in Ikeja industrial parks. The Lekki Free Trade Zone concentrates new manufacturing facilities specifying compliant interior metal coatings.
Rivers State
NUPRC asset integrity mandates drive recurring demand for marine-grade epoxy systems across offshore platforms. Port Harcourt's cluster of oilfield service contractors bundles coating application with preventive maintenance contracts. The Onne Oil and Gas Free Zone hosts specialized applicator networks certified for splash-zone specifications.
Delta State
Warri and Escravos petrochemical corridors sustain procurement of high-build polyurethane pipeline coatings. The Nigerian Maritime Administration and Safety Agency (NIMASA) regulations for vessel maintenance create secondary demand for marine systems. Local blending facilities in Sapele compete on lead times for construction-grade alkyds.
Kano State
Commercial vehicle refinishing density supports polyurethane clearcoat demand in northern Nigeria's automotive repair cluster. BUA Cement's Kalambaina plant and other industrial installations specify protective metal coatings for process equipment. The Kano Economic City initiative is expanding manufacturing floor coating requirements.
Ogun State
Ogun Guangdong Free Trade Zone and Agbara industrial corridor drive manufacturing facility coating procurement. SON-compliant water-based epoxies displace solvent-borne systems in warehouse and production floor applications. The Lagos-Ogun industrial belt's concentration of consumer goods manufacturers accelerates interior air quality-driven specification changes.
Nigeria Protective Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with petrochemical procurement favoring technical service networks while construction buyers prioritize material availability and lead time compression. The market structures around three tiers: multinational formulators with global certification portfolios, domestic manufacturers with scaled local production, and specialized blenders serving niche automotive and marine applications. Strategic moves concentrate on preventive maintenance contract bundling and SON certification acceleration for low-VOC formulations.
Within the multinational tier, Akzo Nobel N.V. and PPG Industries exemplify technical service-intensive positioning for offshore and marine accounts. Berger Paints Nigeria Plc and Meyer Plc represent domestic manufacturing scale competing on construction sector responsiveness. Ultimate Paint and Coatings Limited occupies the specialized refinishing segment serving Kano and Lagos automotive clusters.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Ultimate Paint and Coatings Limited |
| Berger Paints Nigeria Plc |
| First Paint and Coating Industries Limited |
| PPAN Paints and Coatings Limited |
| CAP Plc |
| Jotun Powder Coatings |
| Meyer Plc |
| PPG Industries |
| Others |
Supply & Pricing Matrix
Skilled applicator concentration in Port Harcourt and Lagos compresses labor-cost differentials between premium marine coating tiers and standard construction-grade formulations, widening pricing spreads as SON certification requirements add compliance premiums to technical service bundles.
Pricing Analysis
Capacity additions in Ogun and Lagos industrial corridors are reshaping price floors for water-based epoxy formulations as domestic manufacturers scale production. Three-tier pricing structure across premium certified marine, standard industrial, and economy construction grades differentiates on SON compliance status and applicator certification level. Price erosion runs through solvent-borne alkyd tiers as VOC enforcement accelerates substitution toward compliant water-based alternatives. Construction contractors in bridge and pipeline segments exhibit highest price sensitivity, while Niger Delta offshore operators prioritize performance warranties over unit material costs.
Supply Chain Analysis
Regional distribution centers in Lagos and Port Harcourt operate hub-and-spoke patterns feeding applicator networks across the Niger Delta petrochemical corridor. Epoxy resin and isocyanate feedstocks draw from European and Asian supplier bases, with corrosion inhibitors and high-performance pigments anchored in specialty chemical manufacturing clusters in Germany, Netherlands, and China. Single-source vulnerability concentrates in marine-grade additive imports exposed to currency fluctuation and shipping cost volatility. Distribution runs through authorized dealer networks certified for SON product registration and technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigeria's protective coatings market functions as a stable compounder, with NUPRC asset integrity mandates generating recurring procurement cycles that insulate volume from short-term construction volatility.
For Market Incumbents: Deploy preventive maintenance contract bundling to lock in recurring revenue streams across Niger Delta offshore accounts. Deepen technical service capabilities in Port Harcourt and Warri to defend against emerging regional applicator networks. Accelerate SON certification pipelines for low-VOC formulations to capture first-mover positioning as enforcement tightens in Lagos industrial zones. For New Entrants and Emerging Players: E-commerce platforms serving Kano automotive refinishing clusters offer channel entry with lower certification overhead than marine segments. Target underpenetrated northern Nigeria commercial vehicle repair density with polyurethane clearcoat formulations tailored to high-UV durability requirements. Partner with established SON-registered distributors to bypass four-to-eight-month product launch timelines. For Investors and Strategic Acquirers: Domestic paint manufacturers with scaled blending capacity are the most active acquirer in this space, consolidating regional applicator networks to capture integrated service margins. Five-to-ten-year viability rests on water-based technology transition execution and NUPRC regulatory alignment. Monitor SON laboratory testing backlog resolution as signal for certification timeline compression and product launch acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captures margin compression from naphtha and propylene feedstock volatility for domestic blenders. |
| SON Certification Fast-Track Investment | Accelerates product registration timelines for low-VOC formulations ahead of enforcement tightening. |
| Preventive Maintenance Contract Expansion | Bundles coating application with material supply, transferring technical risk to applicator-contractors. |
| Kano Distribution Channel Establishment | Accesses northern Nigeria automotive refinishing density with lower competitive intensity than Lagos. |
| Hybrid Epoxy-Siloxane Formulation Launch | Unifies chemical resistance and UV durability for simplified offshore platform maintenance procurement. |
Research Methodology
Multiple input streams — primary interviews with coating formulators, applicator contractors, and petrochemical procurement managers, alongside secondary trade data and regulatory filings — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included technical directors at multinational coating suppliers, plant managers at domestic blending facilities, NUPRC compliance officers, and SON certification specialists. Secondary validation drew from Nigerian Customs Service import records, NUPRC asset integrity guidelines, SON product registration databases, and industry association technical bulletins.
Data-stream reconciliation anchored volume and value outputs across resin chemistry, end-use sector, application surface, and formulation technology dimensions. CAGRs were derived from segment-level demand modeling incorporating infrastructure project pipelines, offshore platform maintenance schedules, and regulatory compliance transition curves. Forecast inputs included petrochemical feedstock price trajectories, SON enforcement intensity projections, and applicator network expansion rates.
The model assumes a particular technology adoption path; alternative pathways for water-based epoxy cure reliability in humid conditions would alter the outlook for interior metal coating substitution rates. Forecasts reflect documented assumptions regarding NUPRC regulatory stability and naphtha derivative pricing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
United States Automotive OEM Coatings Market
Coatings
United States Floor Coatings Market
Coatings
Trim Coatings Market
Coatings
Coating Resins Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Qatar Protective Coatings Market
Coatings
Acrylic Protective Coating Market
Coatings
ASEAN Protective Coatings Market
Coatings
Global Passive Fire Protection Coatings Market
Coatings
Electron Beam Curable Coating Market
Coatings
PU Coatings Market
Coatings
Protective Coatings Market
Coatings
Global Sputter Coater Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
Coating Pigments Market
Coatings
Japan Marine Coatings Market