
 Hull Coatings Market | 2026-2036
Hull Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Hull Coatings Market Foresight
Specialized marine coating chemists and applicators is reorganizing supply capacity as yards adopt faster dry-docking schedules and advanced hull preparation robotics. PPG Industries sustains broad geographic coverage through integrated marine distribution networks. Jotun specializes in high-performance antifouling systems for deep-water commercial fleets. Hempel A/S anchors European supply through captive manufacturing of solvent-free epoxy primers.
Hull coatings are protective film systems applied to submerged and weather-exposed ship surfaces, typically comprising epoxy binders, copper-based biocides, silicone elastomers, or fluoropolymer resins, designed to prevent biofouling accumulation, galvanic corrosion, and hydrodynamic drag degradation. Antifouling formulations command the largest product share due to mandatory dry-dock inspection cycles, while self-cleaning silicone technologies are gaining fastest adoption among cruise and container operators seeking fuel savings. Commercial vessels generate the dominant application demand, though offshore structures present higher per-unit coating value due to extreme cathodic protection requirements and splash-zone durability specifications.
The International Maritime Organization enforces MARPOL Annex VI emission standards that directly link hull performance to fuel consumption compliance, while the EU Green Deal's Fit for 55 framework extends carbon intensity benchmarks to maritime supply chains. The EPA regulates copper discharge from antifouling leachates in US harbors, pushing manufacturers toward biocide-alternative chemistries. Stakeholders must monitor how pending IMO lifecycle carbon rules and regional port authority green tariff schemes reshape product certification requirements and yard procurement criteria.
Market Dynamics
The International Maritime Organization's MARPOL Annex VI fuel efficiency mandates are compressing dry-dock cycles and forcing fleet operators to prioritize hull performance as a direct compliance lever.
Growth Catalysts
- IMO carbon intensity regulations:The CII rating system penalizes vessels with fouled hulls, creating mandatory demand for high-performance antifouling systems across container and tanker fleets.
- Robotics-enabled surface preparation:Automated grit-blasting and laser-cleaning systems reduce dry-dock turnaround times, allowing yards to process more vessels per quarter.
- South Korean shipbuilding clusters:Concentrated newbuild activity around Ulsan and Geoje generates concentrated procurement volumes for coating applicators and distributors.
Market Restraints
- Copper biocide supply concentration:Chilean and Peruvian mining output volatility affects copper pyrithione availability, squeezing formulation costs for traditional antifouling producers.
- Silicone raw material oligopoly:Fluoropolymer resin production concentrates among a handful of German and Japanese chemical suppliers, creating single-source risk for self-polishing coating lines.
- REACH authorization delays:ECHA's prolonged substance evaluation timelines for zinc pyrithione alternatives extend product certification cycles by 18-24 months.
Strategic Opportunities
- Brazilian pre-salt fleet expansion:Petrobras's floating production storage and offloading vessel orders create demand for extreme-depth cathodic protection coatings with 25-year service life specifications.
- EU Green Deal port tariffs:The Fit for 55 framework's green berth incentives reward vessels with documented hull performance, creating premium pricing power for certified low-friction systems.
- Drone-based hull inspection:Remote underwater vehicle and aerial drone survey services enable condition-based recoating decisions, opening aftermarket service revenue streams beyond scheduled dry-dock events.
Industry Challenges
- Specialized applicator shortage:Certification requirements for spray-applied silicone elastomers exceed the supply of trained technicians in emerging ship repair hubs.
- Multi-layer system integration:Epoxy primer, tie-coat, and topcoat compatibility testing extends qualification timelines for new formulation introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hull Coatings Market |
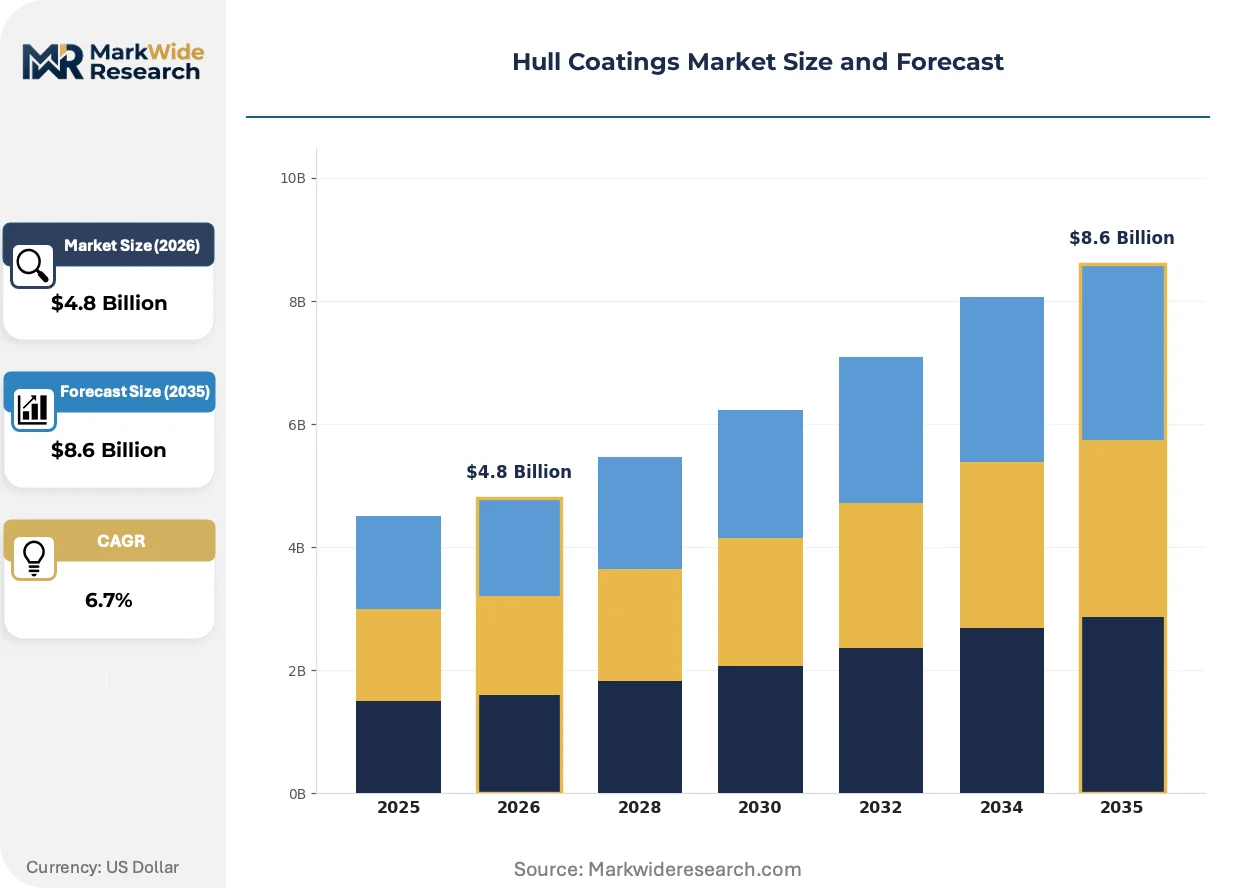
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Abrasion-Resistant, Antifouling, Anticorrosive, Self-Cleaning Application: Commercial Vessels, Recreational Boats, Fishing Boats, Offshore Structures Technology: Solvent-Based, Water-Based, High-Solids, Powder Coating End User: Shipbuilders, Marine Service Providers, Owners/Operators, Ship Repair Facilities |
| Companies Covered | Akzo Nobel N.V., PPG Industries Inc., Jotun, Hempel A/S, Chugoku Marine Paints Ltd., The Sherwin-Williams Company, Axalta Coating Systems Ltd., Nippon Paint Holdings Co. Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hull Coatings Market Shifts & Advancements
Coating chemistry is diverging along performance-versus-compliance axes as regulators ban legacy biocides and operators demand measurable fuel savings. Formulation science, application robotics, and procurement analytics are converging to redefine competitive advantage.
Silicone-based foul-release coatings are bifurcating the antifouling category into biocide-dependent and biocide-free camps. Cruise operators and premium container lines are adopting these systems for their measurable drag reduction and fuel savings. The technology is bifurcating procurement criteria, separating buyers who prioritize lifecycle cost from those optimizing for lowest initial application expense.
EPA's Vessel General Permit revisions are tightening copper discharge limits in US harbors, forcing manufacturers to accelerate biocide-alternative development. The industrial consequence is a pipeline shift toward hybrid organic biocide and purely physical foul-release systems. Deep-water commercial fleets operating on trans-Pacific routes face the steepest compliance cost increases, redirecting R&D budgets toward silicone and fluoropolymer platforms.
Ship operators are consolidating coating procurement under fleet-wide performance contracts that guarantee fuel consumption outcomes. The traditional specification-based purchasing model is losing ground to vendor-managed inventory and application service bundles. Japanese and South Korean container lines are pioneering these arrangements, tying coating supplier payments to documented vessel speed-power curve improvements.
Hull Coatings Market Segmentation
Hull coatings procurement diverges sharply across vessel types and regulatory jurisdictions, with product chemistry and application method determining compliance eligibility and lifecycle economics. Understanding where value concentrates within each dimension enables suppliers to align R&D and distribution investments with margin-accretive segments.
Product Type:
Margin pools concentrate in high-performance systems that deliver measurable fuel savings and extended dry-dock intervals, particularly those qualifying for EU Green Deal port tariff incentives.
- Antifouling:Copper-based biocide formulations dominate commercial fleet procurement due to mandatory inspection cycles under IMO MARPOL Annex VI. Container operators on trans-Pacific routes generate concentrated demand as CII rating penalties directly link hull fouling to compliance costs.
- Self-Cleaning:Silicone elastomer and fluoropolymer foul-release systems command premium positioning through documented drag reduction. Cruise lines and premium container operators adopt these biocide-free alternatives to meet EPA copper discharge limits in US harbors while capturing fuel savings.
- Anticorrosive:Epoxy primer systems with cathodic protection compatibility serve offshore structures and deep-water vessels requiring 25-year service life specifications.
- Abrasion-Resistant:Reinforced ceramic-filled coatings protect ice-class vessels and shallow-draft barges operating in abrasive littoral environments.
The dominant share belongs to Antifouling, while Self-Cleaning is closing the gap fastest through regulatory tailwinds and fleet decarbonization mandates.
Application:
Per-unit coating value escalates with structural complexity and environmental exposure severity, creating tiered pricing architecture across vessel categories.
- Commercial Vessels:Container ships, tankers, and bulk carriers drive baseline procurement volumes through fleet renewal programs concentrated in South Korean yards at Ulsan and Geoje. Dry-dock cycle compression under IMO fuel efficiency mandates sustains recurring demand for high-performance antifouling systems.
- Offshore Structures:Floating production storage and offloading vessels, platforms, and subsea equipment require extreme cathodic protection integration and splash-zone durability. Petrobras's Brazilian pre-salt fleet expansion exemplifies demand for 25-year specification coatings with specialized applicator certification requirements.
- Fishing Boats:Smaller vessel operators prioritize initial cost minimization over lifecycle performance, constraining penetration of premium silicone systems.
- Recreational Boats:Yacht and pleasure craft segments favor aesthetic finish quality and DIY application compatibility over commercial-grade specifications.
Commercial Vessels anchor procurement volumes, though Offshore Structures deliver the highest per-square-meter coating value through extreme performance requirements.
Technology:
Formulation chemistry determines regulatory compliance pathways and yard handling protocols, with solvent content directly affecting worker safety standards and emission permits.
- High-Solids:Reduced volatile organic compound formulations balance application efficiency with tightening ECHA REACH authorization requirements. European and East Asian yards adopt these systems to maintain throughput under stricter environmental permitting.
- Water-Based:Zero-solvent alternatives serve enclosed shipyard environments and applicator health compliance, though film formation challenges limit adoption in high-humidity coastal climates.
- Solvent-Based:Legacy systems retain cost advantage in price-sensitive segments despite regulatory pressure from EPA and EU emission frameworks.
- Powder Coating:Thermoset epoxy powders serve specialized offshore structural components requiring factory-controlled application conditions and thick-film edge protection.
High-Solids technology holds the installed base majority, while Water-Based formulations are expanding most quickly through regulatory phase-out schedules for solvent-containing alternatives.
End User:
Procurement authority fragmentation across the vessel lifecycle creates distinct customer segments with divergent technical sophistication and price sensitivity profiles.
- Owners/Operators:Fleet managers at Japanese and South Korean container lines pioneer performance-based contracting, tying supplier payments to documented speed-power curve improvements. These stakeholders control lifecycle coating economics and increasingly consolidate procurement under fleet-wide agreements.
- Shipbuilders:Newbuild yards in concentrated industrial clusters generate high-volume, specification-driven demand with compressed delivery timelines favoring established supplier relationships.
- Ship Repair Facilities:Dry-dock operators face faster turnaround pressures from robotics-enabled surface preparation, requiring coating systems compatible with automated grit-blasting and laser-cleaning workflows.
- Marine Service Providers:Third-party applicators and distributors serve fragmented regional demand with inventory and technical support services, though certification scarcity for spray-applied silicone elastomers constrains expansion.
Owners/Operators command the largest decision-making influence through lifecycle cost accountability, while Ship Repair Facilities are gaining procurement share fastest through dry-dock cycle compression and condition-based recoating adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium coating systems command pricing power in South Korean shipbuilding clusters, while Latin American operators absorb higher logistics costs for specialized offshore formulations. This asymmetry reflects divergent regulatory enforcement intensity and yard concentration patterns.
South Korea
Container fleet renewal programs at Hyundai Heavy Industries and Samsung Heavy Industries drive concentrated demand for IMO-compliant antifouling systems. The Ministry of Oceans and Fisheries enforces stringent volatile organic compound emission standards at Ulsan and Geoje shipyards. Coating applicators cluster around these industrial zones to serve compressed dry-dock schedules.
United States
EPA Vessel General Permit revisions tighten copper discharge limits in Los Angeles, Long Beach, and Houston harbors. Cruise operators and Jones Act tanker fleets accelerate adoption of biocide-free silicone foul-release systems. Gulf Coast repair facilities expand capacity to handle condition-based recoating contracts.
Brazil
Petrobras floating production storage and offloading vessel orders create demand for extreme-depth cathodic protection coatings with 25-year service specifications. The National Petroleum Agency mandates corrosion protection standards for pre-salt field infrastructure. Rio de Janeiro shipyards and Macaé service bases anchor coating procurement for offshore construction.
China
State-owned shipbuilders at Dalian, Shanghai, and Guangzhou consolidate procurement under fleet decarbonization mandates aligned with dual carbon goals. The Ministry of Ecology and Environment enforces emission permits for solvent-based coating application. Yangtze River Delta yards adopt robotics-enabled surface preparation to accelerate turnaround times.
Germany
Meyer Werft and Flensburger Schiffbau-Gesellschaft specialize in cruise vessel newbuilds requiring premium self-cleaning silicone systems. ECHA REACH authorization timelines for zinc pyrithione alternatives extend product certification cycles. Hamburg and Bremerhaven repair clusters serve North Sea and Baltic container feeder fleets.
Hull Coatings Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated chemical conglomerates controlling high-performance resin formulations and regional distributors capturing price-sensitive maintenance demand. The market structure concentrates among five multinational coating specialists with captive manufacturing networks. Three strategic archetypes dominate: full-system integrators with robotics partnerships, biocide-free formulation specialists, and regional applicator networks with inventory scale. Competitive moves center on performance-based contracting guarantees and automated application service bundles.
Among European-anchored specialists, Akzo Nobel N.V. and Hempel A/S exemplify the integrated formulation archetype with captive epoxy primer production. PPG Industries Inc. represents the geographic coverage model through marine distribution networks spanning multiple continents. Jotun occupies a position within the high-performance antifouling tier, serving deep-water commercial fleet operators with documented fuel efficiency outcomes. These three company structures illustrate how competitive positioning diverges between chemistry-led and logistics-led value capture strategies.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries Inc. |
| Jotun |
| Hempel A/S |
| Chugoku Marine Paints Ltd. |
| The Sherwin-Williams Company |
| Axalta Coating Systems Ltd. |
| Nippon Paint Holdings Co. Ltd. |
| BASF SE |
| Others |
Supply & Pricing Matrix
IMO MARPOL Annex VI certification gates both supplier qualification and price tiering simultaneously, as yards restrict procurement to coating systems with documented CII compliance performance while fleet operators pay premiums for biocide-free silicone formulations that satisfy EPA copper discharge limits in US harbors.
Pricing Analysis
South Korean shipbuilding clusters command 15-20% price premiums over Southeast Asian repair yards for equivalent antifouling specifications. Three-tier pricing structure across premium silicone foul-release, standard copper-biocide antifouling, and economy solvent-based systems dominates procurement. Price differentiation rests on IMO compliance certification grade and guaranteed fuel efficiency outcomes. Cost compression in economy tiers is intensifying because Brazilian and Chinese yards absorb higher logistics costs for specialized offshore formulations. Fishing boat operators exhibit highest price sensitivity, while Japanese container lines prioritize lifecycle cost over initial application expense.
Supply Chain Analysis
Inventory cycles for copper pyrithione and fluoropolymer resins extend 8-12 weeks due to concentrated mining and chemical processing capacity. Supply draws from Chilean and Peruvian copper concentrate, German and Japanese fluoropolymer resin production, and South Korean epoxy formulation. Single-source vulnerability concentrates in silicone elastomer precursors where three chemical conglomerates control global output. Distribution runs through captive marine networks at major coating specialists, with regional distributors serving fragmented repair yard demand in Mediterranean and Southeast Asian hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across applicator certification scarcity and drone-based hull inspection services, as IMO dry-dock cycle compression creates niches for specialized technical service providers beyond traditional coating supply.
For Market Incumbents: Shield market position by deepening captive manufacturing of solvent-free epoxy primers to offset REACH authorization delays for zinc pyrithione alternatives. Secure spray-applied silicone applicator certification capacity in South Korean and Chinese clusters before specialized technician shortages widen. Vertical integration into robotics-enabled surface preparation partnerships defends against emerging application-service bundlers. For New Entrants and Emerging Players: Anchor in Brazilian pre-salt FPSO maintenance cycles where 25-year coating specifications and extreme cathodic protection requirements exceed local applicator capacity. Target drone-based hull inspection and condition-based recoating advisory services as the most penetrable aftermarket segment. Go-to-market through Petrobras-approved service base partnerships in Macaé and Rio de Janeiro bypasses established distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biocide-free formulation R&D as EPA and ECHA regulatory timelines extend product certification cycles. Long-term viability favors integrated coating applicators with robotics partnerships and fleet-wide performance contracting capabilities. Acquisition target archetype: regional distributors with ISO-compliant inventory management and established South Korean or Chinese shipyard relationships. Watch for IMO lifecycle carbon rule finalization as inflection signal for premium silicone system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Contracting | Ties supplier payments to documented vessel speed-power curve improvements at Japanese and South Korean container lines. |
| Robotics-Enabled Application | Automated grit-blasting and laser-cleaning partnerships compress dry-dock turnaround at Ulsan and Geoje yards. |
| Biocide-Free Formulation Pipeline | Silicone and fluoropolymer R&D addresses EPA copper discharge limits in Los Angeles and Long Beach harbors. |
| Applicator Certification Scale-Up | Spray-applied silicone elastomer training programs alleviate technician scarcity in emerging repair hubs. |
| Drone Inspection Service Launch | Remote underwater vehicle surveys enable condition-based recoating decisions beyond scheduled dry-dock events. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with coating R&D directors, shipyard procurement managers, marine applicator technicians, and fleet operations executives; and secondary validation through customs trade data, IMO regulatory filings, ECHA substance evaluation records, and SEC 10-K disclosures from listed coating specialists. Bottom-up vessel fleet analysis triangulated against top-down market sizing from regional shipbuilding output statistics.
Across the projection horizon, the analytical framework modeled volume and value outputs by product chemistry tier, vessel type, application method, and regional regulatory cluster. CAGRs derived from regression analysis of historical coating procurement against fleet renewal cycles and dry-dock interval compression. Industry-specific forecast inputs incorporated copper pyrithione supply volatility indices and robotics adoption curves at major ship repair facilities.
Material uncertainties — Chilean mining output disruptions, ECHA authorization timeline extensions, and IMO carbon intensity rule finalization — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and shipyard capacity expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Yacht Coatings Market
Coatings
Anti-Corrosion Nanocoatings Market
Coatings
Japan Automotive OEM Coatings Market
Coatings
Asia-Pacific Coil Coatings Market
Coatings
Textile Coatings Market
Coatings
Ultraviolet (UV) Coatings Market
Coatings
Stain Resistance Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
Global Anti Slip Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
FBE Coatings Market
Coatings
Global Plastic Coatings Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Marine Deck Coatings Market
Coatings
Asia-Pacific Thermal Spray Market
Coatings
Global Conformal Coatings Market