
 Cranial Doppler Market | 2026-2036
Cranial Doppler Market Size, Share, and Industry Trends Forecast 2026-2036
Cranial Doppler Market Outlook
Modular platform designs that separate hardware acquisition from software subscription tiers is restructuring how hospitals evaluate total cost of ownership for neurovascular ultrasound investments. GE Healthcare leverages its installed base of imaging ecosystems to bundle transcranial Doppler modules with broader neurology workstation contracts. Koninklijke Philips anchors its competitive stance through integrated informatics that connect cerebral blood flow data to enterprise-wide patient records. Natus Medical specializes in neonatal and pediatric neurodiagnostic applications, occupying a defensible niche where clinical protocols demand specialized probe configurations.
Cranial Doppler encompasses non-invasive ultrasound systems that emit and receive high-frequency acoustic waves through the temporal bone to measure cerebral blood flow velocity, typically operating at 2 MHz for transcranial applications. These devices quantify hemodynamic parameters including mean flow velocity, pulsatility index, and cerebrovascular reactivity, serving primary clinical purposes in stroke risk stratification, vasospasm detection after subarachnoid hemorrhage, and sickle cell disease monitoring. Transcranial Doppler systems command the largest revenue pool due to their established reimbursement codes and mandatory use in specific neurocritical care protocols, while portable Doppler configurations represent the fastest-expanding segment as point-of-care neurology programs decentralize acute stroke triage from centralized catheterization labs. Pulsed wave Doppler technology maintains dominant share in hospital settings where depth-gated vessel specificity proves essential, though color Doppler imaging commands premium positioning where simultaneous anatomical visualization justifies higher capital expenditure.
FDA 510(k) clearance requirements govern device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for transcranial Doppler systems marketed in Europe. Japan's PMDA maintains distinct technical documentation requirements that prolong market entry timelines for manufacturers lacking prior Japanese regulatory experience. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market surveillance obligations under MDR Article 83, as connected Doppler platforms become standard in integrated neurovascular care networks.
Market Dynamics
Modular hardware-software decoupling is restructuring hospital capital allocation for neurovascular ultrasound, forcing vendors to defend recurring revenue streams against upfront equipment commoditization.
Growth Catalysts
- EU MDR Article 83 post-market surveillance:Mandatory clinical follow-up for transcranial Doppler devices creates replacement demand as legacy systems lack connectivity infrastructure for automated data capture.
- Sickle cell disease protocols:Expanded screening mandates in pediatric hematology departments drive dedicated pediatric probe procurement separate from general neurology installations.
- Japan's aging demographic:Prefectural stroke center certification requirements concentrate equipment orders in designated neurovascular hubs across Kanto and Kansai regions.
Market Restraints
- Piezoelectric crystal supply concentration:Single-source dependency on specialized 2 MHz transducer materials from limited Japanese and German suppliers creates input cost volatility.
- FDA 510(k) predicate device requirements:Substantial equivalence pathways for novel signal processing algorithms extend clearance timelines beyond 18 months for software-centric submissions.
- CT angiography substitution:Non-contrast perfusion imaging advances in emergency radiology departments displace transcranial Doppler for initial stroke triage in well-capitalized systems.
Strategic Opportunities
- India's district hospital tier:PLI scheme medical device incentives and CDSCO streamlined Class B approvals open procurement channels outside metro neurology centers.
- AI-assisted spectral interpretation:Machine learning integration with pulsed wave Doppler systems enables automated emboli detection without specialist sonographer presence.
- Subscription-based software tiers:Cloud-connected platforms separate hemodynamic analytics from hardware acquisition, creating recurring revenue pools in hospital system purchasing.
Industry Challenges
- Sonographer specialization shortage:Transcranial window acquisition requires neurovascular ultrasound certification that fewer radiology technologists pursue, constraining device utilization rates.
- Cybersecurity validation burden:FDA guidance on interconnected medical devices demands penetration testing and SBOM documentation that prolongs product release cycles for connected Doppler platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cranial Doppler Market |
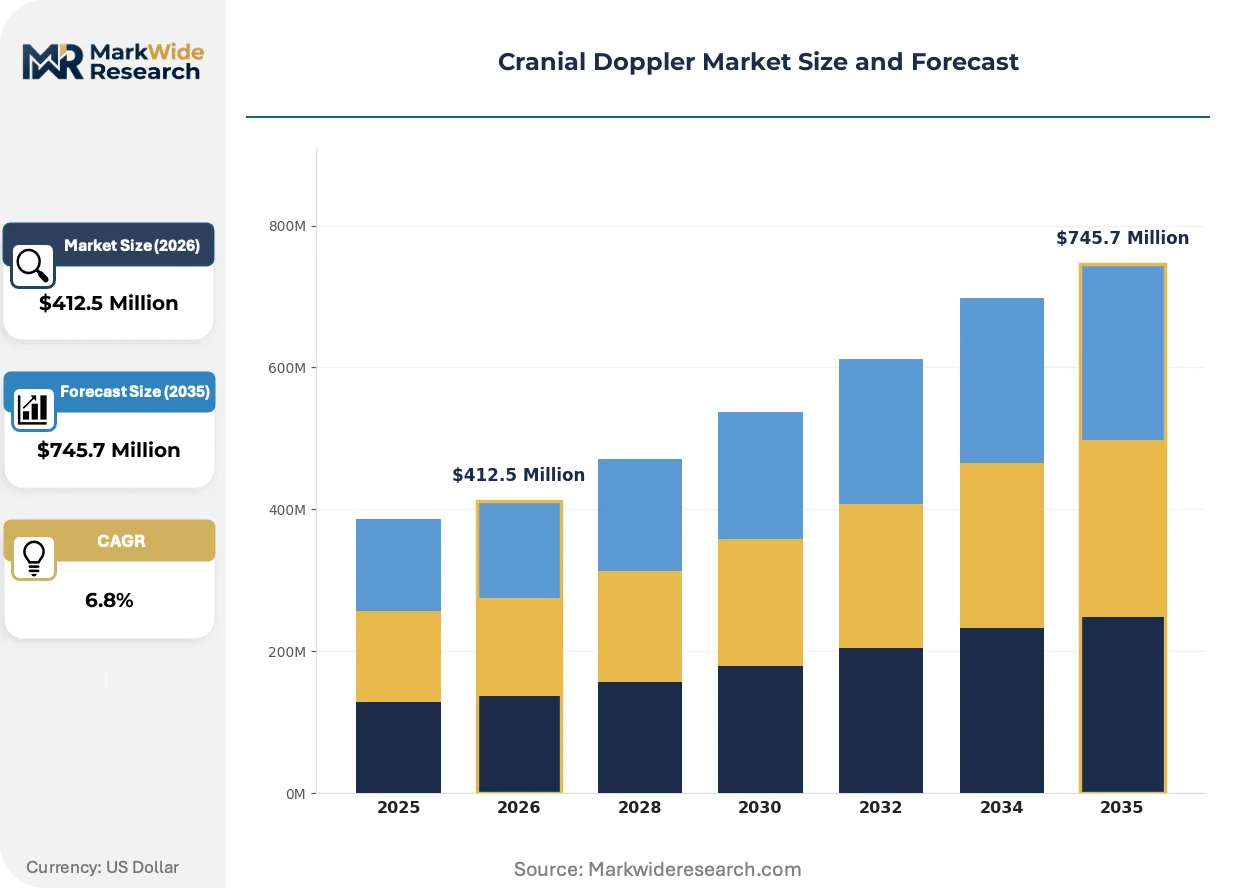
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transcranial Dopplers, Neurovascular Ultrasound Systems, Portable Dopplers, Fixed Dopplers End User: Hospitals, Clinics, Research Institutions, Diagnostic Centers Technology: Pulsed Wave Doppler, Continuous Wave Doppler, Color Doppler, Doppler Imaging Application: Stroke Diagnosis, Hemodynamic Monitoring, Cerebral Assessment, Research Applications |
| Companies Covered | GE Healthcare, Koninklijke Philips, Mindray Medical International, Compumedics Limited, Natus Medical Incorporated, Nihon Kohden Corporation, Viasonix, Atys Medical, Rimed Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cranial Doppler Market Strategic Shifts
Signal processing convergence with enterprise imaging informatics is compressing the boundary between dedicated neurovascular devices and general ultrasound platforms, reshaping vendor competitive moats around data integration rather than hardware performance.
Artificial intelligence-based spectral analysis is unifying embolus detection and vasospasm monitoring into automated interpretation workflows. Academic medical centers in the United States and Germany are piloting these systems to reduce specialist sonographer dependency. This convergence is compressing the value capture from hardware differentiation toward software licensing and clinical decision support subscriptions.
The EU Medical Device Regulation's stricter clinical evidence requirements for Class IIa devices are extending development timelines for transcranial Doppler manufacturers without established European notified body relationships. Manufacturers must generate prospective clinical data or systematic literature reviews that previous directives accepted through equivalence arguments. Smaller vendors without MDR transition experience are consolidating regulatory functions or withdrawing from European markets entirely.
Point-of-care neurology programs are fragmenting traditional capital equipment procurement by separating acute stroke triage from centralized catheterization lab budgets. Hospital systems in Japan and the United States are acquiring portable Doppler configurations through emergency medicine departmental funds rather than radiology capital allocations. This channel shift forces vendors to maintain dual sales organizations targeting emergency physicians alongside established neurology specialists.
Cranial Doppler Market Segmentation
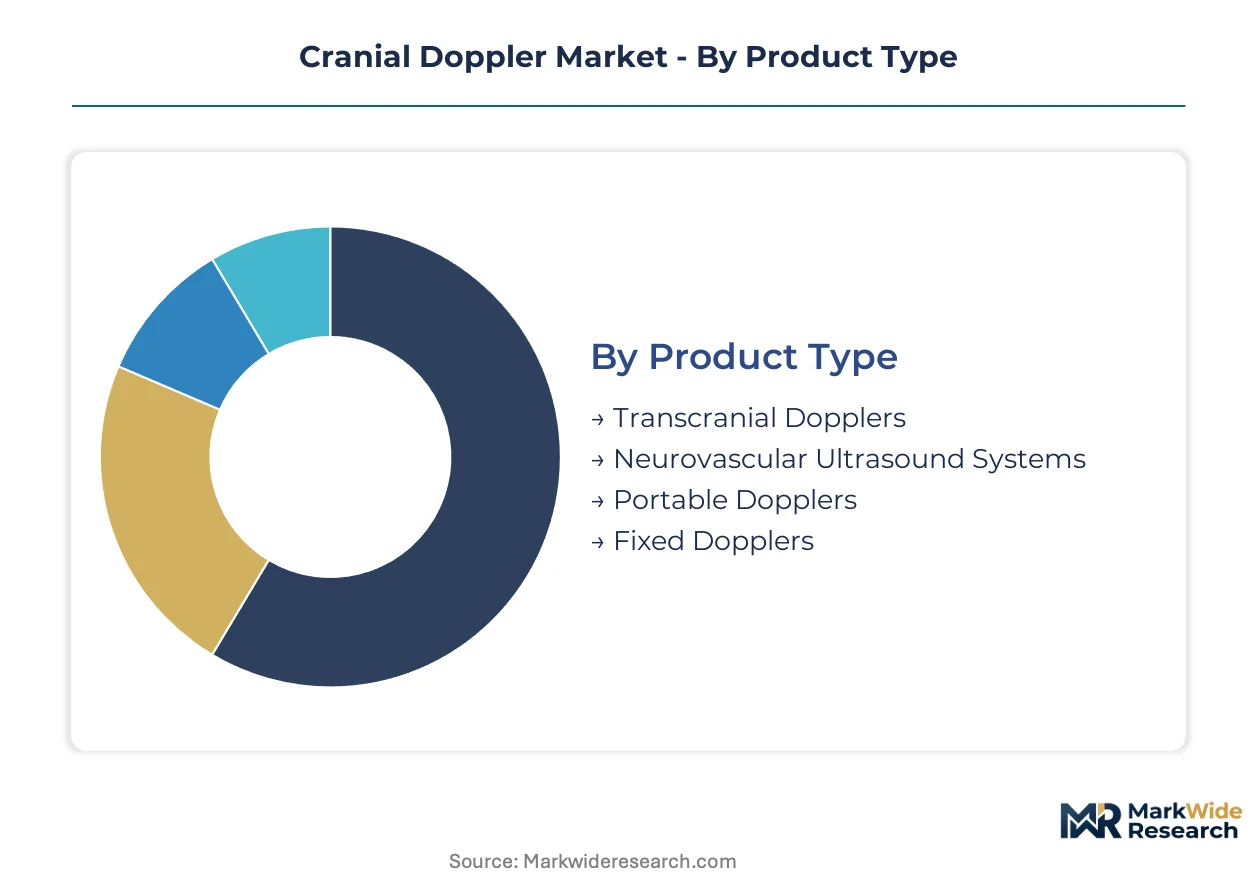
Segmentation in cranial Doppler markets reveals how procurement authority fragments across hospital departments and how technology choices cascade into entirely different regulatory pathways. Understanding these divisions exposes where vendors must maintain dual sales channels versus unified platform strategies.
Product Type:
Standardized hardware platforms dominate high-volume hospital contracts, while specialized configurations command premium positioning in pediatric and neurocritical care settings.
- Transcranial Dopplers:Fixed-installation systems operating at 2 MHz through the temporal bone window, measuring mean flow velocity and pulsatility index. Demand concentrates in certified stroke centers across the United States, Germany, and Japan where reimbursement codes mandate their use for vasospasm monitoring protocols. FDA 510(k) clearance requirements and established predicate device pathways sustain incumbent vendor positions.
- Neurovascular Ultrasound Systems:Integrated platforms combining transcranial Doppler with extracranial carotid imaging in unified workstations. Hospital neurology departments in the United States and Germany prioritize these for comprehensive cerebrovascular assessment, though capital expenditure thresholds limit penetration in district-tier facilities.
- Portable Dopplers:Battery-powered configurations enabling point-of-care neurology outside radiology suites. Emergency medicine departments in Japan and the United States are acquiring these through separate departmental budgets.
- Fixed Dopplers:Permanent installation systems tethered to dedicated neurovascular laboratories. Research institutions and academic medical centers maintain these for standardized longitudinal studies.
Leading the category by volume: Transcranial Dopplers. Growing fastest: Portable Dopplers.
End User:
Procurement authority varies dramatically by setting, with hospitals consolidating purchasing through enterprise imaging contracts while research institutions negotiate directly with specialized vendors.
- Hospitals:Integrated delivery networks in the United States and Germany negotiate enterprise contracts bundling cranial Doppler modules with broader imaging ecosystems. EU MDR Article 83 post-market surveillance requirements are accelerating replacement cycles for legacy systems lacking connectivity infrastructure.
- Clinics:Outpatient neurology practices and community stroke prevention programs. CDSCO streamlined Class B approvals in India are opening procurement channels outside metro neurology centers.
- Research Institutions:Academic medical centers conducting longitudinal cerebrovascular studies. PMDA technical documentation requirements in Japan prolong market entry timelines for manufacturers lacking prior Japanese regulatory experience.
- Diagnostic Centers:Independent imaging facilities performing outsourced neurovascular assessment. These facilities prioritize portable configurations enabling mobile service delivery to nursing homes and rehabilitation centers.
Hospitals generate the largest equipment orders. Diagnostic centers are expanding most quickly as stroke risk stratification decentralizes from acute care settings.
Technology:
Depth-gated specificity versus real-time anatomical visualization defines the trade-off between pulsed wave and color Doppler architectures.
- Pulsed Wave Doppler:Depth-selective sampling enabling vessel-specific velocity measurement at defined intracranial locations. Hospital neurocritical care units rely on this technology for precise vasospasm detection following subarachnoid hemorrhage.
- Continuous Wave Doppler:Uninterrupted signal transmission without depth discrimination, suitable for screening applications where vessel localization is secondary to flow detection.
- Color Doppler:Two-dimensional flow mapping superimposed on anatomical B-mode imaging. Premium positioning in well-capitalized systems where simultaneous anatomical visualization justifies higher capital expenditure.
- Doppler Imaging:Spectral analysis with automated measurement packages reducing sonographer interpretation burden. AI-assisted spectral interpretation is enabling automated emboli detection without specialist presence.
Pulsed Wave Doppler holds the largest installed base. Color Doppler commands the steepest expansion trajectory as imaging capabilities integrate into emergency radiology workflows.
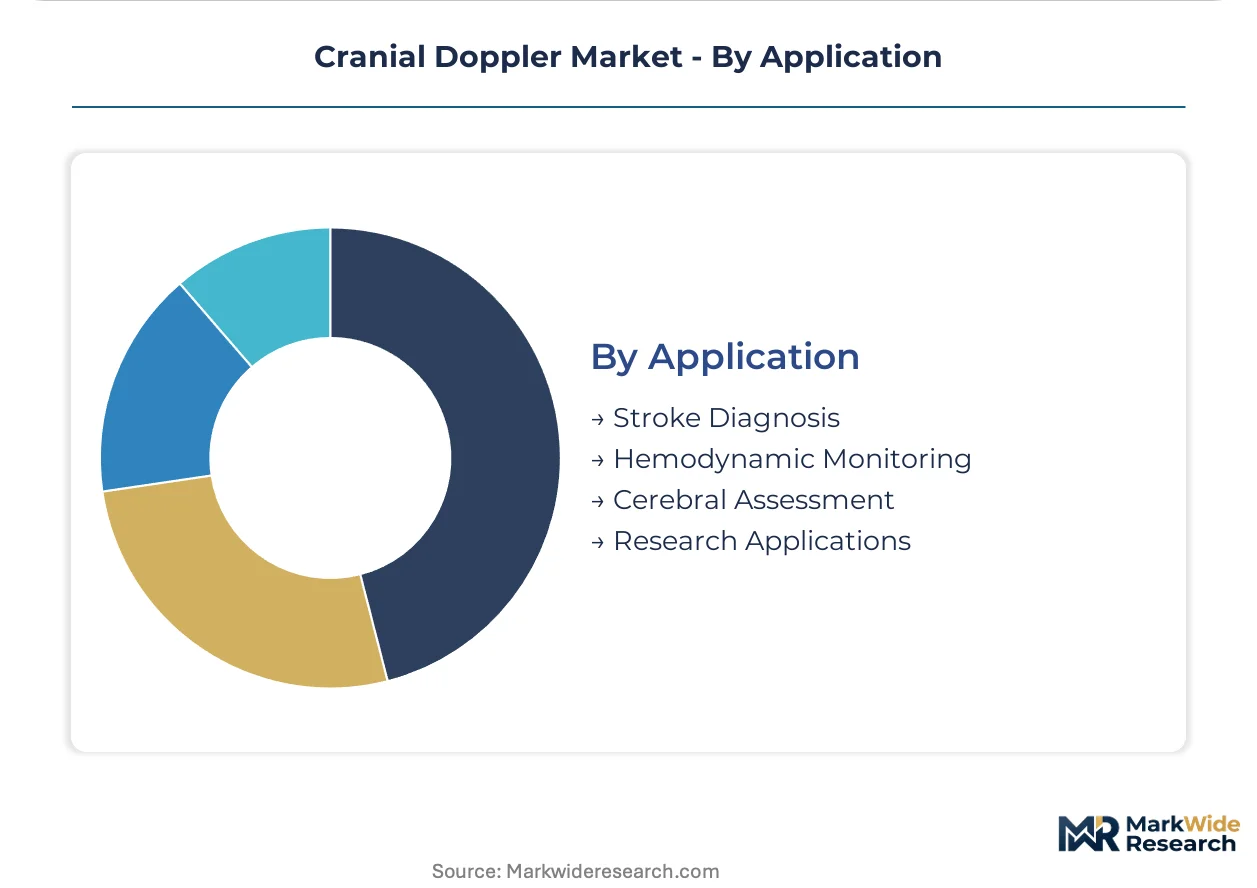
Application:
Clinical utility ranges from mandatory protocol-driven monitoring to discretionary research instrumentation with vastly different reimbursement profiles.
- Stroke Diagnosis:Acute triage and risk stratification for cerebrovascular events. Hospital neurology departments in Japan's Kanto and Kansai regions concentrate orders as prefectural stroke center certification requirements tighten.
- Hemodynamic Monitoring:Continuous or intermittent assessment of cerebral blood flow dynamics. Neurocritical care protocols following subarachnoid hemorrhage mandate transcranial Doppler surveillance for vasospasm detection.
- Cerebral Assessment:Comprehensive evaluation of cerebrovascular reserve and autoregulatory capacity. Pediatric hematology departments deploy specialized probe configurations for sickle cell disease screening protocols.
- Research Applications:Investigational studies of cerebral autoregulation, CO2 reactivity, and microemboli detection. Academic consortia in the United States and Germany pilot machine learning integration with spectral interpretation workflows.
Stroke diagnosis generates the highest procedure volume. Research applications are climbing the fastest as AI-enabled spectral analysis opens new investigational pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Japan and Germany where piezoelectric crystal fabrication and precision transducer assembly sustain component supply. Consumption gravitates toward the United States and established Asian markets where stroke center certification and aging demographics concentrate equipment procurement.
United States
Hospital neurology departments drive demand through stroke center certification requirements and established reimbursement codes for vasospasm monitoring. FDA 510(k) clearance pathways govern device commercialization with predicate device requirements extending timelines for novel signal processing algorithms. Academic medical centers in Boston and the Research Triangle pilot AI-assisted spectral interpretation for automated emboli detection.
Germany
Integrated delivery networks bundle cranial Doppler modules with enterprise imaging contracts across Baden-Württemberg and Bavaria. EU Medical Device Regulation Article 83 imposes mandatory post-market surveillance that accelerates replacement cycles for legacy systems lacking connectivity infrastructure. The Rhine-Main cluster around Frankfurt anchors neurovascular research consortia testing machine learning integration with pulsed wave systems.
Japan
Prefectural stroke center certification concentrates equipment orders in Kanto and Kansai regions as METI guidelines tighten neurovascular care standards. PMDA maintains distinct technical documentation requirements that prolong market entry timelines for manufacturers lacking prior Japanese regulatory experience. Tokyo and Osaka academic hospitals drive adoption of portable Doppler configurations through emergency medicine departmental budgets.
India
PLI scheme medical device incentives and CDSCO streamlined Class B approvals open procurement channels in Maharashtra and Karnataka outside metro neurology centers. District hospital tier expansion decentralizes stroke risk stratification from centralized facilities. Hyderabad and Bengaluru clusters attract contract manufacturing for transducer assemblies serving domestic and export markets.
United Kingdom
NHS integrated care systems consolidate purchasing through enterprise imaging contracts with standardized hardware platforms. MHRA post-Brexit regulatory alignment with EU MDR clinical evidence standards extends development timelines for transcranial Doppler submissions. London and Manchester academic centers maintain fixed-installation systems for longitudinal cerebrovascular research protocols.
Cranial Doppler Market Competitive Environment
The competitive structure tilts toward diversified imaging conglomerates with installed base leverage. Hospital procurement consolidation favors vendors bundling neurovascular modules with broader workstation ecosystems. Three archetypes dominate: diversified medical technology conglomerates anchoring enterprise contracts, specialized neurodiagnostic firms occupying pediatric and research niches, and emerging point-of-care specialists attacking emergency medicine channels. M&A activity concentrates on regulatory capability acquisition and AI-enabled software assets. Geographic expansion into India's district hospital tier represents the primary growth vector.
Among diversified imaging conglomerates, GE Healthcare and Koninklijke Philips exemplify the enterprise bundling archetype through neurology workstation contracts. Natus Medical occupies a defensible position within specialized neurodiagnostic applications. These three companies represent contrasting strategic postures: scale-driven platform integration versus niche clinical protocol specialization.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips |
| Mindray Medical International |
| Compumedics Limited |
| Natus Medical Incorporated |
| Nihon Kohden Corporation |
| Viasonix |
| Atys Medical |
| Rimed Technologies |
| Others |
Value Chain & Pricing Dynamics
Piezoelectric crystal spot pricing volatility cascades through cranial Doppler manufacturing into three-tier pricing structure across premium, standard, and economy levels. Japanese and German suppliers of specialized 2 MHz transducer materials command leverage that concentrates margin capture upstream, forcing device manufacturers to absorb input swings or pass through via certification-grade tiering.
Pricing Analysis
Cost-down pressure on portable Doppler configurations accelerates because emergency medicine departmental budgets lack radiology capital allocation flexibility. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared systems from CE-marked equivalents and CDSCO Class B streamlined approvals. Price differentiation hinges on connectivity infrastructure for EU MDR Article 83 compliance and probe specialization for pediatric applications. District hospital buyers in India exhibit highest price sensitivity; academic stroke centers in Japan and Germany show lowest.
Supply Chain Analysis
Direct-to-hospital channels handle enterprise imaging contract demand while specialized distributors serve research institutions and diagnostic centers. Manufacturing concentrates in Japan and Germany for piezoelectric crystal fabrication and precision transducer assembly. Raw material dependencies include lead zirconate titanate crystals, specialized acoustic coupling gels, and medical-grade probe housings. Single-source vulnerability on 2 MHz transducer materials from limited Japanese and German suppliers creates structural risk. Distribution runs through GPO-negotiated enterprise contracts in the United States and direct prefectural procurement in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with regulatory capability depth and installed base leverage. EU MDR Article 83 post-market surveillance obligations force weaker players lacking connectivity infrastructure into exit or acquisition.
For Market Incumbents: Deploy software subscription tiers to defend recurring revenue against hardware commoditization pressure from portable Doppler entrants. Acquire AI-enabled spectral interpretation assets to reduce sonographer dependency and lock in hospital system purchasing. CE marking pathway investment under MDR tightens creates defensive moat against non-compliant competitors. For New Entrants and Emerging Players: CDSCO streamlined Class B approvals in India open a window for district hospital tier penetration outside metro neurology centers. Target portable Doppler configurations for emergency medicine departmental budgets in Japan and the United States where procurement authority fragments from radiology. Pursue AI-assisted emboli detection partnerships with academic medical centers to bypass specialist sonographer shortage constraints. For Investors and Strategic Acquirers: The window for entry favors neurodiagnostic specialists with pediatric probe configurations and MDR transition experience. Long-term viability rests on software-enabled platform economics rather than transactional hardware sales. Watch FDA cybersecurity guidance enforcement on interconnected devices as inflection indicator for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Article 83 Connectivity Upgrade | Legacy system replacement cycles accelerate as EU post-market surveillance mandates automated data capture infrastructure. |
| AI Spectral Interpretation Development | Machine learning integration reduces specialist sonographer dependency and enables point-of-care deployment outside radiology suites. |
| Pediatric Probe Specialization | Sickle cell disease screening mandates in pediatric hematology create defensible niche with dedicated hardware-software configurations. |
| India District Hospital Expansion | PLI scheme incentives and CDSCO streamlined approvals open procurement channels outside established metro neurology centers. |
| Subscription Software Tiering | Cloud-connected platforms separate hemodynamic analytics from hardware acquisition, creating recurring revenue pools in hospital purchasing. |
Study Parameters
FDA 510(k) clearance databases, EU MDR notified body technical documentation, and hospital procurement records formed the secondary backbone of this analysis. Primary interviews with stroke center neurologists, biomedical engineering directors, GPO contracts managers, and pediatric hematology department heads validated demand assumptions. Bottom-up and top-down triangulation reconciled device shipment data with procedure volume estimates across certified stroke centers.
Bottom-up modeling built from individual country-level procedure volumes, reimbursement code utilization, and equipment replacement cycles. Segmentation dimensions included product type, end-user setting, technology architecture, and application across the analysis window. CAGRs derived from logistic adoption curves for AI-enabled platforms and linear replacement assumptions for legacy systems. Forecast inputs incorporated prefectural stroke center certification timelines in Japan and PLI scheme incentive disbursement patterns in India.
The model assumes a particular technology adoption path; alternative pathways for non-contrast CT perfusion imaging would alter the outlook for transcranial Doppler triage applications. Forecasts reflect assumptions about regulatory clearance timelines, sonographer training pipeline recovery, and piezoelectric crystal supply stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
Global MRI Scanner Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
China Medical Imaging Market
Medical Imaging
Brazil Mammography Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
Gallium-68 Market
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market
Medical Imaging
Digital Breast Tomosynthesis (DBT) Equipment Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
South Africa Mammography Market