
 Cone Beam Computed Tomography (CBCT) System Market | 2026-2036
Cone Beam Computed Tomography (CBCT) System Market Size, Share, and Industry Trends Forecast 2026-2036
Cone Beam Computed Tomography (CBCT) System Market Outlook
The gap between flat-panel detector resolution and source brightness is narrowing as manufacturers integrate photon-counting architectures into next-generation CBCT platforms. Dentsply Sirona leverages its installed base of intraoral scanners to bundle digital workflow solutions with imaging hardware. Planmeca Group anchors its competitive stance through captive manufacturing of rotating anode tubes and sensor arrays in Helsinki. Vatech competes aggressively on price in Asian markets while sustaining margins via software subscription tiers.
Cone Beam Computed Tomography (CBCT) systems generate three-dimensional volumetric reconstructions from a divergent X-ray beam rotating around the patient, typically operating at 90–120 kVp tube voltage with voxel resolutions below 0.3 mm for craniofacial applications; these systems serve orthodontists, oral surgeons, and implantologists requiring sub-millimeter bone mapping without superimposition artifacts common to panoramic radiography. Fixed installations dominate hospital and radiology center procurement budgets where throughput justifies capital expenditure, while portable configurations penetrate dental clinics seeking chairside convenience without construction costs. The implantology application segment commands premium pricing due to surgical guide compatibility requirements, whereas orthodontics represents the fastest-growing application as clear aligner therapy expands CBCT utilization for root angulation assessment.
FDA 510(k) premarket notification requirements govern device safety and efficacy claims for US market entry, while EU MDR technical documentation demands clinical evidence for higher-risk classifications that CBCT manufacturers now face under recast rules. Japan's PMDA enforces JIS standards for electromagnetic compatibility and radiation output consistency, creating compliance complexity for multinational suppliers. Stakeholders must monitor evolving AI-enabled reconstruction algorithms that regulators in multiple jurisdictions are scrutinizing for diagnostic decision support claims.
Market Dynamics
Photon-counting detector architectures are compressing the resolution gap between CBCT and conventional CT, forcing incumbent flat-panel suppliers to accelerate R&D cycles or cede premium positioning to semiconductor imaging specialists.
Growth Catalysts
- EU MDR recast classification:Higher-risk device categories now demand clinical evidence dossiers, accelerating consolidation toward manufacturers with robust quality management systems and tilting procurement toward established brands.
- Clear aligner therapy expansion:Orthodontic practices are integrating CBCT into root angulation assessment protocols, creating installed base pull-through for imaging hardware bundled with treatment planning software.
- Japan PMDA JIS standardization:Electromagnetic compatibility and radiation output consistency requirements are harmonizing product specifications across Asian export markets, reducing variant complexity for multinational suppliers.
Market Restraints
- Flat-panel detector supply concentration:Amorphous silicon photodiode arrays depend on specialized foundry capacity concentrated in Taiwan and South Korea, exposing lead times to semiconductor cycle volatility.
- Rotating anode tube technical ceiling:Thermal loading limits at 120 kVp constrain scan protocol flexibility for bariatric craniofacial applications, restricting addressable patient populations.
- FDA 510(k) predicate device pathway:Substantial equivalence determinations for iterative reconstruction algorithms create regulatory friction for AI-enabled feature rollouts.
Strategic Opportunities
- India dental clinic underpenetration:Chairside imaging adoption remains below 15% in tier-2 and tier-3 cities, creating whitespace for portable configurations priced below fixed-installation alternatives.
- AI reconstruction algorithm regulatory tailwind:FDA breakthrough device designation pathways for computer-aided detection are accelerating clearance timelines for vendors with validated training datasets.
- Subscription software bundling:Cloud-based surgical guide planning tools are displacing perpetual license models, generating recurring revenue streams that offset hardware margin compression.
Industry Challenges
- Medical physics specialist scarcity:Qualified personnel for dose optimization protocol development and quality assurance are concentrated in academic medical centers, limiting deployment in community dental settings.
- Legacy PACS integration complexity:DICOM conformance variations between vendor implementations create workflow friction during hospital information system deployments.
- CE marking technical documentation burden:Clinical evaluation report requirements under EU MDR Annex XIV are extending certification timelines by 8-14 months for novel detector technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cone Beam Computed Tomography (CBCT) System Market |
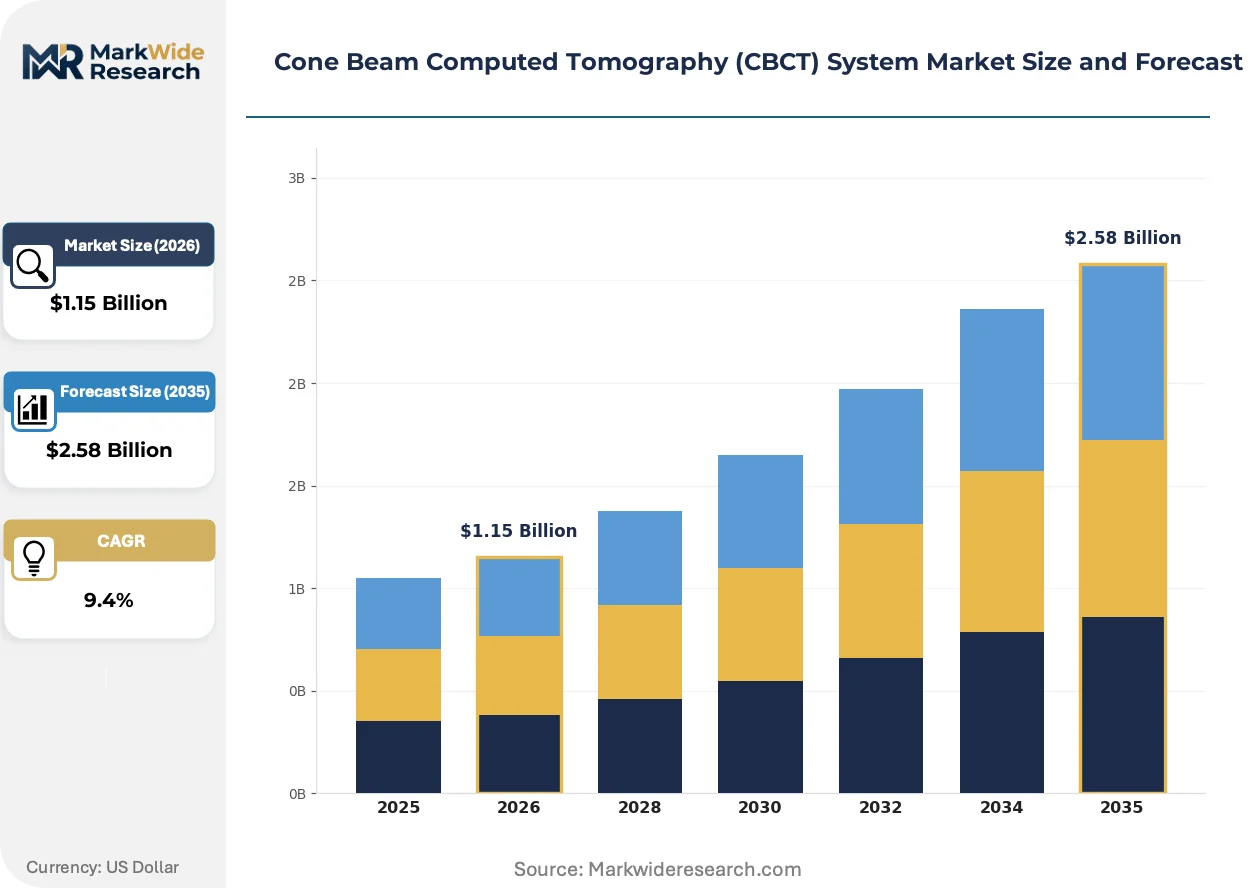
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.58 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Hybrid, Stand-alone End User: Dental Clinics, Radiology Centers, Hospitals, Imaging Centers Technology: 2D, 3D, 4D, Advanced Imaging Application: Orthodontics, Oral Surgery, Implantology, Endodontics |
| Companies Covered | Dentsply Sirona, Vatech, Carestream Health, Planmeca Group, J. Morita Mfg. Corp., Danaher Corporation, Philips, Envista Holdings, Cefla S.C., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cone Beam Computed Tomography (CBCT) System Market Strategic Shifts
Reconstruction algorithm advancement is compressing the trade-off between scan time and diagnostic image quality, enabling chairside workflows that previously required offsite processing. Three developments are restructuring competitive positioning.
Cadmium telluride photon-counting detectors are hybridizing spectral imaging capability into CBCT platforms previously limited to energy-integrating architectures. Oral surgery groups in Germany and Japan are piloting these systems for implant site characterization, collapsing the distinction between preoperative planning and intraoperative navigation hardware categories.
EU MDR Annex VIII reclassification of CBCT devices with AI-enabled diagnostic support has triggered clinical evidence generation requirements that favor manufacturers with prospective study infrastructure. Dental radiology equipment with computer-aided detection features now faces notified body scrutiny comparable to class IIb implantable devices, compressing vendor timelines for feature commercialization.
After-sales service unbundling is fragmenting procurement decisions across capital equipment, software licensing, and maintenance contracts. Large dental service organizations in the United States are negotiating direct detector replacement schedules with component suppliers, bypassing OEM service networks that historically captured 40-50% of lifetime customer value.
Cone Beam Computed Tomography (CBCT) System Market Segmentation
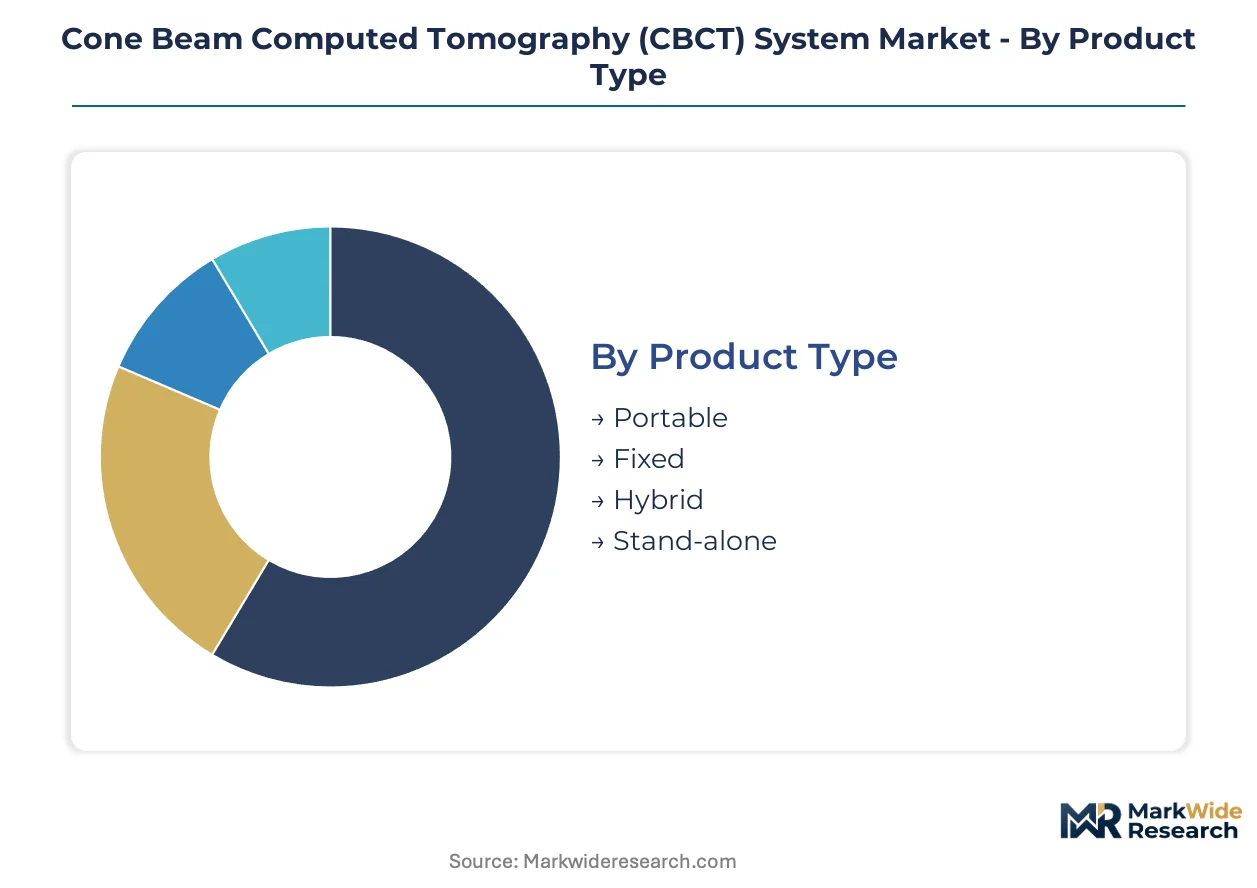
CBCT procurement patterns diverge sharply across clinical settings, with hardware specifications and software bundles calibrated to procedure volume and reimbursement structures. Understanding these segment boundaries clarifies why pricing spreads exceed 300% between entry-level portable units and premium fixed installations with photon-counting detectors.
Product Type:
Cost tier determines installation complexity, detector specification, and service contract structure across the four hardware categories.
- Portable:Battery-powered or plug-in units with flat-panel detectors below 20 cm field-of-view, designed for chairside deployment without lead-lined room construction. Demand concentrates in Germany and Japan where dental clinic real estate premiums justify mobility over throughput.
- Fixed:Ceiling-mounted or floor-standing systems with rotating gantries, thermal management for extended scan protocols, and voxel resolutions below 0.15 mm for craniofacial applications. Hospital radiology departments in the United States anchor procurement volumes for high-throughput implant planning workflows.
- Hybrid:Configurations combining panoramic 2D functionality with limited-field CBCT reconstruction, targeting orthodontic practices seeking dual-modal coverage without duplicate capital expenditure.
- Stand-alone:Dedicated CBCT hardware without integrated cephalometric or panoramic capabilities, positioned for imaging centers with existing 2D equipment bases.
Fixed installations command the established base. The steepest expansion runs through portable configurations.
End User:
Customer type shapes software bundling, service response commitments, and financing structures.
- Dental Clinics:Solo and group practices purchasing 1-2 units per location, prioritizing chairside workflow integration with intraoral scanners and surgical guide fabrication. Clear aligner therapy expansion in the United States is pulling CBCT into orthodontic generalist settings previously reliant on referral networks.
- Radiology Centers:Dedicated imaging facilities processing high volumes across referring dentist networks, demanding DICOM conformance with hospital PACS and sub-24-hour report turnaround.
- Hospitals:Academic medical centers and community hospitals requiring FDA 510(k) clearance for trauma, ENT, and maxillofacial surgery applications beyond dental scope.
- Imaging Centers:Multi-modality outpatient facilities integrating CBCT alongside MRI and CT, where equipment utilization rates justify premium detector specifications.
Dental clinics anchor volume. The steepest expansion trajectory runs through imaging centers.
Technology:
Dimensional capability determines reconstruction algorithm requirements and regulatory classification burden.
- 2D:Conventional panoramic and cephalometric radiography with limited tomographic slicing, retained in cost-sensitive markets for initial screening before CBCT referral.
- 3D:Volumetric reconstruction from circular or helical scan trajectories, representing the core CBCT architecture for implant planning and airway assessment.
- 4D:Time-resolved imaging capturing mandibular motion or respiratory-driven soft tissue displacement, piloted in Japan for temporomandibular joint disorder diagnosis.
- Advanced Imaging:Photon-counting spectral detection and metal artifact reduction algorithms, commanding 40-60% price premiums over energy-integrating alternatives.
3D technology commands the established base. The steepest expansion runs through advanced imaging.
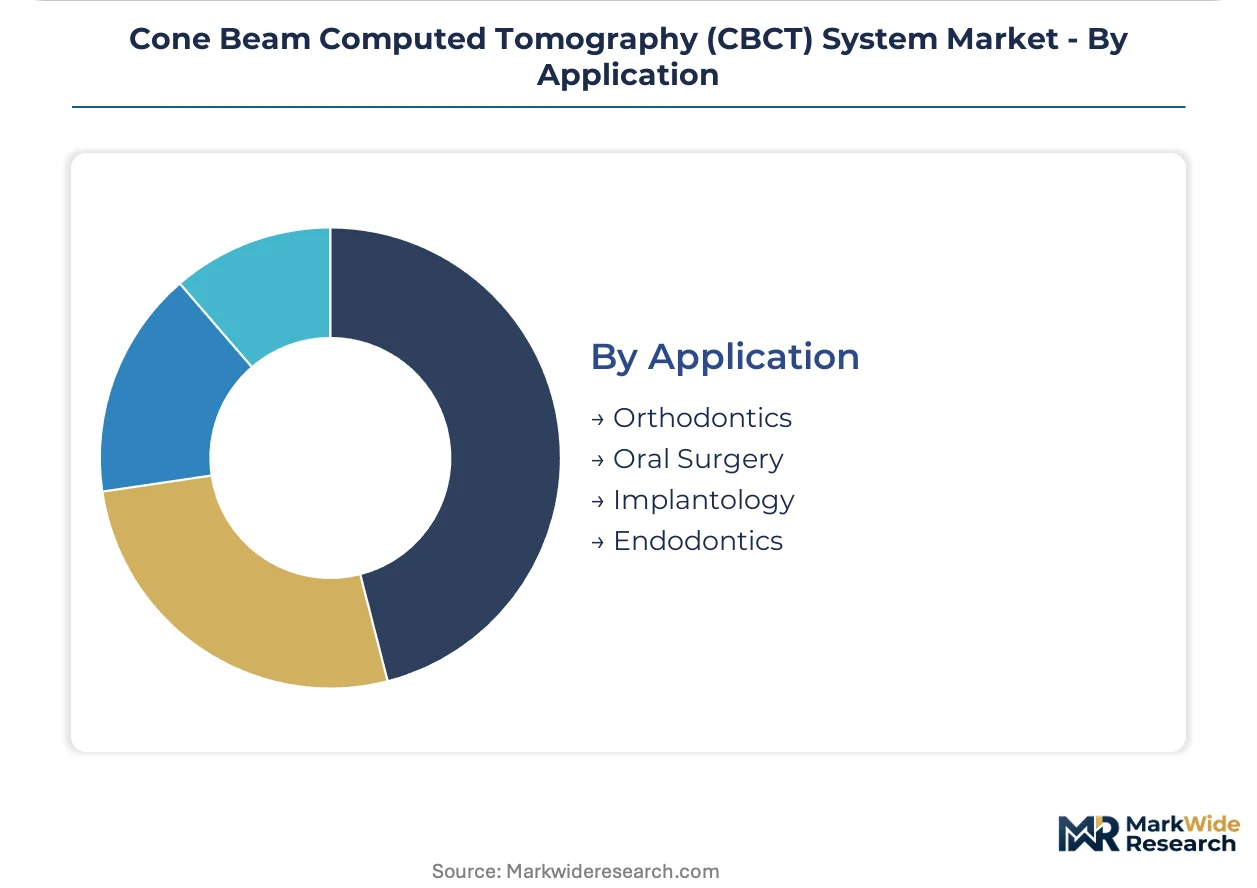
Application:
Clinical use case dictates field-of-view requirements, dose optimization protocols, and software module pricing.
- Orthodontics:Root angulation assessment, airway volume quantification, and temporomandibular joint evaluation for treatment planning. Clear aligner therapy volume in the United States and Germany is integrating CBCT into standard records protocols.
- Oral Surgery:Third molar impaction assessment, orthognathic surgical planning, and pathology localization requiring extended field-of-view configurations. German maxillofacial surgery departments are piloting photon-counting systems for intraoperative navigation integration.
- Implantology:Preoperative bone mapping, nerve canal tracing, and surgical guide fabrication with sub-0.3 mm accuracy requirements.
- Endodontics:Root canal morphology visualization and periapical lesion detection, typically served by limited-field high-resolution protocols.
Implantology commands the established base. The steepest expansion runs through orthodontics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export CBCT hardware to dental clinic networks across the United States and Japan, establishing a trade corridor that channels European engineering precision into high-reimbursement markets demanding sub-millimeter voxel resolution.
United States
Clear aligner therapy chains are pulling CBCT into orthodontic generalist practices previously reliant on external referrals. FDA 510(k) premarket notification pathways govern device safety claims for volumetric reconstruction algorithms. Dallas-Fort Worth dental service organizations negotiate direct detector replacement schedules with component suppliers.
Germany
Maxillofacial surgery departments pilot photon-counting systems for intraoperative navigation integration. EU MDR Annex VIII reclassification demands clinical evidence dossiers for AI-enabled diagnostic support features. Bavarian industrial clusters around Munich and Nuremberg host captive manufacturing of rotating anode tubes and sensor arrays.
Japan
Temporomandibular joint disorder diagnosis drives adoption of time-resolved 4D imaging protocols. PMDA enforces JIS standards for electromagnetic compatibility and radiation output consistency. Osaka-Kobe manufacturing corridors concentrate domestic production of flat-panel detector assemblies.
India
Chairside imaging penetration remains below 15% in tier-2 and tier-3 cities, creating whitespace for portable configurations. CDSCO medical device rules harmonize with ASEAN regulatory frameworks for regional export qualification. Maharashtra dental clinic clusters in Mumbai and Pune anchor early adoption of subscription-software bundling models.
South Korea
Amorphous silicon photodiode foundry capacity concentrates in Seoul-Incheon industrial zones, exposing lead times to semiconductor cycle volatility. MFDS enforces electromagnetic compatibility certification parallel to JIS standards. Busan-Ulsan manufacturing corridors supply detector arrays to multinational CBCT assemblers.
Cone Beam Computed Tomography (CBCT) System Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidation pressure from EU MDR compliance costs favors manufacturers with robust quality management systems and prospective study infrastructure. Strategic archetypes include diversified dental equipment conglomerates, captive-component manufacturers, and price-competitive Asian exporters. Dominant competitive moves center on software subscription bundling and detector technology licensing partnerships.
Among diversified dental equipment conglomerates, Dentsply Sirona and Danaher Corporation represent the channel-control archetype through installed bases of intraoral scanners and treatment planning software. Vatech exemplifies the price-competitive Asian exporter model, while Planmeca Group anchors the captive-manufacturing specialist tier through in-house production of rotating anode tubes in Helsinki.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Vatech |
| Carestream Health |
| Planmeca Group |
| J. Morita Mfg. Corp. |
| Danaher Corporation |
| Philips |
| Envista Holdings |
| Cefla S.C. |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Seoul maritime corridor channels amorphous silicon photodiode arrays and rotating anode tube assemblies from Asian foundries to European assembly plants, with freight cost volatility amplifying the spread between entry-level portable units and premium fixed installations. This logistics backbone concentrates pricing power with detector manufacturers in Taiwan and South Korea while forcing OEMs to absorb margin compression or pass through to dental clinic buyers.
Pricing Analysis
Next-generation photon-counting detector platforms command 40-60% premiums over energy-integrating flat-panel systems, while prior-generation hybrid configurations face price erosion from clear aligner therapy volume procurement. Three-tier pricing structure across premium, standard, and economy levels segments by detector specification and software bundle depth, with FDA 510(k) clearance tier and EU MDR certification grade as primary differentiation drivers. Pricing pressure stems from Asian exporters competing on hardware cost while subsidizing through software subscription tiers. Dental clinics in tier-2 Indian cities exhibit highest price sensitivity; German maxillofacial surgery departments show lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for semiconductor imaging components, with amorphous silicon photodiode foundry capacity concentrated in Taiwan, South Korea, and Japan. Raw material dependencies center on high-purity cadmium telluride crystals, tungsten-rhenium rotating anode targets, and specialized lead-free solder alloys. Single-source vulnerability in photon-counting detector semiconductor fabrication threatens lead time stability. Distribution runs through dental equipment distributors with regional service networks, though large United States dental service organizations increasingly negotiate direct component procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across orthodontics, implantology, and oral surgery application segments creates niche expansion opportunities as clear aligner therapy pulls CBCT into generalist practices previously reliant on referral networks.
For Market Incumbents: Harden quality management systems against EU MDR Annex XIV clinical evaluation report requirements that extend certification timelines 8-14 months for novel detector technologies. Consolidate component supply through captive manufacturing of rotating anode tubes or exclusive photodiode array partnerships to defend margins against Asian price competitors. Channel control through intraoral scanner installed bases remains the priority lever for software subscription attach rates. For New Entrants and Emerging Players: Build out portable configuration distribution in tier-2 and tier-3 Indian cities where chairside imaging penetration remains below 15%, exploiting whitespace between multinational premium positioning and unmet demand. Target orthodontic generalist practices in the United States adopting CBCT for root angulation assessment alongside clear aligner therapy. Cloud-based surgical guide planning tools with usage-based licensing offer the most penetrable go-to-market angle against perpetual license incumbents. For Investors and Strategic Acquirers: Captive-component manufacturers with in-house rotating anode tube production and photodiode array integration capabilities represent the most defensible acquisition archetype as supply concentration intensifies. Long-term viability hinges on regulatory compliance infrastructure rather than hardware differentiation alone. FDA breakthrough device designation pathways for AI-enabled reconstruction algorithms signal inflection timing for computer-aided detection feature commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Platform Launch | Cadmium telluride spectral imaging collapses the distinction between preoperative planning and intraoperative navigation hardware. |
| EU MDR Clinical Evidence Generation | Prospective study infrastructure tilts procurement toward established brands under Annex VIII reclassification. |
| Subscription Software Bundling | Cloud-based surgical guide planning displaces perpetual licenses, generating recurring revenue streams. |
| Direct Component Procurement Partnerships | Large United States dental service organizations bypass OEM service networks capturing 40-50% of lifetime value. |
| India Portable Configuration Distribution | Tier-2 and tier-3 city whitespace supports sub-premium pricing without fixed-installation construction costs. |
Study Parameters
Operator-level perspectives from biomedical engineers at academic medical centers, dental clinic practice managers, GPO contracts managers, and maxillofacial surgery department heads anchored the qualitative base for this analysis. Primary interviews combined with secondary validation against FDA 510(k) premarket notification databases, EU MDR technical documentation filings, PMDA JIS standard compliance records, and hospital procurement contract databases. Bottom-up unit economics from detector component costs and top-down market sizing from procedure volume estimates triangulated to cross-verify outputs.
Scenario-bracketing around semiconductor cycle volatility, regulatory clearance timeline variation, and clear aligner therapy adoption curves bounded the projection range across the analysis window. Segmentation dimensions modeled include product type, end user category, technology generation, and application with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from procedure volume elasticity to imaging hardware penetration, reimbursement framework stability indices, and software attach rate trajectories. Forecast inputs incorporated rotating anode tube thermal loading constraints and photon-counting detector yield rates.
Practitioners should monitor FDA predicate device pathway friction for AI-enabled reconstruction algorithms, EU notified body capacity constraints under MDR recast, and amorphous silicon foundry utilization rates for early signals requiring forecast reassessment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Fluoroscopy Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
North America MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Middle East and Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Open Magnetic Resonance Imaging System Market
Medical Imaging
Brazil Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Spain Magnetic Resonance Imaging Market
Medical Imaging
Stationary Anode CT X-Ray Tube Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
US Magnetic Resonance Imaging Market
Medical Imaging
Digital Breast Tomosynthesis (DBT) Equipment Market
Medical Imaging
Canada Diagnostic Imaging Equipment Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Vendor Neutral Archive Market