
 Portable Ultrasound Market | 2026-2036
Portable Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Ultrasound Market Analysis
Multi-source component sourcing is pivoting toward captive semiconductor and transducer manufacturing among leading device makers. GE Healthcare leverages in-house piezoelectric crystal fabrication to secure transducer supply chains. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. anchors its cost position through vertically integrated PCB assembly in domestic facilities. Fujifilm SonoSite Inc. competes by concentrating final assembly in North American plants for faster FDA turnaround.
Portable ultrasound denotes compact diagnostic imaging equipment operating at 2–15 MHz frequencies, generating real-time anatomical visualizations through piezoelectric transducer arrays for bedside clinical assessment. Handheld devices command the fastest expansion trajectory as semiconductor miniaturization shrinks form factors below 300 grams. Doppler ultrasound technology sustains premium positioning in cardiology workflows where hemodynamic measurement accuracy determines clinical utility. Tabletop systems occupy mature demand in hospital radiology departments where image resolution requirements exceed pocket-sized alternatives.
FDA 510(k) premarket notification governs device clearance timelines in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence thresholds for European market access. The FDA's breakthrough device designation pathway accelerates review for AI-augmented imaging algorithms, reshaping competitive timelines for software-integrated hardware. Stakeholders must monitor evolving reimbursement codes for remote diagnostic billing as telemedicine application volumes expand.
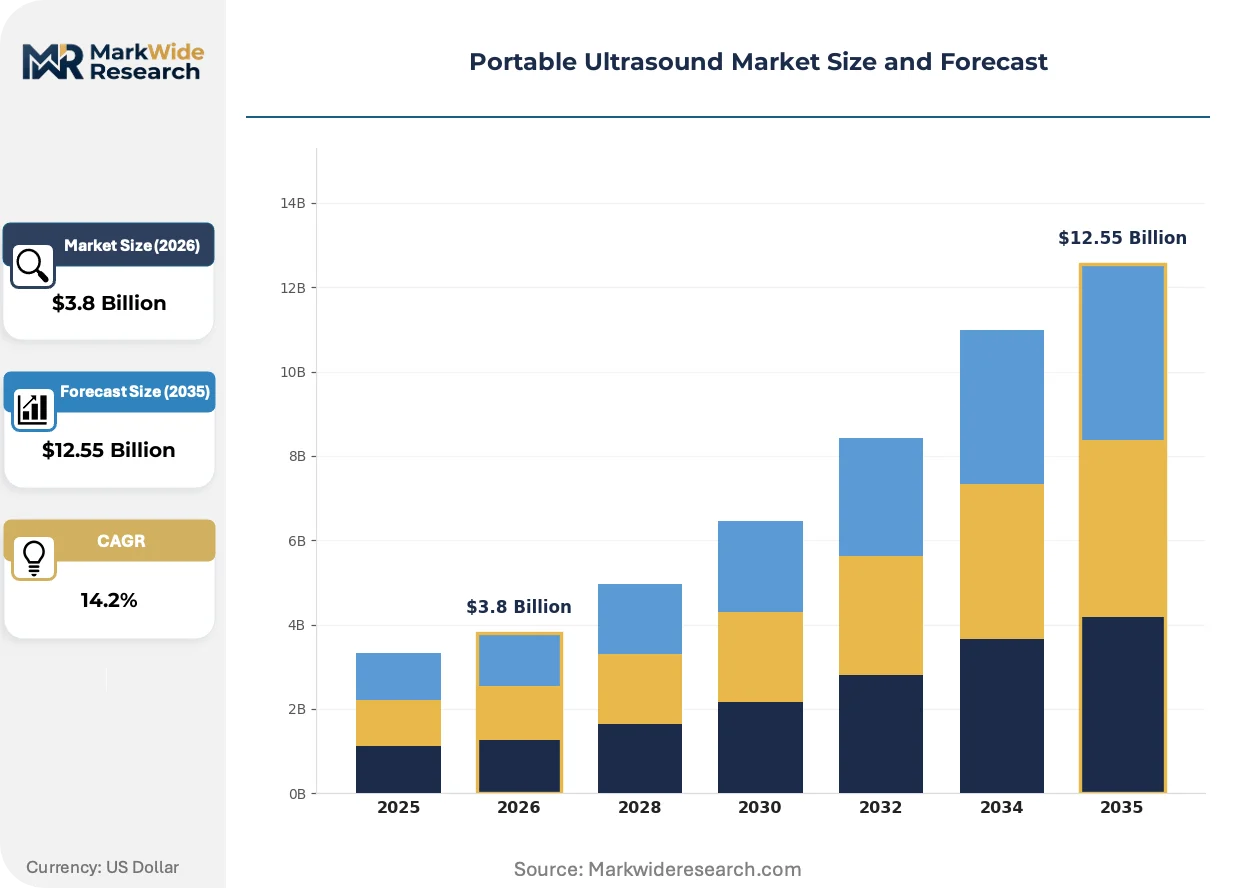
Market Dynamics
Semiconductor miniaturization is compressing form factors below 300 grams while FDA 510(k) clearance pathways accelerate handheld device commercialization, fundamentally restructuring competitive timelines between established radiology equipment and point-of-care alternatives.
Growth Catalysts
- Hospital-at-Home Expansion:CMS reimbursement codes for remote diagnostic billing incentivize bedside imaging procurement across United States health systems. Rural clinic networks deploy handheld units where fixed radiology infrastructure remains uneconomical.
- AI-Augmented Imaging:FDA breakthrough device designation compresses review timelines for machine-learning diagnostic algorithms. Software-integrated hardware commands premium positioning in emergency medicine workflows.
- Emergency Medicine Adoption:Point-of-care protocols integrate pocket-sized Doppler systems for trauma assessment. Hemodynamic measurement accuracy at triage drives replacement of stethoscope-first examination.
Market Restraints
- Piezoelectric Crystal Supply Concentration:Single-source dependency on synthetic crystal growth facilities in East Asia creates transducer manufacturing vulnerability. GE Healthcare's captive fabrication remains an exception among device makers.
- EU MDR Clinical Evidence Thresholds:Stricter documentation requirements for European market access extend clearance timelines versus FDA 510(k) pathways. Small manufacturers face disproportionate compliance burden.
- Image Resolution Limitations:Pocket-sized alternatives fail to satisfy deep-tissue visualization requirements in abdominal radiology. Tabletop systems retain installed base in hospital departments.
Strategic Opportunities
- Telemedicine Application Expansion:Remote diagnostic billing codes create reimbursement infrastructure for home-based ultrasound services. United States Medicare Advantage plans pilot prenatal monitoring programs.
- Cardiology Workflow Integration:Wearable Doppler patches converge with handheld consoles for continuous hemodynamic monitoring. Dual-modality systems address ambulatory heart failure management.
- Vertically Integrated Manufacturing:Captive PCB assembly and transducer fabrication insulate margin structures from component volatility. Shenzhen-based facilities anchor cost positions for emerging market penetration.
Industry Challenges
- Specialized Sonographer Training Gaps:Point-of-care adoption requires cross-training emergency physicians in image acquisition protocols. Competency certification programs lag device deployment velocity.
- Legacy PACS Integration Complexity:Handheld devices must interface with hospital radiology information systems through DICOM middleware. Custom API development extends implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Ultrasound Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Tabletop Systems, Laptop Systems, Wearable Devices Application: Emergency Care, Telemedicine, Obstetrics, Cardiology End User: Hospitals, Clinics, Home Care, Military Technology: 2D Imaging, 3D Imaging, Doppler Ultrasound, Elastography |
| Companies Covered | Canon Medical Systems Corporation, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., GE Healthcare, Clarius Mobile Health Corp., Butterfly Network Inc., Koninklijke Philips N.V., Fujifilm SonoSite Inc., Esaote S.p.A., Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Ultrasound Market Emerging Trajectories
Artificial intelligence is embedding inference engines directly at the edge, compressing the gap between image capture and diagnostic interpretation while regulatory frameworks race to accommodate software-as-medical-device classifications.
Deep-learning segmentation algorithms are automating anatomical boundary detection in real-time cardiac imaging. Emergency departments at United States academic medical centers deploy these tools for unsupervised resident training. The technology is automating preliminary report generation that previously required attending radiologist review.
EU Medical Device Regulation imposes post-market surveillance requirements that exceed FDA 510(k) obligations for software updates. Manufacturers must submit clinical evidence packages for algorithm modifications that alter diagnostic thresholds. European notified bodies prioritize AI-augmented submissions, creating review queue congestion for hardware-only devices.
Subscription-based hardware access is displacing capital purchase models among United States ambulatory surgery centers. Monthly per-device fees bundle probe replacement, cloud storage, and software licensing. Anesthesia groups in Texas and Florida lead adoption where case volume fluctuation makes depreciation schedules unfavorable.
Portable Ultrasound Market Segmentation
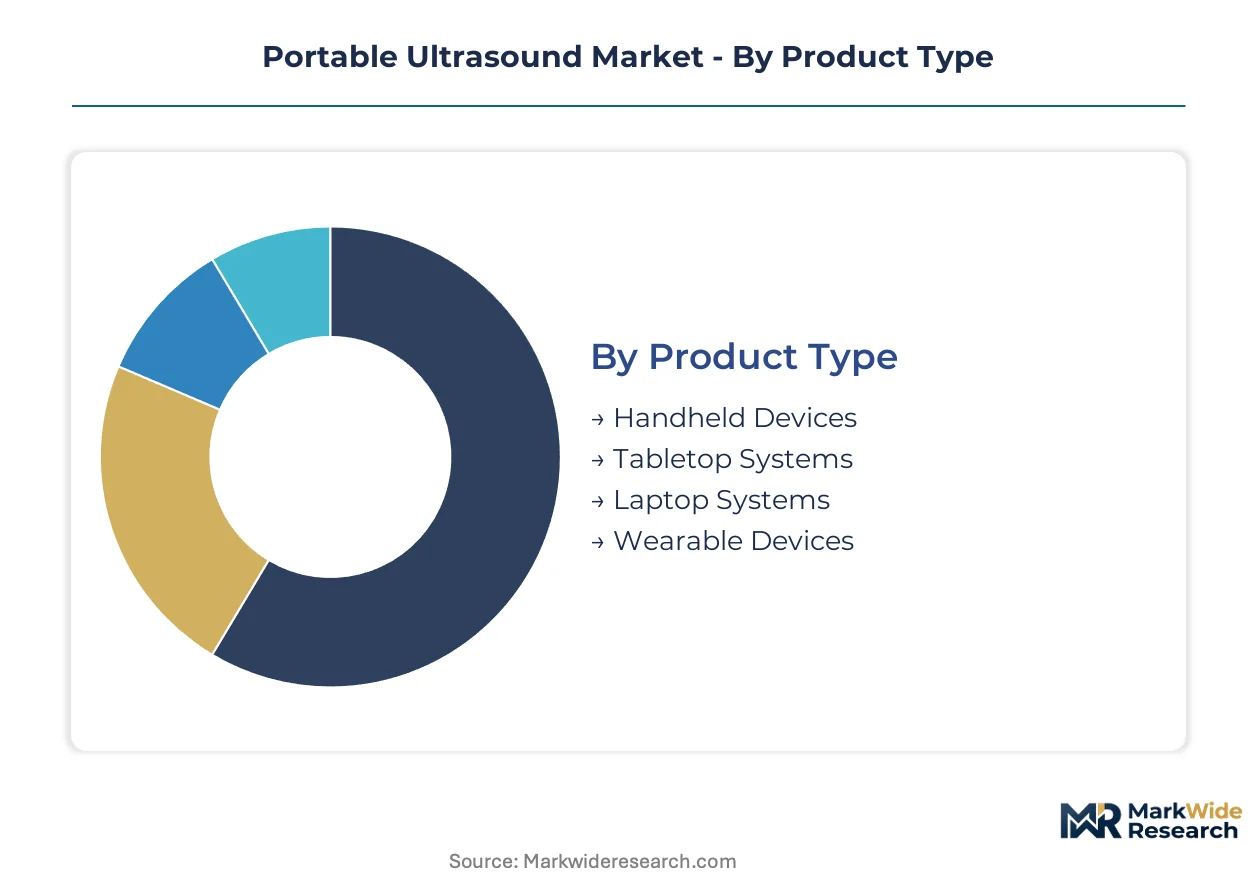
Portable ultrasound segmentation reveals distinct procurement patterns across clinical settings. Product form factor determines reimbursement pathways, while application specificity dictates regulatory complexity and software integration requirements.
Product Type:
Cost tier separates budget-constrained purchasers from capital-rich health systems seeking premium imaging capabilities.
- Handheld Devices:Semiconductor miniaturization has compressed these units below 300 grams, enabling single-operator use in ambulances and field clinics. United States hospital-at-home programs and rural networks in Texas and Florida deploy these where fixed radiology infrastructure remains uneconomical.
- Tabletop Systems:These occupy mature demand in hospital radiology departments where image resolution requirements exceed pocket-sized alternatives. Deep-tissue visualization capabilities in abdominal imaging sustain installed base retention despite higher capital outlay.
- Laptop Systems:Mid-tier mobility balances transportability with display quality for mobile clinic fleets.
- Wearable Devices:Emerging patch-based Doppler systems target continuous hemodynamic monitoring in ambulatory cardiology workflows.
Tabletop systems lead volumes today; handheld devices are gaining share fastest.
Application:
Volume concentration varies sharply by reimbursement code availability and clinical workflow integration maturity.
- Emergency Care:Point-of-care protocols integrate pocket-sized Doppler systems for trauma assessment at triage. United States academic medical centers deploy AI-augmented tools for unsupervised resident training, replacing stethoscope-first examination protocols.
- Telemedicine:Remote diagnostic billing codes create reimbursement infrastructure for home-based ultrasound services. Medicare Advantage plans pilot prenatal monitoring programs where probe data transmits to centralized interpretation centers.
- Obstetrics:Fetal biometric measurement demands consistent image quality across operator skill levels.
- Cardiology:Hemodynamic measurement accuracy determines clinical utility in heart failure management protocols.
Emergency care commands current procedure volume; telemedicine applications show steepest expansion trajectory.
End User:
Customer type dictates procurement model preference between capital purchase and subscription-based hardware access.
- Hospitals:Large health systems negotiate enterprise contracts bundling device fleets with PACS integration services. Legacy radiology information system compatibility requirements extend implementation timelines through custom API development.
- Clinics:Ambulatory surgery centers in Texas and Florida lead subscription model adoption where case volume fluctuation makes depreciation schedules unfavorable.
- Home Care:Reimbursement code evolution determines addressable market size for remote diagnostic services.
- Military:Ruggedized specifications and field durability requirements drive specialized procurement channels.
Hospitals dominate installed base; clinics are expanding procurement most rapidly.
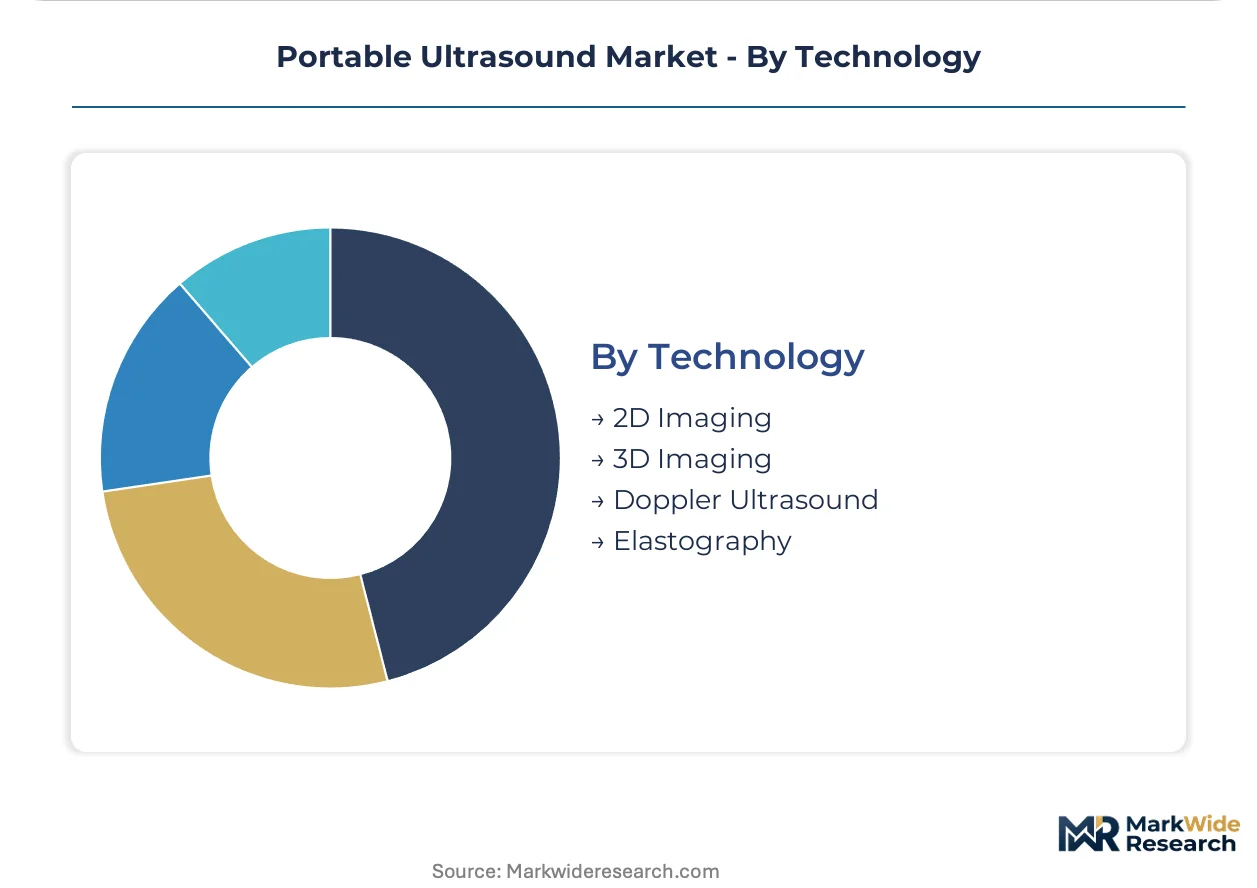
Technology:
Margin structure separates commodity imaging from premium diagnostic modalities requiring specialized transducer arrays.
- 2D Imaging:Baseline grayscale anatomical visualization serves generalist screening applications across all end-user categories. Cost compression in piezoelectric crystal sourcing sustains mass-market accessibility.
- Doppler Ultrasound:Blood flow velocity measurement sustains premium positioning in cardiology workflows where hemodynamic accuracy determines clinical utility. FDA breakthrough device designation accelerates review for AI-integrated implementations.
- 3D Imaging:Volumetric reconstruction adds computational overhead requiring enhanced processing hardware.
- Elastography:Tissue stiffness measurement targets oncology and hepatology subspecialty applications.
2D imaging anchors current revenue; Doppler ultrasound commands highest per-procedure value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors portable ultrasound manufacturing through vertically integrated PCB assembly and transducer fabrication clusters serving domestic and export markets. Hospital-at-home programs in the United States and rural clinic networks in Texas and Florida drive point-of-care adoption. Regulatory divergence between FDA 510(k) pathways and EU MDR requirements reshapes geographic market entry sequencing.
United States
Hospital-at-home expansion and Medicare Advantage prenatal monitoring pilots concentrate demand in Texas and Florida ambulatory networks. FDA breakthrough device designation accelerates AI-integrated hardware review timelines for emergency medicine applications. Academic medical centers in Boston and California deploy handheld Doppler systems for trauma triage protocols.
Germany
EU MDR clinical evidence thresholds extend clearance timelines for small manufacturers seeking European market access. The country's notified bodies prioritize AI-augmented submissions, creating review queue congestion for hardware-only devices. Industrial clusters in Bavaria and Baden-Württemberg host precision transducer component suppliers serving tabletop system integrators.
China
Shenzhen-based facilities anchor global cost positions through captive PCB assembly and piezoelectric crystal sourcing. NMPA regulatory pathways streamline domestic approvals for semiconductor-miniaturized handheld devices. Yangtze River Delta manufacturing hubs supply transducer arrays to both domestic brands and contract manufacturers.
Japan
PMDA review frameworks emphasize post-market surveillance for software-integrated diagnostic hardware. METI industrial policy supports miniaturization R&D in Kanto and Kansai corridor electronics clusters. Aging demographics drive home-based ultrasound service pilots in Tokyo and Osaka metropolitan networks.
United Kingdom
NHS hospital-at-home reimbursement codes incentivize bedside imaging procurement across England and Scotland. MHRA regulatory alignment with FDA timelines attracts North American manufacturers seeking European launch platforms. London and Southeast England radiology networks pilot AI-augmented emergency department workflows.
Portable Ultrasound Market Vendor Landscape
Global majors compete with regional champions across semiconductor integration and transducer fabrication capabilities. Market structure consolidates around three tiers: diversified imaging conglomerates with captive crystal growth, mid-scale specialists with vertical PCB control, and software-native entrants leveraging AI-augmented regulatory pathways. Dominant competitive moves include M&A for transducer technology access and strategic partnerships for cloud-based image interpretation infrastructure.
Among diversified imaging conglomerates, GE Healthcare and Siemens Healthineers occupy positions defined by in-house piezoelectric fabrication and radiology system integration heritage. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. exemplifies the vertically integrated cost-leader archetype through domestic PCB and transducer control. Butterfly Network Inc. and Clarius Mobile Health Corp. represent software-native entrants capitalizing on FDA breakthrough pathways for AI-integrated handheld platforms.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| GE Healthcare |
| Clarius Mobile Health Corp. |
| Butterfly Network Inc. |
| Koninklijke Philips N.V. |
| Fujifilm SonoSite Inc. |
| Esaote S.p.A. |
| Siemens Healthineers |
| Others |
Supply Flow & Price Mechanics
United States hospital-at-home programs and ambulatory surgery centers concentrate procurement volume, anchoring subscription-based hardware access as the dominant pricing model across the portable ultrasound sector. This buyer concentration creates pricing power asymmetries that favor bundled service contracts over transactional equipment sales.
Pricing Analysis
Input-cost pass-through from piezoelectric crystal sourcing and semiconductor miniaturization compresses margins at the economy tier while premium Doppler systems maintain pricing power through FDA breakthrough device designation. Three-tier pricing structure across premium AI-integrated, standard handheld, and economy refurbished units separates clinical utility grades. Pricing pressure stems from Shenzhen-based manufacturers leveraging captive PCB assembly for cost-position aggression. Emergency medicine departments show lowest price sensitivity due to workflow integration requirements; rural clinic networks exhibit highest sensitivity where capital constraints dominate procurement.
Supply Chain Analysis
Domestic-content mandates in China's NMPA regulatory framework and United States Buy American provisions for hospital procurement reshape sourcing toward regional assembly footprints. Manufacturing gravity centers on China for PCB fabrication and transducer arrays, the United States for final assembly serving FDA turnaround requirements, and Japan for precision semiconductor components. Synthetic crystal growth facilities in East Asia and advanced packaging in South Korea constitute critical input dependencies. Single-source vulnerability in piezoelectric crystal supply creates structural exposure. Distribution runs through GPO contracts for hospital systems and direct-to-clinic subscription platforms for ambulatory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable ultrasound sector represents a late-cycle quality story where emergency medicine workflows and cardiology hemodynamic monitoring drive specification premiums toward AI-integrated Doppler systems. Demand is shifting from grayscale screening toward continuous monitoring capabilities that command service-based revenue models.
For Market Incumbents: Lock in transducer fabrication capabilities through backward integration into piezoelectric crystal growth or long-term offtake agreements with East Asian suppliers. Defend installed base in hospital radiology departments by accelerating PACS integration middleware development to neutralize software-native entrant disruption. FDA breakthrough device designation for AI algorithms remains the critical certification lever for premium positioning.
For New Entrants and Emerging Players: Begin with telemedicine application expansion where reimbursement code evolution creates white-space opportunity ahead of incumbent coverage. Target United States Medicare Advantage prenatal monitoring pilots and rural clinic networks in Texas and Florida where subscription economics outperform capital purchase models. Lead with cloud-based image interpretation partnerships to bypass legacy PACS integration complexity.
For Investors and Strategic Acquirers: Diversified imaging conglomerates with radiology system integration heritage are the most active acquirers in this space, seeking handheld platform capabilities to complement tabletop installed bases. The long-term viability window favors targets with captive semiconductor sourcing or AI-augmented regulatory clearances. Watch FDA breakthrough device designation queue velocity as the inflection signal for competitive timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates review timelines for AI-integrated handheld platforms in emergency medicine workflows. |
| Captive Piezoelectric Crystal Fabrication | Secures transducer supply chains against East Asian single-source concentration risk. |
| Hospital System Partnership | Locks in enterprise fleet contracts bundling devices with PACS integration services. |
| Software Companion Development | Enables real-time deep-learning segmentation for unsupervised clinical training applications. |
| Reimbursement Strategy | Aligns device procurement with CMS remote diagnostic billing code expansion for hospital-at-home. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with emergency medicine physicians, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, CMS reimbursement databases, NMPA approval records, and SEC 10-K disclosures from listed device manufacturers. Bottom-up unit shipment estimates triangulated against top-down revenue aggregation across product tiers.
Segment-weighting approaches modeled handheld, tabletop, laptop, and wearable form factors alongside 2D imaging, Doppler ultrasound, 3D reconstruction, and elastography technology tiers. Application dimensions included emergency care, cardiology, obstetrics, and telemedicine end-uses. CAGRs derived from procedure volume growth assumptions tied to hospital-at-home expansion and semiconductor miniaturization trajectories. Forecast inputs incorporated FDA breakthrough device designation velocity and EU MDR clearance timeline differentials.
Several conditions sit outside the modeled scope, including geopolitical disruption to East Asian crystal growth facilities, algorithmic diagnostic liability frameworks, and wholesale reimbursement code elimination for remote services. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and component cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
Cone Beam CT Scanner Market
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Europe Open System MRI Market
Medical Imaging
Smart X-Ray Detectors Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
PACS and RIS Market
Medical Imaging
Contrast Media Market
Medical Imaging
Canada Mammography Market
Medical Imaging
Australia Magnetic Resonance Imaging Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
Global Positron Emission Tomography [PET] Scanners Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
Dental X-Ray Market