
 Global Stroke Post Processing Software Market | 2026-2036
Global Stroke Post Processing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stroke Post Processing Software Market Foresight
A capital-intensity divergence between cloud-native AI developers and legacy imaging hardware vendors is bifurcating competitive dynamics. Siemens Healthineers leverages its installed base of CT and MRI systems to bundle post-processing modules. RapidAI sustains pure-play innovation through stroke-specific algorithm portfolios without hardware dependencies.
Stroke post processing software applies computational algorithms to neurovascular imaging data, extracting perfusion parameters, collateral flow scores, and clot burden metrics from DICOM datasets to guide thrombectomy decisions. Automated software commands the largest revenue pool by reducing radiologist interpretation time for ischemic stroke cases. Cloud-based deployment is expanding fastest among telemedicine services requiring real-time specialist access across distributed hospital networks.
FDA 510(k) pathways and EU MDR Class IIa software requirements govern clinical validation standards, while HIPAA and GDPR frameworks dictate cross-border patient data handling. These regulatory layers elevate compliance costs for entrants but protect incumbent positions. Stakeholders must monitor evolving FDA guidance on AI-enabled diagnostic tools as classification criteria tighten.
Market Dynamics
Automated perfusion analysis algorithms are compressing radiologist interpretation windows from hours to minutes, forcing stroke networks to reconfigure triage protocols around software-enabled decision speed rather than specialist availability alone.
Growth Catalysts
- FDA 510(k) clearance pathways:Streamlined premarket notification routes for AI-enabled diagnostic software accelerate commercialization timelines for stroke imaging algorithms. Developers leverage predicate device strategies to reduce validation burdens.
- Telemedicine service expansion:Rural hospital systems deploy cloud-based post-processing tools to access specialist-level clot characterization without on-site neuroradiologists. Real-time DICOM streaming collapses geographic expertise gaps.
- Thrombectomy-capable center proliferation:Mechanical clot retrieval programs at comprehensive stroke centers generate institutional demand for automated collateral scoring and perfusion mismatch quantification to guide patient selection.
Market Restraints
- EU MDR Class IIa software compliance:Clinical evidence requirements for neuroimaging algorithms under the Medical Device Regulation extend development cycles and elevate documentation costs for European market entry.
- Cloud infrastructure concentration:HIPAA-compliant hosting dependencies on a limited set of certified data center providers create single-point vulnerabilities for distributed stroke networks managing cross-border patient data flows.
- Legacy PACS integration friction:Proprietary DICOM communication protocols at established imaging archives impede seamless algorithm deployment without costly middleware development or system replacement.
Strategic Opportunities
- Japan's aging demographic pressure:METI-funded digital health initiatives and PMDA's accelerated review pathways for AI diagnostics create favorable conditions for stroke software vendors targeting Asia-Pacific's fastest-aging population.
- Prehospital ambulance deployment:Mobile CT units equipped with edge-computing post-processing modules enable clot detection during patient transport, opening emergency medical services as a new procurement channel.
- EU AI Act risk classification:High-risk AI system designations for medical diagnostic software will mandate conformity assessments that favor established developers with quality management systems already aligned to MDR requirements.
Industry Challenges
- Neuroradiologist algorithm skepticism:Specialist resistance to automated interpretation tools in academic medical centers slows institutional adoption despite demonstrated time savings in peer-reviewed validation studies.
- Multi-site clinical trial coordination:FDA-mandated reader studies across diverse scanner platforms and patient populations require substantial recruitment resources and extended timelines for 510(k) submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stroke Post Processing Software Market |
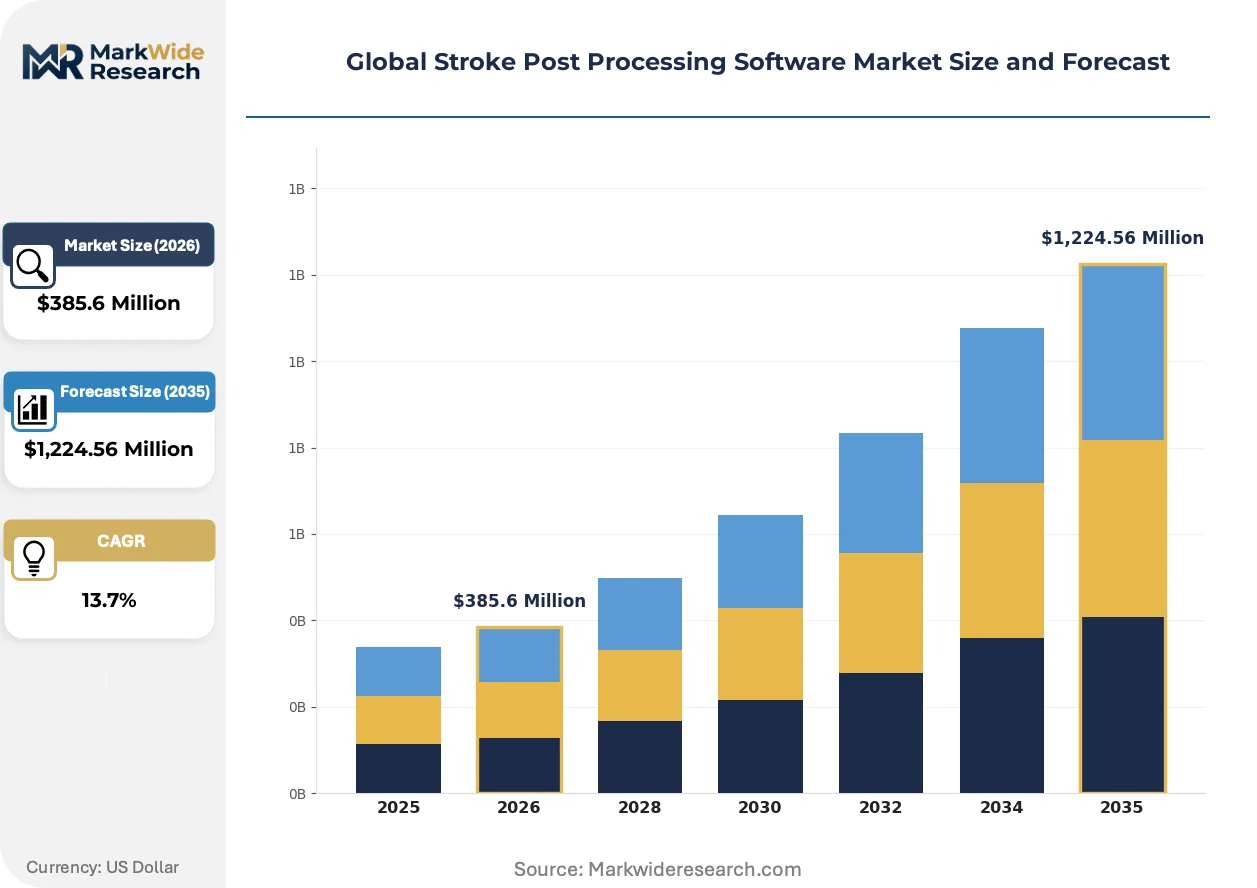
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,224.56 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Software, Semi-Automated Software, Manual Software, Hybrid Solutions Application: Ischemic Stroke Analysis, Hemorrhagic Stroke Assessment, Aneurysm Evaluation, Vascular Mapping End User: Neurology Clinics, Radiology Centers, Telemedicine Services, Diagnostic Labs Deployment: Cloud-Based, On-Premise, Hybrid Deployment, Edge Computing |
| Companies Covered | Siemens Healthineers, Philips Healthcare, RapidAI, Aidoc, Canon Medical Systems, Viz.AI, GE HealthCare, Qure.AI, Brainomix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stroke Post Processing Software Market Shifts & Advancements
Computational methods for extracting quantitative biomarkers from non-contrast CT and CTA sources are displacing conventional imaging sequences, compressing both scan duration and contrast agent exposure for acute stroke evaluation.
Large vessel occlusion detection algorithms are fragmenting the traditional radiologist workflow by inserting automated alerts directly into emergency department communication systems. Stroke coordinators at comprehensive centers receive clot location notifications before formal imaging interpretation begins. This interruption of sequential diagnostic pathways is compressing door-to-puncture intervals and redefining liability frameworks for missed findings.
EU MDR software classification rules are elevating clinical validation standards for algorithm-based perfusion mapping tools. Manufacturers must now demonstrate diagnostic accuracy across scanner platforms and patient demographics through prospective data collection. German notified bodies have tightened review timelines, forcing developers to front-load evidence generation before submission rather than responding to iterative requests.
Hospital procurement committees are consolidating vendor relationships through enterprise imaging contracts that bundle post-processing modules with PACS and RIS infrastructure. Academic medical centers in the United States increasingly require interoperability certifications before adding standalone stroke algorithms to approved technology lists. This preference for integrated suites disadvantages pure-play AI developers lacking hardware partnerships or established radiology information system connections.
Global Stroke Post Processing Software Market Segmentation
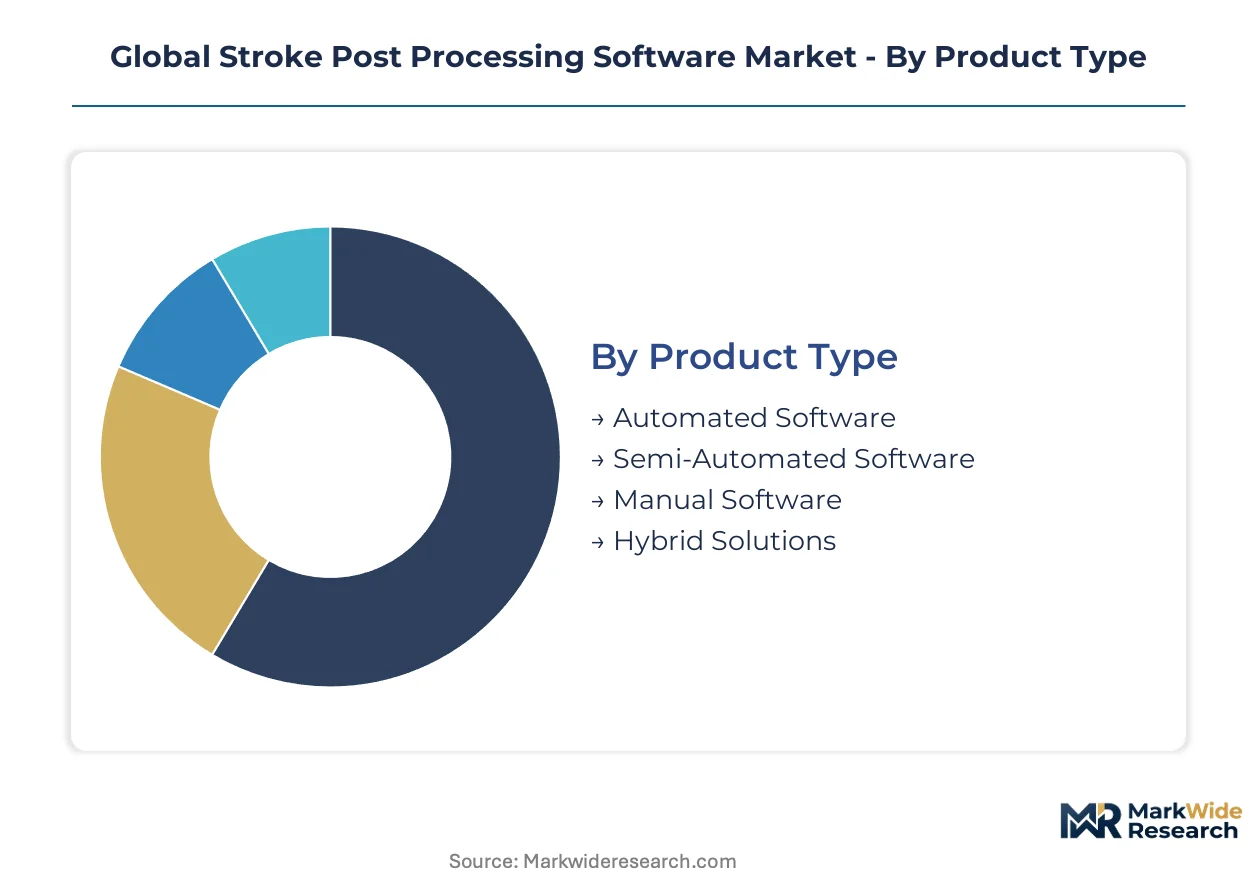
Stroke post processing software segments reflect divergent clinical workflows and infrastructure maturity across healthcare systems. Product architecture choices determine integration complexity, while deployment models shape regulatory exposure and data sovereignty requirements for hospital procurement committees.
Product Type:
Margin pools concentrate in solutions that compress interpretation time while minimizing hardware retrofit costs for stroke networks.
- Automated Software:Fully algorithmic perfusion mapping and clot detection pipelines process DICOM streams without radiologist intervention for initial triage. Comprehensive stroke centers in the United States and Germany deploy these tools to collapse door-to-puncture intervals below institutional targets.
- Hybrid Solutions:Configurable workflows blend automated preprocessing with manual override capabilities for complex cases. Academic medical centers in Japan favor this architecture to preserve neuroradiologist authority while capturing time savings from algorithmic first-pass analysis.
- Semi-Automated Software:Radiologist-supervised algorithms requiring confirmation clicks before report generation.
- Manual Software:Conventional measurement tools with digital calipers and region-of-interest selectors.
Automated Software holds installed capacity. Hybrid Solutions is rotating up the share rankings.
Application:
Clinical validation requirements vary sharply across stroke subtypes, with ischemic pathways commanding the deepest algorithm development investment.
- Ischemic Stroke Analysis:Perfusion-diffusion mismatch quantification and large vessel occlusion detection dominate algorithm training datasets. FDA 510(k) clearances cluster here as thrombectomy eligibility drives reimbursement-linked procurement decisions at US comprehensive stroke centers.
- Hemorrhagic Stroke Assessment:Intracerebral hemorrhage volume segmentation and expansion risk scoring address distinct workflow pressures. German neurology clinics prioritize these tools for rapid anticoagulation reversal decisions where minutes alter functional outcomes.
- Aneurysm Evaluation:Morphological characterization for endovascular planning.
- Vascular Mapping:Collateral circulation assessment for chronic cerebrovascular disease.
Ischemic Stroke Analysis anchors current revenue. Hemorrhagic Stroke Assessment is climbing the fastest.
End User:
Procurement authority fragmentation between radiology and neurology departments creates multiple entry points with divergent technical requirements.
- Telemedicine Services:Cloud-native platforms serving rural hospital networks require real-time DICOM streaming with sub-minute latency. Japan's METI-funded regional stroke hubs and US hub-and-spoke networks drive concentrated demand for browser-based interpretation tools.
- Neurology Clinics:Stroke unit-integrated workflows prioritize EHR connectivity and alert routing to mobile devices. Academic centers in the United States embed post-processing outputs directly into multidisciplinary team dashboards for treatment selection.
- Radiology Centers:High-volume imaging facilities with established PACS infrastructure.
- Diagnostic Labs:Independent facilities processing outsourced neurovascular studies.
Telemedicine Services captures expansion velocity. Neurology Clinics retains the deepest incumbent relationships.
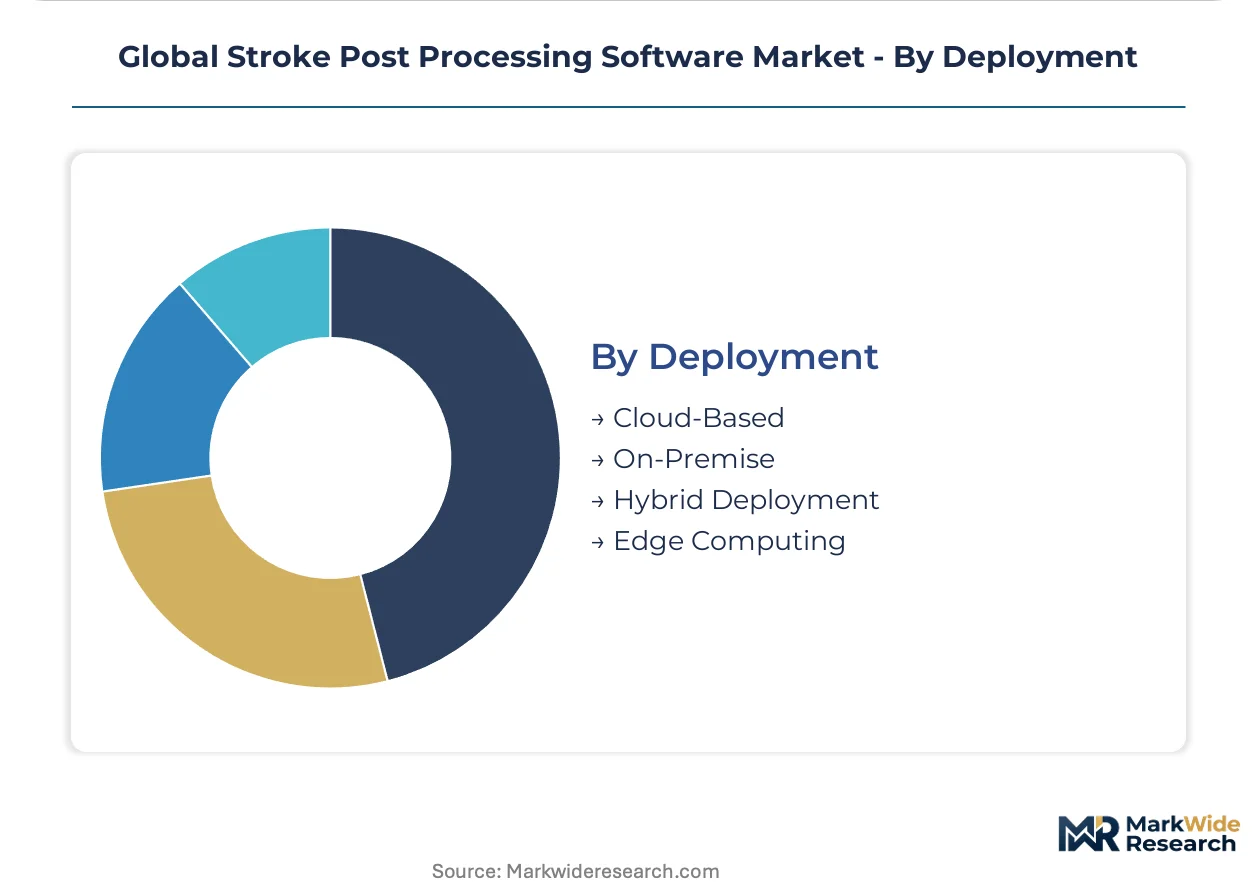
Deployment:
Infrastructure liability frameworks and data residency rules partition the market between centralized and distributed architectures.
- Cloud-Based:HIPAA and GDPR-compliant hosting enables cross-border specialist access without on-premise hardware. German notified bodies have clarified MDR Class IIa software requirements for cloud-native stroke algorithms, accelerating European hospital adoption.
- Edge Computing:Prehospital CT units and ambulance-mounted systems process imaging locally without network dependency. Japanese emergency medical services trials with mobile stroke units demonstrate viability for transport-time diagnosis.
- On-Premise:Hospital-controlled servers with air-gapped security for high-risk environments.
- Hybrid Deployment:Local preprocessing with cloud-based storage and analytics.
Cloud-Based deployment holds scale advantages. Edge Computing is gaining share fastest in emergency services procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software licensing flows concentrate outbound from the United States and Germany toward digitizing stroke networks in Japan and emerging Asian markets. Import dependencies for cloud infrastructure and AI validation services create bilateral technology transfer patterns shaped by divergent regulatory timelines.
United States
Comprehensive stroke centers in Texas and Florida drive automated perfusion tool procurement to meet thrombectomy volume targets. FDA 510(k) clearance pathways compress commercialization cycles for algorithm developers targeting hub-and-spoke networks. Boston's digital health cluster anchors multi-site clinical validation trials for large vessel occlusion detection systems.
Germany
Notified bodies in Munich and Berlin enforce EU MDR Class IIa software requirements that extend evidence generation timelines for neuroimaging algorithms. Bavarian stroke networks integrate post-processing modules into enterprise imaging contracts bundling PACS infrastructure. Heidelberg's university hospital system validates collateral scoring tools across diverse CT scanner platforms.
Japan
METI-funded regional stroke hubs in Kansai and Kyushu deploy cloud-native platforms to address neuroradiologist shortages in rural prefectures. PMDA accelerated review pathways for AI diagnostics attract US and European vendors seeking Asia-Pacific market entry. Tokyo's emergency medical services trial mobile CT units with edge-computing modules for prehospital clot detection.
United Kingdom
NHS England's stroke service specifications mandate imaging turnaround times that favor automated interpretation tools in London and Manchester networks. MHRA convergence with EU MDR standards elevates quality management requirements for software suppliers. Cambridge's medical imaging cluster develops computational biomarker extraction from non-contrast CT sources.
Australia
TGA software medical device regulations align with international standards to streamline approval for US and EU-cleared stroke algorithms. Telestroke networks in Queensland and Western Australia import cloud-based post-processing services to connect rural hospitals with metropolitan specialists. Melbourne's biomedical precinct hosts validation studies for hemorrhagic stroke volume segmentation tools.
Global Stroke Post Processing Software Market Competitive Landscape
Concentration sits with imaging hardware vendors bundling post-processing modules through installed base leverage. Siemens Healthineers and Philips Healthcare embed software within CT and MRI system contracts, while pure-play AI developers pursue standalone algorithm sales. Three archetypes define positioning: equipment-integrated suites, cloud-native specialists, and hybrid workflow configurators. Dominant competitive moves include strategic partnerships between hardware OEMs and AI startups, plus geographic expansion through regulatory harmonization.
Within the equipment-integrated tier, Siemens Healthineers and Philips Healthcare exemplify bundling strategies that capture stroke network procurement committees. RapidAI occupies a position as the pure-play archetype without hardware dependencies. Among emerging specialists, Brainomix and Qure.AI represent geographic diversification patterns targeting European and Asian validation requirements respectively. These named entities anchor competitive dynamics without constraining the full spectrum of market participation.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Philips Healthcare |
| RapidAI |
| Aidoc |
| Canon Medical Systems |
| Viz.AI |
| GE HealthCare |
| Qure.AI |
| Brainomix |
| Others |
Supply & Pricing Matrix
Fixed-cost amortization across cloud-native AI development teams creates steep scale advantages for established stroke software vendors, compressing unit economics for entrants and anchoring price floors to regulatory compliance burdens rather than raw compute costs alone. This concentration dynamic funnels procurement power toward hospital systems with enterprise imaging contracts while fragmenting standalone algorithm pricing.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the stroke post processing software market. Premium tiers bundle FDA-cleared algorithms with dedicated implementation support and SLAs for comprehensive stroke centers, while standard offerings target mid-tier hospitals with cloud-based deployment and limited customization. Price differentiation stems from certification grade—FDA 510(k) versus CE-marked modules—and volume scale through multi-site network licensing. Cost compression in the standard tier is intensifying because pure-play AI developers compete against hardware-bundled suites from Siemens Healthineers and Philips Healthcare. Academic medical centers exhibit lowest price sensitivity due to grant-funded procurement, whereas rural telemedicine services face acute budget constraints and favor per-case transactional models.
Supply Chain Analysis
Inventory cycles for HIPAA-compliant cloud infrastructure stretch 8-12 weeks for new hospital onboarding, creating bottlenecks for stroke network expansion. Software development draws from concentrated engineering talent pools in the United States, Germany, and Israel, with algorithm training dependent on curated DICOM datasets from academic medical centers and synthetic data generation platforms. Supply chain risk centers on single-source vulnerability for GPU cloud compute from NVIDIA-anchored providers, with limited alternatives for training large vessel occlusion detection models at scale. Distribution runs through direct enterprise sales teams targeting hospital procurement committees, supplemented by channel partnerships with PACS vendors and radiology information system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists in stroke post processing software as telemedicine service expansion and prehospital deployment models create underserved niches beyond incumbent hardware bundling. Demand-side digitization of rural stroke networks and emergency medical services procurement channels generates entry points for specialized vendors.
For Market Incumbents: Secure algorithm portfolio breadth through targeted acquisitions of hemorrhagic stroke assessment specialists, as this application segment climbs fastest yet remains underdeveloped relative to ischemic stroke tools. Fortify cloud infrastructure partnerships with HIPAA-compliant hosting providers to preempt single-point vulnerabilities that could disrupt multi-site stroke network deployments. Prioritize EU MDR quality management system alignment ahead of AI Act high-risk system designations, using existing MDR documentation to accelerate conformity assessments. For New Entrants and Emerging Players: Edge computing deployment for prehospital ambulance units represents a service-layer gap where incumbents under-serve, with Japanese emergency medical services trials demonstrating viable procurement pathways. Target Japanese regional stroke hubs and Australian telestroke networks as most penetrable geographies, where METI funding and TGA regulatory alignment lower entry barriers relative to FDA-saturated US markets. Pursue go-to-market angles through partnerships with mobile CT unit manufacturers rather than direct hospital sales, embedding algorithms at the hardware layer to bypass entrenched PACS procurement committees. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native specialists with telemedicine service contracts, where subscription models generate predictable cash flows compared to perpetual license hardware-integrated suites. Long-term viability favors developers with cross-regulatory validation—simultaneous FDA 510(k), CE marking, and PMDA clearance—enabling geographic diversification without redundant development costs. Acquisition target archetype: pure-play AI vendors with validated large vessel occlusion algorithms and established cloud deployment infrastructure. Monitor FDA guidance evolution on AI-enabled diagnostic classification criteria as inflection indicator for compliance cost escalation that favors scaled incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Enterprise imaging contracts with comprehensive stroke centers in Texas and Florida secure installed base leverage against pure-play competitors. |
| Regulatory Harmonization Investment | Simultaneous FDA 510(k) and EU MDR Class IIa submissions reduce redundant clinical validation costs for algorithm developers. |
| Edge Computing Module Development | Prehospital CT integration with Japanese emergency medical services trials opens ambulance procurement as new revenue channel. |
| Platform Integration | PACS and RIS interoperability certifications embed post-processing tools within hospital workflow infrastructure. |
| Geographic Expansion | PMDA accelerated review pathways attract METI-funded regional stroke hub deployments in Kansai and Kyushu prefectures. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with neuroradiologists, stroke unit directors, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, PMDA accelerated review pathway filings, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up and top-down triangulation cross-referenced algorithm deployment counts with enterprise imaging contract values across comprehensive stroke centers.
Across the analysis window, the forecasting framework modeled deployment model segmentation, end-user organization type, regional regulatory cluster, and integration complexity with legacy PACS infrastructure. CAGRs were derived from algorithm adoption velocity in hub-and-spoke stroke networks and telemedicine service expansion rates. Industry-specific inputs included thrombectomy-capable center proliferation timelines and neuroradiologist workforce density projections by metropolitan statistical area.
Underlying assumptions cover continued FDA 510(k) pathway stability and EU MDR software classification consistency, with deviation risk concentrated in AI Act high-risk system designation enforcement and cloud infrastructure concentration vulnerabilities. Forecasts reflect these conditions without claiming predictive certainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market
Medical Imaging
China Medical Imaging Market
Medical Imaging
Handheld Dental X-Ray Systems Market
Medical Imaging
Global Vendor-Neutral Archive (VNA) and PACS Market
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
Europe Nuclear Medicine Market
Medical Imaging
Europe Nuclear Imaging Devices Market
Medical Imaging
Argentina Nuclear Imaging Market
Medical Imaging
North America Fluoroscopy Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
AI Fetal Ultrasound View Detection Software Market
Medical Imaging
France Mammography Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Breast MRI Screening Market