
 Global Immunoassay Market | 2026-2036
Global Immunoassay Market Size, Share, and Industry Trends Forecast 2026-2036
Global Immunoassay Market Outlook
CE marking under the EU In Vitro Diagnostic Regulation is rotating the competitive landscape toward manufacturers with dedicated regulatory affairs teams and notified body relationships. Abbott leverages its integrated diagnostics platform to sustain installed-base loyalty across hospital networks. Siemens Healthineers anchors its position through automated analyzer ecosystems that lock in reagent contracts. Danaher Corporation differentiates via vertical integration into consumables and calibration materials.
An immunoassay is a biochemical test that measures the concentration of a target analyte through antigen-antibody binding, typically achieving detection limits in the picogram-per-milliliter range using labeled reporter molecules. Its primary commercial purpose is to enable quantitative or qualitative detection of biomarkers, pathogens, drugs, and hormones across clinical and non-clinical settings. Chemiluminescent technology captures the dominant margin pool due to superior sensitivity and throughput on automated platforms, while lateral flow assays occupy the point-of-care expansion corridor with simpler workflows. ELISA remains the workhorse format in research labs and food safety screening, where batch flexibility outweighs speed requirements.
The FDA governs premarket submission pathways for immunoassays through the 510(k) and De Novo frameworks, while the EU MDR and IVDR impose stricter clinical evidence and post-market surveillance obligations that extend product development timelines. ISO 13485 certification has become a baseline qualification for supplier relationships with major diagnostic OEMs, effectively filtering out smaller contract manufacturers. Stakeholders must monitor how AI-assisted assay interpretation tools trigger new software-as-medical-device classifications across multiple jurisdictions.
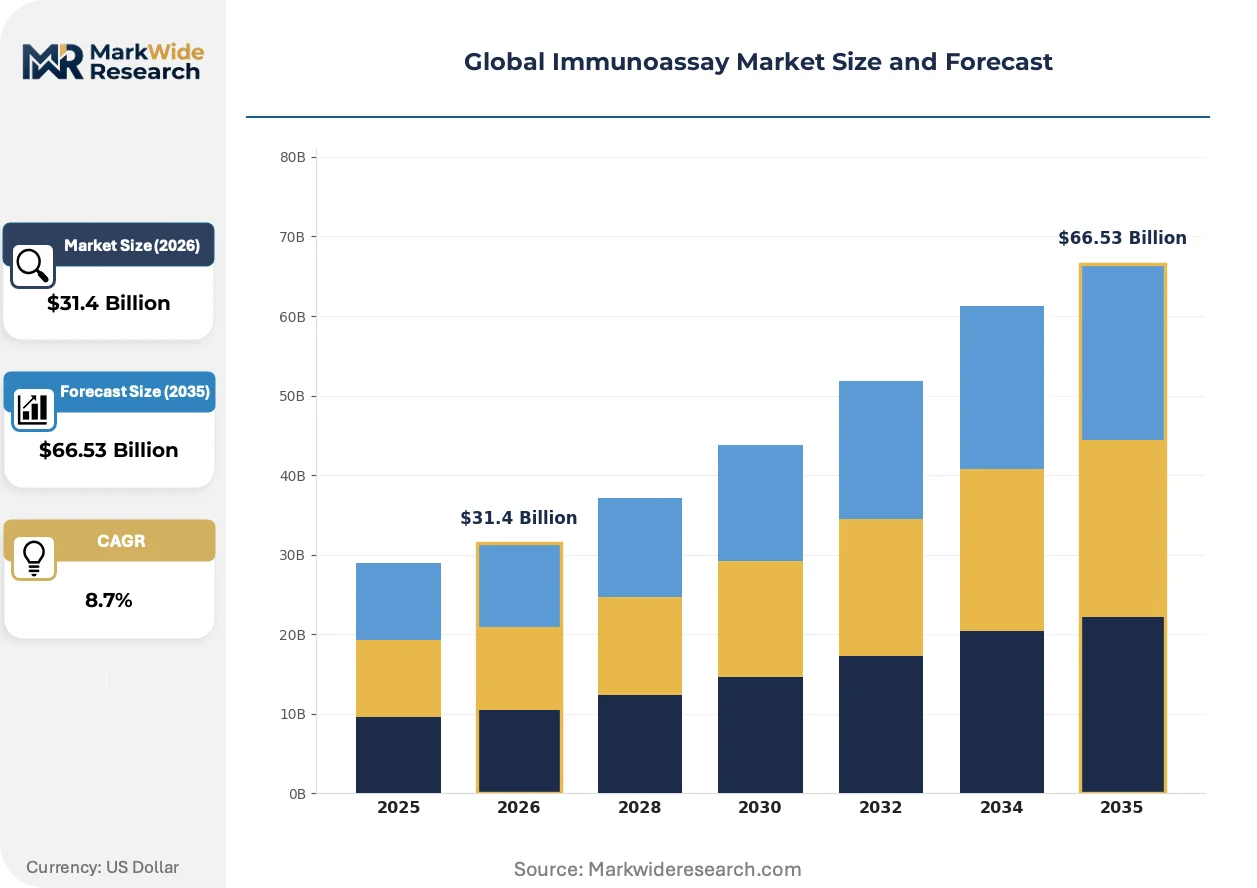
Market Dynamics
Automated chemiluminescent platforms are compressing batch turnaround times while the FDA's De Novo pathway and EU IVDR clinical evidence mandates are elongating product development cycles, creating a structural tension between speed-to-market and regulatory compliance burdens.
Growth Catalysts
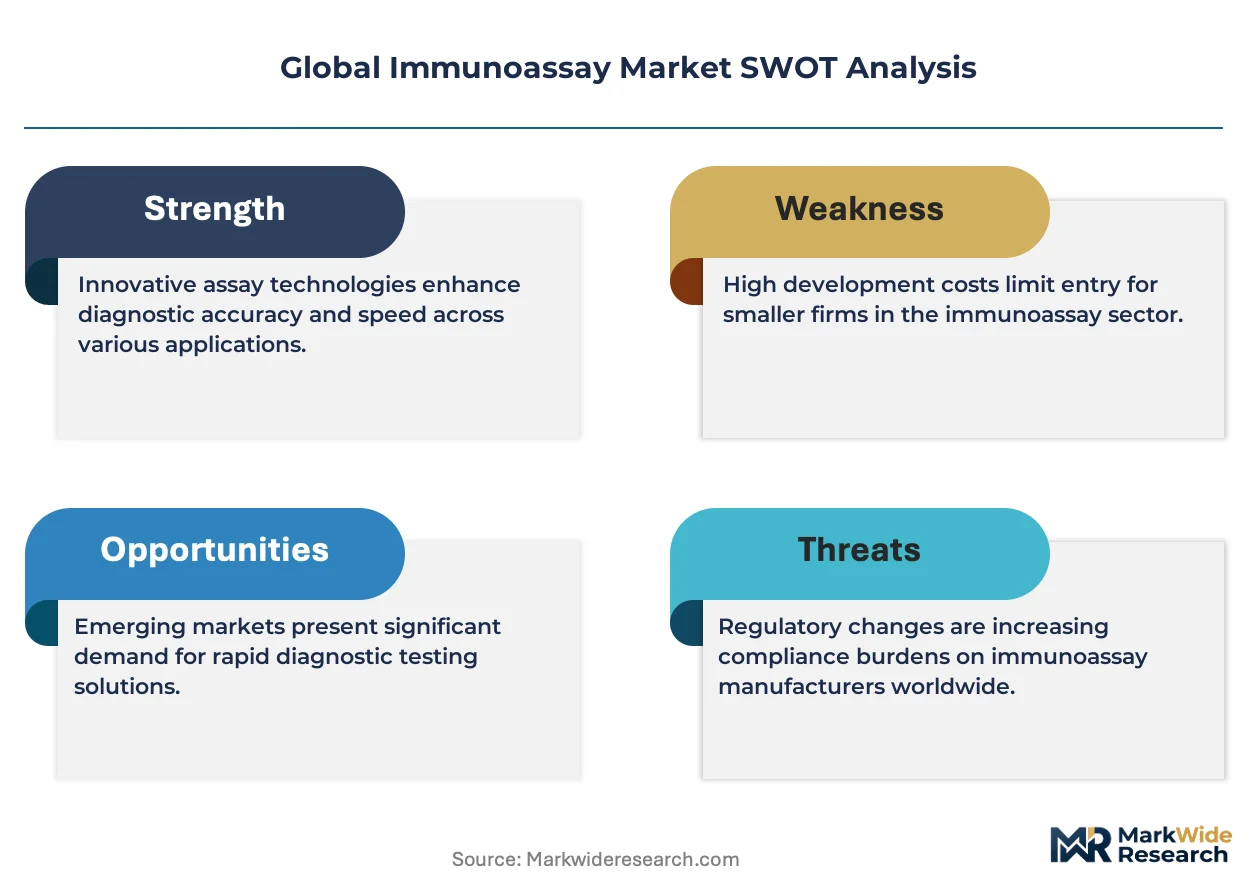
- EU IVDR Implementation:Stricter post-market surveillance obligations under the In Vitro Diagnostic Regulation are filtering out marginal competitors and concentrating procurement among established manufacturers with dedicated notified body relationships.
- Hospital Laboratory Consolidation:Health system mergers in the United States are favoring high-throughput immunoassay analyzers that reduce per-test labor costs across centralized reference laboratories.
- Point-of-Care Expansion:Lateral flow assay miniaturization is opening ambulatory settings and retail clinic channels previously served by centralized labs.
Market Restraints
- Reagent Contract Lock-in:Closed-system analyzer architectures from dominant OEMs create switching costs that suppress price competition and fragment procurement autonomy.
- Antibody Raw Material Concentration:Hybridoma cell line production concentrates in a limited supplier base, exposing assay manufacturers to batch-to-batch variability and supply interruptions.
- Validation Timeline Extension:FDA 510(k) substantive review delays and EU IVDR technical documentation requirements are stretching product commercialization cycles.
Strategic Opportunities
- India Diagnostic Infrastructure:Ayushman Bharat health coverage expansion is creating demand for affordable immunoassay platforms in tier-two and tier-three cities with limited cold-chain logistics.
- AI-Assisted Interpretation:Machine learning algorithms for assay signal processing are triggering software-as-medical-device classifications that enable recurring revenue models.
- Multiplex Panel Development:Simultaneous detection of infectious disease and inflammation biomarkers on single cartridges addresses sepsis diagnosis workflows in emergency departments.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Cross-functional expertise spanning FDA 510(k) preparation, EU IVDR technical file compilation, and ISO 13485 quality management commands premium compensation and extends hiring timelines.
- Legacy Analyzer Integration:Hospital information system connectivity with installed-base instruments requires middleware development that fragments IT resources and delays go-live dates.
- Calibrator Traceability:Reference material sourcing for master lot calibration is concentrating among national metrology institutes, creating bottlenecks for assay kit release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Immunoassay Market |
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $66.53 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA, RIA, LFA, FIA Technology: Colorimetric, Fluorescent, Chemiluminescent, Radiometric End User: Hospitals, Clinics, Research Labs, Diagnostic Centers Application: Clinical Diagnostics, Drug Testing, Food Safety, Environmental Testing |
| Companies Covered | Abbott, F. Hoffmann-La Roche AG, Siemens Healthineers, Danaher Corporation, Thermo Fisher Scientific, Becton, Dickinson and Company, bioMérieux SA, Bio-Rad Laboratories, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Immunoassay Market Strategic Shifts
Digital microfluidics and smartphone-connected readout devices are compressing the boundary between laboratory-grade sensitivity and point-of-care convenience, while regulatory frameworks scramble to classify novel software-augmented diagnostic workflows.
Digital microfluidics is fragmenting traditional assay workflows by manipulating discrete droplets through electrowetting-on-dielectric surfaces, enabling programmable reagent mixing without mechanical pumps. Research laboratories and decentralized testing sites are piloting cartridge-based systems that reduce sample volumes from milliliters to microliters. This technology is fragmenting the historical trade-off between analytical sensitivity and operational simplicity that has segmented the market between centralized labs and bedside testing.
The EU AI Act's risk classification framework for medical device software is reshaping how immunoassay manufacturers validate algorithmic components for result interpretation and quality flagging. Manufacturers must now maintain technical documentation and post-market monitoring systems for machine learning modules previously treated as ancillary features. In vitro diagnostic OEMs with European commercialization strategies are most affected, responding by segregating AI development teams under distinct quality management subsystems.
Hospital procurement committees are unbundling reagent contracts from analyzer placement agreements, demanding itemized pricing transparency previously obscured by total-cost-of-ownership models. This behavioral shift is disrupting the traditional capital-equipment subsidy model and forcing manufacturers to defend reagent margins through performance guarantees rather than hardware discounts. The United States health system consolidation trend is amplifying this pattern, with integrated delivery networks leveraging volume concentration to extract contractual concessions.
Global Immunoassay Market Segmentation
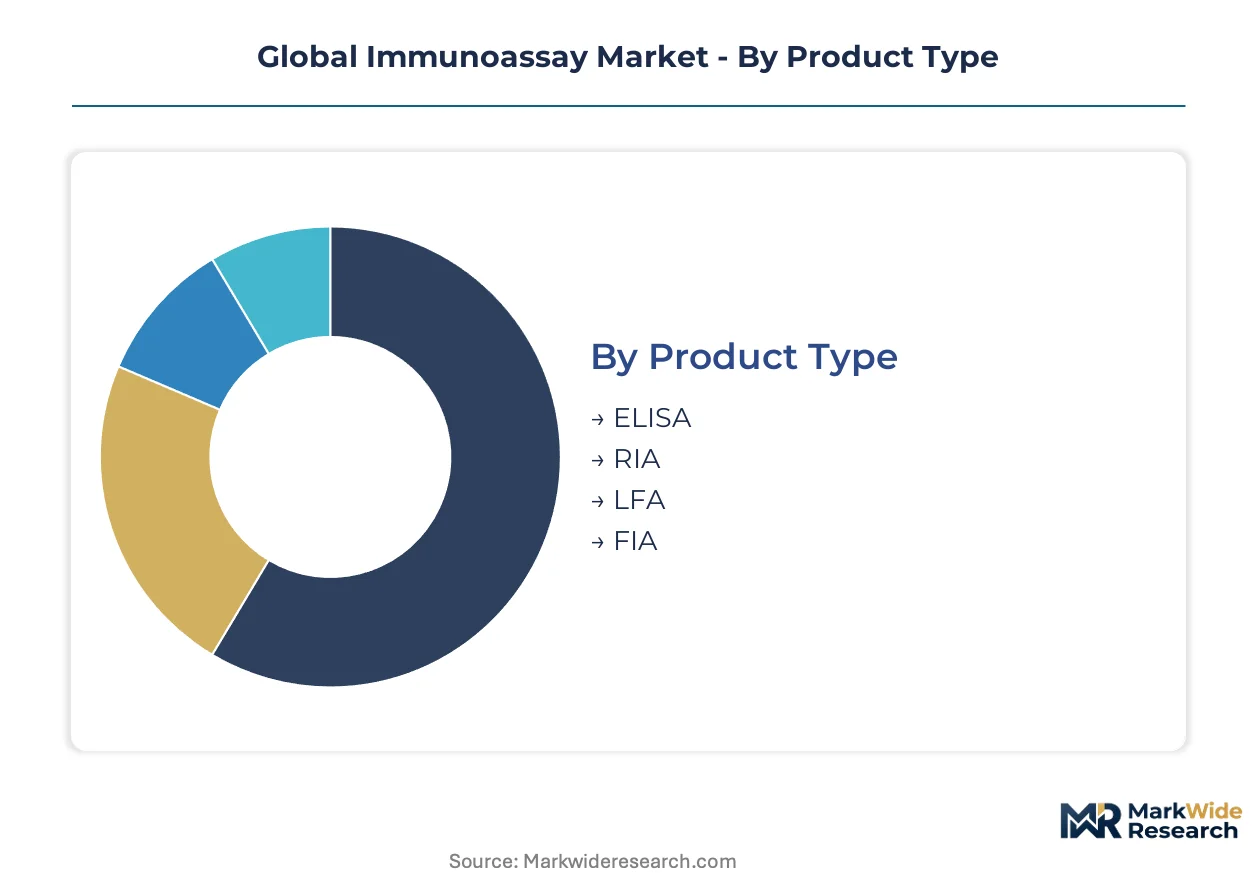
Immunoassay purchasing decisions fragment sharply across settings where analytical sensitivity requirements, regulatory burden, and throughput demands diverge. Manufacturers must architect product portfolios that span picogram-level detection in centralized laboratories to single-use qualitative screening at decentralized points of care.
Product Type:
Substitution pressure from chemiluminescent and digital microfluidic platforms is reshaping the competitive viability of legacy assay formats, with volume concentration shifting toward technologies that compress turnaround time without sacrificing analytical performance.
- ELISA:Enzyme-linked immunosorbent assays deploy horseradish peroxidase or alkaline phosphatase conjugates for colorimetric endpoint detection in 96-well microplate formats. Hospital clinical chemistry departments in the United States and research laboratories across Germany retain substantial installed bases where batch flexibility outweighs speed requirements, though open-system architectures face margin compression from automated platform substitution.
- LFA:Lateral flow assays utilize nitrocellulose membranes with colloidal gold or fluorescent nanoparticle reporters for visual or instrument-read qualitative detection. Retail clinic chains in the United Kingdom and pharmacy-based testing sites in India are expanding procurement of SARS-CoV-2, pregnancy, and cardiac marker panels where patient throughput and minimal operator training dominate purchasing criteria.
- RIA:Radioimmunoassays employ gamma-emitting isotope labels for femtomolar detection limits in specialized endocrinology and toxicology reference laboratories.
- FIA:Fluorescence immunoassays leverage time-resolved fluorometry or europium chelate chemistry for enhanced signal-to-noise ratios in automated analyzer environments.
ELISA anchors the volume base while LFA gains share at the steepest rate.
Technology:
Margin concentration follows sensitivity thresholds, with detection chemistry directly determining reimbursement eligibility and clinical utility in differentiated diagnostic workflows.
- Chemiluminescent:Acridinium ester and alkaline phosphatase-amplified dioxetane chemistries achieve sub-picogram detection limits on automated random-access analyzers. Integrated delivery networks in the United States and hospital laboratory consortia in France are consolidating procurement around platforms that lock in reagent contracts through closed-system architectures, compressing per-test labor costs below colorimetric alternatives.
- Fluorescent:Time-resolved fluorescence and fluorescence polarization methods exploit long-lived emission decay to eliminate background interference in high-sensitivity hormone and tumor marker quantification. Specialty reference laboratories in Switzerland and reproductive health centers in Japan maintain demand for assays requiring detection below chemiluminescent noise floors.
- Colorimetric:Enzyme-mediated absorbance changes at 450nm or 620nm wavelengths serve food safety screening and research batch processing where capital equipment minimization outweighs sensitivity requirements.
- Radiometric:Gamma and beta counting of iodine-125 or tritium labels persists in niche therapeutic drug monitoring and specialized endocrinology applications with limited non-isotopic alternatives.
Chemiluminescent technology commands the dominant margin pool while fluorescent methods expand most quickly in specialized reference settings.
End User:
Customer procurement autonomy varies inversely with health system consolidation intensity, with centralized purchasing committees displacing individual laboratory discretion.
- Hospitals:Acute care institutions with clinical pathology departments operate high-throughput automated platforms for infectious disease, cardiac, and thyroid panels. Health system mergers in the United States and NHS trust consolidation in England are concentrating analyzer placement decisions at network headquarters, extracting volume-based reagent pricing concessions from manufacturers.
- Diagnostic Centers:Independent reference laboratories and commercial testing chains process outsourced specimens from physician offices and smaller institutions. Laboratory chains in Brazil and diagnostic networks in South Korea are expanding automated immunoassay capacity to capture referral volume from hospital budget constraints.
- Clinics:Ambulatory care sites and urgent care facilities deploy point-of-care immunoassays for rapid infectious disease and cardiac marker screening.
- Research Labs:Academic and pharmaceutical research institutions utilize open-platform ELISA and multiplex bead arrays for biomarker discovery and preclinical studies.
Hospitals anchor the volume base while diagnostic centers climb the fastest as outsourcing accelerates.
Application:
Regulatory pathway complexity fragments commercialization timelines, with clinical diagnostics facing the steepest evidence requirements and food safety screening permitting faster market entry.
- Clinical Diagnostics:Quantitative measurement of disease biomarkers, hormones, and infectious agents for patient management decisions. FDA 510(k) and EU IVDR pathways for high-complexity assays demand analytical and clinical validation studies that extend development timelines, favoring established manufacturers with dedicated regulatory affairs infrastructure.
- Drug Testing:Workplace, forensic, and athletic screening for illicit substances and therapeutic drug monitoring. Certified laboratories in the United States under SAMHSA guidelines and forensic institutes across Australia maintain demand for chain-of-custody compliant immunoassay platforms with defensible cutoff concentrations.
- Food Safety:Detection of pathogens, allergens, and toxins in agricultural and processed food supply chains.
- Environmental Testing:Quantification of pesticides, industrial chemicals, and endocrine disruptors in water and soil matrices.
Clinical diagnostics anchors the volume base while drug testing gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathway refinements in the United States and EU IVDR implementation timelines are redistributing manufacturer resources across regulatory jurisdictions with divergent evidence requirements. Procurement concentration in integrated delivery networks and national health systems is compressing vendor margins in mature markets while opening volume corridors in emerging economies with expanding diagnostic infrastructure.
United States
Hospital laboratory consolidation through health system mergers is concentrating analyzer procurement decisions at network headquarters in Nashville, Tennessee and Cleveland, Ohio. The FDA's tightening of 510(k) substantive review timelines is extending product commercialization cycles for novel biomarker assays. Academic medical centers in Boston and the Research Triangle are piloting AI-assisted interpretation modules that trigger software-as-medical-device classification discussions.
Germany
Reference laboratory networks in Munich and Heidelberg are expanding automated chemiluminescent capacity to capture outsourced hospital testing volume. The EU IVDR mandates stricter clinical evidence documentation through notified body relationships that favor established manufacturers with dedicated regulatory affairs teams. The Rhine-Main cluster around Frankfurt anchors reagent production for European distribution.
China
Domestic diagnostic manufacturers in Suzhou and Shenzhen are localizing chemiluminescent platform production to displace imported analyzers in tier-two city hospitals. NMPA regulatory pathway harmonization with international standards is accelerating approval timelines for innovative assay formats. The Yangtze River Delta concentration supports vertical integration into magnetic microparticle and enzyme conjugate supply chains.
India
Ayushman Bharat health coverage expansion is creating procurement corridors for affordable immunoassay platforms in tier-three cities with limited cold-chain logistics. CDSCO import licensing requirements for diagnostic devices are incentivizing domestic manufacturing partnerships near Hyderabad and Ahmedabad. Diagnostic center chains in Bangalore and Chennai are consolidating reference testing volume previously fragmented across hospital laboratories.
Japan
Specialty reference laboratories in Tokyo and Osaka maintain demand for high-sensitivity hormone and tumor marker assays requiring detection below standard chemiluminescent noise floors. PMDA quality management system inspections enforce ISO 13485 compliance that filters supplier relationships toward established contract manufacturers. The Kansai region's precision instrument heritage supports optical component sourcing for fluorescence immunoassay development.
Global Immunoassay Market Competitive Environment
Listed leaders compete with private specialists across platform architecture and reagent contract structures, creating a tiered competitive field where scale advantages in regulatory affairs and installed-base loyalty offset specialist agility in niche biomarker development. The vendor base concentrates around automated analyzer ecosystems that lock in consumable revenue through closed-system architectures. Three archetypes dominate: diversified life science conglomerates with diagnostics divisions, pure-play in vitro diagnostic manufacturers, and emerging regional challengers with cost-optimized platform offerings. Competitive dynamics center on M&A activity to acquire novel biomarker portfolios and strategic partnerships to secure antibody raw material supply.
Within the diversified conglomerate tier, Abbott and Danaher Corporation exemplify platform-ecosystem strategies that integrate analyzer hardware with captive reagent supply chains. F. Hoffmann-La Roche AG anchors the premium-tier positioning through reference laboratory relationships and specialized high-sensitivity assay menus. These three listed entities represent contrasting geographic emphases: Abbott through United States hospital network penetration, Roche through European reference laboratory dominance, and Danaher through vertical control over consumables and calibration materials.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche AG |
| Siemens Healthineers |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Becton, Dickinson and Company |
| bioMérieux SA |
| Bio-Rad Laboratories |
| Sysmex Corporation |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification gates both supplier qualification and price differentiation simultaneously, filtering contract manufacturers into tiered procurement pools where certified facilities command premium positioning against uncertified competitors in hospital network tenders.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread across three distinct pricing tiers. Premium-grade chemiluminescent platforms with full FDA 510(k) and EU IVDR documentation capture the upper tier, while research-use-only ELISA kits without clinical claims occupy the economy band. Price erosion runs through the mid-tier as health system consolidation in the United States extracts volume-based concessions from manufacturers. Diagnostic center chains demonstrate highest price sensitivity, whereas academic medical centers prioritize analytical performance over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for magnetic microparticle and enzyme conjugate shipments. Hybridoma cell line production concentrates in the United States, Switzerland, and Japan, while nitrocellulose membrane manufacturing feeds from China and Germany. Single-source vulnerability in acridinium ester chemistry exposes assay kit manufacturers to release delays. Distribution runs through regional distribution centers serving hospital networks, with direct-to-laboratory replenishment for high-volume reagent contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The immunoassay market is entering a cyclical recovery phase as hospital capital expenditure budgets rebound from pandemic-era deferrals and laboratory consolidation accelerates instrument replacement cycles.
For Market Incumbents: Shield installed-base loyalty by deepening captive reagent supply through backward integration into antibody raw material production. Fortify regulatory affairs infrastructure to navigate EU IVDR technical documentation requirements that are elongating product development timelines and filtering out marginal competitors.
For New Entrants and Emerging Players: FDA De Novo pathway fast-track programs offer entry corridors for AI-assisted interpretation modules that trigger software-as-medical-device classifications. White-space concentration sits in India's tier-three cities under Ayushman Bharat expansion, where affordable platforms with minimal cold-chain requirements address diagnostic infrastructure gaps. Partner with domestic distributors possessing CDSCO import licensing relationships.
For Investors and Strategic Acquirers: EU IVDR implementation reshapes the acquisition landscape toward targets with notified body relationships and completed technical file portfolios. Long-term viability favors manufacturers with multiplex panel development capabilities spanning infectious disease and inflammation biomarkers. Monitor FDA 510(k) substantive review timeline trends as an inflection indicator for commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Technical File Completion | Notified body relationships accelerate market access across German and French hospital networks. |
| Antibody Raw Material Backward Integration | Captive hybridoma production insulates against batch-to-batch variability and supply interruptions. |
| AI-Assisted Interpretation Module Development | Software-as-medical-device classification enables recurring revenue models in academic medical centers. |
| India Distribution Partnership Formation | CDSCO-licensed domestic partners navigate import licensing for tier-two and tier-three city expansion. |
| Multiplex Sepsis Panel Launch | Simultaneous infectious disease and inflammation detection addresses emergency department workflow requirements. |
Study Parameters
Cross-validation between regulatory filing databases and hospital procurement records anchors the qualitative findings. Primary interviews with regulatory affairs directors, clinical laboratory managers, GPO contracts managers, and diagnostic OEM procurement leads were synthesized with secondary validation from FDA 510(k) databases, EU IVDR notified body documentation, CMS Medicare reimbursement schedules, and hospital capital expenditure disclosures. Bottom-up instrument placement modeling and top-down reagent revenue analysis were triangulated against manufacturer reported segment performance.
Sensitivity analysis across regulatory approval timeline scenarios, health system consolidation intensity assumptions, and point-of-care adoption curves shaped the analytical framework. Segmentation dimensions modeled include product format, detection chemistry, end-user setting, clinical versus non-clinical application, and regional regulatory cluster. CAGRs were derived from instrument installed-base projections and per-test reagent consumption rates, with infectious disease panel demand and thyroid testing volume serving as primary forecast inputs.
Underlying assumptions cover stable FDA review staffing levels and EU notified body capacity expansion, with deviation risk concentrated in antibody raw material supply disruptions and hospital merger regulatory approval delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Sperm Count Test Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Global Rapid Diagnostic Kits Market
Diagnostics
Predictive Disease Analytics Market
Diagnostics
E.Coli Latex Agglutination Test Kits Market
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
Global Urinalysis Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
DNA Probes - Based Diagnostics Market
Diagnostics
Paper Based Diagnostic Test Kits Market
Diagnostics
Population Screening Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Asia-Pacific Ovarian Cancer Diagnostics Market