
 Immunochemistry Analyzer Market | 2026-2036
Immunochemistry Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Immunochemistry Analyzer Market Outlook
High-throughput specification tiers is bifurcating the competitive landscape into premium automation vendors and mid-scale system suppliers. Siemens Healthineers AG leverages its installed base of large-scale chemistry-immunoassay integration platforms across European hospital networks. Abbott Laboratories anchors its position through vertical control over assay menus and consumables pull-through. Danaher Corporation differentiates via Beckman Coulter's specialized focus on academic medical center workflows.
An immunochemistry analyzer is an analytical instrument that quantifies antigen-antibody binding reactions through detection methods including chemiluminescence, electrochemiluminescence, or enzyme amplification, typically processing 80–600 tests per hour depending on platform class. These systems serve as the backbone of clinical diagnostic laboratories for detecting hormones, tumor markers, infectious agents, and cardiac biomarkers with picogram-per-milliliter sensitivity thresholds. Automated analyzers command the dominant share of capital expenditure budgets as laboratories prioritize walkaway random-access processing and reduced manual intervention. Enzyme-Linked Immunosorbent Assay technology maintains volume leadership in infectious disease screening, while flow cytometry-based immunophenotyping captures expanding oncology testing demand. Clinical laboratories represent the most concentrated end-user margin pool, though pharmaceutical companies are accelerating instrument purchases for companion diagnostic development.
FDA 510(k) and premarket approval pathways govern U.S. market entry for novel assay-instrument combinations, while IVDR transition timelines in Europe are forcing manufacturers to rebuild technical documentation and clinical evidence packages. China's NMPA has tightened registration requirements for imported diagnostic devices, extending review cycles for multinational submissions. Stakeholders must monitor regulatory divergence across FDA, EMA, and NMPA jurisdictions to anticipate compliance cost escalation and potential market access delays.
Market Dynamics
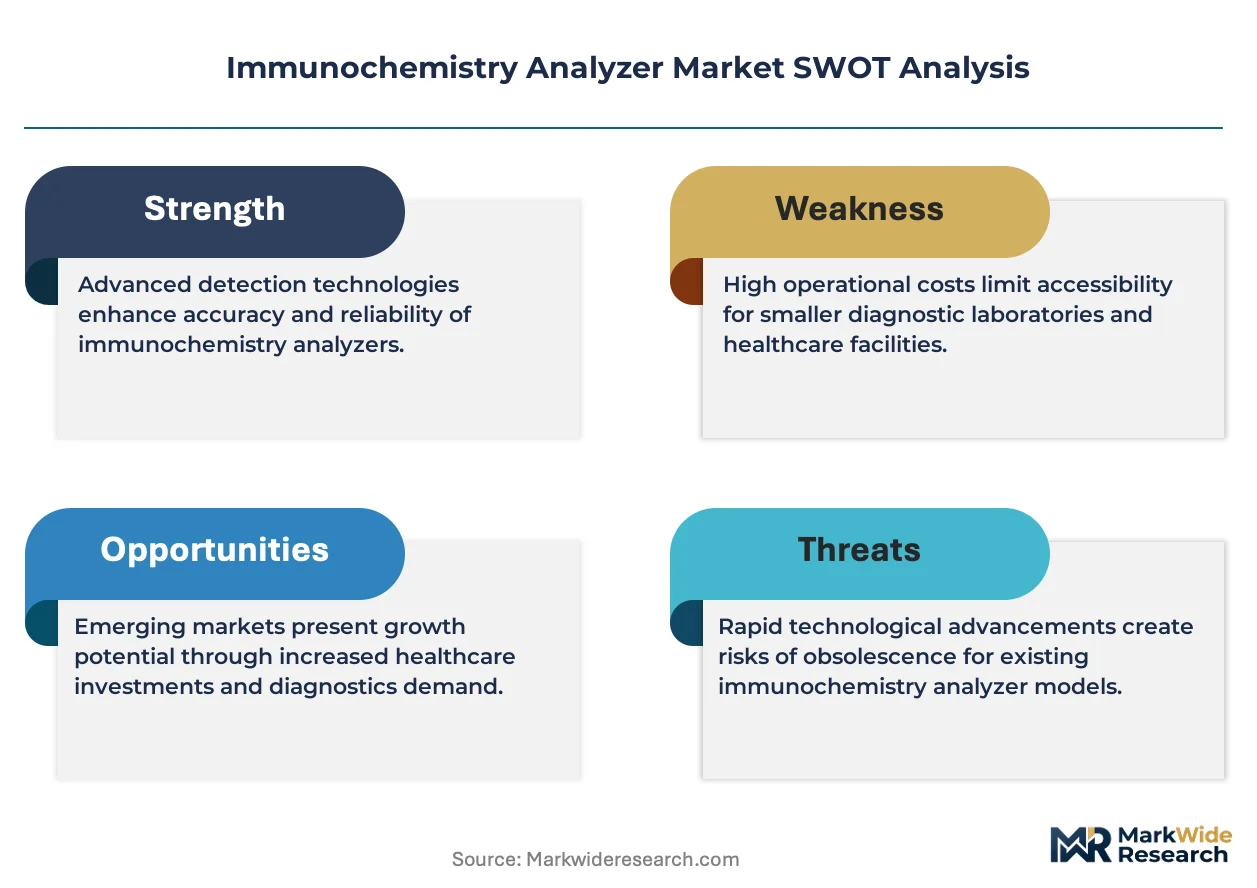
High-throughput random-access automation is compressing laboratory footprints while expanding test menus, forcing capital equipment decisions toward integrated chemistry-immunoassay platforms that displace standalone systems.
Growth Catalysts
- IVDR Technical Documentation Mandate:European laboratories are accelerating analyzer replacements ahead of 2027 IVDR enforcement deadlines, pulling forward capital expenditure cycles for compliant platforms.
- Cardiac Biomarker Testing Expansion:Emergency departments in Germany and the United States are deploying point-of-care immunochemistry systems to reduce troponin turnaround times below 30 minutes.
- Flow Cytometry Convergence:Academic medical centers are integrating immunophenotyping workflows with core chemistry analyzers, consolidating vendor relationships and service contracts.
Market Restraints
- Reagent Rental Lock-In:Consumables contracts tie laboratories to single-vendor assay menus, blocking competitive bidding and inflating lifetime ownership costs.
- European Supply Concentration:Critical optical components and precision fluidics subassemblies concentrate among German and Swiss component suppliers, exposing lead time vulnerability.
- Electrochemiluminescence Patent Thickets:Core detection chemistries remain encumbered by overlapping intellectual property estates, constraining new entrant assay development.
Strategic Opportunities
- China NMPA Localization Incentives:Domestic manufacturing partnerships unlock preferential registration pathways and hospital procurement list eligibility for multinational platforms.
- Companion Diagnostic Co-Development:Pharmaceutical companies are purchasing dedicated analyzer lines for biomarker validation during Phase II/III oncology trials.
- AI-Assisted Result Interpretation:Machine learning algorithms for pattern recognition in complex antibody panels are creating differentiation for premium-tier systems.
Industry Challenges
- Cross-Training Shortfalls:Laboratory technologists require simultaneous expertise in immunoassay biochemistry, informatics integration, and preventive maintenance protocols.
- Legacy LIS Integration:Hospital information systems built on HL7 v2.x architectures demand costly middleware development for bidirectional analyzer communication.
- Proficiency Testing Logistics:External quality assessment programs struggle to standardize calibrator traceability across chemiluminescence and enzyme amplification methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunochemistry Analyzer Market |
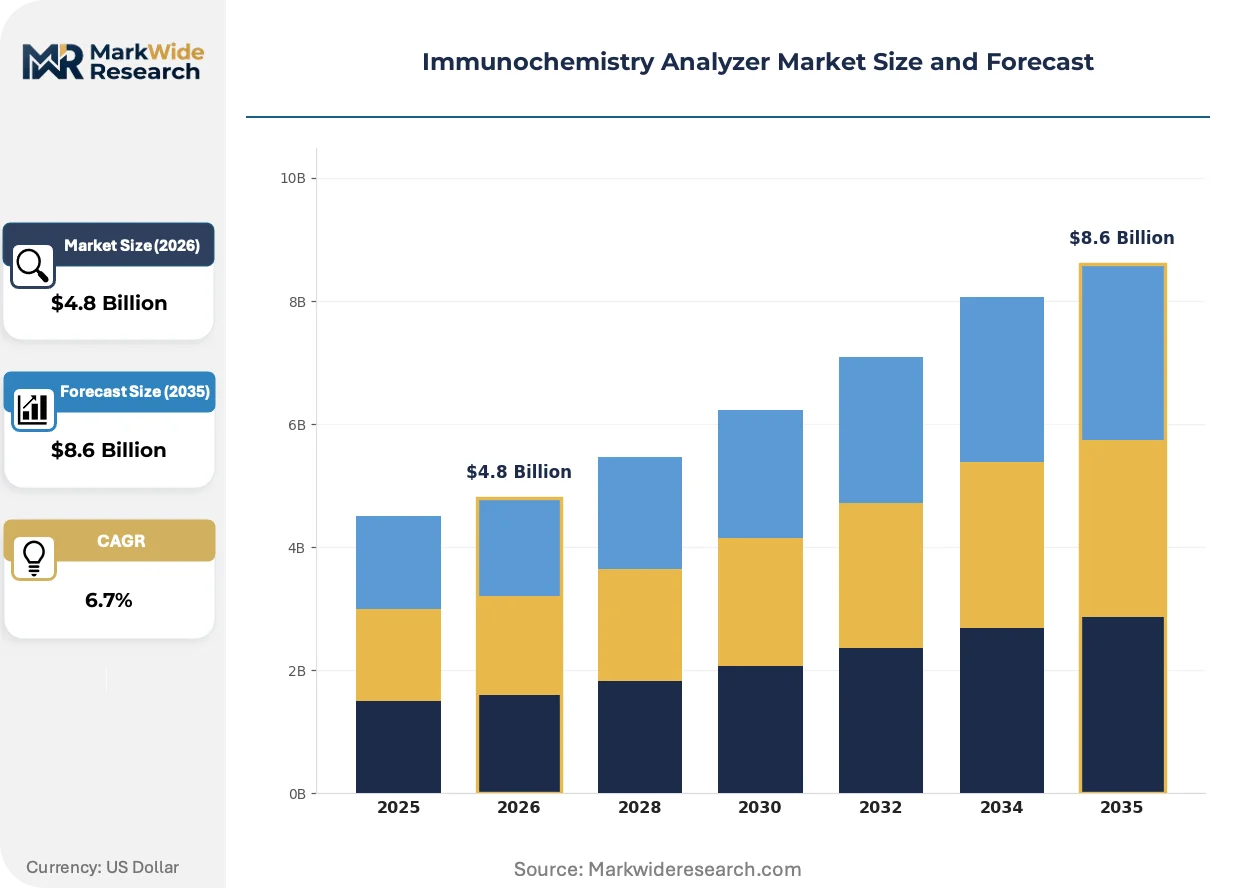
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Analyzers, Semi-Automated Analyzers, Reagents, Control Materials Technology: Enzyme-Linked Immunosorbent Assay, Western Blotting, Flow Cytometry, Radioimmunoassay End User: Clinical Laboratories, Research Institutions, Diagnostic Centers, Pharmaceutical Companies Application: Oncology, Infectious Diseases, Autoimmune Disorders, Cardiology |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Danaher Corporation, Thermo Fisher Scientific Inc., bioMérieux, Sysmex Corporation, Beckman Coulter, QuidelOrtho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunochemistry Analyzer Market Strategic Shifts
Detection platform architectures are fragmenting into three performance tiers while regulatory evidence requirements intensify, compressing product development timelines and reshaping competitive differentiation.
Microfluidic cartridge technology is miniaturizing sample processing volumes from milliliters to microliters, enabling near-patient testing deployment in satellite clinics and retail health settings. Primary care networks in the United States are piloting these systems for same-day infectious disease screening. The footprint reduction is miniaturizing capital allocation decisions, allowing distributed testing nodes that bypass centralized laboratory infrastructure.
Europe's IVDR transition is mandating clinical performance studies for legacy assays previously cleared under the IVD Directive, forcing manufacturers to rebuild technical documentation for entire installed menus. German notified bodies are experiencing capacity constraints that extend review timelines for Class C and D devices. Smaller assay developers are abandoning European market entry, concentrating menu innovation among established platform vendors with dedicated regulatory affairs infrastructure.
Hospital procurement committees are unbundling service contracts from instrument sales, competitively bidding maintenance and calibration separately from capital acquisitions. Integrated delivery networks in Texas and Florida are piloting this model for multi-site standardization. The disaggregation pressures vendor margins on aftermarket revenue, compelling manufacturers to embed predictive diagnostics and remote monitoring capabilities that justify premium service tiers.
Immunochemistry Analyzer Market Segmentation
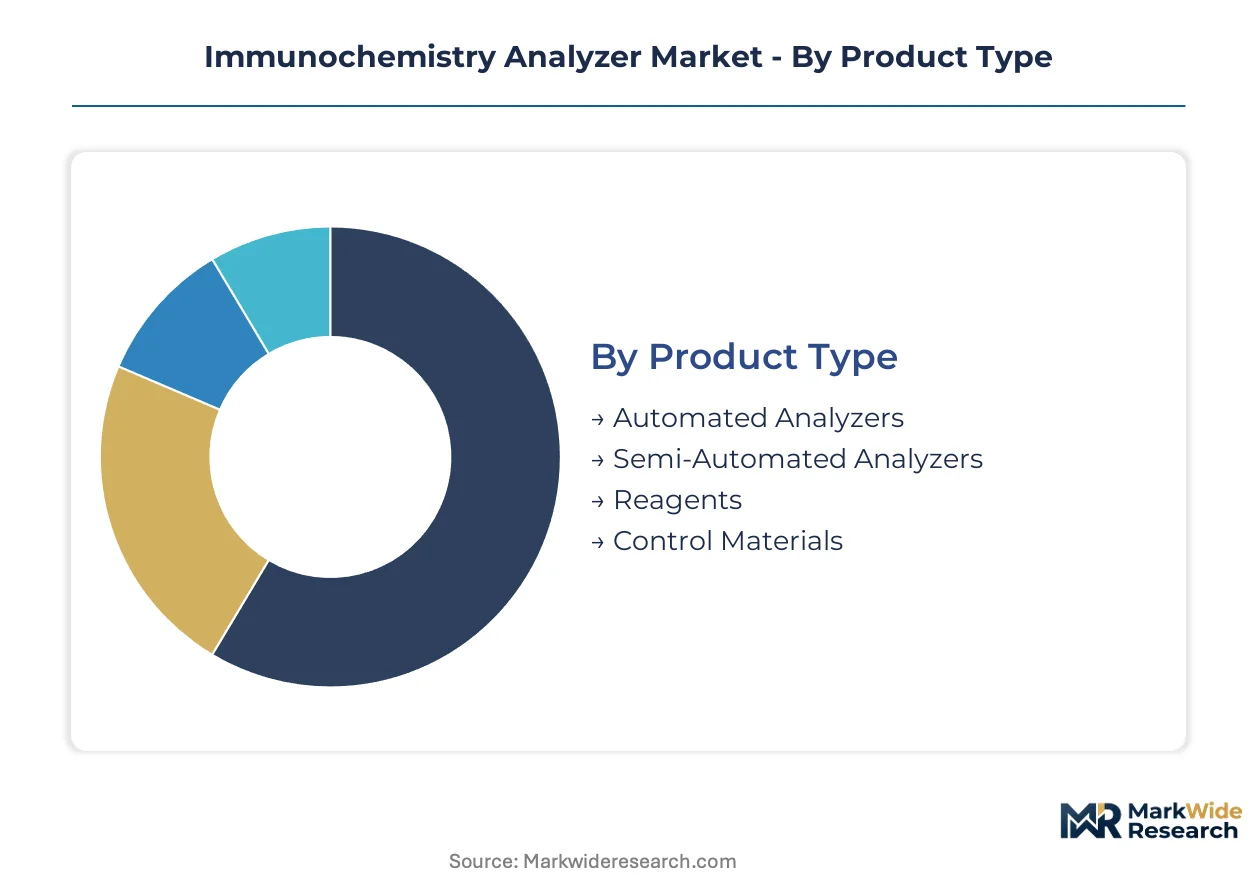
Segmentation reveals how capital deployment, regulatory burden, and workflow complexity concentrate across distinct equipment classes and use environments. Laboratories align purchasing decisions with test volume thresholds, assay menu breadth, and compliance requirements specific to each tier.
Product Type:
Domestic production concentrates on reagents and control materials, while automated and semi-automated platforms flow through import-dependent supply chains subject to NMPA and FDA review cycles.
- Automated Analyzers:These systems integrate random-access processing with continuous loading capabilities, processing 400–800 tests hourly through chemiluminescence or electrochemiluminescence detection. Demand clusters in United States hospital networks and German university medical centers consolidating core laboratory operations. IVDR technical documentation mandates are accelerating replacement cycles ahead of enforcement deadlines.
- Reagents:Liquid-stable chemistries and lyophilized conjugates constitute the recurring revenue anchor for platform vendors, with menu breadth determining laboratory switching costs. Chinese domestic manufacturers are expanding registered assay portfolios to capture procurement list eligibility under NMPA localization incentives.
- Semi-Automated Analyzers:Batch-processing instruments serve mid-volume laboratories in India and Southeast Asia with lower capital barriers.
- Control Materials:Third-party calibrators and proficiency testing panels ensure traceability across chemiluminescence methodologies.
Automated analyzers command the established base. The steepest expansion runs through reagents.
Technology:
Detection chemistry selection directly determines sensitivity thresholds, throughput ceilings, and intellectual property exposure for assay developers.
- Enzyme-Linked Immunosorbent Assay:Colorimetric or chemiluminescent substrate amplification enables picogram-per-milliliter detection of antibodies and antigens in 96-well microplate formats. Infectious disease screening programs in Brazil and South Africa deploy these platforms for HIV and hepatitis surveillance due to reagent stability and minimal cold-chain requirements.
- Flow Cytometry:Laser-based immunophenotyping quantifies cell-surface marker expression for leukemia classification and minimal residual disease monitoring. Academic medical centers in the United States and Germany are integrating these workflows with core chemistry analyzers to consolidate vendor relationships.
- Western Blotting:Semi-quantitative protein detection serves confirmatory testing in research settings.
- Radioimmunoassay:Isotopic detection persists in specialized endocrinology reference laboratories despite disposal and regulatory burdens.
Enzyme-Linked Immunosorbent Assay retains volume leadership. Flow cytometry gains share fastest in oncology applications.
End User:
Customer type determines pricing tolerance, service contract structure, and assay menu customization requirements.
- Clinical Laboratories:Hospital-based and independent reference laboratories generate the concentrated margin pool for instrument vendors, prioritizing walkaway automation and bidirectional LIS integration. Integrated delivery networks in Texas and Florida are unbundling service contracts from capital acquisitions to drive multi-site standardization.
- Pharmaceutical Companies:Companion diagnostic development programs require dedicated analyzer lines for biomarker validation during Phase II/III oncology trials, with CDx co-development agreements locking in platform selections early.
- Research Institutions:Academic cores demand flexible assay development capabilities and open reagent architectures.
- Diagnostic Centers:Outpatient imaging and pathology networks seek throughput-matched systems for routine hormone and tumor marker panels.
Clinical laboratories anchor installed base economics. Pharmaceutical company procurement is climbing the fastest.
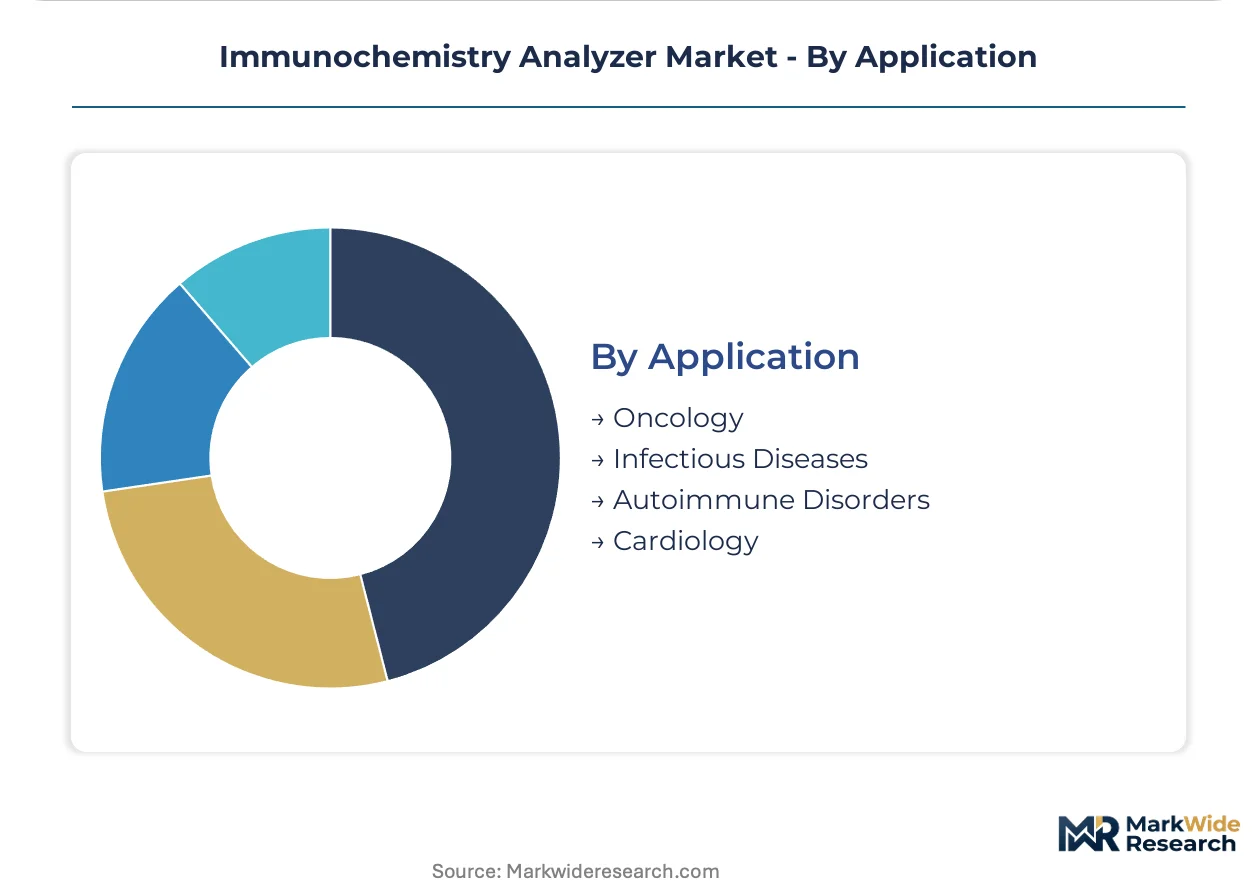
Application:
Disease area focus shapes menu development priorities and regulatory evidence requirements for new assay launches.
- Oncology:Immunophenotyping and tumor marker quantification drive premium-tier system placements, with PSA, CA-125, and HER2/neu assays commanding high test frequencies. German and United States emergency departments are deploying point-of-care systems to reduce troponin turnaround times below 30 minutes for chest pain rule-out protocols.
- Infectious Diseases:HIV, hepatitis, and respiratory pathogen panels sustain high-throughput screening volumes in public health programs and blood bank settings.
- Autoimmune Disorders:ANA and specific antibody panels serve rheumatology and nephrology referral networks.
- Cardiology:High-sensitivity troponin I and T assays dominate emergency department testing workflows.
Oncology commands the established base. Cardiology applications are expanding most quickly through point-of-care deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate low price elasticity for integrated chemistry-immunoassay platforms, while procurement committees in India and Southeast Asia prioritize capital efficiency over throughput specifications.
United States
Emergency departments in Texas and Florida are deploying point-of-care immunochemistry systems to compress troponin turnaround times below 30 minutes. FDA 510(k) pathways govern market entry for novel assay-instrument combinations. The Greater Boston corridor anchors companion diagnostic co-development activity, with pharmaceutical companies purchasing dedicated analyzer lines for Phase II/III oncology trials.
Germany
University medical centers in Bavaria and North Rhine-Westphalia are consolidating core laboratory operations around large-scale automation platforms. IVDR technical documentation mandates are accelerating replacement cycles ahead of 2027 enforcement deadlines. The Rhine-Main cluster around Frankfurt hosts notified bodies experiencing capacity constraints that extend review timelines for Class C and D devices.
China
Hospital procurement committees in Shanghai and Beijing are scaling diagnostic infrastructure under healthcare reform timelines. NMPA has tightened registration requirements for imported diagnostic devices, extending review cycles for multinational submissions. Domestic manufacturers in the Yangtze River Delta are expanding registered assay portfolios to capture procurement list eligibility under localization incentives.
India
Mid-volume laboratories in Maharashtra and Karnataka are adopting semi-automated batch-processing instruments with lower capital barriers. CDSCO regulates diagnostic device registration through centralized and state-level pathways. The Delhi-NCR corridor concentrates independent reference laboratory networks unbundling service contracts from capital acquisitions to drive multi-site standardization.
Japan
Academic medical centers in the Kanto region are integrating immunophenotyping workflows with core chemistry analyzers to consolidate vendor relationships. PMDA oversees pharmaceutical and medical device approvals through premarket consultation frameworks. The Osaka-Kobe manufacturing belt supplies precision optical components and fluidics subassemblies to platform vendors globally.
Immunochemistry Analyzer Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Premium automation vendors dominate high-throughput specifications through integrated chemistry-immunoassay platforms, while mid-scale system suppliers compete on capital efficiency for emerging markets. Three archetypes define the landscape: full-menu platform vendors with consumables lock-in, specialized academic medical center suppliers, and domestic champions leveraging localization policies. Consolidation through strategic partnerships and geographic expansion represents the dominant competitive moves.
Within the full-menu platform tier, Abbott Laboratories and Siemens Healthineers AG exemplify archetypes anchored by installed base economics and vertical control over assay menus. Danaher Corporation occupies a position representing specialized focus on academic medical center workflows through its Beckman Coulter subsidiary. These three entities collectively illustrate how vendor concentration concentrates menu innovation among established players with dedicated regulatory affairs infrastructure.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| bioMérieux |
| Sysmex Corporation |
| Beckman Coulter |
| QuidelOrtho Corporation |
| Others |
Value Chain & Pricing Dynamics
IVDR technical documentation mandates gate both supply qualification and price differentiation simultaneously, as notified bodies in Germany enforce Class C and D device standards that only established vendors can satisfy, compressing procurement options while inflating compliance premiums for compliant platforms.
Pricing Analysis
After-sales service contracts and consumables pull-through drive lifetime value, with reagent rental agreements locking laboratories into multi-year commitments that obscure true per-test costs. Three-tier pricing structure across premium, standard, and economy levels separates integrated chemistry-immunoassay platforms from standalone systems and entry-level batch processors. Cost compression in mid-scale tiers is intensifying because Chinese domestic manufacturers are expanding registered assay portfolios under NMPA localization incentives. Hospital procurement committees in India and Southeast Asia demonstrate highest price sensitivity, while German university medical centers prioritize throughput specifications over capital efficiency.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for precision optical components sourced from Japanese manufacturers in the Osaka-Kobe belt. Critical fluidics subassemblies and chemiluminescence detection modules draw from concentrated production in Germany, Switzerland, and Japan. Single-source vulnerability persists for electrochemiluminescence reagents encumbered by overlapping patent estates. Distribution runs through import-dependent channels subject to FDA, IVDR, and NMPA review cycles, with domestic production limited to control materials and reagent formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in Texas and Florida, where multi-site standardization committees unbundle service contracts from capital acquisitions to extract pricing concessions.
For Market Incumbents: Shield installed base economics by embedding predictive diagnostics and remote monitoring capabilities that justify premium service tiers against disaggregation pressures. Deepen backward integration into precision fluidics subassemblies to reduce exposure to German and Swiss component supplier concentration. Prioritize regulatory affairs infrastructure investments that accelerate IVDR technical documentation completion ahead of notified body capacity constraints. For New Entrants and Emerging Players: Anchor in companion diagnostic co-development partnerships with pharmaceutical companies purchasing dedicated analyzer lines for Phase II/III oncology trials, where CDx agreements lock in platform selections early. Target mid-volume laboratories in India and Southeast Asia with semi-automated batch-processing instruments that bypass premium-tier competitive intensity. Lead with AI-assisted result interpretation capabilities that differentiate through machine learning pattern recognition in complex antibody panels. For Investors and Strategic Acquirers: IVDR transition timelines reshape the acquisition landscape by forcing smaller assay developers to abandon European market entry, concentrating menu innovation among established platform vendors with dedicated regulatory infrastructure. Five-to-ten year viability favors full-menu platform vendors with consumables lock-in over specialized academic suppliers exposed to unbundling pressures. Monitor notified body capacity constraints in Germany as the signal indicating regulatory bottleneck severity and accelerated replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Completion | Notified body capacity constraints in Germany favor early movers with complete clinical evidence packages. |
| Companion Diagnostic Co-Development Partnership | Pharmaceutical companies purchasing dedicated analyzer lines for oncology trials lock in platform selections. |
| AI-Assisted Result Interpretation Development | Machine learning algorithms for complex antibody panel pattern recognition differentiate premium-tier systems. |
| NMPA Localization Manufacturing Partnership | Domestic production in Yangtze River Delta unlocks preferential registration pathways and procurement eligibility. |
| Service Contract Predictive Diagnostics Integration | Remote monitoring capabilities justify premium tiers against hospital procurement committee disaggregation pressures. |
Study Parameters
The analysis maps automated analyzers, reagents, semi-automated platforms, and control materials, each validated through laboratory directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, IVDR technical documentation databases, NMPA registration records, and hospital procurement databases. Bottom-up instrument shipment tracking and top-down diagnostic infrastructure spending estimates triangulate market sizing.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include product type, detection technology, end-user category, and application area, with additional granularity on regulatory pathway tier. CAGRs were derived from installed base replacement cycles, test volume expansion rates, and assay menu breadth expansion. Forecast inputs incorporated IVDR enforcement timeline assumptions, NMPA localization incentive penetration, and point-of-care immunochemistry deployment rates in emergency departments.
Underlying assumptions cover regulatory pathway stability, notified body capacity recovery, and trade lane normalization, with deviation risk concentrated in IVDR timeline delays, NMPA registration requirement tightening, and precision component supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Global Blood Gas and Electrolyte Analyzer Market
Diagnostic Instruments
Diagnostic Electrocardiograph Market
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Platelet Aggregation Devices Market
Diagnostic Instruments
Global Point of Care Ultrasound Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Global Radioimmunoassay Market
Diagnostic Instruments
Visual Field Testing Equipment Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Nasometry Devices Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market